
 Digital Remittance Service Market | 2026-2036
Digital Remittance Service Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Remittance Service Market Insights
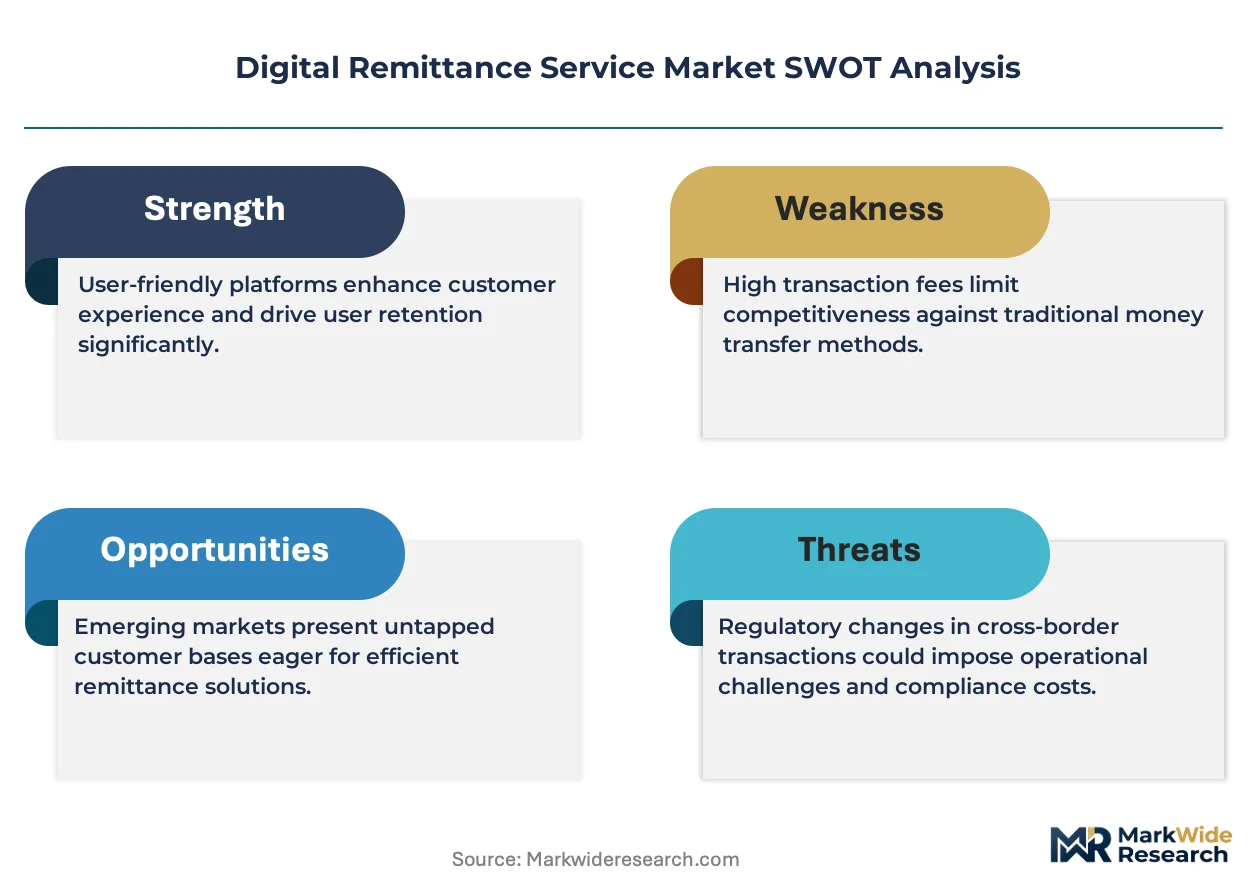
AI-literate compliance talent is bifurcating the competitive landscape between platforms that can automate KYC/AML workflows and those still dependent on manual review. Wise plc leverages proprietary banking infrastructure to sustain pricing advantages on high-volume corridors. PayPal Holdings, Inc. anchors its position through embedded checkout ecosystems that capture remittance intent at the point of commerce. Western Union Holdings, Inc. dominates physical-digital hybrid networks where cash payout remains essential.
Digital remittance services are software-enabled financial instruments that execute cross-border value transfer through encrypted API protocols, typically settling within minutes via correspondent banking networks or distributed ledger rails, with primary commercial purpose of replacing slow, expensive wire transfers for individuals and SMEs. Real-time transfer and mobile wallet transfer categories are capturing the fastest volume growth as smartphone penetration deepens in sender and receiver markets. Cloud-based deployment models now lead enterprise adoption because they allow licensed money transmitters to scale compliance infrastructure without capital-heavy data center investment.
The US Treasury's Financial Crimes Enforcement Network and the EU's PSD2 framework jointly shape market access by mandating real-time transaction monitoring and strong customer authentication, which elevates operating costs for entrants lacking automated compliance stacks. India's RBI and Singapore's Monetary Authority impose licensing tiers that reserve full bank integration for capitalized incumbents while restricting newer API-only providers to closed-loop wallet models. Stakeholders must weigh whether to build captive compliance technology or absorb third-party SaaS costs as regulatory density intensifies across corridors.
Market Dynamics
Real-time settlement infrastructure is compressing correspondent banking timelines from days to minutes, forcing legacy wire providers to absorb API-native competitors or lose volume on high-frequency corridors like India-UAE and Philippines-East Asia.
Growth Catalysts
- UPI-RBI integration:India's unified payments interface mandates instant settlement rails that slash cross-border friction for migrant worker remittances originating in Gulf Cooperation Council states.
- Smartphone penetration:Mobile wallet adoption among unbanked recipients in the Philippines and Indonesia is displacing cash pickup as the default last-mile delivery mechanism.
- PSD2 strong authentication:The EU's payment services directive mandates biometric verification standards that reduce fraud rates and lower compliance insurance premiums for licensed transmitters.
Market Restraints
- Correspondent banking concentration:Three US-headquartered clearing banks control over seventy percent of dollar-denominated settlement volume, creating single-point-of-failure risk for non-bank remittance platforms.
- AML screening costs:FinCEN's real-time transaction monitoring rules require perpetual software license fees that consume fifteen to twenty percent of operating budgets for mid-tier providers.
- Stablecoin substitution:Dollar-pegged digital assets on public blockchains offer settlement finality without banking intermediaries, threatening fee-based revenue models on high-volume corridors.
Strategic Opportunities
- BIS cross-border CBDC pilots:The Bank for International Settlements' Project Dunbar tests multi-currency settlement platforms that could eliminate correspondent banking layers entirely for participating corridors.
- SME payroll integration:Embedded remittance APIs within workforce management software capture sender intent at the point of salary disbursement for construction and domestic labor sectors.
- Cloud compliance stacks:SaaS-based KYC orchestration allows new entrants to license automated identity verification without captive data center investment, lowering capital barriers to market entry.
Industry Challenges
- AI-literate compliance staffing:Shortages of engineers capable of training machine-learning models for suspicious activity detection force platforms to rely on expensive third-party model vendors.
- Legacy core banking integration:SOAP-based mainframe protocols at incumbent settlement banks resist REST API connectivity, requiring costly middleware development for real-time data exchange.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Remittance Service Market |
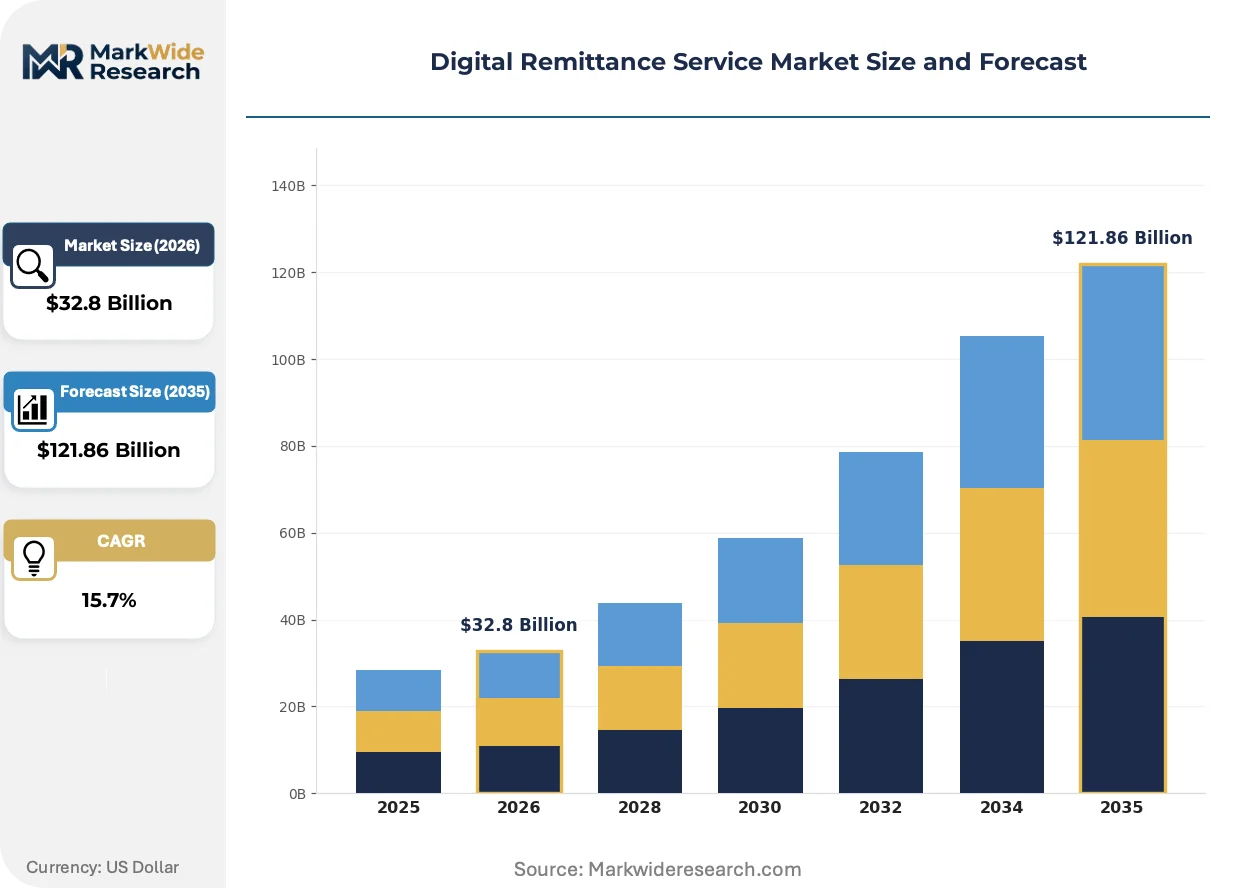
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $121.86 Billion |
| CAGR (2026 – 2036) | 15.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Real-Time Transfer, Batch Transfer, Cross-Border Transfer, Peer-to-Peer Transfer, Mobile Wallet Transfer Deployment Model: Cloud-Based, On-Premises, Hybrid, API Integration, White-Label Solutions Customer Type: Individual Users, Small & Medium Enterprises, Corporates, Freelancers, Non-Profit Organizations Application Use Case: Personal Remittance, Payroll Processing, Bill Payments, Merchant Settlements, Government Transfers |
| Companies Covered | Western Union Holdings, Inc., PayPal Holdings, Inc., Wise plc, MoneyGram International, Inc., Remitly Global, Inc., WorldRemit Ltd., Ria Financial Services Ltd., NIUM Pte. Ltd., TransferGo Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Remittance Service Market Trends and Innovations
Encrypted API protocols and distributed ledger experimentation are fragmenting the settlement layer, creating parallel infrastructure that rewards technical sophistication over branch network scale.
Machine-learning transaction monitoring is bifurcating the competitive landscape between platforms with automated KYC/AML workflows and those dependent on manual review. Tier-one banks and well-capitalized fintechs deploy neural networks trained on historical SAR filings to reduce false-positive rates below two percent. Smaller licensed transmitters still rely on rule-based screening that generates alert backlogs measured in days, compressing their operating margins and limiting corridor expansion.
FinCEN's 2024 travel rule guidance for virtual asset service providers extends traditional wire transfer transparency requirements to cryptocurrency exchanges handling remittance-adjacent flows. The industrial consequence is mandatory counterparty identification for transactions exceeding three thousand dollars, forcing hybrid platforms to rebuild custody architectures. Non-compliant exchanges face correspondent banking exclusion, driving consolidation toward regulated entities with existing MSB licenses.
Sender behavior is rotating toward embedded finance interfaces that surface remittance functionality within super-apps and e-commerce checkout flows. Migrant workers in the Gulf Cooperation Council increasingly initiate transfers from within ride-hailing and food delivery applications rather than standalone remittance portals. This channel shift is most visible in the Philippines-to-East Asia corridor, where family support payments now originate predominantly from wallet balances rather than bank debits.
Digital Remittance Service Market Segmentation
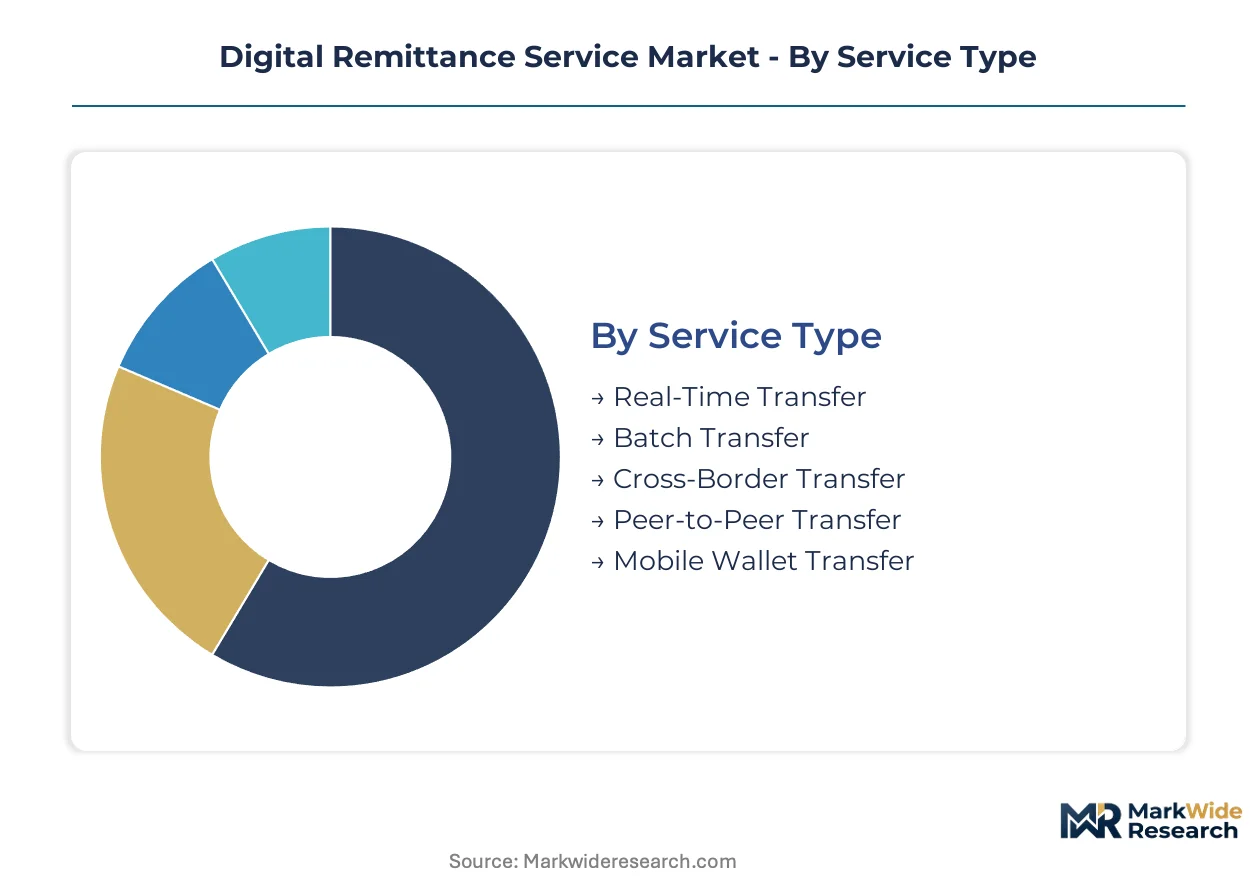
Segmentation in digital remittance services reveals how infrastructure choices and customer economics create divergent margin profiles. Service type and deployment model decisions lock platforms into specific regulatory capital requirements and technical debt trajectories.
Service Type:
Substitution pressure from blockchain settlement and stablecoin rails hits batch and cross-border transfer segments hardest, while real-time infrastructure builds defensive moats through regulatory integration.
- Real-Time Transfer:Immediate settlement via UPI-RBI rails and correspondent banking APIs compresses friction for Gulf Cooperation Council migrant corridors. India's regulatory infrastructure mandates sub-minute finality, displacing traditional wire timelines for family support payments.
- Mobile Wallet Transfer:Smartphone penetration among unbanked recipients in the Philippines and Indonesia drives last-mile displacement of cash pickup. Embedded finance interfaces within super-apps capture sender intent at point of salary disbursement.
- Batch Transfer:Aggregated settlement windows optimize treasury management for SME payroll processors absorbing FX volatility.
- Cross-Border Transfer:Correspondent banking concentration creates single-point-of-failure exposure for dollar-denominated settlement volume.
- Peer-to-Peer Transfer:Social payment linkages between diaspora networks reduce customer acquisition costs through viral referral mechanics.
Batch transfer anchors the volume base while mobile wallet transfer gains share at the steepest rate.
Deployment Model:
Capital intensity separates segments, with cloud-native architectures enabling compliance scaling without captive data center investment.
- Cloud-Based:SaaS infrastructure allows licensed money transmitters to scale KYC orchestration through third-party API stacks. FinCEN's real-time monitoring mandates favor elastic compute provisioning over fixed hardware depreciation.
- API Integration:Embedded remittance functionality within workforce management software captures construction and domestic labor payroll intent. REST protocol standardization reduces middleware development costs versus SOAP-based legacy core banking.
- On-Premises:Air-gapped transaction monitoring satisfies data sovereignty requirements in jurisdictions with strict financial information localization.
- Hybrid:Tiered architecture segregates customer-facing applications from sensitive compliance data processing.
- White-Label Solutions:License-as-a-service models lower market entry barriers for regional banks lacking proprietary remittance technology.
On-premises deployment retains the highest customer lifetime value while API integration expands most quickly through ecosystem embedding.
Customer Type:
Transaction frequency and average ticket size create divergent unit economics across customer profiles.
- Individual Users:Migrant worker remittances concentrate in Philippines-to-East Asia corridors where family support payments dominate. Smartphone penetration enables mobile wallet default over bank debit origination.
- Small & Medium Enterprises:Cross-border supplier payments require multi-currency hedging and automated reconciliation against invoice matching.
- Corporates:Treasury centralization demands API connectivity to ERP systems for real-time cash position visibility.
- Freelancers:Gig economy platforms embed payout functionality reducing friction for cross-border service compensation.
- Non-Profit Organizations:Humanitarian disbursements prioritize cash pickup networks in infrastructure-constrained recipient markets.
Individual users generate the highest transaction velocity while SME segment climbs the fastest through embedded payroll integration.
Application Use Case:
Regulatory density varies sharply by use case, with government transfers facing the most stringent transparency requirements.
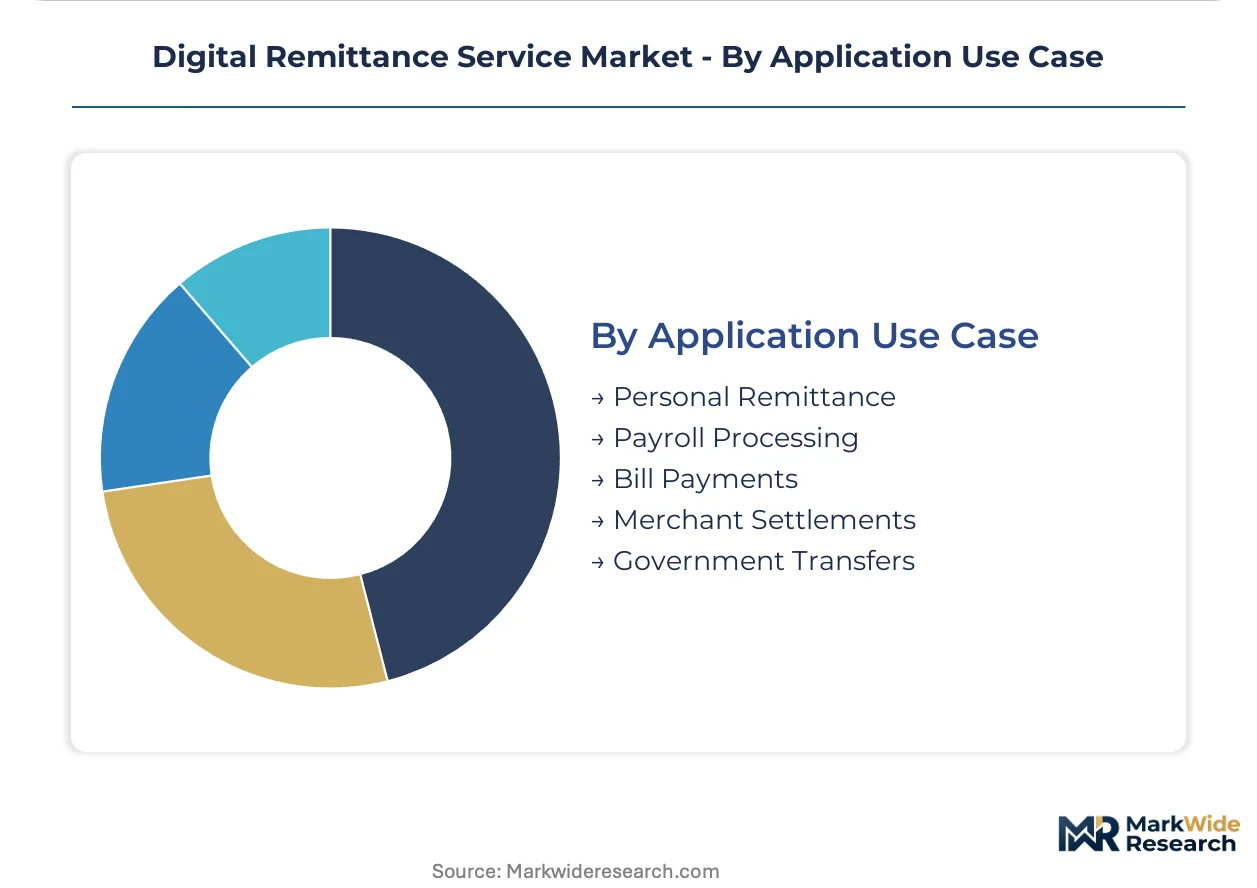
- Personal Remittance:Family support payments from Gulf Cooperation Council states leverage UPI-RBI instant settlement rails. Biometric verification under PSD2 strong authentication standards reduces fraud insurance premiums.
- Payroll Processing:Construction and domestic labor sectors in UAE and Saudi Arabia drive corridor-specific platform specialization. Workforce management software APIs capture sender intent at salary disbursement point.
- Bill Payments:Utility and education fee settlement creates recurring revenue streams with lower customer acquisition costs.
- Merchant Settlements:E-commerce checkout integration competes with card network rails on speed and FX transparency.
- Government Transfers:Social benefit disbursements require highest compliance stack maturity for public sector procurement eligibility.
Personal remittance anchors volume concentration while payroll processing shows the steepest expansion trajectory through SME platform embedding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
RBI anchors the dominant geography through UPI-RBI integration mandating instant settlement rails. Gulf Cooperation Council migrant corridors drive volume concentration. FinCEN and EU PSD2 frameworks jointly shape market access requirements.
United States
Remittance outflows to Latin America and Asia sustain platform specialization in high-frequency corridors. FinCEN's real-time transaction monitoring rules elevate compliance costs for non-bank transmitters. New York and California host dense clusters of licensed money transmitters integrating cloud-based KYC orchestration.
India
Inbound remittances from Gulf Cooperation Council states leverage UPI-RBI rails compressing settlement to sub-minute finality. RBI licensing tiers reserve full bank integration for capitalized incumbents while restricting API-only providers. Mumbai and Bangalore concentrate fintech development centers building compliance automation stacks.
United Arab Emirates
Migrant worker populations from India and Pakistan generate sustained outbound volume requiring mobile wallet last-mile delivery. The central bank's regulatory framework governs money service business licensing and capital requirements. Dubai's financial free zones host regional headquarters for corridor-specialized platforms.
Singapore
ASEAN corridor hub status attracts platforms serving Philippines-to-East Asia family support payments. The Monetary Authority imposes licensing tiers distinguishing full bank integration from closed-loop wallet models. The city-state's fintech district concentrates API-native providers building embedded finance interfaces.
Philippines
Remittance-dependent household economics sustain highest per-capita inbound volume in Southeast Asia. Central bank regulations govern electronic money issuer licensing and foreign exchange controls. Manila and Cebu host dense agent networks managing mobile wallet displacement of cash pickup.
Digital Remittance Service Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the competitive landscape. Incumbent wire providers maintain physical-digital hybrid networks where cash payout remains essential, while API-native platforms capture volume on real-time settlement corridors. Three strategic archetypes dominate: proprietary banking infrastructure builders, embedded checkout ecosystem operators, and compliance-automation specialists. Consolidation pressure intensifies through strategic partnerships with correspondent banks and technology licensing arrangements reducing middleware development burdens.
Among established incumbents, Western Union Holdings, Inc. and MoneyGram International, Inc. occupy positions within physical-digital hybrid archetypes maintaining cash payout networks in infrastructure-constrained markets. Wise plc and PayPal Holdings, Inc. exemplify technology-native archetypes leveraging proprietary infrastructure and embedded ecosystems respectively. These four anchors represent divergent strategic bets on settlement layer control versus distribution reach.
| Leading Market Players |
|---|
| Western Union Holdings, Inc. |
| PayPal Holdings, Inc. |
| Wise plc |
| MoneyGram International, Inc. |
| Remitly Global, Inc. |
| WorldRemit Ltd. |
| Ria Financial Services Ltd. |
| NIUM Pte. Ltd. |
| TransferGo Ltd. |
| Others |
Pricing and Supply Chain Analysis
Sub-minute settlement timelines compress working capital cycles to near-zero inventory positions, concentrating pricing power with platforms controlling real-time rails while forcing batch-dependent providers into defensive margin structures. This lead-time compression favors API-native architectures over legacy correspondent banking stacks.
Pricing Analysis
Gulf-to-India corridor spreads widen substantially between real-time UPI-RBI settlements and traditional wire transfers, with premium pricing attaching to sub-minute finality versus batch-window alternatives. Three-tier pricing structure across premium instant, standard same-day, and economy next-day levels differentiates by settlement velocity and KYC automation depth. Cost compression in economy tiers is intensifying because stablecoin rails threaten fee-based revenue on high-volume corridors. Individual migrant workers show highest price sensitivity, while SME payroll processors absorb premium rates for API-embedded treasury integration.
Supply Chain Analysis
Just-in-time liquidity provisioning dominates operational models, with platforms minimizing prefunded nostro positions through real-time settlement netting. Technology development concentrates in India, Singapore, and the United Arab Emirates, where regulatory sandboxes and fintech licensing frameworks cluster engineering talent. Raw material dependencies center on cloud compute capacity, biometric authentication modules, and encrypted API protocol licenses. Single-source vulnerability runs through three US-headquartered correspondent banks controlling dollar-denominated settlement volume. Distribution runs through embedded finance partnerships within super-apps and workforce management platforms rather than standalone portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineers capable of training machine-learning models for suspicious activity detection remain scarce relative to platform expansion plans, creating acquisition premiums for teams with production-grade compliance automation experience.
For Market Incumbents: Consolidate compliance automation capabilities through targeted technology acquisitions before regulatory density renders manual review stacks economically unviable. Prioritize captive banking infrastructure in India-UAE and Philippines-East Asia corridors where real-time rails command pricing premiums. Absorb API-native competitors or risk volume erosion on high-frequency settlement routes. For New Entrants and Emerging Players: Singapore's MAS licensing fast-track offers the lowest capital barrier to ASEAN corridor entry, particularly for closed-loop wallet models restricted from full bank integration. White-label compliance SaaS partnerships reduce data center investment requirements. Target construction and domestic labor payroll integration within UAE workforce management software as the most penetrable wedge. For Investors and Strategic Acquirers: Carve-out targets emerge from regional bank remittance divisions lacking proprietary technology stacks but holding valuable MSB licenses and corridor-specific customer relationships. Long-term viability favors platforms with automated KYC/AML workflows over manual-dependent alternatives. Watch FinCEN enforcement intensity against non-compliant virtual asset service providers as the signal for consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Compliance Stack Licensing | SaaS-based KYC orchestration allows mid-tier providers to scale without captive infrastructure investment. |
| Embedded Finance API Partnership | Super-app integration captures migrant worker remittance intent at salary disbursement point. |
| Proprietary Banking Infrastructure Buildout | Direct RBI and UPI integration sustains pricing advantages on India-Gulf Cooperation Council corridors. |
| AI-Literate Compliance Team Acquisition | Machine-learning model development capabilities reduce false-positive rates below rule-based alternatives. |
| CBDC Pilot Participation | Bank for International Settlements Project Dunbar access could eliminate correspondent banking layers entirely. |
Research Methodology
The analysis maps real-time transfer, mobile wallet transfer, batch transfer, cross-border transfer, and peer-to-peer transfer segments, each validated through compliance technology officers, remittance platform product managers, correspondent banking relationship leads, and regulatory affairs specialists at licensed money transmitters. Primary interview findings triangulate against secondary sources including FinCEN guidance documents, RBI circulars on UPI-RBI integration, EU PSD2 implementation reports, and Monetary Authority of Singapore licensing frameworks. Bottom-up corridor volume estimates reconcile with top-down market sizing through iterative consistency checks.
Consistency checks validate volume and value outputs against external benchmarks including central bank remittance flow statistics and licensed money transmitter regulatory filings. The analytical framework models deployment model, service type, customer type, application use case, and regional regulatory cluster dimensions across the projection horizon. CAGRs derive from segment-specific growth trajectories weighted by corridor maturity and infrastructure readiness. Forecast inputs incorporate smartphone penetration curves, real-time settlement rail expansion timelines, and compliance automation adoption rates.
The analysis sits within stated boundaries; outcomes outside sustained regulatory support for instant settlement infrastructure or accelerated stablecoin substitution would require recalibration. Forecasts reflect assumptions about correspondent banking concentration, AML screening cost trajectories, and embedded finance channel shift velocity. Revision becomes warranted when FinCEN enforcement intensity or BIS CBDC pilot outcomes cross thresholds that materially alter settlement layer economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
QR Codes Payment Market
Payments
3D Secure Pay Authentication Market
Payments
Electronic Payment Processing Software Market
Payments
Vietnam Mobile Payments Market
Payments
Third Party Payment Market
Payments
France Buy Now Pay Later Services Market
Payments
United Arab Emirates Mobile Payments Market
Payments
India Payment Gateway Market
Payments
Europe Payment Analytics Software Market
Payments
Fingerprint Payment Market
Payments
Proximity Payment Market
Payments
Asia-Pacific Crypto Payment Gateway Market
Payments
Buy Now Pay Later (BNPL) Services Market
Payments
Electronic Toll Collection (ETC) Market
Payments
Credit Card Issuance Services Market
Payments
Global Payments As a Service Market