
 Finland Payments Market | 2026-2036
Finland Payments Market Size, Share, and Industry Trends Forecast 2026-2036
Finland Payments Market Analysis
SME merchant acquirers is bifurcating from large corporate treasury services as the fastest-growing buyer archetype in Finnish payments. OP Financial Group leverages its cooperative banking structure to sustain deep penetration across rural and urban merchant networks. Nets Finland anchors the domestic infrastructure layer through its control of terminal deployment and clearing protocols. Adyen competes aggressively on cross-border e-commerce enablement, extending unified acquiring services to Finnish retailers expanding into Nordic and Continental European markets.
Payments systems encompass the technical infrastructure, protocols, and intermediaries that enable value transfer between transacting parties, operating through authorization networks, settlement rails, and reconciliation engines that process transactions in sub-second latency for digital channels and batch cycles for legacy instruments. The Finland Payments Market spans Credit Card, Debit Card, Mobile Wallet, and Bank Transfer methods, with Mobile Wallet and Bank Transfer gaining structural momentum as instant payment rails displace card dependency among younger demographics and cost-sensitive merchants. Online Payment and Peer-to-peer Payment transaction types are capturing disproportionate growth investment from fintech entrants, while Recurring Payment volumes remain concentrated among utility and subscription service providers with established mandate frameworks.
Finanssivalvonta, the Finnish Financial Supervisory Authority, enforces PSD2 compliance and open banking interface standards that mandate account access APIs for licensed third-party providers, reshaping competitive entry conditions for non-bank payment initiators. The EU AI Act and GDPR impose algorithmic transparency and data localization requirements on automated fraud scoring and customer authentication workflows, elevating compliance costs for cloud-native payment processors. Stakeholders must monitor the European Banking Authority's forthcoming instant payment pricing guidelines and Finanssivalvonta's interpretation of liability frameworks for authorized push payment fraud, as these determinations will redistribute risk capital between merchants, issuers, and infrastructure providers.
Market Dynamics
The EU's instant payment regulation is compressing settlement cycles from T+2 to T+0, forcing Finnish acquirers to rebuild core infrastructure around real-time rails while merchant pricing models fragment between flat-rate and interchange-plus structures.
Growth Catalysts
- Open Banking APIs:Finanssivalvonta's PSD2 enforcement mandates standardized account access interfaces, enabling licensed third-party providers to initiate payments directly from customer bank accounts without card network intermediation.
- SME Merchant Digitization:Helsinki's fintech corridor concentrates venture deployment into merchant onboarding automation, reducing KYC timelines from weeks to hours for small retailers adopting integrated POS-terminal solutions.
- Cross-Border E-commerce:Unified acquiring services spanning Nordic and Continental European markets allow Finnish retailers to process multi-currency transactions through single technical integrations.
Market Restraints
- Cloud Infrastructure Concentration:Hyperscaler dominance in Nordic data center regions creates single-point-of-failure risk for fraud scoring workloads requiring sub-100-millisecond latency.
- Authorized Push Payment Fraud Liability:Unclear allocation of losses between merchants, issuers, and infrastructure providers under Finanssivalvonta's evolving interpretation of PSD2 dispute frameworks elevates risk capital requirements.
- Legacy Core Banking Dependencies:Cooperative banking structures maintain batch-oriented settlement architectures that resist real-time API integration without substantial middleware investment.
Strategic Opportunities
- Rural Merchant Underpenetration:OP Financial Group's cooperative network extends terminal deployment into Lapland and Eastern Finland regions where independent acquirer competition remains thin.
- AI-Act Compliance Automation:Algorithmic transparency mandates for automated fraud scoring create demand for explainable machine learning tooling that documents decision pathways for regulatory audit.
- Subscription Billing Infrastructure:Utility and telecommunications providers with established SEPA mandate frameworks seek white-label recurring payment orchestration for adjacent vertical software platforms.
Industry Challenges
- Instant Payment Engineering Talent:Scarcity of engineers experienced in ISO 20022 message formats and real-time gross settlement system integration compresses development timelines for legacy processor modernization.
- GDPR Data Localization:Cross-border transaction data routing requirements complicate cloud-native processor architectures that rely on distributed edge computing for latency optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Finland Payments Market |
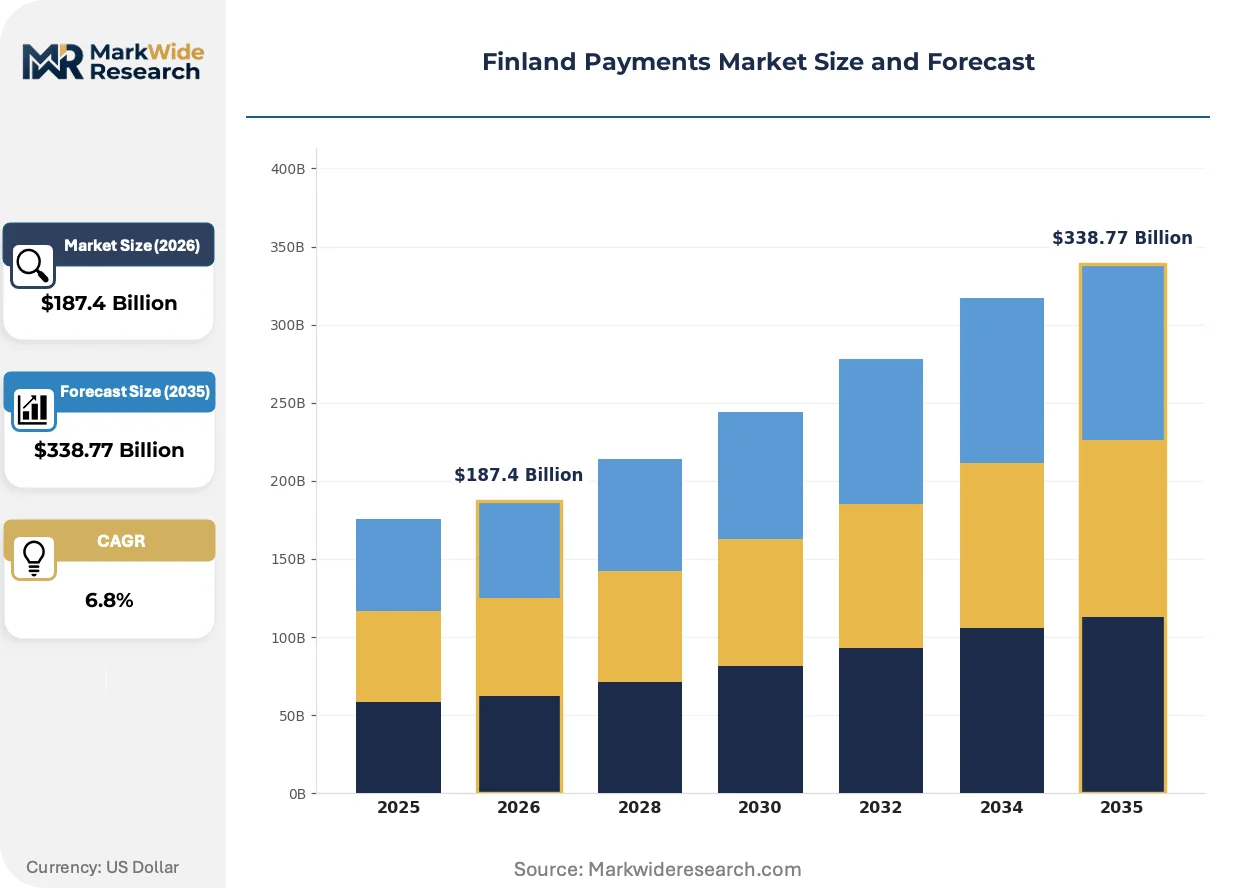
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Method: Credit Card, Debit Card, Mobile Wallet, Bank Transfer End User: Consumers, SMEs, Corporates, E-commerce Transaction Type: Online Payment, In-store Payment, Recurring Payment, Peer-to-peer Payment Service Provider: Fintech, Banks, Payment Gateways, Traditional Banks |
| Companies Covered | Adyen, S-Pankki Oyj, OP Financial Group, Klarna Bank AB, Nets Finland, Nordea Bank Abp, Paytrail Oyj, Epassi, Danske Bank A/S, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Finland Payments Market Emerging Trajectories
Finnish payment infrastructure is converging around real-time account-to-account settlement, with merchant-facing innovation prioritizing invisible authentication and embedded finance integration over traditional card-present experiences.
Biometric authentication hardware is miniaturizing into smartphone-native facial recognition and fingerprint sensors, eliminating dedicated POS terminal peripherals. Finnish merchants in quick-service retail and transit verticals are adopting these standards at pace, with pilot deployments exceeding contactless card volumes in Helsinki metro corridors. The technology is miniaturizing fraud risk vectors by binding transaction authorization to device-bound cryptographic credentials rather than static card data.
The EU AI Act imposes documentation requirements on automated fraud scoring systems, mandating human-reviewable audit trails for algorithmic decisions affecting payment authorization. Finnish processors must reengineer black-box machine learning models into interpretable rule sets or ensemble architectures with explicit feature attribution. Merchants handling high-value B2B transactions face the steepest compliance costs, as their fraud models historically relied on opaque behavioral biometrics.
Merchant procurement of payment services is compressing from multi-year processor contracts toward modular, API-first component sourcing. Finnish retailers unbundle gateway, risk, and acquiring functions to optimize unit economics across transaction types, with subscription merchants prioritizing mandate management capabilities over authorization speed. This pattern is most visible among Helsinki's software-as-a-service sector, where finance teams negotiate separate contracts for domestic SEPA and international card acceptance.
Finland Payments Market Segmentation
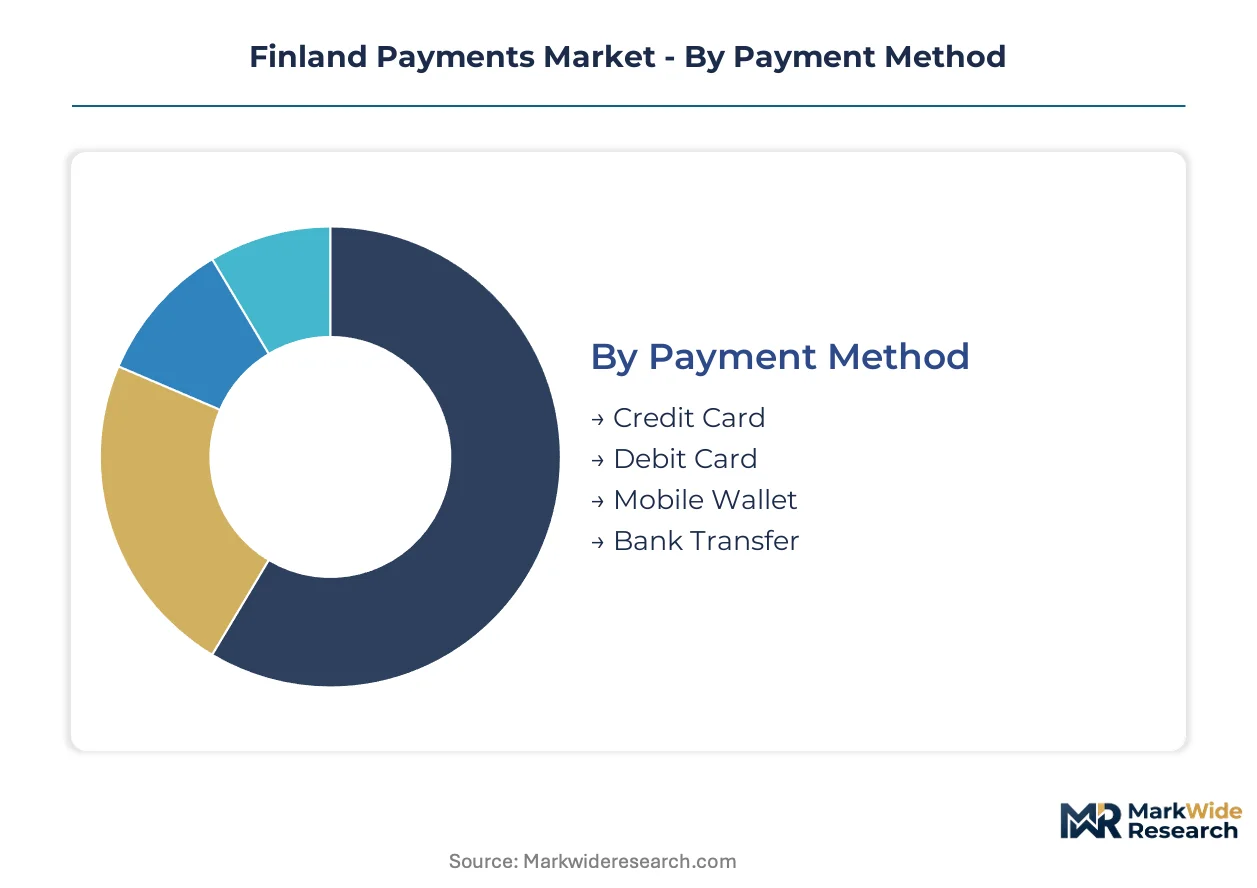
Finnish payment infrastructure exhibits sharp geographic concentration in Helsinki's fintech corridor, with rural Lapland and Eastern Finland presenting distinct service gaps. Segmentation reveals how instant payment regulation and cooperative banking structures fragment competitive entry across transaction types and merchant tiers.
Payment Method:
Domestic rails dominate consumer-facing transactions, while cross-border e-commerce merchants rely on international card networks for Nordic and Continental European settlement.
- Credit Card:Interchange-plus pricing structures prevail among large retailers processing multi-currency transactions. Demand concentrates in Helsinki metro corridors where contactless terminals exceed contact card volumes.
- Debit Card:Real-time authorization networks process sub-second verification through domestic clearing protocols. Finnish consumers favor debit for everyday purchases, with penetration deepest among cost-sensitive demographics in urban merchant networks.
- Mobile Wallet:Device-bound cryptographic credentials displace static card data in quick-service retail and transit verticals.
- Bank Transfer:SEPA instant credit transfers gain structural momentum as PSD2 APIs enable direct account-to-account settlement without card intermediation.
Debit Card holds the largest share; momentum sits with Bank Transfer.
End User:
Merchant size determines pricing model fragmentation, with flat-rate structures dominating micro-merchants and interchange-plus prevailing among volume processors.
- Consumers:Individual transaction behavior shifts toward invisible authentication and biometric authorization in smartphone-native environments.
- SMEs:Automated onboarding reduces KYC timelines from weeks to hours, enabling rapid terminal deployment across Helsinki's software-as-a-service sector. Demand concentrates among merchant acquirers seeking unified domestic and cross-border acceptance.
- Corporates:Treasury services require batch-oriented settlement architectures resistant to real-time API integration without substantial middleware investment.
- E-commerce:Multi-currency transaction processing through single technical integrations drives vendor selection among retailers expanding into Nordic markets.
SMEs anchor volume concentration; E-commerce climbs the fastest.
Transaction Type:
Settlement cycle compression from T+2 to T+0 forces infrastructure rebuilds around real-time rails, with legacy batch systems persisting in recurring mandate frameworks.
- Online Payment:API-first component sourcing unbundles gateway, risk, and acquiring functions for unit economics optimization.
- In-store Payment:Terminal deployment and clearing protocol control concentrate infrastructure investment in domestic acquirer networks.
- Recurring Payment:Established SEPA mandate frameworks among utility and telecommunications providers create white-label orchestration demand for adjacent vertical software platforms. Volume concentrates where mandate management capabilities outweigh authorization speed in procurement decisions.
- Peer-to-peer Payment:Licensed third-party providers initiate direct account transfers through PSD2-mandated APIs, bypassing card network intermediation. Growth concentrates among younger demographics in Helsinki fintech clusters.
Recurring Payment holds the largest share; Peer-to-peer Payment gains share fastest.
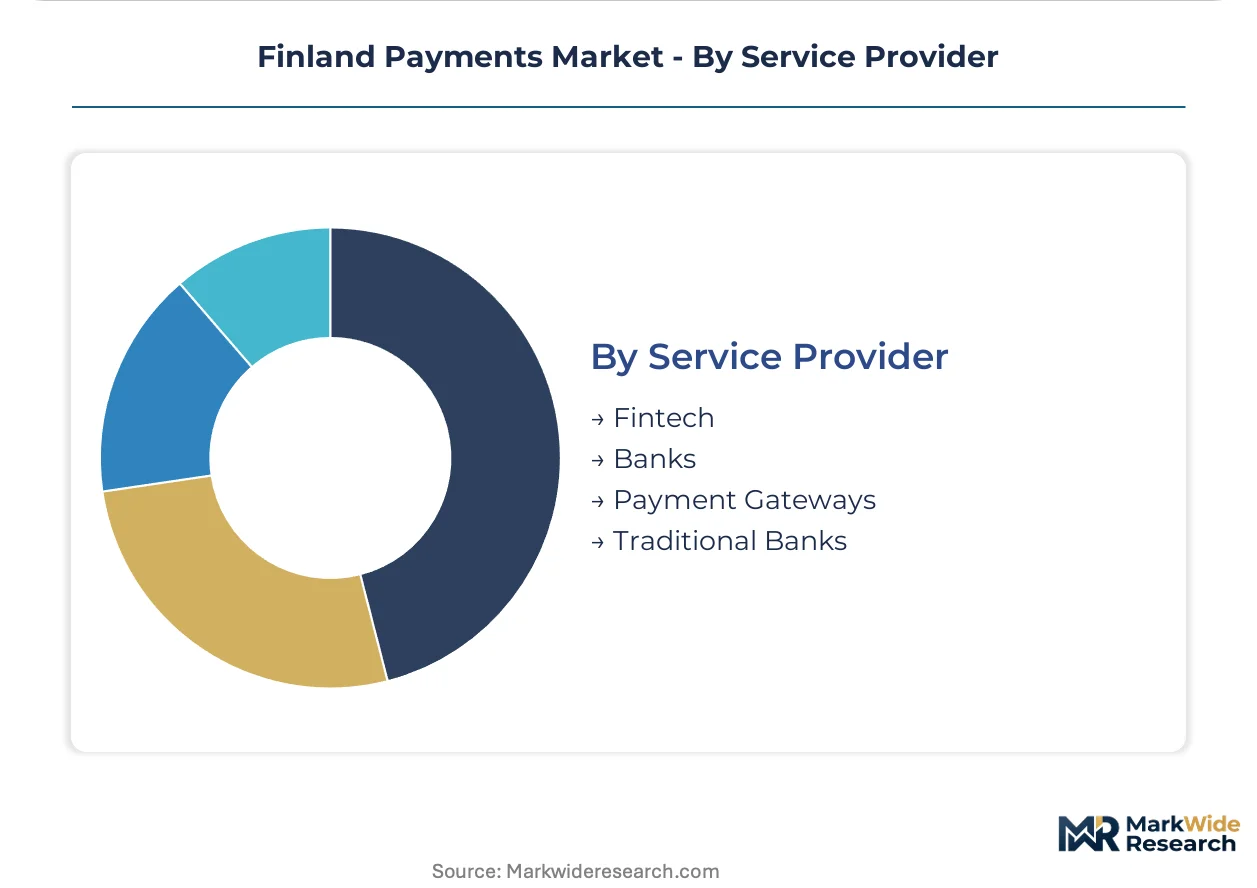
Service Provider:
Regulatory licensing requirements under Finanssivalvonta reshape competitive entry, with PSD2 compliance costs elevating capital barriers for non-bank entrants.
- Fintech:Cloud-native processors automate fraud scoring with sub-100-millisecond latency requirements, though hyperscaler concentration creates single-point-of-failure risk in Nordic data center regions.
- Banks:Cooperative structures sustain deep penetration across rural and urban merchant networks through legacy branch infrastructure.
- Payment Gateways:Modular service procurement compresses contract duration from multi-year terms toward API-first component sourcing.
- Traditional Banks:Batch-oriented core banking dependencies resist real-time integration without substantial middleware investment, particularly in Eastern Finland cooperative networks.
Banks hold the largest share; Fintech shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Finnish payment flows concentrate through Helsinki fintech clusters while extending terminal infrastructure into peripheral regions. Cross-border settlement corridors link Nordic cooperative banks to Continental European clearing networks.
Helsinki Capital Region
SEPA instant credit transfers dominate SME merchant acquiring through API-first onboarding platforms. Finanssivalvonta mandates PSD2 compliance for all licensed payment initiators operating within the metropolitan zone. Helsinki's fintech corridor concentrates venture deployment into invisible authentication and embedded finance integration.
Pirkanmaa and Tampere
Manufacturing supply chains drive B2B payment orchestration demand among industrial distributors. The Finnish Financial Supervisory Authority enforces open banking interface standards for third-party providers serving corporate treasury functions. Tampere's technology cluster hosts processors specializing in subscription billing infrastructure for SaaS verticals.
Southwest Finland and Turku
Maritime logistics corridors generate cross-border e-commerce settlement volumes for Nordic retail expansion. EU AI Act algorithmic transparency requirements reshape automated fraud scoring deployments across port-city merchant networks. Turku's startup ecosystem incubates peer-to-peer payment applications leveraging PSD2-mandated account access.
Lapland
Tourism-dependent merchants require resilient terminal deployment across remote Arctic settlements. Cooperative banking structures extend rural penetration where independent acquirer competition remains thin. Rovaniemi's seasonal retail peaks stress-test real-time settlement infrastructure against batch-oriented legacy dependencies.
Eastern Finland
Border commerce with Russia historically structured regional payment flows now rerouting through Baltic corridors. GDPR data localization complicates cloud-native processor architectures relying on distributed edge computing. Joensuu and Kuopio merchant networks represent underpenetrated terrain for unified domestic and cross-border acquiring services.
Finland Payments Market Vendor Landscape
Player mix skews toward cooperative banking networks with substantial infrastructure control. Market structure concentrates around legacy terminal deployment and clearing protocol ownership, with fintech entrants fragmenting service procurement patterns. Two strategic archetypes dominate: domestic infrastructure incumbents with cooperative ownership structures, and cross-border specialists enabling Nordic retail expansion. Competitive moves center on API-first component unbundling and middleware investment for real-time rail integration.
Among cooperative banking networks, OP Financial Group anchors rural and urban merchant penetration through legacy branch infrastructure. Nets Finland occupies the infrastructure layer through terminal deployment and clearing protocol control. Adyen represents the cross-border archetype, extending unified acquiring services to Finnish retailers expanding into Nordic and Continental European markets.
| Leading Market Players |
|---|
| Adyen |
| S-Pankki Oyj |
| OP Financial Group |
| Klarna Bank AB |
| Nets Finland |
| Nordea Bank Abp |
| Paytrail Oyj |
| Epassi |
| Danske Bank A/S |
| Others |
Supply Flow & Price Mechanics
ISO 20022 migration timelines spanning 18-24 months compress vendor selection windows while amplifying pricing power for processors with pre-certified message-handling infrastructure. This lead-time pressure concentrates procurement decisions among acquirers capable of immediate real-time rail integration, squeezing margins for middleware-dependent providers.
Pricing Analysis
Legacy-batch versus real-time API pricing gaps exceed 40 basis points at the transaction level, with flat-rate structures dominating micro-merchant acquiring while interchange-plus prevails among volume processors. Price differentiation hinges on authorization latency guarantees and SEPA instant mandate management capabilities. Pricing pressure stems from EU instant payment regulation mandating T+0 settlement without corresponding interchange adjustment. SME acquirers exhibit highest price sensitivity; large retailers with multi-currency exposure prioritize technical integration speed over unit cost.
Supply Chain Analysis
Nordic data center concentration in Stockholm and Copenhagen regions creates hyperscaler chokepoints for sub-100-millisecond fraud scoring workloads. Cloud infrastructure draws from Amazon Web Services, Microsoft Azure, and Google Cloud Platform regions; terminal hardware sources from Ingenico and Verifone manufacturing networks in China and Malaysia. Single-source vulnerability runs through SWIFT message relay dependencies for cross-border settlement. Distribution runs through Nets Finland's domestic terminal deployment network and OP Financial Group's cooperative branch infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
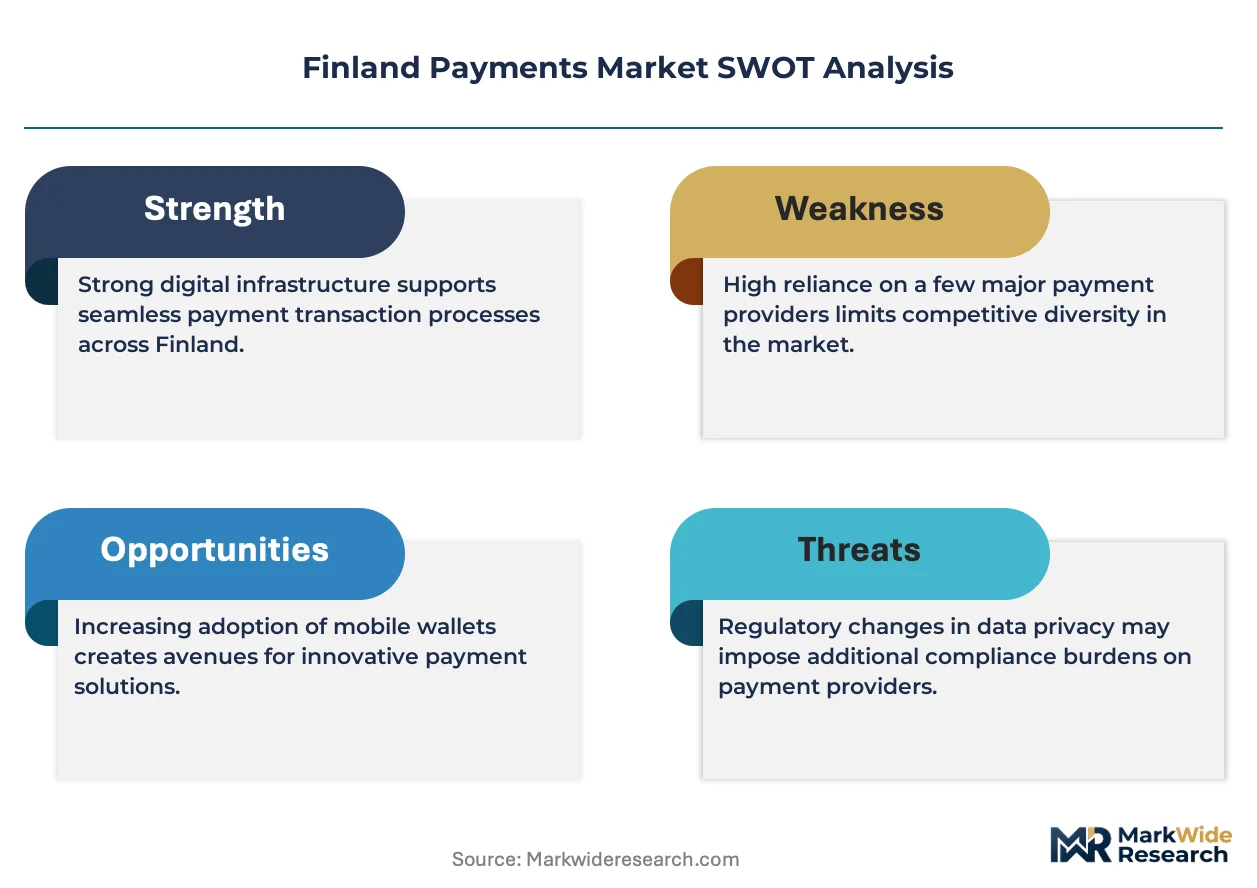
Finnish payment incumbents face substitution defense against account-to-account rails disintermediating card networks, requiring infrastructure repositioning before PSD2-mandated instant payment ubiquity erodes interchange revenue pools.
For Market Incumbents: Compound defensive positioning through middleware acquisition for real-time core banking integration and API-first component unbundling to retain merchant relationships against fintech entrants. Legacy cooperative structures must neutralize the threat of cloud-native processors by accelerating ISO 20022 certification timelines and deepening rural terminal penetration where independent competition remains thin. For New Entrants and Emerging Players: PSD2 license fast-tracks through Finanssivalvonta's regulatory sandbox offer lowest barrier entry into Helsinki fintech clusters. White-space targets concentrate in rural Lapland merchant acquiring and subscription billing orchestration for vertical SaaS platforms. Go-to-market execution should anchor on automated KYC compression and invisible authentication integration for quick-service retail verticals. For Investors and Strategic Acquirers: Carve-out targets emerge from cooperative banking groups seeking to monetize non-core payment infrastructure assets amid real-time rail investment burdens. Long-term viability favors processors with pre-built AI-Act compliance tooling and explainable fraud scoring architectures. Watch Finanssivalvonta's authorized push payment liability determinations as the inflection signal for risk capital redistribution across the value chain.| Strategic Initiative | Industry Significance |
|---|---|
| Real-Time Rail Integration | ISO 20022 message handling capability separates viable acquirers from legacy-batch processors facing obsolescence. |
| API-First Component Unbundling | Modular gateway-risk-acquiring procurement patterns fragment multi-year contracts into optimized unit economics. |
| AI-Act Compliance Automation | Explainable machine learning tooling documentation satisfies Finanssivalvonta audit requirements for fraud scoring algorithms. |
| Rural Terminal Deployment | OP Financial Group's cooperative network extension into Lapland captures underpenetrated merchant segments. |
| Cross-Border Acquiring Consolidation | Unified Nordic and Continental European settlement services reduce technical integration burden for expanding retailers. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of Finanssivalvonta regulatory filings, SEPA instant payment volume disclosures, and EU AI Act implementation guidance. Primary interviews engaged payment infrastructure executives, merchant acquiring specialists, open banking API developers, and cooperative banking technology officers. Secondary validation drew from European Banking Authority consultation papers, Nordic data center capacity reports, and PSD2 compliance audit documentation. Bottom-up transaction volume modeling triangulated against top-down macroeconomic payment flow estimates.
Segmentation dimensions modeled span payment method, end-user archetype, transaction type, and service provider category across the analysis window. The analytical framework projected value expansion through CAGR derivation from historical rail adoption curves and instant payment regulatory enforcement timelines. Forecast inputs incorporated SEPA instant penetration assumptions and merchant onboarding automation adoption rates without specifying year-over-year breakpoints.
Decision-makers should treat outputs as directional under assumptions of sustained EU instant payment regulation enforcement and stable Finanssivalvonta PSD2 interpretation; material deviation in authorized push payment liability allocation or hyperscaler infrastructure concentration would warrant model refresh. Forecasts reflect base-case assumptions regarding cooperative banking modernization investment and fintech venture deployment continuity. Practitioners should keep alternative scenarios live as EU AI Act algorithmic transparency enforcement intensity and GDPR data localization requirements evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Remote Deposit Capture Market
Payments
Mobile Payment Market
Payments
Japan Virtual Cards Market
Payments
Asia-Pacific Payment Analytics Software Market
Payments
Mexico POS Terminals Market
Payments
France Payments Market
Payments
Asia Pacific POS Terminal Market
Payments
India Gift Card and Incentive Card Market
Payments
Canada Real Time Payments Market
Payments
Payment Analytics Software Market
Payments
India Real Time Payments Market
Payments
Digital Transaction Management Market
Payments
Global Payment Gateways Market
Payments
Enterprise Payment Software Market
Payments
Global Real-Time Payments Market
Payments
In Vehicles Payment Market