
 MENA Digital Payments Market | 2026-2036
MENA Digital Payments Market Size, Share, and Industry Trends Forecast 2026-2036
MENA Digital Payments Market Foresight
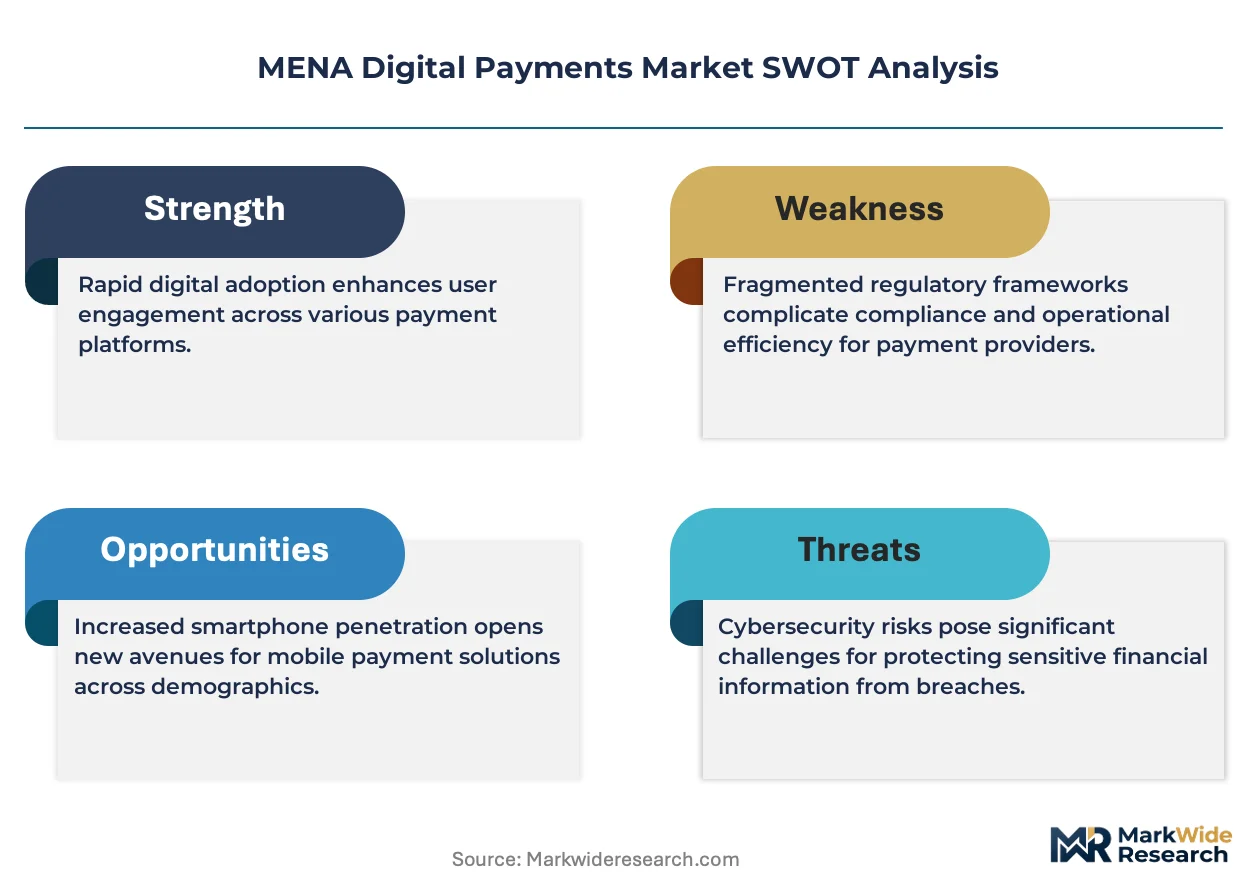
Multi-source gateway partnerships is repositioning how merchants across the Gulf acquire payment capabilities. Network International leverages its regional processor network to dominate merchant acquiring in the UAE and Saudi Arabia. Fawry sustains its position through agent-based cash collection networks that extend digital payment access into Egypt's underserved governorates. STC Pay anchors Saudi wallet adoption through telecom-integrated user onboarding and government disbursement linkages.
MENA digital payments encompass electronic fund transfer systems, mobile wallet architectures, and tokenized card networks that route transactions through regional switches and international schemes. These systems rely on ISO 20022 messaging standards, real-time gross settlement integration with central bank infrastructures, and PCI-DSS Level 1 certification for card data environments. Mobile wallet penetration is outpacing card growth across North African corridors where banking infrastructure remains sparse. Contactless payment terminals are expanding fastest in Gulf hospitality and retail sectors, though peer-to-peer remittance flows generate the highest transaction frequency volumes.
SAMR in Saudi Arabia and the UAE's central bank impose licensing tiers that separate payment service providers from full banking charters, shaping capital requirements and foreign ownership limits. Egypt's CBE mandates interoperability between mobile wallets and national switch infrastructure, while GDPR-aligned data localization rules across Gulf states constrain cross-border transaction hosting. Stakeholders must monitor how central bank digital currency pilots in the UAE and Saudi Arabia reshape clearing and settlement economics for private wallet operators.
Market Dynamics
Central bank digital currency pilots across the Gulf are compressing clearing timelines for private wallet operators while forcing interoperability investments that reshape capital allocation across the MENA payments stack.
Growth Catalysts
- Real-time settlement infrastructure:SAMR's licensing framework in Saudi Arabia mandates direct integration with the Saudi Payments Network, accelerating merchant onboarding velocity for licensed operators.
- Agent-based cash digitization:Egypt's CBE interoperability mandates between mobile wallets and national switch infrastructure extend financial access into governorates where banking penetration remains minimal.
- Telecom-wallet convergence:STC Pay's government disbursement linkages demonstrate how mobile network operator channels reduce customer acquisition costs for digital wallet penetration.
Market Restraints
- Data localization compliance:GDPR-aligned hosting requirements across Gulf states fragment transaction processing architecture and inflate infrastructure capex for cross-border operators.
- Foreign ownership caps:UAE central bank licensing tiers restrict non-Gulf capital participation in payment service provider categories below full banking charters.
- Legacy cash preference:Egypt's informal economy sustains paper-based settlement for B2B trade, delaying wallet adoption in high-frequency commercial corridors.
Strategic Opportunities
- Underserved North African corridors:Morocco's unbanked rural populations present white space for agent-network wallet models proven in Egyptian governorates.
- Hospitality contactless expansion:Dubai's smart city infrastructure investments create concentrated demand for NFC terminal deployment across hotel and retail clusters.
- Cross-border remittance tokenization:Regional switch integration with international schemes enables corridor-specific pricing compression for South Asian labor flows.
Industry Challenges
- ISO 20022 migration complexity:Legacy core banking systems across Jordanian and Lebanese institutions require multi-year transformation timelines to achieve messaging standard compliance.
- PCI-DSS certification bottlenecks:Level 1 certification capacity constraints in the Gulf create queue delays for new market entrants seeking card data environment authorization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MENA Digital Payments Market |
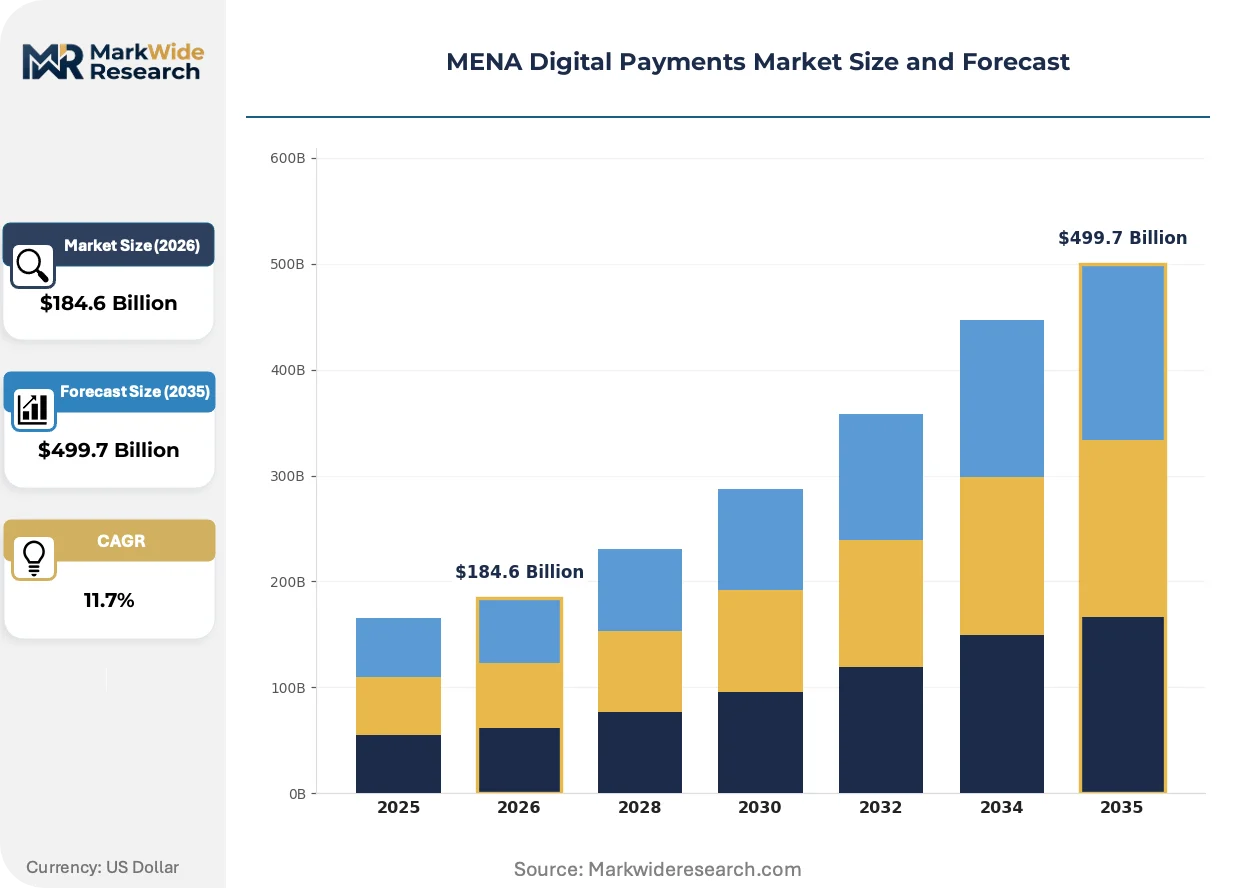
| Market Size in 2026 | $184.6 Billion |
| Market Size in 2035 | $499.7 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Payment Mode: Credit Card, Debit Card, Mobile Wallet, Bank Transfer End User Segment: Retail, E-commerce, Hospitality, Transportation Transaction Type: Online Payment, In-store Payment, Contactless Payment, Peer-to-Peer Payment Security Feature: Tokenization, Biometrics, Two-Factor Authentication, Encryption |
| Companies Covered | Network International, Apple, Visa, STC Pay, Google, Mastercard, Samsung Electronics, Fawry, PayPal, Others |
| Regions Covered | MENA: Saudi Arabia, UAE, Qatar, Kuwait, Egypt, Morocco, Algeria, Tunisia, Rest of MENA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MENA Digital Payments Market Shifts & Advancements
Biometric authentication protocols and tokenized credential architectures are displacing static PIN verification across high-value transaction corridors, compressing fraud incidence while elevating infrastructure investment requirements for authentication service layers.
Tokenized card networks are integrating dynamic cryptogram generation with host card emulation, enabling smartphone-based contactless payments without physical plastic issuance. UAE hospitality operators are deploying these capabilities fastest, eliminating card-present hardware dependencies for guest checkout. This architecture is integrating with property management systems to compress authorization latency below 300 milliseconds.
SAMR's tightened capital reserve requirements for fintech operators are forcing balance sheet restructuring among Saudi payment service providers. The regulation elevates minimum liquidity thresholds above prior central bank guidelines, compressing available capital for technology investment. Licensed operators are responding by consolidating merchant acquiring portfolios to achieve scale economies against fixed compliance costs.
Merchant procurement of payment gateway services is fragmenting across multi-source partnerships rather than single-vendor consolidation. Gulf retail chains are unbundling acquiring, processing, and fraud management into separate supplier relationships. This pattern is most visible in Abu Dhabi's regulatory sandbox environment, where pilot licenses enable rapid vendor rotation without full charter requirements.
MENA Digital Payments Market Segmentation
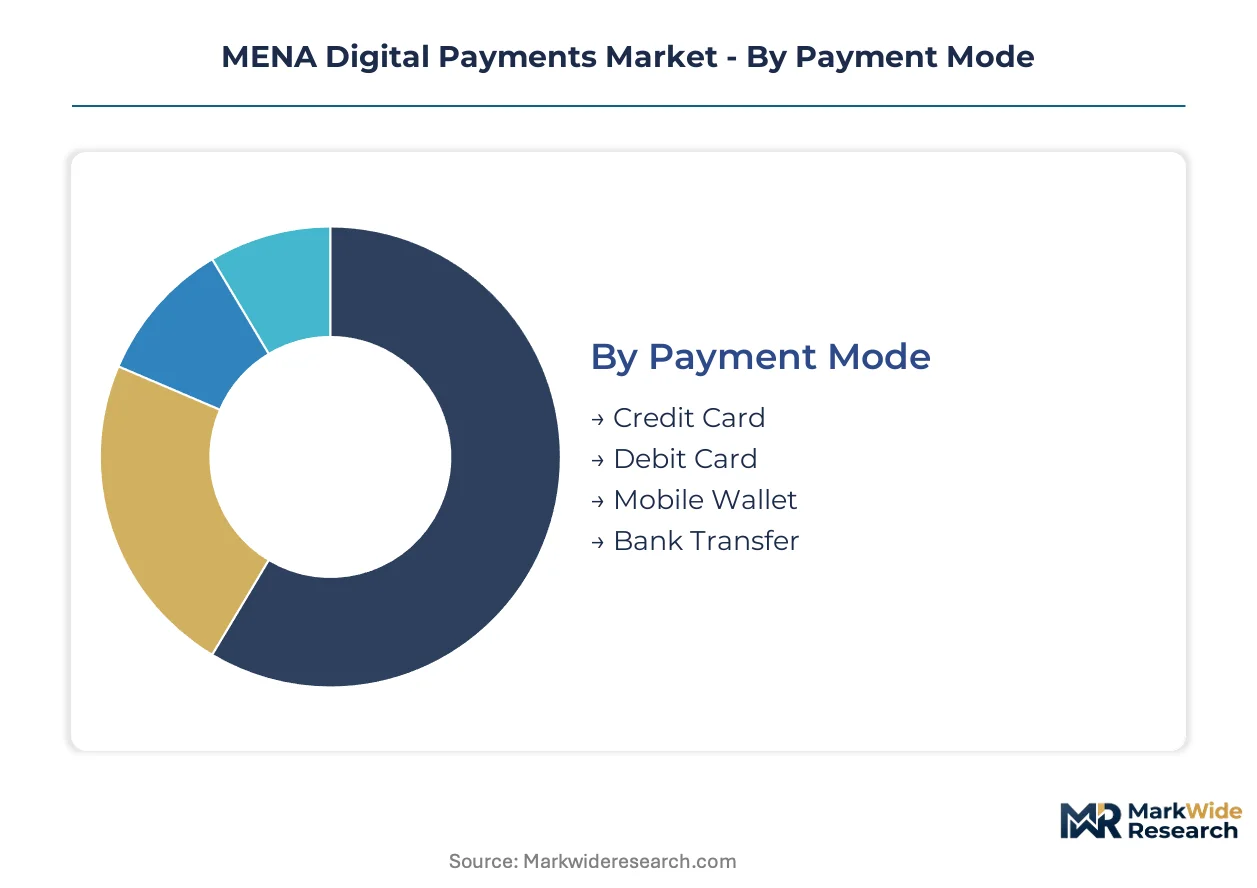
Segmentation across the MENA Digital Payments Market reveals how transaction infrastructure fragments between legacy card rails and mobile-native architectures. Each dimension exposes different competitive moats: payment mode determines capital intensity, end-use shapes merchant acquisition economics, and security tiers separate compliant operators from sandbox-limited entrants.
Payment Mode:
Integration depth varies sharply—mobile wallets embed directly into super-app ecosystems while card networks require ISO 20022 middleware and central bank switch connectivity.
- Credit Card:Plastic-based revolving credit instruments route through regional switches with international scheme interoperability. Demand concentrates in UAE hospitality and Saudi retail corridors where foreign tourist volumes sustain card-present transaction density.
- Debit Card:Direct-account-linked payment instruments with real-time balance verification. Egyptian and Moroccan banks are pushing debit issuance to reduce cash handling costs in branch networks.
- Mobile Wallet:Smartphone-hosted stored-value accounts with QR and NFC acceptance capabilities. STC Pay and similar telecom-anchored wallets demonstrate standalone deployment without legacy banking infrastructure dependencies.
- Bank Transfer:Account-to-account push payments through real-time gross settlement systems. SAMR licensing mandates direct Saudi Payments Network integration for licensed operators.
Volume placements concentrate in Debit Card; the faster expansion belongs to Mobile Wallet.
End User Segment:
Customer acquisition cost tiers separate these segments—hospitality and transportation demand instant onboarding while retail and e-commerce tolerate longer KYC cycles.
- Retail:Brick-and-mortar merchant acceptance spanning supermarkets, convenience stores, and specialty shops. Dubai's smart city terminal deployment programs are compressing NFC activation timelines across mall clusters.
- E-commerce:Remote card-not-present transactions through gateway-integrated checkout flows. Saudi platform operators are unbundling acquiring and fraud management into separate supplier relationships.
- Hospitality:Hotel, restaurant, and entertainment venue payment acceptance with tokenized guest checkout. UAE hospitality operators are eliminating card-present hardware through host card emulation.
- Transportation:Transit and logistics corridor payments including fuel, tolls, and ride-hailing. Contactless penetration is climbing fastest in Riyadh and Jeddah metro integration pilots.
Transaction density peaks in Retail; hospitality contactless deployment is climbing the fastest.
Transaction Type:
Settlement velocity requirements create structural separation—peer-to-peer and contactless demand instant confirmation while online and in-store tolerate batch processing.
- Online Payment:Remote digital checkout through browser or app-hosted interfaces. Egyptian e-commerce platforms are accelerating wallet-based adoption to reduce card decline rates.
- In-store Payment:Physical terminal-present transactions with chip or magnetic stripe verification. Legacy cash preference in Jordanian and Lebanese informal commerce delays terminal saturation.
- Contactless Payment:NFC or QR tap-to-pay with sub-300-millisecond authorization latency. Gulf retail chains are deploying these capabilities fastest in Abu Dhabi's regulatory sandbox environment.
- Peer-to-Peer Payment:Individual-to-individual fund transfers through wallet or bank rails. South Asian labor remittance corridors generate the highest transaction frequency volumes across the region.
Settlement volume concentrates in Online Payment; peer-to-peer remittance flows are gaining share fastest.
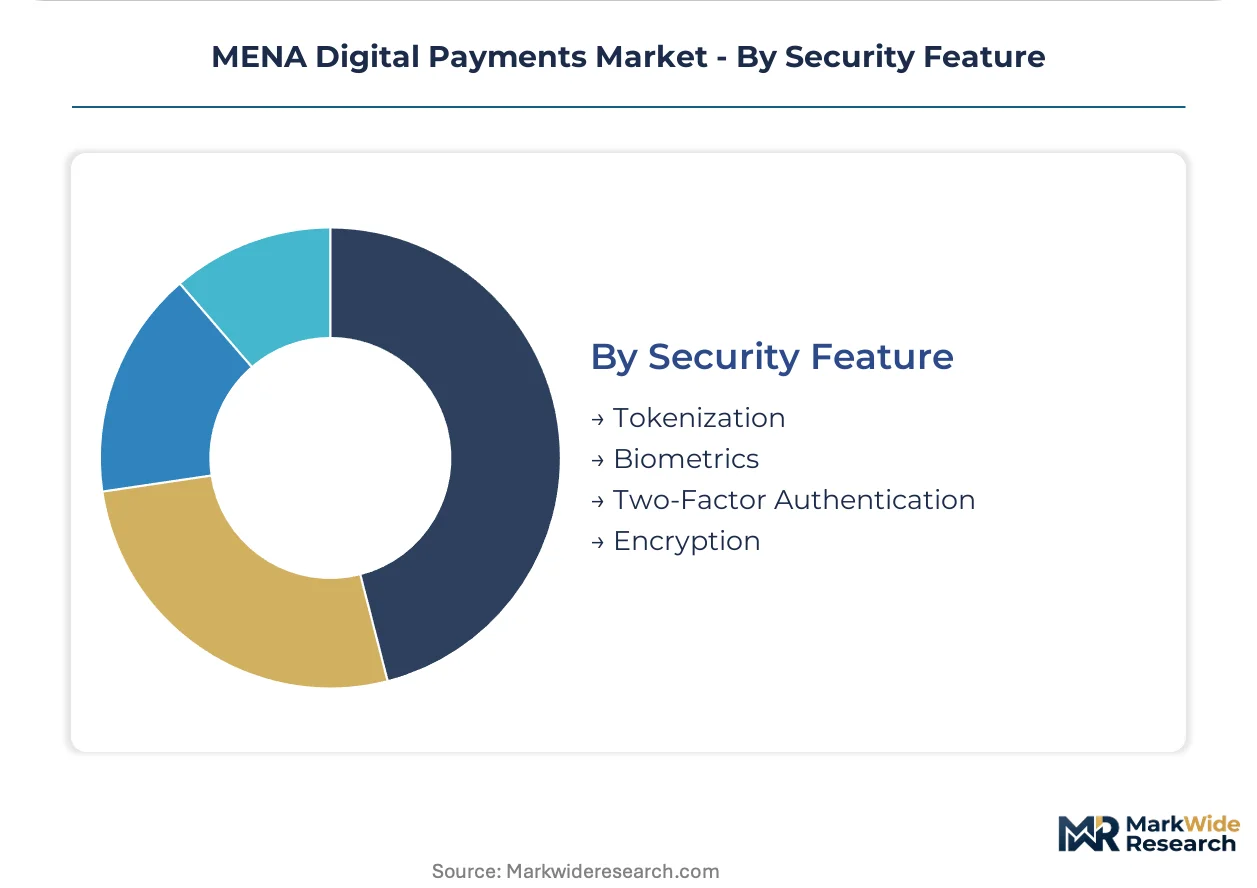
Security Feature:
Compliance cost tiers separate these capabilities—biometrics and tokenization require PCI-DSS Level 1 certification while encryption and two-factor authentication operate under lighter attestations.
- Tokenization:Dynamic credential substitution replacing static primary account numbers. UAE hospitality operators are integrating tokenized guest checkout with property management systems.
- Biometrics:Fingerprint, facial, or iris verification for transaction authorization. Saudi SAMR frameworks are mandating biometric KYC for wallet onboarding above threshold limits.
- Two-Factor Authentication:Secondary verification through SMS, email, or hardware token. Egyptian CBE interoperability mandates require 2FA for wallet-to-bank transfers.
- Encryption:Transport and data-at-rest cryptographic protection for cardholder environments. PCI-DSS certification bottlenecks in the Gulf are creating queue delays for encryption infrastructure upgrades.
Deployment breadth concentrates in Encryption; biometric authentication protocols are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transaction density concentrates in the UAE and Saudi Arabia, where smart city infrastructure and regulatory sandboxes compress merchant onboarding timelines for licensed payment operators. Egypt and Morocco anchor North African expansion through agent-based cash digitization networks that extend financial access beyond formal banking corridors.
United Arab Emirates
Dubai's smart city terminal deployment programs and Abu Dhabi's regulatory sandbox environment concentrate hospitality contactless adoption and multi-source gateway procurement. The central bank's licensing tiers separate payment service providers from full banking charters, shaping foreign ownership limits and capital requirements. Dubai International Financial Centre hosts regional headquarters for processors seeking Gulf market access.
Saudi Arabia
Telecom-integrated wallet onboarding and government disbursement linkages accelerate digital payment penetration in Riyadh and Jeddah. SAMR mandates direct Saudi Payments Network integration for licensed operators, tightening capital reserve and KYC rules above prior central bank guidelines. Riyadh metro integration pilots drive contactless transit payment adoption across transportation corridors.
Egypt
Agent-based cash collection networks extend mobile wallet access into underserved governorates where banking penetration remains minimal. The Central Bank of Egypt mandates interoperability between mobile wallets and national switch infrastructure, forcing cross-platform settlement standardization. Cairo and Alexandria anchor e-commerce platform growth that accelerates wallet-based checkout adoption.
Morocco
Unbanked rural populations present expansion terrain for agent-network wallet models proven in Egyptian governorates. The country's national banking regulator imposes interoperability requirements that mirror regional standardization trends. Casablanca and Rabat concentrate merchant acquiring infrastructure while rural corridors lag in terminal deployment density.
Jordan
Legacy core banking systems require multi-year transformation timelines to achieve ISO 20022 messaging standard compliance, delaying real-time settlement integration. The central bank's regulatory framework shapes capital requirements for payment service providers seeking licensing. Amman hosts regional processing centers that route transactions through Levantine corridor switches.
MENA Digital Payments Market Competitive Landscape
Multi-source gateway partnerships dominate the current landscape, fragmenting merchant procurement across separate acquiring, processing, and fraud management supplier relationships. The vendor base spans three tiers: international scheme operators with regional switch integration, telecom-anchored wallet providers leveraging subscriber bases for user onboarding, and processor networks dominating merchant acquiring through geographic density. Consolidation pressures concentrate among Saudi payment service providers restructuring balance sheets against SAMR's elevated liquidity thresholds. Competitive positioning depends on regulatory sandbox access and central bank digital currency pilot participation.
Within the telecom-wallet convergence archetype, STC Pay exemplifies subscriber-base leverage for government disbursement linkages. Network International and Fawry occupy distinct positions in the merchant-acquiring hierarchy—Network International through regional processor density in the UAE and Saudi Arabia, Fawry through agent-network reach into Egypt's underserved governorates. These three anchors demonstrate how licensing tier access and infrastructure integration separate scalable operators from sandbox-limited entrants.
| Leading Market Players |
|---|
| Network International |
| Apple |
| Visa |
| STC Pay |
| Mastercard |
| Samsung Electronics |
| Fawry |
| PayPal |
| Others |
Supply & Pricing Matrix
PCI-DSS Level 1 certification costs cascade through the MENA payments stack, elevating entry thresholds for wallet operators while compressing margins for merchant acquirers competing on transaction fee compression.
Pricing Analysis
Volume-heavy transaction processing separates from high-margin value-added services across the MENA payments landscape. Three-tier pricing structure across enterprise-grade acquiring, mid-market gateway services, and SME aggregator models dominates procurement patterns. Price differentiation hinges on SAMR licensing tier and real-time settlement capability. Pricing pressure stems from STC Pay and telecom-wallet convergence driving zero-fee peer-to-peer corridors. SME merchants exhibit highest price sensitivity; hospitality operators in Dubai tolerate premium tiers for sub-300-millisecond authorization latency.
Supply Chain Analysis
Regional distribution centers for payment terminals cluster in Dubai's Jebel Ali corridor and Riyadh's logistics zones, feeding hub-and-spoke deployment across Gulf retail clusters. Hardware manufacturing concentrates in China, South Korea, and Taiwan; software development localizes in UAE and Saudi Arabia. Supply chain risk centers on single-source vulnerability for NFC terminal chipsets amid semiconductor allocation constraints. Distribution runs through Network International's regional processor density and Fawry's agent-network last-mile reach into underserved governorates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressures are intensifying as SAMR's elevated liquidity thresholds force smaller Saudi payment service providers into distressed restructuring or acquisition.
For Market Incumbents: To counter telecom-wallet convergence eroding traditional acquiring margins, Network International and regional processors should deepen backward integration into tokenization infrastructure while expanding ISO 20022 middleware capabilities for Jordanian and Lebanese bank transformation timelines. SAMR licensing tier maintenance requires balance sheet restructuring that favors scale economies through merchant portfolio consolidation. For New Entrants and Emerging Players: Abu Dhabi's regulatory sandbox environment opens a window for rapid vendor rotation pilots without full charter requirements, enabling unbundled fraud-management or authentication-layer specialization. Morocco's unbanked rural populations present the most penetrable geography for agent-network wallet models proven in Egyptian governorates. Go-to-market positioning should leverage government disbursement linkages following STC Pay's anchor model. For Investors and Strategic Acquirers: Central bank digital currency pilot announcements in the UAE and Saudi Arabia are the leading indicator that clearing economics for private wallet operators face structural compression. Long-term viability favors processors with regulatory sandbox access and multi-source gateway partnership density. Acquisition targets should demonstrate PCI-DSS Level 1 certification capacity and central bank switch integration completion.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Participation | Abu Dhabi's pilot licenses enable rapid capability testing without full SAMR charter compliance burdens. |
| Agent Network Expansion | Fawry's cash-digitization model extends wallet access into Egypt's governorates beyond formal banking reach. |
| ISO 20022 Migration Investment | Legacy core banking transformation in Jordan and Lebanon creates multi-year service contracts for compliant operators. |
| Biometric Authentication Layer Buildout | SAMR's biometric KYC mandates above threshold limits elevate infrastructure requirements for wallet onboarding. |
| Cross-Border Remittance Tokenization | Regional switch integration with international schemes enables corridor-specific pricing for South Asian labor flows. |
Research Methodology
Document review covered regulatory filings from SAMR, UAE Central Bank, and Egypt's CBE, complemented by interviews with payment platform CTOs, merchant acquiring executives, regulatory affairs leads at fintech operators, and central bank digital currency program directors. Secondary validation drew from central bank licensing registries, PCI-DSS certification databases, and switch transaction volume disclosures. Bottom-up merchant onboarding velocity metrics and top-down regional GDP-linked payment penetration estimates were triangulated.
Historical transaction volume trajectories were cross-referenced against panel input from processor network operators and telecom-wallet providers across the projection horizon. Segmentation modeling incorporated payment mode, end-user industry, transaction type, and security feature tier dimensions. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points. Forecast inputs included SAMR liquidity threshold implementation timelines and contactless terminal deployment curves in Dubai's smart city clusters.
The model assumes a particular technology adoption path; alternative pathways for central bank digital currency clearing integration would alter the outlook for private wallet operator economics. Forecasts reflect documented assumptions regarding regulatory sandbox expansion and interoperability mandate enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Smart POS System Market
Payments
Smart Payment Market
Payments
Czech Republic POS Terminals Market
Payments
Europe Fuel Cards Market
Payments
Poland POS Terminal Market
Payments
Philippines Remittance Market
Payments
Canada POS Terminal Market
Payments
India Forex Cards Market
Payments
Germany Payments Market
Payments
Bitcoin Payments Market
Payments
Middle East Gift Card and Incentive Card Market
Payments
In-Vehicle Payment Services Market
Payments
Proximity Payment Market
Payments
India RTP Market
Payments
Brazil Real Time Payments Market
Payments
Global Payments As a Service Market