
 United Kingdom Payment Gateway Market | 2026-2036
United Kingdom Payment Gateway Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Payment Gateway Market Insights
Merchant sourcing of payment infrastructure is shifting from single-vendor relationships toward multi-gateway architectures that reduce concentration risk. Stripe leverages developer-centric tooling to anchor its position among UK SaaS and marketplace platforms. Adyen sustains global acquiring licenses that let merchants consolidate cross-border settlement through one integration. Square competes aggressively for in-person retail share with hardware-software bundles that simplify omnichannel reconciliation.
A payment gateway is a technology layer that encrypts, routes, and authorizes transaction data between merchant systems and acquiring banks, typically processing card-not-present payments through HTTPS-secured APIs with sub-500-millisecond response times. Its commercial purpose is to reduce fraud exposure while enabling merchants to accept diverse payment instruments without direct bank integration. Cloud-based deployment leads structural growth as UK merchants abandon on-premises hardware for elastic, PCI-DSS-compliant infrastructure that scales with seasonal transaction spikes. API payment service types capture the fastest expansion as developers embed checkout experiences directly into mobile apps and progressive web applications. E-commerce end users generate the deepest margin pools, though hospitality recovery is accelerating gateway adoption for reservation and delivery platforms.
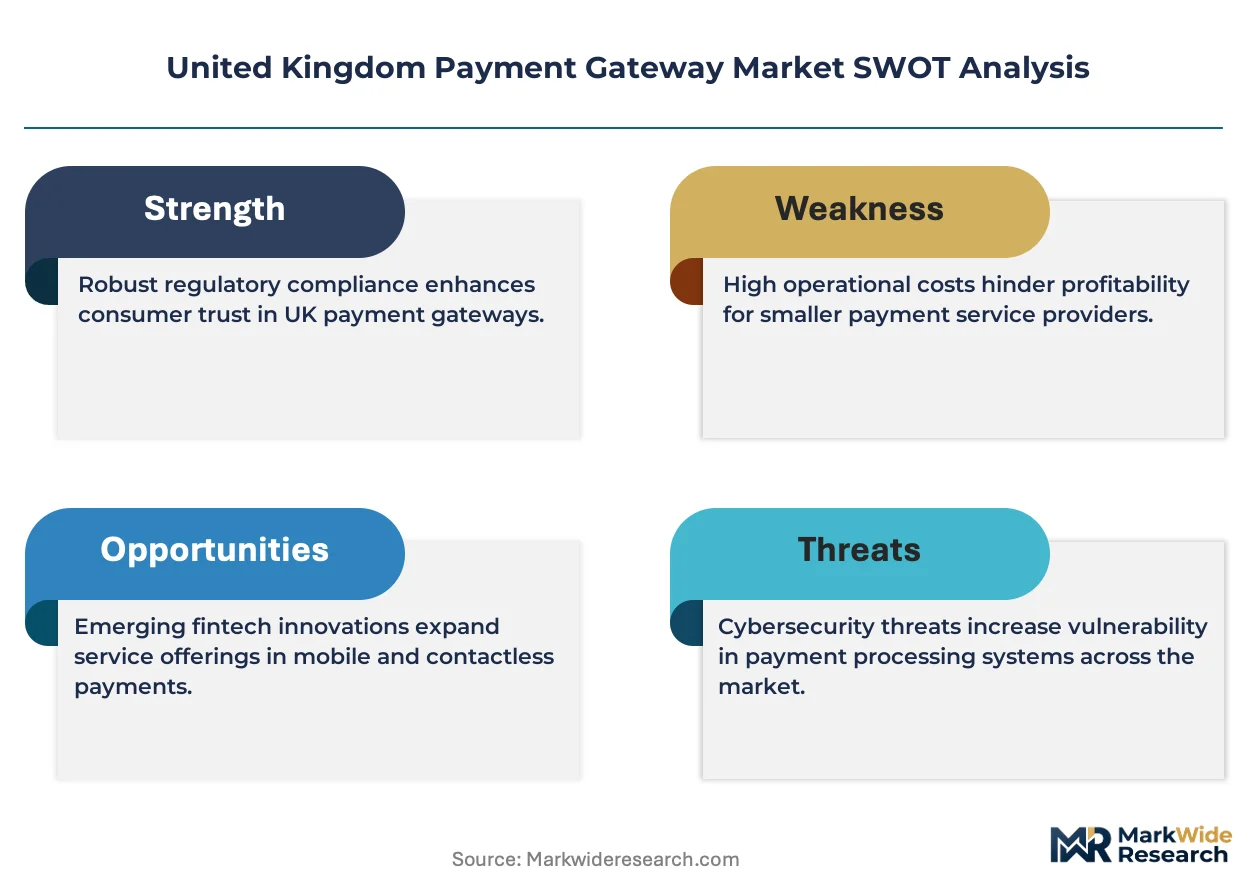
The Financial Conduct Authority enforces PSD2 strong customer authentication mandates that compel gateway providers to support multi-factor verification flows, reshaping product roadmaps for UK-licensed operators. PCI-DSS compliance requirements from the Payment Card Industry Security Standards Council impose annual audit burdens that favor established providers with dedicated compliance teams over emerging entrants. The UK Information Commissioner's Office GDPR enforcement adds data-localization complexity to cross-border transaction processing. Stakeholders must monitor how the Bank of England's digital pound consultations alter settlement architecture demands for gateway intermediaries.
Market Dynamics
Multi-gateway architectures are displacing single-vendor relationships as UK merchants prioritize resilience against provider outages and optimize transaction routing costs across competing acquirers.
Growth Catalysts
- PSD2 Strong Customer Authentication:Regulatory mandates from the Financial Conduct Authority compel gateway upgrades to support biometric and tokenized verification flows, expanding addressable market for compliant infrastructure providers.
- Mobile Commerce Channel Expansion:UK fashion and grocery retailers are embedding native checkout experiences within iOS and Android applications, requiring API-first gateway capabilities that legacy processors cannot deliver.
- Open Banking API Standards:The Open Banking Implementation Entity's technical specifications enable account-to-account payment initiation, creating new revenue pools for gateways that orchestrate real-time bank transfers alongside card networks.
Market Restraints
- PCI-DSS Compliance Burden:Annual audit requirements and quarterly vulnerability scanning impose fixed costs that disadvantage smaller gateway entrants against established providers with dedicated compliance teams.
- Cloud Infrastructure Concentration:Reliance on hyperscale cloud providers for elastic compute creates systemic risk if AWS, Google Cloud, or Azure experience regional outages affecting transaction processing continuity.
- Card Scheme Fee Pressure:Interchange and scheme fee structures set by Mastercard and Visa compress merchant margins, limiting willingness to absorb additional gateway service charges.
Strategic Opportunities
- Embedded Finance Convergence:Partnerships between gateways and Buy-Now-Pay-Later platforms like Klarna and Clearpay enable checkout-integrated lending, capturing interchange-plus-financing revenue stacks.
- Subscription Economy Verticalization:SaaS and membership merchants require vaulting and dunning management capabilities that generalist gateways underserve, creating niche specialization potential.
- Scotland and Northern England Merchant Acquisition:Underpenetrated mid-market retail corridors outside London present lower customer acquisition costs for challenger gateways with localized support operations.
Industry Challenges
- Legacy Core Banking Integration:Tier-1 UK clearing banks operate on COBOL-based authorization systems that require expensive middleware development for real-time gateway connectivity.
- SCA Friction Management:Balancing PSD2 authentication requirements against checkout abandonment demands sophisticated risk-scoring engines that smaller providers struggle to build.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Payment Gateway Market |
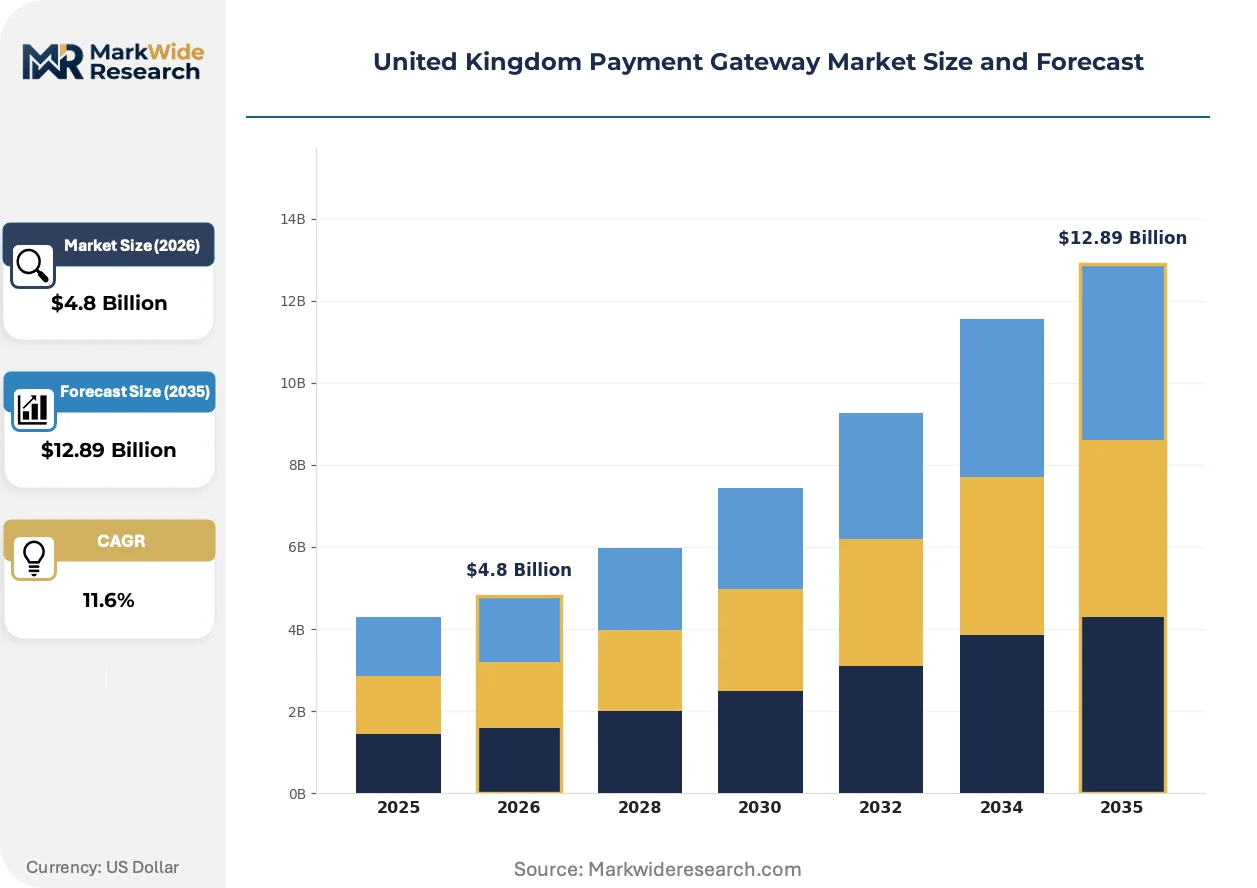
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.89 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, API Integration Service Type: Hosted Payment, Direct Payment, API Payment, Virtual Terminal End User: E-Commerce, Retail, Hospitality, Non-Profit Transaction Type: Credit Card, Debit Card, Digital Wallet, Bank Transfer |
| Companies Covered | Stripe, Adyen, PayPal, Braintree, Authorize.net, Cashflows, Mollie, WooCommerce Payments, Square, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Payment Gateway Market Trends and Innovations
Payment orchestration layers are emerging as a distinct architectural category, abstracting multiple gateway relationships behind unified APIs that optimize routing logic and failure recovery.
Network tokenization is expanding into the UK e-commerce stack, replacing primary account numbers with device-bound cryptograms that reduce fraud liability and enable one-click checkout experiences. Mid-market fashion and electronics merchants are adopting this technology fastest, with implementation timelines compressing from eighteen months to under six. The structural consequence is that gateway providers without vaulting and token lifecycle management capabilities are losing anchor tenant relationships to orchestration specialists.
The Financial Conduct Authority's Consumer Duty regulations now require gateway providers to demonstrate fair value and transparency in pricing disclosures to merchant customers. This policy shift forces contractual renegotiation of blended rate structures into unbundled fee schedules. Small and mid-sized merchants are the most affected segment, demanding itemized reporting that legacy gateway contracts did not provide.
Merchant procurement of payment infrastructure is consolidating through platform intermediaries rather than direct gateway relationships. Marketplace operators and e-commerce platforms are embedding payment capabilities as core infrastructure, displacing standalone gateway selection by sub-merchants. This pattern is most visible in UK hospitality and food delivery verticals, where franchise and aggregator models dominate merchant onboarding flows.
United Kingdom Payment Gateway Market Segmentation
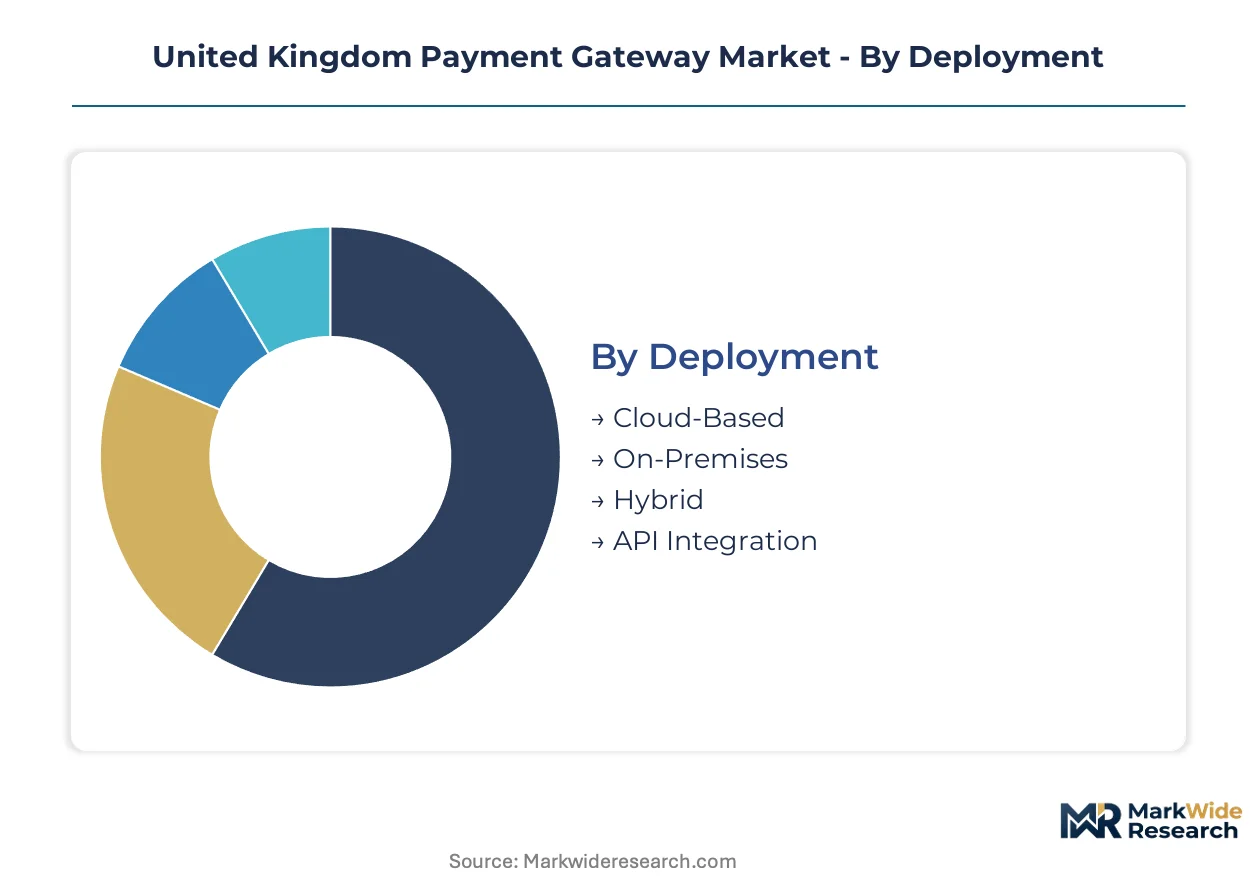
Payment gateway segmentation reveals how UK merchants match infrastructure choices to operational constraints. Deployment models determine compliance burden and scalability. Service types align with developer resources and checkout control requirements.
Deployment:
Cloud-native architectures now dominate merchant procurement as elastic compute replaces fixed-capital infrastructure.
- Cloud-Based:Multi-tenant SaaS delivery eliminates PCI-DSS scope for merchant environments through provider-assumed compliance. UK fashion and grocery retailers deploy this model to absorb Black Friday transaction spikes without pre-provisioning.
- On-Premises:Dedicated hardware within merchant data centers persists among Tier-1 banks and government contractors with sovereign data mandates. Fixed-cost depreciation models appeal to organizations with existing colocation investments.
- Hybrid:Split processing routes sensitive authentication through private infrastructure while leveraging public cloud for transaction volume. This architecture serves UK healthcare payment processors balancing GDPR localization with burst capacity.
- API Integration:Embedded connectivity layers enable headless checkout experiences within merchant-controlled frontends. Developer-centric merchants in London's SaaS corridor favor this approach for brand-consistent payment flows.
Cloud-Based leads on scale; API Integration leads on momentum.
Service Type:
Service differentiation tracks merchant technical sophistication and risk tolerance for checkout control.
- Hosted Payment:Provider-controlled checkout pages redirect customers away from merchant domains. Small UK retailers without development teams adopt this to minimize PCI-DSS audit scope and fraud liability exposure.
- Direct Payment:Server-to-server APIs transmit card data without customer-visible redirection. Mid-market merchants with compliance teams use this to preserve on-site checkout branding while maintaining security standards.
- API Payment:Fully programmable interfaces enable native checkout embedding within iOS, Android, and progressive web applications. UK food delivery platforms and marketplace operators require this capability for frictionless mobile experiences.
- Virtual Terminal:Web-based manual entry interfaces support phone and mail order transactions. Hospitality reservation desks and charity call centers rely on this for card-not-present processing without integrated software.
API Payment captures the steepest expansion trajectory as mobile commerce accelerates; Hosted Payment retains the broadest merchant base.
End User:
Vertical-specific requirements shape gateway selection criteria across merchant categories.
- E-Commerce:Pure-play online retailers demand sub-500-millisecond authorization speeds and global currency settlement. This segment generates the deepest margin pools through high transaction volumes and cross-border complexity.
- Retail:Omnichannel merchants require unified reconciliation across in-person terminals and online storefronts. Hardware-software bundles from integrated providers dominate this category.
- Hospitality:Hotels and restaurants need pre-authorization capabilities for reservations and tab management. Post-pandemic recovery is accelerating gateway replacement cycles in this vertical.
- Non-Profit:Charitable organizations prioritize low-cost card-present alternatives for fundraising events and recurring donation processing. Simplified onboarding and transparent pricing dominate procurement decisions.
E-Commerce leads on scale; Hospitality leads on momentum.
Transaction Type:
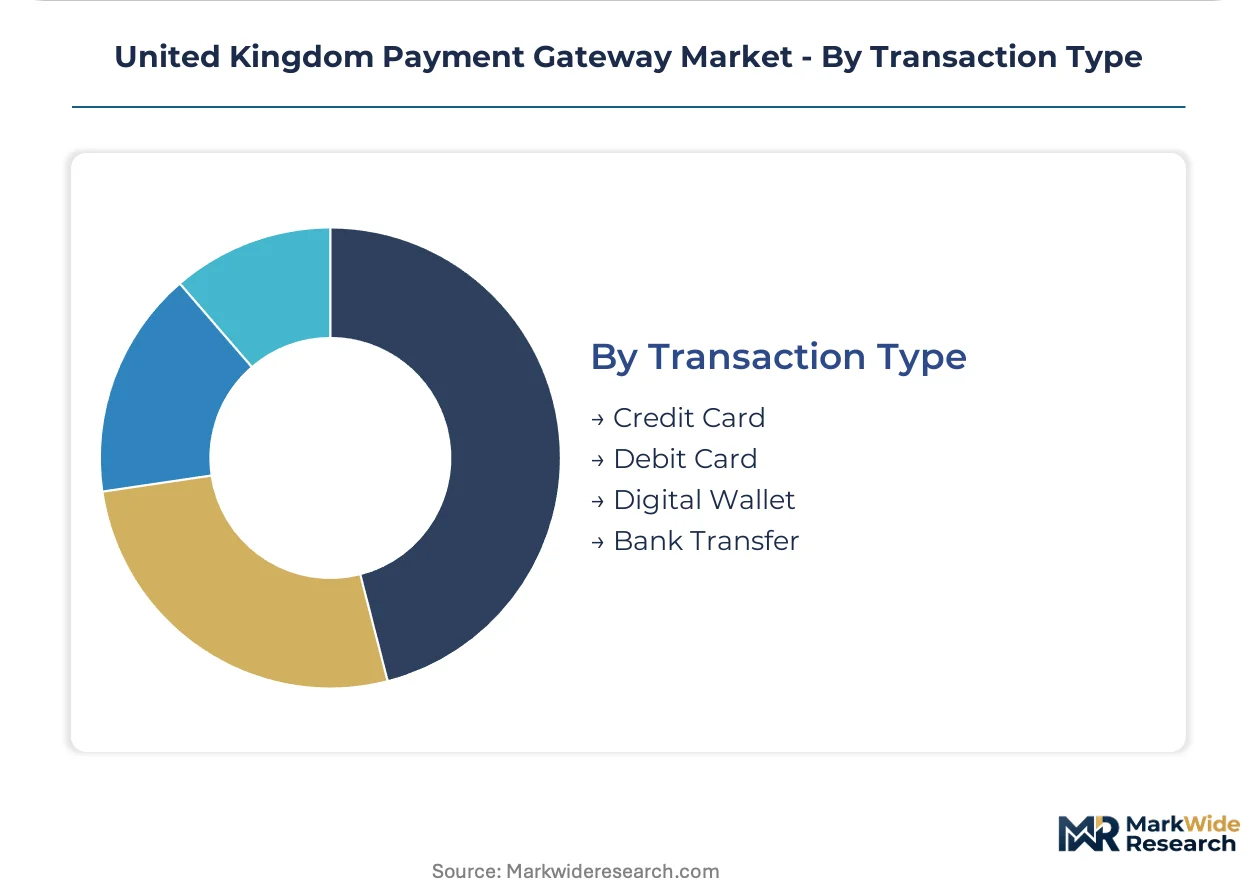
Payment instrument mix determines gateway routing logic and interchange cost optimization.
- Credit Card:Revolving credit products carry higher interchange fees but enable larger average transaction values. UK luxury goods merchants optimize for this instrument type despite margin compression.
- Debit Card:Direct bank account debiting offers lower scheme fees and stronger authorization rates. Supermarket chains and utility billers prioritize debit routing to minimize processing costs.
- Digital Wallet:Tokenized credentials from Apple Pay, Google Pay, and PayPal reduce fraud liability through biometric authentication. Mobile-first merchants in London and Manchester report accelerating wallet adoption.
- Bank Transfer:Account-to-account payments through Open Banking APIs bypass card networks entirely. Real-time settlement and eliminated interchange make this the fastest-climbing instrument category for B2B and subscription merchants.
Credit Card leads on scale; Bank Transfer leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's financial technology corridor concentrates payment gateway demand through merchant density and regulatory proximity. The United Kingdom's regional markets exhibit distinct adoption patterns shaped by industrial composition and digital infrastructure maturity.
London and the Southeast
Fashion marketplace operators and SaaS platforms drive API-first gateway procurement across Shoreditch and Canary Wharf clusters. The Financial Conduct Authority's PSD2 enforcement compels local merchants to upgrade authentication stacks. Fintech incubators in King's Cross and Old Street accelerate challenger gateway testing among venture-backed startups.
The Midlands
Manufacturing exporters and automotive parts distributors prioritize multi-currency settlement capabilities for EU trade corridors. Birmingham's merchant base demands hybrid cloud deployments balancing GDPR data localization with burst capacity. Coventry's logistics platforms integrate gateway APIs directly into warehouse management systems for B2B invoice automation.
North England
Underpenetrated mid-market retail corridors in Manchester and Leeds present acquisition opportunities for challenger providers with localized support operations. The region's hospitality recovery accelerates gateway replacement for reservation platforms. Liverpool's creative economy generates demand from freelance marketplaces and subscription content creators.
Scotland
Edinburgh's asset management and insurance technology sectors require vaulting capabilities for recurring premium collection. Glasgow's retail and food service merchants adopt omnichannel bundles that unify in-person terminals with online storefronts. The Scottish Government's digital economy initiatives subsidize small merchant gateway onboarding in Aberdeen's energy services corridor.
Wales and Northern Ireland
Cardiff's public sector procurement platforms mandate sovereign data processing for government payment acceptance. Belfast's cross-border retail merchants face dual compliance requirements with Irish and UK regulatory frameworks. Tourism-dependent coastal economies in both regions prioritize mobile-first checkout experiences for seasonal visitor spikes.
United Kingdom Payment Gateway Market Competitive Landscape
Global majors compete with regional champions across developer tooling and compliance specialization. The United Kingdom market exhibits tiered concentration where a handful of integrated platforms anchor high-volume merchant relationships while specialists capture vertical niches. Three archetypes dominate: API-native developer platforms, full-stack acquirer-gateway combinations, and vertical SaaS-embedded providers. Competitive moves center on payment orchestration layer acquisitions and Open Banking partnership networks that expand account-to-account capabilities.
Among developer-centric platforms, Stripe and Adyen exemplify the API-first archetype through infrastructure that merchants embed directly into controlled frontends. PayPal occupies a position bridging consumer wallet recognition with merchant services. These three anchors represent distinct strategic postures: pure infrastructure abstraction, global acquiring consolidation, and consumer brand leverage.
| Leading Market Players |
|---|
| Stripe |
| Adyen |
| PayPal |
| Braintree |
| Authorize.net |
| Cashflows |
| Mollie |
| WooCommerce Payments |
| Square |
| Others |
Pricing and Supply Chain Analysis
Venture-backed API-native platforms and private-equity-rolled-up payment infrastructure specialists dominate UK gateway ownership structures, concentrating pricing discipline among scaled providers with dedicated compliance teams while forcing smaller entrants toward cost-plus models that erode service differentiation.
Pricing Analysis
Interchange and scheme fee pass-through from Mastercard and Visa anchors UK gateway pricing models, with providers layering subscription SaaS tiers atop per-transaction basis points. Price differentiation rests on PCI-DSS certification level and API response latency guarantees, where sub-100-millisecond authorization commands premium positioning. Pricing pressure stems from Open Banking account-to-account alternatives that bypass card network fees entirely. Mid-market e-commerce merchants exhibit highest price sensitivity, while enterprise SaaS platforms prioritize integration reliability over rate negotiation.
Supply Chain Analysis
Cross-border data center provisioning and submarine cable capacity constrain UK gateway logistics costs, with hyperscale cloud regions in Ireland, Netherlands, and UK sovereign zones feeding elastic compute demand. Infrastructure dependencies center on AWS, Google Cloud, and Azure availability zones, plus Thales and Entrust hardware security modules for encryption key lifecycle management. Single-source vulnerability concentrates in cloud provider regional outages. Distribution runs through direct API documentation and developer relations teams rather than traditional channel intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK payment gateway market functions as a stable compounder, with regulatory-mandated infrastructure refresh cycles from PSD2 and Open Banking sustaining replacement demand regardless of macroeconomic volatility.
For Market Incumbents: Deploy payment orchestration layer acquisitions to anchor multi-gateway relationships before challenger orchestration specialists capture merchant switching windows. Consolidate acquiring licenses across EU-UK corridors to defend against cross-border settlement fragmentation from divergent post-Brexit regulatory frameworks. Deepen vaulting and token lifecycle capabilities as network tokenization displaces primary account number storage. For New Entrants and Emerging Players: Mid-market hospitality merchants in Manchester and Leeds represent the most penetrable buyer archetype, with localized support operations and pre-authorization features for reservation platforms creating differentiation against London-centric incumbents. Scotland's asset management technology corridor offers secondary white-space for recurring billing specialization. A direct sales model with embedded implementation support outperforms self-serve onboarding in these underpenetrated corridors. For Investors and Strategic Acquirers: Valuations sit cheapest among hybrid cloud deployment specialists with healthcare and public sector compliance credentials, where GDPR localization requirements and sovereign data mandates create durable moats. Long-term viability hinges on Open Banking partnership network density and orchestration layer integration. The signal to watch is Bank of England digital pound consultation outcomes, which would reshape settlement architecture demands and gateway intermediary economics.| Strategic Initiative | Industry Significance |
|---|---|
| Payment Orchestration Layer Acquisition | Captures merchant multi-gateway relationships before orchestration specialists consolidate routing logic control. |
| Open Banking API Partnership Expansion | Enables real-time account-to-account settlement that bypasses Mastercard and Visa interchange fee structures. |
| Network Tokenization Infrastructure Buildout | Reduces fraud liability exposure while enabling one-click checkout experiences for fashion and electronics merchants. |
| Regional Support Operation Localization | Penetrates underpenetrated Manchester and Leeds retail corridors with lower customer acquisition costs than London. |
| Hybrid Cloud Compliance Certification | Captures NHS and government contractor procurement requiring GDPR data localization with burst capacity flexibility. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with payment gateway product managers, merchant CTOs, acquiring bank relationship directors, and Financial Conduct Authority policy specialists with secondary validation against SEC filings of listed payment infrastructure providers, UK Finance industry statistics, Open Banking Implementation Entity technical specifications, and Payment Card Industry Security Standards Council compliance disclosure databases. Bottom-up merchant adoption modeling and top-down market sizing triangulated volume estimates.
Historical reference periods anchored the projection horizon through comparable-period growth rate analysis and regulatory implementation timeline alignment. Segmentation dimensions modeled encompassed deployment architecture, service type integration complexity, end-use vertical, transaction instrument mix, and UK regional adoption pattern. CAGRs derived from segment-level trajectory blending weighted by addressable merchant base expansion. Forecast inputs incorporated PSD2 strong customer authentication compliance deadline impacts and Open Banking payment initiation API adoption curves.
Underlying measurement precision varies by segment; cloud-based deployment and API payment service types carry tighter precision than on-premises legacy installations given disclosure transparency differences. Forecasts reflect assumptions around regulatory enforcement continuity and cloud infrastructure availability. A model refresh is warranted upon material change in Bank of England digital pound settlement architecture consultations or hyperscale cloud provider regional outage frequency.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Payments
Spain Payments Market
Payments
Bus Card Reader Market
Payments
North America Payments Market
Payments
Mobile Money Market
Payments
India Mobile Payments Market
Payments
Mobile Payment Security Software Market
Payments
3D Secure Pay Authentication Market
Payments
Denmark POS Terminals Market
Payments
Global Gift Card Market
Payments
Credit Card Payments Market
Payments
Smart POS System Market
Payments
Online Payment Gateway Market
Payments
Hong Kong Credit Cards Market
Payments
Mobile Point of Sale Devices (Mpos) Market
Payments
Payment Processing Solutions Market
Payments
Buy Now Pay Later Market