
 Hemp-Based Products Market | 2026-2036
Hemp-Based Products Market Size, Share, and Industry Trends Forecast 2026-2036
Hemp-Based Products Market Outlook
The hemp-based products sector is expanding along a widening gulf between premium certified-organic tiers and commodity bulk supply. Charlotte's Web leverages its seed-to-shelf vertical integration to command shelf space in US health stores. Nutiva Inc. anchors the North American organic hemp food segment through longstanding retailer relationships. Ecofibre Limited dominates textile-grade fiber production from its Australian cultivation base.
Hemp-based products encompass derivatives from Cannabis sativa L. containing less than 0.3% THC by dry weight, including cold-pressed oils with 75-80% polyunsaturated fat content, hulled seeds, bast fibers, and concentrated protein isolates. These materials serve food fortification, cosmetic emollient systems, and composite textile manufacturing. Hemp oil and hemp seeds lead consumer-facing revenue pools due to established retail penetration, while hemp fiber captures industrial margins through automotive and construction composite applications. Textile producers represent the fastest-growing end user category as decortication technology improves fiber consistency for apparel-grade spinning.
The FDA maintains evolving guidance on hemp ingredient safety assessments, while the USDA oversees organic certification and interstate commerce compliance for hemp cultivation. The EU Green Deal and REACH frameworks shape European market access through stringent contaminant thresholds and sustainability disclosure requirements. Stakeholders must monitor regulatory divergence on THC limits between jurisdictions to avoid supply chain disqualification.
Market Dynamics
Regulatory harmonization on THC thresholds is compressing cross-border formulation cycles while decortication technology improvements unlock textile-grade fiber consistency for apparel manufacturers.
Growth Catalysts
- FDA GRAS Pathway Clarification:The FDA's evolving guidance on hemp-derived ingredient safety assessments is accelerating food manufacturer procurement of hemp seed and protein isolates for fortification applications.
- EU Green Deal Sustainability Mandates:REACH framework contaminant thresholds and sustainability disclosure requirements are steering European cosmetic formulators toward hemp oil emollient systems.
- Automotive Composite Demand:Bast fiber applications in lightweight vehicle components are expanding as decortication technology improves fiber consistency for thermoplastic reinforcement.
Market Restraints
- THC Threshold Divergence:Jurisdictional variation in THC limits between US federal standards, EU member state implementations, and Canadian thresholds creates supply chain disqualification risks for multi-market suppliers.
- Organic Certification Bottlenecks:USDA organic certification timelines for hemp cultivation extend 24-36 months, constraining premium tier supply expansion.
- Polymer Substitution Pressure:Synthetic fiber price compression in textile applications limits hemp fiber margin capture despite sustainability premiums.
Strategic Opportunities
- Construction Composite White Space:Hempcrete and fiber-reinforced building materials represent underpenetrated applications as building codes in Germany and France incorporate biogenic carbon accounting.
- Direct-to-Consumer Protein Channels:E-commerce subscription models for hemp protein isolates are bypassing conventional natural retail slotting fee structures.
- CSRD-Driven Ingredient Sourcing:Corporate sustainability reporting obligations are mandating Scope 3 emission disclosures that favor hemp seed oil over petroleum-derived cosmetic emollients.
Industry Challenges
- Decortication Equipment Scarcity:Specialized fiber processing machinery requires capital deployment of $2-4 million per installation, limiting processor entry.
- Cross-Jurisdictional Compliance Talent:Regulatory affairs professionals with simultaneous expertise in FDA, USDA, and REACH frameworks command premium compensation and extended search timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemp-Based Products Market |
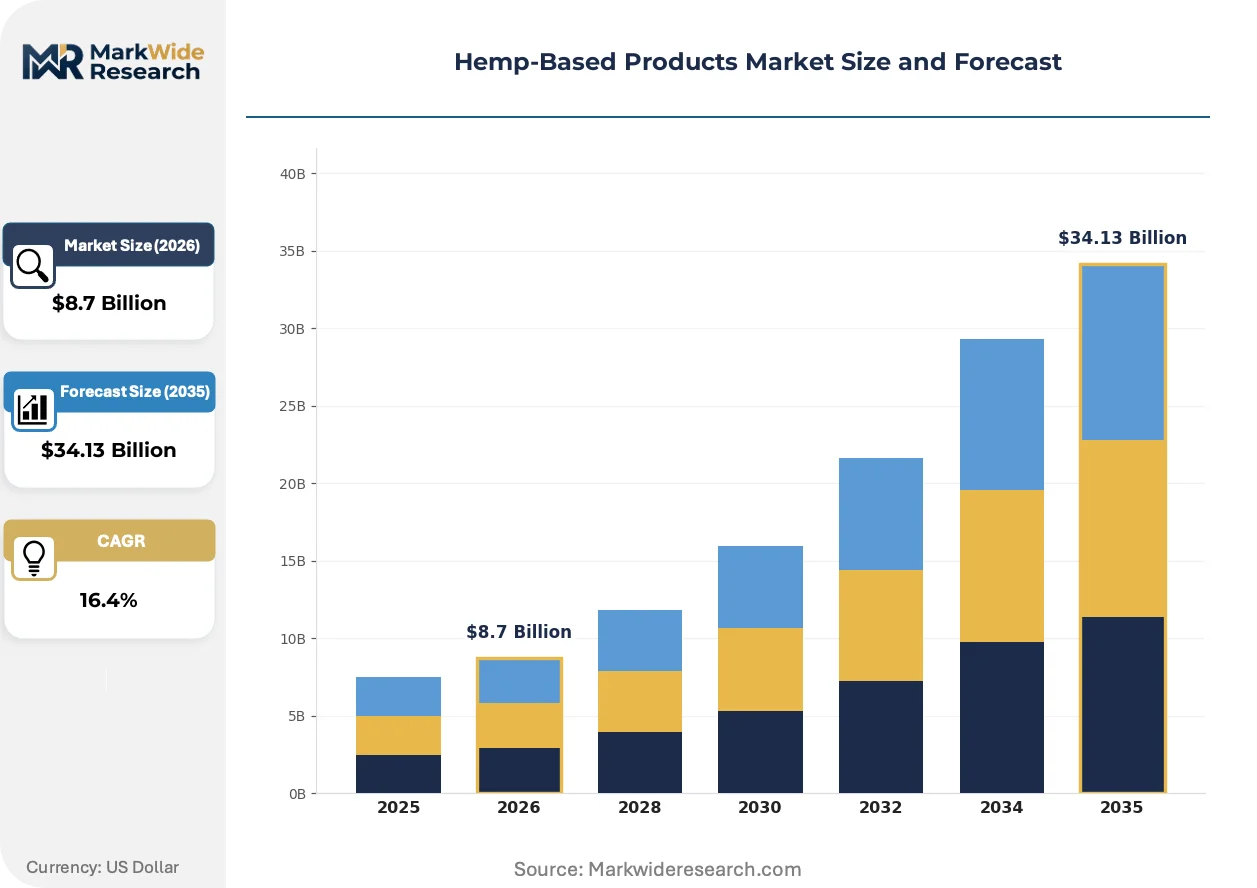
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hemp Oil, Hemp Seeds, Hemp Fiber, Hemp Protein Application: Food & Beverage, Dietary Supplements, Cosmetics, Textiles End User: Retail Consumers, Food Manufacturers, Cosmetic Brands, Textile Producers Distribution Channel: Online Retail, Supermarkets, Health Stores, Direct Sales |
| Companies Covered | Charlotte's Web, Canopy Growth Corporation, Aurora Cannabis Inc., CV Sciences Inc., Medterra CBD, Green Roads, Koi CBD, Nutiva Inc., Ecofibre Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemp-Based Products Market Strategic Shifts
Processing technology maturation is bifurcating the market between commodity bulk supply and certified-organic premium tiers, while regulatory transparency accelerates ingredient approval timelines.
Water-retting alternatives using enzymatic and mechanical decortication are expanding into textile-grade fiber production. European spinning mills are adopting these processes at pilot scale to reduce weather dependency and fiber quality variance. This technology is expanding into apparel supply chains previously dominated by cotton and synthetic blends.
REACH framework updates on residual solvent limits for hemp-derived extracts are tightening extraction facility compliance requirements. CO2 and ethanol extraction operators face capital upgrades to meet revised contaminant thresholds. Cosmetic formulators in France and Germany are responding by consolidating supplier bases toward vertically integrated processors with in-house analytical capabilities.
Ingredient procurement from seed-to-shelf traceable sources is displacing commodity spot purchasing among North American natural product brands. Third-party blockchain verification platforms are capturing preference share from traditional certificate-based documentation. This pattern concentrates in California and Colorado health store channels where consumer interrogation of supply chain provenance is most intensive.
Hemp-Based Products Market Segmentation
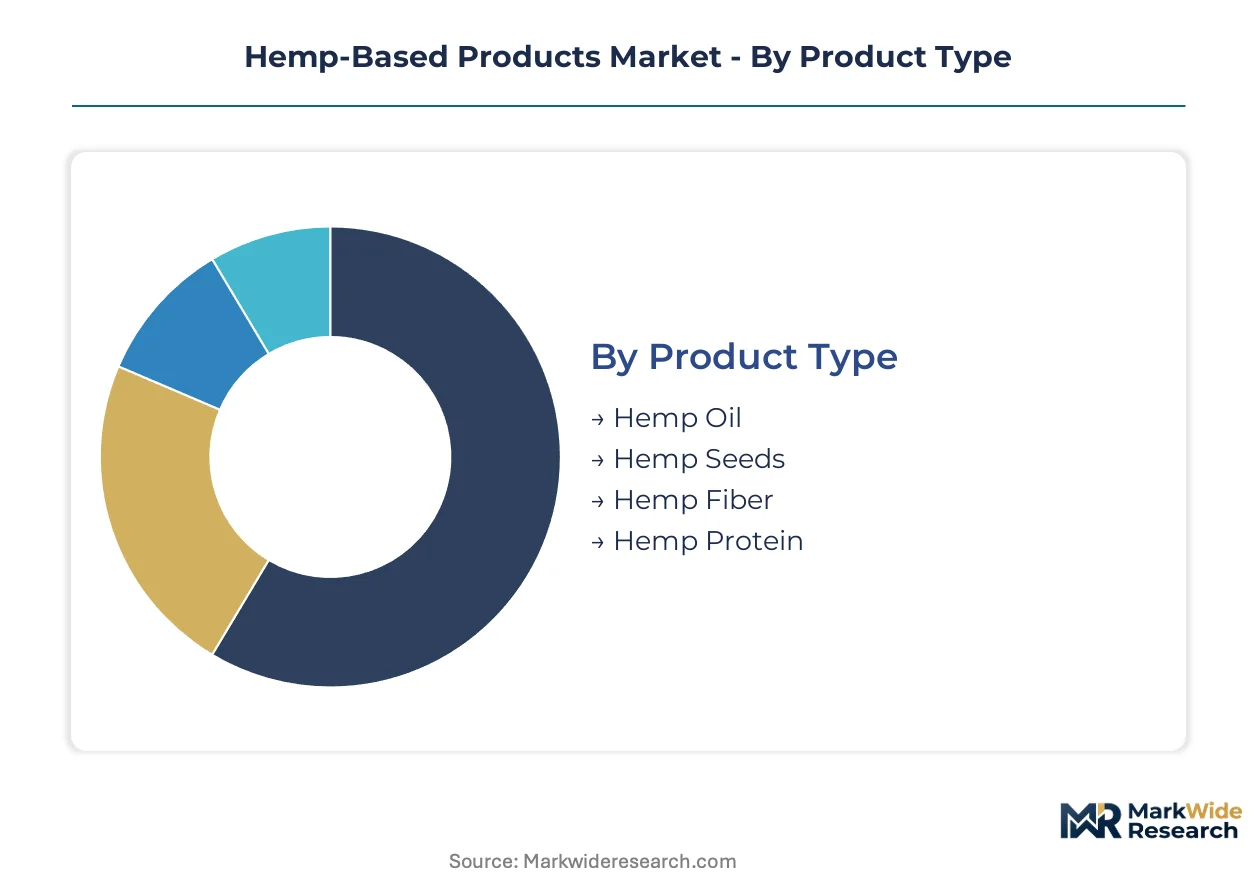
Hemp-based products fragment across four distinct category axes. Product type determines margin structure and regulatory pathway. Application and end-user concentration dictate procurement patterns and channel strategy. Distribution channel selection reflects consumer trust requirements and certification visibility.
Product Type:
Standardization dominates commodity grades while certified-organic tiers command premium positioning through traceability infrastructure.
- Hemp Oil:Cold-pressed extraction yields 75-80% polyunsaturated fat content with omega-3/6 ratios suited to cosmetic emollient systems. Demand concentrates in French and German cosmetic formulators responding to REACH solvent limit updates. EFSA novel food consultations are accelerating food-grade approval timelines for EU market entry.
- Hemp Seeds:Hulled seeds and cold-pressed derivatives serve protein fortification in North American natural retail. USDA organic certification bottlenecks constrain premium tier expansion as procurement timelines extend 24-36 months.
- Hemp Fiber:Bast fiber from decortication processes supplies automotive and construction composites. German and French building codes incorporating biogenic carbon accounting are unlocking hempcrete demand.
- Hemp Protein:Concentrated isolates bypass conventional retail slotting fees through direct-to-consumer subscription channels. CSRD-driven Scope 3 disclosures favor hemp protein over petroleum-derived alternatives.
Leading the category by volume: Hemp Oil. Growing fastest: Hemp Fiber.
Application:
Margin capture varies by regulatory burden and formulation complexity across end-use sectors.
- Food & Beverage:Hemp seed and oil integration accelerates as FDA GRAS pathways clarify. California and Colorado health stores drive certified-organic procurement with blockchain-verified provenance requirements.
- Dietary Supplements:Protein isolate demand climbs through e-commerce subscription models bypassing traditional retail structures. FDA safety assessment evolution shapes ingredient approval timelines.
- Cosmetics:Hemp oil emollient systems displace petroleum-derived alternatives under EU Green Deal sustainability mandates. REACH residual solvent limits are consolidating supplier bases toward vertically integrated processors.
- Textiles:Apparel-grade fiber adoption expands as enzymatic decortication reduces weather dependency. European spinning mills pilot mechanical processing to improve consistency for cotton blend substitution.
Dominant by revenue: Food & Beverage. Steepest expansion trajectory: Textiles.
End User:
Procurement sophistication scales with supply chain control requirements and compliance burden.
- Retail Consumers:California and Colorado channels exhibit intensive supply chain provenance interrogation. Third-party blockchain verification displaces certificate-based documentation.
- Food Manufacturers:FDA GRAS pathway clarification accelerates hemp seed and protein procurement for fortification applications. Formulation cycles compress with regulatory transparency.
- Cosmetic Brands:French and German formulators consolidate toward processors with in-house analytical capabilities under REACH contaminant thresholds.
- Textile Producers:Automotive composite demand expands for lightweight vehicle components. Decortication technology improvements unlock thermoplastic reinforcement applications.
Largest procurement volume: Food Manufacturers. Gaining share fastest: Textile Producers.
Distribution Channel:
Channel selection reflects certification visibility requirements and consumer trust infrastructure.
- Online Retail:Subscription models for hemp protein isolates bypass conventional natural retail slotting fee structures. Direct-to-consumer channels capture margin from premium tiers.
- Supermarkets:Commodity bulk supply concentrates in conventional grocery as certified-organic tiers occupy specialty positioning. Price compression limits margin capture.
- Health Stores:California and Colorado channels drive seed-to-shelf traceable sourcing. Consumer interrogation of provenance is most intensive in these clusters.
- Direct Sales:B2B procurement from vertically integrated processors serves cosmetic and textile manufacturers with compliance documentation requirements.
Highest transaction volume: Supermarkets. Expanding most quickly: Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Boulder, Colorado anchors North American hemp product innovation through dense clustering of seed-to-shelf operators and FDA-engaged formulation labs. Charlotte's Web maintains headquarters operations there alongside analytical testing facilities serving natural retail channels.
United States
California health stores and Colorado natural retail channels drive certified-organic procurement with blockchain-verified provenance requirements. FDA GRAS pathway clarification accelerates food manufacturer hemp seed and protein procurement. Boulder-Denver corridor concentrates vertically integrated operators with in-house analytical capabilities.
Germany
French and German cosmetic formulators consolidate supplier bases toward processors meeting REACH residual solvent limits. EU Green Deal sustainability mandates steer hemp oil emollient system adoption. Baden-Württemberg spinning mills pilot enzymatic decortication for apparel-grade fiber consistency.
France
Building codes incorporating biogenic carbon accounting unlock hempcrete demand in construction composites. EFSA novel food consultations accelerate food-grade hemp oil approval timelines. Provence-Alpes-Côte d'Azur hosts cosmetic formulation clusters responding to REACH framework updates.
Canada
Health Canada oversight of THC thresholds shapes cross-border supply chain compliance for multi-market suppliers. Prairie provinces concentrate cultivation operations feeding North American protein isolate demand. Ontario processors serve dietary supplement manufacturers with extraction-derived ingredients.
Australia
Ecofibre Limited dominates textile-grade fiber production from Australian cultivation bases serving automotive composite manufacturers. State-level hemp regulations vary, creating compliance complexity for interstate operators. Queensland and New South Wales concentrate decortication capacity for bast fiber export.
Hemp-Based Products Market Competitive Environment
Premium-margin players sit above commodity-margin players across certification and traceability infrastructure. The vendor base separates into seed-to-shelf vertically integrated operators, commodity bulk suppliers, and specialized fiber processors. Three archetypes dominate: organic-certified premium tier specialists, scale-driven commodity suppliers, and textile-focused fiber processors. Competitive moves concentrate on backward integration into cultivation and strategic partnerships with analytical testing facilities.
Within the seed-to-shelf tier, Charlotte's Web and Nutiva Inc. exemplify premium positioning through traceable supply chain control. Ecofibre Limited occupies the textile-specialist vector with Australian-based fiber production. These three represent distinct strategic postures: direct-to-consumer brand building, organic retail channel anchoring, and industrial-grade fiber supply respectively.
| Leading Market Players |
|---|
| Charlotte's Web |
| Canopy Growth Corporation |
| Aurora Cannabis Inc. |
| CV Sciences Inc. |
| Medterra CBD |
| Green Roads |
| Koi CBD |
| Nutiva Inc. |
| Ecofibre Limited |
| Others |
Value Chain & Pricing Dynamics
FDA GRAS pathway clarification for hemp-derived ingredients is accelerating food manufacturer procurement timelines, forcing suppliers to secure USDA organic certification and in-house analytical capabilities that compress margins across premium tiers.
Pricing Analysis
Certification-grade premiums anchor value-based pricing for hemp seed and protein isolates, with three-tier pricing structure across premium, standard, and economy levels separating blockchain-verified organic from commodity bulk. Price differentiation hinges on USDA organic status and seed-to-shelf traceability infrastructure. Cost compression in textile-grade fiber is intensifying because synthetic substitution limits margin capture despite sustainability premiums. Food manufacturers exhibit highest price sensitivity due to formulation cost constraints, while cosmetic formulators in France and Germany show lowest sensitivity given REACH compliance requirements.
Supply Chain Analysis
Decortication equipment supply rests on German and Italian specialty machinery producers, with cultivation inputs drawing from Australian bast fiber operations and Canadian prairie provinces. Raw material dependencies center on certified hemp seed stock, enzymatic processing reagents, and analytical testing consumables. Single-source vulnerability concentrates in specialized fiber processing machinery requiring capital deployment per installation. Distribution runs through vertically integrated seed-to-shelf operators serving health store channels and direct B2B procurement for textile and cosmetic manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over cultivation certification and in-house decortication capacity determines margin capture across premium tiers.
For Market Incumbents: Cement seed-to-shelf traceability infrastructure through backward integration into certified organic cultivation, defending against commodity bulk suppliers encroaching on natural retail shelf space. Prioritize decortication technology partnerships to lock in textile-grade fiber consistency before enzymatic processing scales. For New Entrants and Emerging Players: Capture construction composite white space in German and French markets where building codes incorporating biogenic carbon accounting unlock hempcrete demand. Target direct-to-consumer protein subscription channels bypassing conventional retail slotting fees, leveraging e-commerce infrastructure for margin retention. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated processors with in-house analytical capabilities given REACH framework updates on residual solvent limits. Long-term viability favors operators controlling both cultivation certification and extraction facility compliance infrastructure. Watch for FDA novel food consultation outcomes as inflection indicators for food-grade hemp oil market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Cultivation | USDA organic certification bottlenecks constrain supply expansion, favoring operators with captive acreage. |
| Enzymatic Decortication Scale-Up | European spinning mills pilot mechanical processing to reduce weather dependency for apparel-grade fiber. |
| Direct-to-Consumer Channel Launch | Subscription models for hemp protein isolates bypass conventional natural retail slotting fee structures. |
| REACH Compliance Infrastructure Investment | French and German cosmetic formulators consolidate toward processors with in-house analytical capabilities. |
| Blockchain Verification Platform Partnership | California and Colorado health stores drive third-party provenance documentation displacing certificate-based systems. |
Study Parameters
Trade databases, FDA guidance documents, and EU regulatory filings formed the secondary backbone, cross-referenced with primary interviews involving hemp cultivation operators, cosmetic formulation chemists, textile procurement managers, and natural retail category buyers. Bottom-up volume modeling triangulated against top-down market sizing across product type, application, and regional regulatory cluster dimensions.
Historical trendline analysis of hemp seed, oil, fiber, and protein isolate volumes informed trajectory projections across the analysis window, with segmentation modeling by certification tier, end-use sector, and distribution channel. CAGRs derived from regression analysis of procurement pattern shifts and regulatory approval timelines, incorporating EFSA novel food consultation progress and decortication technology maturation curves as industry-specific inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to THC threshold harmonization delays and organic certification backlog resolution. Projections reflect assumptions on FDA GRAS pathway finalization and REACH solvent limit enforcement intensity. A small set of named triggers—regulatory divergence on THC limits, decortication equipment deployment rates, and CSRD-driven corporate sourcing mandates—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Algae Fats Market
Alternative Food Sources
North America Fat Replacers Market
Alternative Food Sources
Vegan Eggs Market
Alternative Food Sources
Dunaliella Salina Market
Alternative Food Sources
Egg Replacers Market
Alternative Food Sources
Asia-Pacific Fat Replacers Market
Alternative Food Sources
Fishless Fillets Market
Alternative Food Sources
Vegan Caviar Market
Alternative Food Sources
Upcycled Food Products Market
Alternative Food Sources
Global Algae Protein Market
Alternative Food Sources
Global Meal Replacement Shakes Market
Alternative Food Sources
Global Meal Replacement Market
Alternative Food Sources
Vegan Ham Market
Alternative Food Sources
Europe Algae Protein Market
Alternative Food Sources
Products from Food Waste Market
Alternative Food Sources
Vegetable Proteins Market