
 Africa Fat Replacers Market | 2026-2036
Africa Fat Replacers Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Fat Replacers Market Outlook
The price-performance gap between premium protein-based fat replacers and commodity starch-based alternatives is hardening across African food manufacturing. Cargill, Incorporated leverages its regional grain processing infrastructure to anchor supply security for cost-sensitive bakery producers. BENEO GmbH differentiates through chicory-root-derived fiber systems that command preference in North African dairy reformulations. Tate & Lyle PLC competes on modified starch portfolios optimized for tropical climate stability.
Technical fat replacers encompass carbohydrate, protein, and lipid-based compounds engineered to mimic the organoleptic and functional properties of conventional fats while reducing caloric density and saturated lipid content. These systems typically achieve 50-90% fat displacement in finished food matrices through water-binding, gelation, and mouthfeel modulation mechanisms. Protein-based formulations lead margin capture in premium dairy and meat applications where emulsion stability and texture fidelity justify higher ingredient costs. Fiber-based segments occupy the fastest trajectory as prebiotic positioning and clean-label demand reshape bakery and sauce formulations across the continent.
South Africa's Department of Health food fortification mandates, Nigeria's NAFDAC processed food standards, and Kenya's KEBS labeling requirements collectively elevate product specification thresholds for imported and locally manufactured fat replacers. Compliance with CODEX Alimentarius frameworks increasingly governs cross-border trade within AfCFTA implementation zones. Stakeholders must monitor how evolving front-of-pack warning label regimes across Egypt, Morocco, and South Africa redirect formulation investment toward lower-fat product architectures.
Market Dynamics
Protein-based fat replacer systems are capturing margin from starch alternatives as North African dairy reformulators prioritize emulsion stability over cost minimization. This technology bifurcation is compressing mid-tier positioning and forcing suppliers to choose between premium functionality and commodity scale.
Growth Catalysts
- NAFDAC Processed Food Standards:Nigeria's tightening additive safety protocols are accelerating formal channel adoption of certified fat replacer systems in Lagos-Abuja manufacturing corridors.
- Chicory-root fiber systems:Prebiotic positioning in Moroccan and Tunisian dairy applications is absorbing reformulation investment as clean-label demand hardens.
- South Africa's Health Department:Mandatory food fortification regulations are embedding fat displacement requirements into industrial bakery specifications.
Market Restraints
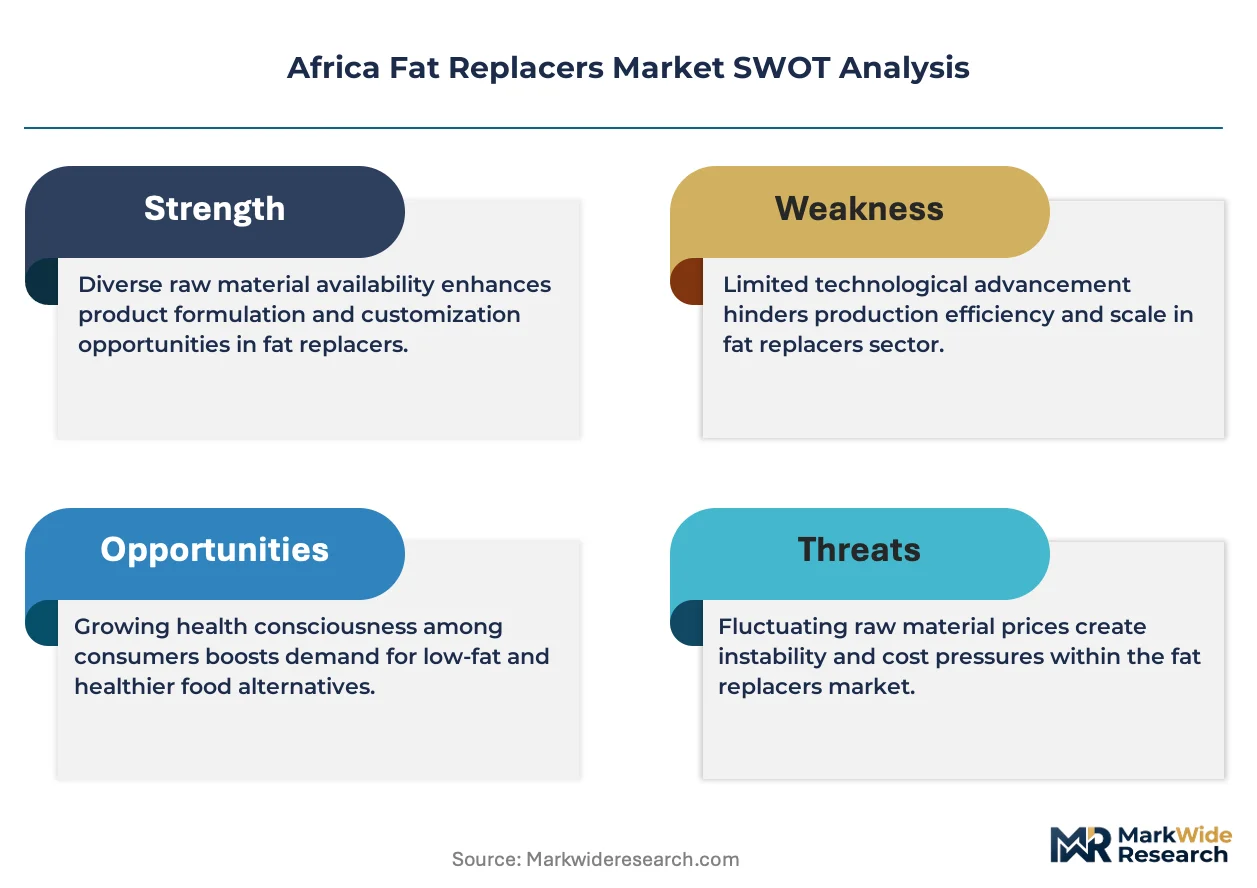
- Sorghum and cassava starch volatility:Input cost swings from West African grain harvests destabilize margin planning for cost-sensitive bakery producers.
- Egypt-Morocco supply concentration:North African import dependency on European specialty protein isolates creates foreign exchange exposure and tariff vulnerability.
- Tropical climate stability gaps:Modified starch systems suffer viscosity degradation during Sub-Saharan ambient storage, limiting inland distribution reach.
Strategic Opportunities
- Kenyan KEBS labeling alignment:Front-of-pack disclosure requirements are redirecting Nairobi-based sauce manufacturers toward lower-fat architectures.
- Cell-cultured protein convergence:Hybrid fat replacer formulations combining plant fiber with precision fermentation proteins are opening premium meat-analogue positioning.
- AfCFTA cross-border harmonization:CODEX-aligned SADC trade corridors are reducing regulatory friction for multi-territory product launches.
Industry Challenges
- Food technologist scarcity:Formulation expertise for protein-starch hybrid systems remains concentrated in South African and Egyptian technical centers, constraining Nigerian and Kenyan plant-scale deployment.
- Legacy equipment retrofit costs:Starch-to-protein line conversions require extruder and hydration system upgrades that extend payback periods for mid-cap African processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Fat Replacers Market |
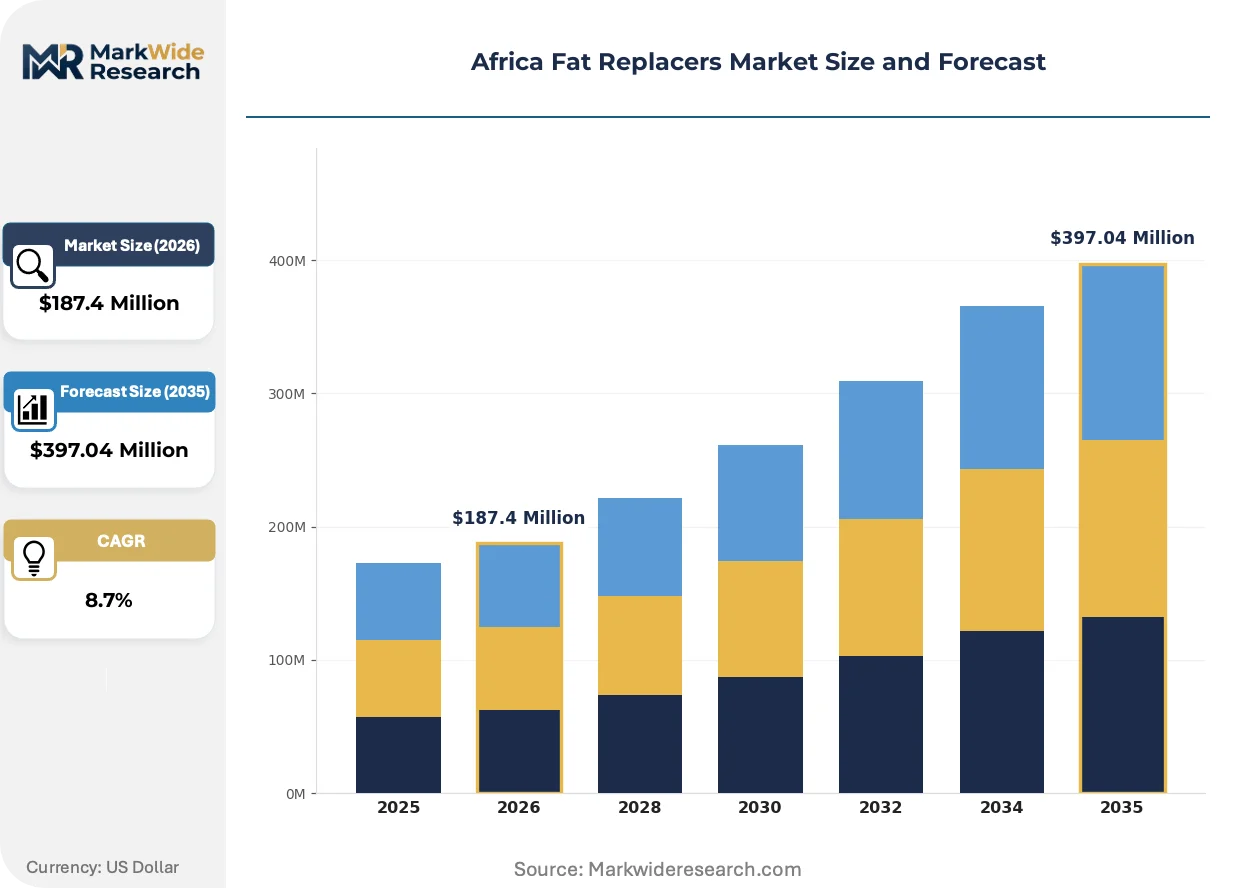
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Starch-Based, Protein-Based, Fiber-Based, Sugar-Based Application: Bakery, Dairy Products, Meat Products, Sauces End User: Food Manufacturers, Beverage Companies, Retailers, Restaurants Form: Powder, Liquid, Granular, Concentrate |
| Companies Covered | Ingredion Incorporated, Corbion N.V., Tate & Lyle PLC, Lesaffre, Ulrick & Short Limited, IOI Corporation Berhad, CP Kelco U.S., Inc., BENEO GmbH, Cargill, Incorporated, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Fat Replacers Market Strategic Shifts
Clean-label prebiotic positioning is displacing purely caloric-reduction claims as the primary purchase driver across African retail channels. This reorientation favors fiber-based systems with demonstrated gut-health benefits over legacy carbohydrate mimics.
Enzymatically treated oat and fava bean protein isolates are absorbing moisture-binding functions in North African processed cheese applications. Egyptian and Moroccan dairy cooperatives are adopting these systems at pilot scale. The technology is absorbing reformulation budgets that previously flowed toward modified starch portfolios, compressing supplier margins in commodity segments.
South Africa's Department of Health is expanding front-of-pack warning label criteria to cover high saturated-fat thresholds. Industrial bakers in Johannesburg and Cape Town are preemptively reformulating to avoid shelf-position penalties. The regulation is accelerating specification changes in contract manufacturing agreements with pan-African retail chains.
Direct-procurement relationships between ingredient suppliers and Nigerian bakery cooperatives are replacing traditional distributor intermediaries. Lagos-based manufacturing clusters are consolidating purchase volumes to secure volume pricing and technical service access. This pattern is most visible in the starch-based fat mimetic segment where price transparency pressures distributor markups.
Africa Fat Replacers Market Segmentation
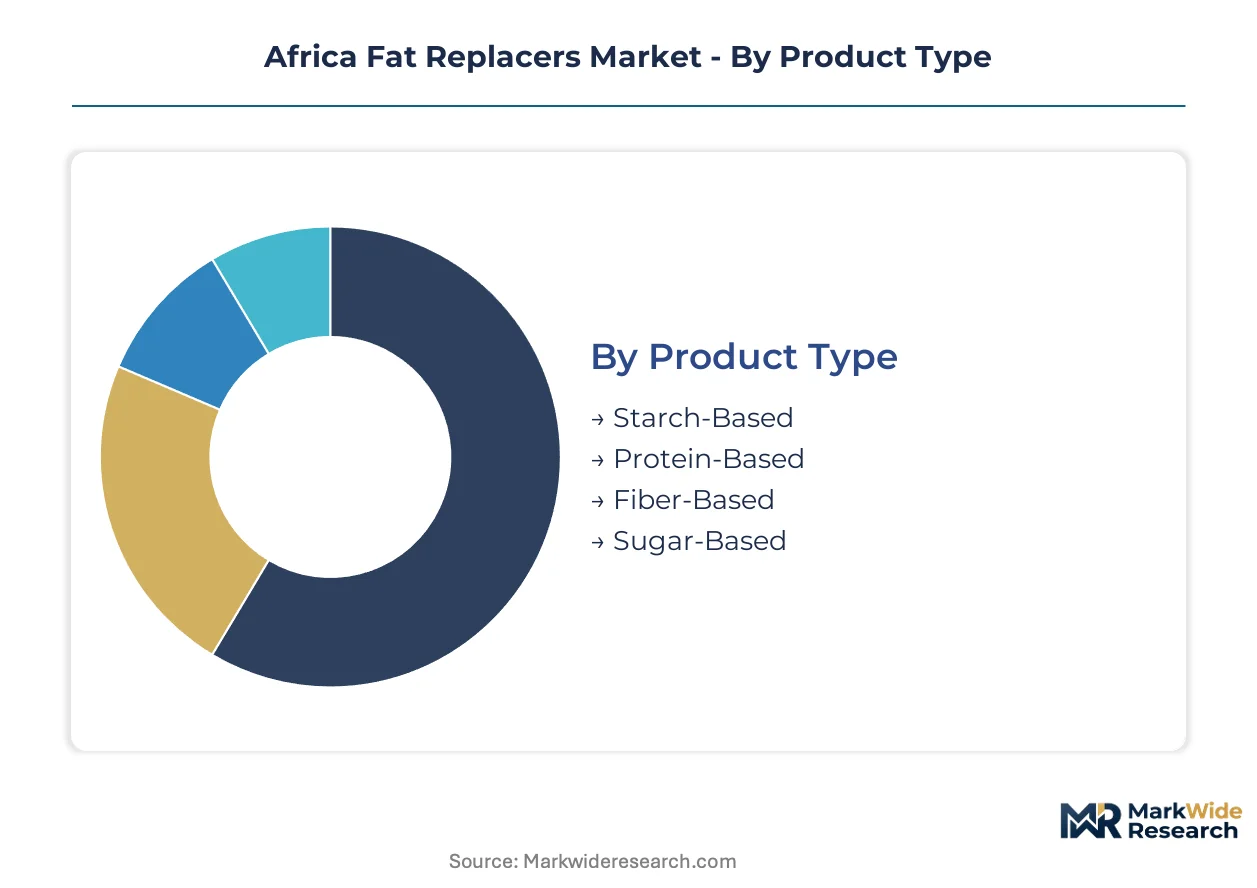
Formulation choices in African fat replacers hinge on climate stability, regulatory alignment, and the technical capabilities of local manufacturing clusters. Buyers prioritize supply security and functional performance over pure cost minimization, creating tiered demand patterns across the continent's diverse food processing landscape.
Product Type:
Buyers segment primarily by the trade-off between functional fidelity and ingredient cost, with climate resilience and clean-label positioning as secondary filters.
- Starch-Based:Sorghum and cassava-derived modified starches deliver cost-efficient fat mimetic performance in ambient-stable bakery applications. Nigerian manufacturers in the Lagos-Abuja corridor absorb the bulk of regional volume, though tropical storage degradation constrains inland distribution reach.
- Protein-Based:Whey and plant protein isolates achieve superior emulsion stability in processed cheese and meat analogues. North African dairy reformulators in Egypt and Morocco absorb premium-priced volumes as FSSAI-aligned safety protocols spread through SADC trade corridors.
- Fiber-Based:Chicory-root and oat fiber systems command preference in clean-label bakery and sauce formulations across Tunisian and Moroccan retail channels.
- Sugar-Based:Maltodextrin and dextrin carriers serve cost-sensitive confectionery and beverage applications with limited functional complexity requirements.
Starch-based systems lead on scale across West African manufacturing; fiber-based formulations lead on momentum as prebiotic positioning hardens in North African retail.
Application:
End-use concentration follows regional dietary patterns and regulatory pressure points, with bakery and dairy absorbing divergent technology investments.
- Bakery:Industrial bread and biscuit producers deploy starch-based fat mimetics to meet South Africa's Department of Health fortification mandates. Johannesburg and Cape Town contract manufacturers preemptively reformulate to avoid front-of-pack warning label penalties.
- Dairy Products:Processed cheese and yogurt applications absorb protein-based and fiber-based systems for emulsion stability and mouthfeel modulation. Egyptian and Moroccan cooperatives pilot enzymatically treated oat and fava bean protein isolates at scale.
- Meat Products:Sausage and processed meat reformulations utilize protein-fat hybrids to reduce saturated fat content while maintaining texture integrity.
- Sauces:Mayonnaise and dressing manufacturers in Nairobi redirect formulation budgets toward lower-fat architectures under Kenya's KEBS labeling disclosure requirements.
Bakery commands the largest installed formulation base; dairy applications are climbing the fastest as North African processors upgrade emulsion technology.
End User:
Procurement sophistication varies sharply by buyer scale, with direct-supplier relationships displacing traditional distribution in high-volume clusters.
- Food Manufacturers:Pan-African bakery and dairy processors consolidate purchase volumes to secure technical service access and volume pricing. Direct procurement patterns are most visible in Nigerian starch-based fat mimetic sourcing.
- Beverage Companies:Limited direct absorption; fat replacer deployment concentrates in dairy-based ready-to-drink applications with texture requirements.
- Retailers:Private-label reformulation mandates from pan-African chains drive specification changes in contract manufacturing agreements.
- Restaurants:Minimal direct procurement; food service demand flows through prepared sauce and dressing manufacturers.
Food manufacturers dominate absolute volume; retailer-driven reformulation specifications are gaining share fastest as front-of-pack regulations tighten.
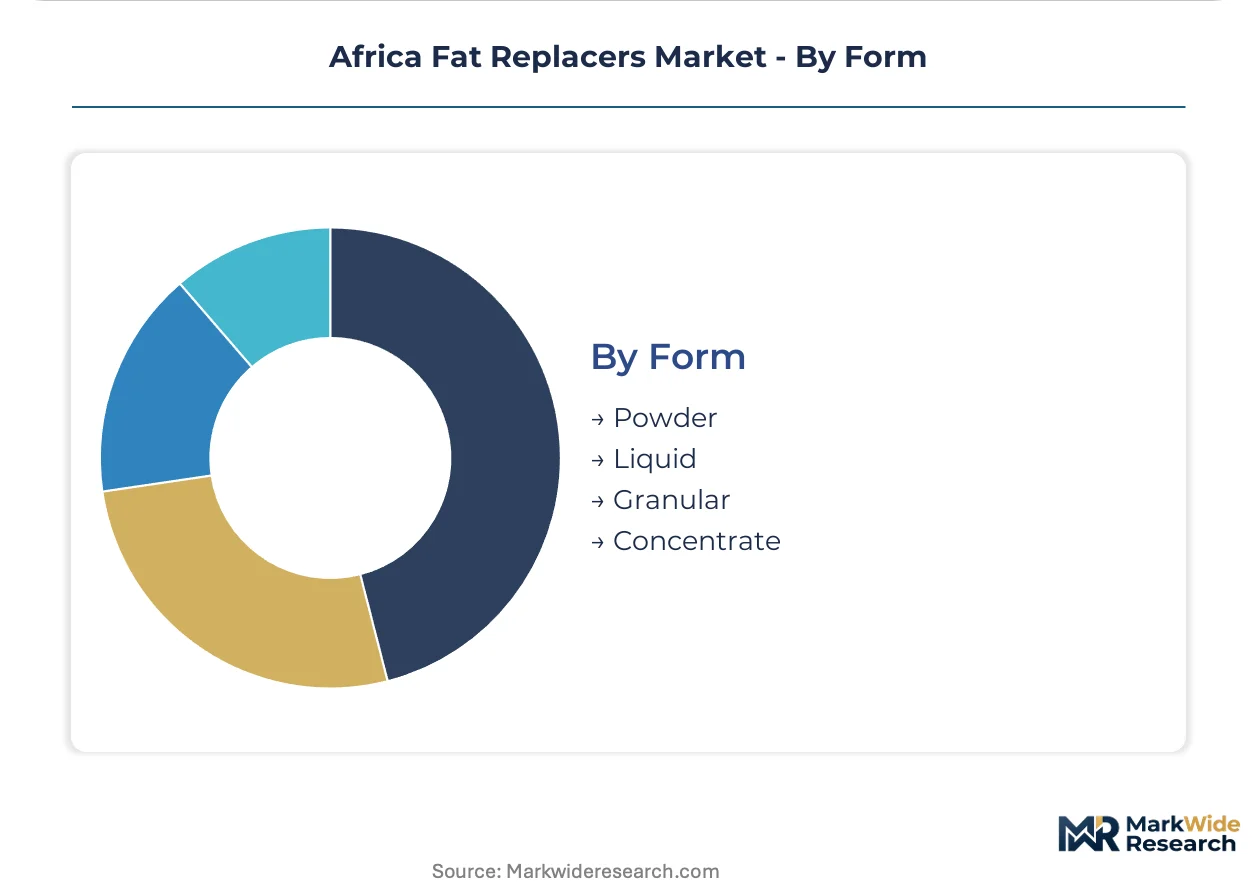
Form:
Physical format selection tracks processing equipment compatibility and ambient storage constraints across Sub-Saharan distribution networks.
- Powder:Dominant format for starch and protein isolates, offering extended shelf stability and flexible hydration in bakery and dairy applications. Dry handling infrastructure is widespread across African manufacturing plants.
- Liquid:Pre-hydrated protein and fiber suspensions reduce processing steps for sauce and dairy manufacturers with continuous production lines.
- Granular:Intermediate format for specific meat and bakery applications requiring controlled particle size distribution.
- Concentrate:High-solids fiber and protein preparations for freight-efficient import into landlocked manufacturing clusters.
Powder formulations lead on manufacturing penetration; liquid concentrates are expanding most quickly as coastal processors seek line-efficiency gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Food technologists and formulation chemists cluster in Johannesburg, Cairo, and Casablanca, anchoring technical service capabilities for fat replacer deployment across the continent. These talent concentrations shape where suppliers locate application laboratories and where processors first adopt advanced protein-starch hybrid systems.
South Africa
Industrial bakers in Johannesburg and Cape Town absorb starch-based fat mimetics to comply with Department of Health fortification mandates. Front-of-pack warning label expansion is accelerating preemptive reformulation in contract manufacturing agreements. The Western Cape dairy corridor is piloting protein-based emulsion systems for processed cheese applications.
Nigeria
Bakery cooperatives in the Lagos-Abuja manufacturing corridor consolidate procurement volumes for sorghum and cassava-derived starch systems. NAFDAC processed food standards are tightening additive safety protocols and accelerating formal channel adoption. Direct supplier relationships are displacing traditional distributor intermediaries in starch-based fat mimetic sourcing.
Egypt
Dairy reformulators in Cairo and Alexandria prioritize protein-based systems for emulsion stability in processed cheese. The country's national food safety regulator aligns with CODEX Alimentarius frameworks governing cross-border trade. Egyptian cooperatives are piloting enzymatically treated oat and fava bean protein isolates at scale.
Morocco
Clean-label demand in Tunisian and Moroccan retail channels is absorbing chicory-root fiber systems for prebiotic positioning. The country's food safety authority enforces standards that elevate specification thresholds for imported fat replacers. Casablanca-based dairy processors are upgrading emulsion technology to capture premium positioning.
Kenya
Sauce manufacturers in Nairobi are redirecting formulation budgets toward lower-fat architectures under KEBS labeling disclosure requirements. The country's standards body mandates front-of-pack disclosure that redirects investment. Kenyan food technologists remain scarce, constraining plant-scale deployment of protein-starch hybrid systems outside Nairobi.
Africa Fat Replacers Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the African fat replacers landscape. Integrated grain processors with captive starch extraction capacity face specialty ingredient houses sourcing protein isolates through third-party toll manufacturing. The market structure fragments between commodity-scale starch suppliers and premium-positioned fiber and protein specialists. Two strategic archetypes dominate: regional grain processors leveraging local supply security, and European specialty houses differentiating through clean-label prebiotic positioning. Competitive intensity centers on direct procurement relationships with Nigerian bakery clusters and technical service proximity to North African dairy reformulators.
Among the integrated agribusiness tier, Cargill, Incorporated anchors supply security through regional grain processing infrastructure. BENEO GmbH exemplifies the European specialty archetype, occupying a position in chicory-root-derived fiber systems. Tate & Lyle PLC sits within the modified starch segment, representing climate-stability-focused formulation capabilities. These three companies illustrate the competitive spectrum from commodity scale to premium functionality.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Corbion N.V. |
| Tate & Lyle PLC |
| Lesaffre |
| Ulrick & Short Limited |
| IOI Corporation Berhad |
| CP Kelco U.S., Inc. |
| BENEO GmbH |
| Cargill, Incorporated |
| Others |
Value Chain & Pricing Dynamics
Sorghum and cassava starch price indices in West African grain markets cascade through three distinct pricing tiers for fat replacer procurement. Nigerian bakery cooperatives in the Lagos-Abuja corridor absorb economy-grade modified starches when harvest volatility compresses margins, while North African dairy reformulators in Egypt and Morocco absorb premium protein isolates regardless of commodity cycles.
Pricing Analysis
Technical service bundling versus unbundled ingredient supply splits the African fat replacer market into divergent pricing architectures. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and volume scale, with FSSAI-aligned safety protocols commanding tier premiums. Price erosion runs through starch-based segments as direct procurement displaces distributor markups in Nigerian manufacturing clusters. Food manufacturers with pan-African retail contracts exhibit lowest price sensitivity; small bakery cooperatives in inland Nigeria show highest elasticity to input cost swings.
Supply Chain Analysis
Direct-to-manufacturer channels handle high-volume demand from Johannesburg and Lagos bakery clusters, while distributor networks serve fragmented Kenyan and Tunisian processors. Supply concentrates in South Africa, Egypt, and Nigeria as regional formulation hubs, with European specialty protein isolates feeding North African dairy operations. Raw material flows draw from West African sorghum and cassava harvests, chicory-root fiber from European toll manufacturers, and whey protein from SADC trade corridors. Single-source vulnerability in European protein isolate supply creates foreign exchange exposure for Egyptian and Moroccan reformulators. Distribution runs through coastal port infrastructure with limited cold-chain reach into Sub-Saharan inland markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where front-of-pack warning label expansion across Egypt, Morocco, and South Africa mechanically redirects formulation investment toward lower-fat architectures.
For Market Incumbents: Cement technical service proximity to North African dairy reformulators by locating application laboratories in Casablanca and Cairo. Defend margin position through backward integration into regional grain processing, capturing sorghum and cassava starch supply security that insulates against West African harvest volatility. Incumbent suppliers face displacement risk from hybrid protein-fiber systems combining precision fermentation with plant fiber. For New Entrants and Emerging Players: Launch via direct-procurement relationships with Nigerian bakery cooperatives consolidating volumes in the Lagos-Abuja corridor. Target Kenyan sauce manufacturers under KEBS labeling disclosure requirements as the most penetrable white-space segment. White-space opportunity sits with enzymatically treated oat and fava bean protein isolates for North African processed cheese applications where incumbent portfolios lag. For Investors and Strategic Acquirers: Asymmetric upside sits with European specialty houses possessing chicory-root fiber extraction capacity and clean-label prebiotic positioning. Five-to-ten year viability hinges on AfCFTA cross-border harmonization reducing regulatory friction for multi-territory product launches. Acquisition target archetype: mid-cap African grain processors with captive starch extraction and underutilized extrusion infrastructure. Signal to watch: NAFDAC processed food standards tightening accelerating formal channel adoption rates in Nigerian manufacturing corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Application Laboratory Expansion | Cairo and Casablanca technical centers anchor protein-starch hybrid deployment for North African dairy reformulators. |
| Direct Procurement Consolidation | Lagos-Abuja bakery clusters bypass distributor markups through volume aggregation with starch-based fat mimetic suppliers. |
| Backward Integration into Grain Processing | Captive sorghum and cassava extraction insulates Nigerian manufacturers from West African harvest volatility. |
| Prebiotic Positioning Investment | Chicory-root fiber systems capture clean-label premium in Tunisian and Moroccan retail channels. |
| CODEX Alignment Certification | FSSAI-aligned safety protocols enable cross-border trade through SADC corridors into South African industrial bakeries. |
Study Parameters
Coverage spans North Africa, West Africa, East Africa, and Southern Africa, with primary inputs from each regional manufacturing cluster. Research combines structured interviews with food technologists, procurement leads at pan-African bakery processors, regulatory affairs officers at NAFDAC and South Africa's Department of Health, and distribution channel partners in Nairobi and Lagos. Secondary validation draws from CODEX Alimentarius framework documentation, AfCFTA trade corridor harmonization protocols, KEBS labeling requirement filings, and customs records for starch and protein isolate imports. Bottom-up volume estimates from manufacturing plant capacities triangulate against top-down demand projections from retail channel audits.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type, application, end-user procurement sophistication, and physical form compatibility with ambient storage constraints. CAGRs derive from regression against historical formulation adoption curves in comparable regulatory environments. Industry-specific forecast inputs incorporate front-of-pack warning label implementation timelines and NAFDAC processed food standards evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under AfCFTA implementation delays or front-of-pack regulatory reversal. Projections reflect assumptions regarding climate stability technology advancement and food technologist talent pipeline development in Nigerian and Kenyan technical centers. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Mycoprotein Products Market
Alternative Food Sources
Single Cell Oil Market
Alternative Food Sources
Egg Replacers Market
Alternative Food Sources
Spirulina Beverages Market
Alternative Food Sources
Fat Replacers Market
Alternative Food Sources
Flaxseed Based Egg Replacement Market
Alternative Food Sources
Single Cell Protein Market
Alternative Food Sources
Europe Emergency Food Market
Alternative Food Sources
Konjac Market
Alternative Food Sources
United States Hemp Protein Market
Alternative Food Sources
Vegan Caviar Market
Alternative Food Sources
Global Algal Oil Market
Alternative Food Sources
Low Calorie Rice Market
Alternative Food Sources
Vegan Sashimi Market
Alternative Food Sources
North America Algae Protein Market
Alternative Food Sources
Global Algae Market