
 Monoprotein Market | 2026-2036
Monoprotein Market Size, Share, and Industry Trends Forecast 2026-2036
Monoprotein Market Foresight
Single-protein pouches and portion-controlled trays is decoupling bulk kibble from premium-positioned monoprotein offerings, letting buyers trial novel proteins without committing to large-format bags. Purina PetCare leverages its veterinary channel relationships to sustain clinic-level recommendation rates for its limited-ingredient lines. Mars competes through specialized manufacturing assets that anchor European production of species-specific formulations. Brit Mono Protein differentiates via regional sourcing partnerships that control ingredient traceability across its lamb and fish portfolios.
Monoprotein denotes pet nutrition formulations containing one identifiable animal protein source, typically achieving protein digestibility coefficients above 85% through controlled hydrolysis or minimal-processing thermal treatments designed to preserve amino acid bioavailability. The primary commercial purpose centers on elimination-diet protocols for food-sensitive companion animals and clean-label positioning for health-conscious owners. Dog Food occupies the dominant value share as veterinary prescription diets and premium retail lines both expand single-protein SKUs, while Fish-based sourcing represents the fastest-growing origin category as ocean-derived proteins address both novel-protein demand and omega-3 functional claims. Pouch packaging captures accelerating share among urban pet owners prioritizing portion precision and refrigeration convenience over traditional can formats.
FEDIAF guidelines in Europe, FDA Center for Veterinary Medicine feed regulations in the United States, and AAFCO nutrient profiles collectively define protein minimums, contaminant thresholds, and label claim permissibility for monoprotein products. These frameworks elevate compliance costs for new entrants while rewarding incumbents with established analytical laboratories and regulatory affairs infrastructure. Stakeholders must monitor evolving novel-protein approval pathways for insect and cultivated meat sources, as regulatory clarity will determine which suppliers can credibly extend their single-protein positioning beyond conventional livestock and fish species.
Market Dynamics
The monoprotein market is absorbing structural pressure from veterinary channel consolidation and clean-label certification requirements, which are compressing formulation flexibility while rewarding suppliers with dedicated analytical infrastructure and species-specific manufacturing assets.
Growth Catalysts
- Novel protein sourcing:Insect and cultivated meat R&D pipelines are advancing through EFSA novel food approval pathways, creating future category expansion vectors beyond conventional livestock proteins.
- FEDIAF nutritional guidelines:Tightening European formulation standards are elevating compliance barriers that favor incumbents with established laboratory networks and regulatory affairs capabilities.
- Veterinary prescription protocols:Elimination-diet recommendations from companion animal clinics are driving sustained demand for single-protein formulations with documented digestibility coefficients.
Market Restraints
- Novel protein cost premiums:Insect and cell-cultured protein inputs carry 3-5x cost multiples versus conventional poultry and fish meals, compressing margin structures for mass-market positioning.
- Atlantic fishmeal supply concentration:Peruvian and Norwegian fishery quotas dominate omega-3-rich protein inputs, exposing formulations to El Niño-driven catch volatility and quota restrictions.
- Hydrolysis equipment scarcity:Controlled thermal treatment systems achieving 85%+ protein digestibility require specialized stainless-steel vessels with limited European manufacturing capacity.
Strategic Opportunities
- Urban pet owner channel expansion:Refrigerated pouch formats are capturing trial-oriented buyers in Paris, Milan, and Berlin who prioritize portion precision over bulk kibble economics.
- AAFCO nutrient profile harmonization:Converging US and European protein minimum standards are enabling formulation platform standardization across transatlantic markets.
- Telemedicine veterinary platforms:Remote consultation services are expanding prescription diet access beyond traditional clinic footprints, opening direct-to-consumer pathways for limited-ingredient lines.
Industry Challenges
- Clean-label certification timelines:Third-party traceability audits for single-origin protein claims require 12-18 month validation cycles that delay product launches.
- Thermal processing expertise gaps:Minimal-processing techniques preserving amino acid bioavailability demand specialized food engineering talent scarce in conventional pet food operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Monoprotein Market |
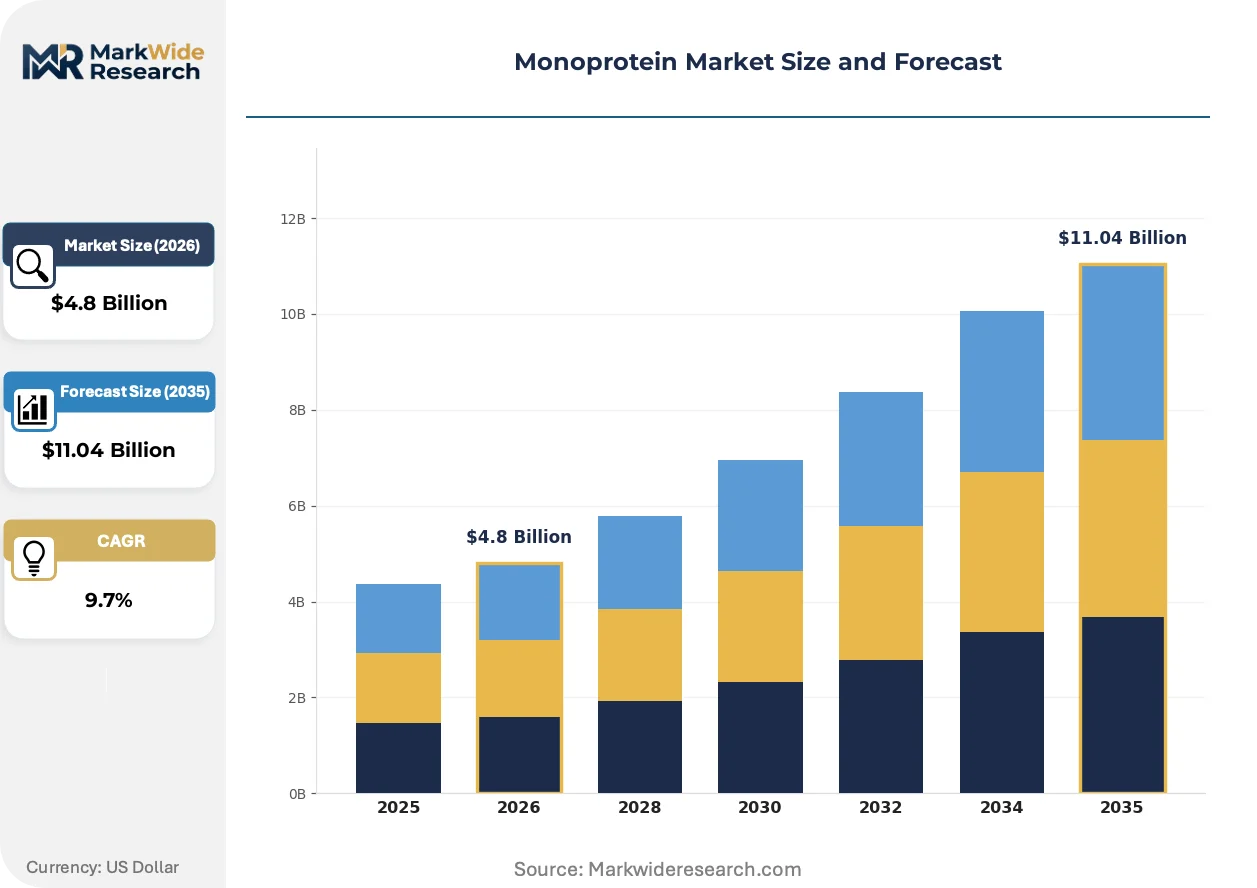
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dog Food, Cat Food, Treats, Supplements Source: Beef, Chicken, Fish, Lamb End User: Pet Owners, Veterinarians, Retailers, Distributors Packaging Type: Bags, Cans, Pouches, Wrappers |
| Companies Covered | Monge SPA, Purina PetCare, Brit Mono Protein, Country Farms, Stuzzy Monoprotein, Nestlé, Mars, Blue Diamond Growers, Danone SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Monoprotein Market Shifts & Advancements
Formulation science and packaging engineering are converging to reshape competitive positioning, with controlled hydrolysis methods and portion-controlled formats displacing legacy canning and bulk kibble conventions.
Cold-pressed protein extraction is absorbing thermal degradation risk from conventional rendering while preserving immunoglobulin integrity for sensitive companion animals. Premium retail buyers in France and Germany are adopting these formats at accelerating rates. The technology is absorbing shelf space from traditional canned monoprotein lines as refrigeration infrastructure penetrates urban households.
EFSA novel food approval frameworks are tightening substantiation requirements for insect and cultivated protein safety dossiers. Compliance timelines now extend 24-36 months for first-mover suppliers. European monoprotein innovators are responding by pre-submission engagement with EFSA scientific panels and parallel-track US FDA consultations.
Subscription-based replenishment models are compressing traditional retail stocking cycles for single-protein pouches. Urban millennial pet owners in London and Amsterdam are shifting volume from supermarkets to direct channels offering personalized portion algorithms. This behavioral pivot is most visible among dog owners managing chronic food sensitivities requiring consistent protein rotation protocols.
Monoprotein Market Segmentation
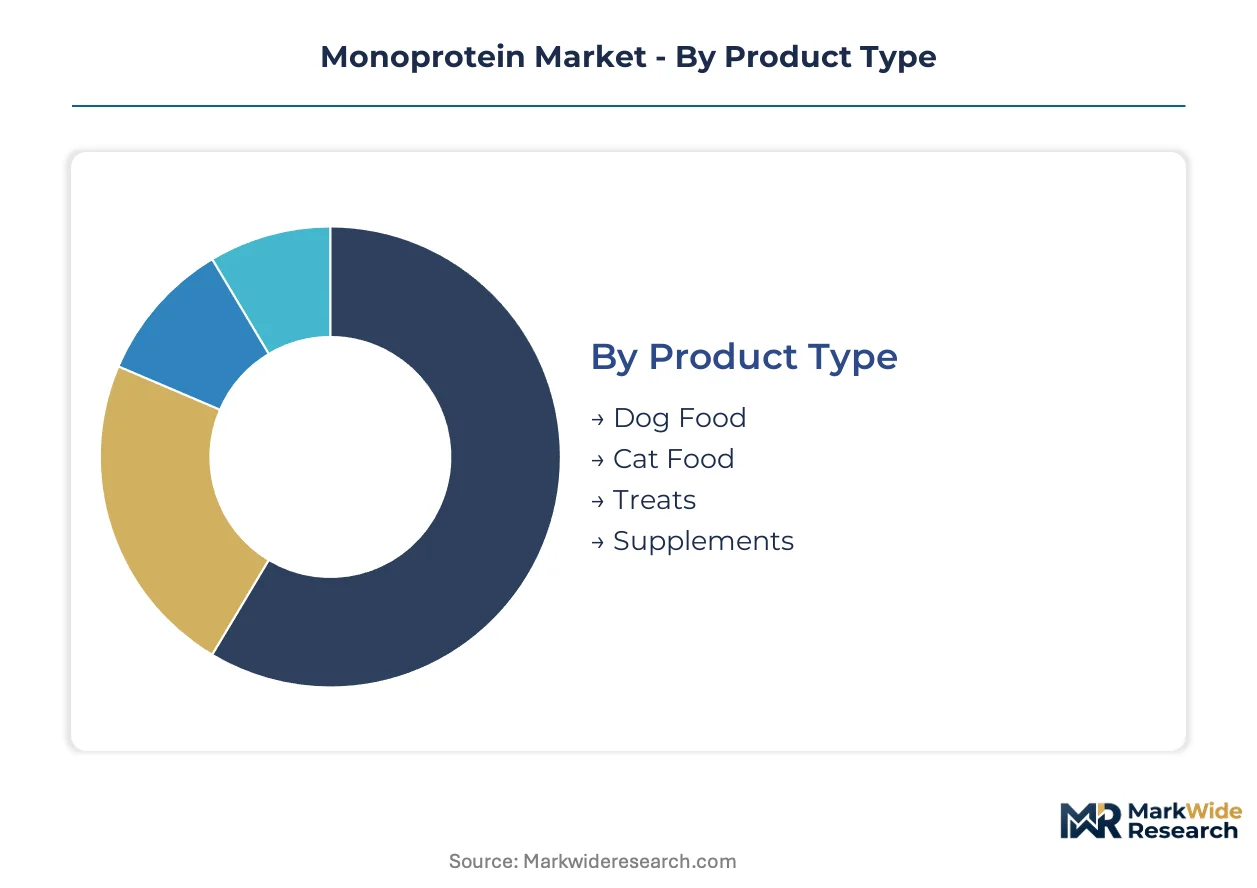
Monoprotein segmentation reflects divergent supply chain capabilities across protein sourcing, species-specific formulation expertise, and packaging cold-chain infrastructure. Each dimension carries distinct margin profiles and regulatory compliance burdens that reshape competitive positioning.
Product Type:
Supply concentration in veterinary-grade manufacturing assets favors species-specific production lines over flexible co-packing arrangements.
- Dog Food:Veterinary prescription diets and premium retail lines command dedicated single-protein SKUs with documented digestibility coefficients above 85%. Demand concentrates in France, Germany, and Italy where clinic-level endorsement drives sustained shelf space and owner willingness to pay formulation premiums.
- Cat Food:Feline obligate carnivore physiology necessitates higher protein minimums and taurine fortification, elevating raw material specification thresholds. Italian and German urban owners are adopting refrigerated pouch formats for portion-controlled feeding regimens.
- Treats:Functional positioning around dental health and training rewards absorbs novel protein inputs at lower inclusion rates than complete diets.
- Supplements:Powder and liquid formats target owners managing chronic conditions through protein rotation protocols.
Today's leader: Dog Food. Tomorrow's challenger: Cat Food.
Source:
Cost tier stratification separates commodity poultry inputs from premium-positioned novel proteins with traceability premiums.
- Fish:Ocean-derived proteins address dual demand for novel-protein rotation and omega-3 functional claims. Norwegian and Peruvian fishery quotas dominate supply, exposing formulations to El Niño-driven catch volatility.
- Lamb:Regional sourcing partnerships in New Zealand and Australia control ingredient traceability for elimination-diet protocols. British and French buyers absorb premium positioning for grass-fed provenance claims.
- Chicken:Conventional poultry meal dominates volume through cost-efficient hydrolysis and established supply chains.
- Beef:Bovine protein carries higher allergen incidence in companion animals, limiting prescription diet adoption.
Current volume anchor: Chicken. Steepest expansion trajectory: Fish.
End User:
Application-specific purchasing behavior separates trial-oriented retail buyers from protocol-driven veterinary channel demand.
- Veterinarians:Elimination-diet recommendations require documented protein digestibility and batch-level consistency. German and French clinic networks maintain direct supplier relationships bypassing distributor markups.
- Pet Owners:Urban millennial buyers in London, Amsterdam, and Berlin prioritize subscription replenishment and portion precision over bulk economics.
- Retailers:Supermarket and specialty pet chains stock limited SKUs based on velocity thresholds and certification requirements.
- Distributors:Cold-chain logistics capabilities determine pouch format penetration in secondary markets.
Dominant influence point: Veterinarians. Fastest-growing access channel: Pet Owners.
Packaging Type:
Customer type differentiation separates urban apartment dwellers prioritizing refrigeration convenience from rural bulk buyers.
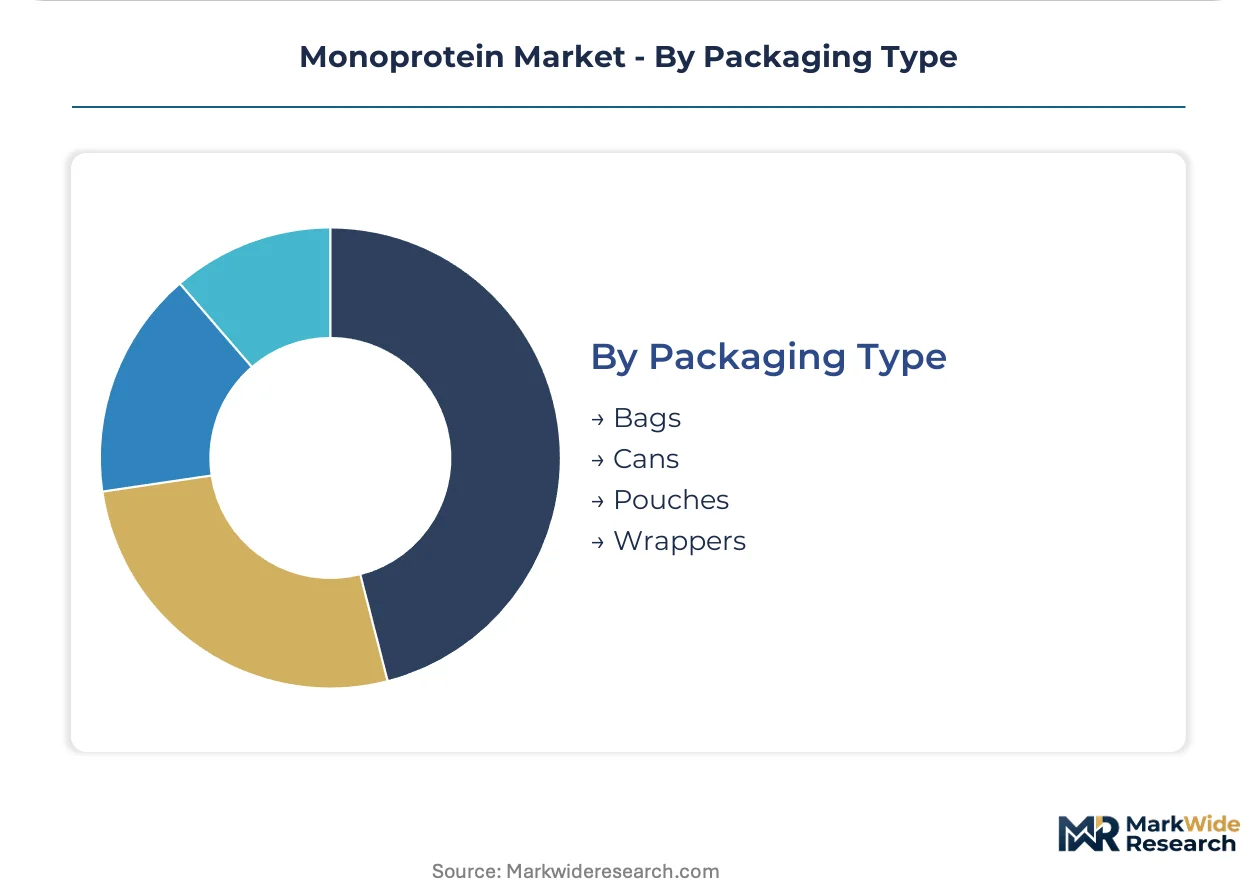
- Pouches:Portion-controlled formats capture accelerating share among Paris, Milan, and Berlin owners managing food-sensitive animals through precise protein rotation. Refrigeration infrastructure penetration enables displacement of traditional can formats.
- Cans:Thermal sterilization preserves shelf stability for stockpiling behavior and veterinary clinic inventory management.
- Bags:Bulk kibble economics retain volume in multi-pet households and price-sensitive segments.
- Wrappers:Single-serve treat formats support training and intermittent reinforcement schedules.
Established standard: Cans. Gaining share fastest: Pouches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Monoprotein nutrition originated in Western European veterinary clinics during the 1990s, where elimination-diet protocols for food-sensitive companion animals first achieved clinical standardization. France, Germany, and Italy remain the foundational markets where premium single-protein formulations command sustained shelf space and veterinary endorsement.
France
Paris and Lyon urban owners drive refrigerated pouch adoption for portion-controlled feeding regimens. ANSM veterinary feed oversight aligns with FEDIAF nutritional guidelines to elevate formulation compliance costs. The Île-de-France corridor concentrates cold-chain logistics infrastructure enabling direct-to-consumer subscription models.
Germany
Berlin and Munich millennial pet owners prioritize subscription replenishment over supermarket bulk purchasing. KBA-adjacent feed safety frameworks and BfR contaminant thresholds tighten batch-level consistency requirements. Bavaria hosts specialized hydrolysis equipment manufacturers serving species-specific production lines.
Italy
Milan and Rome clinics sustain direct supplier relationships bypassing distributor markups for prescription diet protocols. Ministry of Health veterinary feed regulations mandate documented protein digestibility coefficients above 85%. The Emilia-Romagna region anchors refrigerated pouch manufacturing for feline obligate carnivore formulations.
United Kingdom
London and Amsterdam-influenced urban corridors absorb novel protein rotation demand through telemedicine veterinary platforms. FSA and Defra feed regulations converge with post-Brexit AAFCO harmonization efforts. The Southeast England cluster develops insect-protein R&D pipelines awaiting EFSA novel food clearance.
United States
Coastal metropolitan owners in Boston and San Francisco trial limited-ingredient lines through direct channels. FDA Center for Veterinary Medicine feed regulations and AAFCO nutrient profiles define protein minimums and label claim permissibility. Pacific Northwest cold-pressed extraction facilities preserve immunoglobulin integrity for sensitive animals.
Monoprotein Market Competitive Landscape
Premium-margin players sit above commodity-margin players across protein traceability and veterinary channel certification tiers. The vendor base stratifies between multinational pet nutrition conglomerates with dedicated analytical laboratories and regional specialists controlling single-origin sourcing partnerships. Three archetypes dominate: veterinary-channel incumbents leveraging clinic endorsement networks, manufacturing-asset owners with species-specific production lines, and traceability-focused regionalists commanding grass-fed provenance premiums. Competitive moves concentrate on M&A for hydrolysis equipment access and strategic partnerships securing Norwegian and Peruvian fishery quotas.
Within the veterinary-channel tier, Purina PetCare and Mars exemplify incumbents with established regulatory affairs infrastructure. Brit Mono Protein occupies a position among regional specialists emphasizing ingredient traceability. Monge SPA anchors Italian manufacturing heritage in species-specific formulation.
| Leading Market Players |
|---|
| Monge SPA |
| Purina PetCare |
| Brit Mono Protein |
| Country Farms |
| Stuzzy Monoprotein |
| Nestlé |
| Mars |
| Blue Diamond Growers |
| Danone SA |
| Others |
Supply & Pricing Matrix
Specialized food engineering talent concentrated in Bavaria and Emilia-Romagna commands wage premiums that widen spreads between premium hydrolyzed formulations and standard thermal-processed lines. Labor-cost differentials in these regions directly translate into pricing-tier stratification across European markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates veterinary prescription diets from retail premium lines and private-label economy offerings. Price differentiation rests on certification grade—FEDIAF-compliant formulations command 15-20% premiums over baseline AAFCO-aligned products—and protein digestibility documentation above 85%. Cost compression in the economy tier is intensifying because commodity poultry meal oversupply in Brazil and Thailand feeds into European co-packing networks. Veterinary clinics exhibit lowest price sensitivity due to protocol-driven purchasing, while multi-pet households in suburban France absorb highest price sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with Norwegian and Peruvian fishery quotas dominating omega-3-rich fishmeal inputs. Geographic supply concentration centers on Peru, Norway, and Chile for marine proteins, while New Zealand and Australia anchor lamb sourcing for elimination-diet protocols. Raw material dependencies include Atlantic fishmeal, grass-fed lamb shoulder, and hydrolyzed poultry isolate. Tariff exposure looms as post-Brexit UK-EU veterinary feed certification divergence threatens cross-border ingredient flows. Distribution runs through cold-chain logistics specialists serving Paris, Berlin, and Milan metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where FEDIAF guideline tightening through 2024-2025 elevates compliance barriers that permanently advantage incumbents with laboratory infrastructure.
For Market Incumbents: Extend analytical laboratory networks into secondary European markets to preempt regional certification requirements. Consolidate manufacturing assets around species-specific production lines in Bavaria and Emilia-Romagna to defend against emerging regional specialists with traceability partnerships. Channel control through direct veterinary clinic relationships remains the critical defensive lever. For New Entrants and Emerging Players: The mid-tier price gap between premium veterinary prescriptions and economy retail lines offers white-space entry for certified-clean-label challengers. Target refrigerated pouch formats in London and Amsterdam where subscription-oriented millennials exhibit low brand loyalty and high trial willingness. Pursue telemedicine veterinary platform partnerships as the most penetrable go-to-market angle bypassing traditional clinic gatekeepers. For Investors and Strategic Acquirers: Multinational pet nutrition conglomerates are the most active acquirer in this space, seeking hydrolysis equipment access and novel-protein R&D pipelines. Long-term viability favors targets with EFSA pre-submission engagement and parallel-track FDA consultation capabilities. The inflection signal to watch is EFSA novel food approval clarity for insect and cultivated meat sources, which will determine category expansion vectors.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrolysis Equipment Acquisition | Secures Bavarian stainless-steel vessel capacity for 85%+ digestibility certification. |
| Fishery Quota Partnership | Locks Norwegian and Peruvian marine protein supply against El Niño volatility. |
| EFSA Pre-Submission Engagement | Accelerates insect-protein approval timelines through early scientific panel dialogue. |
| Telemedicine Platform Integration | Expands prescription diet access beyond traditional clinic footprints in urban corridors. |
| Cold-Chain Logistics Expansion | Enables pouch format penetration in Milan and Berlin apartment-dwelling segments. |
Research Methodology
Direct dialogue with veterinary nutritionists, regulatory affairs directors at feed manufacturers, cold-chain logistics operators, and specialty pet retail category buyers grounded qualitative findings. Secondary validation drew from FEDIAF annual reports, FDA Center for Veterinary Medicine feed guidance documents, EFSA novel food safety opinions, and customs trade data for fishmeal and hydrolyzed protein inputs. Bottom-up SKU-level volume estimates triangulated against top-down market sizing from industry federation disclosures.
Segment-level value projections across the analysis window reflect modeled interactions between protein source cost curves, packaging format adoption rates, and channel shift dynamics. The analytical framework incorporated dog food, cat food, treats, and supplements by product type; fish, lamb, chicken, and beef by source; and veterinarians, pet owners, retailers, and distributors by end user. CAGRs were derived from regression analysis of historical protein input pricing and veterinary channel expansion rates, with cross-validation against FEDIAF member company production disclosures.
Caveats apply where EFSA novel food approval delays, El Niño-driven fishery quota cuts, or telemedicine regulatory restrictions could materially shift the outlook. Forecasts reflect assumptions about sustained veterinary endorsement rates and urban refrigeration infrastructure penetration. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Mock Meat Market
Alternative Food Sources
Meal Replacement Products Market
Alternative Food Sources
Synthetic Food Market
Alternative Food Sources
South American Algae Protein Market
Alternative Food Sources
Gluten Replacer Market
Alternative Food Sources
Africa Protein Market
Alternative Food Sources
Mycoprotein Market
Alternative Food Sources
North America Meat Substitutes Market
Alternative Food Sources
Single Cell Protein Market
Alternative Food Sources
Spirulina Beverages Market
Alternative Food Sources
Edible Packaging Market
Alternative Food Sources
Meal Replacement Bars Market
Alternative Food Sources
North America Algae Protein Market
Alternative Food Sources
Quinoa Protein Market
Alternative Food Sources
Bagasse Disposable Cutlery Market
Alternative Food Sources
Flaxseed Based Egg Replacement Market