
 Molecular Imaging Market | 2026-2036
Molecular Imaging Market Size, Share, and Industry Trends Forecast 2026-2036
Molecular Imaging Market Outlook
Oncology is pivoting toward theranostic protocols that pair diagnostic scans with targeted radionuclide therapy, reshaping capital allocation across hospital networks. GE HealthCare leverages its cyclotron network to secure isotope supply chains for PET radiopharmaceuticals. Siemens Healthineers anchors its position through dual-source CT integration with PET systems for sub-minute whole-body imaging. Koninklijke Philips N.V. competes on AI-enabled reconstruction software that reduces tracer dose requirements while preserving image quality.
Molecular imaging comprises non-invasive techniques that detect and visualize cellular and molecular processes in living organisms using radioactive tracers, magnetic fields, or light-emitting probes, with spatial resolution ranging from millimeters to sub-millimeter scales depending on modality. Its primary purpose is to enable early disease detection, monitor therapeutic response, and guide personalized treatment selection before structural anatomical changes become visible. Positron Emission Tomography dominates value capture due to high cyclotron infrastructure barriers and recurring radiopharmaceutical consumption. Hybrid Imaging represents the fastest-expanding technology segment as PET-MRI and PET-CT systems consolidate anatomical and functional data into single workflows. Optical Imaging occupies a specialized niche in preclinical research and intraoperative guidance where real-time feedback outweighs depth penetration limits.
FDA regulates radiopharmaceutical safety and efficacy under 21 CFR Part 315, while EMA oversees centralized marketing authorization for tracer agents across EU member states, and NMPA enforces GB standards for medical imaging equipment performance in China. These frameworks shape demand by determining which tracers reach clinical practice and what technical specifications equipment must satisfy for market access. Stakeholders must monitor reimbursement decisions for novel radiotracers in major markets, as coverage determinations will dictate whether capital investments in hybrid systems generate adequate procedure volume.
Market Dynamics
Theranostic convergence is compressing the diagnostic-therapy continuum, forcing hospital networks to consolidate PET-CT procurement with radionuclide therapy infrastructure rather than treating these as separate capital decisions.
Growth Catalysts
- IRA Medicare Reimbursement Expansion:The US Inflation Reduction Act's coverage provisions for novel radiotracers is accelerating clinical trial enrollment and commercial launch velocity for precision oncology agents.
- Hybrid Imaging Adoption:Academic medical centers in Germany, China, and the United States are deploying PET-MRI suites for pediatric and neurologic applications where reduced radiation exposure outweighs throughput considerations.
- Cyclotron Network Densification:Regional isotope production hubs in Texas, Bavaria, and Guangdong are shortening fluorine-18 half-life logistics, enabling same-day tracer synthesis for community hospital networks.
Market Restraints
- Molybdenum-99 Supply Concentration:Four aging reactors in the Netherlands, Belgium, South Africa, and Australia supply the majority of technetium-99m generators; unplanned outages create procedure backlogs.
- Radiopharmaceutical Manufacturing Complexity:Current Good Manufacturing Practice (cGMP) compliance for positron-emitting tracers requires specialized cleanroom infrastructure that limits contract manufacturing options.
- Deep Tissue Penetration Limits:Optical imaging modalities face fundamental physics constraints that restrict clinical translation beyond intraoperative and dermatologic applications.
Strategic Opportunities
- India Diagnostic Infrastructure Gap:The country's PET-CT installed base remains below one unit per million population, creating first-mover advantage for equipment-leasing models tied to radiotracer supply contracts.
- AI-Enabled Dose Reduction:Deep learning reconstruction algorithms are converging with low-count PET acquisition protocols to enable pediatric and repeat-scan applications previously excluded by cumulative radiation limits.
- EU Green Deal Isotope Diversification:Accelerator-based molybdenum-100 photonuclear production incentives are creating alternative supply pathways independent of high-enriched uranium reactor dependencies.
Industry Challenges
- Radiochemist Talent Scarcity:Cyclotron operation and tracer synthesis require specialized nuclear pharmacy training programs that graduate fewer than two hundred specialists annually across North America and Europe.
- Legacy PACS Integration Friction:Hybrid imaging workstations must reconcile DICOM-RT and proprietary vendor formats with decade-old hospital information systems, delaying deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molecular Imaging Market |
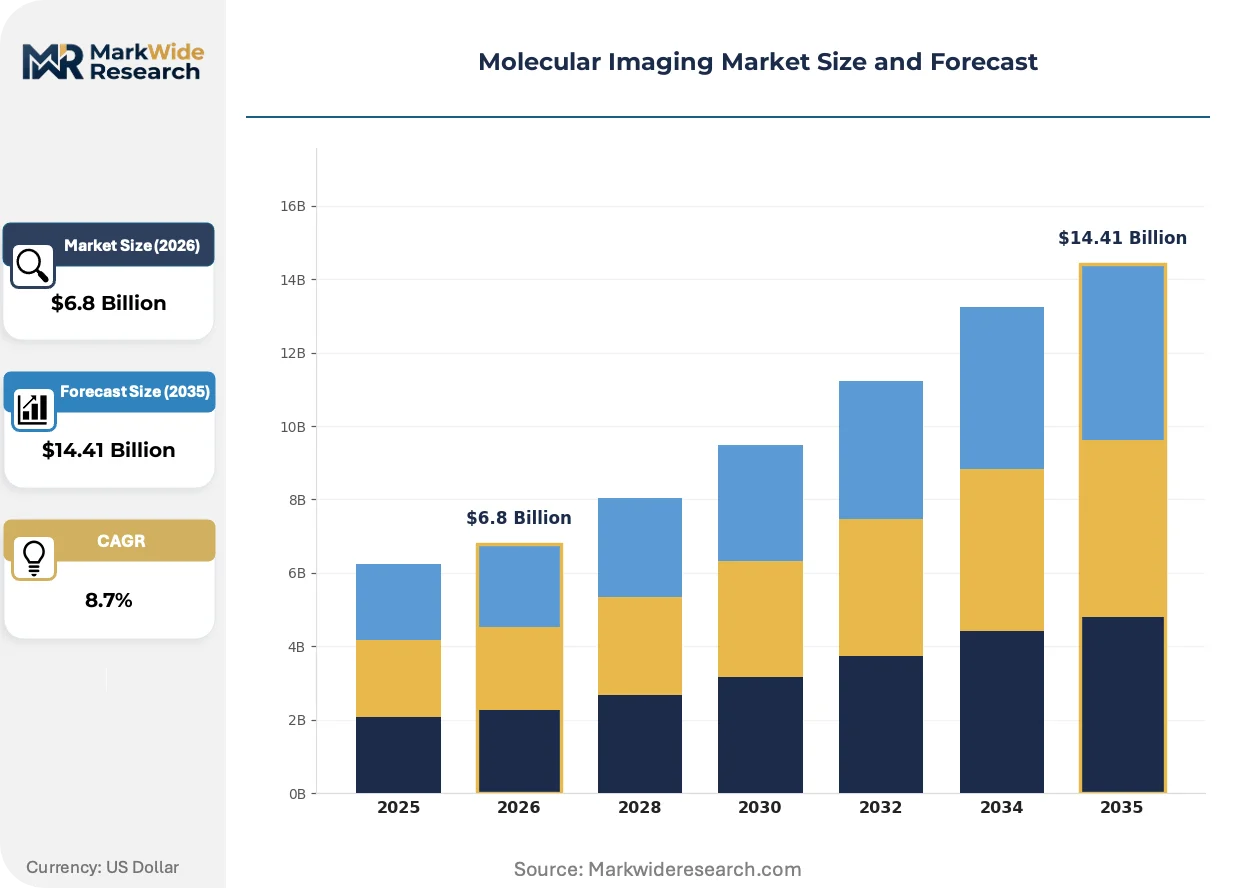
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.41 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Positron Emission Tomography, Magnetic Resonance Imaging, Single Photon Emission Computed Tomography, Optical Imaging Technology: Hybrid Imaging, Spectral Imaging, Fluorescence Imaging, Radiopharmaceuticals Application: Oncology, Cardiology, Neurology, Infectious Diseases End User: Hospitals, Diagnostic Centers, Research Institutions, Pharmaceutical Companies |
| Companies Covered | GE HealthCare, Siemens Healthineers, Koninklijke Philips N.V., Canon Medical Systems Corporation, Bruker, Shimadzu Corporation, United Imaging Healthcare, Mediso, Cubresa Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molecular Imaging Market Strategic Shifts
Artificial intelligence reconstruction is compressing scan acquisition windows while preserving diagnostic confidence, fundamentally altering throughput economics for high-capital imaging suites.
Total-body PET systems are electrifying clinical workflows by capturing pharmacokinetic data across all tissues simultaneously rather than sequencing bed positions. Major academic centers in Heidelberg, Houston, and Shanghai are prioritizing these installations for multi-organ disease characterization. This technology is electrifying the competitive positioning of manufacturers with integrated tracer-to-software ecosystems.
EMA's centralized marketing authorization for radiopharmaceuticals under the EU Clinical Trials Regulation is harmonizing multi-country study designs, reducing redundant national submissions. Pharmaceutical sponsors now conduct single pivotal trials with reference to EMA scientific advice rather than sequential national procedures. Oncology tracer developers targeting European market access are consolidating regulatory strategy around Amsterdam timelines.
Hospital procurement committees are unbundling equipment acquisition from radiopharmaceutical supply, favoring multi-vendor tracer sourcing over captive isotope arrangements. Independent cyclotron operators in the United States are displacing OEM-locked supply models with competitive tendering for F-18 FDG and novel agent distribution. This pattern is most visible in metropolitan hospital networks across Texas, Florida, and California where procedure volume justifies direct cyclotron investment.
Molecular Imaging Market Segmentation
Equipment replacement cycles in molecular imaging accelerate when hybrid modalities demonstrate throughput gains over standalone systems. Hospital procurement committees now evaluate total cost of ownership across tracer consumption, software licensing, and service contracts rather than capital expenditure alone.
Product Type:
Upgrade momentum concentrates where cyclotron infrastructure and radiopharmaceutical supply chains already exist, favoring modalities with recurring revenue models over one-time hardware sales.
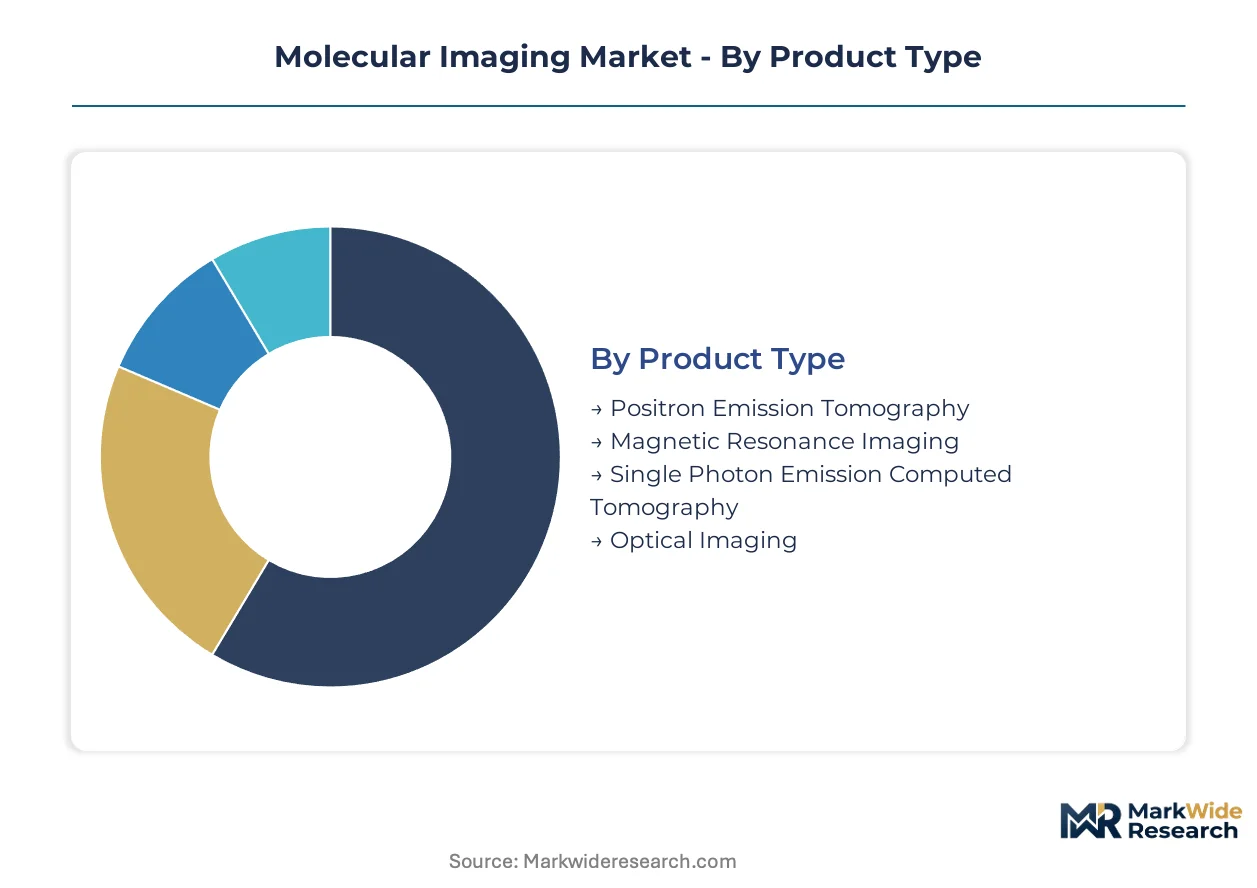
- Positron Emission Tomography:PET systems detect positron-emitting radiotracers with spatial resolution approaching 4 millimeters for metabolic activity mapping. Demand clusters in academic medical centers across the United States, Germany, and China where FDG oncology protocols justify cyclotron investments. High infrastructure barriers protect incumbent vendors with integrated isotope networks.
- Magnetic Resonance Imaging:MRI employs strong magnetic fields and radiofrequency pulses to generate high-resolution anatomical images without ionizing radiation. Pediatric neurology departments in Heidelberg and Houston prioritize PET-MRI hybrid installations where reduced radiation exposure outweighs longer scan durations. Siemens Healthineers anchors this segment through dual-source integration.
- Single Photon Emission Computed Tomography:SPECT utilizes gamma-emitting radioisotopes from technetium-99m generators for functional cardiac and bone imaging.
- Optical Imaging:Near-infrared and bioluminescent probes enable real-time visualization for preclinical research and intraoperative guidance.
Positron Emission Tomography sits at the top of the volume ranking, with Hybrid Imaging configurations climbing the fastest.
Technology:
Technology selection follows reimbursement density, with modalities commanding premium procedure codes attracting capital allocation ahead of research-stage alternatives.
- Hybrid Imaging:PET-CT and PET-MRI systems fuse functional and anatomical data into unified diagnostic workflows. German university hospitals deploy these suites for precision oncology staging where single-session comprehensive evaluation reduces patient logistics. GE HealthCare competes on integrated tracer-to-software ecosystems.
- Spectral Imaging:Energy-resolved detection separates multiple tracer signatures simultaneously for multi-parametric assessment.
- Fluorescence Imaging:Exogenous fluorophore excitation enables real-time tissue characterization during surgical resection.
- Radiopharmaceuticals:Cyclotron-produced and generator-derived tracers constitute the consumable foundation of molecular imaging economics.
Hybrid Imaging commands the largest installed base, while Radiopharmaceuticals gain share fastest through novel agent pipelines.
Application:
Application prioritization reflects disease burden demographics and reimbursement generosity, with oncology commanding disproportionate capital allocation due to therapeutic decision-making leverage.
- Oncology:Tumor detection, staging, and treatment response monitoring consume the majority of PET-CT procedure volume. Precision medicine programs at MD Anderson and Memorial Sloan Kettering drive theranostic protocol adoption where diagnostic scans directly guide radionuclide therapy selection.
- Cardiology:Myocardial perfusion imaging and viability assessment utilize SPECT and PET tracers for coronary artery disease evaluation.
- Neurology:Amyloid and tau PET imaging for Alzheimer's disease characterization expands where CMS coverage determinations permit.
- Infectious Diseases:White blood cell labeling and specific pathogen imaging address antibiotic stewardship and prosthetic joint infection.
Oncology dominates procedure volume, with Neurology expanding most quickly through dementia biomarker validation.
End User:
End-user economics diverge sharply between fee-for-service hospital systems and research institutions where grant funding replaces reimbursement dependence.
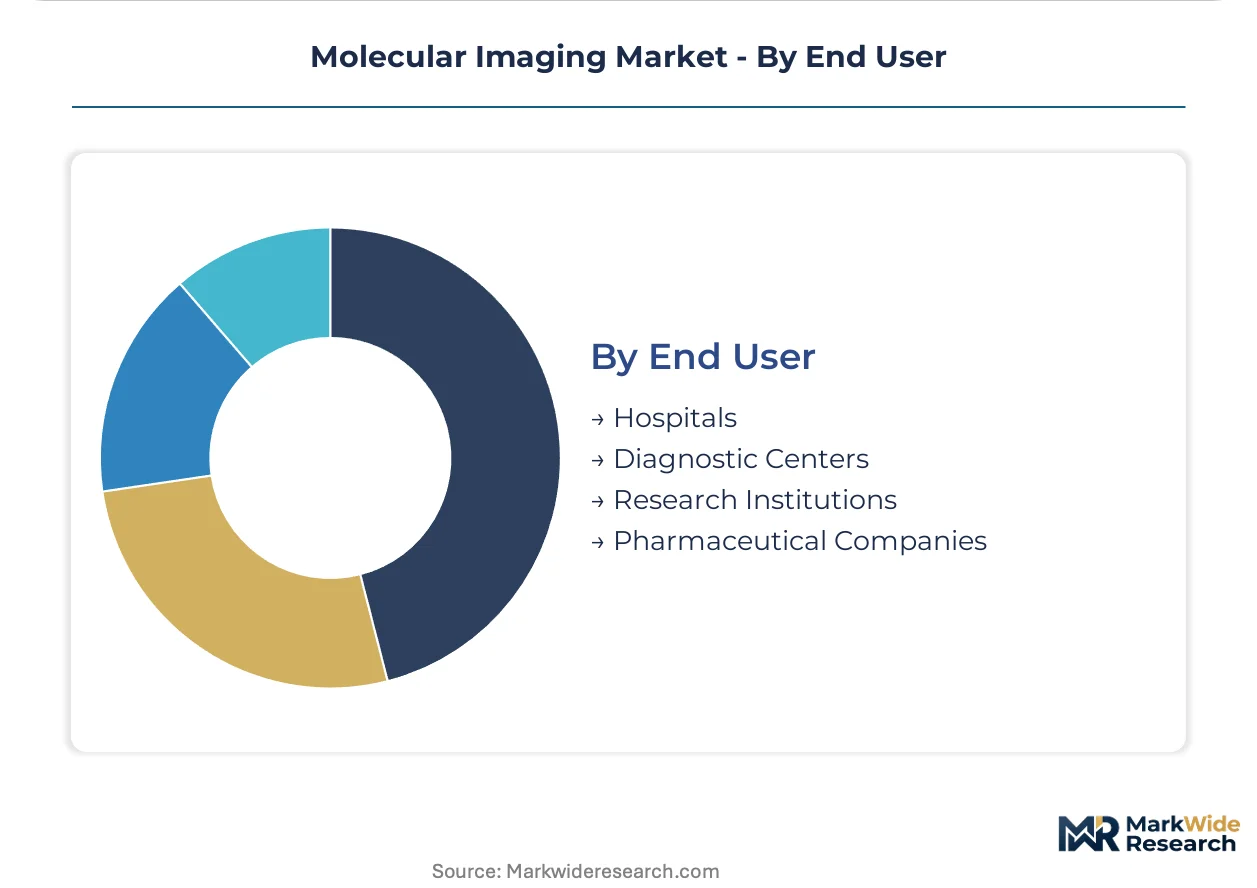
- Hospitals:Integrated delivery networks consolidate imaging procurement with therapeutic service lines under unified capital budgets. Texas Medical Center members deploy total-body PET systems for multi-organ pharmacokinetic studies that attract pharmaceutical sponsorship.
- Diagnostic Centers:Independent imaging facilities compete on throughput and appointment availability for routine oncology surveillance.
- Research Institutions:Preclinical optical imaging and tracer development programs operate outside clinical reimbursement frameworks.
- Pharmaceutical Companies:Sponsored imaging cores support clinical trial endpoints for novel therapeutic development.
Hospitals anchor the customer base, with Pharmaceutical Companies representing the steepest expansion trajectory through trial imaging mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Texas Medical Center in Houston anchors global molecular imaging deployment through its concentration of total-body PET installations and pharmaceutical-sponsored pharmacokinetic research programs.
United States
Academic medical centers in Houston, Boston, and New York Metro drive hybrid imaging procurement for precision oncology staging. FDA clearance pathways under 21 CFR Part 315 compress radiotracer development timelines for novel agents. The Texas Medical Center operates the densest concentration of cyclotron facilities, enabling same-day fluorine-18 synthesis for community hospital networks across the Gulf Coast.
Germany
University hospitals in Heidelberg and Munich prioritize PET-MRI suites for pediatric neurology applications where radiation exposure reduction outweighs throughput constraints. EMA centralized marketing authorization harmonizes multi-country trial designs under the EU Clinical Trials Regulation. The Bavarian cyclotron network supplies tracer agents to clinical sites across southern Germany with sub-four-hour logistics windows.
China
Shanghai and Guangdong province deploy hybrid imaging suites at scale for cancer center expansion under national healthcare infrastructure programs. NMPA enforces GB standards for medical imaging equipment performance and radiopharmaceutical quality. The Yangtze River Delta cluster concentrates domestic PET-CT manufacturing capacity alongside imported system installations.
India
Metropolitan hospital networks in Maharashtra and Karnataka address diagnostic infrastructure gaps where PET-CT installed base remains below one unit per million population. CDSCO regulates radiopharmaceutical import and manufacturing licensure for clinical tracer applications. Diagnostic chains in Mumbai and Bangalore pilot equipment-leasing models tied to radiotracer supply contracts for first-mover market entry.
Molecular Imaging Market Competitive Environment
Strategic partnerships dominate the current landscape as equipment manufacturers secure cyclotron network access and radiopharmaceutical distribution agreements. The vendor base concentrates around three integrated conglomerates with captive isotope supply chains, supplemented by specialized regional equipment fabricators and independent cyclotron operators. Two strategic archetypes prevail: full-stack providers controlling tracer-to-software ecosystems, and modular specialists competing on AI-enabled reconstruction and dose optimization. Competitive intensity centers on M&A activity targeting cyclotron assets and technology licensing arrangements for total-body PET detector arrays.
Among the integrated full-stack providers, GE HealthCare, Siemens Healthineers, and Koninklijke Philips N.V. represent the dominant competitive anchors. GE HealthCare occupies a position tied to cyclotron network control, while Siemens Healthineers exemplifies dual-source CT integration capabilities. Koninklijke Philips N.V. sits within the AI-enabled software tier, competing on reconstruction algorithms that reduce tracer dose requirements. These three conglomerates anchor the premium equipment segment while independent cyclotron operators in Texas, Florida, and California displace captive supply models through competitive tendering.
| Leading Market Players |
|---|
| GE HealthCare |
| Siemens Healthineers |
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Bruker |
| Shimadzu Corporation |
| United Imaging Healthcare |
| Mediso |
| Cubresa Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive cyclotron networks anchor supply positions for PET radiopharmaceuticals while simultaneously determining pricing power through isotope availability guarantees. Equipment manufacturers with in-house production of fluorine-18 tracers command premium positioning against modular competitors dependent on third-party distribution.
Pricing Analysis
Input-cost pass-through from molybdenum-99 reactor outages and cyclotron maintenance cycles directly shapes contract pricing for technetium-99m generators and positron-emitting tracers. Three-tier pricing structure across premium, standard, and economy levels separates academic medical centers with guaranteed supply agreements from community hospitals on spot procurement. Pricing pressure stems from independent cyclotron operators in Texas and Florida introducing competitive tendering for FDG distribution. Community hospital networks exhibit highest price sensitivity due to thin procedure margins, while pharmaceutical-sponsored research institutions absorb premium rates for novel agent access.
Supply Chain Analysis
Single-source vulnerability sits with the Netherlands, Belgium, and South Africa, where four aging reactors supply the majority of global molybdenum-99 for technetium-99m generators. Raw material dependencies center on high-enriched uranium feedstock, specialized target plates, and generator column resins. Supply chain risk concentrates in unplanned reactor outages that cascade into procedure backlogs across cardiac and bone imaging workflows. Distribution runs through radiopharmaceutical manufacturing facilities with cGMP cleanroom certification, limiting contract manufacturing alternatives for positron-emitting tracers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in molecular imaging rests on AI-enabled reconstruction software reducing tracer dose requirements while preserving diagnostic confidence, shifting value capture toward premium software tiers.
For Market Incumbents: Deploy cyclotron network densification as the primary defensive lever. Expand regional isotope production hubs in Texas, Bavaria, and Guangdong to shorten fluorine-18 half-life logistics and lock out independent operators. Secure FDA clearance pathways for novel radiotracers under 21 CFR Part 315 ahead of emerging entrants with limited regulatory affairs capacity. Fortify software licensing revenue through AI reconstruction algorithms that reduce dose requirements for pediatric applications. For New Entrants and Emerging Players: Enter via equipment-leasing models tied to radiotracer supply contracts in India, where PET-CT installed base remains below one unit per million population. Target metropolitan hospital networks in Maharashtra and Karnataka with first-mover positioning before integrated conglomerates establish cyclotron infrastructure. Pursue CDSCO manufacturing licensure for clinical tracer applications as the regulatory gateway. White-space concentration in diagnostic infrastructure gaps offers procurement committee access without direct equipment sales competition. For Investors and Strategic Acquirers: Consolidation pressure builds where radiochemist talent scarcity constrains cyclotron operation and tracer synthesis capacity. Long-term viability favors full-stack providers controlling tracer-to-software ecosystems over modular equipment fabricators exposed to commoditization. Acquisition target archetype: independent cyclotron operators with established distribution networks in Texas, Florida, or California displacing OEM-locked supply models. Signal to watch: EMA centralized marketing authorization timelines under EU Clinical Trials Regulation compressing multi-country study designs and accelerating novel agent commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Network Expansion | Regional isotope production in Texas and Bavaria shortens fluorine-18 logistics windows for same-day synthesis. |
| AI Reconstruction Software Development | Deep learning algorithms from Koninklijke Philips N.V. reduce tracer dose while preserving PET image quality. |
| FDA 21 CFR Part 315 Submission | Novel radiotracer clearance pathways compress development timelines for precision oncology agents. |
| Total-Body PET System Installation | Heidelberg and Houston academic centers capture multi-organ pharmacokinetic data for pharmaceutical sponsorship. |
| Independent Cyclotron Acquisition | Equipment manufacturers secure isotope supply chains against third-party distribution disruption. |
Study Parameters
Coverage spans the United States, Germany, China, and India, with primary inputs from each market's hospital procurement committees, cyclotron operators, and regulatory affairs specialists. Interviews with biomedical engineers, GPO contracts managers, and nuclear pharmacy directors combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and hospital procurement databases. Bottom-up equipment installation tracking and top-down radiopharmaceutical consumption estimates were triangulated to anchor market sizing.
Rate-of-change decomposition across the projection horizon modeled technology adoption curves for hybrid imaging configurations, radiotracer pipeline maturation, and reimbursement density evolution. Segmentation dimensions included modality type, application area, end-user category, and regional regulatory cluster. CAGRs were derived from procedure volume elasticity to reimbursement expansion, equipment replacement cycle compression, and cyclotron network densification patterns.
Inputs from FDA, EMA, and NMPA regulatory filings were available through the study window; gaps in real-time hospital procurement transaction data introduce uncertainty bands around equipment installation forecasts. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Radiology Services Market
Medical Imaging
Canada Mammography Market
Medical Imaging
Hand-Held X-Rays Market
Medical Imaging
Global Micro-Ultrasound Systems Market
Medical Imaging
Small Animal Imaging (in-Vivo) Market
Medical Imaging
Optical Coherence Tomography Market
Medical Imaging
Preclinical MRI Equipment Market
Medical Imaging
Mexico Mammography Market
Medical Imaging
Digital Pathology Scanner Calibration and Image Quality Test Systems Market
Medical Imaging
AI-Based Medical Imaging Algorithm Validation Test Platforms Market
Medical Imaging
South Africa Computed Tomography Market
Medical Imaging
Intraoperative Imaging Market
Medical Imaging
Global Super Resolution Microscopes Market
Medical Imaging
US Magnetic Resonance Angiography Market
Medical Imaging
United Kingdom Computed Tomography Market
Medical Imaging
United Kingdom Digital X-Ray Devices Market