
 Echocardiography Market | 2026-2036
Echocardiography Market Size, Share, and Industry Trends Forecast 2026-2036
Echocardiography Market Intelligence
Hospital procurement consolidation is realigning how echocardiography vendors engage large health systems. General Electric Company leverages its installed base of cardiovascular imaging suites to sustain long-term service agreements with integrated delivery networks. Siemens Healthcare GmbH competes through its digital echo workflow platforms that anchor enterprise-wide cardiology informatics.
Echocardiography employs high-frequency ultrasound transducers, typically operating between 2.5 and 7.5 megahertz, to generate real-time images of cardiac structure and blood flow for diagnostic assessment. The technology serves primary clinical purposes in detecting valvular dysfunction, wall motion abnormalities, and congenital defects without invasive catheterization. Doppler echocardiography leads the product type landscape due to its established reimbursement pathways and essential role in hemodynamic evaluation, while 3D echocardiography represents the fastest-expanding segment as interventional cardiology teams adopt volumetric imaging for structural heart procedures. Mobile echocardiography technology captures growing margin pools by enabling point-of-care deployment in emergency departments and intensive care units where fixed systems remain impractical.
The FDA enforces medical device cybersecurity requirements under its premarket guidance, compelling manufacturers to embed threat mitigation into echocardiography system architecture. The European Medicines Agency coordinates with notified bodies under the Medical Device Regulation to enforce clinical evidence standards for contrast echocardiography agents and software-enabled diagnostic tools. Japan's Ministry of Economy, Trade and Industry oversees adoption of JIS-compliant imaging equipment, shaping market access for vendors targeting Japanese cardiology departments. Stakeholders must monitor how artificial intelligence classification rules evolve across jurisdictions, as algorithm-based automated ejection fraction analysis triggers divergent regulatory pathways that will determine competitive positioning.
Market Dynamics
Hospital procurement consolidation is compressing vendor margins while favoring suppliers capable of delivering integrated cardiovascular imaging ecosystems across entire health systems.
Growth Catalysts
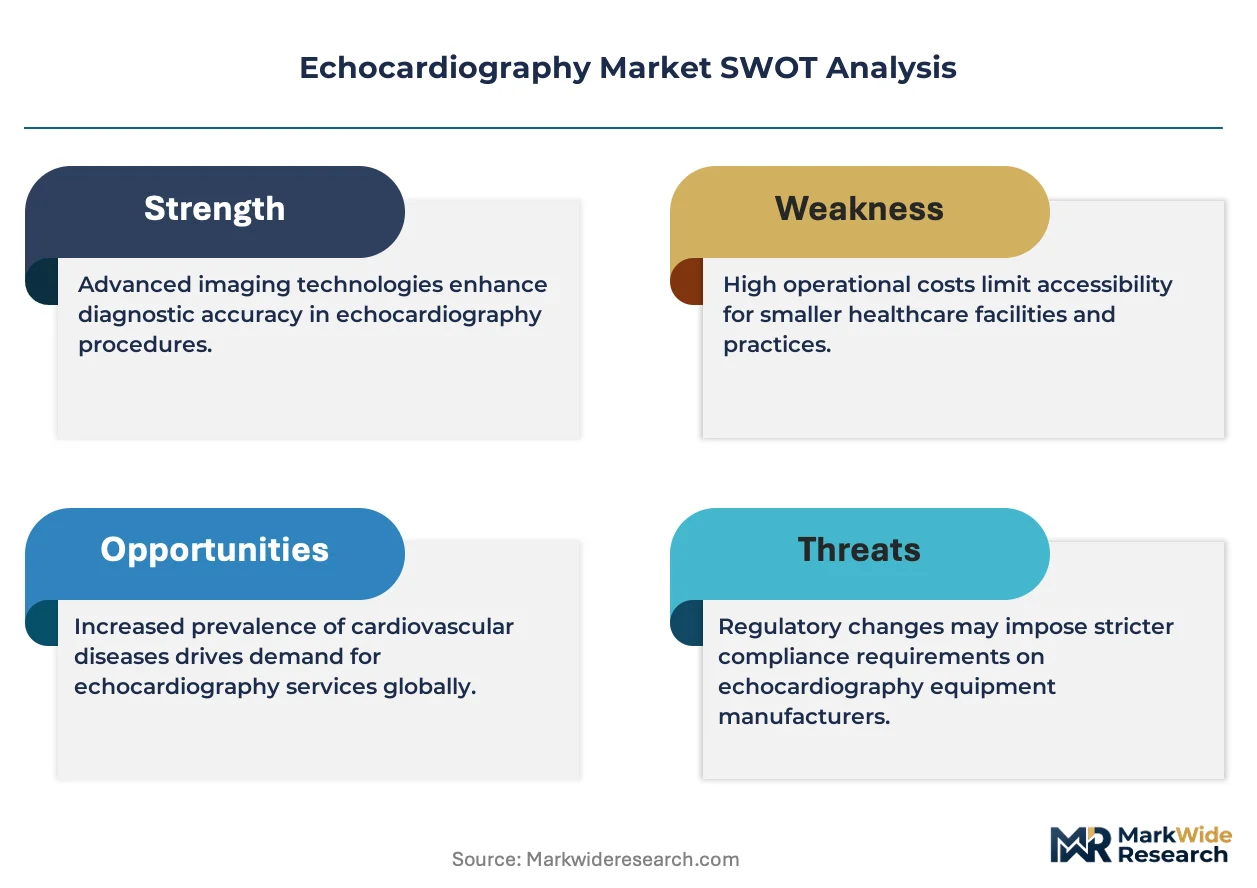
- FDA Cybersecurity Mandates:The FDA's updated premarket guidance for medical device cybersecurity compels manufacturers to embed threat mitigation protocols, accelerating replacement cycles for legacy echocardiography systems lacking hardened architecture.
- Interventional Cardiology Expansion:Structural heart procedures including transcatheter aortic valve replacement create demand for real-time 3D echocardiography guidance in hybrid operating suites.
- German Hospital Network Standardization:University hospital networks across Germany are consolidating echocardiography platforms to reduce training overhead and streamline maintenance contracts.
Market Restraints
- Transducer Supply Concentration:Piezoelectric crystal supply chains concentrate among Asian material processors, exposing manufacturers to input volatility and geopolitical disruption risk.
- CE Mark Clinical Evidence Burden:The EU Medical Device Regulation imposes expanded clinical evidence requirements for contrast echocardiography agents, extending time-to-market and compliance costs.
- Point-of-Care Ultrasound Substitution:Handheld cardiac ultrasound devices from Butterfly Network and Philips Lumify capture low-acuity cases previously referred to departmental echocardiography.
Strategic Opportunities
- Artificial Intelligence Classification Clarity:Divergent regulatory pathways for algorithm-based automated ejection fraction analysis across FDA, EMA, and PMDA jurisdictions create first-mover advantage for vendors achieving multi-market clearance.
- Mobile Echocardiography Deployment:Emergency departments and intensive care units represent underpenetrated point-of-care settings where cart-based systems remain impractical and wheeled compact systems command premium placement.
- JIS-Compliant Platform Entry:Japan's Ministry of Economy, Trade and Industry standards for imaging equipment create a defined regulatory pathway for vendors targeting Japanese cardiology departments with localized workflow interfaces.
Industry Challenges
- Sonographer Workforce Constraints:Specialized cardiac sonographer certification programs face enrollment bottlenecks, limiting health system capacity to deploy additional echocardiography units despite capital availability.
- Legacy PACS Integration Complexity:Enterprise cardiology informatics platforms must interface with heterogeneous picture archiving systems, requiring costly customization for each integrated delivery network.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Echocardiography Market |
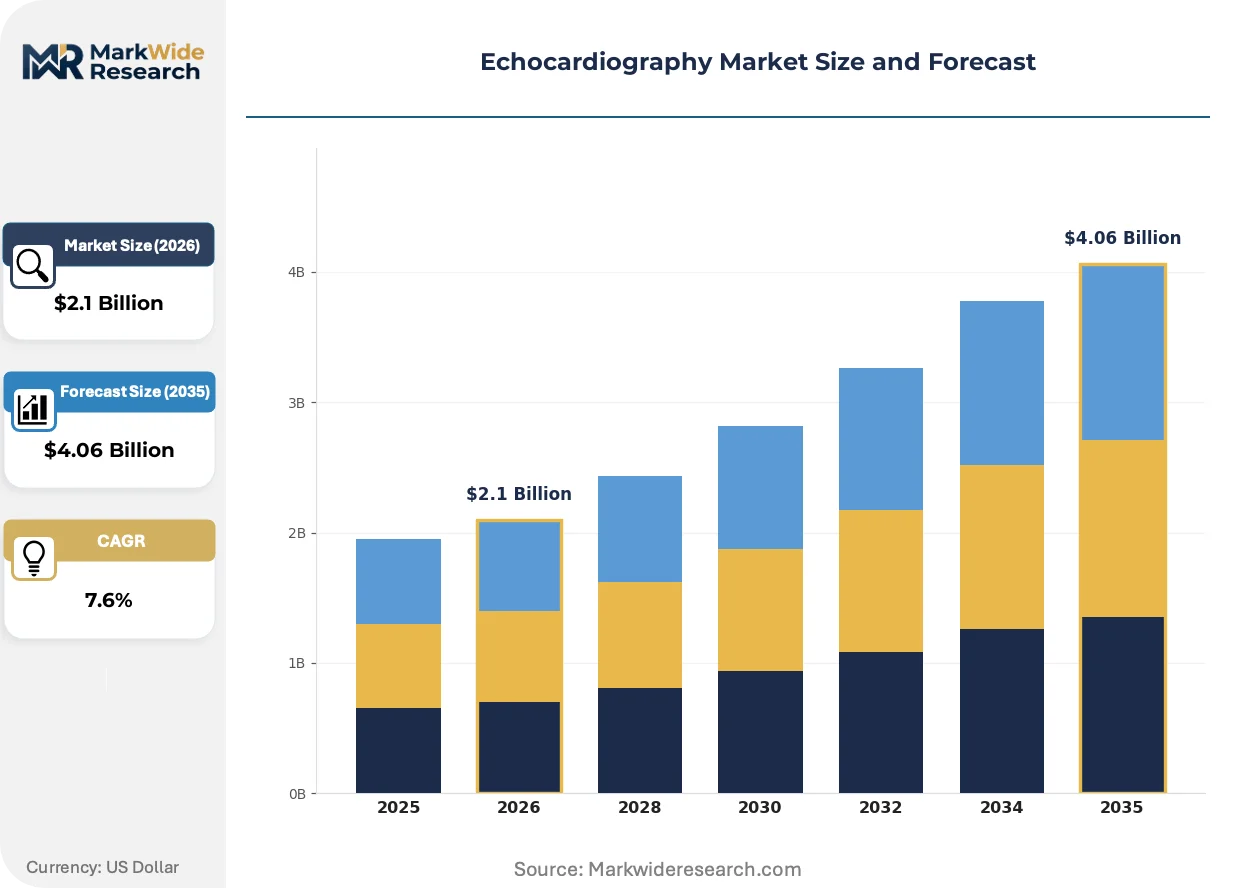
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $4.06 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: 2D Echocardiography, 3D Echocardiography, Doppler Echocardiography, Transesophageal Echocardiography Technology: Ultrasound, Contrast Echocardiography, Mobile Echocardiography, Computerized Echocardiography End User: Hospitals, Diagnostic Centers, Cardiology Clinics, Research Institutions Application: Cardiac Diagnosis, Congenital Heart Disease, Heart Valve Assessment, Stress Echocardiography |
| Companies Covered | Koninklijke Philips N.V., Canon Medical Systems Corporation, Samsung Electronics Co. Ltd., Hitachi Medical Corporation, Esaote SpA, General Electric Company, Shenzhen Mindray Bio-Medical Electronics Co. Ltd., FUJIFILM Sonosite, Siemens Healthcare GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Echocardiography Market Strategic Shifts & Innovations
Artificial intelligence is embedding into echocardiography workflows, compressing analysis time while regulatory frameworks scramble to classify algorithm-enabled diagnostic tools.
Cloud-native echocardiography workstations are consolidating image storage and computational analysis away from on-premise servers. Hospital IT departments favor subscription-based deployment models that shift capital expenditure to operational budgets. This architecture is consolidating vendor relationships toward platform providers capable of delivering seamless hybrid cloud connectivity.
The EU Medical Device Regulation is enforcing clinical evidence standards for software-enabled diagnostic tools that exceed previous directive requirements. Manufacturers must now submit prospective validation studies for AI-augmented measurement algorithms. Cardiology informatics vendors with established quality management systems are responding by accelerating MDR technical documentation preparation.
Integrated delivery networks are unbundling after-sales service contracts from equipment procurement, pitting third-party clinical engineering firms against original manufacturers. Large health systems in the United States negotiate multi-vendor service agreements covering ultrasound, CT, and MRI modalities under single-source contracts. This behavior is most visible among Catholic health systems and regional Blue Cross-affiliated networks consolidating vendor management overhead.
Echocardiography Market Segmentation
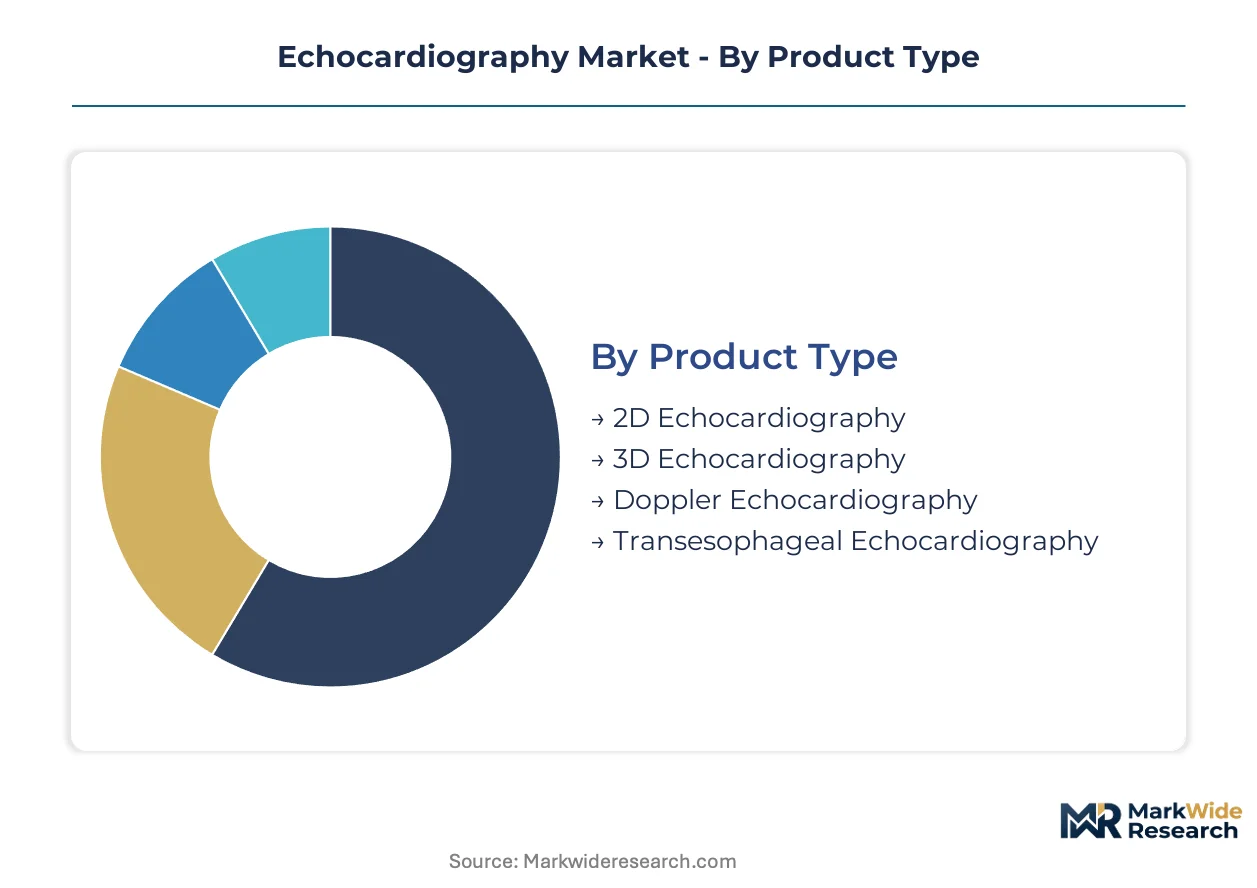
Product, technology, and end-user segmentation in echocardiography reveals how procurement consolidation and clinical workflow specialization are reshaping vendor priorities. Each dimension exposes distinct margin structures and competitive moats that determine supplier positioning across integrated delivery networks.
Product Type:
Piezoelectric crystal supply chains concentrate among Asian material processors, concentrating manufacturing leverage for transducer-dependent modalities.
- 2D Echocardiography:Conventional two-dimensional imaging remains the workhorse modality for routine cardiac assessment, utilizing phased-array transducers between 2.5 and 5.0 megahertz. Demand concentrates in community hospital emergency departments across the United States where rapid triage protocols depend on established reimbursement codes.
- 3D Echocardiography:Volumetric reconstruction from matrix-array transducers enables real-time visualization of cardiac structures without geometric assumptions. German university hospital networks are standardizing these platforms across cardiac centers to support structural heart intervention programs.
- Doppler Echocardiography:Spectral and color flow mapping for hemodynamic quantification anchors departmental echocardiography suites.
- Transesophageal Echocardiography:Intracardiac imaging via esophageal probe placement serves intraoperative guidance and thrombus detection.
Doppler echocardiography absorbs the bulk of installed capacity; 3D echocardiography is expanding most quickly.
Technology:
Cost tier differentiation separates capital-intensive fixed installations from portable systems that shift expenditure to operational budgets.
- Ultrasound:Fundamental acoustic imaging technology underpins all echocardiography modalities through piezoelectric transducer arrays. Demand concentrates in Japanese cardiology departments where METI-compliant equipment procurement favors established harmonic imaging platforms.
- Contrast Echocardiography:Microbubble-enhanced perfusion imaging improves endocardial border delineation in technically difficult patients. The EMA's MDR clinical evidence requirements for contrast agents are extending time-to-market for new formulations.
- Mobile Echocardiography:Compact cart-based and handheld systems enable point-of-care deployment.
- Computerized Echocardiography:Software-enabled measurement and reporting tools integrate with PACS infrastructure.
Ultrasound platforms command the largest installed base; mobile echocardiography is gaining share fastest among new deployments.
End User:
Customer type determines purchasing authority structure, with integrated delivery networks consolidating procurement across previously independent facilities.
- Hospitals:Acute care institutions with catheterization laboratories and hybrid operating suites represent the highest-value installation sites. Catholic health systems and regional Blue Cross-affiliated networks in the United States are negotiating multi-vendor cardiovascular imaging contracts.
- Diagnostic Centers:Outpatient imaging facilities compete on throughput and report turnaround time. Indian diagnostic chains are expanding cardiac ultrasound capacity to capture referral volume from tier-2 cities.
- Cardiology Clinics:Physician office-based practices favor compact systems with streamlined workflows.
- Research Institutions:Academic medical centers drive protocol development for novel imaging applications.
Hospitals absorb the bulk of installed capacity; diagnostic centers are expanding most quickly.
Application:
Volume concentration in routine diagnosis contrasts with premium pricing for specialized procedural guidance.
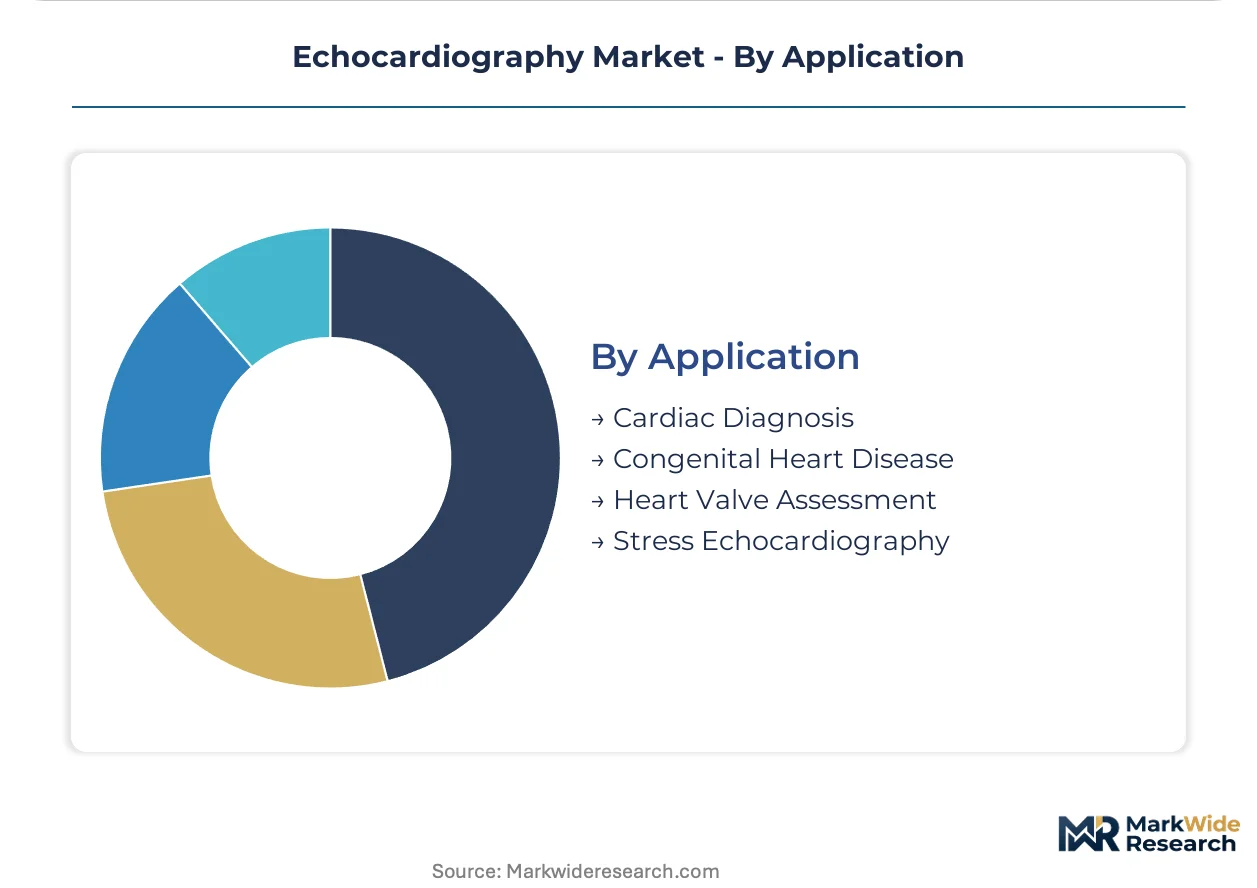
- Cardiac Diagnosis:General evaluation of cardiac structure and function constitutes the foundational use case for echocardiography. Demand concentrates in United States emergency departments where CMS reimbursement pathways support point-of-care deployment.
- Congenital Heart Disease:Pediatric and adult congenital imaging requires specialized probe selection and interpreter expertise. German pediatric cardiology centers are consolidating referral networks to concentrate complex case volume.
- Heart Valve Assessment:Quantitative evaluation of stenosis and regurgitation severity guides surgical and interventional decisions.
- Stress Echocardiography:Exercise or pharmacologic stress testing with imaging detects ischemia in patients with intermediate-risk presentations.
Cardiac diagnosis absorbs the bulk of installed capacity; congenital heart disease applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Piezoelectric crystal processing concentrates among Asian material suppliers, yet echocardiography system demand distributes across cardiac centers in Germany, the United States, Japan, and India where procurement consolidation reshapes vendor relationships.
United States
Catholic health systems and Blue Cross-affiliated regional networks negotiate multi-vendor cardiovascular imaging contracts covering ultrasound, CT, and MRI modalities. The FDA enforces updated premarket cybersecurity guidance that accelerates replacement cycles for legacy echocardiography systems lacking hardened architecture. Major cardiac centers in Cleveland and Boston standardize platforms across integrated delivery networks to reduce training overhead.
Germany
University hospital networks consolidate echocardiography platforms across cardiac centers to streamline maintenance contracts and reduce training complexity. The EU Medical Device Regulation imposes expanded clinical evidence requirements for contrast echocardiography agents through coordination with notified bodies. Berlin and Munich anchor structural heart intervention programs driving 3D echocardiography standardization.
Japan
The Ministry of Economy, Trade and Industry oversees adoption of JIS-compliant imaging equipment, shaping market access for vendors targeting cardiology departments. PMDA coordinates with METI on software-enabled diagnostic tool classifications as artificial intelligence embedding accelerates. Tokyo and Osaka metropolitan areas concentrate academic medical centers that drive protocol development for novel imaging applications.
India
Diagnostic chains expand cardiac ultrasound capacity to capture referral volume from tier-2 cities where outpatient imaging facilities compete on throughput. The Central Drugs Standard Control Organization regulates medical device import and manufacturing under evolving quality management frameworks. Bangalore and Hyderabad host emerging clinical engineering service providers that challenge original manufacturers on after-sales contracts.
China
Domestic manufacturers leverage cost positioning to capture share in provincial hospital procurement tenders for conventional 2D systems. The National Medical Products Administration enforces cybersecurity and clinical evidence standards for software-enabled diagnostic tools that exceed previous requirements. Shanghai and Beijing academic medical centers pilot AI-augmented measurement algorithms requiring prospective validation studies.
Echocardiography Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue point-of-care and AI-augmented niches. The vendor base stratifies across integrated cardiovascular imaging ecosystems, standalone echocardiography platforms, and handheld diagnostic devices. Three archetypes dominate: diversified medical technology conglomerates with installed base leverage, specialized ultrasound manufacturers with transducer supply control, and software-centric entrants with cloud-native workflow platforms. Competitive dynamics center on multi-vendor service contract consolidation and MDR technical documentation acceleration.
Among diversified imaging conglomerates, General Electric Company and Siemens Healthcare GmbH exemplify platform providers with enterprise cardiology informatics integration. Koninklijke Philips N.V. occupies a position within the premium-tier vector through digital echo workflow platforms. Shenzhen Mindray Bio-Medical Electronics Co. Ltd. represents cost-optimized system manufacturers expanding through provincial hospital tenders. These anchors illustrate how geographic origin and corporate structure shape competitive archetype positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Canon Medical Systems Corporation |
| Samsung Electronics Co. Ltd. |
| Hitachi Medical Corporation |
| Esaote SpA |
| General Electric Company |
| Shenzhen Mindray Bio-Medical Electronics Co. Ltd. |
| FUJIFILM Sonosite |
| Siemens Healthcare GmbH |
| Others |
Cost & Logistics Intelligence
Piezoelectric crystal processing costs in Japan and South Korea flow through transducer manufacturing tiers, compressing margins on economy-grade 2D systems while premium 3D platforms absorb upstream volatility through service bundling.
Pricing Analysis
Extended warranty and preventive maintenance unbundling from equipment procurement is reshaping how integrated delivery networks negotiate cardiovascular imaging contracts. Three-tier pricing structure across premium, standard, and economy levels separates AI-augmented 3D platforms from conventional Doppler systems and refurbished 2D carts. Price differentiation hinges on FDA cybersecurity certification tier and sonographer training package inclusion. Cost compression in standard-tier deployments is intensifying because third-party clinical engineering firms underbid original manufacturers on multi-vendor service agreements. Diagnostic centers in India exhibit highest price sensitivity due to throughput-dependent margin structures; German university hospital networks show lowest sensitivity given standardization mandates.
Supply Chain Analysis
Regional distribution centers in the Netherlands and Singapore coordinate hub-and-spoke patterns for transducer replenishment and field service parts. Manufacturing concentrates in China, Japan, and Germany for system assembly, with piezoelectric crystal sourcing drawn from South Korean and Japanese material processors. Critical inputs include lead zirconate titanate crystals, specialized acoustic lenses, and FPGA chipsets for beamforming. Single-source vulnerability in Asian material processing exposes manufacturers to geopolitical disruption risk. Distribution runs through manufacturer-direct sales for large hospital networks and specialized medical distributors for mid-tier clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native echocardiography workstations are displacing on-premise PACS infrastructure, forcing stakeholders to recalibrate platform investments around subscription economics and hybrid deployment architectures.
For Market Incumbents: Hedge installed base erosion by embedding AI-augmented measurement algorithms into existing cardiovascular imaging suites before handheld ultrasound devices from Butterfly Network and Philips Lumify capture additional low-acuity cases. Deepen backward integration into piezoelectric crystal supply through captive sourcing agreements with South Korean material processors. Accelerate MDR technical documentation preparation to defend CE marking positions against notified body backlog. For New Entrants and Emerging Players: The price-point gap between premium AI-enabled 3D platforms and economy 2D carts creates white-space opportunity for mid-tier compact systems with localized workflow interfaces. Target Japanese cardiology departments seeking JIS-compliant equipment with METI-standardized deployment protocols. Penetrate emergency department point-of-care settings where wheeled compact systems command premium placement against fixed installations. For Investors and Strategic Acquirers: FDA clearance for algorithm-based automated ejection fraction analysis is the leading indicator that AI classification pathways are stabilizing across jurisdictions. Position acquisition screens toward cloud-native workflow platform specialists with hospital IT department relationships and established quality management systems. Monitor PMDA software-enabled diagnostic tool coordination with METI as inflection signal for Japanese market entry viability.| Strategic Initiative | Industry Significance |
|---|---|
| AI Algorithm FDA Submission | Automated ejection fraction analysis triggers divergent regulatory pathways determining competitive positioning. |
| Hospital System Partnership | Integrated delivery network consolidation favors vendors with enterprise cardiology informatics integration. |
| CE Marking Pathway Acceleration | MDR clinical evidence requirements for contrast agents extend time-to-market for new formulations. |
| Software Companion Development | Cloud-native workstations shift capital expenditure to operational budgets favored by hospital IT departments. |
| Reimbursement Strategy | CMS pathways for point-of-care deployment in emergency departments shape procurement priorities. |
Research Approach
FDA 510(k) filings, EMA MDR submission databases, and hospital procurement contract records formed the secondary backbone, supplemented by customs data on piezoelectric crystal trade flows and GPO contract repositories. Primary interviews with cardiac sonographers, hospital purchasing committee chairs, biomedical engineering directors, and GPO contracts managers validated demand assumptions and pricing dynamics. Bottom-up unit economics for transducer manufacturing and top-down health system capital expenditure patterns were triangulated to anchor market sizing.
Historical trendline analysis of installed base replacement cycles and capital equipment procurement patterns informed projection modeling across the analysis window. Segmentation dimensions included product type, technology tier, end-user facility scale, and regional regulatory cluster. CAGRs were derived from weighted average of equipment shipment trajectories and service contract value expansion. Forecast inputs incorporated sonographer workforce enrollment constraints and cybersecurity mandate compliance timelines.
Inputs from regulatory filing databases and hospital procurement platforms were available through the study window; gaps in real-time contract pricing transparency introduce uncertainty bands around vendor margin estimates. Forecasts reflect documented assumptions regarding procurement consolidation velocity and AI classification rule finalization. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Argentina Mammography Market
Medical Imaging
South Korea Diagnostic Imaging Equipment Market
Medical Imaging
Small Animal Imaging (in-Vivo) Market
Medical Imaging
Ultrasound Systems Market
Medical Imaging
South Africa Magnetic Resonance Imaging Market
Medical Imaging
Digital Mobile X-Ray Products Market
Medical Imaging
Veterinary Imaging Systems Market
Medical Imaging
Global Medical Imaging Workstation Market
Medical Imaging
Weightbearing Low Dose (CT) Systems Market
Medical Imaging
Industrial X-Ray Machine Market
Medical Imaging
Global Confocal Microscope Market
Medical Imaging
Italy Digital X-Ray Market
Medical Imaging
Specimen Radiography Systems Market
Medical Imaging
Medical X-Ray Market
Medical Imaging
Japan Digital Radiology Market
Medical Imaging
Brazil Magnetic Resonance Imaging (MRI) Market