
 Portable MRI Market | 2026-2036
Portable MRI Market Size, Share, and Industry Trends Forecast 2026-2036
Portable MRI Market Analytics
A shortage of board-certified radiologists is reorganizing how imaging services reach patients, pushing providers toward decentralized scanning models. Siemens Healthineers leverages its established service infrastructure to sustain installed-base loyalty across European and North American hospital networks. Hyperfine competes through aggressive pricing of its FDA-cleared Swoop system, while GE Healthcare anchors its position via deep integration with hospital enterprise software ecosystems.
Portable MRI denotes a magnet-based diagnostic system engineered for transportability, typically operating at field strengths below 0.5 tesla using permanent magnets or resistive coils rather than superconducting cryostats, and designed to generate tomographic images at bedside or in non-traditional clinical settings. The technology serves acute stroke triage, intensive care monitoring, and perioperative assessment where fixed-scanner access proves impractical. Open MRI architectures currently dominate unit shipments due to patient tolerance and claustrophobia mitigation, though low-field MRI represents the fastest-expanding technology segment as manufacturers resolve signal-to-noise limitations through advanced software reconstruction. Deployment through mobile units captures the steepest growth trajectory, reflecting health system capital constraints and preference for operational expenditure models over fixed-asset commitments.
The FDA's 510(k) and breakthrough device pathways govern US market entry, while the EU Medical Device Regulation imposes stricter clinical evidence requirements for Class IIa and above systems, lengthening European certification cycles. China's NMPA has accelerated review timelines for domestically manufactured low-field systems under innovation channel designations, reshaping competitive dynamics for foreign OEMs. Stakeholders must monitor evolving reimbursement parity between portable and conventional MRI scans, as payment policy rather than technical capability now determines adoption velocity.
Market Dynamics
Medicare reimbursement reforms in the United States are accelerating procurement of point-of-care diagnostic systems, compressing capital cycles for rural hospitals and ambulatory surgical centers seeking neuroimaging access beyond tertiary centers.
Growth Catalysts
- Breakthrough Device Designation:The FDA's expedited pathway for low-field MRI systems has compressed clearance timelines, enabling faster commercialization of portable units.
- Permanent Magnet Innovation:Advances in permanent magnet engineering are eliminating superconducting cryostat dependencies, reducing system weight and infrastructure requirements for bedside deployment.
- Rural Hospital Demand:United States rural facilities facing radiologist shortages are procuring mobile units to extend stroke triage capabilities without fixed-asset construction.
Market Restraints
- Signal-to-Noise Constraints:Low-field systems operating below 0.5 tesla face inherent physics limitations that compromise image resolution for certain neurological applications.
- Helium Supply Concentration:Residual dependence on helium-3 and helium-4 for some magnet cooling systems exposes manufacturers to Qatar and United States supply volatility.
- EU MDR Certification Friction:The European Medical Device Regulation imposes stricter clinical evidence requirements for Class IIa systems, lengthening European approval cycles versus FDA pathways.
Strategic Opportunities
- Intensive Care Expansion:Neurocritical care units represent an underpenetrated application where bedside monitoring could displace repeated patient transport to fixed scanners.
- China Innovation Channel:NMPA accelerated review timelines for domestically manufactured low-field systems are reshaping competitive dynamics for foreign OEMs seeking market entry.
- Subscription Service Models:Operational expenditure structures replacing capital purchases align with health system budget constraints and mobile unit deployment preferences.
Industry Challenges
- Radiologist Workforce Gap:Board-certified neuroradiologist shortages limit interpretation capacity for decentralized scanning models, requiring teleradiology infrastructure investment.
- Legacy PACS Integration:Hospital enterprise software compatibility demands create implementation friction for point-of-care systems seeking seamless workflow incorporation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portable MRI Market |
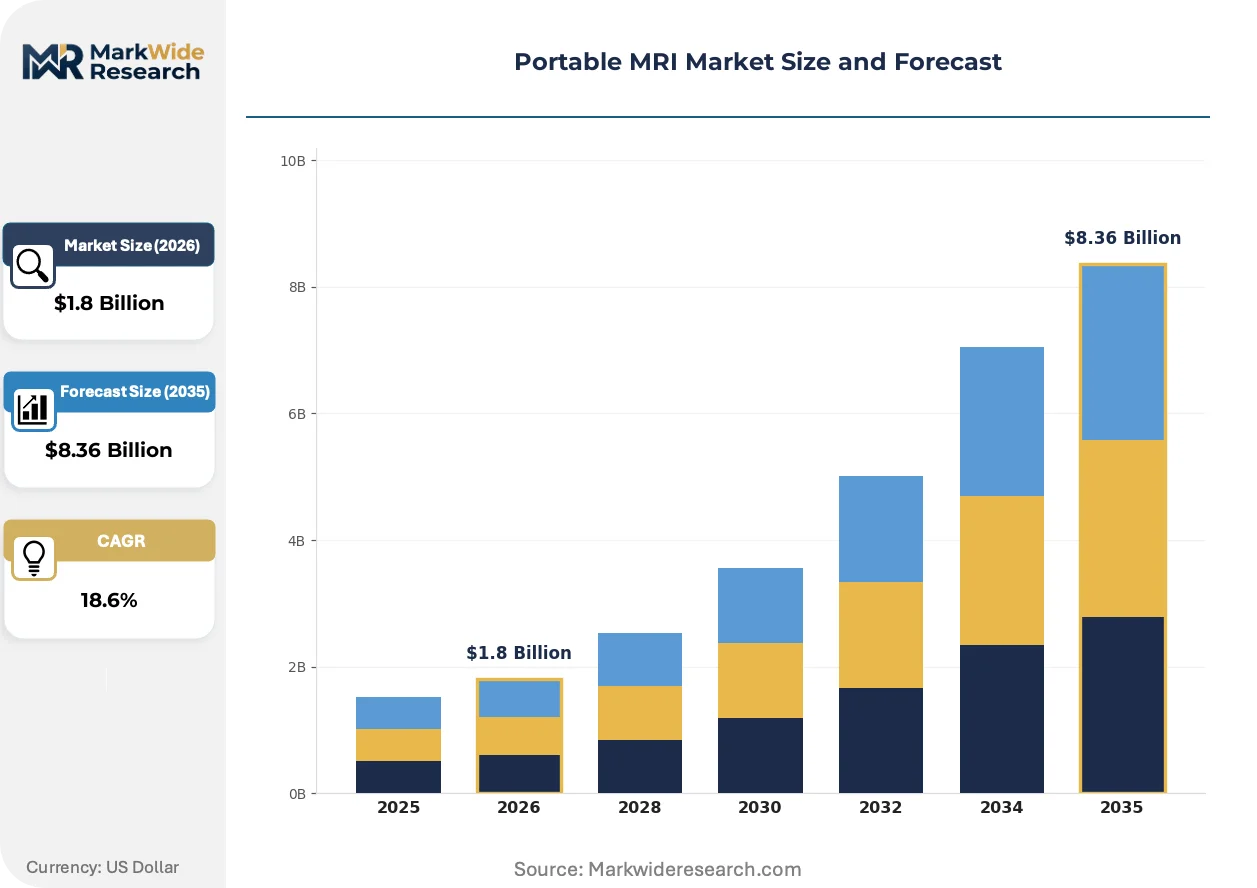
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $8.36 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open MRI, Closed MRI, Extremity MRI, Functional MRI End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Technology: Superconducting, Permanent Magnet, Hybrid MRI, Low Field MRI Deployment Model: Cloud-based, On-premises, Hybrid, Mobile Units |
| Companies Covered | Philips Healthcare, United Imaging, Hyperfine, Synaptive Medical, Promaxo, Siemens Healthineers, Canon Medical Systems, Voxelgrids Innovations, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portable MRI Market Evolving Landscape
Software reconstruction algorithms are resolving fundamental hardware limitations, enabling competitive image quality from lightweight magnet architectures previously dismissed as clinically insufficient.
Deep learning-based image reconstruction is fragmenting the traditional correlation between field strength and diagnostic utility. Academic medical centers in the United States are piloting these systems for acute stroke protocols, accepting trade-offs in resolution for speed and accessibility. The technology is fragmenting installed-base loyalty among hospitals previously locked into high-field vendor ecosystems.
The FDA's breakthrough device designation pathway is compressing development-to-commercialization timelines for low-field MRI innovators. This regulatory acceleration is shifting competitive advantage toward software-native entrants versus legacy hardware manufacturers. Stroke triage applications in United States emergency departments are capturing the earliest volume benefits from this policy tailwind.
Operational expenditure models are displacing capital purchase structures across United States hospital procurement. Rural facilities and ambulatory surgical centers now favor mobile unit leasing with bundled service agreements over fixed-asset MRI suite construction. This financing rotation is most visible in Medicare-dependent markets where reimbursement parity between portable and conventional scans determines acquisition decisions.
Portable MRI Market Segmentation
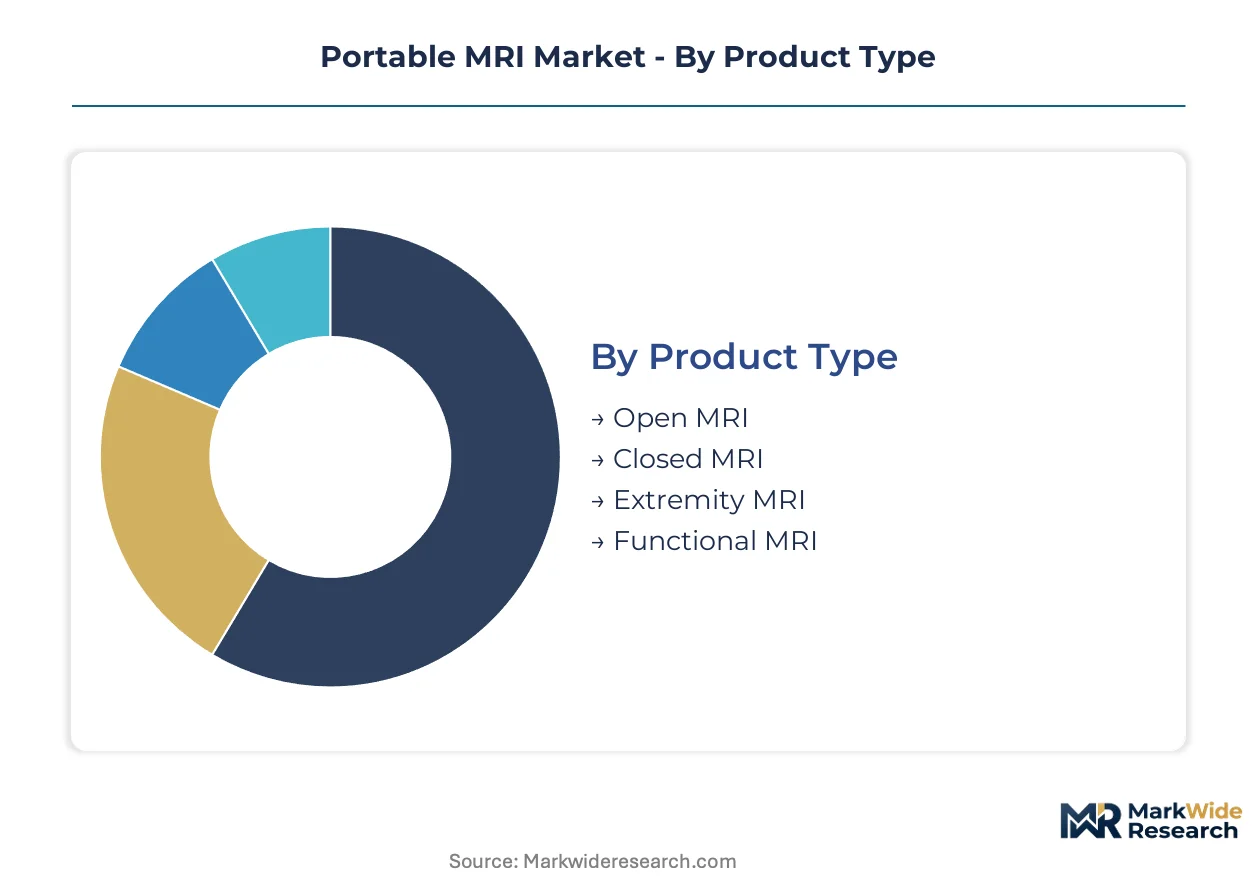
Portable MRI segmentation reveals divergent regulatory pathways shaping product development priorities. FDA breakthrough designations favor low-field architectures, while EU MDR stringency steers manufacturers toward comprehensive clinical evidence packages for superconducting platforms.
Product Type:
FDA clearance timelines diverge sharply across magnet architectures, with open systems securing 510(k) approvals faster than closed geometries requiring novel safety validations.
- Open MRI:C-shaped or double-doughnut magnet geometries eliminate patient enclosure, addressing claustrophobia rates that reach 10% in conventional scanners. United States rural hospitals prioritize these units for bedside stroke triage where patient compliance determines throughput. Medicare reimbursement parity for point-of-care neuroimaging accelerates procurement in critical access facilities.
- Closed MRI:Cylindrical bore designs with integrated radiofrequency shielding achieve superior field homogeneity for spectroscopic applications. Academic medical centers in Germany and Japan deploy these for functional neuroimaging research despite infrastructure demands. EU MDR Class IIa certification requirements extend development cycles versus FDA pathways.
- Extremity MRI:Dedicated limb-scanning systems with compact permanent magnets target orthopedic outpatient volumes.
- Functional MRI:Blood-oxygen-level-dependent imaging capabilities require specialized pulse sequences and post-processing software.
Open MRI handles the majority of throughput; Low Field MRI is the fastest mover on share.
End User:
Capital availability and reimbursement structures fragment demand across institutional categories, with Medicare-dependent providers exhibiting distinct procurement patterns from research-funded entities.
- Hospitals:Integrated health systems leverage enterprise PACS infrastructure to justify point-of-care MRI investments against fixed-scanner alternatives. United States neurocritical care units represent underpenetrated demand where bedside monitoring displaces repeated patient transport. Teleradiology partnerships resolve radiologist workforce constraints in decentralized deployment models.
- Clinics:Ambulatory surgical centers favor operational expenditure structures with bundled service agreements over capital purchases. Mobile unit leasing aligns with budget constraints and avoids fixed-asset construction timelines.
- Diagnostic Centers:Independent imaging facilities compete on throughput metrics and patient convenience positioning.
- Research Institutions:National Institutes of Health and comparable funding agencies support methodological validation studies for novel low-field reconstruction algorithms.
Hospitals concentrate the installed base; Clinics are expanding most quickly as mobile deployment models mature.
Technology:
Magnet engineering trajectories determine helium dependence and infrastructure requirements, with permanent magnet advances eliminating cryostat logistics for specific clinical applications.
- Superconducting:Niobium-titanium coil architectures operating at 4 Kelvin deliver field strengths exceeding 1.5 tesla for high-resolution neuroimaging. Qatar and United States helium supply concentration exposes manufacturers to price volatility and export restriction risks. China's NMPA innovation channel accelerates domestic alternatives, reshaping competitive dynamics for foreign OEMs.
- Permanent Magnet:Rare-earth alloys eliminate liquid helium requirements and reduce system weight below 500 kilograms for bedside deployment. Signal-to-noise constraints historically limited clinical acceptance until deep learning reconstruction algorithms resolved fundamental physics limitations.
- Hybrid MRI:Combined magnet technologies target specialized interventional applications with integrated imaging-guidance capabilities.
- Low Field MRI:Sub-0.5 tesla systems using resistive coils or permanent magnets achieve regulatory clearance through streamlined pathways.
Superconducting platforms retain the revenue base; Permanent Magnet is gaining share fastest as software reconstruction matures.
Deployment Model:
Health system preference for operational versus capital expenditure rotates procurement toward service-based structures, particularly in Medicare-reimbursed markets where payment policy determines modality selection.
- Cloud-based:Image reconstruction and storage offload computational demands to remote servers, reducing on-site IT infrastructure for small facilities. United States rural hospitals leverage these architectures to access advanced post-processing without dedicated biomedical engineering staff. Cybersecurity validation requirements from FDA and HIPAA govern data transmission protocols.
- On-premises:Local server installations preserve institutional control over patient data and minimize latency for time-critical stroke protocols. Academic medical centers with established IT security frameworks prefer this architecture for research data governance.
- Hybrid:Mixed local and remote processing balances latency sensitivity with computational scalability.
- Mobile Units:Vehicle-mounted systems with self-contained power and climate control extend neuroimaging access beyond fixed infrastructure.
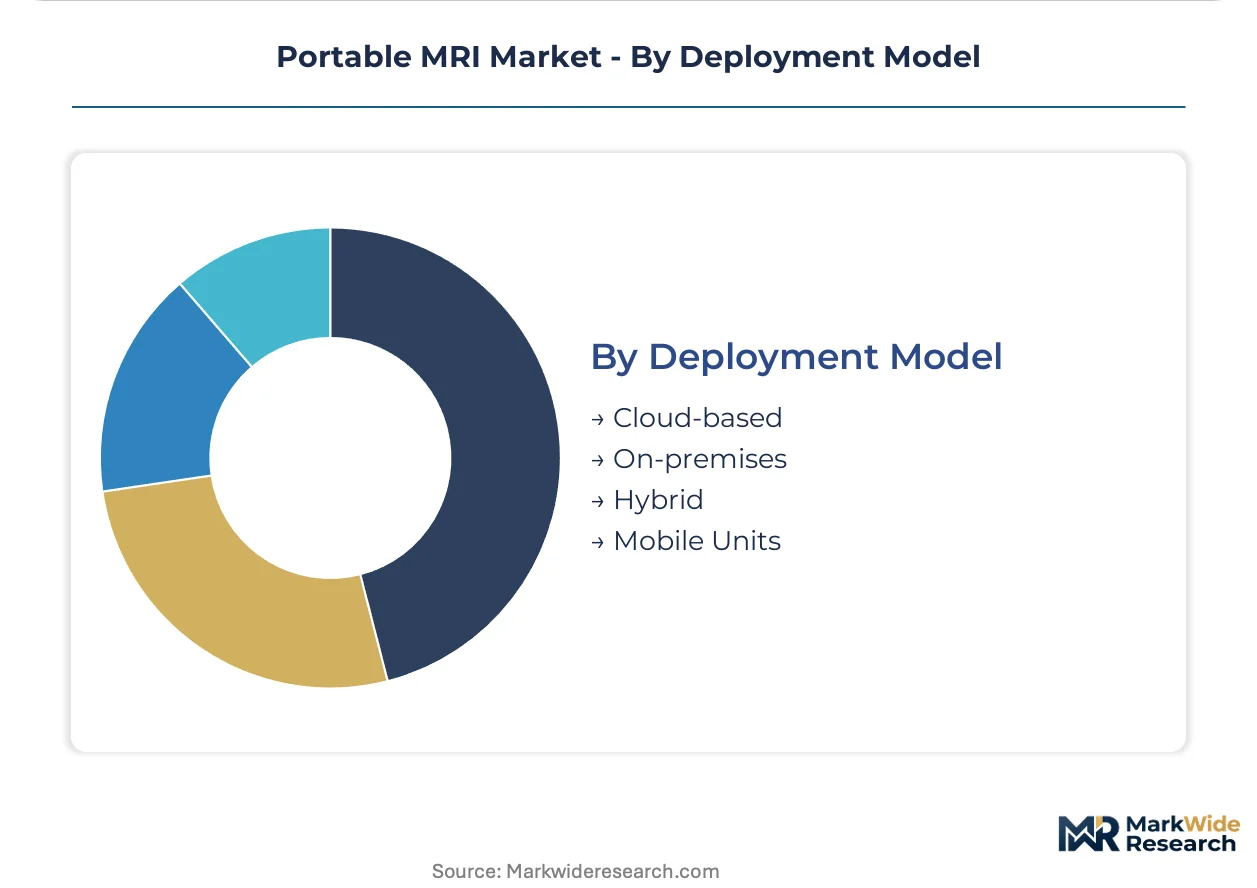
On-premises deployment retains institutional preference; Mobile Units show the steepest expansion trajectory as capital constraints reshape procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States while procurement velocity accelerates in China, creating a structural asymmetry that favors manufacturers with dual regulatory capabilities. Medicare reimbursement reforms in the United States compress capital cycles for rural hospitals, whereas NMPA innovation channels in China compress development timelines for domestic low-field entrants.
United States
FDA breakthrough device designations have compressed clearance timelines for low-field systems, accelerating commercialization of bedside neuroimaging units. Medicare reimbursement parity between portable and conventional MRI scans determines procurement decisions across critical access hospitals and ambulatory surgical centers. The Mayo Clinic in Rochester and Massachusetts General Hospital in Boston anchor clinical validation studies for stroke triage protocols.
China
NMPA accelerated review timelines for domestically manufactured low-field systems are reshaping competitive dynamics for foreign OEMs seeking market entry. Dual carbon goals from the Ministry of Ecology and Environment favor permanent magnet architectures that eliminate helium-dependent superconducting cryostats. Manufacturing clusters in Shenzhen and Beijing concentrate domestic production of lightweight resistive coil systems.
Germany
EU MDR Class IIa certification requirements extend development cycles for portable MRI systems versus FDA pathways, creating regulatory friction for superconducting platform manufacturers. The KBA medical device oversight framework imposes stringent post-market surveillance obligations on deployed neuroimaging equipment. Industrial concentration in Baden-Württemberg and Bavaria hosts Siemens Healthineers service infrastructure and academic research partnerships.
Japan
PMDA review timelines for novel low-field reconstruction algorithms lag FDA breakthrough pathways, slowing software-native entrant penetration. METI funding for aging-population healthcare infrastructure targets point-of-care diagnostic deployment in rural prefectures. Tokyo and Osaka medical districts concentrate high-field research installations while peripheral regions drive portable unit demand.
United Kingdom
NHS England procurement frameworks favor operational expenditure models for mobile diagnostic units, aligning with health system capital constraints. MHRA post-Brexit regulatory autonomy has streamlined 510(k)-equivalent pathways for FDA-cleared low-field systems. London teaching hospitals and Manchester neurosciences centers pilot decentralized scanning models for stroke network integration.
Portable MRI Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated structure where established imaging conglomerates compete with software-native disruptors. The vendor base clusters around three strategic positions: full-stack hardware-software integrators with enterprise PACS compatibility, lightweight permanent magnet specialists with aggressive pricing, and AI reconstruction algorithm developers licensing to OEM partners. Dominant competitive moves include strategic partnerships for teleradiology infrastructure and geographic expansion through mobile unit leasing networks.
Among diversified health technology conglomerates, Siemens Healthineers and GE Healthcare occupy positions anchored by installed-base loyalty and enterprise software integration capabilities. Hyperfine exemplifies the software-native archetype with FDA-cleared low-field systems. Philips Healthcare and Canon Medical Systems sit within the full-stack imaging tier with established service networks across European and North American hospital systems.
| Leading Market Players |
|---|
| Philips Healthcare |
| United Imaging |
| Hyperfine |
| Synaptive Medical |
| Promaxo |
| Siemens Healthineers |
| Canon Medical Systems |
| Voxelgrids Innovations |
| GE Healthcare |
| Others |
Value Network & Pricing Analysis
Scale economies in permanent magnet manufacturing concentrate production among Chinese and Japanese rare-earth processors, compressing price floors for lightweight systems while helium-dependent superconducting platforms face cost escalation from Qatar supply volatility. This dual-track cost structure fragments vendor pricing power across magnet architectures.
Pricing Analysis
Configured-to-order pricing for FDA-cleared low-field systems commands premiums of 15-25% over standard configurations with basic reconstruction software. The dominant pricing structure stratifies across subscription-based service models, per-unit transactional sales, and hybrid leasing with bundled teleradiology support. Price differentiation hinges on FDA breakthrough designation tier and geographic delivery infrastructure, with Medicare-reimbursed US hospitals exhibiting lowest price sensitivity and EU clinics facing highest budget constraints. Cost compression in permanent magnet tiers is intensifying because Chinese domestic OEMs are scaling NMPA-cleared production.
Supply Chain Analysis
China dominates rare-earth magnet production and NMPA-cleared system assembly, while Germany and the United States concentrate superconducting coil fabrication and helium-3/4 refining. The supply chain draws from neodymium-iron-boron alloys, niobium-titanium superconductors, and specialized RF coil arrays. Single-source vulnerability concentrates in Qatar helium exports, where geopolitical restrictions disrupt cooling system logistics. Distribution runs through hospital GPO contracts in the United States and direct OEM service networks in Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Portable MRI sits in early-cycle expansion as bedside neuroimaging protocols displace fixed-scanner transport for stroke triage, with Medicare reimbursement parity accelerating hospital procurement beyond traditional capital cycles.
For Market Incumbents: Consolidate installed-base loyalty through deep PACS integration and teleradiology infrastructure partnerships that neutralize software-native entrants. Siemens Healthineers and GE Healthcare should extend service contracts into AI reconstruction licensing to defend against Hyperfine's aggressive subscription pricing. Vertical integration into permanent magnet sourcing reduces exposure to Chinese rare-earth export controls. For New Entrants and Emerging Players: Teleradiology workflow gaps in rural US critical access hospitals represent the most penetrable white-space, where incumbent service networks under-serve decentralized scanning models. Target neurocritical care units with cloud-based image reconstruction and bundled interpretation services. The optimal go-to-market angle pairs mobile unit leasing with stroke protocol training programs that accelerate clinician adoption. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-native vendors with FDA breakthrough designations and subscription-based deployment models. Long-term viability over the next decade hinges on reimbursement parity expansion beyond Medicare into commercial payer networks. Acquisition targets should demonstrate NMPA regulatory capabilities for China market access. The signal to watch is CMS coverage determination for portable MRI in intensive care settings.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Mayo Clinic and Mass General anchor clinical validation studies for stroke triage protocols. |
| Software Companion Development | Deep learning reconstruction algorithms resolve signal-to-noise constraints in sub-0.5 tesla architectures. |
| Reimbursement Strategy | Medicare parity between portable and conventional MRI scans determines rural hospital procurement velocity. |
| CE Marking Pathway | EU MDR Class IIa requirements extend certification cycles versus FDA breakthrough pathways. |
| Geographic Expansion | NMPA innovation channels accelerate domestic Chinese low-field entrants, reshaping foreign OEM positioning. |
Research Methodology
The analysis maps low-field MRI, permanent magnet systems, superconducting platforms, and mobile deployment models, each validated through primary interviews with neuroradiologists, hospital procurement committees, biomedical engineers, and GPO contracts managers. Secondary sources include FDA 510(k) and breakthrough device filings, CMS Medicare reimbursement databases, NMPA innovation channel registrations, and EU MDR Class IIa certification records. Bottom-up unit shipment estimates triangulate against top-down health system capital expenditure surveys.
Consistency checks validate volume and value outputs against hospital procurement database benchmarks and manufacturer service contract disclosures across the projection horizon. Segmentation dimensions modeled include magnet architecture, deployment model, end-user institution type, and regional regulatory pathway. CAGRs derive from logistic adoption curves fitted to Medicare reimbursement policy timelines and NMPA review acceleration patterns. Forecast inputs incorporate radiologist workforce density by state and helium supply concentration risk indices.
Underlying assumptions cover Medicare reimbursement parity maintenance, FDA breakthrough pathway continuity, and rare-earth magnet supply stability, with deviation risk concentrated in EU MDR certification friction and Qatar helium export restrictions. Recalibration cycles align with material shifts in CMS coverage determinations and NMPA domestic preference policies.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Global 3D Ultrasound Market
Medical Imaging
Italy Mammography Market
Medical Imaging
Mobile Vascular Imaging Market
Medical Imaging
India Digital X-Ray Market
Medical Imaging
Global Electroretinography Market
Medical Imaging
United States Mammography Market
Medical Imaging
Spain Computed Tomography Market
Medical Imaging
Preclinical Brain Imaging Market
Medical Imaging
X-Ray Flat Panel Detectors Market
Medical Imaging
Positron Emission Tomography Devices (PET) Market
Medical Imaging
South America Mammography Market
Medical Imaging
Magnetic Resonance Imaging (MRI) Equipment Market
Medical Imaging
Intravascular Imaging Market
Medical Imaging
Asia-Pacific Intraoperative Imaging Market
Medical Imaging
US Teleradiology Market
Medical Imaging
Teleradiology Services Market