
 Video Paas Market | 2026-2036
Video Paas Market Size, Share, and Industry Trends Forecast 2026-2036
Video Paas Market Analytics
Modular API bundling is repositioning buyer choice in the Video PaaS landscape. Twilio, Inc. leverages its programmable video stack to anchor developer-centric procurement decisions. Microsoft competes through Azure-embedded delivery that sustains enterprise retention across productivity workflows. Zoom differentiates by occupying the simplicity tier for mid-market customers seeking rapid deployment without engineering overhead.
Video Platform as a Service denotes cloud-native infrastructure that ingests, processes, and distributes real-time or on-demand video streams through programmable APIs, typically supporting WebRTC sub-second latency and adaptive bitrate protocols such as HLS and MPEG-DASH for cross-device playback. The architecture eliminates capital-intensive encoding hardware while enabling elastic scaling for broadcast-grade reliability. Live Streaming commands the largest revenue pool among service types due to premium bandwidth and compute requirements, whereas Video Analytics exhibits the steepest growth trajectory as computer vision integration expands. Public Cloud deployment dominates volume, though Hybrid Cloud configurations capture disproportionate margin as regulated enterprises in finance and healthcare demand data sovereignty controls.
FCC guidelines on net neutrality and accessibility standards shape bandwidth pricing and captioning mandates for US-delivered streams, while GDPR and the EU AI Act impose consent frameworks and algorithmic transparency obligations on European platforms processing viewer metadata. ISO/IEC 27001 certification has become a non-negotiable gating factor for enterprise procurement evaluations. Stakeholders must monitor regulatory divergence between jurisdictions as compliance fragmentation threatens to fragment platform architecture and inflate operational complexity.
Market Dynamics
Live streaming adoption by educational institutions is accelerating as GDPR and EU AI Act compliance requirements reshape platform architecture across Germany, France, and the United Kingdom.
Growth Catalysts
- EU AI Act algorithmic transparency mandates:European platforms processing viewer metadata must implement consent frameworks and explainability layers, creating procurement pull for compliant Video PaaS infrastructure.
- WebRTC sub-second latency protocols:Real-time interactive use cases in telehealth and financial services demand edge-optimized delivery stacks that programmable APIs provision elastically.
- Hybrid Cloud data sovereignty controls:Regulated enterprises in finance and healthcare require on-premise encryption key custody alongside public cloud burst capacity.
Market Restraints
- Bandwidth pricing volatility:FCC net neutrality guideline uncertainty in the United States creates input cost unpredictability for high-bitrate live streaming workloads.
- ISO/IEC 27001 certification timeline:Enterprise procurement gating factors demand 12-18 month audit cycles that delay platform vendor onboarding.
- Edge compute infrastructure concentration:Hyperscaler cloud regions in Western Europe and North America create geographic dependency risk for sub-50ms latency guarantees.
Strategic Opportunities
- Computer vision integration in Video Analytics:Convergence of machine learning inference pipelines with real-time encoding workflows opens premium service tier expansion.
- Mid-market simplicity positioning:Rapid deployment without engineering overhead captures buyers underserved by developer-centric programmable stacks.
- Adaptive bitrate protocol standardization:HLS and MPEG-DASH interoperability reduces fragmentation friction for cross-device playback experiences.
Industry Challenges
- Regulatory divergence between jurisdictions:Compliance fragmentation threatens to inflate operational complexity as platforms maintain parallel architecture configurations for GDPR, FCC, and emerging national AI frameworks.
- Legacy on-premise encoding hardware displacement:Capital-intensive infrastructure retirement cycles delay cloud-native migration for broadcast incumbents with amortized equipment positions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Video Paas Market |
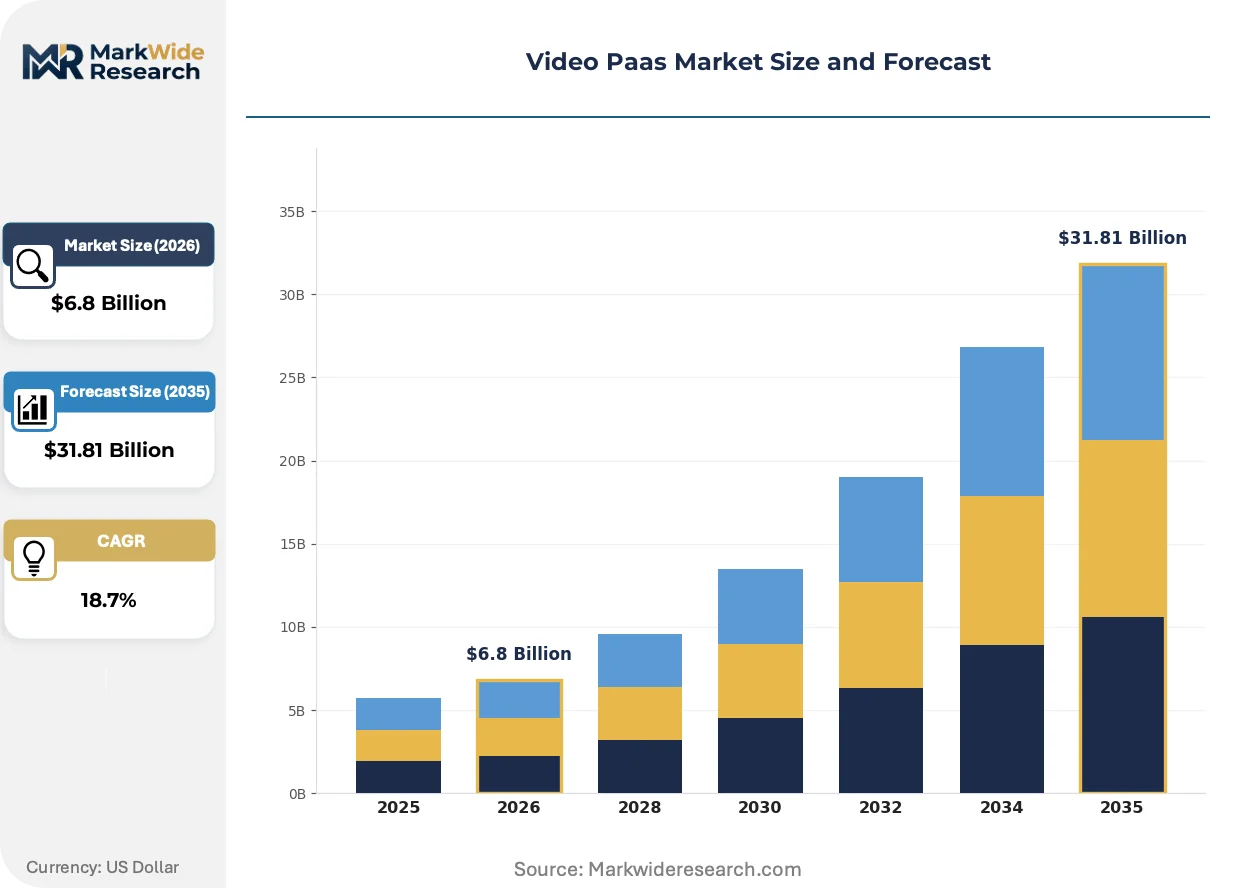
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $31.81 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Live Streaming, Video Hosting, Video Processing, Video Analytics Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premise End User: Media Companies, Educational Institutions, Enterprises, Content Creators Technology: WebRTC, RTMP, HLS, MPEG-DASH |
| Companies Covered | Twilio, Inc., Zoom, Microsoft, Cisco Systems Inc., Vidyo, Sinch, Sightcall, GENBAND, TokBox, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Video Paas Market Evolving Landscape
Artificial intelligence integration is compressing encoding decisions and viewer personalization from batch processing to real-time inference at the edge.
Edge-deployed computer vision is automating content moderation, audience sentiment analysis, and adaptive thumbnail generation for live streams. Telehealth platforms and interactive retail broadcasters are adopting these inference pipelines fastest. The technology is automating manual post-production workflows that previously required human operator intervention.
GDPR and the EU AI Act impose consent frameworks and algorithmic transparency obligations on European platforms processing viewer metadata. These requirements force architectural redesign of metadata storage and model explainability interfaces. Live streaming services in Germany, France, and the United Kingdom are responding with privacy-by-default API configurations.
Buyers are compressing vendor evaluation cycles from multi-year enterprise agreements to modular API bundling with usage-based pricing. Mid-market customers particularly favor rapid deployment without engineering overhead over feature depth. This pattern is most visible in United Kingdom educational technology procurement and United States telehealth platform selection.
Video Paas Market Segmentation
Video PaaS procurement decisions hinge on matching latency requirements, compliance obligations, and scaling economics to specific workload profiles. Buyers evaluate service tiers against deployment sovereignty needs and end-user technical sophistication.
Service Type:
Upgrade cycles from legacy broadcast infrastructure to cloud-native stacks concentrate demand in segments offering programmable elasticity.
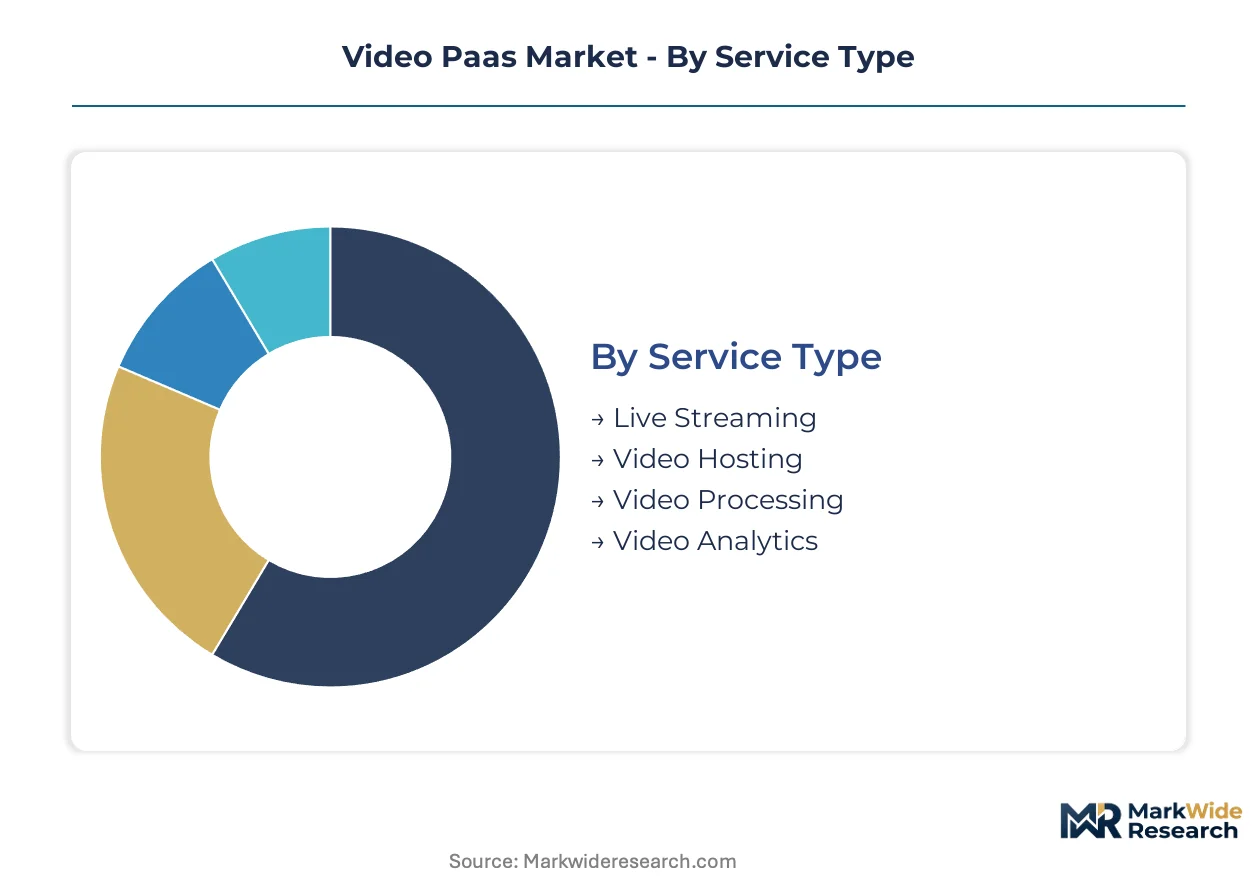
- Live Streaming:Real-time ingestion and distribution infrastructure supporting WebRTC sub-second latency and adaptive bitrate protocols. Educational institutions in Germany, France, and the United Kingdom drive procurement as GDPR and EU AI Act mandates force architectural redesign.
- Video Analytics:Computer vision pipelines for content moderation, sentiment analysis, and automated thumbnail generation. Telehealth platforms and interactive retail broadcasters adopt edge-deployed inference fastest, compressing encoding decisions from batch to real-time.
- Video Hosting:On-demand storage and delivery with CDN optimization for cross-device playback.
- Video Processing:Transcoding, format conversion, and quality optimization workflows.
Live Streaming sits at the top of the volume ranking, with Video Analytics climbing the fastest.
Deployment Model:
Cost tier differentiation separates hyperscaler convenience from sovereign control premiums.
- Public Cloud:Elastic scaling with metered bandwidth and compute. Volume dominance reflects startup and mid-market preference for zero-capital onboarding.
- Hybrid Cloud:Public cloud burst capacity paired with on-premise encryption key custody. Finance and healthcare enterprises in regulated European jurisdictions pay disproportionate margin for data sovereignty controls.
- Private Cloud:Dedicated tenant isolation with single-organization infrastructure.
- On-Premise:Fully captive hardware deployment for classified or air-gapped environments.
Public Cloud commands the widest adoption base, while Hybrid Cloud expands most quickly among compliance-sensitive buyers.
End User:
Customer type determines API complexity tolerance and procurement cycle length.
- Media Companies:Broadcast-grade reliability requirements with 24/7 linear streaming and ad-insertion workflows. Legacy on-premise encoding hardware retirement cycles delay cloud migration for amortized equipment positions.
- Enterprises:Unified communications integration with productivity suite embedding. Microsoft Azure-anchored delivery sustains retention across workflow dependencies.
- Educational Institutions:Rapid deployment preference without engineering overhead. United Kingdom edtech procurement compresses vendor evaluation from multi-year agreements to modular API bundling.
- Content Creators:Individual and small-team production with simplicity-tier demands.
Enterprises anchor current revenue concentration, with Educational Institutions gaining share fastest as live streaming adoption accelerates.
Technology:
Protocol maturity shapes interoperability friction and device reach.
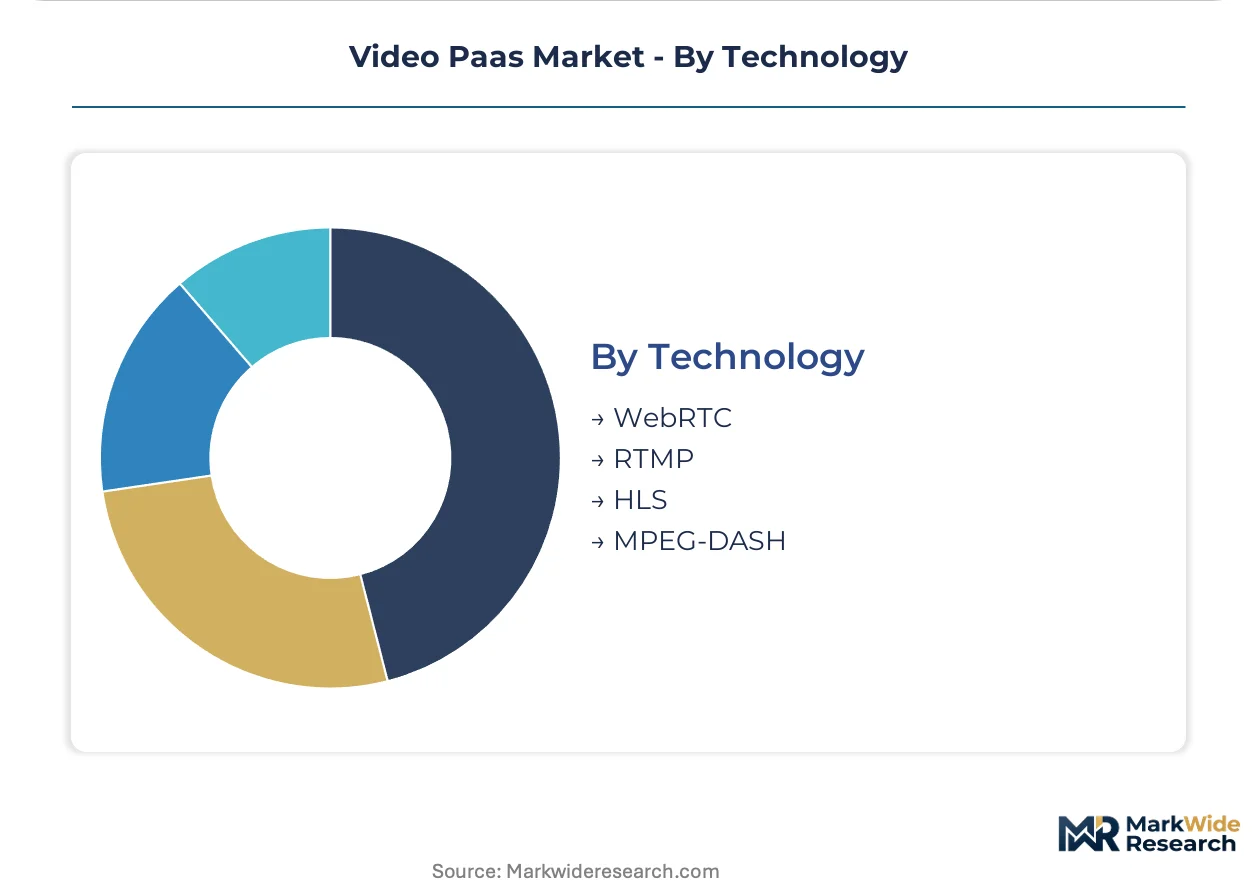
- WebRTC:Peer-to-peer real-time communication with sub-50ms latency guarantees. Financial services and telehealth use cases demand edge-optimized delivery stacks that programmable APIs provision elastically.
- HLS:HTTP Live Streaming with adaptive bitrate segmentation. Apple device ecosystem penetration sustains deployment across iOS and macOS endpoints.
- RTMP:Legacy Real-Time Messaging Protocol for ingest workflows.
- MPEG-DASH:Dynamic Adaptive Streaming over HTTP with standardized manifest structures.
WebRTC leads interactive use case adoption, with MPEG-DASH expanding most quickly as cross-device standardization reduces fragmentation friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Video PaaS infrastructure originated in Silicon Valley's developer tooling ecosystem during the early WebRTC standardization period, with subsequent scaling across European financial centers and Asia-Pacific telehealth corridors. Geographic deployment patterns now track regulatory complexity rather than pure latency optimization.
United States
Enterprise productivity suite embedding and telehealth platform proliferation drive procurement volume. FCC net neutrality guideline uncertainty creates bandwidth pricing volatility for high-bitrate live streaming workloads. The San Francisco Bay Area and Seattle technology clusters anchor hyperscaler cloud region concentration for sub-50ms latency guarantees.
Germany
Industrial automation live streaming and automotive engineering collaboration tools expand addressable demand. GDPR consent frameworks and EU AI Act algorithmic transparency obligations force architectural redesign of metadata storage systems. Berlin and Munich edtech procurement compresses vendor evaluation cycles toward modular API bundling.
United Kingdom
Educational technology live streaming adoption accelerates as institutions seek rapid deployment without engineering overhead. ICO enforcement of GDPR viewer metadata processing rules mandates privacy-by-default API configurations. London's financial services sector demands hybrid cloud encryption key custody alongside public cloud burst capacity.
France
Telehealth platform scaling and interactive retail broadcasting create edge-deployed computer vision demand. CNIL oversight of automated decision-making systems requires explainability layers for audience sentiment analysis algorithms. Parisian media technology clusters concentrate broadcast-grade reliability engineering talent.
Japan
Financial services real-time communication and aging population telehealth infrastructure drive WebRTC protocol adoption. METI data sovereignty guidelines encourage on-premise encryption key custody for regulated enterprises. Tokyo and Osaka metropolitan areas host edge compute infrastructure for sub-second latency financial trading applications.
Video Paas Market Competitive Landscape
The competitive structure tilts toward hyperscaler-anchored consolidation with persistent mid-market simplicity specialization. Developer-centric programmable stacks and enterprise productivity suite embedding represent the dominant strategic archetypes. Capacity expansion through edge compute region densification and strategic API bundling partnerships constitute the primary competitive moves.
Within the developer-centric tier, Twilio, Inc. and TokBox exemplify programmable video stack positioning that anchors procurement decisions for engineering-led organizations. Microsoft occupies the enterprise productivity integration vector through Azure-embedded delivery sustaining retention across workflow dependencies. Zoom sits within the simplicity tier for mid-market customers seeking rapid deployment without engineering overhead.
| Leading Market Players |
|---|
| Twilio, Inc. |
| Zoom |
| Microsoft |
| Cisco Systems Inc. |
| Vidyo |
| Sinch |
| Sightcall |
| GENBAND |
| TokBox |
| Others |
Value Network & Pricing Analysis
Captive edge compute infrastructure in hyperscaler cloud regions anchors both supply positioning and pricing power for Video PaaS vendors. Microsoft Azure-embedded delivery and Twilio's programmable video stack demonstrate how vertical integration into encoding hardware and CDN nodes compresses unit economics while sustaining premium tier capture.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates enterprise workload contracts from mid-market simplicity tiers and developer-centric pay-as-you-go APIs. ISO/IEC 27001 certification grade and WebRTC sub-second latency guarantees drive price differentiation between compliant and non-compliant infrastructure tiers. Cost compression in the standard tier is intensifying because bandwidth pricing volatility from FCC net neutrality guideline uncertainty feeds into metered compute contracts. Educational institutions in the United Kingdom exhibit highest price sensitivity due to compressed procurement cycles, while financial services in London demonstrate lowest sensitivity given hybrid cloud data sovereignty requirements.
Supply Chain Analysis
Regional distribution centers in hyperscaler cloud regions follow hub-and-spoke patterns radiating from San Francisco Bay Area, Seattle, Frankfurt, and Tokyo metropolitan clusters. Supply concentration in the United States, Germany, and Japan feeds from specialized semiconductor fabrication for encoding accelerators, optical fiber bandwidth provisioning, and edge server assembly. Single-source vulnerability in WebRTC protocol stack licensing creates structural risk for vendors dependent on Google-maintained open-source implementations. Distribution runs through direct API marketplace integrations and channel partner systems integrators serving enterprise productivity suite deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Video PaaS market functions as a regulatory compounder where GDPR and EU AI Act algorithmic transparency mandates force architectural redesign and sustain procurement pull for compliant infrastructure across European jurisdictions.
For Market Incumbents: Anticipate margin compression from modular API bundling by defending position through ISO/IEC 27001 certification investment and edge compute region densification in Berlin, Munich, and London. Hybrid cloud encryption key custody capabilities represent the priority lever for retaining finance and healthcare enterprises facing data sovereignty requirements. Counter Zoom's simplicity-tier capture in educational institutions by embedding video APIs within existing productivity workflow dependencies. For New Entrants and Emerging Players: GDPR and EU AI Act compliance requirements in Germany, France, and the United Kingdom open a window for privacy-by-default API configurations targeting edtech procurement. White-space concentration sits in mid-market telehealth platforms seeking rapid deployment without engineering overhead, and in interactive retail broadcasters demanding edge-deployed computer vision for automated content moderation. Go-to-market positioning should emphasize usage-based pricing against multi-year enterprise agreements. For Investors and Strategic Acquirers: Roll-up economics work for developer-centric programmable video specialists because hyperscaler-anchored consolidation is compressing vendor counts while sustaining premium multiples for compliance-authenticated infrastructure. Acquisition targets should demonstrate WebRTC protocol expertise and existing ISO/IEC 27001 certification. The signal to watch is FCC net neutrality guideline resolution, which would clarify bandwidth pricing inputs and reset valuation multiples for high-bitrate live streaming workloads.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Compute Region Densification | Frankfurt and London expansion supports GDPR-compliant sub-50ms latency for financial services. |
| Hybrid Cloud Certification Program | ISO/IEC 27001 audit acceleration reduces 12-18 month procurement delays for enterprise buyers. |
| Computer Vision Pipeline Integration | Real-time inference at edge nodes captures Video Analytics growth from telehealth sentiment analysis demand. |
| API Marketplace Partnership | Channel integration with systems integrators defends against Zoom's direct simplicity-tier capture. |
| Regulatory Compliance Automation | EU AI Act explainability layer embedding sustains premium positioning against non-compliant competitors. |
Research Methodology
Bottom-up educational institution and telehealth platform modeling reconciled against top-down hyperscaler capex and bandwidth provisioning tracking forms the analytical core. Primary interviews with CTOs, IT procurement officers, platform engineers, and channel partners combined with secondary validation against SEC filings, hyperscaler infrastructure disclosure reports, and European Data Protection Board regulatory guidance. GDPR enforcement action databases and FCC docket filings provided compliance timeline calibration.
Input-output matrices map WebRTC latency requirements, adaptive bitrate protocol adoption curves, and deployment model preferences across service type segments. Modeled dimensions span live streaming versus video analytics workload profiles, public versus hybrid cloud configurations, and enterprise versus educational institution end-use characteristics. CAGRs derive from elasticity-adjusted bandwidth demand curves and computer vision integration penetration assumptions. Forecast inputs include edge compute region expansion timelines and ISO/IEC 27001 certification velocity across vendor bases.
Revisions become necessary when FCC net neutrality guideline resolution, EU AI Act enforcement precedent, or WebRTC protocol standardization shifts materialize. Forecasts reflect documented assumptions regarding bandwidth pricing stability and regulatory compliance fragmentation trajectories. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Wearable Solar Devices Market
Others
Process Instrumentation Equipment Market
Others
Middle East and Africa Medium Voltage Switchgear Market
Others
Printing Machines Market
Others
DNA Data Storage Market
Others
Paraffin Physical Therapy Market
Others
China Automotive LED Lighting Market
Others
DIY Smart Home Market
Others
Commercial Aircraft Angle of Attack Sensors Market
Others
Spain Automotive LED Lighting Market
Others
Asia-Pacific B2B Legal Services Market
Others
North America Wiring Duct Market
Others
Latin America Travel Retail Market
Others
Three Proofing Rugged Tablet Market
Others
Running Apparel Market
Others
Pediatric Measuring Devices Market