
 Europe Refrigerated Display Cases Market | 2026-2036
Europe Refrigerated Display Cases Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Refrigerated Display Cases Market Insights
Refrigeration technician shortages across Central Europe is reorganizing how OEMs structure service networks and aftermarket support. Epta S.p.A. leverages its Italian manufacturing base to control spare-part lead times for southern European clients. AHT Cooling Systems anchors its position through captive production of hydrocarbon-ready compressors in Austria. Daikin Industries competes by extending its heat-pump expertise into integrated climate systems for hypermarket formats.
Europe refrigerated display cases are insulated, temperature-controlled enclosures designed to present perishable goods while maintaining precise thermal conditions, typically using forced-air or gravity-coil cooling with polyurethane foam insulation and low-emissivity glazing. Their primary commercial purpose is to reduce food spoilage in retail environments while enabling visible product presentation that stimulates impulse purchases. Glass door merchandisers now lead product-type revenue as energy-conscious retailers abandon open-display formats, while undercounter refrigerators represent the fastest-growing installation segment in compact urban convenience stores. Modular systems capture disproportionate margin pools by allowing retailers to reconfigure floor plans without full equipment replacement.
The EU F-Gas Regulation and Ecodesign Directive shape product standards by mandating refrigerant phase-downs and minimum energy performance thresholds, forcing manufacturers to redesign compressor architectures and insulation packages. REACH compliance adds material-selection constraints on foams, coatings, and electrical components that enter the European Economic Area. Stakeholders must monitor how the EU Green Deal's evolving carbon-border adjustments and national building-efficiency codes will redefine total-cost-of-ownership calculations for retail refrigeration fleets.
Market Dynamics
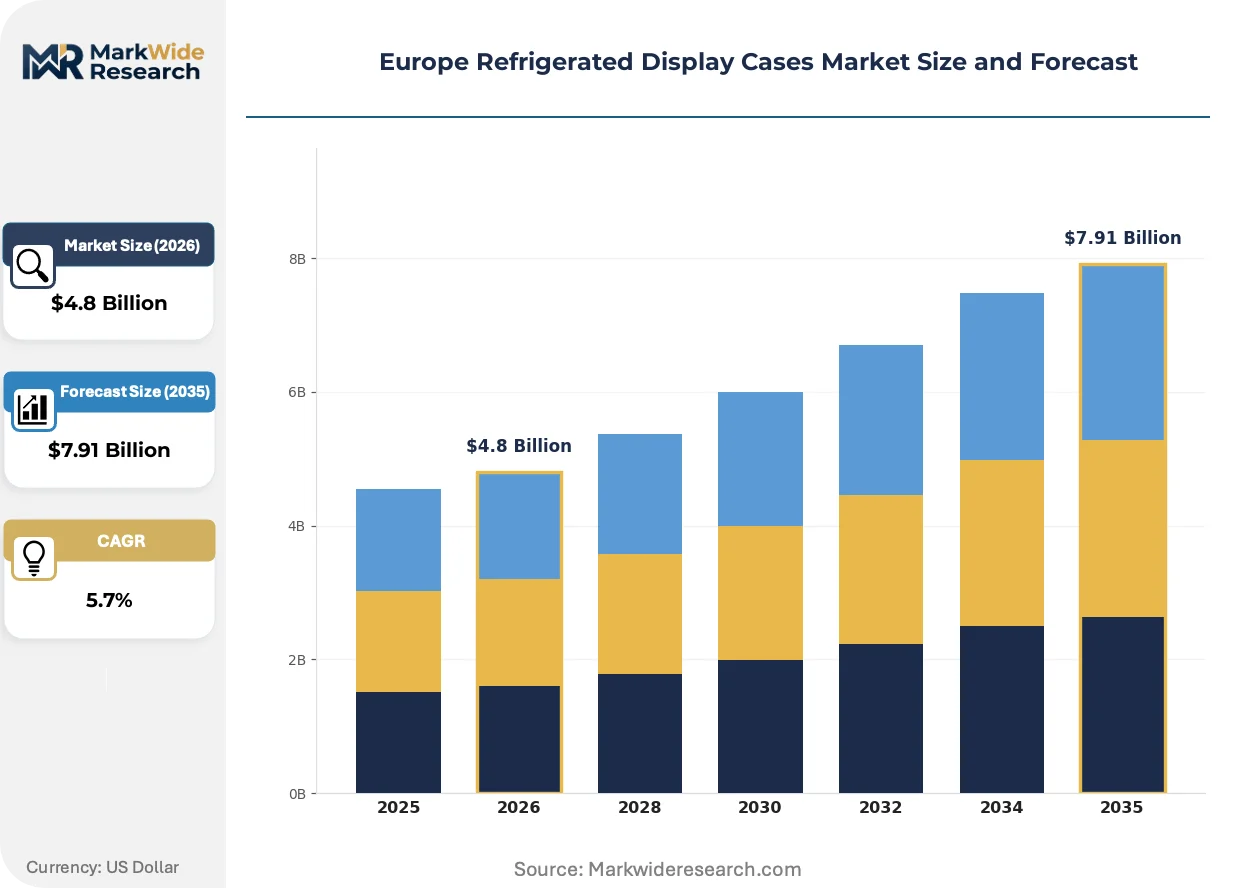
The EU F-Gas Regulation's refrigerant phase-down mandate is compressing equipment replacement cycles and forcing compressor architecture redesigns across European food retail chains. This regulatory pressure intersects with supermarket consolidation trends to reshape procurement patterns for refrigerated display infrastructure.
Growth Catalysts
- Energy-efficiency retrofit mandates:Germany's national building codes and France's thermal regulation RT2012 are compelling hypermarket operators to replace aging open-front units with glass-door merchandisers that cut electricity consumption.
- Natural refrigerant transition:Propane and CO2 systems are capturing specification share as the EU F-Gas Regulation tightens hydrofluorocarbon quotas, driving R&D investment in hydrocarbon-ready compressor platforms.
- Urban convenience store expansion:Compact undercounter refrigerator demand is accelerating in Italy and Spain where city-center retail footprints are shrinking and fresh-food proximity retail is displacing traditional supermarkets.
Market Restraints
- Copper and aluminum price volatility:Raw material cost swings for heat exchanger metals are compressing OEM margins and complicating long-term contract pricing with retail chains.
- Refrigeration technician scarcity:Central Europe's qualified service workforce shortage is extending equipment downtime and forcing manufacturers to absorb training costs for aftermarket network expansion.
- Legacy HFC infrastructure lock-in:Existing supermarket fleets with substantial remaining depreciation life are delaying full-system conversions despite regulatory deadlines.
Strategic Opportunities
- Polish and Romanian retail modernization:Eastern European grocery chains are entering their first major refrigerated display replacement wave as EU cohesion funds upgrade commercial infrastructure.
- Modular reconfigurable systems:Retailers in France are adopting plug-and-play case architectures that permit floor-plan changes without complete equipment removal, capturing margin pools in high-rent urban locations.
- Heat pump integration convergence:Combined heating-cooling climate systems for hypermarket formats are opening specification pathways for HVAC specialists entering food retail refrigeration.
Industry Challenges
- Certification timeline compression:CE marking and Ecodesign Directive compliance testing for new natural refrigerant platforms is extending product launch schedules by 8-14 months.
- Legacy control system integration:New energy-management hardware must interface with decades-old supermarket building automation protocols, multiplying commissioning complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Refrigerated Display Cases Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Open Display Cases, Glass Door Merchandisers, Undercounter Refrigerators, Portable Display Cabinets End User: Supermarkets, Restaurants, Convenience Stores, Foodservice Outlets Installation Type: Built-in, Freestanding, Modular, Custom-designed Energy Source: Electric, Solar, Hybrid, Others |
| Companies Covered | Epta S.p.A., Illinois Tool Works, Lennox International, AHT Cooling Systems, Hussmann Corporation, Dover Corporation, Hoshizaki Corporation, Metalfrio Solutions, Daikin Industries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Refrigerated Display Cases Market Trends and Innovations
Equipment architecture is pivoting toward closed-cabinet designs and intelligent thermal management as energy costs and refrigerant regulations tighten simultaneously. These shifts are compressing traditional equipment lifecycles and redrawing competitive boundaries between refrigeration specialists and building climate providers.
Variable-speed compressor technology with integrated electronic expansion valve control is miniaturizing cabinet footprints while maintaining precise temperature bands for delicate categories like prepared salads and sushi. Discount grocery chains in Germany are deploying these compact forced-air systems at pace, enabling smaller-format stores in dense urban cores where square-meter economics previously prohibited full fresh-food offerings.
The EU F-Gas Regulation's 2024 quota reduction is accelerating CO2 transcritical system adoption in northern European climates. Manufacturers are redesigning high-pressure compressor architectures and safety enclosures to accommodate the refrigerant's thermodynamic properties. Scandinavian supermarket operators are responding fastest, driven by national carbon-neutrality targets that predate EU-wide mandates.
Retailers are unbundling after-sales service from initial equipment procurement, selecting third-party maintenance providers through competitive tender rather than OEM-captive contracts. This behavior shift is most visible in the Netherlands where supermarket cooperatives have consolidated technical service purchasing across member banners, compressing incumbent supplier service margins and opening entry points for independent refrigeration contractors with hydrocarbon certification credentials.
Europe Refrigerated Display Cases Market Segmentation
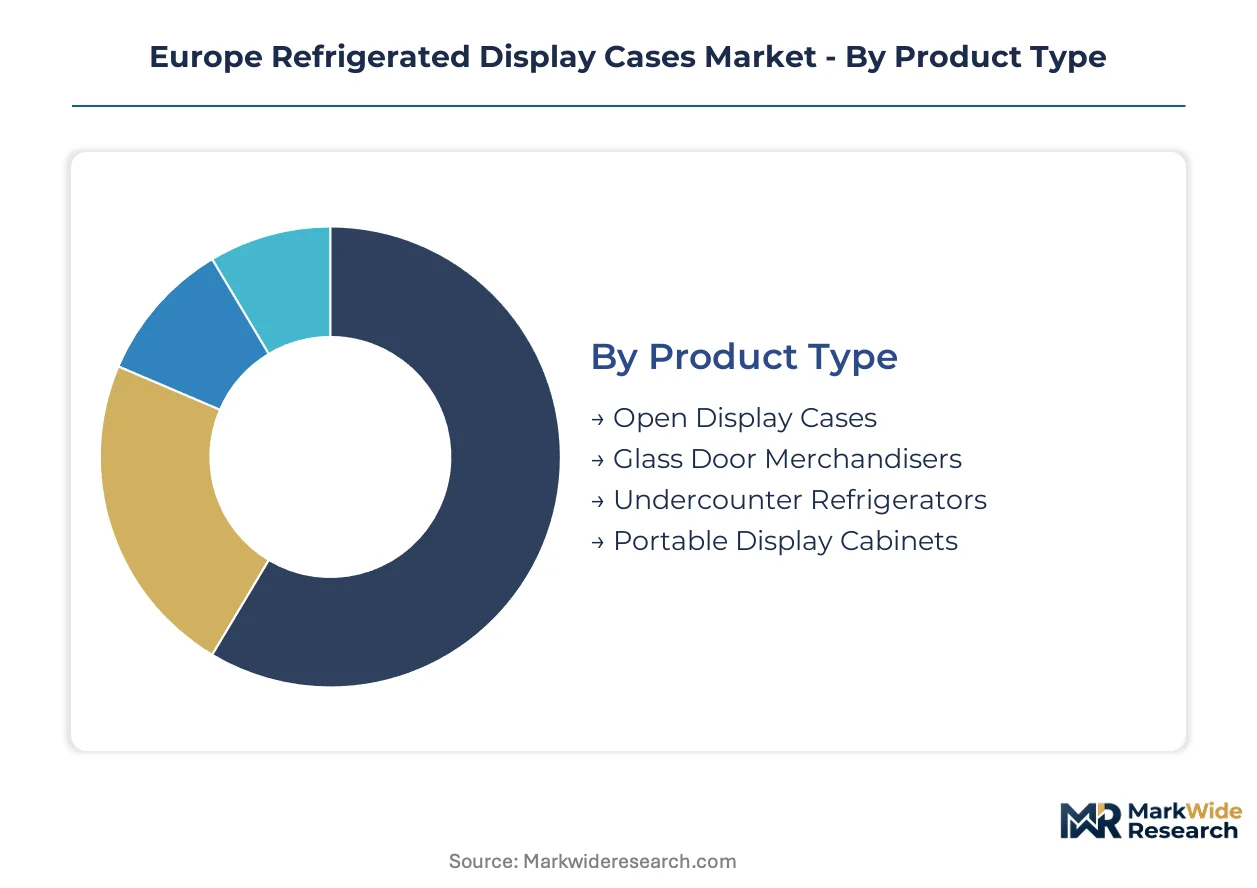
Refrigerated display case segmentation in Europe reflects divergent regulatory pressures across member states. The EU F-Gas Regulation and national energy codes create distinct specification requirements that reshape procurement patterns by product type, end-use, and installation format.
Product Type:
Regulatory differentiation separates high-efficiency glass-door systems from legacy open formats, with Ecodesign Directive thresholds determining viable equipment architectures across climate zones.
- Glass Door Merchandisers:Forced-air cooling systems with low-emissivity double-glazing and LED illumination dominate German and French hypermarket retrofits. Operators in these markets face binding energy-efficiency mandates that disqualify open-front alternatives from new installations.
- Undercounter Refrigerators:Compact forced-air units with polyurethane foam insulation serve urban convenience stores in Italy and Spain. These formats expand most quickly where city-center retail footprints shrink and fresh-food proximity formats displace traditional supermarkets.
- Open Display Cases:Gravity-coil cooling without physical barriers persists in discount grocery segments but faces phase-out timelines under national building codes.
- Portable Display Cabinets:Mobile units with plug-and-play refrigeration circuits address temporary retail and catering applications with lower capital commitment.
Established volume favors glass door merchandisers; emerging adoption favors undercounter refrigerators.
End User:
Consolidation intensity determines procurement sophistication, with centralized buying groups in supermarket chains imposing uniform technical specifications that fragment vendor access.
- Supermarkets:Large-format operators deploy integrated climate systems with heat recovery and centralized CO2 refrigeration plants. German chains lead hydrocarbon-ready compressor specification due to national carbon-neutrality targets.
- Convenience Stores:Small-footprint retailers prioritize modular plug-and-play cases that permit rapid floor-plan reconfiguration. French urban operators drive demand for reconfigurable architectures in high-rent districts.
- Restaurants:Foodservice operators select undercounter and back-of-house units with NSF hygiene certification and rapid temperature recovery for high-turnover service periods.
- Foodservice Outlets:Institutional caterers and contract foodservice providers specify durable equipment with extended warranty terms and captive service network coverage.
Procurement concentration sits with supermarket chains; specification fragmentation characterizes foodservice outlets.
Installation Type:
Real estate economics drive format selection, with lease duration and square-meter costs determining whether retailers invest in permanent built-in systems or retain operational flexibility.
- Modular:Standardized cabinet dimensions with universal connection interfaces allow retailers to reconfigure sales floors without equipment replacement. French and Dutch operators lead adoption where urban retail rents command rapid layout adaptation.
- Built-in:Architecturally integrated cases with custom finishes anchor flagship stores and premium supermarket formats in Germany and Austria.
- Freestanding:Self-contained units with integral refrigeration circuits serve temporary locations and secondary retail spaces with limited infrastructure.
- Custom-designed:Bespoke dimensions and finishes address flagship retail concepts and heritage building constraints in historic city centers.
Capital efficiency favors modular formats; brand investment favors custom-designed installations.
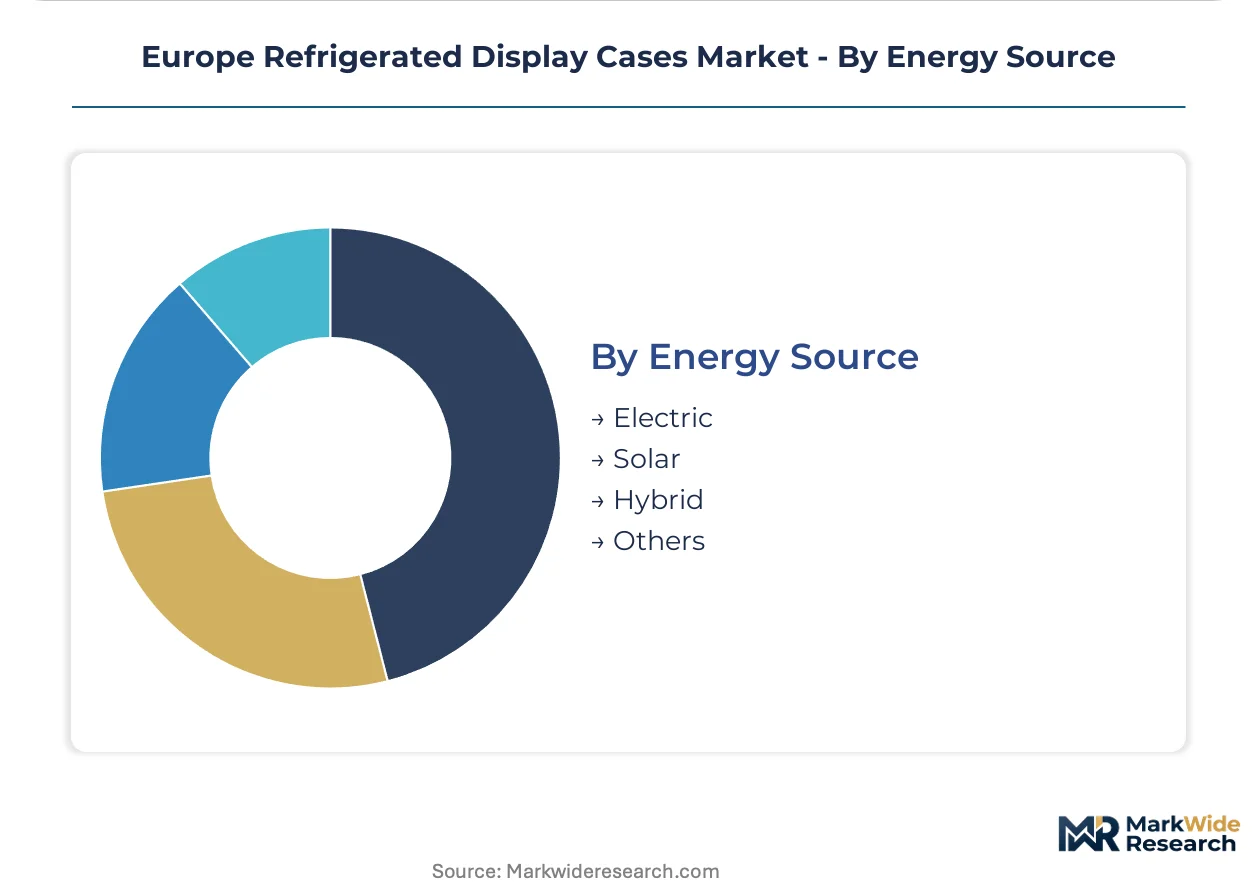
Energy Source:
Grid carbon intensity and national renewable energy incentives reshape total-cost-of-ownership calculations for retail refrigeration fleets across member states.
- Electric:Grid-connected compressor systems dominate installed base, with efficiency gains from variable-speed drives and electronic expansion valve control.
- Solar:Photovoltaic-integrated cases with battery storage address off-grid locations and sustainability commitments in southern European markets with high irradiance.
- Hybrid:Combined grid and on-site generation systems with intelligent load management optimize operating costs where time-of-use electricity pricing varies.
- Others:Absorption cooling and thermal storage alternatives serve specialized applications with waste heat availability or critical backup requirements.
Operational reliability favors electric systems; carbon reduction targets favor hybrid configurations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation anchors Germany's dominant position, compressing replacement cycles across Central European retail chains. National energy codes in France and Italy accelerate glass-door retrofits, while Eastern European markets enter their first major modernization wave.
Germany
Hypermarket operators face binding efficiency mandates under the national Building Energy Act. The KBA enforces refrigerant containment standards for commercial fleets. Bavarian manufacturing clusters around Munich supply hydrocarbon-ready compressor platforms to domestic chains.
France
Urban convenience stores drive modular case demand in high-rent Paris districts. The RT2012 thermal regulation compels open-front unit phase-outs. Retail cooperatives in the Île-de-France region consolidate technical service purchasing across member banners.
Italy
Fresh-food proximity formats displace traditional supermarkets in Milan and Rome city centers. REACH compliance constrains foam and coating selections for equipment entering the European Economic Area. Northern Italian industrial districts produce spare parts for southern European service networks.
Poland
Grocery chains initiate first major refrigerated display replacement programs. EU cohesion funds upgrade commercial infrastructure in Warsaw and Kraków. Retail modernization concentrates in urban centers as foreign banners expand local footprints.
Netherlands
Supermarket cooperatives unbundle after-sales service from equipment procurement. The national building code accelerates energy-efficiency retrofits in Amsterdam and Rotterdam. Independent contractors with hydrocarbon certification capture service market share from incumbent suppliers.
Europe Refrigerated Display Cases Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in Europe's refrigerated display case supply base. Italian and Austrian manufacturers anchor the upper tier through captive component production and controlled spare-part logistics. Mid-scale specialists compete on modular reconfigurability and rapid floor-plan adaptation. Consolidation pressure intensifies as retailers centralize procurement through buying groups, while natural refrigerant certification requirements filter out smaller service providers.
Among Italy-based fabricators, Epta S.p.A. exemplifies the integrated manufacturer archetype through its domestic manufacturing footprint and southern European service network control. AHT Cooling Systems represents the component-integrated specialist model with its Austrian production base for hydrocarbon-ready compressors. Daikin Industries occupies a position bridging refrigeration and building climate systems, leveraging heat-pump expertise into hypermarket format specifications.
| Leading Market Players |
|---|
| Epta S.p.A. |
| Illinois Tool Works |
| Lennox International |
| AHT Cooling Systems |
| Hussmann Corporation |
| Dover Corporation |
| Hoshizaki Corporation |
| Metalfrio Solutions |
| Daikin Industries |
| Others |
Pricing and Supply Chain Analysis
Ninety-day compressor lead times from Austrian manufacturing hubs concentrate pricing power among integrated OEMs with captive component production, while spot-market copper volatility feeds directly into contract renegotiation cycles for smaller fabricators serving Eastern European retail chains.
Pricing Analysis
Price spreads between German hypermarket retrofits and Polish first-time installations exceed fifty percent on equivalent glass-door specifications, reflecting divergent regulatory compliance burdens and service bundling expectations. Three-tier pricing structure across premium, standard, and economy levels segments by hydrocarbon certification status and after-sales network density, with French retail cooperatives extracting volume discounts through centralized procurement. Cost compression in the standard tier is intensifying because aluminum heat-exchanger input volatility transfers directly to equipment quotations. Discount grocery chains in Germany exhibit highest price sensitivity; premium supermarket banners in Austria prioritize energy-performance guarantees over upfront capital expenditure.
Supply Chain Analysis
Compressor inventory buffers at Italian and Austrian manufacturing clusters determine downstream availability for southern European service networks during peak replacement seasons. Supply concentrates in Germany, Italy, and Austria for hydrocarbon-ready compressor platforms and precision refrigeration controls, while polyurethane foam insulation draws from Benelux chemical processing hubs. Copper tubing and aluminum heat-exchanger sourcing rests on commodity exchange pricing with limited long-term hedging by mid-scale fabricators. Single-source vulnerability in electronic expansion valve controllers from German automotive-tier suppliers creates bottleneck exposure. Distribution runs through OEM-captive service networks in Western Europe and independent refrigeration contractors with hydrocarbon certification in the Netherlands and Poland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as supermarket cooperatives in France and the Netherlands consolidate technical service purchasing across member banners, fragmenting vendor access and compressing incumbent supplier margins.
For Market Incumbents: Shield installed-base revenue by embedding predictive maintenance sensors that extend replacement cycles and complicate third-party service entry. Deepen backward integration into compressor architectures to offset commodity volatility exposure. The EU F-Gas Regulation's accelerating refrigerant phase-down timeline threatens legacy HFC service margins; priority investment in hydrocarbon-ready technician certification programs secures aftermarket lock-in against independent contractors. For New Entrants and Emerging Players: Lead with modular reconfigurable case architectures targeting French urban convenience stores where rapid floor-plan adaptation commands premium positioning. Polish grocery chains entering first major replacement cycles present the most penetrable geography, with EU cohesion funds de-risking capital commitment for equipment procurement. A service-unbundled go-to-market model—selling equipment without captive maintenance contracts—aligns with Dutch cooperative purchasing behavior and opens specification pathways against integrated incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with refrigerated display case divisions below strategic priority thresholds, particularly those lacking hydrocarbon certification infrastructure. Long-term viability across the analysis window hinges on natural refrigerant platform readiness and Eastern European service network density. The signal to watch is technician certification completion rates relative to F-Gas quota reduction timelines, as workforce constraints will determine which OEMs capture replacement cycle volume.| Strategic Initiative | Industry Significance |
|---|---|
| Hydrocarbon Compressor Platform Development | CE marking and Ecodesign Directive compliance for propane-ready architectures secures specification share under tightening F-Gas quotas. |
| Modular Case Architecture Launch | Plug-and-play reconfigurability captures margin pools in high-rent Paris and Amsterdam urban retail districts. |
| Eastern European Service Network Expansion | Polish and Romanian technician training centers position for EU cohesion fund-driven replacement cycles. |
| Predictive Maintenance Sensor Integration | IoT-enabled thermal monitoring extends equipment lifecycles and defends aftermarket revenue against unbundling trends. |
| Heat Pump Climate System Convergence | Combined heating-cooling specifications for hypermarket formats open procurement pathways from HVAC specialists. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with equipment procurement directors at German and French supermarket chains, refrigeration service network managers in Italy and Poland, and compressor platform engineers at Austrian manufacturing facilities; alongside secondary validation through EU F-Gas Regulation implementation reports, Ecodesign Directive compliance databases, and national building code amendments across member states. Bottom-up equipment shipment estimates triangulated against top-down retail construction and renovation permits.
Across the projection horizon, the analytical framework modeled volume and value outputs by product type, end-user consolidation intensity, installation format flexibility, and refrigerant platform architecture. CAGRs derived from replacement cycle compression under regulatory mandates, urban retail footprint shrinkage patterns, and natural refrigerant adoption S-curves. Forecast inputs incorporated technician workforce availability projections and copper-aluminum price band scenarios.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated Eastern European retail modernization would require recalibration. Forecasts reflect documented assumptions regarding F-Gas quota phase-down adherence and cohesion fund disbursement timelines. Supply chain disruption from commodity price spikes or certification bottleneck delays represents specific revision triggers. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Others
Europe Indoor Air Purification Market
Others
Middle East and Africa Electric Vehicle Battery Electrolyte Market
Others
AI in Precision Medicine Market
Others
Middle East and Africa Induced Pluripotent Stem Cells (Ipscs) Market
Others
Egg Market
Others
Folding Screen Mobile Phone Market
Others
Cloud DVR Market
Others
Mobile MRI Services Market
Others
Smart Plug Market
Others
Spend Analytics Market
Others
Ultra Mobile Devices (UMD) Market
Others
Europe Battery Packaging Market
Others
Fresh Durian Market
Others
Griffin Beaker Market
Others
Animal Feed Alternative Protein Market
Others
Europe Video Encoder Market