
 Lubricants for Cement Industry Market | 2026-2036
Lubricants for Cement Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Lubricants for Cement Industry Market Foresight
Maintenance-as-a-service is consolidating how lubricant vendors monetize cement plant relationships beyond fluid sales. ExxonMobil leverages its technical service networks to embed predictive maintenance contracts directly into supply agreements. Fuchs anchors European cement corridors with specialty greases formulated for high-temperature kiln bearings. Kluber Lubrication differentiates through application engineering that reduces re-lubrication intervals in critical cement equipment.
Lubricants for the cement industry comprise formulated oils and greases engineered with base stocks, viscosity index improvers, and anti-wear additives to withstand extreme pressure, thermal oxidation, and particulate contamination in rotary kilns, crushers, and grinding mills. These products primarily reduce mechanical wear, dissipate heat, and seal contaminants to extend equipment life in continuous-process cement manufacturing. Hydraulic fluids dominate volume demand as open gear systems and roller press circuits require high-viscosity, water-resistant formulations that command premium pricing over standard motor oils. Gear oils represent the fastest-growing product category as cement producers retrofit larger mills with centralized lubrication systems that demand synthetic polyglycol formulations. Bulk delivery leads the delivery mode segment because integrated cement manufacturers operate captive blending facilities that receive tanker shipments to minimize packaging costs and handling waste.
EPA regulates used lubricant disposal under RCRA hazardous waste rules, forcing cement plants to invest in reclamation systems or certified recycling contracts that elevate total cost of ownership. REACH restricts certain extreme-pressure additives in European formulations, compelling reformulation investments that reshape supplier qualification criteria for EU-based cement producers. India's BIS certification mandates lubricant quality benchmarks for imported products, creating compliance barriers for non-domestic suppliers serving the country's expanding clinker capacity. Stakeholders must monitor evolving carbon border adjustments and local content requirements that will increasingly determine supplier selection and contract structures in major cement-producing jurisdictions.
Market Dynamics
Synthetic lubricant adoption is compressing re-lubrication cycles across cement manufacturing as producers prioritize kiln uptime over fluid cost. EPA emissions enforcement and EU F-Gas Regulation are simultaneously tightening disposal protocols and reformulation standards, forcing suppliers to requalify product portfolios across multiple jurisdictions.
Growth Catalysts
- EPA RCRA hazardous waste rules:Used lubricant disposal mandates are cementing reclamation service contracts as recurring revenue streams for technical service providers.
- India's clinker capacity expansion:Bulk hydraulic fluid procurement from integrated manufacturers is concentrating volume demand in captive blending facilities.
- Synthetic polyglycol gear oils:Centralized lubrication systems in retrofitted grinding mills are pulling high-viscosity formulations into faster replacement cycles.
Market Restraints
- Base oil price volatility:Group II and III base stock cost swings are compressing blender margins on long-term supply contracts.
- REACH additive restrictions:Extreme-pressure compound limitations are forcing reformulation investments that delay EU supplier qualification timelines.
- Mineral oil substitution ceiling:High-temperature kiln bearing applications retain mineral oil dependence due to synthetic cost thresholds at extreme thermal loads.
Strategic Opportunities
- India BIS certification barriers:Domestic blending capacity investments by multinational suppliers can capture import-restricted volume in expanding clinker corridors.
- Predictive maintenance convergence:IoT sensor networks and fluid analysis platforms are enabling condition-based lubricant replacement contracts.
- EU carbon border adjustment mechanism:Low-carbon lubricant formulations may qualify for preferential treatment in cement import calculations.
Industry Challenges
- Tribology specialization shortage:Cement plant maintenance teams lack personnel trained in synthetic lubricant compatibility assessment.
- Legacy equipment retrofit complexity:Centralized lubrication system installation in dated kiln bearing housings requires extended shutdown windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lubricants for Cement Industry Market |
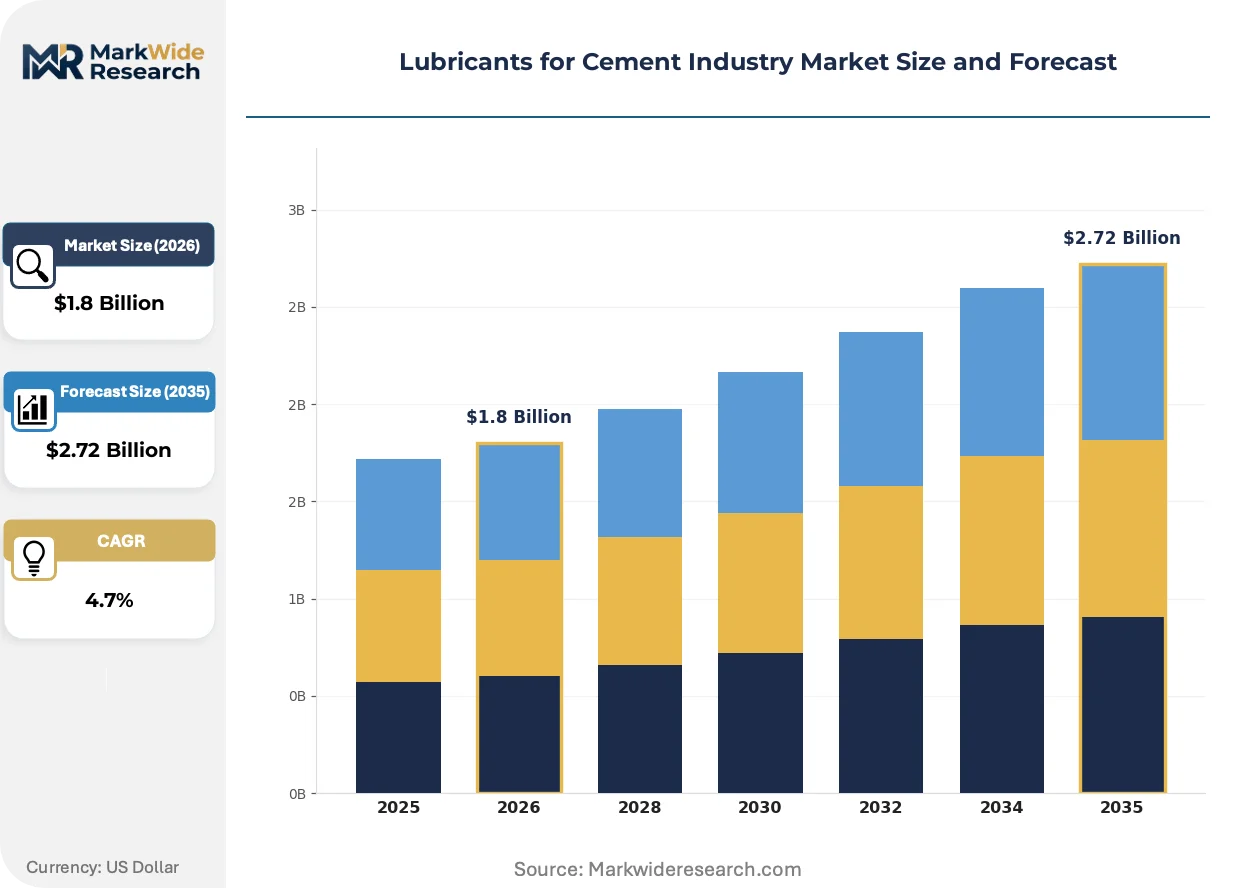
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Motor Oils, Gear Oils, Hydraulic Fluids, Greases Application: Cement Plants, Crushers, Mixers, Conveyors Delivery Mode: Bulk Delivery, Canisters, Drums, Pails End User: Cement Manufacturers, Contractors, Equipment Suppliers, Maintenance Providers |
| Companies Covered | TotalEnergies, ExxonMobil, Sinopec, Kluber Lubrication, Chevron Lubricants, Whitmore, Fuchs, Matrix Specialty Lubricants, Lubrication Engineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lubricants for Cement Industry Market Shifts & Advancements
Synthetic formulation chemistry and predictive service models are converging to redefine how cement manufacturers contract for fluid supply. Technical service bundling is displacing transactional procurement across integrated producers.
Polyglycol-based gear oils are absorbing thermal stress in high-load mill applications that previously required mineral oil top-up every 72 hours. Cement producers operating centralized lubrication systems are adopting these formulations at accelerating rates in India and Germany. The technology is absorbing maintenance labor costs while extending bearing life in continuous-process environments.
EU F-Gas Regulation is phasing down fluorinated greenhouse gas content in specialty lubricant formulations used in cement plant refrigeration and pneumatic systems. Blenders serving European cement corridors are reformulating with hydrofluoroolefin alternatives ahead of 2030 phase-down milestones. High-performance greases for kiln bearing applications face the steepest substitution requirements.
Maintenance-as-a-service contracts are unbundling fluid supply from technical advisory and condition monitoring functions. Integrated cement manufacturers in North America are signing multi-year agreements that embed predictive analytics and on-site engineering support. This model is most visible among producers operating multiple kiln lines where downtime costs exceed fluid expenditures by orders of magnitude.
Lubricants for Cement Industry Market Segmentation
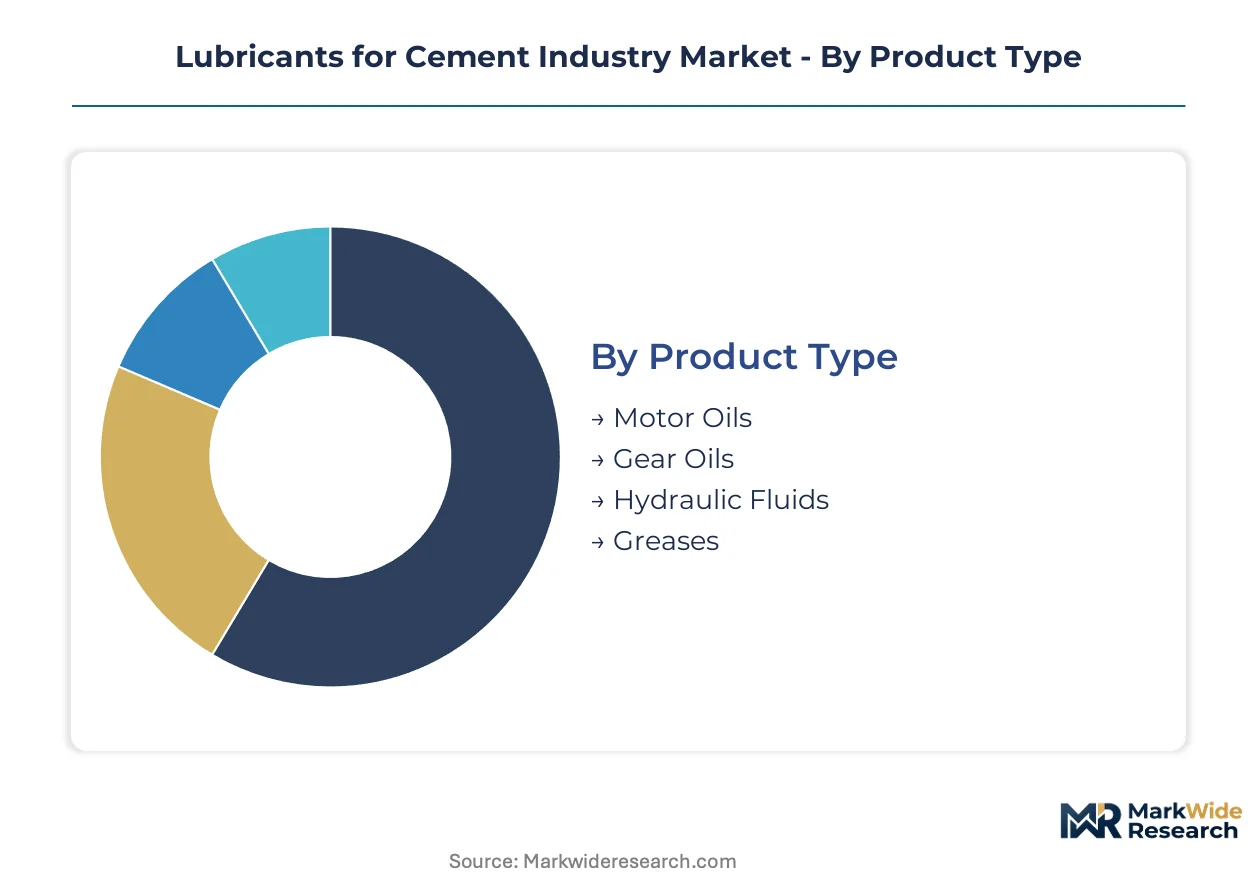
Cement plant operators segment lubricant procurement by equipment criticality and fluid consumption volume. Capital-intensive kilns and grinding mills drive formulation specifications that cascade through supplier qualification and contract structures.
Product Type:
Capital intensity varies sharply across fluid categories, with synthetic formulations requiring dedicated blending infrastructure and technical service networks.
- Hydraulic Fluids:High-viscosity, water-resistant formulations dominate volume demand in open gear systems and roller press circuits. India's integrated cement corridors absorb bulk shipments through captive blending facilities as clinker capacity expands.
- Gear Oils:Synthetic polyglycol formulations withstand thermal stress in high-load mill applications, extending bearing life beyond mineral oil limits. Centralized lubrication retrofits in Germany and India are accelerating replacement cycles for these premium products.
- Motor Oils:Standard mineral formulations serve auxiliary equipment with lower thermal loads and shorter duty cycles.
- Greases:High-temperature specialty grades formulated with complex thickeners protect kiln bearings operating above 150°C.
Hydraulic fluids absorb the bulk of installed capacity; gear oils are expanding most quickly.
Application:
Application segmentation tracks where equipment failure costs exceed fluid expenditures by the widest margin.
- Cement Plants:Rotary kilns and grinding mills command synthetic formulations and predictive maintenance contracts due to unplanned downtime costs. EPA RCRA rules are forcing reclamation system investments that elevate total cost of ownership across US facilities.
- Crushers:Extreme-pressure additives protect bearings under shock loads from limestone and clinker fragmentation. REACH restrictions on certain EP compounds are compelling reformulation investments for EU-based operations.
- Mixers:Water-resistant greases seal against slurry contamination in batch processing environments.
- Conveyors:Centralized lubrication systems reduce manual re-lubrication labor across extended material handling networks.
Cement plants concentrate procurement volume; crushers are gaining share fastest as wear-part intensity rises with harder feedstocks.
Delivery Mode:
Delivery economics favor bulk systems where consumption scale justifies tanker infrastructure and on-site storage.
- Bulk Delivery:Tanker shipments to captive blending facilities eliminate packaging waste and handling costs. Integrated manufacturers in India and Germany operate dedicated receiving infrastructure.
- Drums:Standard 200-liter containers serve mid-scale operations without bulk storage capital.
- Canisters:Small-volume packaging supports maintenance provider spot purchases and trial formulations.
- Pails:Manual handling formats suit remote quarry equipment and contractor mobilization.
Bulk delivery commands the volume base; drums retain flexibility for multi-site operators.
End User:
End-user type determines whether procurement emphasizes technical service bundling or transactional supply.
- Cement Manufacturers:Integrated producers sign multi-year agreements embedding predictive analytics and on-site engineering. ExxonMobil and Fuchs anchor these relationships through technical service networks.
- Maintenance Providers:Independent service contractors prioritize fluid analysis platforms and condition-based replacement contracts.
- Contractors:Project-based demand favors flexible procurement without long-term supply commitments.
- Equipment Suppliers:OEM factory-fill specifications influence initial lubricant selection that often persists through equipment life.
Cement manufacturers drive contract innovation; maintenance providers are expanding fastest as outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cement production concentrates in China and India while consumption patterns diverge across construction-intensive economies. Synthetic lubricant procurement tracks kiln capacity additions and regulatory compliance investments rather than crude output geography. Regional formulation standards and bulk delivery infrastructure shape supplier qualification priorities.
United States
Integrated cement manufacturers operating along the Gulf Coast and Midwest corridors drive bulk hydraulic fluid procurement through captive blending terminals. EPA RCRA hazardous waste enforcement mandates reclamation system investments that elevate total cost of ownership for facilities in Texas and Pennsylvania. The Houston Ship Channel cluster absorbs tanker deliveries serving multiple kiln lines with predictive maintenance contracts.
Germany
Specialty grease demand from high-temperature kiln bearing applications concentrates in the North Rhine-Westphalia cement corridor. EU F-Gas Regulation phase-down timelines compel reformulation of fluorinated lubricant components ahead of 2030 milestones. The Rhine-Ruhr industrial basin anchors centralized lubrication retrofits pulling synthetic polyglycol formulations into faster replacement cycles.
India
Clinker capacity expansion across Rajasthan, Gujarat, and Andhra Pradesh concentrates bulk hydraulic fluid demand in integrated manufacturer blending facilities. BIS certification requirements for imported lubricants create compliance barriers favoring domestic blending investments by multinational suppliers. The Delhi-Mumbai Industrial Corridor absorbs premium synthetic formulations as kiln uptime economics override fluid cost considerations.
China
Cement sector consolidation around state-owned producers concentrates procurement volume in Yangtze River Delta and Pearl River Delta manufacturing clusters. National dual carbon goals pressure kiln efficiency investments that accelerate synthetic lubricant substitution for mineral oil formulations. The Shandong Peninsula cement belt drives gear oil demand from retrofitted grinding mills with centralized lubrication systems.
Saudi Arabia
Greenfield cement capacity in the Eastern Province and Western Region pulls bulk lubricant shipments through Red Sea and Arabian Gulf port infrastructure. Industrial diversification programs under Vision 2030 elevate technical service bundling requirements in supply contracts. The Riyadh construction corridor absorbs high-viscosity formulations for extreme-pressure crusher applications processing limestone feedstocks.
Lubricants for Cement Industry Market Competitive Landscape
Top-tier vendors anchor multi-year predictive maintenance contracts, while mid-tier blenders compete on bulk delivery economics and regional certification compliance. The vendor structure stratifies between integrated petrochemical majors with captive base oil supply and specialty formulators with application engineering depth. Two dominant archetypes emerge: technical service bundlers embedding IoT analytics into supply agreements, and regional blenders capturing import-restricted volume through domestic certification. Competitive moves concentrate on backward integration into base oil refining and strategic partnerships with cement OEMs for factory-fill specifications.
Within the technical service tier, ExxonMobil and Kluber Lubrication exemplify archetypes that monetize cement plant relationships beyond fluid sales through predictive maintenance platforms and application engineering support. Fuchs occupies a position among European specialty formulators leveraging regional regulatory expertise to navigate REACH additive restrictions and F-Gas reformulation mandates. These three entities represent the competitive spectrum from petrochemical-scale supply security to tribology-specialized service depth.
| Leading Market Players |
|---|
| TotalEnergies |
| ExxonMobil |
| Sinopec |
| Kluber Lubrication |
| Chevron Lubricants |
| Whitmore |
| Fuchs |
| Matrix Specialty Lubricants |
| Lubrication Engineers |
| Others |
Supply & Pricing Matrix
Captive blending infrastructure anchors supply position and pricing power for integrated cement manufacturers operating tanker-receiving terminals. Backward integration into base oil refining compresses blender margins while elevating procurement leverage for buyers with dedicated storage capacity.
Pricing Analysis
Cost-down pressure on synthetic formulations accelerates because Group II and III base stock volatility compresses long-term contract margins. Three-tier pricing structure across premium synthetic, standard mineral, and economy-grade hydraulic fluids differentiates by thermal performance certification and volume scale. Price differentiation traces to REACH-mandated reformulation investments that delay EU supplier qualification. Maintenance providers exhibit highest price sensitivity; integrated manufacturers with captive blending prioritize uptime economics over fluid unit cost.
Supply Chain Analysis
Dual-sourcing requirements from multinational cement producers mandate multi-supplier qualification across Group II/III base oil corridors. Supply concentrates in the United States, Saudi Arabia, and South Korea for premium base stock; India and China anchor regional blending capacity. Raw material dependencies rest on viscosity index improvers, anti-wear additive packages, and complex thickeners for high-temperature greases. Single-source vulnerability persists in specialty polyglycol formulations for centralized lubrication retrofits. Distribution runs through tanker-to-terminal bulk delivery for integrated manufacturers, with drum logistics serving mid-scale operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards vertical-integration race dynamics where base oil refining control and captive blending infrastructure determine contract-winning position. Players pursuing downstream technical service bundling capture multi-year predictive maintenance revenue streams.
For Market Incumbents: Cement defensive positioning through backward integration into Group III base oil production and captive additive compounding capacity. Consolidate technical service networks to embed IoT fluid analysis platforms directly into supply agreements. Mineral oil substitution ceilings in extreme thermal kiln applications threaten synthetic-only portfolios; diversify formulation ranges to retain high-temperature bearing contracts. For New Entrants and Emerging Players: Enter via BIS certification-compliant domestic blending in India's Rajasthan-Gujarat clinker corridor where import barriers concentrate demand. Target maintenance provider outsourcing acceleration with condition-based replacement contracts and fluid analysis platforms. White-space exists in predictive service bundling for mid-scale cement producers lacking captive engineering resources. For Investors and Strategic Acquirers: Exit pathways concentrate in technical service bundlers with embedded predictive analytics and multi-year cement plant contracts. Long-term viability favors suppliers with base oil refining integration and regional certification depth across EPA, REACH, and BIS jurisdictions. Watch synthetic polyglycol adoption rates in Indian and German centralized lubrication retrofits as inflection indicator for premium formulation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Refining | Captive Group III supply secures margin control against feedstock volatility. |
| Predictive Maintenance Contract Embedding | ExxonMobil-style technical service bundling locks multi-year cement plant relationships. |
| Domestic Blending Capacity Investment | India BIS certification compliance captures import-restricted volume in expanding clinker corridors. |
| REACH-Compliant Formulation Reformulation | Fuchs leverages regulatory expertise to retain EU cement producer qualification. |
| Centralized Lubrication System Partnership | Synthetic polyglycol gear oil demand accelerates with German and Indian mill retrofits. |
Research Methodology
Trade databases, cement industry association publications, and regulatory filing repositories formed the secondary backbone for demand quantification and competitive mapping. Primary interviews with maintenance directors, plant engineers at integrated cement manufacturers, lubricant procurement leads, and aftermarket service heads validated consumption patterns and contract structures. Bottom-up and top-down triangulation cross-checked volume estimates against clinker capacity additions and fluid intensity benchmarks.
Analytical lens alternated between bottom-up equipment-level consumption modeling and top-down regional production capacity allocation. Segmentation dimensions spanned product type, application criticality, delivery mode scale, and end-user procurement sophistication. CAGRs derived from trend extrapolation of synthetic substitution rates and regulatory compliance investment cycles across the projection horizon. Forecast inputs incorporated kiln uptime economics, centralized lubrication retrofit penetration, and bulk infrastructure development timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt base oil price shocks or accelerated EU F-Gas phase-down timelines. Model outputs reflect assumptions regarding clinker capacity expansion schedules and synthetic formulation cost parity thresholds. A model refresh is warranted upon material change in India's BIS certification enforcement intensity or major cement producer consolidation events.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Europe Grease Market
Lubricants
Russia Lubricants Market
Lubricants
Netherlands Metalworking Fluids Market
Lubricants
Marine Lubricants Market
Lubricants
United States Commercial Vehicles Lubricants Market
Lubricants
Nigeria Lubricants Market
Lubricants
Africa Commercial Vehicles Lubricants Market
Lubricants
Vietnam Automotive Engine Oils Market
Lubricants
Contact Lubricants Market
Lubricants
Poland Commercial Vehicles Lubricants Market
Lubricants
Africa Heavy Equipment Lubricants Market
Lubricants
Japan Automotive Lubricants Market
Lubricants
Lubricity Improvers Market
Lubricants
Cutting Fluid Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
Poland Automotive Lubricants Market