
 Food Grade Lubricant Market | 2026-2036
Food Grade Lubricant Market Size, Share, and Industry Trends Forecast 2026-2036
Food Grade Lubricant Market Intelligence
Direct-to-end-user sales channels, supported by specialized technical teams, are reconfiguring traditional distributor-led models in the food grade lubricant sector. This shift favors suppliers with deep application expertise. Klüber Lubrication leverages its strong brand and specialized portfolio to command a premium. Fuchs Petrolub SE competes on a broad product range and extensive geographic reach, while ExxonMobil Corporation anchors its position through its global supply chain and R&D capabilities in synthetic base oils.
Food grade lubricants are specialized formulations designed for machinery where incidental contact with food products is possible. These lubricants are typically based on white mineral oils or synthetic fluids like polyalphaolefins (PAOs) to ensure non-toxicity. Within product types, synthetic oils represent the fastest-growing category due to superior performance at extreme temperatures. Demand from processing equipment applications, such as mixers and slicers, continues to dominate volume, driven by the need for high-performance and reliable machinery operation.
The market operates under stringent regulatory oversight, with NSF H1 registration being the primary global standard for incidental food contact. Compliance with regulations from bodies like the U.S. FDA and the European Food Safety Authority (EFSA) is non-negotiable for market access. These frameworks dictate acceptable base stocks and additives, directly shaping product development. Consequently, lubricant manufacturers must decide whether to invest in bio-based formulations or focus on optimizing high-performance synthetics to meet future sustainability goals.
Market Dynamics
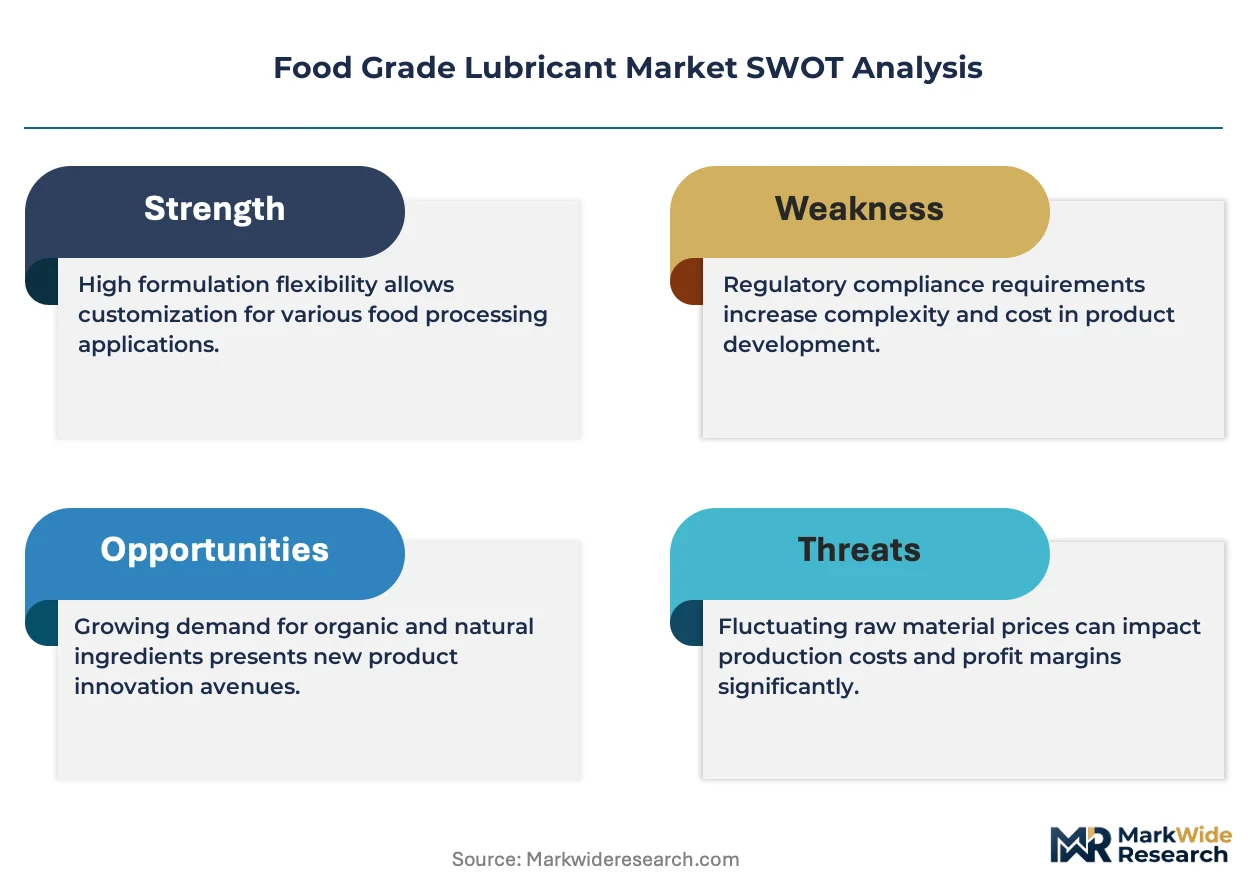
The central force shaping the food grade lubricant market is the non-negotiable pressure from food safety regulations. Mandates from bodies like the U.S. FDA and Europe's EFSA are compelling food processors to abandon conventional lubricants for certified formulations, elevating product compliance over price.
Growth Catalysts
- Stringent Regulatory Frameworks:Intensified food safety legislation from regulators, including the U.S. FDA's Food Safety Modernization Act (FSMA), compels processors to use certified H1 lubricants to mitigate contamination risks and ensure compliance, directly stimulating market conversion.
- Beverage Sector Expansion:Growth in the global beverage industry, particularly in high-speed bottling and canning operations, requires high-performance lubricants that can withstand moisture, sugar contamination, and cleaning cycles while maintaining food-safe certifications.
- Advanced Processing Equipment:Demand concentration in geographies like Germany, with its sophisticated food processing and packaging machinery industry, pulls through demand for specialized lubricants engineered for the specific requirements of advanced mixers, slicers, and conveyors.
Market Restraints
- Higher Formulation Cost:The use of high-purity white mineral oils, synthetic base stocks like polyalphaolefins (PAOs), and specialized non-toxic additives results in a significant price premium over conventional industrial lubricants, creating a cost barrier for smaller operators.
- Performance Trade-offs:Certain food grade lubricant formulations, particularly those based on simpler mineral oils, can exhibit lower thermal stability or oxidative resistance compared to their industrial-grade counterparts, potentially leading to shorter service intervals and increased maintenance.
- Substitution from Machine Design:The trend toward designing food processing machinery with sealed-for-life bearings or lubrication-free components reduces the lifetime consumable lubricant volume required per machine, acting as a long-term structural restraint on volume growth.
Strategic Opportunities
- Bio-Based Formulations:Developing and marketing high-performance bio-based lubricants derived from renewable resources presents a significant opportunity to capture demand from food and beverage companies with aggressive corporate sustainability goals and a preference for non-petroleum inputs.
- Plant-Based Food Processing:The rapid expansion of the plant-based meat and dairy alternative sector creates a new application frontier, with unique processing equipment and conditions that require specialized, allergen-free food grade lubricant solutions.
- Emerging Market Modernization:As food processing industries in regions like Southeast Asia and Latin America modernize and align with global food safety standards, there is a substantial opportunity to penetrate these markets with certified H1 lubricant products and technical expertise.
Industry Challenges
- Global Compliance Complexity:Managing and maintaining a portfolio of product certifications, such as NSF H1 registration, Halal, and Kosher, across numerous global jurisdictions is a complex and costly operational burden for manufacturers.
- End-User Education Gap:A persistent challenge is the need to educate maintenance personnel at food processing plants on the correct selection, application, and handling of food grade lubricants to prevent misapplication or cross-contamination with non-food-grade products.
- Specialized Additive Sourcing:Securing a consistent and reliable supply of approved, non-toxic additives and high-purity base oils presents a supply chain challenge, as the supplier base for these components is more limited than for conventional lubricants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Grade Lubricant Market |
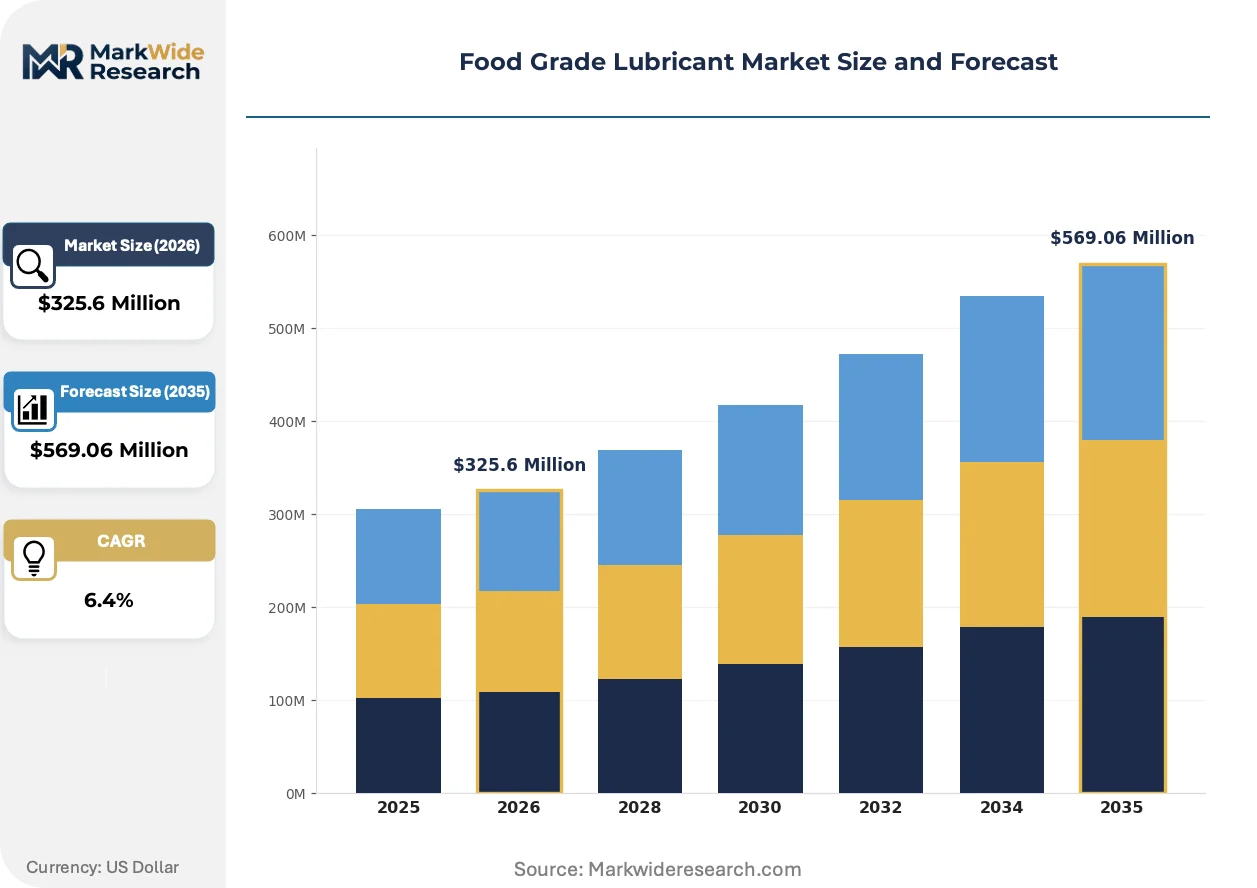
| Market Size in 2026 | $325.6 Million |
| Market Size in 2035 | $569.06 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grease, Oil, Spray, Solid Application: Processing Equipment, Packaging Machinery, Conveyor Systems, Food Handling End User: Food Processing, Beverage Manufacturing, Pharmaceuticals, Specialty Food Compliance Standard: NSF H1, Kosher, Halal, FDA |
| Companies Covered | Klüber Lubrication, Chevron Corporation, Fuchs Petrolub SE, JAX Inc., SKF, ExxonMobil Corporation, Petro-Canada Lubricants, BP Plc (Castrol), TotalEnergies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Grade Lubricant Market Strategic Shifts & Innovations
Product innovation is driven by the dual objectives of enhancing machinery performance under extreme processing conditions and meeting stricter environmental and health standards. This convergence is pushing formulations beyond simple compliance toward advanced synthetic and bio-based solutions that offer tangible operational benefits.
Synthetic Oil Dominance
Synthetic oils, particularly those based on polyalphaolefins (PAOs), represent the fastest-growing product category. Their inherent advantages, including superior thermal stability, wider operating temperature ranges, and extended drain intervals, justify their premium cost for critical applications. Food processors in demanding segments like frozen foods and baking are standardizing on synthetics to improve equipment reliability and reduce unscheduled downtime. This shift is compressing the market for conventional mineral oil-based food grade lubricants in high-performance machinery.
Regulatory Scrutiny on Mineral Oils
Heightened regulatory focus from bodies like the European Food Safety Authority (EFSA) on Mineral Oil Hydrocarbons (MOH) is a significant trend. This scrutiny is compelling lubricant formulators to develop and promote formulations with minimal or zero mineral oil content to preempt future restrictions. The packaged food and confectionery sectors are most sensitive to this issue, accelerating their evaluation of fully synthetic and bio-based lubricants to de-risk their operations from potential MOH contamination concerns.
Direct-to-End-User Channel Shift
A significant demand-side shift involves food processors moving away from generalist industrial distributors and toward direct purchasing relationships with lubricant manufacturers. This change is driven by the need for deep technical expertise in lubricant selection, troubleshooting, and compliance management for specific food processing applications. This direct engagement model is most visible within large, multinational food corporations and in specialized equipment clusters like the packaging machinery sector in Italy.
Food Grade Lubricant Market Segmentation
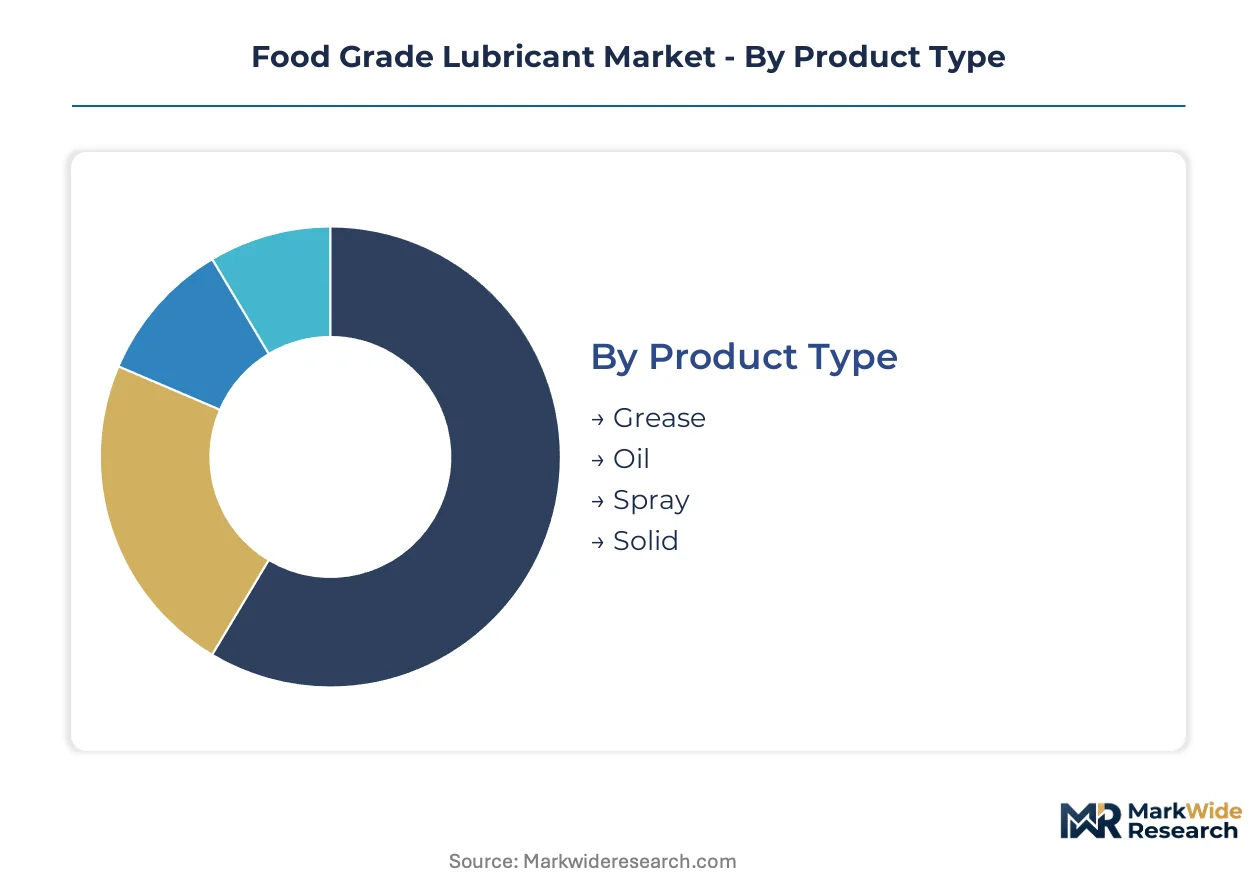
The Food Grade Lubricant Market's segmentation is critical for understanding specific product requirements, application challenges, and compliance pathways. Analyzing these distinct segments reveals how specialized formulations cater to diverse operational demands, influencing product development and market access strategies.
Product Type:
The product type segment reflects the maturity spectrum of lubricant formulations, from established mineral oil-based options to advanced synthetic and bio-based solutions.
- Grease:These semi-solid lubricants, often thickened with metallic soaps, provide excellent adhesion and sealing properties for bearings and gears in food processing equipment. Demand concentrates in high-load, low-speed applications like mixers and ovens in German food plants.
- Oil:Liquid lubricants, frequently based on polyalphaolefins (PAOs) or white mineral oils, offer superior cooling and flow characteristics, essential for hydraulic systems and gearboxes. This segment sees significant demand from high-speed bottling lines in the beverage sector.
- Spray:Aerosol-delivered lubricants provide convenient application for hard-to-reach areas or for thin-film corrosion protection on machinery surfaces. Food processors use these for chains and hinges in packaging equipment.
- Solid:Dry film lubricants, such as PTFE or graphite-based coatings, prevent friction and wear in environments where liquid lubricants are impractical or undesirable. These are often found in low-friction sliding applications.
Grease handles the majority of throughput; Oil is the fastest mover on share.
Application:
Application segments delineate where food grade lubricants are primarily utilized, highlighting the operational criticality and volume demand across the food supply chain.
- Processing Equipment:This segment includes lubricants for machinery directly involved in food transformation, such as mixers, slicers, ovens, and cookers, requiring high thermal stability. Demand dominates in large-scale food production facilities across Europe and North America.
- Packaging Machinery:Lubricants for bottling, canning, sealing, and wrapping equipment operate under high speeds and often wet conditions, necessitating resistance to washdown chemicals and moisture. Beverage manufacturing in regions like Southeast Asia drives significant demand.
- Conveyor Systems:Lubricants for chains, belts, and rollers ensure smooth material flow and prevent wear in both raw ingredient transport and finished product handling. Bakery and confectionery operations require specialized lubricants for these systems.
- Food Handling:This niche involves lubricants for machinery with potential direct contact with food, such as cutting blades or transfer mechanisms, demanding the highest purity and non-toxic formulations. Meat and poultry processing plants utilize these specialized lubricants.
Processing Equipment applications drive significant volume, while Packaging Machinery exhibits substantial growth due to high-speed operations.
End User:
The end-user segmentation reflects the diverse industries that consume food grade lubricants, each with unique operational environments and regulatory compliance needs.
- Food Processing:This broad category encompasses meat, dairy, bakery, and confectionery sectors, requiring a wide range of lubricants for various machinery types and operating conditions. Stringent U.S. FDA and European EFSA regulations compel H1 lubricant use.
- Beverage Manufacturing:High-speed bottling, canning, and brewing operations demand lubricants resistant to water, sugar, and cleaning agents, ensuring continuous production and hygiene. This sector is witnessing rapid expansion in emerging markets like Brazil.
- Pharmaceuticals:The pharmaceutical industry requires ultra-pure lubricants for manufacturing equipment, adhering to Good Manufacturing Practices (GMP) and avoiding cross-contamination. Production facilities in Germany and Switzerland prioritize these formulations.
- Specialty Food:This segment includes niche food producers, often dealing with specific allergens or organic certifications, necessitating lubricants that meet highly specialized and often customized compliance standards. Artisan food producers in Japan often seek these specific solutions.
Food Processing commands the largest share of lubricant consumption, with Beverage Manufacturing demonstrating robust expansion.
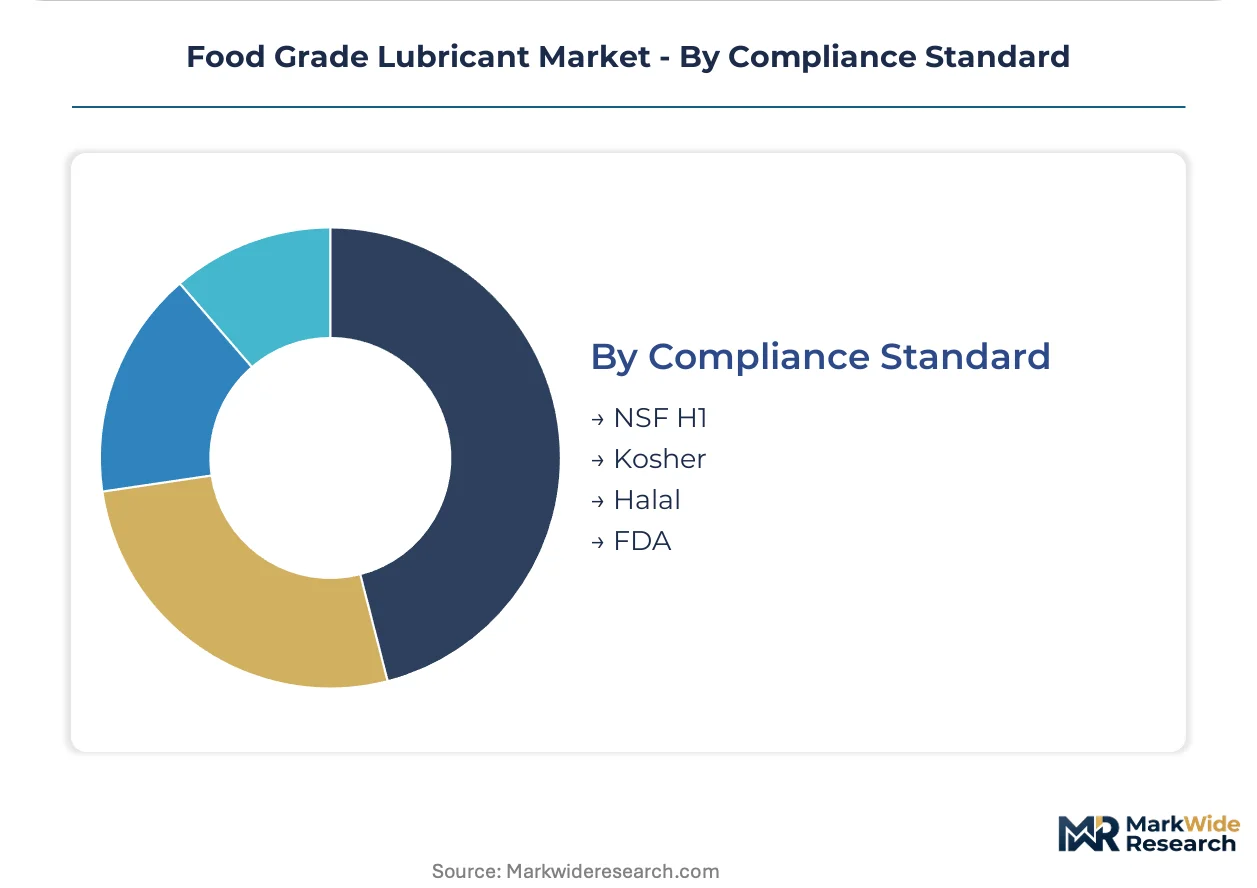
Compliance Standard:
Compliance standards define the regulatory landscape for food grade lubricants, acting as critical gatekeepers for market entry and product acceptance across different geographies.
- NSF H1:This is the primary global standard for lubricants with incidental food contact, certifying that formulations are non-toxic and suitable for use in food processing environments. NSF H1 registration is non-negotiable for market access in most developed economies.
- Kosher:Kosher certification ensures lubricants meet Jewish dietary laws, requiring specific ingredients and manufacturing processes free from non-Kosher substances. Food manufacturers targeting Jewish communities require this certification.
- Halal:Halal certification verifies that lubricants comply with Islamic dietary laws, prohibiting certain ingredients like alcohol or pork-derived components. This standard is increasingly important for market penetration in Muslim-majority countries.
- FDA:The U.S. Food and Drug Administration (FDA) sets specific regulations for food-contact substances, including base oils and additives, ensuring their safety for human consumption. Compliance is mandatory for all lubricants used in U.S. food production.
NSF H1 remains the foundational requirement, as Kosher and Halal certifications expand market reach for specific consumer segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extensive global shipping lanes and interconnected logistics networks underwrite the widespread distribution of food products, driving demand for compliant lubricants in processing facilities worldwide. This infrastructure supports the movement of raw materials and finished goods, necessitating reliable machinery operation across diverse geographies.
Germany
Germany's advanced food processing and packaging equipment industry drives demand for specialized high-performance lubricants. The European Food Safety Authority (EFSA) mandates stringent compliance for lubricants in food contact applications. Munich and Stuttgart house engineering clusters that innovate machinery requiring precise lubrication solutions.
United States
The United States food and beverage sector demands high-volume, certified food grade lubricants for its vast production scale. The U.S. FDA's Food Safety Modernization Act (FSMA) compels processors to use H1 lubricants to prevent contamination. California's central valley food processing hubs utilize these formulations for diverse agricultural outputs.
Brazil
Brazil's expanding beverage manufacturing sector, particularly in high-speed bottling, requires lubricants resistant to moisture and sugar. ANVISA, the national health surveillance agency, enforces food safety standards that include lubricant certification. São Paulo's industrial belt sees significant investment in modern food processing plants.
China
China's rapidly modernizing food processing industry, driven by rising consumer demand, utilizes specialized lubricants for new equipment. GB standards, enforced by SAMR, increasingly align with international food safety requirements for lubricants. The Yangtze River Delta region hosts numerous large-scale food production facilities.
Japan
Japan's focus on high-quality, specialty food production necessitates ultra-pure food grade lubricants for sensitive applications. The Ministry of Health, Labour and Welfare (MHLW) oversees food safety regulations, influencing lubricant specifications. Tokyo's dense urban food processing and packaging centers adopt advanced lubrication technologies.
Food Grade Lubricant Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream providing critical material science. The market structure exhibits a tiered consolidation, with a few global players dominating the premium segment and numerous smaller, regional specialists. Key strategic archetypes include integrated solution providers, niche technology leaders, and broad-portfolio suppliers. Geographic expansion and portfolio diversification represent dominant competitive moves among larger entities.
Within the specialized formulation segment, Klüber Lubrication exemplifies a premium brand focus, leveraging its strong reputation. Fuchs Petrolub SE represents a broad product range and extensive geographic reach across various industrial applications. ExxonMobil Corporation anchors its position as a global energy major, drawing on its R&D capabilities in synthetic base oils and extensive supply chain.
| Leading Market Players |
|---|
| Klüber Lubrication |
| Chevron Corporation |
| Fuchs Petrolub SE |
| JAX Inc. |
| SKF |
| ExxonMobil Corporation |
| Petro-Canada Lubricants |
| BP Plc (Castrol) |
| TotalEnergies |
| Others |
Cost & Logistics Intelligence
Global shipping lanes' cost dynamics influence the food grade lubricant supply chain, driving concentration among key producers and impacting downstream price differentiation for specialized formulations. This market requires a delicate balance between cost efficiency and stringent regulatory compliance.
Pricing Analysis
Volume-discount tiering structures characterize food grade lubricant pricing, reflecting economies of scale for large purchasers. Price differentiation stems from certification levels like NSF H1 and the superior performance of synthetic base oils, commanding a premium over mineral-based alternatives. Pricing softness affects conventional mineral oil-based formulations due to increased regulatory scrutiny and performance trade-offs. Smaller food processors, often with tighter budgets, exhibit higher price sensitivity compared to large multinational corporations prioritizing compliance and reliability.
Supply Chain Analysis
Upstream feedstock sourcing for high-purity white mineral oils and synthetic polyalphaolefins (PAOs) primarily draws from chemical industries in Germany and the United States. Specialized non-toxic additives, critical for food grade formulations, also source from a concentrated base of global suppliers. Supply chain risk centers on the limited supplier base for these specialized additives, creating potential single-source vulnerabilities. Downstream distribution is shifting towards direct-to-end-user channels, with lubricant manufacturers providing specialized technical support to food processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires a strong substitution defense as machinery designs trend towards lubrication-free components, posing a long-term threat to consumable lubricant volumes.
For Market Incumbents:
Build technical expertise and service moats around specialized application knowledge to counter the threat of machine design innovation. Invest heavily in R&D for advanced synthetic and bio-based formulations that offer superior performance and meet evolving sustainability goals. Deepen direct-to-end-user relationships, offering comprehensive technical support and compliance management to large food and beverage corporations. Focus on expanding certification portfolios, including Kosher and Halal, to unlock new geographic markets.
For New Entrants and Emerging Players:
Emerging market modernization in Southeast Asia and Latin America represents a significant underpenetrated opportunity for certified H1 lubricant products. Target the rapidly expanding plant-based food processing sector with specialized, allergen-free lubricant solutions tailored to unique equipment requirements. Leverage agility to develop niche bio-based formulations that align with corporate sustainability mandates from food and beverage companies. Penetrate through direct sales channels, emphasizing technical support and cost-effective compliance solutions.
For Investors and Strategic Acquirers:
Carve-out targets emerge from larger chemical or energy conglomerates seeking to divest non-core lubricant divisions with strong food grade portfolios. The market offers long-term viability driven by non-negotiable food safety regulations and beverage sector expansion over the coming decade. Focus on acquiring niche technology leaders specializing in bio-based or advanced synthetic formulations with robust intellectual property. Increased M&A activity in specialized additive or bio-based feedstock suppliers is a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Synthetics | Secures supply for the fastest-growing product segment, meeting rising performance demands from food processors. |
| Green Manufacturing Transition | Aligns with corporate sustainability goals of food and beverage companies, capturing demand for bio-based inputs. |
| Long-term Supply Agreements | Mitigates supply chain risks for critical high-purity base oils and specialized non-toxic additives. |
| Strategic OEM Partnerships | Integrates lubricant solutions early in equipment design, ensuring optimal performance and compliance for new machinery. |
| Geographic Expansion in Emerging Markets | Captures demand from modernizing food processing industries in regions like Southeast Asia and Latin America. |
Research Approach
Desk research of regulatory body publications, industry association reports, and company financial filings preceded structured interviews with plant managers, procurement leads, R&D directors at lubricant manufacturers, and food safety officers. This approach combined primary insights with secondary validation, ensuring a comprehensive understanding of market dynamics. Bottom-up data aggregation and top-down market sizing provided triangulation for all quantitative estimates.
The analytical framework assumed stable regulatory environments and continued technological advancements in food processing equipment over the projection horizon. Segmentation dimensions modeled included product type, application, end-user, compliance standard, and regional regulatory alignment. Compound annual growth rates were derived from historical trends, competitive landscape analysis, and projected impacts of food safety regulation updates. Key forecast inputs included global food processing equipment sales and beverage production volumes.
Practitioners should monitor shifts in global trade policies, new food safety mandates, or significant technological breakthroughs in lubrication-free designs for early signals of market inflection. Forecasts reflect current assumptions regarding raw material availability and pricing stability. Monthly review of regulatory updates and raw material pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Vietnam Automotive Engine Oils Market
Lubricants
Industrial Gear Oil Market
Lubricants
Open Gear Lubricants Market
Lubricants
Global Fire Resistant Hydraulic Fluid Market
Lubricants
Firearm Lubricants Market
Lubricants
Netherlands Metalworking Fluids Market
Lubricants
Norway Commercial Vehicles Lubricants Market
Lubricants
Offshore Lubricants Market
Lubricants
Hydraulic Oil Additives Market
Lubricants
Kenya Lubricants Market
Lubricants
Lube Skid Market
Lubricants
Philippines Lubricants Market
Lubricants
North America Automotive Lubricants Market
Lubricants
Global Agricultural Lubricants Market
Lubricants
Malaysia Automotive Lubricants Market
Lubricants
United Kingdom Automotive Lubricants Market