
 Germany Lubricants Market | 2026-2036
Germany Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Lubricants Market Foresight
Multi-source procurement among German industrial buyers is broadening as manufacturers seek supply resilience against raw material volatility. Fuchs Petrolub SE anchors its position through captive additive blending capabilities. Liqui Moly GmbH differentiates via aftermarket channel density across German automotive workshops. Shell Deutschland Oil GmbH competes on low-viscosity synthetic portfolios aligned with OEM factory-fill contracts.
Lubricants are formulated mixtures of base oils and functional additives designed to reduce friction, dissipate heat, and prevent wear between moving mechanical surfaces, with synthetic polyalphaolefin bases now dominating OEM specifications requiring SAE 0W-20 and lower grades for fuel economy compliance. Engine oil commands the largest value pool given passenger car parc density and extended drain intervals, while metalworking fluids represent a structurally faster-growing segment as German precision engineering and aerospace suppliers adopt minimum quantity lubrication systems. Hydraulic oil remains a mature, volume-heavy category tied to construction machinery replacement cycles.
The KBA enforces ACEA and API performance standards that OEMs must meet for type approval, while REACH and the EU F-Gas Regulation constrain fluorinated lubricant chemistries and mandate biodegradability disclosures for environmentally sensitive applications. The EU Green Deal's transport decarbonization pathway is redirecting R&D spending toward e-fluids compatible with electric axle thermal management. Stakeholders must monitor how the EU AI Act's predictive maintenance mandates reshape condition-monitoring oil analysis services.
Market Dynamics
The EU Green Deal's transport decarbonization pathway is compressing lubricant specification cycles as German OEMs accelerate synthetic adoption to meet fleet emission targets. KBA enforcement of extended oil drain intervals simultaneously raises performance barriers and reduces per-vehicle consumption volumes.
Growth Catalysts
- EU Green Deal Fleet Targets:German automotive OEMs are expanding factory-fill contracts for low-viscosity synthetics to comply with 2035 combustion phaseout milestones and interim CO2 reduction mandates.
- Precision Engineering Demand:Aerospace and machine tool suppliers in Baden-Württemberg are adopting minimum quantity lubrication systems that require advanced metalworking fluid chemistries.
- KBA Extended Drain Standards:Stricter oil change interval regulations are forcing formulation upgrades toward higher-performance synthetic bases that command premium positioning.
Market Restraints
- Base Oil Supply Concentration:European Group III and polyalphaolefin feedstock production clusters in Rotterdam and Antwerp create import dependency for German blenders.
- REACH Biodegradability Mandates:Disclosure requirements for environmentally sensitive applications constrain fluorinated lubricant chemistries and raise R&D compliance costs.
- Electric Powertrain Displacement:Battery electric vehicle penetration eliminates engine oil demand in passenger car segments where lubricant volumes concentrate.
Strategic Opportunities
- E-Fluid Thermal Management:Electric axle cooling and battery thermal regulation applications represent white space as OEMs redesign lubricant specifications for electrified platforms.
- Condition-Monitoring Services:The EU AI Act's predictive maintenance mandates are creating demand for sensor-integrated oil analysis platforms in industrial maintenance contracts.
- Workshop Channel Density:Aftermarket service networks in Bavaria and North Rhine-Westphalia remain fragmented, offering consolidation potential for technical service programs.
Industry Challenges
- Additive Chemistry Sourcing:Captive blending capabilities require sustained capital allocation as supply resilience priorities clash with margin compression in commodity segments.
- Legacy Equipment Compatibility:New low-viscosity grades face adoption friction in Germany's aging commercial vehicle parc where drain interval skepticism persists among fleet operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Lubricants Market |
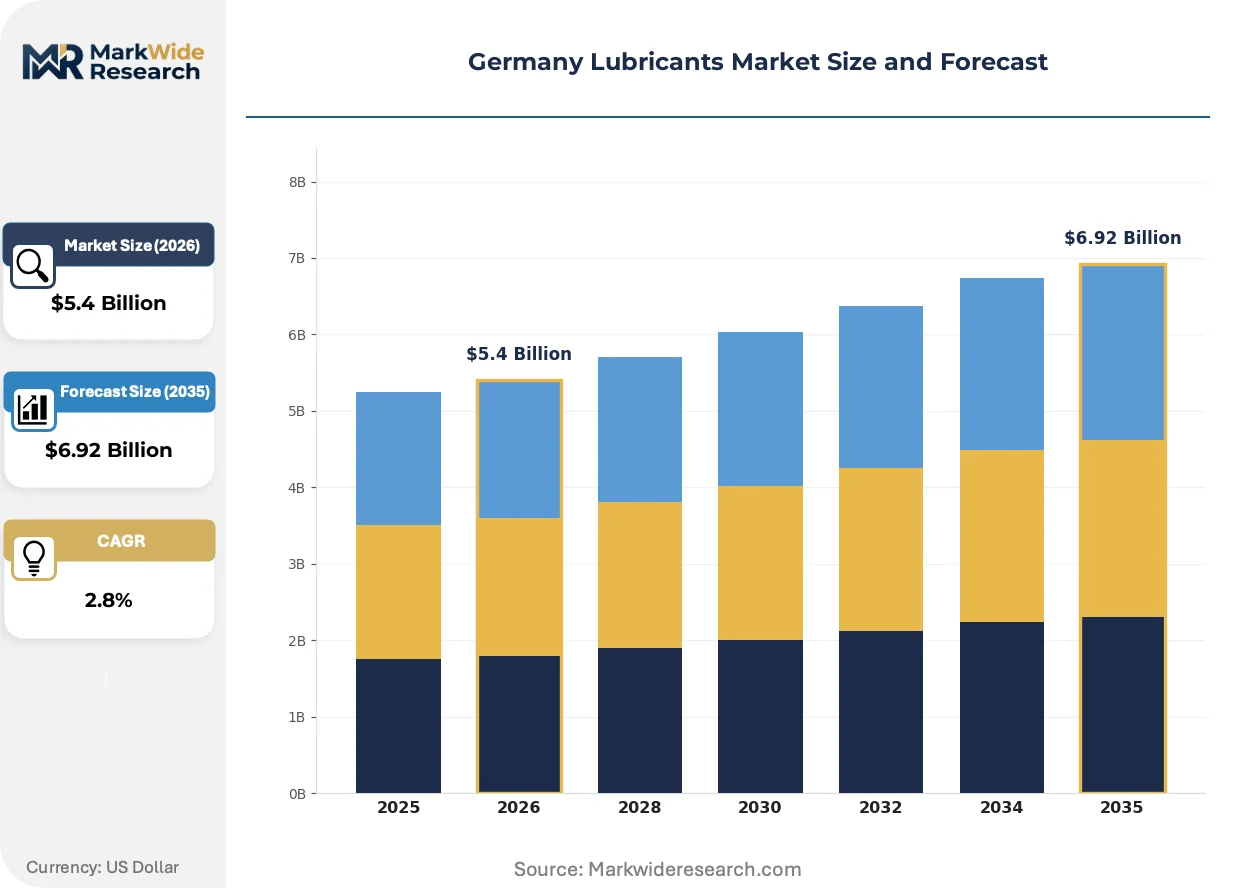
| Market Size in 2026 | $5.4 Billion |
| Market Size in 2035 | $6.92 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Gear Oil, Hydraulic Oil, Metalworking Fluids, Compressor Oil Application: Automotive Engines, Industrial Machinery, Marine Equipment, Metal Processing, Construction Machines End User Industry: Transportation Sector, Manufacturing Sector, Energy Sector, Marine Sector, Mining Operations Distribution Channel: Direct Sales, Distributors, E-commerce Platforms, Automotive Workshops, Industrial Suppliers |
| Companies Covered | TotalEnergies Marketing Deutschland GmbH, Castrol Limited, Shell Deutschland Oil GmbH, Klüber Lubrication München SE & Co. KG, Liqui Moly GmbH, BP Europa SE, ExxonMobil, Chevron Deutschland GmbH, Fuchs Petrolub SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Lubricants Market Shifts & Advancements
Synthetic formulation chemistry is diverging from historical petroleum-based standards as thermal performance requirements intensify across electrified and downsized combustion platforms. Three developments are restructuring competitive positioning.
Polyalphaolefin base stocks are converging with ester co-base technologies to achieve the oxidative stability and low-temperature flow demanded by SAE 0W-8 and 0W-12 specifications. BMW and Mercedes-Benz powertrain engineers are validating these chemistries for factory-fill contracts. The convergence is compressing the viable supplier base to blenders with in-house additive synthesis capabilities.
REACH authorization procedures and the EU F-Gas Regulation are constraining perfluoropolyether formulations in aerospace and semiconductor applications. Industrial buyers must qualify alternative chemistries ahead of sunset dates for legacy substances. Metalworking fluid suppliers serving Bavarian precision engineering clusters are accelerating biodegradable ester substitutions.
Workshop purchasing patterns are fragmenting as independent service operators bypass traditional distributor tiers to source directly from regional blending facilities. Digital procurement platforms are displacing long-term supply agreements in the German aftermarket. This disintermediation concentrates in North Rhine-Westphalia's dense automotive service corridor around Cologne and Düsseldorf.
Germany Lubricants Market Segmentation
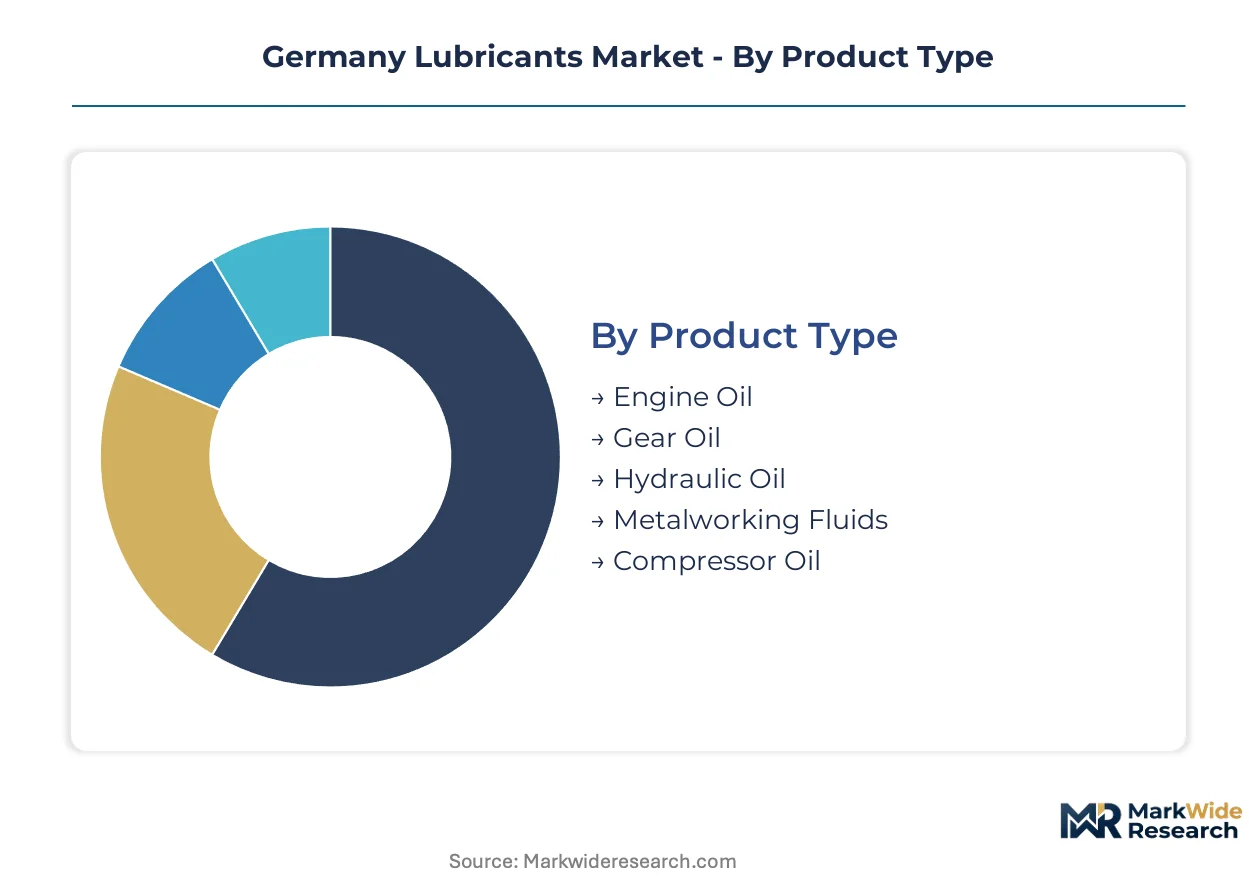
German lubricant procurement patterns diverge sharply across end-use contexts, with OEM factory-fill contracts, industrial maintenance programs, and aftermarket service networks each demanding distinct formulation portfolios and delivery mechanisms. Segment boundaries are blurring as electrification and precision manufacturing reshape fluid specifications.
Product Type:
Upgrade cycles are compressing as KBA-mandated drain intervals and EU emission targets force rapid specification turnover across every product category.
- Engine Oil:Synthetic polyalphaolefin and Group III base stocks now dominate OEM approvals for SAE 0W-20 and lower viscosity grades. Demand concentrates in Baden-Württemberg's automotive corridor where Mercedes-Benz and Porsche powertrain engineers validate factory-fill chemistries against ACEA C5 and C6 sequences.
- Metalworking Fluids:Minimum quantity lubrication systems in Bavarian aerospace and precision engineering clusters require advanced ester-based formulations with enhanced mist control and biodegradability profiles under REACH disclosure mandates.
- Hydraulic Oil:Construction machinery replacement cycles in North Rhine-Westphalia drive volume.
- Gear Oil:Wind turbine gearbox maintenance contracts favor synthetic PAO grades.
- Compressor Oil:Food-grade NSF H1 specifications dominate Bavarian packaging equipment applications.
Engine Oil sits at the top of the volume ranking, with Metalworking Fluids climbing the fastest.
Application:
Cost-tier stratification separates premium synthetic formulations for OEM first-fill from commodity-grade volumes serving legacy equipment parc maintenance.
- Automotive Engines:Passenger car and commercial vehicle powertrains account for the dominant value pool, with synthetic adoption accelerating as KBA enforcement of extended drain intervals raises technical barriers. Stuttgart-based OEM engineering centers specify low-viscosity grades that reduce parasitic losses for CO2 compliance.
- Metal Processing:Aerospace suppliers in Augsburg and machine tool builders in Stuttgart are retrofitting MQL-capable equipment, creating demand for high-pressure delivery-compatible fluid chemistries with extended sump life.
- Industrial Machinery:Predictive maintenance contracts in Ruhr Valley manufacturing plants favor condition-monitoring-compatible hydraulic and circulating oils.
- Marine Equipment:Inland waterway operators on Rhine-Danube corridors face VGP-compliant biodegradable stern tube lubricant mandates.
- Construction Machines:Fleet replacement cycles in Berlin-Brandenburg infrastructure projects drive bulk hydraulic oil procurement.
Automotive Engines commands the largest revenue base, though Metal Processing is expanding most quickly.
End User Industry:
Customer-type fragmentation separates specification-driven OEM technical service agreements from price-sensitive maintenance, repair, and operations procurement.
- Transportation Sector:Automotive OEM factory-fill contracts and commercial fleet maintenance programs represent the highest-margin application, with synthetic penetration deepest among premium passenger car producers. KBA type-approval requirements lock in formulation specifications for multi-year contract durations.
- Manufacturing Sector:Precision engineering clusters in Baden-Württemberg and Bavaria are consolidating supplier relationships around technical service partnerships that integrate fluid management with equipment uptime guarantees.
- Energy Sector:Wind turbine operators in northern coastal states specify synthetic gear oils for 20,000-hour service intervals.
- Marine Sector:Inland shipping cooperatives on Rhine-Main-Danube network prioritize cost-minimized mineral oil volumes.
- Mining Operations:Lignite extraction in Lusatia drives heavy-duty hydraulic fluid demand.
Transportation Sector dominates contract value, with Manufacturing Sector gaining share fastest.
Distribution Channel:
Supply concentration in Rotterdam-Antwerp base oil clusters shapes channel economics, with direct procurement rising among volume buyers seeking to bypass distributor markups.
- Automotive Workshops:Independent service operators across Bavaria and North Rhine-Westphalia are fragmenting purchasing patterns, with digital platforms enabling direct sourcing from regional blending facilities. Workshop density around Cologne and Düsseldorf supports technical service program consolidation opportunities.
- Direct Sales:Industrial accounts in automotive and aerospace manufacturing are negotiating direct supply agreements with captive additive blenders to secure formulation continuity and supply resilience.
- Distributors:Traditional tiered distribution retains relevance for fragmented metalworking and maintenance customers.
- Industrial Suppliers:Technical distributors serve precision engineering MRO demand in Stuttgart region.
- E-commerce Platforms:Small fleet operators and agricultural contractors in rural states favor price-transparent digital procurement.
Automotive Workshops captures the highest transaction volume, with Direct Sales climbing fastest among large accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's automotive manufacturing corridor around Stuttgart anchors German lubricant demand through OEM factory-fill contracts and precision engineering clusters.
Baden-Württemberg
Mercedes-Benz and Porsche powertrain engineering centers in Stuttgart specify low-viscosity synthetic grades for CO2 compliance. KBA type-approval requirements lock formulations into multi-year technical service agreements. Metalworking fluid demand concentrates in Augsburg aerospace supplier parks adopting minimum quantity lubrication systems.
Bavaria
Machine tool builders in Munich and Nuremberg retrofit MQL-capable equipment requiring advanced metalworking chemistries. REACH biodegradability mandates accelerate ester-based formulation substitutions. Food-grade compressor oil specifications dominate packaging equipment corridors around Ingolstadt.
North Rhine-Westphalia
Construction machinery fleets in Cologne and Düsseldorf drive bulk hydraulic oil procurement through infrastructure replacement cycles. Independent automotive workshops fragment purchasing patterns via digital direct-sourcing platforms. Workshop density supports technical service program consolidation opportunities.
Lower Saxony
Volkswagen Group manufacturing in Wolfsburg anchors factory-fill contract volumes for synthetic engine oils. Extended drain interval enforcement by KBA raises technical barriers for local service networks. Wind turbine operators in coastal zones specify synthetic gear oils for 20,000-hour service intervals.
Berlin-Brandenburg
Infrastructure projects around the capital drive heavy-duty hydraulic fluid demand from construction equipment fleets. E-fluids for electric axle thermal management attract R&D investment from electrification startups. The EU AI Act's predictive maintenance mandates reshape condition-monitoring service offerings in industrial maintenance contracts.
Germany Lubricants Market Competitive Landscape
Global majors compete with regional champions across formulation technology and distribution reach, producing a tiered structure where captive additive capabilities separate premium-positioned blenders from commodity processors. Integrated oil companies leverage upstream base oil access against specialized lubricant houses emphasizing technical service partnerships. Three archetypes dominate: global energy majors with captive supply chains, mid-cap European specialists with regional formulation expertise, and independent aftermarket brands with dense workshop networks. Competitive intensity concentrates on M&A-driven additive technology access and direct industrial account procurement bypassing traditional distribution tiers.
Among Germany-based lubricant houses, Fuchs Petrolub SE and Liqui Moly GmbH occupy distinct positioning archetypes. Fuchs Petrolub SE exemplifies the integrated specialist model with in-house additive blending capabilities securing supply resilience for industrial accounts. Liqui Moly GmbH anchors the aftermarket-focused tier through technical service program density across independent automotive workshops. Shell Deutschland Oil GmbH represents the global major archetype competing on low-viscosity synthetic portfolios aligned with OEM factory-fill specifications. These three entities collectively illustrate how formulation control, channel access, and OEM technical relationships define competitive differentiation in the German market.
| Leading Market Players |
|---|
| TotalEnergies Marketing Deutschland GmbH |
| Castrol Limited |
| Shell Deutschland Oil GmbH |
| Klüber Lubrication München SE & Co. KG |
| Liqui Moly GmbH |
| BP Europa SE |
| ExxonMobil |
| Chevron Deutschland GmbH |
| Fuchs Petrolub SE |
| Others |
Supply & Pricing Matrix
Polyalphaolefin base stock convergence with ester co-base technologies is simultaneously elevating formulation costs and compressing the viable supplier base toward blenders with captive additive synthesis capabilities. KBA-mandated drain interval extensions and EU Green Deal emission targets are forcing rapid specification turnover that rewards integrated producers while squeezing commodity processors.
Pricing Analysis
Input-cost pass-through from Rotterdam-Antwerp Group III and PAO feedstock clusters dominates pricing dynamics for German blenders lacking backward integration. Three-tier pricing structure across premium synthetic, mid-tier Group III, and economy mineral grades separates OEM factory-fill contracts from aftermarket volumes. Cost compression in commodity hydraulic segments is intensifying because construction fleet operators prioritize price over performance. Independent automotive workshops in North Rhine-Westphalia exhibit highest price sensitivity, while Mercedes-Benz and Porsche technical service agreements lock in premium positioning.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Stuttgart-based automotive engineering centers, while fragmented workshop networks in Bavaria source through digital procurement platforms. European supply concentrates in Netherlands and Belgium for Group III and polyalphaolefin feedstocks, with German blenders drawing from these clusters. Raw material dependencies rest on ethylene alpha-olefin feedstocks, additive packages from specialty chemical suppliers, and biodegradable ester alternatives. Single-source vulnerability in Rotterdam-Antwerp base oil corridors creates concentration risk. Distribution runs through captive direct sales for industrial accounts, tiered distributors for metalworking customers, and emerging e-commerce for rural fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
German lubricant margins are expanding through synthetic formulation premiums and extended-drain service bundling, even as per-vehicle volumes compress. E-fluids for electric axle thermal management represent a new premium tier with limited competition.
For Market Incumbents: Cement factory-fill relationships with Stuttgart OEM engineering centers through dedicated technical service teams co-located at powertrain development facilities. Deepen backward integration into additive synthesis capabilities to defend against supply disruption from Rotterdam-Antwerp cluster concentration. Lock in multi-year KBA type-approval specifications before competitor qualification cycles complete.
For New Entrants and Emerging Players: Independent precision engineering shops in Augsburg and Nuremberg represent an underserved buyer archetype seeking fluid management partnerships beyond commodity supply. E-fluids for battery thermal regulation offer penetrable white space with limited incumbent R&D focus. Target technical service bundling with MQL system retrofits as the go-to-market angle, leveraging biodegradable ester formulations to satisfy REACH mandates.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional blending facilities without captive additive capabilities but with established workshop channel density. Long-term viability hinges on electrification transition pacing and synthetic formulation control. Acquisition target archetype: mid-cap blenders with Baden-Württemberg industrial account access and biodegradable fluid certifications. Monitor KBA enforcement patterns on extended drain intervals as the inflection indicator for premium synthetic penetration rates.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Synthesis | Secures supply resilience against Rotterdam-Antwerp cluster concentration for industrial accounts. |
| E-Fluid R&D Partnership with OEMs | Positions blenders for electric axle thermal management specifications in Stuttgart engineering centers. |
| Technical Service Program Expansion | Captures fragmented workshop demand in North Rhine-Westphalia through fluid management bundling. |
| Biodegradable Ester Certification Investment | Unlocks REACH-compliant metalworking fluid contracts in Bavarian aerospace supplier parks. |
| Digital Procurement Platform Launch | Disintermediates traditional distributors for independent automotive service operators in Cologne-Düsseldorf corridor. |
Research Methodology
Multiple input streams — primary interviews with lubricant plant managers, OEM procurement leads at Tier 1 suppliers, aftermarket distribution channel partners, and technical R&D directors; secondary validation through KBA type-approval databases, customs and trade data from German Federal Statistical Office, ACEA oil sequence publications, and SEC filings from listed lubricant houses; plus bottom-up volume modeling and top-down market sizing reconciliation — were integrated to construct segment-level demand estimates.
Data-stream reconciliation across the projection horizon employed vehicle parc modeling by propulsion architecture, content-per-vehicle assumptions for synthetic penetration rates, and industrial production indices for metalworking fluid demand. Segmentation dimensions included product viscosity grade, end-use application, OEM versus aftermarket channel, and regional manufacturing cluster. CAGRs were derived from trend extrapolation of KBA enforcement patterns and EU Green Deal target compliance trajectories.
Underlying measurement precision varies by segment; engine oil factory-fill contracts carry tighter precision than fragmented workshop aftermarket volumes. Forecasts reflect assumptions regarding electric vehicle penetration pacing, REACH authorization timelines, and base oil supply cluster stability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Poland Industrial Lubricants Market
Lubricants
Hydro Lubricants Market
Lubricants
Brazil Automotive Lubricants Market
Lubricants
Vietnam Automotive Lubricants Market
Lubricants
US Lubricants Market
Lubricants
Canada Automotive Lubricants Market
Lubricants
Turkey Commercial Vehicles Lubricants Market
Lubricants
France Lubricants Market
Lubricants
Plastic Lubricants Market
Lubricants
Automotive Suspension System Lubricants Market
Lubricants
Synthetic Lubricants Market
Lubricants
Neat Cutting Oil Market
Lubricants
India Commercial Vehicles Lubricants Market
Lubricants
Mexico Lubricants Market
Lubricants
Asia-Pacific Automotive Lubricants Market
Lubricants
Qatar Lubricants Market