
 Heavy Equipment Lubricants Market | 2026-2036
Heavy Equipment Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Heavy Equipment Lubricants Market Foresight
Construction's share of lubricant offtake is repositioning as mining operators extend drain intervals to match longer maintenance windows. Exxon Mobil Corporation leverages synthetic formulations to capture high-load hydraulic applications. Shell plc sustains channel control through direct OEM supply agreements with Caterpillar and Komatsu. Chevron Corporation anchors North American demand via its Delo brand and mining-focused technical service network.
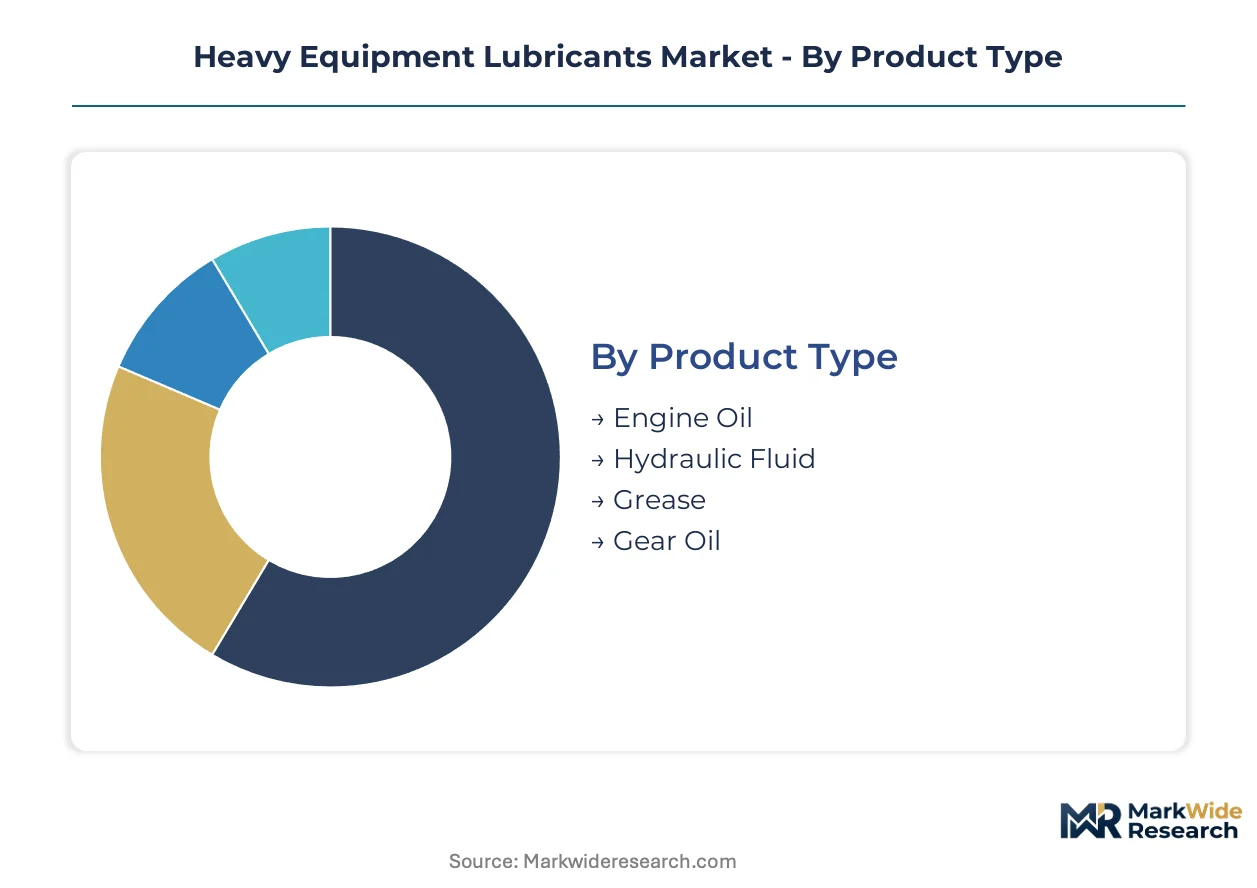
Heavy equipment lubricants are formulated base oil and additive packages engineered to reduce friction, dissipate heat, and prevent wear in engines, hydraulics, transmissions, and open gears operating under extreme load and contamination exposure. Viscosity grades typically span SAE 15W-40 to 10W-30 for engines and ISO VG 32-68 for hydraulics, with total base number (TBN) retention dictating service life in diesel engines burning high-sulfur fuel. Engine oil commands the largest revenue pool due to high volume and premium synthetic conversion, while hydraulic fluid is the fastest-growing product type as electrified implements and precision hydraulics demand thermal stability and shear resistance. Grease occupies a mature, margin-defensive niche in chassis and bearing applications where relubrication access is limited.
EPA and the EU's F-Gas Regulation shape product chemistry through emission-linked equipment design changes that alter lubricant thermal and soot-handling requirements. China's MIIT enforces GB standards on lubricant quality that filter import access and dictate local blending specifications. Formulators must monitor regulatory divergence between EPA Tier 4, EU Stage V, and China's National VI emission tiers to align additive chemistry and base oil selection with diverging hardware requirements.
Market Dynamics
EPA Tier 4 Final and EU Stage V emission rules are forcing formulators to recalibrate additive chemistry for lower-ash, lower-viscosity engine oils that protect exhaust aftertreatment systems without sacrificing wear protection in high-load mining and construction equipment.
Growth Catalysts
- Extended oil-drain intervals:Mining fleet operators in Australia's Pilbara iron ore belt now demand lubricants capable of 500+ hour service life, reducing equipment downtime and maintenance labor costs.
- Electrified hydraulic implements:Precision agriculture and construction machinery require thermal-stable hydraulic fluids with enhanced shear resistance to manage heat loads from variable-frequency electric drives.
- China's western mining expansion:Xinjiang and Inner Mongolia provinces are driving concentrated offtake of high-TBN diesel engine oils formulated for high-sulfur fuel combustion.
Market Restraints
- Group III+ base oil supply concentration:Synthetic feedstock production clusters in South Korea and the US Gulf Coast create geographic vulnerability for premium lubricant formulators.
- Additive package cost volatility:Molybdenum disulfide and zinc dialkyldithiophosphate prices fluctuate with mining commodity cycles, compressing blender margins.
- Ash limit technical ceiling:Sulfated ash levels below 1.0% required by Stage V hardware reduce detergent reserve capacity, shortening oil life in severe-duty cycles.
Strategic Opportunities
- Bio-based hydraulic fluids:USDA BioPreferred program and EU Green Deal procurement mandates create preference pull for ester-based formulations in government-funded infrastructure projects.
- Condition monitoring integration:Mining operators are embedding particle counters and viscosity sensors into lube systems, enabling predictive drain-interval optimization and premium fluid upsell.
- Open gear specialty greases:Wind turbine pitch bearing and mining shovel swing gear applications remain underpenetrated by synthetic-calcium sulfonate formulations with extreme-pressure additive packages.
Industry Challenges
- Field tribology expertise shortage:Mining and construction maintenance teams lack personnel trained in used oil analysis interpretation and root-cause wear diagnosis.
- OEM approval timeline compression:Caterpillar and Komatsu are reducing lubricant qualification cycles from 24 months to 12 months, straining formulator testing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Heavy Equipment Lubricants Market |
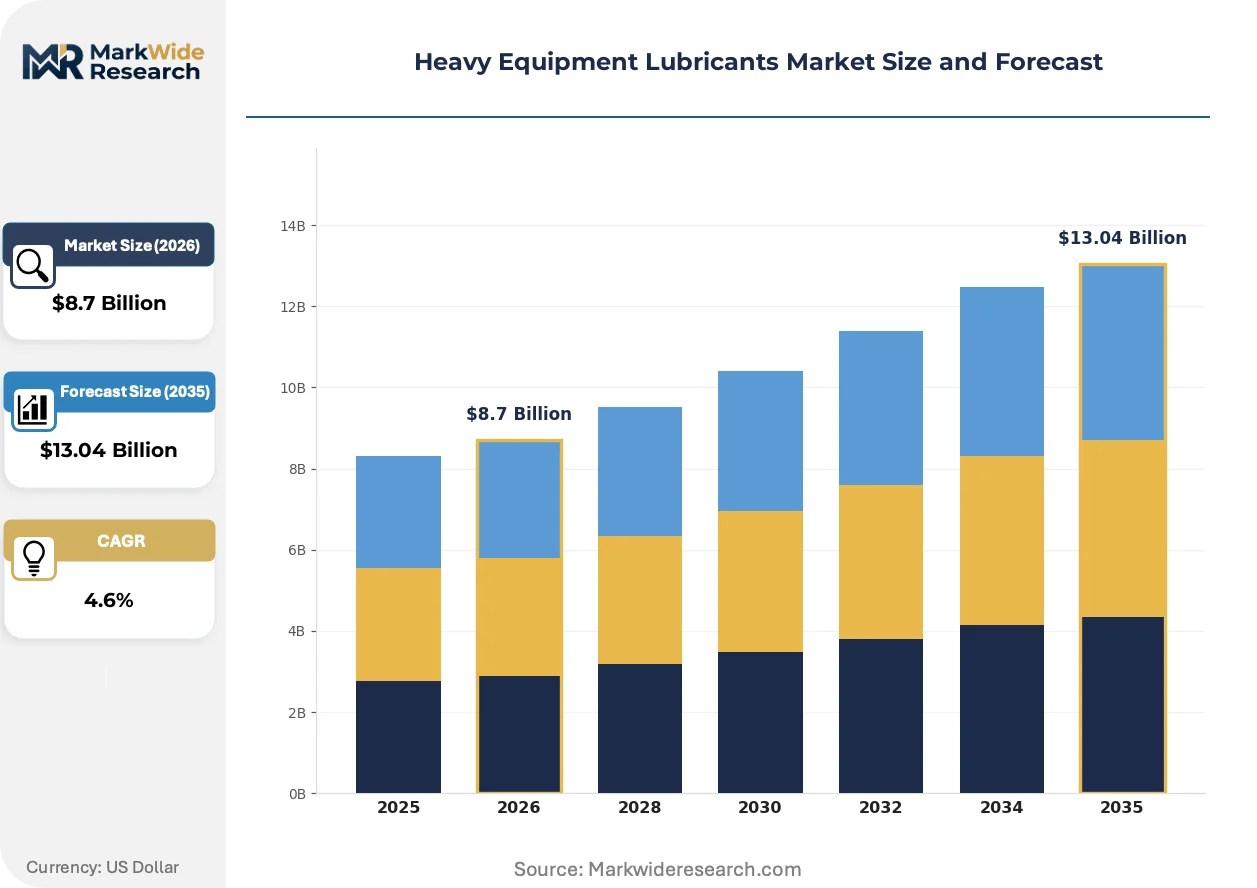
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.04 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Hydraulic Fluid, Grease, Gear Oil End User: Construction, Mining, Agriculture, Forestry Application: Heavy Machinery, Trucks, Earth Movers, Cranes Distribution Channel: Retail Stores, Online, Distributors, OEMs |
| Companies Covered | BP p.l.c., China Petroleum & Chemical Corporation, Exxon Mobil Corporation, Fuchs Petrolub SE, Valvoline Inc., Shell plc, TotalEnergies SE, Petroliam Nasional Berhad, Chevron Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Heavy Equipment Lubricants Market Shifts & Advancements
Synthetic base oil technology is displacing mineral formulations across high-value hydraulic and engine applications, while regulatory emission tiers and predictive maintenance systems are rewiring how lubricant value is measured and purchased.
Polyalkylene glycol synthetic hydraulic fluids are integrating into electrified construction equipment where thermal management demands exceed petroleum-based ISO VG 68 capabilities. Komatsu and Volvo CE are specifying these fluids for their hybrid excavator lines. This integration is compressing the addressable market for conventional anti-wear hydraulic oils in premium equipment segments.
REACH SVHC candidate list expansion is restricting chlorinated paraffin extreme-pressure additives in metalworking and open gear lubricants used in European mining operations. Formulators are substituting sulfur-phosphorus chemistry at 15-20% cost premiums. The restriction is accelerating most visibly in Germany's lignite mining sector, where KBA equipment certification now requires full formulation disclosure.
Fleet operators are consolidating lubricant procurement through integrated supplier contracts that bundle fluid supply with used oil analysis and filtration services. Direct OEM channel agreements with Shell and ExxonMobil are displacing independent distributor relationships in North American mining. This consolidation is most advanced in Wyoming's Powder River Basin coal operations, where three operators now account for 60% of regional offtake.
Heavy Equipment Lubricants Market Segmentation
Equipment operators select lubricants based on duty severity, drain interval targets, and OEM warranty requirements. Segmentation reveals where formulation premiums command pricing power versus where commodity blending suffices.
Product Type:
Purchase decisions pivot on thermal load tolerance and service life guarantees.
- Engine Oil:Formulated with detergent-dispersant packages and TBN reserves to neutralize acids from high-sulfur diesel combustion. Mining fleets in Australia's Pilbara iron ore belt specify 500-hour drain intervals, forcing additive chemistry toward premium synthetics. Volume sits with engine oil; growth tilts toward hydraulic fluid.
- Hydraulic Fluid:Polyalkylene glycol and synthetic ester bases manage heat rejection from electrified implements. Komatsu hybrid excavators specify these fluids for variable-frequency drive compatibility. Precision agriculture in the US Midwest drives fastest share gains as tractor hydraulics integrate electronic load sensing.
- Grease:Calcium sulfonate and lithium complex thickeners with extreme-pressure additives for chassis and open gear bearings. Mature demand concentrated in mining shovel swing gears where relubrication access is limited.
- Gear Oil:Sulfur-phosphorus EP formulations for transmission and final drive protection. Construction transmission rebuild cycles dictate replacement demand in North American equipment parc.
Margin pools diverge sharply: synthetics in hydraulics and engines versus commodity pricing in greases.
End User:
Operating environment severity determines formulation specification tier.
- Mining:24-hour continuous duty with high contamination exposure demands extended-drain synthetics. Xinjiang coal operations in China's western provinces concentrate offtake for high-TBN diesel oils. Volume concentrates in mining; agriculture shows steepest expansion trajectory.
- Construction:Cyclical utilization patterns favor standard drain intervals with occasional synthetic upgrade for extreme climate zones. US infrastructure project restarts are reactivating dormant equipment fleets.
- Agriculture:Seasonal intensity with precision hydraulics requiring shear-stable ISO VG 46 fluids. Brazilian soybean mechanization and Ukrainian grain sector recovery are accelerating specification upgrades.
- Forestry:Bio-based hydraulic fluid mandates in EU government procurement preference chains. Nordic equipment operators face REACH SVHC restrictions on conventional EP additives.
Equipment utilization rates separate price-sensitive construction from premium-specification mining.
Application:
Hardware architecture dictates fluid compatibility requirements.
- Heavy Machinery:Integrated powertrain systems requiring matched engine-hydraulic-transmission fluid families. Caterpillar and Komatsu factory fill agreements dominate procurement channels.
- Trucks:On-highway and vocational classifications with EPA Tier 4 Final aftertreatment sensitivity to sulfated ash levels. Long-haul fleets in Wyoming's Powder River Basin consolidate through direct OEM supply contracts.
- Earth Movers:Severe-duty cycles with high soot loading. Australia's iron ore surface mining operations specify the most demanding TBN retention targets.
- Cranes:Precision hydraulic positioning with anti-wear requirements for variable load conditions. Wind turbine installation vessels in the North Sea drive specialty marine-grade specifications.
Earth movers absorb the highest per-unit fluid volumes; cranes command the steepest formulation premiums.
Distribution Channel:
Procurement consolidation is rewiring channel economics.
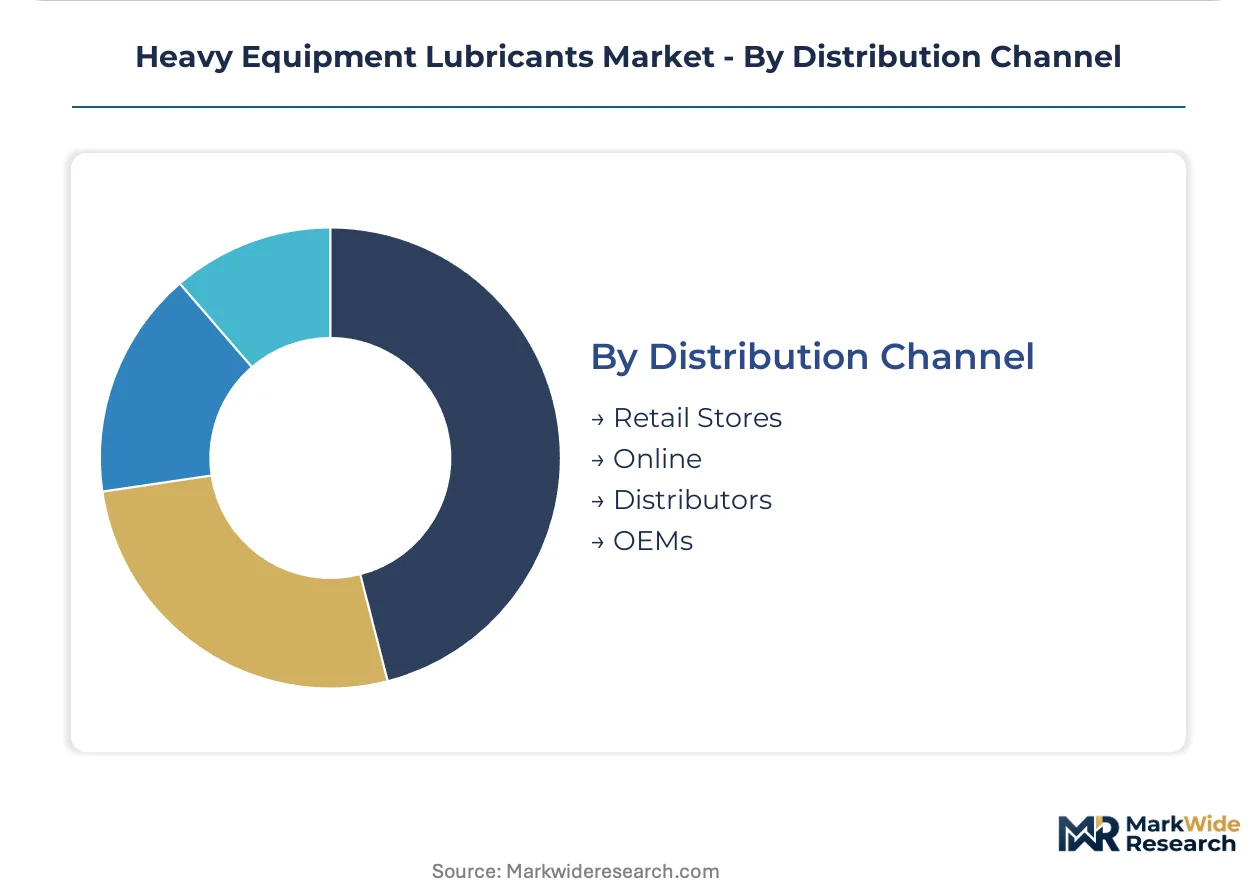
- OEMs:Factory fill and service-in-life agreements with captive fluid branding. Shell's direct supply contracts with Caterpillar and Komatsu lock in specification control.
- Distributors:Independent blending and private label access for mid-tier fleet operators. Channel share is compressing as integrated supply contracts bundle fluids with analysis services.
- Retail Stores:Aftermarket replacement for owner-operators and small contractors. Limited to standard viscosity grades without OEM approval premiums.
- Online:Emerging channel for bulk hydraulic fluid orders with specification transparency. Mining procurement platforms in Western Australia pilot direct-to-site delivery.
OEM direct channels capture specification premiums; online gains traction in commodity hydraulic replenishment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pilbara's iron ore tax concessions concentrate mining fleet investment. Xinjiang's resource zones draw state-directed capital. Western Australia's special economic zones anchor Asia-Pacific lubricant demand.
United States
Wyoming's Powder River Basin coal operators consolidate procurement through direct OEM supply contracts. EPA Tier 4 Final rules mandate sulfated ash limits below 1.0% for exhaust aftertreatment compatibility. Texas Permian Basin equipment yards specify extended-drain synthetics for 24-hour fracturing operations.
Australia
Pilbara iron ore surface mining drives 500-hour drain interval specifications. The country's national resources regulator enforces mine safety standards that lubricant performance must satisfy. Western Australia's Karratha-Geraldton corridor concentrates fleet maintenance infrastructure.
China
Xinjiang and Inner Mongolia coal expansion demands high-TBN diesel oils for high-sulfur fuel combustion. MIIT's GB standards filter import access and dictate local blending specifications. Shanxi Province's coal machinery clusters absorb premium hydraulic fluid volumes.
Germany
KBA equipment certification now requires full formulation disclosure for mining lubricants. REACH SVHC restrictions accelerate substitution of chlorinated paraffin extreme-pressure additives. The country's lignite mining sector in Rhineland tests sulfur-phosphorus chemistry at 15-20% cost premiums.
Brazil
Soybean mechanization in Mato Grosso accelerates specification upgrades for shear-stable ISO VG 46 fluids. ANVISA's chemical substance regulations influence additive import compliance. São Paulo state's construction equipment parc reactivates with infrastructure project restarts.
Heavy Equipment Lubricants Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with factory fill agreements locking in specification control at the premium tier while independent blenders serve mid-tier fleet operators through distributor channels. The vendor base organizes around three strategic archetypes: integrated oil majors with captive base oil supply, regional formulators with OEM approval specialization, and niche synthetics producers targeting electrified equipment thermal management. Competitive moves concentrate on backward integration into Group III+ base oil production and predictive service bundling that embeds fluid supply with condition monitoring.
Among integrated oil majors, Exxon Mobil Corporation, Shell plc, and Chevron Corporation exemplify the factory fill archetype through direct supply relationships with heavy equipment OEMs. These entities anchor premium positioning via synthetic formulation capabilities and technical service networks. Regional specialists including Fuchs Petrolub SE occupy positions between global scale and application-specific expertise. The competitive terrain rewards those controlling additive chemistry development and OEM qualification timelines compressed to twelve-month cycles.
| Leading Market Players |
|---|
| BP p.l.c. |
| China Petroleum & Chemical Corporation |
| Exxon Mobil Corporation |
| Fuchs Petrolub SE |
| Valvoline Inc. |
| Shell plc |
| TotalEnergies SE |
| Petroliam Nasional Berhad |
| Chevron Corporation |
| Others |
Supply & Pricing Matrix
OEM factory fill agreements with Caterpillar and Komatsu anchor premium pricing tiers, while independent distributors compete on spot availability for mid-tier mining fleets. This buyer concentration forces formulators to absorb additive cost volatility or surrender specification control.
Pricing Analysis
Short lead time premiums of 12-15% apply to synthetic hydraulic fluids for electrified equipment where OEM qualification delays constrain supply. Three-tier pricing structure across premium synthetic, semi-synthetic, and mineral base stocks separates factory fill contracts from aftermarket replenishment. Cost compression in Group III+ feedstocks is intensifying because South Korean and US Gulf Coast supply concentration limits blender bargaining power. Small construction contractors exhibit highest price sensitivity, while Pilbara mining operators prioritize drain interval guarantees over unit cost.
Supply Chain Analysis
Used oil collection and re-refining circuits are expanding as Wyoming coal operators and Western Australian iron ore fleets close fluid loops for sustainability compliance. Base oil production clusters in South Korea, the United States, and Singapore, with additive packages drawing from molybdenum disulfide and zinc dialkyldithiophosphate suppliers tethered to mining commodity cycles. Single-source vulnerability in polyalkylene glycol synthetic feedstocks threatens thermal fluid availability for hybrid excavator lines. Distribution runs through OEM captive channels for premium tiers and independent distributors for standard formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over Group III+ base oil supply and additive chemistry development determines margin capture. Players are pursuing upstream feedstock security as the decisive lever.
For Market Incumbents: Lock in factory fill agreements with Komatsu and Volvo CE by compressing qualification cycles below twelve months. Secure backward integration into synthetic ester production to defend margin position against feedstock cost spikes. Channel control through direct OEM contracts remains the priority defensive lever against independent distributor encroachment. For New Entrants and Emerging Players: Bio-based hydraulic fluid formulations certified under USDA BioPreferred offer a technology-first wedge into government-funded infrastructure procurement chains. Target EU forestry equipment operators facing REACH SVHC additive restrictions as the most penetrable white-space segment. Partner with used oil analysis platforms to bundle fluid supply with predictive maintenance services. For Investors and Strategic Acquirers: The window for entry favors regional formulators with OEM approval specialization and captive base oil supply. Long-term viability hinges on synthetic conversion capabilities and electrified equipment thermal management expertise. Monitor EPA Tier 5 and EU Stage VI emission rule developments as the critical inflection signal for additive chemistry investment cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III+ Base Oil | Captive synthetic feedstock supply insulates ExxonMobil and Shell from South Korean refinery concentration risk. |
| Condition Monitoring Service Bundling | Predictive drain interval optimization embeds Chevron's Delo brand into Wyoming Powder River Basin maintenance workflows. |
| Bio-based Hydraulic Fluid Certification | USDA BioPreferred and EU Green Deal procurement mandates create preference pull for Fuchs Petrolub ester formulations. |
| OEM Qualification Timeline Compression | Twelve-month testing cycles strain regional formulator capacity and favor integrated oil majors with dedicated R&D facilities. |
| Open Gear Specialty Grease Development | Calcium sulfonate formulations for mining shovel swing gears address underpenetrated extreme-pressure applications in Australia's Pilbara. |
Research Methodology
Document review covered trade customs data, SEC filings from lubricant manufacturers, and EPA emission compliance records, complemented by interviews with maintenance directors at Pilbara iron ore operations, procurement leads at Caterpillar and Komatsu, and technical service heads at regional distributors. Primary fieldwork included discussions with plant engineers at Xinjiang coal operations and aftermarket service managers in Wyoming's Powder River Basin. Bottom-up triangulation across product type volumes and top-down validation against regional mining fleet data anchored the analysis.
Segment-level projections across engine oil, hydraulic fluid, grease, and gear oil categories were generated over the projection horizon, with end-user splits for mining, construction, agriculture, and forestry applications. CAGRs were derived from equipment parc growth, drain interval extension trends, and synthetic conversion rates. Key inputs included EPA Tier 4 Final and EU Stage V emission hardware requirements, China's MIIT GB standard enforcement patterns, and electrified hydraulic implement penetration in precision agriculture.
Several conditions sit outside the modeled scope, including abrupt base oil supply disruptions from geopolitical events, rapid battery-electric equipment adoption eliminating hydraulic fluid demand, and regulatory divergence beyond Tier 4/Stage V/National VI alignment. Forecasts reflect assumptions about additive chemistry development timelines and OEM qualification cycle stability. Practitioners should monitor EPA Tier 5 rulemaking progress and EU F-Gas Regulation expansion for early signals of formulation requirement shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Germany Lubricants Market
Lubricants
Global Refrigeration Lubricants Market
Lubricants
Canada Lubricants Market
Lubricants
Slideway Oil Market
Lubricants
Thailand Automotive Engine Oils Market
Lubricants
Synthetic Lubricants Market
Lubricants
Mexico Commercial Vehicles Lubricants Market
Lubricants
Gun Lubricant Market
Lubricants
United States Automotive Lubricants Market
Lubricants
EDM Oils/Fluids Market
Lubricants
Polyurea Greases Market
Lubricants
Italy Commercial Vehicles Lubricants Market
Lubricants
Non-Flammable Hydraulic Fluids Market
Lubricants
Graphite Lubricant Market
Lubricants
Colombia Lubricants Market
Lubricants
Mexico Lubricants Market