
 Norway Commercial Vehicles Lubricants Market | 2026-2036
Norway Commercial Vehicles Lubricants Market Size, Share, and Industry Trends Forecast 2026-2036
Norway Commercial Vehicles Lubricants Market Analytics
Fleet operator consolidation in Norway's logistics sector is expanding the buying power of large transport groups. Royal Dutch Shell Plc leverages its integrated fuel-and-lubricant retail network to secure multi-year supply contracts with national haulage companies. FUCHS anchors its position through specialized heavy-duty formulations calibrated for Arctic operating temperatures. ExxonMobil Corporation differentiates via advanced synthetic engine oils that extend drain intervals for high-utilization commercial fleets.
Norway commercial vehicles lubricants are formulated blends of base oils and additive packages engineered to reduce friction, dissipate heat, and protect powertrain components under sustained load cycles, with key specifications including SAE viscosity grades, ACEA performance categories, and TBN retention thresholds for extended drain intervals. Engine oil dominates product type value contribution due to higher per-unit pricing and frequent replacement cycles in heavy-duty applications. Hydraulic fluid competes for fastest-growing product type status as electrified commercial vehicles introduce new thermal management demands. Fleet operators command the largest end user share, while OEMs represent a concentrated but strategically vital channel for factory-fill specifications and warranty-aligned service programs.
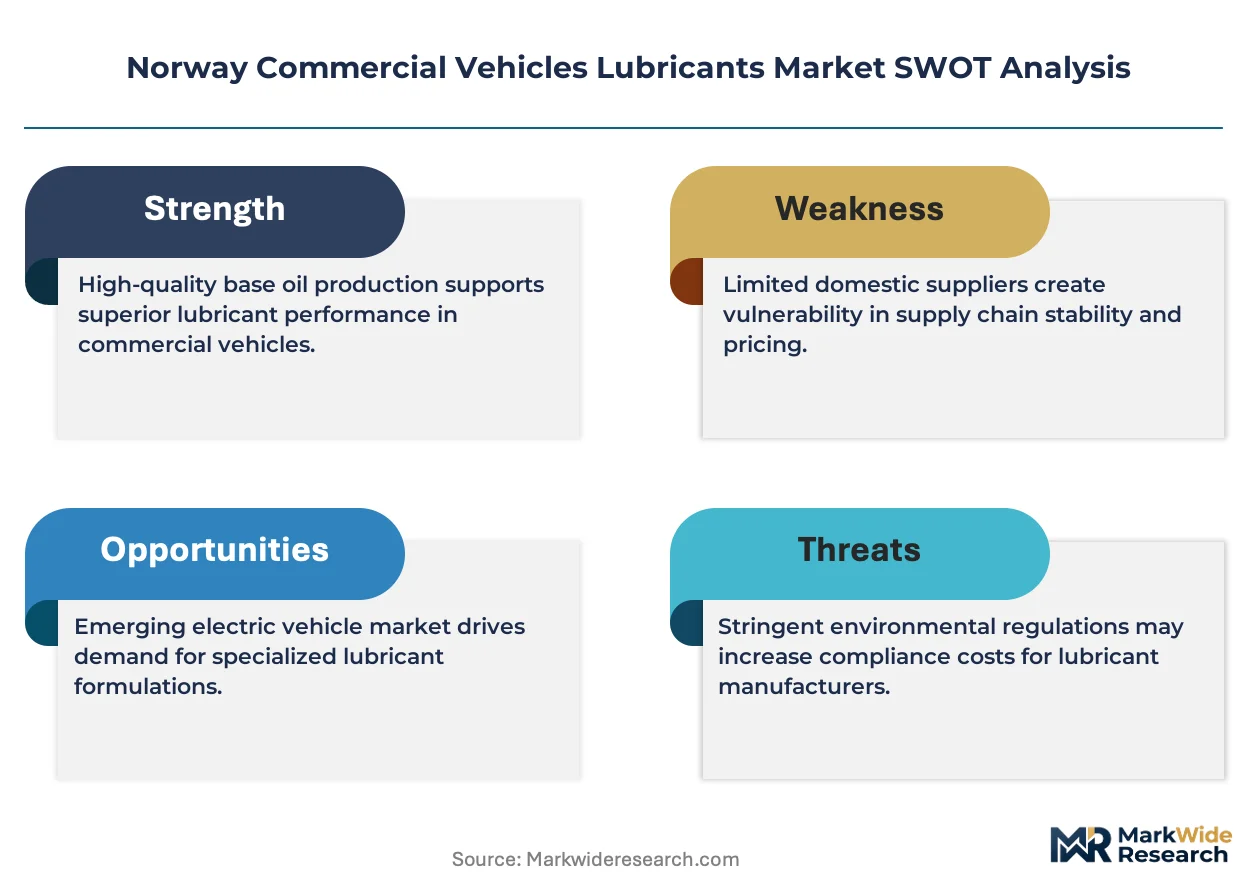
The Norwegian Environment Agency enforces REACH compliance and national CO2 reduction pathways that constrain conventional mineral oil formulations, while the EU F-Gas Regulation and impending Euro VII standards pressure lubricant producers to demonstrate lifecycle emissions compatibility. Norway's adoption of EU MDR-aligned sustainability reporting through the CSRD framework will require supply chain disclosure from lubricant manufacturers serving public procurement contracts. Stakeholders must monitor regulatory timing on low-carbon fuel standards and electrification infrastructure subsidies, as these policy levers will determine whether synthetic lubricant premiumization or reduced fluid volumes from electric drivetrains becomes the dominant market force.
Market Dynamics
Fleet electrification across Norway's commercial transport sector is fragmenting lubricant demand between legacy internal combustion engine volumes and emerging thermal management fluid categories for battery-electric and hybrid platforms.
Growth Catalysts
- EU Green Deal transport decarbonization targets:Norway's alignment with these binding emission reduction pathways is mandating extended drain intervals and higher-performance lubricant specifications for commercial fleets operating under CO2 compliance pressure.
- Arctic operating conditions:Cold-weather heavy-duty transport corridors through Troms and Finnmark require specialized low-temperature viscosity formulations that command formulation premiums and repeat purchase cycles.
- Electrified commercial vehicle thermal management:Battery-electric trucks and vans in the Oslo-Akershus logistics corridor are creating parallel demand for dielectric coolants and advanced hydraulic fluids distinct from conventional engine oils.
Market Restraints
- REACH compliance costs:The Norwegian Environment Agency's enforcement of ECHA-mandated substance restrictions is elevating R&D expenditure for reformulating additive packages away from legacy chemistries.
- Base oil supply concentration:European Group II and Group III base stock production clusters in Rotterdam and Antwerp expose Norwegian blenders to cross-border logistics bottlenecks and currency-adjusted input volatility.
- Electric drivetrain fluid volume compression:Battery-electric commercial platforms eliminate engine oil consumption entirely, threatening the largest product category's addressable market as fleet electrification accelerates through 2030.
Strategic Opportunities
- Norwegian public procurement CSRD disclosure mandates:Sustainability reporting requirements for state logistics contracts create preferential positioning for lubricant suppliers with verified lifecycle emissions documentation and circular economy service models.
- Factory-fill OEM partnerships:Warranty-aligned service programs with Scandinavian commercial vehicle manufacturers offer captive aftermarket demand through dealer network lock-in for specified fluid brands.
- Hybrid powertrain complexity:Dual-system lubrication requirements in plug-in hybrid trucks combine internal combustion engine oil with electric motor cooling fluids, expanding per-vehicle fluid revenue versus pure ICE platforms.
Industry Challenges
- Formulation chemist talent scarcity:Norway's specialized lubricant R&D workforce concentrates around Stavanger's offshore oil sector, creating recruitment friction for automotive fluid development teams.
- Euro VII pre-certification timeline compression:Anticipated emission standards are forcing premature reformulation cycles before regulatory text finalization, straining product development pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Norway Commercial Vehicles Lubricants Market |
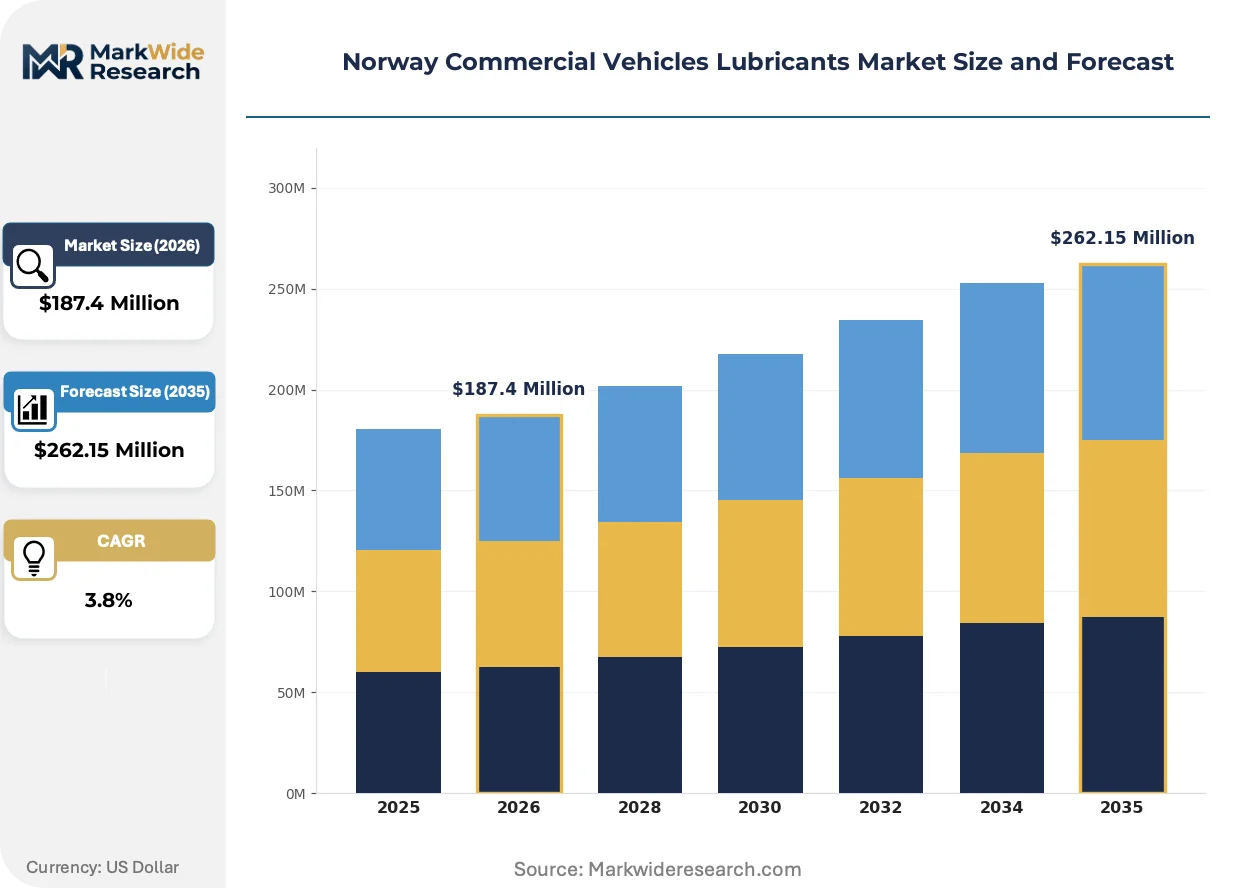
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $262.15 Million |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Oil, Transmission Fluid, Grease, Hydraulic Fluid End User: Fleet Operators, Logistics Providers, Maintenance Services, OEMs Distribution Channel: Retail, Direct Sales, Online, Wholesalers Application: Heavy-Duty Trucks, Buses, Light Commercial Vehicles, Agricultural Vehicles |
| Companies Covered | BP PLC (Castrol), ExxonMobil Corporation, FUCHS, Royal Dutch Shell Plc, TotalEnergies, Chevron Corporation, Champion Lubricants, Gulf Oil International, Motul, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Norway Commercial Vehicles Lubricants Market Evolving Landscape
Synthetic base oil technology and additive chemistry are converging to extend service intervals while electrification is spawning entirely new fluid categories for thermal management and power electronics cooling in commercial vehicle platforms.
Synthetic polyalphaolefin (PAO) and ester base stocks are displacing Group I mineral oils in heavy-duty engine formulations. Fleet operators running high-utilization long-haul routes between Bergen and Oslo are specifying these advanced chemistries to achieve 100,000-kilometer drain intervals. This transition is decentralizing maintenance scheduling authority from independent workshops toward fleet-controlled predictive service programs based on oil condition monitoring rather than fixed mileage triggers.
REACH authorization procedures and the EU F-Gas Regulation are constraining conventional additive chemistries including certain viscosity modifiers and anti-wear compounds. Norwegian blenders are reformulating with bio-based alternatives and ashless detergents to maintain performance credentials. The impact concentrates most acutely on hydraulic fluid specifications for municipal and construction vehicle fleets where biodegradability mandates intersect with cold-start performance requirements.
Consolidated national haulage groups are unbundling lubricant procurement from bundled maintenance contracts. Large transport operators in the Gardermoen logistics cluster are negotiating direct supply agreements with blenders, bypassing traditional distributor networks. This pattern is most visible among temperature-controlled freight specialists where total fluid cost visibility supports route-level profitability analysis and supplier performance scorecards.
Norway Commercial Vehicles Lubricants Market Segmentation
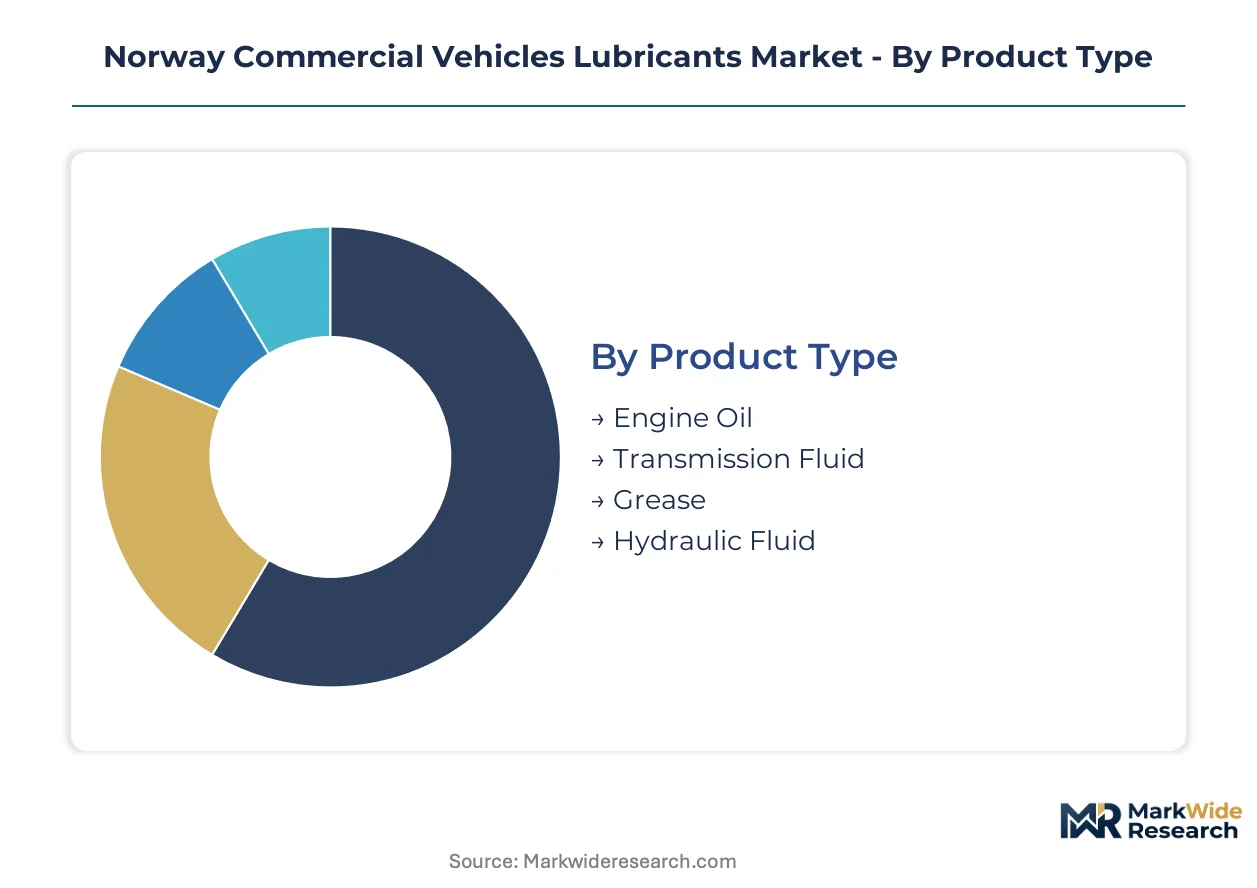
Segmentation in Norway's commercial vehicles lubricants market reveals how electrification, Arctic operating demands, and fleet consolidation are reshaping purchasing patterns across product specifications and channel structures. Understanding these divides exposes where formulation premiums concentrate and where volume erosion threatens incumbent positions.
Product Type:
Buyer priorities pivot on drain interval economics and thermal management complexity rather than upfront price alone.
- Engine Oil:Formulated from Group II/III base stocks with ACEA E6/E9 heavy-duty credentials and elevated TBN retention for extended service cycles. Demand concentrates among long-haul operators along the E6 corridor between Oslo and Trondheim, where 100,000-kilometer drain intervals justify synthetic premiums under fleet total cost of ownership models.
- Hydraulic Fluid:Dielectric and low-conductivity formulations engineered for electrified commercial vehicle thermal management systems and power electronics cooling. Oslo-Akershus logistics clusters are driving specification changes as battery-electric trucks and plug-in hybrid platforms displace conventional engine-driven hydraulic architectures.
- Transmission Fluid:Specialized ATF and MTF chemistries for automated manual and dual-clutch transmissions in Scandinavian commercial vehicle platforms.
- Grease:Lithium complex and calcium sulfonate thickener systems for chassis, wheel bearing, and fifth-wheel applications in temperature-variable operating conditions.
Engine Oil leads on scale; Hydraulic Fluid leads on momentum.
End User:
Procurement authority is migrating toward consolidated buyers with route-level cost visibility and predictive maintenance infrastructure.
- Fleet Operators:National haulage groups and temperature-controlled freight specialists running high-utilization schedules between Bergen, Stavanger, and Oslo. These buyers negotiate direct blender contracts unbundled from distributor maintenance packages, leveraging telematics-derived oil condition monitoring to shift from fixed-mileage to predictive service triggers.
- OEMs:Scandinavian commercial vehicle manufacturers and their captive dealer networks. Factory-fill specifications and warranty-aligned service programs create captive aftermarket demand through dealer lock-in, with fluid brands specified at vehicle purchase governing service bay replenishment for warranty duration.
- Logistics Providers:Third-party freight operators and last-mile delivery consolidators serving urban distribution zones.
- Maintenance Services:Independent workshops and quick-lube chains serving owner-operator segments and municipal vehicle fleets.
Fleet Operators command volume concentration; OEMs deliver margin protection through specification lock-in.
Distribution Channel:
Channel selection reflects buyer scale and the technical support intensity required for specification compliance.
- Direct Sales:National accounts teams from major blenders engaging consolidated transport groups in the Gardermoen logistics cluster and Stavanger port operations. These relationships bypass traditional wholesale markups and include technical field support for oil analysis programs and bulk storage infrastructure.
- Wholesalers:Regional distributors serving independent workshops and smaller fleet operators across Troms, Finnmark, and rural Møre og Romsdal. These intermediaries maintain cold-weather inventory positions and provide credit terms to owner-operators lacking direct blender relationships.
- Retail:Branded service stations and automotive parts chains serving emergency top-up demand and small commercial operators.
- Online:E-procurement platforms and manufacturer-direct portals for standardized specifications with documented technical datasheets.
Direct Sales captures the steepest expansion trajectory; Wholesalers retain geographic coverage advantages in peripheral regions.
Application:
Vehicle duty cycles and electrification penetration rates determine fluid specification intensity and replacement frequency.
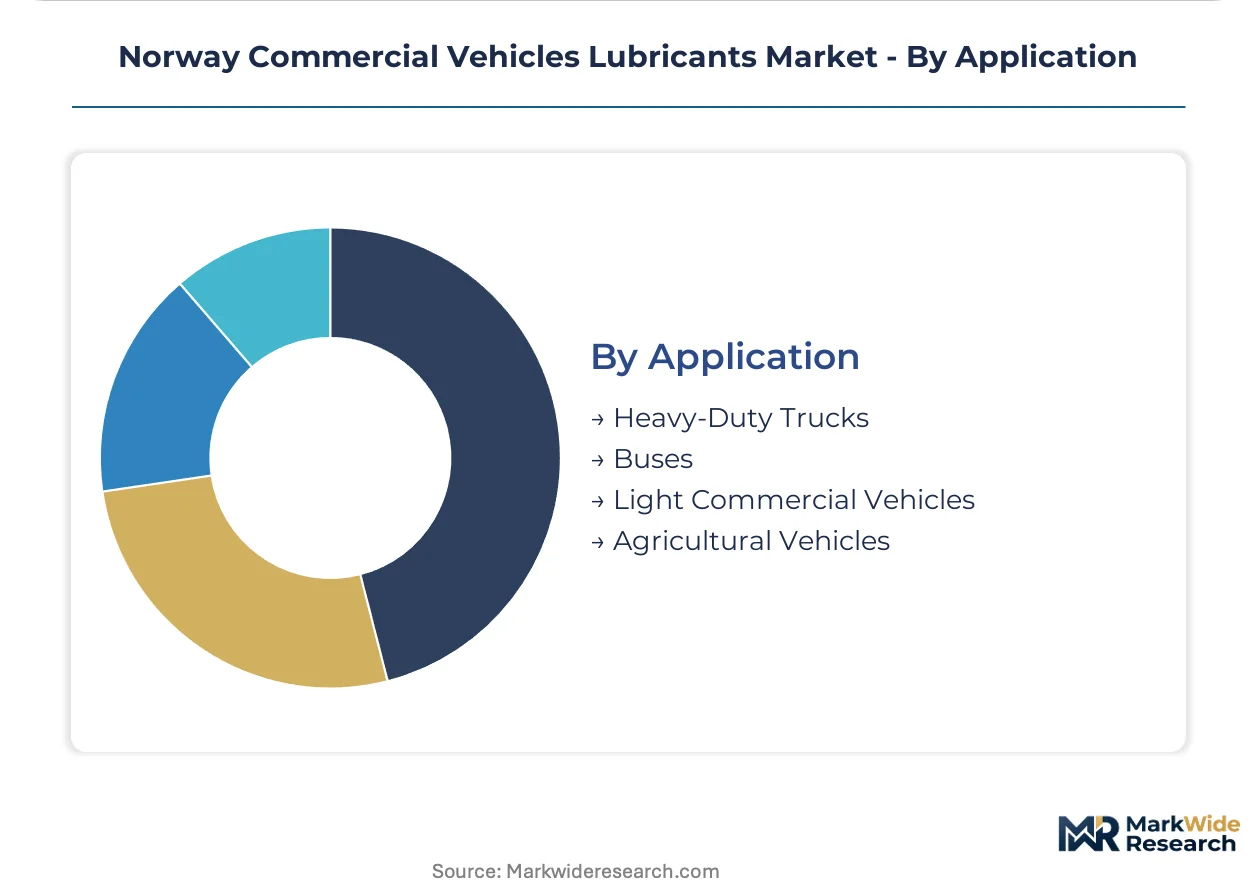
- Heavy-Duty Trucks:Long-haul tractors and rigid trucks operating above 16 tonnes gross vehicle weight across Norway's Arctic corridors. Troms and Finnmark routes demand specialized low-temperature viscosity grades with pour points below minus 40 degrees Celsius, commanding formulation premiums and repeat purchase cycles from temperature-stressed powertrains.
- Buses:Urban transit and intercity coach fleets in Bergen, Trondheim, and Oslo-Akershus. Electrification is advancing fastest in this segment, with battery-electric and fuel-cell platforms eliminating engine oil demand while introducing dielectric coolant and fuel cell humidifier fluid requirements.
- Light Commercial Vehicles:Vans and small trucks in last-mile delivery and tradesman service applications.
- Agricultural Vehicles:Tractors and harvesters in grain and livestock operations across Innlandet and Trøndelag counties.
Heavy-Duty Trucks anchor revenue scale; Buses exhibit the most rapid specification disruption from electrification mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's heavy-duty logistics corridors generate lubricant demand intensity that Norway's Arctic trucking routes cannot match, yet Oslo-Akershus electrification timelines outpace Berlin-Brandenburg by several years.
Oslo-Akershus Corridor
Electrified commercial vehicle adoption concentrates here, with battery-electric trucks and plug-in hybrid platforms creating parallel demand for dielectric coolants and advanced hydraulic fluids. The Norwegian Environment Agency enforces REACH compliance that constrains conventional mineral oil formulations. Fleet operators in the Gardermoen logistics cluster negotiate direct blender contracts unbundled from distributor maintenance packages.
Troms and Finnmark
Arctic operating conditions through these northern counties require specialized low-temperature viscosity formulations with pour points below minus 40 degrees Celsius. Cold-weather heavy-duty transport corridors command formulation premiums from temperature-stressed powertrains. The Norwegian Environment Agency's CO2 reduction pathways pressure lubricant producers to demonstrate lifecycle emissions compatibility in these remote routes.
Bergen-Stavanger Axis
High-utilization long-haul schedules between these western port cities drive specification of synthetic polyalphaolefin base stocks for extended drain intervals. Royal Dutch Shell Plc leverages its integrated fuel-and-lubricant retail network to secure multi-year supply contracts with national haulage companies operating this corridor. Stavanger's offshore oil sector concentrates specialized lubricant R&D workforce, creating recruitment friction for automotive fluid development.
Trøndelag County
Agricultural vehicle operations in grain and livestock applications generate steady demand for hydraulic fluids and greases. The EU F-Gas Regulation pressures reformulation of additive packages away from legacy chemistries for municipal and construction vehicle fleets. Independent workshops and regional distributors serve owner-operators across rural Møre og Romsdal with cold-weather inventory positions and credit terms.
Innlandet County
Last-mile delivery consolidators and tradesman service applications in light commercial vehicles dominate lubricant consumption patterns here. Norway's adoption of EU MDR-aligned sustainability reporting through the CSRD framework requires supply chain disclosure from lubricant manufacturers serving public procurement contracts. Temperature-controlled freight specialists leverage telematics-derived oil condition monitoring to shift from fixed-mileage to predictive service triggers.
Norway Commercial Vehicles Lubricants Market Competitive Landscape
European integrated energy majors anchor one tier; specialized lubricant formulators hold differentiated positions in Arctic and electrification segments. The market structure concentrates around four to six dominant blenders controlling factory-fill specifications and national fleet contracts, with mid-tier distributors retaining geographic coverage in peripheral regions. Strategic archetypes include integrated fuel-lubricant retailers, Arctic-specialized formulators, and synthetic base oil technology licensors. Competitive moves center on multi-year supply contract negotiations with consolidated transport groups and predictive maintenance service bundling.
Within the integrated energy major tier, Royal Dutch Shell Plc, BP PLC (Castrol), and TotalEnergies represent the dominant supply positions for national haulage and logistics contracts. These entities occupy anchor positions through retail network density and bulk supply infrastructure. FUCHS exemplifies the specialized formulator archetype, with naming conventions suggesting German operational origins and a structure calibrated for heavy-duty technical specifications. ExxonMobil Corporation anchors the synthetic technology licensing vector, with corporate form indicating US-based parentage and capacity for extended drain interval formulations. Champion Lubricants and Motul represent mid-tier specialists serving workshop and enthusiast segments where technical specification intensity runs lower.
| Leading Market Players |
|---|
| BP PLC (Castrol) |
| ExxonMobil Corporation |
| FUCHS |
| Royal Dutch Shell Plc |
| TotalEnergies |
| Chevron Corporation |
| Champion Lubricants |
| Gulf Oil International |
| Motul |
| Others |
Value Network & Pricing Analysis
Group II and Group III base oil costs originating from Rotterdam and Antwerp refining clusters flow through currency-adjusted import channels into Norwegian blender pricing tiers, with synthetic premium formulations capturing margin expansion while mineral oil grades face compression from electrification-driven volume erosion.
Pricing Analysis
Capacity additions in Antwerp's Group III base oil facilities are reshaping price floors for synthetic heavy-duty engine oils serving Oslo-Akershus fleet operators. Three-tier pricing structure across premium synthetic, mid-tier semi-synthetic, and economy mineral oil levels stratifies around ACEA E6/E9 certification tiers and drain interval performance. Price differentiation centers on TBN retention thresholds and Arctic viscosity credentials, with Troms and Finnmark routes commanding formulation premiums. Cost compression in economy mineral tiers is intensifying because battery-electric commercial platforms eliminate engine oil demand entirely. Municipal and construction fleets in Trøndelag exhibit highest price sensitivity due to biodegradability mandates intersecting with budget constraints, while national haulage groups running Bergen-Stavanger corridors demonstrate lowest sensitivity under total cost of ownership models.
Supply Chain Analysis
Used lubricant collection and re-refining flows from Gardermoen logistics cluster workshops back to European base oil recovery facilities are creating circular economy feedstock streams for Norwegian blenders. Geographic supply concentration centers on Belgium, Netherlands, and Germany for Group II/III base stocks, with additive packages sourced from specialty chemical production in Germany and France. Raw material dependencies rest on polyalphaolefin feedstocks, ashless detergent additives, and dielectric base fluids for electrified vehicle thermal management. Single-source vulnerability runs through Rotterdam-Antwerp logistics corridors where cross-border bottlenecks expose Norwegian blenders to input volatility. Distribution runs through direct sales channels for consolidated fleet operators, wholesaler networks for peripheral region coverage, and retail points for emergency top-up demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Norway's commercial vehicles lubricants market represents a late-cycle quality story as fleet electrification fragments demand toward premium synthetic specifications and specialized thermal management fluids. The shift from fixed-mileage to predictive service triggers based on oil condition monitoring is elevating formulation performance requirements across all buyer tiers.
For Market Incumbents: Acquire predictive maintenance technology assets and oil analysis platform capabilities to secure fleet operator direct contracts unbundled from distributor networks. Consolidate factory-fill specification lock-in with Scandinavian commercial vehicle manufacturers through warranty-aligned service program extensions. Battery-electric drivetrain fluid volume compression threatens mineral oil revenue bases, requiring accelerated synthetic premiumization and dielectric coolant portfolio expansion.
For New Entrants and Emerging Players: The price-point gap between premium synthetic formulations and economy mineral oils creates white-space opportunity for mid-tier semi-synthetic positioning targeting independent workshops and municipal fleets in Trøndelag and Innlandet counties. Arctic operating condition specialization for Troms and Finnmark temperature-stressed powertrains offers penetrable geographic entry. Bio-based additive formulations aligned with REACH compliance and biodegradability mandates provide differentiated go-to-market positioning against incumbent legacy chemistries.
For Investors and Strategic Acquirers: Consolidation pressure builds where fleet operator procurement unbundling from bundled maintenance contracts concentrates buying power among three to four national haulage groups. Long-term viability over the projection horizon favors blenders with verified lifecycle emissions documentation and circular economy service models qualifying for Norwegian public procurement CSRD disclosure mandates. Acquisition target archetype: specialized Arctic formulators with low-temperature viscosity intellectual property and established Troms-Finnmark distributor relationships. Monitor Euro VII pre-certification timeline compression and low-carbon fuel standard regulatory timing as inflection indicators determining whether synthetic premiumization or electric drivetrain fluid volume compression dominates market force allocation.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Base Oil Supply | Secures Rotterdam-Antwerp corridor access and mitigates currency-adjusted input volatility for Norwegian blenders. |
| Predictive Maintenance Service Bundling | Captures fleet operator direct contracts through telematics-derived oil condition monitoring platform deployment. |
| Dielectric Coolant Portfolio Expansion | Addresses battery-electric and plug-in hybrid thermal management demand in Oslo-Akershus logistics clusters. |
| Arctic Formulation Specialization Investment | Commands premium positioning for Troms and Finnmark cold-weather heavy-duty transport corridors. |
| Circular Economy Service Model Development | Qualifies for Norwegian public procurement CSRD disclosure mandates and used lubricant re-refining feedstock access. |
Research Methodology
Bottom-up fleet operator demand modeling reconciled against top-down base oil supply tracking forms the analytical core of this study. Primary interviews with lubricant blenders, fleet procurement directors, OEM technical specification managers, and aftermarket service heads combined with secondary validation from customs/trade data, SEC 10-K filings of integrated energy majors, and Norwegian Environment Agency regulatory filings. Triangulation across these sources anchors volume and value estimates.
Input-output matrices mapping base oil feedstock availability through formulation tiers to end-use consumption patterns drove the projection framework. Segmentation dimensions modeled include product type, end user procurement authority, distribution channel structure, and application duty cycle intensity across the analysis window. CAGRs derived from elasticity-adjusted demand curves incorporating electrification penetration rates and Arctic operating condition specifications. Industry-specific forecast inputs encompass REACH authorization timelines and Euro VII pre-certification requirements.
Caveats apply where battery-electric commercial vehicle adoption acceleration or Euro VII regulatory finalization delays could materially shift the outlook. Forecasts reflect assumptions on synthetic base oil technology cost curves and fleet operator consolidation trajectories. Practitioners should monitor low-carbon fuel standard implementation timing and electrification infrastructure subsidy allocations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lubricants
Middle East Lubricants Market
Lubricants
Russia Automotive Engine Oils Market
Lubricants
Europe Marine Lubricants Market
Lubricants
Saudi Arabia Lubricants Market
Lubricants
Forestry Lubricants Market
Lubricants
Europe Lubricants Market
Lubricants
Middle East Commercial Vehicles Lubricants Market
Lubricants
Russia Commercial Vehicles Lubricants Market
Lubricants
Global Mineral Oil Market
Lubricants
Hydropower Lubricants Market
Lubricants
China Lubricants Market
Lubricants
Mining Lubricants Market
Lubricants
Philippines Lubricants Market
Lubricants
Fire Resistant Fluids Market
Lubricants
Mexico Commercial Vehicles Lubricants Market
Lubricants
United Arab Emirates Lubricants Market