
 Global Algal Oil Market | 2026-2036
Global Algal Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Global Algal Oil Market Foresight
Multi-source cultivation partnerships between biotech firms and ingredient suppliers is broadening raw material security for omega-3 producers. Cargill leverages its global supply chain infrastructure to secure biomass offtake from multiple algae cultivation sites across temperate zones. Royal DSM sustains technology leadership in fermentation-derived EPA through proprietary strain development programs. Corbion N.V. specializes in photobioreactor systems that deliver consistent DHA yields for infant formula applications.
Algal oil comprises lipid extracts from microalgae biomass, typically containing 30-55% omega-3 fatty acids by dry weight, with DHA and EPA as the principal bioactive fractions used for human and animal nutritional fortification. Photobioreactor production commands premium positioning due to closed-system contamination control and year-round output stability, while open pond cultivation occupies the cost-sensitive animal feed tier with lower capital intensity. Omega-3 DHA leads volume allocation through infant nutrition contracts, whereas dietary supplements represent the fastest-expanding application as clean-label positioning displaces fish-derived alternatives in capsule and soft-gel formats.
FDA GRAS notifications and EFSA novel food authorizations shape ingredient market access timelines and label claim permissibility for algal oil entrants in North America and Europe. REACH compliance and EU Green Deal bioeconomy targets are redirecting European production investments toward closed-loop fermentation systems with reduced water intensity. Stakeholders must monitor strain IP portfolios and regulatory exclusivity windows as barriers to generic biomass supply tighten across major nutrition markets.
Market Dynamics
Fermentation-based EPA production is concentrating contract demand among pharmaceutical-grade buyers, while photobioreactor systems secure premium positioning through closed-loop contamination control. This bifurcation between precision fermentation and open-pond cultivation defines competitive positioning across human nutrition and animal feed tiers.
Growth Catalysts
- EFSA novel food streamlining:Dietary supplement manufacturers in Germany accelerate DHA-rich algal oil purchases as regulatory pathways shorten ingredient access timelines. Infant formula producers leverage these approvals for clean-label positioning against fish-derived alternatives.
- Fermentation technology maturation:Singapore-based facilities achieve pharmaceutical-grade EPA isolates with batch-to-batch consistency that satisfies contract manufacturing specifications. Pharmaceutical buyers concentrate procurement with fermentation-derived suppliers.
- EU Green Deal bioeconomy targets:REACH compliance and water intensity reduction mandates redirect European production investments toward closed-loop systems. Biomass offtake agreements multiply across temperate cultivation zones.
Market Restraints
- Capital intensity barriers:Photobioreactor systems require substantial upfront investment for closed-system infrastructure that excludes cost-sensitive animal feed entrants. Open pond cultivation retains cost advantage at lower omega-3 concentration yields.
- Strain IP concentration:Proprietary fermentation strain portfolios and regulatory exclusivity windows tighten barriers to generic biomass supply. Technology licensing fees compress margins for second-tier producers.
- Fish oil substitution economics:Established fish-derived omega-3 supply chains maintain price competitiveness in bulk feed applications through economies of scale. Algal oil premium positioning limits addressable market penetration.
Strategic Opportunities
- India pharmaceutical expansion:CDSCO regulatory harmonization with ICH standards creates pathway for EPA isolates in prescription cardiovascular applications. Domestic fermentation capacity remains underdeveloped relative to demand potential.
- Cellular agriculture convergence:Integration of precision fermentation infrastructure with cultivated meat and dairy platforms enables shared bioreactor utilization. Algal lipid coproduct streams enhance unit economics for integrated biotech facilities.
- Direct-to-consumer channel development:Subscription-based supplement platforms bypass traditional pharmaceutical distribution markups for DHA soft-gel products. E-commerce penetration in wellness categories accelerates brand building for algae-derived positioning.
Industry Challenges
- Phycology talent scarcity:Specialized expertise in microalgae strain optimization and bioprocess engineering concentrates within academic and flagship corporate laboratories. Workforce development lags facility expansion timelines.
- GRAS notification duration:FDA review timelines for novel algal strains extend commercialization schedules for new entrants. Regulatory exclusivity windows compress effective patent life for fermentation-derived products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Algal Oil Market |
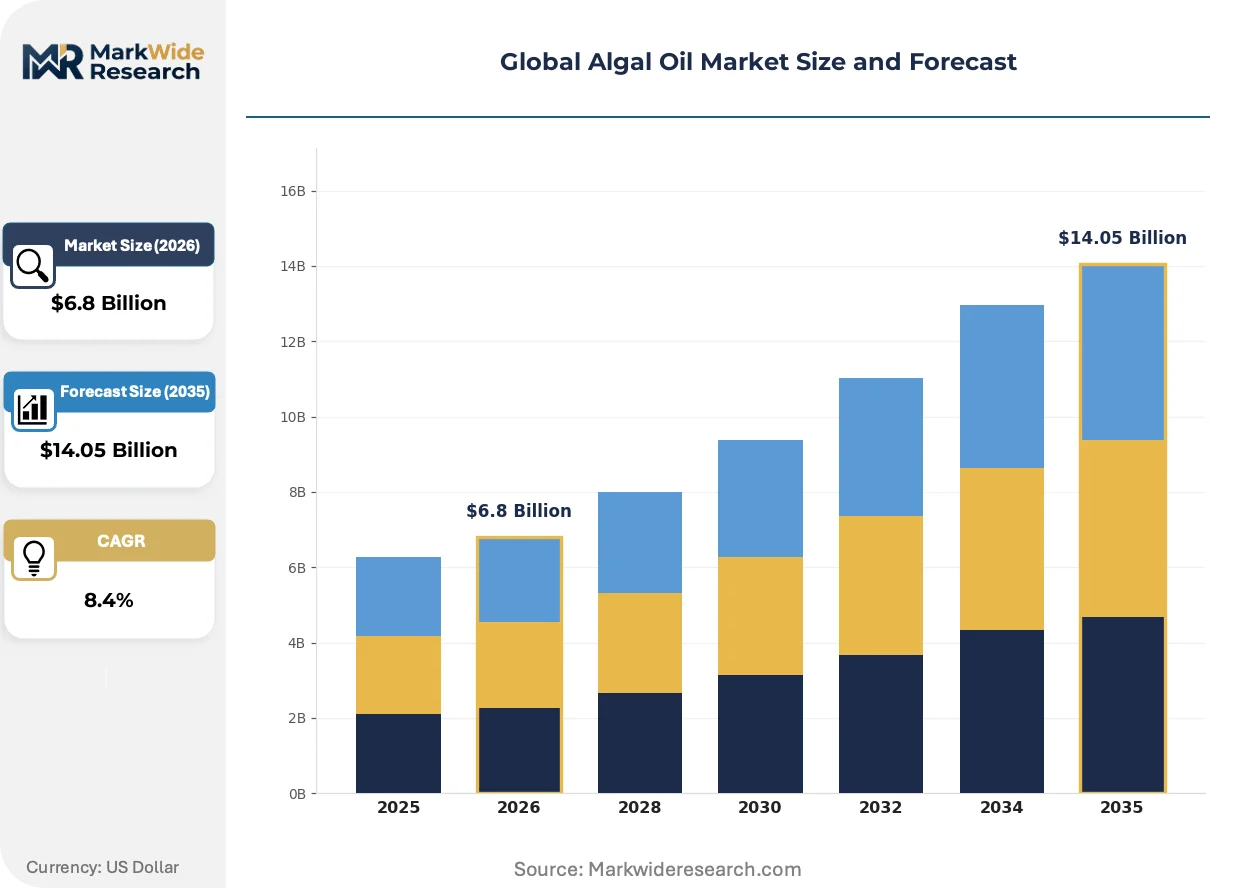
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Omega-3 EPA, Omega-3 DHA, ARA, Saturated Oils, Polyunsaturated Oils Application: Dietary Supplements, Infant Nutrition, Functional Foods, Animal Feed, Cosmetics End User: Pharmaceutical Manufacturers, Nutraceutical Companies, Pet Food Producers, Personal Care Manufacturers, Specialty Ingredient Suppliers Production Method: Photobioreactors, Open Ponds, Fermentation, Hybrid Systems |
| Companies Covered | Cargill, Royal DSM, Lonza Group, Cyanotech Corporation, Algatech Ltd., Corbion N.V., BASF SE, Archer Daniels Midland Company, Algae Floating Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Algal Oil Market Shifts & Advancements
Precision fermentation infrastructure is reshaping competitive economics through strain-specific EPA yields that exceed photobioreactor baselines. Regulatory acceleration in major nutrition markets and procurement model evolution among pharmaceutical buyers define the transformation trajectory.
Continuous fermentation systems with real-time metabolite monitoring are overtaking batch photobioreactor operations for pharmaceutical-grade EPA production. Contract manufacturers in Singapore and Switzerland adopt these platforms to guarantee batch-to-batch fatty acid profiles. The technology is compressing quality assurance timelines from weeks to hours while enabling just-in-time inventory models for pharmaceutical clients.
EFSA novel food authorization pathways are streamlining DHA ingredient access for infant formula fortification across European markets. Manufacturers file consolidated applications covering multiple algal strains and extraction methods to accelerate regulatory clearance. Dietary supplement producers in Germany and the Netherlands leverage these precedents for clean-label capsule positioning against fish oil alternatives.
Long-term offtake contracting is displacing spot market purchasing among pharmaceutical and infant nutrition buyers seeking supply security. Five-year biomass agreements with fermentation facilities now include price escalation clauses tied to agricultural commodity indices. This pattern is most visible in Swiss and German procurement departments where risk management protocols favor predictable input costs over spot market flexibility.
Global Algal Oil Market Segmentation
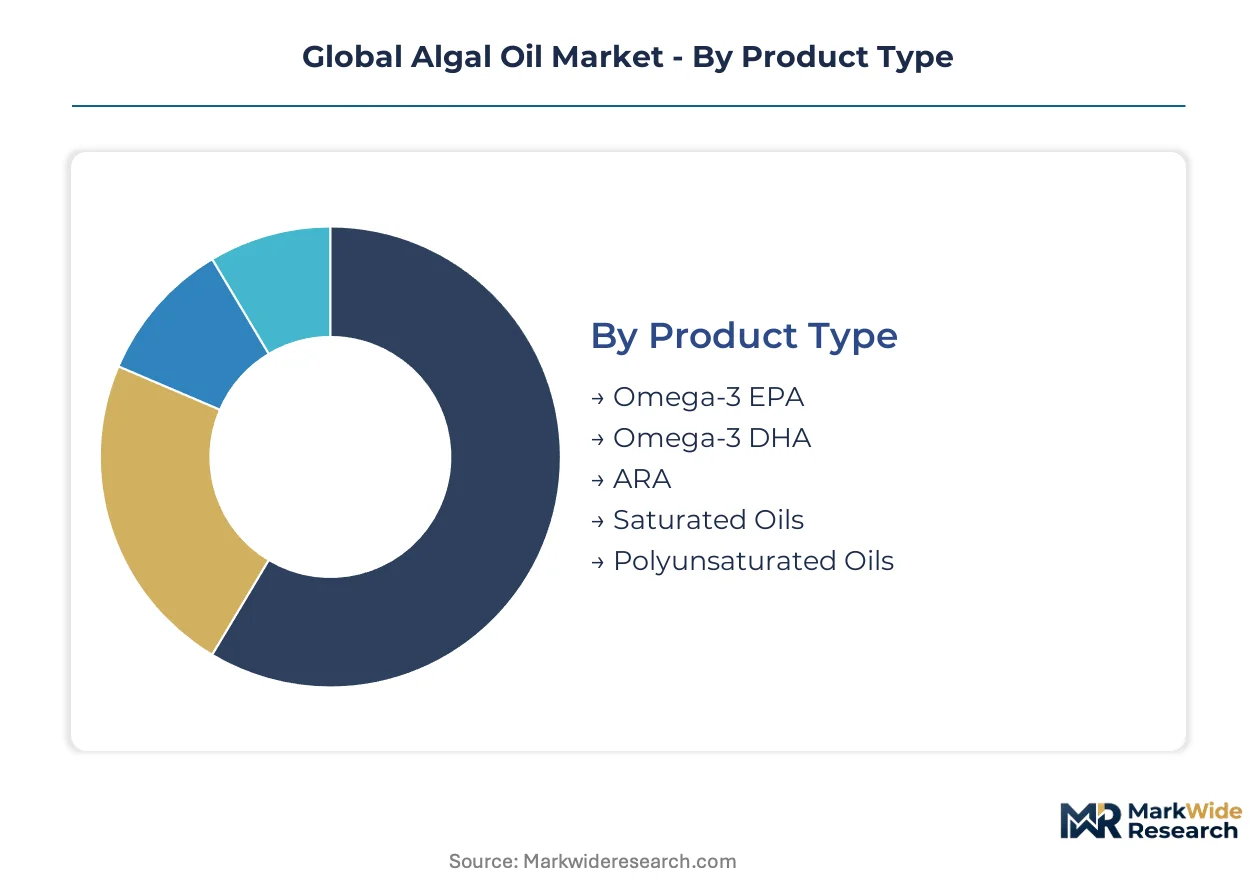
Algal oil market segmentation reveals distinct capital requirements and margin profiles across production technologies and end-use applications. Each dimension carries implications for regulatory pathway complexity, supply chain configuration, and customer procurement behavior.
Product Type:
Capital intensity varies sharply across lipid fractions, with fermentation-derived isolates demanding specialized bioreactor infrastructure while crude extracts utilize simpler extraction trains.
- Omega-3 DHA:Concentrations of 35-50% by dry weight characterize premium strains optimized for infant formula fortification. German and Dutch dietary supplement manufacturers concentrate procurement through long-term offtake agreements with photobioreactor operators seeking supply security for clean-label positioning.
- Omega-3 EPA:Pharmaceutical-grade isolates require strain-specific fermentation platforms achieving batch-to-batch consistency above 98% purity. Singapore-based contract manufacturers capture concentrated demand from cardiovascular drug developers seeking isolates with documented metabolite profiles.
- ARA:Arachidonic acid extracts serve neonatal nutrition formulations with specific fatty acid ratio requirements.
- Saturated Oils:Lower-value fractions enter animal feed and industrial applications with minimal processing.
- Polyunsaturated Oils:Mixed omega-3/omega-6 blends target cost-sensitive functional food fortification.
Most installed capacity flows through Omega-3 DHA. Expansion is steepest in Omega-3 EPA.
Application:
Volume concentration and margin capture diverge across application tiers, with pharmaceutical and infant nutrition commanding premium pricing against commodity feed additives.
- Infant Nutrition:EFSA novel food authorizations and FDA GRAS notifications govern ingredient access for formula fortification. European manufacturers leverage regulatory precedents to displace fish-derived alternatives in premium positioning.
- Dietary Supplements:Soft-gel and capsule formats drive fastest-expanding demand as direct-to-consumer channels proliferate. Subscription-based wellness platforms in Germany and the Netherlands accelerate brand building for algae-derived positioning.
- Functional Foods:Beverage and dairy fortification applications require emulsion-stable lipid forms.
- Animal Feed:Open pond cultivation supplies cost-sensitive aquaculture and livestock sectors with lower omega-3 concentration yields.
- Cosmetics:Topical applications utilize minor lipid fractions for emollient properties.
Revenue concentration sits with Infant Nutrition. Dietary Supplements are gaining share fastest.
End User:
Procurement sophistication and quality assurance requirements separate pharmaceutical-grade buyers from commodity feed purchasers.
- Pharmaceutical Manufacturers:Prescription cardiovascular and neurological drug developers require EPA isolates with documented purity certificates and chain-of-custody documentation. CDSCO regulatory harmonization in India creates pathway for fermentation-derived isolates in domestic prescription applications.
- Nutraceutical Companies:Capsule and soft-gel formulators prioritize DHA-rich oils for clean-label positioning against fish-derived alternatives. German manufacturers accelerate purchases as EFSA novel food pathways streamline ingredient access.
- Pet Food Producers:Premium companion animal formulations incorporate algal DHA for cognitive health claims.
- Personal Care Manufacturers:Cosmetic emulsion formulators utilize saturated lipid fractions.
- Specialty Ingredient Suppliers:Distributors and blenders serve fragmented regional food and supplement manufacturers.
Contract value concentrates with Pharmaceutical Manufacturers. Procurement velocity is highest among Nutraceutical Companies.
Production Method:
Technology selection determines capital deployment scale, contamination risk profile, and achievable omega-3 titers.
- Fermentation:Closed-system bioreactors achieve pharmaceutical-grade EPA yields with batch-to-batch consistency. Singapore facilities concentrate contract demand from buyers seeking isolates with documented metabolite profiles and compressed quality assurance timelines.
- Photobioreactors:Closed-loop cultivation systems command premium positioning through year-round output stability and contamination control. Royal DSM and Corbion N.V. sustain technology leadership through proprietary strain development and consistent DHA yields.
- Open Ponds:Extensive cultivation occupies cost-sensitive animal feed tier with lower capital intensity and reduced omega-3 concentration.
- Hybrid Systems:Combined open-pond biomass generation with closed finishing stages balances yield and capital efficiency.
Most biomass volume originates from Open Ponds. Investment flows most heavily into Fermentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore anchors fermentation-derived algal oil capacity through pharmaceutical-grade contract manufacturing clusters serving international buyers. Germany and the Netherlands concentrate dietary supplement demand as EFSA novel food pathways mature. The United States sustains infant formula fortification leadership through FDA GRAS precedents.
United States
Infant nutrition manufacturers drive DHA procurement through long-term supply agreements with photobioreactor operators. FDA GRAS notifications govern ingredient access timelines for novel algal strains entering formula fortification. California's biotechnology corridor houses fermentation facilities producing EPA isolates for pharmaceutical applications.
Germany
Dietary supplement manufacturers accelerate DHA-rich algal oil purchases as EFSA novel food approvals streamline regulatory pathways. REACH compliance mandates redirect production investments toward closed-loop systems with reduced water intensity. Bavaria's industrial biotechnology cluster concentrates precision fermentation capacity for omega-3 isolates.
Singapore
Pharmaceutical-grade buyers concentrate contract demand for EPA isolates requiring batch-to-batch consistency documentation. The country's national pharmaceutical regulator maintains alignment with ICH standards for prescription cardiovascular applications. Biopolis research corridor anchors continuous fermentation systems with real-time metabolite monitoring capabilities.
India
Domestic pharmaceutical expansion creates demand pathways for EPA isolates in prescription cardiovascular applications. CDSCO regulatory harmonization with ICH standards enables fermentation-derived ingredient market access. Maharashtra's industrial biotechnology zone remains underdeveloped relative to demand potential for pharmaceutical-grade omega-3 production.
Switzerland
Pharmaceutical procurement departments favor five-year biomass agreements with price escalation clauses tied to agricultural commodity indices. Swissmedic oversight ensures quality assurance documentation for prescription drug applications. Basel's life sciences cluster concentrates contract manufacturing demand for documented purity certificates and chain-of-custody documentation.
Global Algal Oil Market Competitive Landscape
Global majors compete with regional champions across technology platforms and end-use specializations. The vendor base stratifies between fermentation-derived pharmaceutical specialists and photobioreactor operators serving infant nutrition contracts. Three archetypes dominate: integrated agribusiness conglomerates leveraging supply chain infrastructure, dedicated biotechnology firms with proprietary strain portfolios, and contract manufacturers offering toll production services. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure biomass offtake agreements across temperate cultivation zones.
Among integrated agribusiness conglomerates, Cargill exemplifies supply chain leverage through multi-source biomass offtake arrangements. Royal DSM and Corbion N.V. anchor the biotechnology specialist tier, with the former representing fermentation-derived EPA leadership and the latter exemplifying photobioreactor system optimization for consistent DHA yields. These three companies occupy positions spanning the technology spectrum from open-pond cost efficiency to pharmaceutical-grade isolation.
| Leading Market Players |
|---|
| Cargill |
| Royal DSM |
| Lonza Group |
| Cyanotech Corporation |
| Algatech Ltd. |
| Corbion N.V. |
| BASF SE |
| Archer Daniels Midland Company |
| Algae Floating Systems, Inc. |
| Others |
Supply & Pricing Matrix
Agricultural commodity indices governing long-term offtake agreements cascade through fermentation facility contracts into three distinct pricing tiers. Pharmaceutical-grade EPA isolates command premium positioning through batch-to-batch consistency documentation, while photobioreactor DHA yields for infant nutrition occupy a mid-tier anchored by EFSA novel food authorization costs, and open-pond crude extracts serve cost-sensitive animal feed applications at economy levels.
Pricing Analysis
Input-cost pass-through from proprietary strain licensing fees and closed-system infrastructure depreciation shapes contract structures across production tiers. Price differentiation separates pharmaceutical-grade EPA with documented metabolite profiles from standard-grade DHA for dietary supplements and economy-grade mixed oils for feed applications. Pricing pressure stems from fish oil substitution economics in bulk feed segments where established marine-derived supply chains retain cost advantages. Nutraceutical capsule manufacturers exhibit highest price sensitivity due to competitive clean-label positioning against fish-derived alternatives, while pharmaceutical buyers prioritize consistency premiums over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from Swiss and German pharmaceutical procurement departments mandate qualified backup suppliers for EPA isolates with documented chain-of-custody documentation. Supply concentrates in Singapore for fermentation-derived pharmaceutical grades, the Netherlands for photobioreactor DHA systems, and India for emerging open-pond capacity expansion. Raw material dependencies include proprietary microalgae strain libraries, fermentation nutrient media, and specialized extraction solvents. Single-source vulnerability around strain IP portfolios creates supply risk as regulatory exclusivity windows tighten. Distribution runs through long-term offtake contracting with price escalation clauses rather than spot market purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fermentation technology maturation and continuous system adoption compress quality assurance timelines from weeks to hours, expanding margin capture for operators achieving pharmaceutical-grade consistency. Premium-tier demand from prescription cardiovascular applications and infant formula fortification displaces commodity feed positioning.
For Market Incumbents: Lock in multi-year biomass offtake agreements across temperate cultivation zones before regulatory exclusivity windows tighten further. Secure proprietary strain portfolios through accelerated R&D investment in EPA-optimized fermentation platforms, as generic biomass supply barriers intensify competition for pharmaceutical-grade contracts. For New Entrants and Emerging Players: Launch via direct-to-consumer subscription platforms for DHA soft-gel products targeting German and Dutch wellness markets where EFSA novel food pathways have streamlined ingredient access. White-space opportunity sits with CDSCO-aligned EPA isolates for India's underdeveloped domestic pharmaceutical fermentation capacity. For Investors and Strategic Acquirers: Asymmetric upside sits with precision fermentation specialists possessing continuous system infrastructure and real-time metabolite monitoring capabilities. Five-to-ten year viability favors platforms integrating algal lipid coproduct streams with cellular agriculture bioreactor utilization. Signal to watch: CDSCO regulatory harmonization completion triggering pharmaceutical contract manufacturing demand in Maharashtra's industrial biotechnology zone.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Biomass Offtake Agreement | Swiss and German pharmaceutical buyers secure supply predictability through five-year contracts with price escalation clauses. |
| Proprietary Strain Development Program | Royal DSM and Corbion N.V. sustain technology leadership through EPA-optimized and DHA-consistent strain portfolios. |
| Continuous Fermentation System Deployment | Singapore and Switzerland facilities compress quality assurance timelines from weeks to hours for pharmaceutical clients. |
| EFSA Novel Food Consolidated Application | German and Dutch manufacturers accelerate regulatory clearance for multiple algal strains and extraction methods. |
| Cellular Agriculture Infrastructure Integration | Shared bioreactor utilization with cultivated meat platforms enhances unit economics through algal lipid coproduct streams. |
Research Methodology
Direct dialogue with fermentation facility operators, pharmaceutical procurement managers, infant formula regulatory affairs leads, and dietary supplement brand managers combined with secondary validation from EFSA novel food authorization databases, FDA GRAS notification filings, CDSCO regulatory harmonization documents, and customs trade data. Bottom-up capacity modeling across Singapore, Germany, Netherlands, and India production sites triangulated with top-down demand segmentation by application tier.
Market sizing outputs reflect installed capacity analysis across fermentation, photobioreactor, and open-pond production methods segmented by omega-3 concentration grade, end-use application, and regional regulatory cluster. CAGRs derive from trajectory analysis of contract manufacturing demand, EFSA approval velocity, and pharmaceutical-grade procurement concentration patterns. Industry-specific inputs include strain IP portfolio maturity assessments and REACH compliance cost structures for European production investments.
Several conditions sit outside the modeled scope, including abrupt fish oil supply disruptions altering substitution economics, unanticipated CDSCO regulatory delays, and strain contamination events forcing facility shutdowns. Deviation in EFSA novel food authorization timelines or FDA GRAS notification durations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Food Cultures Market
Alternative Food Sources
Spirulina Beverages Market
Alternative Food Sources
South America Fat Replacers Market
Alternative Food Sources
Algal Protein Market
Alternative Food Sources
Feather Meal Market
Alternative Food Sources
North America Meal Products Replacement Market
Alternative Food Sources
Asia-Pacific Algae Protein Market
Alternative Food Sources
Vegan Ham Market
Alternative Food Sources
Gluten Substitute Market
Alternative Food Sources
Flour Substitutes Market
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
Global Meal Replacement Shakes Market
Alternative Food Sources
Seitan Market
Alternative Food Sources
Black Soldier Fly (BSF) Market
Alternative Food Sources
Fish Meal Alternative Market
Alternative Food Sources
Europe Algae Protein Market