
 Proptech Market | 2026-2036
Proptech Market Size, Share, and Industry Trends Forecast 2026-2036
Proptech Market Intelligence
North America is rewriting competitive dynamics in proptech infrastructure. CoStar Group leverages its data monopoly across commercial listings to sustain pricing power in analytics subscriptions. Opendoor anchors the iBuying segment through in-house valuation algorithms that compress transaction timelines. Altus Group competes in investment-grade data services for institutional capital deployment.
Proptech encompasses software, hardware, and data platforms that digitize property acquisition, management, and monetization through automated workflows and connected sensor networks. Smart Building Technologies integrate IoT-enabled HVAC, lighting, and access control systems that reduce operational energy expenditure by enabling real-time environmental optimization. Property Management Software leads in recurring revenue stability due to high switching costs and embedded payment processing. Blockchain-based transaction platforms represent the fastest-growing technology segment as distributed ledger protocols streamline title verification and fractional ownership structures.
The EU AI Act and GDPR constrain automated tenant screening algorithms by mandating explainability and data minimization, which elevates compliance costs for platform operators. The SEC regulates crowdfunding platforms under Regulation Crowdfunding, capping retail investor exposure and requiring audited financial disclosures that shape platform design. Stakeholders must monitor how divergent national implementations of AI governance fragment product standardization across jurisdictions.
Market Dynamics
Algorithmic tenant screening and automated lease management platforms are compressing decision cycles for multifamily operators while the EU AI Act forces explainability retrofits across European deployments.
Growth Catalysts
- Smart Building IoT convergence:Sensor networks integrating HVAC, lighting, and access control reduce operational energy expenditure through real-time environmental optimization. Institutional landlords in Germany and the Netherlands prioritize these retrofits.
- EU AI Act compliance infrastructure:Mandated algorithmic explainability for tenant screening creates specialized demand for audit-ready platforms. Vendors embedding compliance-by-design capture premium positioning.
- Blockchain title verification:Distributed ledger protocols streamline fractional ownership structures and cross-border property transactions. Berlin and Munich municipal pilots validate registry modernization pathways.
Market Restraints
- GDPR data minimization requirements:Tenant screening platforms face elevated engineering costs to implement purpose limitation and storage constraints across EU member states.
- Legacy system integration friction:Property management software replacement cycles extend 18-36 months due to embedded payment processing and high switching costs.
- Semiconductor supply concentration:IoT sensor and smart lock manufacturers depend on concentrated Asian foundry capacity, creating input volatility for hardware-dependent proptech.
Strategic Opportunities
- Underpenetrated secondary German cities:Hamburg, Cologne, and Frankfurt exhibit lower proptech adoption than Berlin despite comparable multifamily stock, creating whitespace for platform expansion.
- Regulatory sandbox participation:Germany's Federal Financial Supervisory Authority permits controlled testing of blockchain-based property registries, accelerating validation timelines for compliant architectures.
- Convergence of AI and edge computing:On-device processing for access control and energy management reduces latency and cloud dependency. Industrial real estate operators pilot these architectures.
Industry Challenges
- Embedded systems engineering scarcity:Proptech vendors compete for talent capable of integrating IoT firmware with cloud-native property management platforms.
- Multi-jurisdiction certification timelines:Platforms serving cross-border institutional investors must sequentialize GDPR, EU AI Act, and national financial regulator approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Proptech Market |
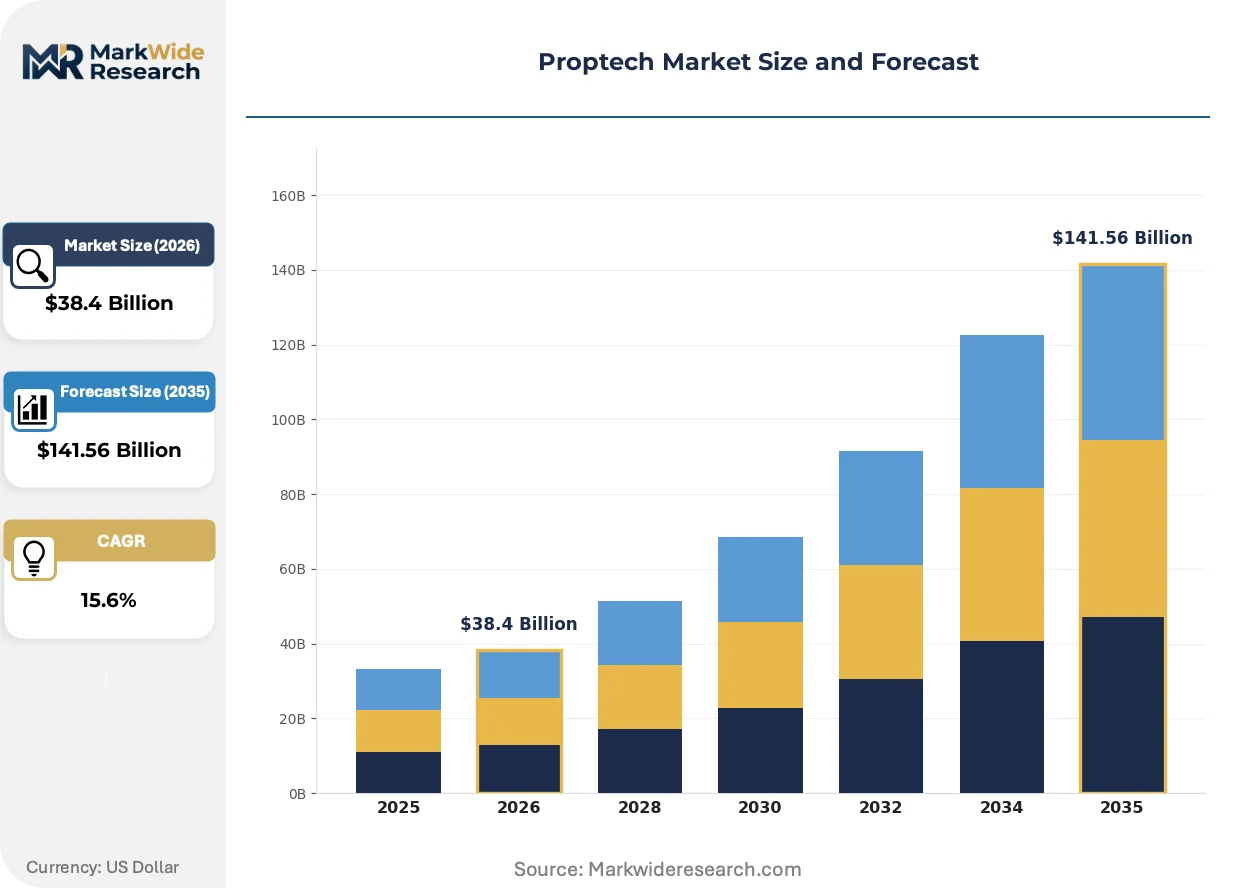
| Market Size in 2026 | $38.4 Billion |
| Market Size in 2035 | $141.56 Billion |
| CAGR (2026 – 2036) | 15.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Property Management Software, Crowdfunding Platforms, Smart Building Technologies, Virtual Tours Service Type: Real Estate Analytics, Investment Solutions, Lease Management Services, Tenant Screening End User: Real Estate Developers, Property Managers, Investors, Tenants Technology: Blockchain, Artificial Intelligence, Internet of Things, Virtual Reality |
| Companies Covered | CoStar Group, Opendoor, Altus Group, Crexi, Pacaso, Casavo, Propy, Engrain, Metropolis Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Proptech Market Strategic Shifts & Innovations
Proptech infrastructure is fragmenting along regulatory fault lines while demand concentrates in jurisdictions offering controlled experimentation frameworks for emerging transaction technologies.
Digital twin technology for commercial asset management is hybridizing physical building data with predictive maintenance algorithms. Institutional real estate investors in Germany deploy these systems to compress capital planning cycles. The technology is hybridizing operational expenditure forecasting with automated work order generation.
The EU AI Act's risk-based classification system imposes conformity assessment obligations on high-risk tenant screening algorithms. Platform operators must document training data provenance and decision logic. Multifamily property managers in France and Germany delay algorithmic deployments pending certified audit frameworks.
Institutional procurement of proptech solutions now emphasizes interoperability certification over single-vendor stacks. Real estate investment trusts unbundle previously integrated software suites. This pattern is most visible in the Netherlands where open API mandates for municipal housing data accelerate platform switching.
Proptech Market Segmentation
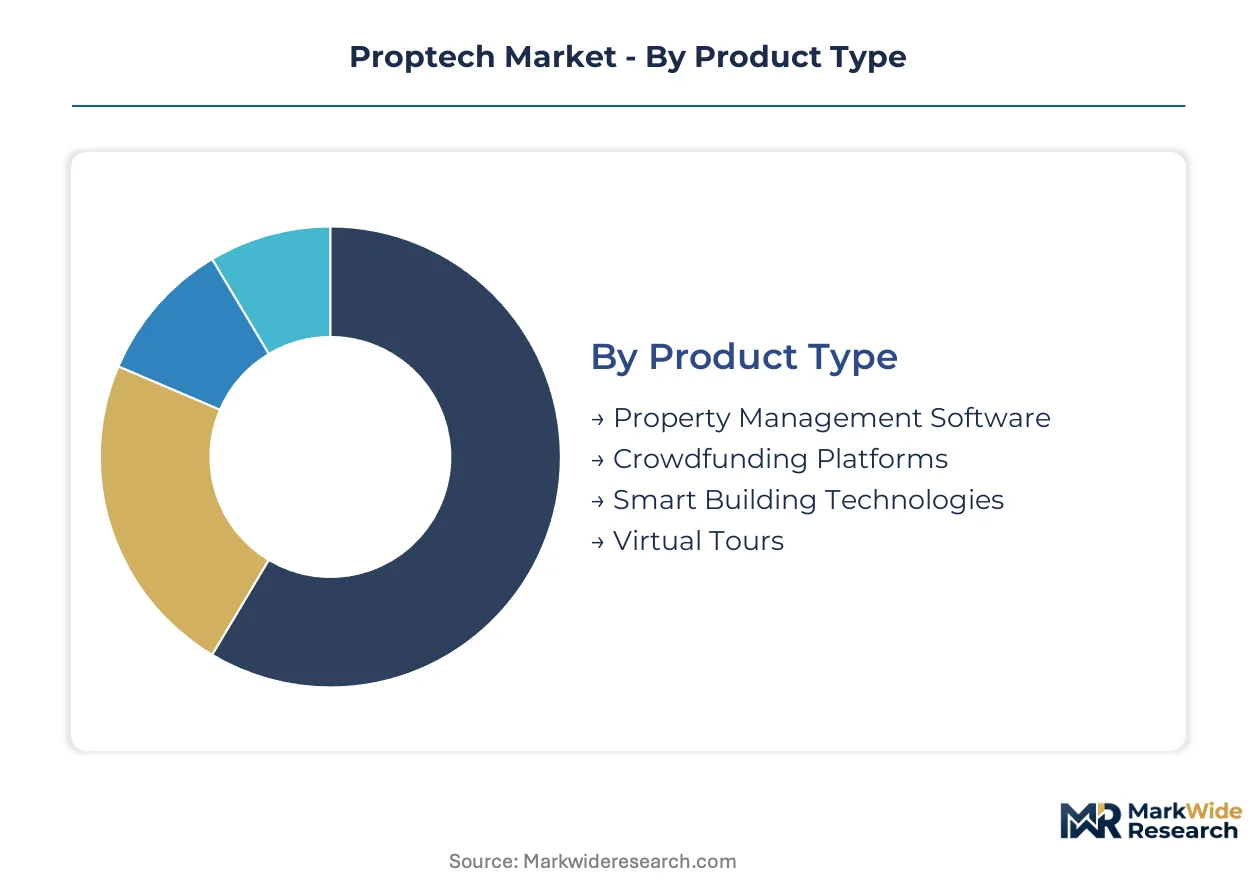
Proptech segmentation reveals how technology specialization shapes vendor positioning and customer procurement patterns. Distinct product architectures command different pricing premiums and integration complexity, while end-user categories determine sales cycle length and contract structure.
Product Type:
Cost tier differentiation separates subscription-based software from capital-intensive hardware deployments, with hybrid models emerging at the boundary.
- Property Management Software:Cloud-native platforms embed payment processing and maintenance ticketing into unified dashboards. Multifamily operators in Germany prioritize these systems for recurring revenue stability and high switching costs that lock in tenant data histories.
- Smart Building Technologies:IoT sensor networks integrate HVAC, lighting, and access control through real-time environmental optimization protocols. Institutional landlords in the Netherlands deploy these retrofits to compress operational energy expenditure.
- Crowdfunding Platforms:SEC-regulated investment vehicles under Regulation Crowdfunding cap retail exposure and mandate audited disclosures.
- Virtual Tours:3D spatial capture tools reduce physical showing requirements for remote tenant acquisition.
Property Management Software holds installed capacity. Smart Building Technologies is rotating up the share rankings.
Service Type:
Application focus determines whether vendors capture value at the transaction layer or through ongoing operational support.
- Real Estate Analytics:Investment-grade data services aggregate comparable sales, rent rolls, and demographic overlays for institutional capital deployment. CoStar Group leverages listing data monopolies to sustain pricing power in subscription analytics.
- Tenant Screening:Algorithmic assessment platforms face EU AI Act compliance mandates requiring explainability documentation and data minimization protocols. French and German property managers delay deployments pending certified audit frameworks.
- Investment Solutions:Portfolio optimization tools target real estate investment trusts with scenario modeling capabilities.
- Lease Management Services:Automated documentation and compliance tracking reduce legal overhead for multifamily operators.
Real Estate Analytics holds installed capacity. Tenant Screening is rotating up the share rankings.
End User:
Customer type dictates procurement authority, with institutional buyers demanding interoperability certification over single-vendor stacks.
- Property Managers:Multifamily operators drive demand for automated lease management and embedded payment processing, prioritizing platforms with open API architectures that unbundle previously integrated software suites.
- Real Estate Developers:Ground-up construction projects require pre-leasing tools and capital stack visualization for institutional equity partners.
- Investors:Cross-border institutional capital requires multi-jurisdiction compliance certification across GDPR, EU AI Act, and national financial regulators.
- Tenants:End-user demand concentrates on mobile-first rent payment interfaces and maintenance request portals.
Property Managers holds installed capacity. Investors is rotating up the share rankings.
Technology:
Maturity curves separate proven deployments from experimental architectures still seeking product-market fit.
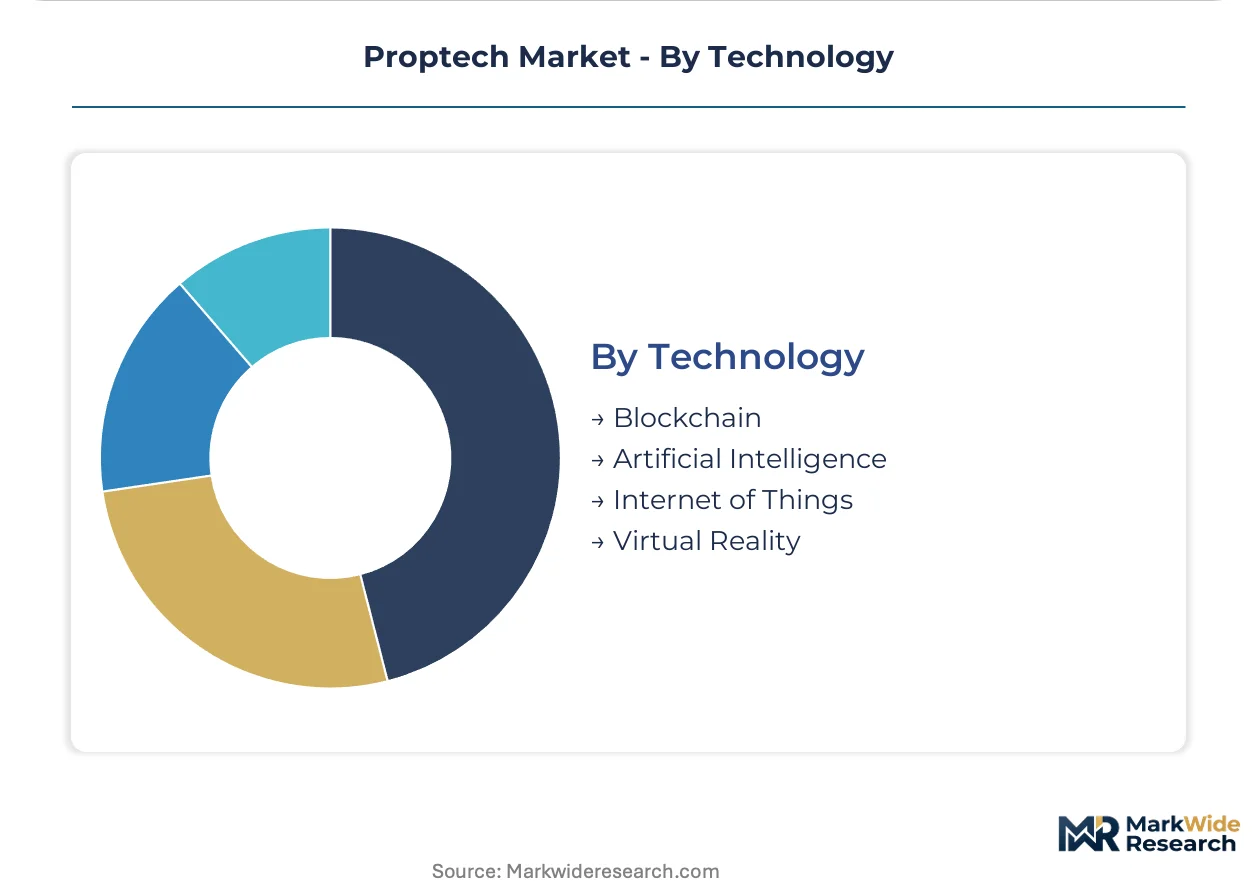
- Blockchain:Distributed ledger protocols streamline title verification and fractional ownership structures through immutable transaction records. Berlin and Munich municipal pilots validate registry modernization pathways under Germany's Federal Financial Supervisory Authority sandbox.
- Artificial Intelligence:Machine learning models compress valuation timelines and predict maintenance failures, though EU AI Act risk classifications impose conformity assessment obligations on high-risk tenant screening deployments.
- Internet of Things:Edge-connected sensors enable real-time building optimization but depend on concentrated Asian foundry capacity for semiconductor inputs.
- Virtual Reality:Immersive property visualization reduces transaction friction for remote investors and international tenants.
Internet of Things holds installed capacity. Blockchain is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. German institutional landlords prioritize embedded compliance architectures for tenant screening, while US operators optimize for transaction velocity through algorithmic valuation platforms. Asian markets emphasize hardware-first smart building retrofits over software-centric property management.
United States
Multifamily operators drive demand for automated lease management and iBuying transaction compression. The SEC's Regulation Crowdfunding shapes platform design through retail exposure caps and audited disclosure mandates. San Francisco and Austin clusters concentrate venture-backed proptech development, with valuation algorithm providers anchoring the iBuying segment.
Germany
Institutional landlords prioritize EU AI Act-compliant tenant screening with embedded explainability documentation. The Federal Financial Supervisory Authority operates regulatory sandboxes for blockchain-based property registry pilots. Berlin and Munich municipal authorities validate distributed ledger protocols for title verification and fractional ownership structures.
United Kingdom
Commercial real estate investors deploy digital twin technology for predictive maintenance and capital planning compression. The Financial Conduct Authority regulates crowdfunding platforms with disclosure requirements parallel to SEC frameworks. London's proptech cluster emphasizes open API architectures that unbundle previously integrated software suites for REIT procurement.
Netherlands
Municipal housing authorities mandate open API standards for property data interoperability, accelerating platform switching cycles. GDPR data minimization requirements elevate engineering costs for tenant screening purpose limitation. Amsterdam and Rotterdam institutional landlords pilot IoT-enabled HVAC and lighting retrofits to compress operational energy expenditure.
China
Smart city initiatives drive hardware-first deployment of IoT sensor networks for building environmental optimization. The Ministry of Industry and Information Technology governs data localization requirements for property management platforms. Shenzhen and Shanghai clusters concentrate manufacturing capacity for smart lock and sensor hardware dependent on domestic semiconductor foundry supply.
Proptech Market Key Industry Players
Capability concentration sits with specialized compliance and data analytics vendors; scale advantage sits with integrated platform operators spanning transaction and management layers. The market structures around three tiers: data monopolists sustaining pricing power through listing control, iBuying specialists compressing transaction timelines through captive valuation algorithms, and compliance-first vendors capturing premium positioning in EU-regulated deployments. Dominant competitive moves include strategic partnerships with institutional landlords for pilot validation and geographic expansion through regulatory sandbox participation.
Within the data monopolist tier, CoStar Group occupies a position exemplifying listing-driven analytics pricing power. Opendoor and Altus Group represent contrasting archetypes—transaction velocity compression versus investment-grade data services for institutional capital deployment. These three entities anchor the competitive landscape without exhausting its structural diversity, as specialized compliance vendors and blockchain registry pilots occupy adjacent positioning.
| Leading Market Players |
|---|
| CoStar Group |
| Opendoor |
| Altus Group |
| Crexi |
| Pacaso |
| Casavo |
| Propy |
| Engrain |
| Metropolis Technologies |
| Others |
Cost & Logistics Intelligence
Semiconductor supply concentration in Asian foundries determines both pricing tier spreads and supply chain shape across hardware-dependent proptech segments. IoT sensor and smart lock manufacturers absorb input volatility through extended inventory positions, while software vendors escape this exposure entirely.
Pricing Analysis
German institutional landlords pay 15-25% premiums for EU AI Act-compliant tenant screening platforms versus standard deployments. Three-tier pricing structure across premium, standard, and economy levels segments by certification depth and audit-readiness. Cost compression in economy-tier property management software intensifies as open API mandates accelerate platform switching. Small multifamily operators exhibit highest price sensitivity; cross-border institutional investors prioritize compliance certification over unit cost.
Supply Chain Analysis
Extended payment terms from 60 to 90 days dominate procurement relationships between smart building hardware vendors and institutional landlords. Semiconductor inputs draw from Taiwan, South Korea, and China; cloud infrastructure rests on hyperscaler capacity concentrated in Ireland, Germany, and the Netherlands. Single-source vulnerability concentrates in advanced sensor fabrication for HVAC optimization. Distribution runs through systems integrators serving REIT procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
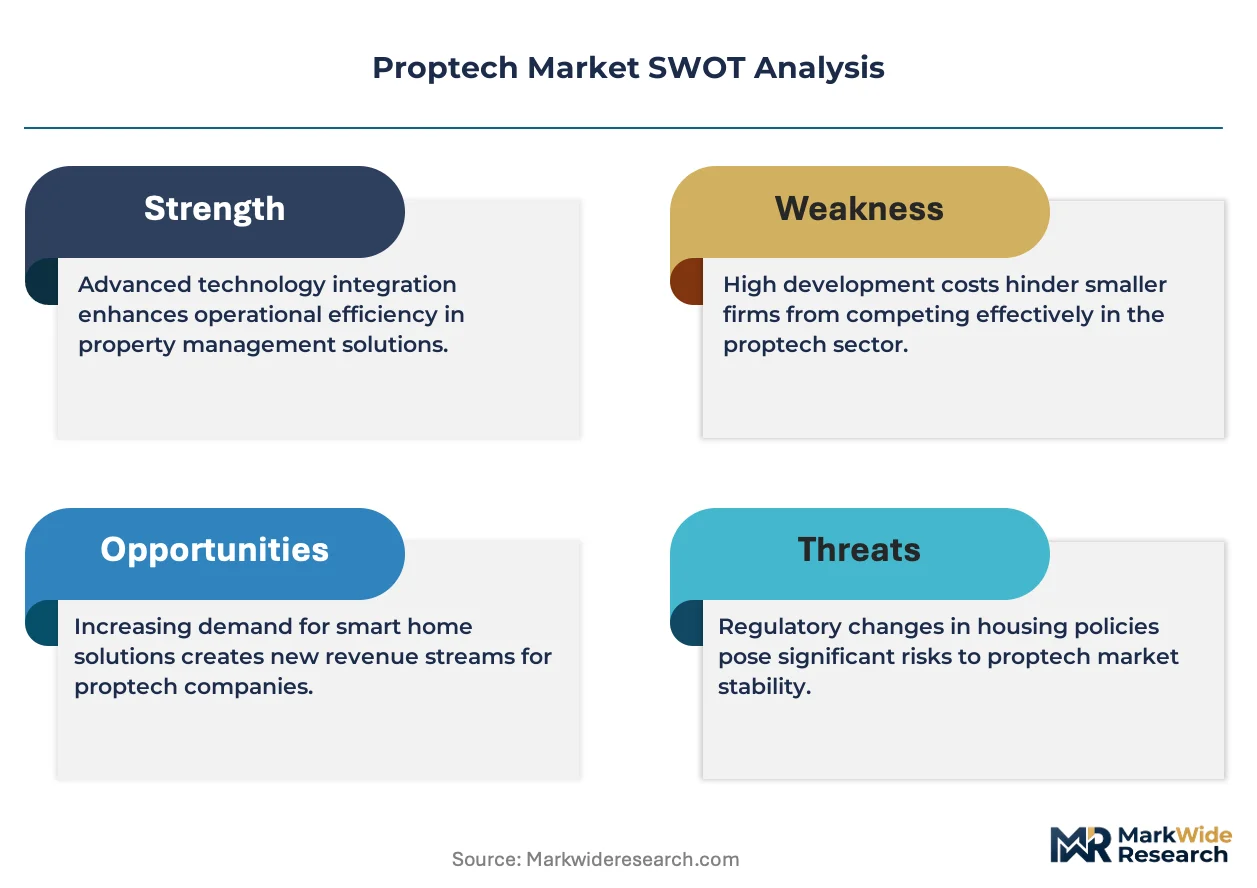
Proptech incumbents face substitution pressure from embedded finance platforms that unbundle payment processing from property management workflows. Defense requires structural repositioning around compliance and data network effects.
For Market Incumbents: Entrench switching costs through deeper tenant data histories and embedded payment processing lock-in. Acquire specialized EU AI Act compliance engineering teams ahead of certified audit framework mandates. Vertical integration into IoT firmware development defends against hardware margin erosion from Asian foundry concentration.
For New Entrants and Emerging Players: Build out regulatory sandbox participation in Germany's Federal Financial Supervisory Authority blockchain registry pilots. Target Hamburg, Cologne, and Frankfurt multifamily markets where proptech penetration trails Berlin despite comparable housing stock. Lead with open API architectures that unbundle incumbent software suites for Dutch municipal housing authority procurement.
For Investors and Strategic Acquirers: The market sits at a compliance-infrastructure buildout phase that favors specialized audit-ready platform vendors. Five-to-ten year viability hinges on EU AI Act implementation depth across member states. Acquisition target archetype: compliance-first vendors with embedded explainability documentation for tenant screening. Monitor divergence in national AI governance implementations as inflection signal for product standardization fragmentation.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Sandbox Participation | Germany's BaFin permits controlled blockchain registry testing that accelerates validation timelines. |
| Compliance-by-Design Platform Development | Embedded EU AI Act explainability captures premium positioning in French and German deployments. |
| Open API Architecture Deployment | Netherlands municipal mandates accelerate REIT procurement unbundling of integrated software suites. |
| IoT Edge Computing Convergence | On-device processing for access control reduces cloud dependency for industrial real estate operators. |
| Secondary City Geographic Expansion | Hamburg and Cologne exhibit whitespace for platform penetration despite comparable multifamily stock. |
Research Approach
Operator-level perspectives from property management executives, institutional landlord asset managers, proptech platform engineers, and municipal housing authority procurement officers anchored the qualitative base. Secondary validation drew from SEC Regulation Crowdfunding filings, EU AI Act implementation guidance, German Federal Financial Supervisory Authority sandbox documentation, and hyperscaler cloud infrastructure disclosures. Bottom-up deployment estimates triangulated against top-down market sizing across software, hardware, and data platform segments.
Scenario-bracketing framed projections across base, accelerated, and constrained adoption pathways. Segmentation dimensions modeled include product architecture, service application focus, end-user procurement authority, and technology maturity curve. CAGRs derived from installed base growth rates, replacement cycle compression, and regulatory compliance-driven upgrade demand. Blockchain registry pilot expansion and EU AI Act enforcement intensity served as primary forecast sensitivity inputs throughout the projection horizon.
Stress conditions across semiconductor supply disruption, GDPR enforcement escalation, and crowdfunding platform regulatory revision were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about compliance timeline adherence and institutional procurement pattern continuity. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Japan Office Real Estate Market
Real Estate
United States Luxury Residential Real Estate Market
Real Estate
UK Facility Management Market
Real Estate
Spain Condominiums and Apartments Market
Real Estate
Mexico Facility Management Market
Real Estate
Japan Manufactured Homes Market
Real Estate
Bahrain Co-Working Office Space Market
Real Estate
Green/Intelligent Buildings Market
Real Estate
Shopping Centers Market
Real Estate
Vietnam Commercial Real Estate Market
Real Estate
North America Soft Facility Management Market
Real Estate
India Residential Construction Market
Real Estate
Europe Luxury Residential Real Estate Market
Real Estate
Global Condominiums and Apartments Market
Real Estate
Malaysia Real Estate Market
Real Estate
ASEAN Manufactured Homes Market