
 Denmark Luxury Residential Real Estate Market | 2026-2036
Denmark Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Denmark Luxury Residential Real Estate Market Outlook
Property management and concierge service revenue is fragmenting across boutique operators and developer-affiliated platforms. Unika Ejendomme ApS leverages its Copenhagen portfolio to sustain premium leasing yields in prime districts. Rødgaard Ejendomme anchors its position through specialized waterfront property expertise along Zealand's coast. Zasa Ejendomme differentiates via integrated smart-home infrastructure across its developments.
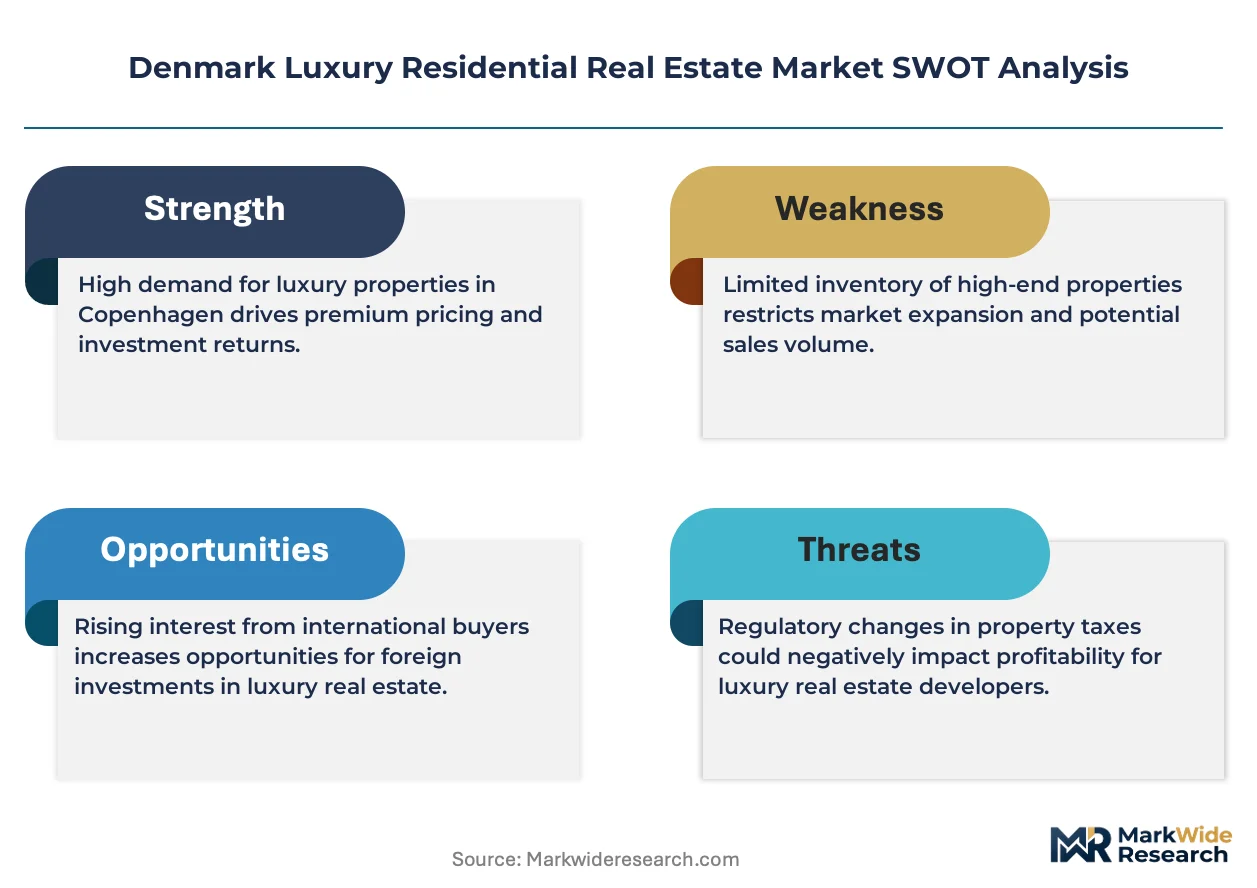
Denmark luxury residential real estate comprises freehold and cooperative dwellings priced above standard market thresholds, typically exceeding DKK 10 million, featuring premium materials such as oak flooring, natural stone, and bespoke joinery with thermal performance meeting BR18 energy frames. The primary commercial purpose centers on wealth preservation, lifestyle amenity, and generational asset transfer for domestic and cross-border principals. Detached houses and penthouses command the deepest margin pools where land scarcity and view premiums compound pricing power. The affordable luxury tier attracts first-time high-net-worth entrants, while ultra-luxury inventory in Hellerup and Charlottenlund remains supply-constrained. Smart home features and energy efficiency specifications increasingly function as baseline qualifying criteria rather than differentiators.
Danish Building Regulations administered by the Danish Transport and Construction Authority mandate stringent energy performance certificates and low-emission heating systems for new construction. The EU Taxonomy for sustainable activities shapes financing access, with Danish banks integrating green criteria into mortgage products for premium properties. Local municipal plans in Copenhagen, Frederiksberg, and Aarhus impose height restrictions and preservation designations that constrain developable supply. Stakeholders must monitor zoning amendments and energy retrofit mandates that could revalue existing stock against new-build competition.
Market Dynamics
Danish Building Regulations administered by the Danish Transport and Construction Authority are tightening envelope performance requirements for new luxury construction, compressing developable supply while elevating retrofit premiums for existing stock in Copenhagen's protected districts.
Growth Catalysts
- BR18 Energy Frame Mandates:Stricter thermal performance standards for new builds are accelerating demand for high-specification envelope retrofits in Østerbro and Frederiksberg, where heritage protections limit new supply.
- Cross-Border Principal Inflows:German and Swedish buyers are concentrating acquisition activity in Copenhagen's waterfront districts, drawn by relative value arbitrage against Stockholm and Hamburg prime markets.
- Smart-Home Infrastructure Integration:Zoning allowances for technology-dense developments in Greater Copenhagen are enabling integrated building management systems as baseline qualifying criteria rather than premium add-ons.
Market Restraints
- Height and Preservation Restrictions:Municipal plans in Copenhagen, Frederiksberg, and Aarhus impose strict zoning limitations that constrain vertical development and protect historic streetscapes, capping inventory expansion.
- Specialized Construction Labor Scarcity:Crafts capable of executing bespoke joinery and natural stone specification are concentrated among aging cohorts in Zealand, creating execution bottlenecks for ultra-luxury projects.
- Land Scarcity in Prime Districts:Developable plots in Hellerup and Charlottenlund face absolute physical constraints, forcing price premiums that exclude first-time high-net-worth entrants from core inventory.
Strategic Opportunities
- Energy Retrofit Value Capture:EU Taxonomy-aligned green mortgage products from Danish banks are creating financing advantages for properties meeting low-emission heating thresholds, revaluing existing stock against new-build competition.
- Cooperative-to-Freehold Conversion:Andelsbolig structures in emerging prime districts offer structural arbitrage for investors capable of navigating complex shareholder negotiations and municipal approval timelines.
- Concierge Service Platform Integration:Fragmentation across boutique property management operators creates white space for technology-enabled platforms bundling maintenance, security, and lifestyle services at portfolio scale.
Industry Challenges
- Heritage Compliance Complexity:Preservation designations in Copenhagen's historic core require specialized architectural review processes that extend development timelines and elevate professional indemnity exposure.
- Supply Chain Reconfiguration for Low-Carbon Materials:Sourcing certified oak flooring and natural stone meeting embodied carbon thresholds demands new supplier relationships and inventory management systems.
- Integration Friction with Legacy Building Systems:Smart-home infrastructure deployment in cooperative dwellings faces technical and governance barriers from existing electrical and data architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Denmark Luxury Residential Real Estate Market |
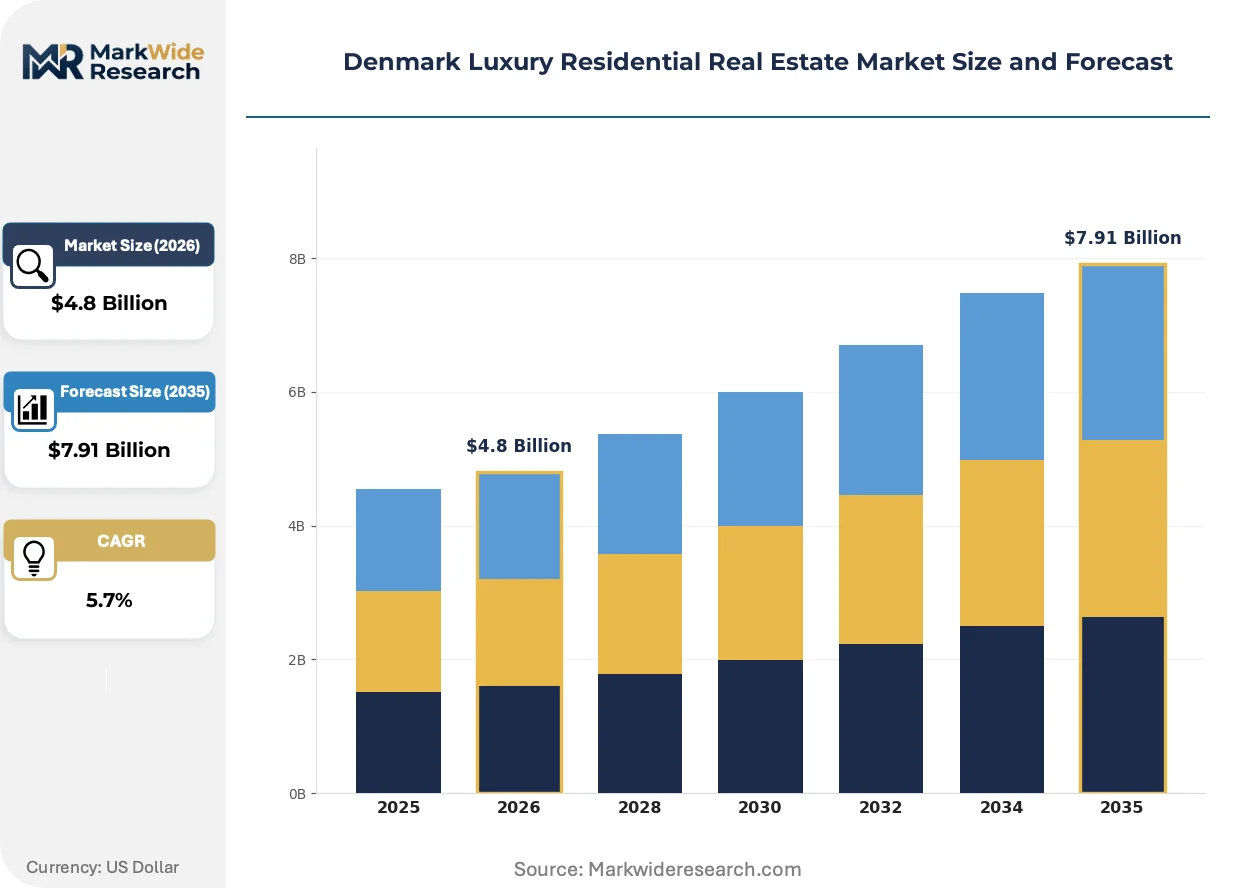
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Detached Houses, Apartments, Villas, Penthouses Price Tier: Affordable Luxury, Mid-Level Luxury, High-End Luxury, Ultra-Luxury Buyer Profile: Local Investors, International Buyers, Expats, Developers Property Features: Smart Home Features, Energy Efficiency, Waterfront Views, High Ceilings |
| Companies Covered | 1927 Estate, Unika Ejendomme ApS, Rødgaard Ejendomme, Zasa Ejendomme, NRE Group, Fink Ejendomme, Juvel Ejendomme, Kaj Ove Madsen A/S, Bruce Turner, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Denmark Luxury Residential Real Estate Market Strategic Shifts
Technology convergence and regulatory compression are restructuring how luxury residential assets are specified, financed, and operated across Denmark's prime districts.
Building-integrated photovoltaic and thermal storage systems are hybridizing traditional envelope functions with energy generation capabilities. Ultra-luxury developers in Charlottenlund are specifying these systems as standard, eliminating the distinction between architectural and mechanical design. This convergence is compressing consultant scopes and accelerating design-build integration timelines.
EU Taxonomy disclosure requirements administered under the Danish Financial Supervisory Authority are reshaping mortgage product architecture for premium properties. Banks must now classify green lending against technical screening criteria for sustainable activities. Copenhagen-based lenders are responding with differentiated rate products tied to energy performance certificates, shifting capital toward retrofit-ready inventory.
Cross-border principals are consolidating advisory relationships around single-family offices with dedicated Nordic real estate capabilities. Boutique Danish brokers and international wealth managers are displacing traditional agency relationships in transactions above DKK 25 million. This concentration is most visible in waterfront penthouse acquisitions where German buyers demand consolidated due diligence and post-closing property management services.
Denmark Luxury Residential Real Estate Market Segmentation
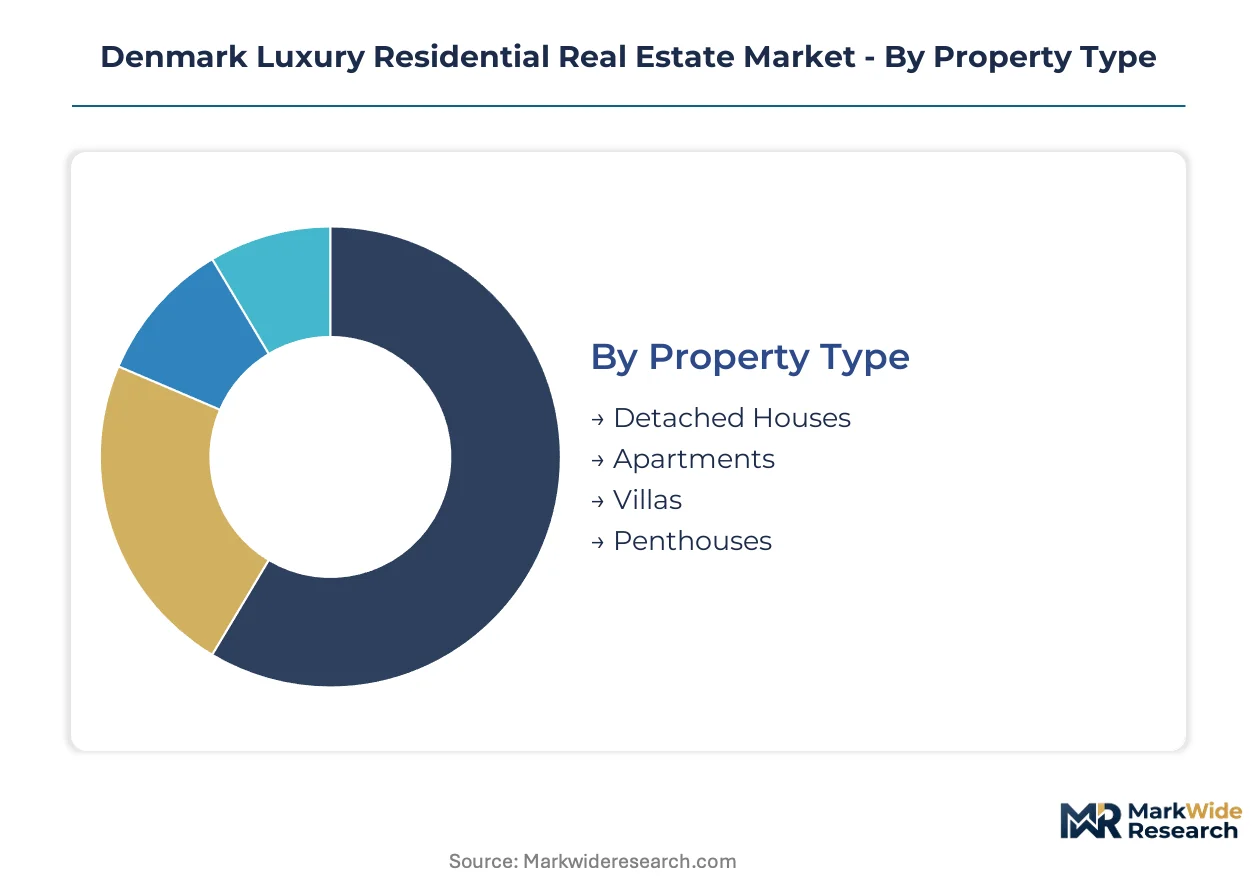
Denmark's luxury residential market segments along four intersecting dimensions that determine pricing power, buyer access, and development feasibility. Each category reflects distinct regulatory constraints and demand drivers specific to Copenhagen's constrained supply environment and cross-border capital flows.
Property Type:
The use-case spectrum spans generational wealth preservation through detached holdings to convenience-oriented urban apartments serving international principals.
- Detached Houses:Freehold structures on privately held land dominate Hellerup and Charlottenlund, where absolute scarcity of developable plots compounds pricing premiums. Danish Building Regulations BR18 mandates elevate construction costs, but completed stock commands the deepest margin pools among all property types.
- Apartments:Cooperative and condominium units concentrate in Østerbro and Frederiksberg, attracting German and Swedish buyers seeking relative value arbitrage against Stockholm and Hamburg prime markets. Heritage protections limit new supply, accelerating retrofit premiums for existing stock.
- Villas:Low-rise detached dwellings with garden plots cluster in Zealand's coastal municipalities, appealing to domestic family offices prioritizing privacy and outdoor amenity.
- Penthouses:Top-floor units with terrace access in Copenhagen's waterfront districts serve expatriate executives and cross-border investors requiring turnkey luxury with concierge infrastructure.
Established volume favors detached houses; emerging adoption favors penthouses.
Price Tier:
Cost stratification determines financing structure, buyer qualification thresholds, and competitive set within each sub-market.
- Affordable Luxury:Entry-level segment priced at DKK 10-15 million attracts first-time high-net-worth entrants and young professionals in Greater Copenhagen. EU Taxonomy-aligned green mortgage products from Danish banks create financing advantages for energy-certified stock in this bracket.
- Mid-Level Luxury:DKK 15-25 million range captures established domestic professionals and regional Nordic buyers. Properties typically feature smart-home infrastructure as baseline qualifying criteria rather than premium differentiation.
- High-End Luxury:DKK 25-40 million segment concentrates transaction activity from German family offices and Swedish industrial principals. Waterfront locations in Copenhagen harbor command persistent premiums.
- Ultra-Luxury:Inventory exceeding DKK 40 million remains supply-constrained in Hellerup and Charlottenlund, where land scarcity and view premiums compound absolute price levels. Bespoke joinery and natural stone specifications require specialized construction labor concentrated among aging cohorts in Zealand.
Transaction velocity concentrates in mid-level luxury; absolute margin expansion characterizes ultra-luxury.
Buyer Profile:
Customer type determines advisory relationship structures, due diligence complexity, and post-closing service requirements.
- Local Investors:Danish family offices and high-net-worth individuals prioritize generational asset transfer and wealth preservation. These buyers dominate cooperative-to-freehold conversion opportunities in emerging prime districts.
- International Buyers:German and Swedish principals are consolidating acquisition activity around single-family offices with dedicated Nordic real estate capabilities. Boutique Danish brokers are displacing traditional agency relationships in transactions above DKK 25 million.
- Expats:Corporate executives on temporary assignment drive demand for furnished turnkey apartments in Frederiksberg and Østerbro with integrated property management services.
- Developers:Construction firms and development platforms acquire land positions and existing structures for repositioning, navigating complex municipal approval timelines and heritage compliance requirements.
Local investors anchor transaction volume; international buyers are expanding most quickly.
Property Features:
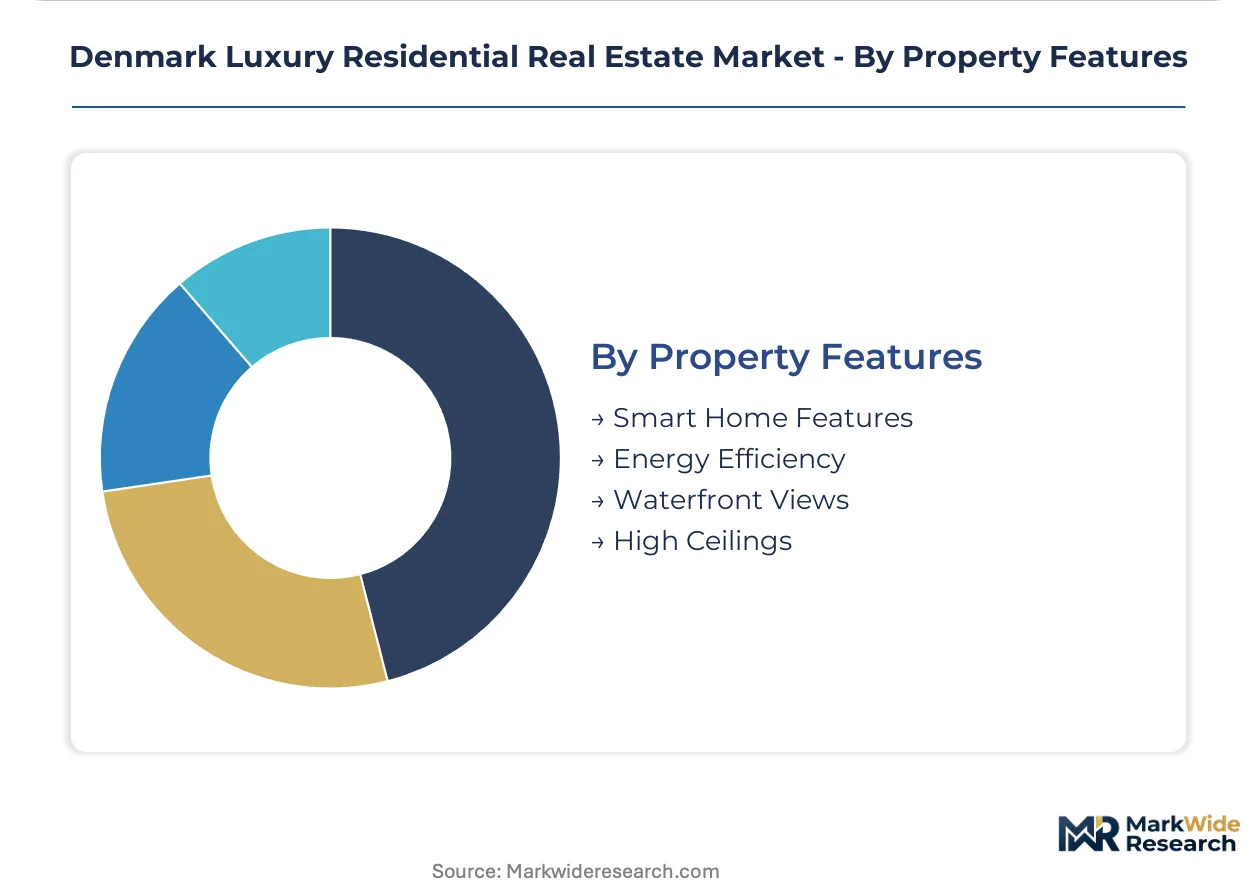
Specification differentiation increasingly functions as market access threshold rather than premium positioning.
- Smart Home Features:Integrated building management systems and automated controls are shifting from premium add-on to baseline qualifying criteria. Zoning allowances for technology-dense developments in Greater Copenhagen enable seamless deployment.
- Energy Efficiency:BR18 energy frame mandates and EU Taxonomy disclosure requirements administered under the Danish Financial Supervisory Authority are reshaping mortgage product architecture. Low-emission heating thresholds revalue existing stock against new-build competition.
- Waterfront Views:Harbor and coastal sightlines command persistent premiums in Copenhagen's waterfront districts, where height restrictions protect historic streetscapes and limit inventory expansion.
- High Ceilings:Spatial volume specifications in pre-war stock appeal to buyers prioritizing architectural character, though preservation designations extend development timelines and elevate professional indemnity exposure.
Energy efficiency dominates financing access; waterfront views sustain pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Developable land in Greater Copenhagen concentrates transaction velocity and pricing power, while Zealand's coastal municipalities and Aarhus anchor secondary demand clusters. The Danish Transport and Construction Authority administers BR18 energy frame mandates that revalue existing stock against new-build competition.
Greater Copenhagen
Waterfront districts in Østerbro and Frederiksberg attract German and Swedish buyers seeking relative value arbitrage against Stockholm and Hamburg prime markets. Municipal height restrictions and preservation designations protect historic streetscapes while capping inventory expansion. Heritage compliance requirements extend development timelines and elevate professional indemnity exposure for repositioning projects.
Hellerup and Charlottenlund
Ultra-luxury inventory exceeding DKK 40 million faces absolute land scarcity that compounds view premiums and pricing power. Bespoke joinery and natural stone specifications demand specialized construction labor concentrated among aging cohorts in Zealand. Freehold detached structures on privately held land dominate this sub-market, serving domestic family offices prioritizing generational wealth preservation.
Zealand Coastal Municipalities
Villas with garden plots appeal to domestic buyers prioritizing privacy and outdoor amenity outside Copenhagen's urban core. Local municipal plans impose design restrictions that protect coastal character while limiting developable supply. Specialized waterfront property expertise anchors competitive positioning for developers active along this corridor.
Aarhus
Denmark's second city attracts regional Nordic buyers and expatriate executives requiring turnkey luxury with integrated property management services. University and healthcare sector employment stabilizes demand for mid-level luxury apartments. Zoning allowances for technology-dense developments enable smart-home infrastructure as baseline qualifying criteria.
Frederiksberg
Cooperative and condominium structures concentrate in this independent municipality surrounded by Copenhagen, offering entry points for first-time high-net-worth entrants. EU Taxonomy-aligned green mortgage products from Danish banks create financing advantages for energy-certified stock. Cooperative-to-freehold conversion opportunities attract local investors capable of navigating complex shareholder negotiations.
Denmark Luxury Residential Real Estate Market Competitive Environment
Boutique developers and integrated property platforms split the market between specialized craftsmanship and technology-enabled scale. Copenhagen-based operators dominate prime district transactions through localized regulatory expertise and municipal relationships. Three archetypes define competitive positioning: heritage-specialized developers, smart-home integrators, and cooperative conversion specialists. Portfolio diversification into concierge services and energy retrofit capabilities represents the dominant competitive move, followed by selective land banking in supply-constrained sub-markets.
Within the boutique developer tier, Unika Ejendomme ApS and Rødgaard Ejendomme exemplify distinct specialization vectors. Unika Ejendomme ApS occupies a position tied to premium leasing yield capture in Copenhagen's prime districts, while Rødgaard Ejendomme anchors its market presence through waterfront property expertise along Zealand's coast. Zasa Ejendomme represents the technology-forward archetype, with integrated smart-home infrastructure deployment across its development portfolio. These three operators collectively illustrate how regulatory compression and buyer specification demands are forcing capability diversification beyond traditional development functions.
| Leading Market Players |
|---|
| 1927 Estate |
| Unika Ejendomme ApS |
| Rødgaard Ejendomme |
| Zasa Ejendomme |
| NRE Group |
| Fink Ejendomme |
| Juvel Ejendomme |
| Kaj Ove Madsen A/S |
| Bruce Turner |
| Others |
Value Chain & Pricing Dynamics
Zealand's coastal construction labor pool constrains ultra-luxury project delivery, concentrating pricing power with developers holding captive relationships with specialized joinery and natural stone craftsmen. BR18 energy frame mandates elevate material specification costs while compressing developable supply, forcing price premiums that cascade through Copenhagen's protected districts.
Pricing Analysis
Danish Building Regulations administered by the Danish Transport and Construction Authority dictate the pricing tier structure across Denmark's luxury residential market. Premium-mid-economy pricing differentiation separates freehold detached houses in Hellerup from cooperative apartments in Frederiksberg and entry-level inventory in emerging districts. Price differentiation rests on energy performance certification levels and waterfront view premiums rather than baseline smart-home specifications. Cost compression in the affordable luxury tier is intensifying because EU Taxonomy-aligned green mortgage products from Danish banks favor certified stock. First-time high-net-worth entrants exhibit highest price sensitivity, while German family offices acquiring above DKK 25 million demonstrate minimal elasticity.
Supply Chain Analysis
EU export-control regimes on embodied carbon certification systems limit flows of verified low-carbon building materials into Danish construction channels. Supply concentration centers on Germany for engineered oak flooring, Italy for natural stone, and domestic Zealand producers for bespoke joinery. Raw material dependencies encompass certified timber meeting BR18 thermal performance thresholds, quarried limestone for facade specification, and copper for low-emission heating infrastructure. Single-source vulnerability runs through aging craftsman cohorts capable of executing ultra-luxury specifications. Distribution feeds from specialized importer networks through Copenhagen-based developer procurement offices to project sites across Greater Copenhagen.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Denmark's luxury residential market approaches a platform-economics inflection as integrated property management systems consolidate fragmented concierge services and energy retrofit capabilities into unified buyer interfaces.
For Market Incumbents: Pre-empt cooperative-to-freehold conversion arbitrage by securing municipal pre-approval pathways in Frederiksberg and Østerbro before regulatory compression tightens shareholder negotiation frameworks. Anchor vertical integration into specialized construction labor pools across Zealand to defend margin position against execution bottlenecks. Threat concentration sits with technology-enabled entrants bundling maintenance, security, and lifestyle services at portfolio scale. For New Entrants and Emerging Players: Pursue white-space capture in concierge service platform integration, where fragmentation across boutique operators creates technology-enabled consolidation opportunities. Energy retrofit value capture in BR18-mandated districts offers the most penetrable segment, given financing advantages from EU Taxonomy-aligned green mortgage products. Go-to-market execution should anchor on municipal relationship velocity for heritage compliance navigation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among developers with integrated property management platforms and captive leasing yield streams in Copenhagen's prime districts. Long-term viability across the projection horizon favors acquisition targets combining land banking in supply-constrained sub-markets with energy retrofit execution capabilities. The signal to monitor is municipal zoning amendments that revalue existing stock against new-build competition.| Strategic Initiative | Industry Significance |
|---|---|
| Energy Retrofit Platform Integration | EU Taxonomy disclosure requirements from the Danish Financial Supervisory Authority revalue certified stock against new-build competition. |
| Cooperative-to-Freehold Conversion Pipeline | Andelsbolig structural arbitrage in Frederiksberg leverages complex shareholder negotiation capabilities for yield expansion. |
| Specialized Labor Pool Captive Arrangements | Aging Zealand craftsman cohorts create execution bottlenecks that developers with anchored relationships can monetize. |
| Smart-Home Infrastructure Standardization | Zoning allowances for technology-dense developments in Greater Copenhagen enable seamless building management system deployment. |
| Waterfront Land Banking in Charlottenlund | Absolute land scarcity compounds view premiums and pricing power for ultra-luxury inventory exceeding DKK 40 million. |
Study Parameters
A spread of perspectives from property development executives, municipal planning officers, heritage compliance architects, and mortgage product specialists at Copenhagen-based lenders converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against Danish Building Regulations filings, EU Taxonomy technical screening criteria disclosures, and municipal zoning plan amendments. Bottom-up transaction analysis across price tiers triangulated with top-down macroeconomic indicators to establish market sizing and growth trajectory parameters.
Demand-supply balance modeling anchored the forecast framework across the analysis window, with segmentation dimensions spanning property type, price tier, buyer profile, and energy performance specification. CAGRs derived from regression analysis of historical transaction velocity against regulatory compression timelines and cross-border capital flow patterns. Industry-specific inputs encompassed BR18 energy frame compliance cost curves and German family office acquisition appetite indices.
Sensitivities concentrate around municipal zoning amendments, energy retrofit mandate timelines, and cross-border principal sentiment shifts. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and craftsman labor pool stability. Material shifts in EU Taxonomy technical screening criteria or Danish Building Regulations energy performance thresholds would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
Oman Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Europe Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Sweden Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Belgium Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
United States Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Bahrain Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Japan Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Switzerland Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Netherlands Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
India Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Australia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Saudi Arabia Luxury Market
Luxury Residential Real Estate Market
South Korea Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
UAE Luxury Residential Real Estate Market