
 GCC REIT Market | 2026-2036
GCC REIT Market Size, Share, and Industry Trends Forecast 2026-2036
GCC REIT Market Insights
REIT eligibility under Shariah-compliant AAOIFI standards is rotating access to GCC capital pools, favoring sponsors with established Islamic finance credentials. Al Rajhi REIT leverages its banking parentage to dominate Saudi retail distribution. Emirates REIT (CEIC) anchors the UAE commercial segment through concentrated Dubai office exposure. Jadwa REIT Saudi Fund differentiates via development-stage risk positioning in Riyadh logistics corridors.
A Real Estate Investment Trust pools capital to acquire, operate, or finance income-producing property portfolios, distributing at least 90% of taxable income to unit holders while maintaining leverage ratios typically capped at 50% of gross asset value under GCC regulatory frameworks. Equity REITs sustain the deepest liquidity pools across Gulf exchanges, while Mortgage REITs occupy a narrower niche given regional banks' preference for direct property lending. Value-Add strategies concentrate investor attention where rental reversion potential intersects with construction cost inflation in Saudi giga-project zones.
Saudi Capital Market Authority REIT rules and UAE SCA listing requirements shape sponsor behavior through mandatory independent valuations, quarterly disclosure cycles, and leverage ceiling enforcement. The UAE Central Bank's macro-prudential filters and Qatar Financial Centre regulatory frameworks further calibrate cross-border capital mobility. Stakeholders must monitor how Oman and Bahrain introduce REIT-specific legislation, as regulatory arbitrage opportunities compress across the six-member bloc.
Market Dynamics
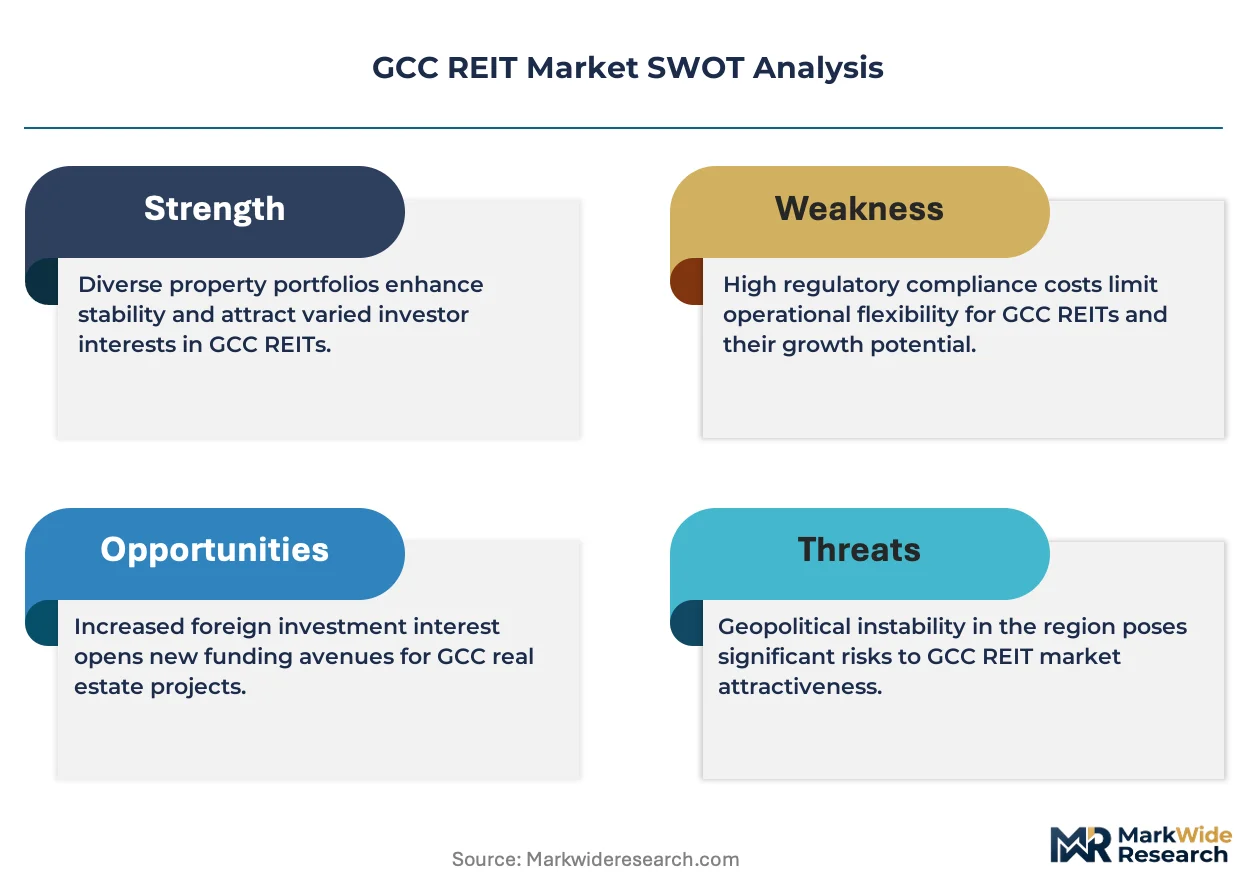
Regulatory convergence across Gulf exchanges is compressing sponsor compliance costs while amplifying disclosure burdens, forcing smaller REITs toward consolidation or specialized niche positioning.
Growth Catalysts
- Capital Market Authority listing rules:Saudi Arabia's tightened disclosure standards attract institutional capital seeking transparency, expanding the investable universe for cross-border allocators.
- Giga-project adjacency:Logistics portfolios proximate to NEOM and Red Sea developments command rental premiums as construction-phase demand concentrates in Riyadh and Jeddah corridors.
- Islamic finance credentialing:AAOIFI Shariah-compliant structures unlock access to GCC sovereign wealth pools and retail distribution networks previously inaccessible to conventional vehicles.
Market Restraints
- Construction cost volatility:Steel and cement input inflation erodes development-stage IRRs for value-add sponsors targeting Riyadh logistics corridors.
- Bank lending concentration:Regional commercial banks prefer direct property exposure over Mortgage REIT paper, constraining debt capital market depth.
- Leverage ceiling enforcement:UAE Securities and Commodities Authority caps at 50% of gross asset value limit acquisition capacity during competitive bidding cycles.
Strategic Opportunities
- Oman and Bahrain legislative gaps:Regulatory arbitrage windows persist as these jurisdictions draft REIT-specific frameworks, offering first-mover positioning for established Saudi and UAE sponsors.
- Technology-REIT convergence:Data center and telecommunications tower assets intersect with traditional property portfolios, creating hybrid vehicle structures.
- Retail distribution innovation:Digital onboarding platforms reduce minimum investment thresholds, expanding unit holder bases beyond traditional high-net-worth channels.
Industry Challenges
- Valuation specialist scarcity:Mandatory independent appraisals under Saudi and UAE rules outstrip qualified local capacity, extending IPO timelines.
- Legacy system integration:Sponsor back-office platforms require costly adaptation to meet quarterly disclosure cycles and real-time NAV reporting demands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC REIT Market |
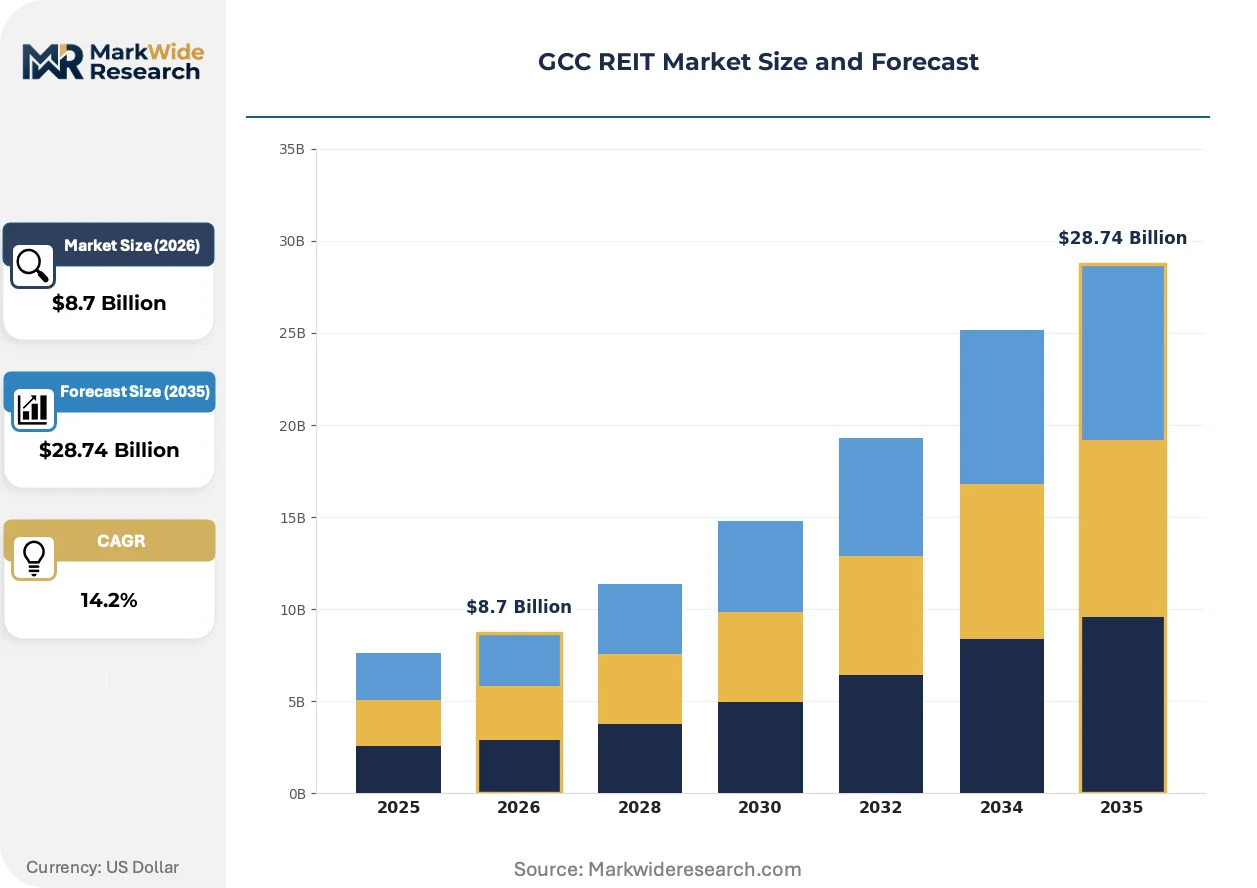
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fund Structure: Equity REITs, Mortgage REITs, Hybrid REITs, Private REITs Investment Stage: Development, Stabilized, Value-Add, Opportunistic Property Type: Residential, Commercial, Industrial, Healthcare Investor Type: Institutional, Retail, Family Office, High-Net-Worth |
| Companies Covered | Musharaka REIT, Al Rajhi REIT, Jadwa REIT Saudi Fund, Ezdan REIT, Riyad REIT, Emirates REIT (CEIC), Sedco Capital REIT, Alkhabeer REIT, ENBD REIT, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC REIT Market Trends and Innovations
Digital infrastructure is penetrating income-producing property portfolios, altering tenant mix calculations and capex allocation frameworks across Gulf exchanges.
Smart building management systems are fragmenting traditional property operations into technology-enabled service layers. Logistics and office sponsors in Dubai and Riyadh deploy IoT-enabled energy optimization at accelerating pace. This capability compression is fragmenting competitive differentiation between institutional-grade and mid-tier sponsors.
UAE Central Bank macro-prudential filters now extend stress-testing requirements to REIT leverage structures, not just direct bank exposures. Industrial consequence includes tighter covenant negotiation and accelerated amortization schedules for highly leveraged vehicles. Dubai office-focused vehicles face the most pronounced refinancing timeline compression.
Institutional procurement of stabilized assets is rotating toward shorter-dated hold periods with explicit value-add exit triggers. Family office and sovereign wealth direct allocations are displacing traditional fund-of-fund intermediation in Saudi retail and logistics segments. This channel compression is most visible in Riyadh giga-project corridor transactions.
GCC REIT Market Segmentation
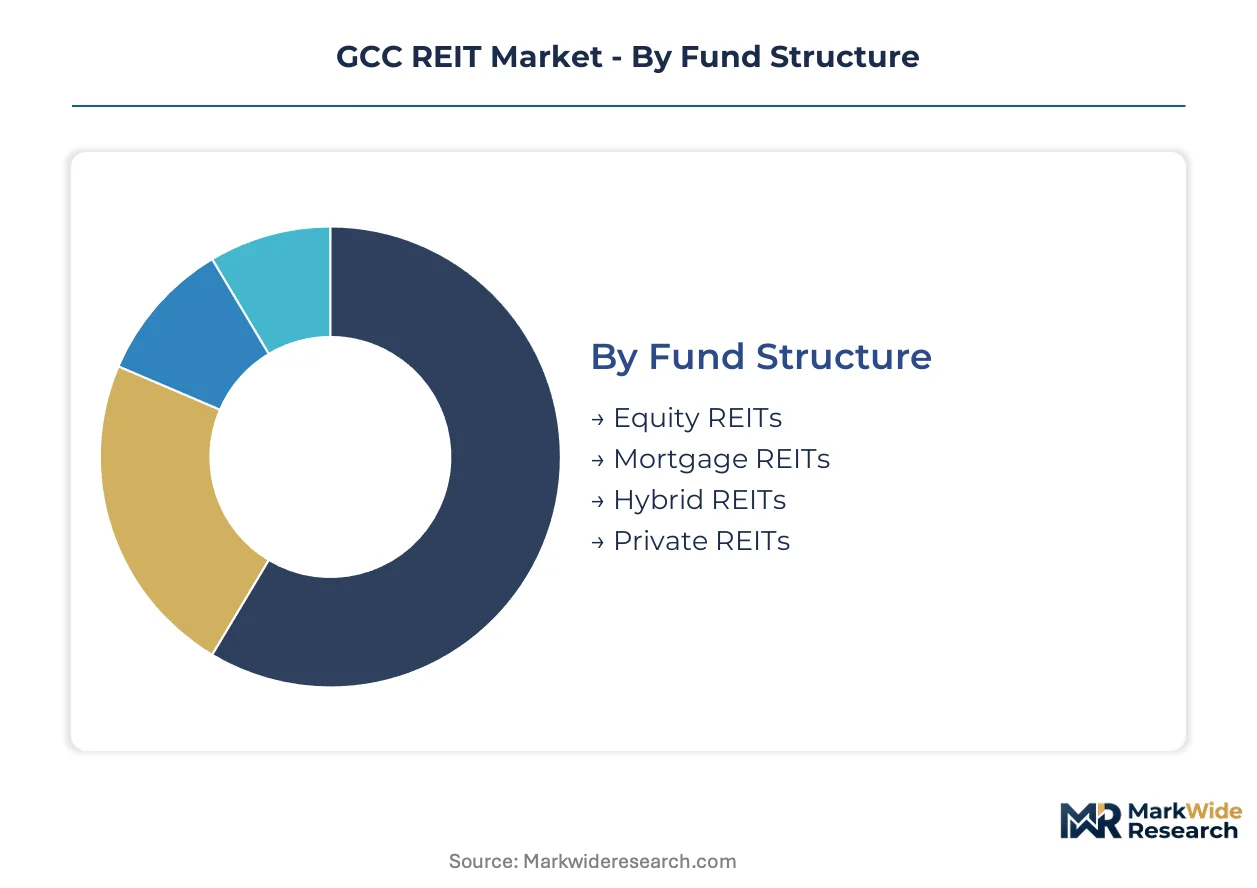
REIT segmentation in the GCC reveals how capital flows through distinct risk-return profiles. Sponsor structuring decisions determine distribution channel access, regulatory treatment, and investor eligibility across Saudi, UAE, and emerging Gulf markets.
Fund Structure:
Channel-mix dynamics concentrate liquidity in exchange-listed vehicles while private placements serve specialized sovereign and family office mandates.
- Equity REITs:Direct property ownership vehicles dominate Tadawul and DFM trading volumes. Saudi Capital Market Authority listing rules require quarterly NAV disclosure, attracting institutional flows from Riyadh-based pension funds and Kuwaiti cross-border allocators seeking yield visibility.
- Hybrid REITs:Blended equity-debt exposure captures development-stage IRR premiums alongside stabilized income. Dubai sponsors deploy this structure for giga-project corridor logistics assets where construction-phase risk intersects with long-dated lease profiles.
- Mortgage REITs:Constrained by regional bank preference for direct property lending rather than securitized paper. Narrow distribution runs through specialized Islamic finance channels in Bahrain and specialized debt funds.
- Private REITs:Unlisted vehicles serve Qatari sovereign wealth direct allocation and Saudi family office consolidation plays. Exempt from public disclosure, these structures target bespoke leverage profiles and hold-period flexibility unavailable in listed formats.
By volume, Equity REITs lead. By growth pace, Hybrid REITs are expanding most quickly.
Investment Stage:
Risk tiering aligns capital deployment with construction cycle positioning across Saudi giga-project zones and Dubai's mature commercial corridors.
- Value-Add:Active repositioning of underperforming assets drives sponsor fee structures and promotes carried interest. Riyadh logistics sponsors target rental reversion where construction-phase tenant demand outstocks existing supply.
- Stabilized:Core-plus income profiles dominate UAE institutional mandates. Dubai office and Abu Dhabi retail assets trade at compressed cap rates through Emirates NBD and FAB distribution networks.
- Development:Greenfield exposure concentrates in NEOM-adjacent industrial and Red Sea tourism corridors. Saudi Capital Market Authority leverage ceilings constrain pure development vehicles, favoring joint-venture structures with sovereign development funds.
- Opportunistic:Distressed and special-situation deployment remains limited by shallow default cycles in Gulf property markets. Occasional activation follows developer liquidity stress in Dubai's secondary locations.
Stabilized assets anchor institutional commitment. Value-Add vehicles show steepest expansion trajectory as sponsors chase giga-project rental premiums.
Property Type:
Asset class selection determines Shariah compliance pathways and AAOIFI structuring complexity for Gulf distribution.
- Industrial:Logistics and warehousing command allocation priority from Saudi Public Investment Fund co-investment vehicles. E-commerce fulfillment demand concentrates in Jeddah Islamic Port and Dubai South free zone corridors.
- Commercial:Grade-A office exposure dominates UAE REIT market capitalization. Dubai International Financial Centre and Abu Dhabi Global Market assets trade through retail brokerage channels with minimum thresholds.
- Residential:Restricted income streams under Saudi and UAE tenancy frameworks limit REIT eligibility. Purpose-built rental housing experiments in Riyadh's Diriyah Gate and Dubai Hills represent emerging test cases.
- Healthcare:Specialized medical facility exposure attracts long-dated capital from Kuwaiti insurance-linked pools. MOHAP licensing requirements and SFDA operational standards impose compliance layers distinct from conventional property management.
Industrial assets lead by capital deployment velocity. Healthcare properties gain share fastest through liability-matching mandates.
Investor Type:
Capital source segmentation dictates minimum thresholds, redemption terms, and regulatory reporting intensity for sponsor platforms.
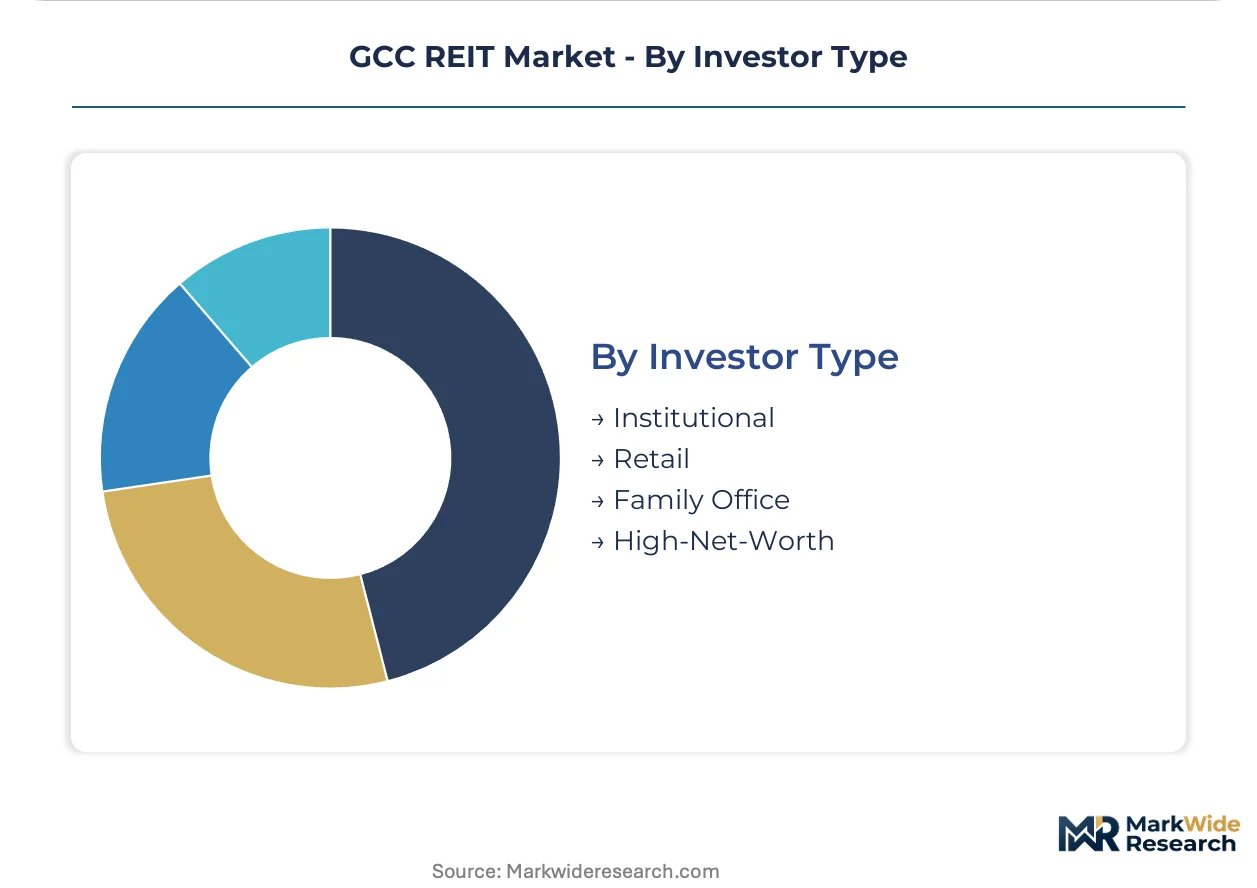
- Institutional:Pension funds and insurance reserves anchor liquidity through Tadawul-listed vehicles. Saudi Social Insurance Organization and UAE-based Emirates Investment Authority concentrate flows in stabilized, AAOIFI-compliant structures.
- Family Office:Direct allocation displaces fund-of-fund intermediation in Riyadh retail and logistics segments. Shorter hold periods and explicit value-add exit triggers differentiate family office mandates from institutional buy-and-hold profiles.
- Retail:Digital onboarding platforms and fractional unit structures expand accessibility beyond traditional high-net-worth thresholds. Al Rajhi Bank distribution networks dominate Saudi retail penetration.
- High-Net-Worth:Individual allocation concentrates in Dubai private banking channels. Minimum ticket sizes and lock-up preferences align with opportunistic and development-stage exposure.
Institutional capital anchors by committed volume. Family Office allocation is climbing the fastest as direct investment platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's Capital Market Authority listing rules attract cross-border institutional flows seeking Shariah-compliant yield visibility. UAE Securities and Commodities Authority disclosure standards compress compliance costs for Dubai and Abu Dhabi sponsors. Qatar Financial Centre frameworks and Bahrain's emerging legislation calibrate capital mobility across the six-member bloc.
Saudi Arabia
NEOM-adjacent logistics corridors and Red Sea tourism developments concentrate construction-phase tenant demand. The Capital Market Authority mandates quarterly NAV disclosure and 50% leverage ceilings for listed vehicles. Riyadh and Jeddah sponsor platforms dominate Tadawul trading volumes through AAOIFI-compliant structures.
United Arab Emirates
Dubai International Financial Centre and Abu Dhabi Global Market assets trade at compressed cap rates through retail brokerage networks. The Securities and Commodities Authority enforces independent valuation standards and real-time reporting protocols. Emirates NBD and FAB distribution channels anchor UAE commercial segment liquidity.
Qatar
Sovereign wealth direct allocation displaces traditional fund-of-fund intermediation in stabilized asset procurement. Qatar Financial Centre regulatory frameworks govern cross-border capital mobility and Shariah compliance pathways. Doha-based sponsors concentrate on healthcare and logistics portfolios serving FIFA legacy infrastructure.
Kuwait
Insurance-linked capital pools seek long-dated liability-matching exposure in medical facility and industrial assets. The central bank's macro-prudential filters extend stress-testing requirements to REIT leverage structures. Cross-border allocators channel flows through Tadawul-listed vehicles rather than domestic exchange development.
Bahrain
Specialized Islamic finance channels distribute Mortgage REIT paper excluded from conventional Saudi and UAE markets. Draft REIT-specific legislation offers regulatory arbitrage windows for established Gulf sponsors. Manama-based structures serve niche debt-fund mandates alongside conventional banking preferences for direct property exposure.
GCC REIT Market Competitive Landscape
Listed leaders compete with private specialists across distribution channel access and Shariah credentialing depth. Saudi Tadawul and UAE DFM listings concentrate liquidity in equity REITs with quarterly disclosure compliance, while private placements serve Qatari sovereign and Saudi family office mandates with bespoke leverage profiles. Three archetypes dominate: banking-parentage sponsors with retail network penetration, development-stage specialists targeting giga-project corridors, and stabilized-asset managers with institutional pension fund relationships. Competitive moves concentrate on portfolio diversification into data center and telecommunications tower hybrids, alongside digital onboarding platforms that reduce minimum investment thresholds.
Within the banking-parentage tier, Al Rajhi REIT leverages its Saudi retail distribution dominance, while Emirates REIT anchors UAE commercial exposure through Dubai office concentration. Jadwa REIT Saudi Fund occupies the development-stage specialist position, targeting Riyadh logistics corridors with construction-phase risk positioning. These three exemplify how sponsor origin and channel control determine capital access across the Gulf exchange landscape.
| Leading Market Players |
|---|
| Musharaka REIT |
| Al Rajhi REIT |
| Jadwa REIT Saudi Fund |
| Ezdan REIT |
| Riyad REIT |
| Emirates REIT (CEIC) |
| Sedco Capital REIT |
| Alkhabeer REIT |
| ENBD REIT |
| Others |
Pricing and Supply Chain Analysis
AAOIFI Shariah compliance certification gates both sponsor qualification and investor access pricing simultaneously, compressing fee structures for conventional vehicles while enabling premium distribution margins for credentialed Islamic finance platforms. This dual-gate mechanism concentrates pricing power among established Gulf banking-parentage sponsors with embedded retail networks.
Pricing Analysis
Certification level (AAOIFI Shariah-compliant vs conventional) creates the primary spread between sponsor fee structures across Tadawul and DFM listings. Premium-mid-economy pricing differentiation runs through management fee tiers, with AAOIFI-compliant vehicles commanding 25-50 basis point spreads due to restricted investor pools and specialized distribution. Cost compression in conventional retail channels is intensifying because digital onboarding platforms reduce minimum thresholds and fragment intermediary control. Family office direct allocation shows least price sensitivity, while retail brokerage channels exhibit highest fee elasticity.
Supply Chain Analysis
Inventory cycles for independent valuation specialists extend IPO timelines by 8-14 weeks across Riyadh and Dubai sponsor pipelines. Geographic supply concentration clusters in Saudi Arabia, UAE, and Bahrain, with Manama-based Islamic finance channels serving niche debt-fund mandates. Raw material dependencies center on steel and cement input volatility, construction labor mobility, and qualified property appraiser scarcity. Single-source vulnerability sits with the four dominant valuation firms serving CMA and SCA disclosure requirements. Distribution runs through Tadawul and DFM exchange listings for liquidity, supplemented by private placement channels for Qatari sovereign and Saudi family office mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across the six-member Gulf bloc creates sponsor consolidation opportunities as compliance cost burdens disproportionately impact mid-tier platforms. Digital infrastructure penetration into property portfolios fragments traditional competitive moats, opening niches for technology-enabled entrants.
For Market Incumbents: Secure exclusive valuation firm relationships to compress IPO timelines and accelerate capital deployment cycles. Lock in AAOIFI certification maintenance through dedicated Shariah board retainers, insulating against emerging sponsor competition from Bahrain's regulatory arbitrage windows. Banking-parentage platforms should deepen captive distribution control before digital onboarding platforms fragment retail channel economics.
For New Entrants and Emerging Players: CMA fast-track disclosure approval processes in Saudi Arabia offer expedited listing pathways for sponsors with pre-qualified valuation partnerships. Target Oman and Bahrain legislative gaps before REIT-specific frameworks close arbitrage windows. White-space concentration sits in data center and telecommunications tower hybrid structures, where technology-REIT convergence has not yet attracted established Gulf sponsor platforms. Go-to-market positioning should anchor on explicit value-add exit triggers rather than institutional buy-and-hold profiles.
For Investors and Strategic Acquirers: UAE SCA leverage ceiling enforcement reshapes the acquisition landscape by constraining highly leveraged vehicles' competitive bidding capacity. Long-term viability favors sponsors with demonstrated sovereign wealth co-investment relationships and giga-project corridor asset positioning. Acquisition target archetype: development-stage specialists with NEOM-adjacent logistics pipelines and pre-negotiated construction-phase tenant commitments. Signal to watch: quarterly NAV disclosure variance as indicator of valuation specialist capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| AAOIFI Certification Maintenance | Retained Shariah board access preserves premium distribution margins through Al Rajhi and Emirates NBD retail networks. |
| Valuation Firm Exclusive Partnership | Locked-in appraisal capacity compresses CMA and SCA IPO timelines against competitor sponsor pipelines. |
| Data Center Asset Integration | Hybrid technology-property structures capture technology-REIT convergence premiums outside traditional competitive sets. |
| Oman/Bahrain First-Mover Positioning | Regulatory arbitrage windows offer sponsor licensing advantages before REIT-specific legislation closes gaps. |
| Digital Onboarding Platform Deployment | Fractional unit structures expand retail penetration beyond traditional high-net-worth minimum thresholds. |
Research Methodology
A standing panel of REIT sponsor executives, Shariah board scholars, Tadawul listing advisors, and CMA regulatory affairs specialists provided ongoing calibration against secondary validation from Saudi Capital Market Authority filings, UAE Securities and Commodities Authority disclosure registers, AAOIFI standards documentation, and Gulf exchange trading data. Bottom-up asset-level cash flow modeling triangulated against top-down macroeconomic scenario analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework segmented by fund structure, investment stage, property type, and investor archetype, with cross-dimensional interaction effects modeled for giga-project adjacency premiums and Shariah compliance pathway economics. CAGRs derived from rolling quarterly NAV trajectories and rental reversion assumptions, incorporating construction cost inflation indices and sovereign wealth co-investment flow patterns.
Decision-makers should treat outputs as directional under assumptions of sustained CMA and SCA regulatory tightening, stable AAOIFI interpretation consistency, and uninterrupted giga-project construction-phase tenant demand; material deviation in any base assumption would warrant model refresh. Specific risks include valuation specialist capacity bottlenecks, steel and cement input volatility, and Oman/Bahrain legislative timing uncertainty. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
India Integrated Facility Management Market
Real Estate
Middle East and Africa Soft Facility Management Market
Real Estate
Proptech Market
Real Estate
Global Property Restoration Software Market
Real Estate
Real Estate Market
Real Estate
Africa Facility Management Market
Real Estate
Chile Facility Management Market
Real Estate
Europe Real Estate Brokerage Market
Real Estate
Europe Flexible Office Market
Real Estate
Canada Hospitality Real Estate Market
Real Estate
Asia-Pacific Soft Facility Management Market
Real Estate
Canada Office Real Estate Market
Real Estate
North America Hard Facility Management Market
Real Estate
United Arab Emirates Facility Management Market
Real Estate
UAE Flexible Office Space Market
Real Estate
IBC Rental Business Market