
 Saudi Arabia Luxury Residential Real Estate Market | 2026-2036
Saudi Arabia Luxury Residential Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Luxury Residential Real Estate Market Analytics
Smart building automation and integrated IoT infrastructure is reconfiguring how luxury residential developments are engineered and delivered across Saudi Arabia's premium housing sector. Dar Al Arkan Real Estate Development leverages its manufacturing scale to control material costs across large master-planned communities. ROSHN Group anchors its competitive position through state-backed land access and standardized premium product lines. Emaar The Economic City differentiates via waterfront and golf-integrated lifestyle concepts that attract institutional investor capital.
Saudi Arabia luxury residential real estate comprises high-value dwellings—typically exceeding 400 square meters with premium finishes, dedicated concierge services, and integrated leisure facilities—designed for wealth preservation and lifestyle elevation among domestic and international elites. Villas and gated communities dominate transaction value, reflecting buyer preference for privacy, larger land plots, and branded community management. The investor buyer segment leads volume absorption, while smart home features within the amenities category represent the fastest-growing margin pool as developers bundle technology packages to justify premium pricing tiers.
The Saudi Building Code, administered by the Ministry of Municipal and Rural Affairs and Housing, mandates seismic resilience and energy efficiency standards that elevate construction costs and filter out subscale developers. The Saudi Central Bank's mortgage regulations and SFDA-aligned construction quality frameworks shape financing accessibility and material certification requirements for luxury projects. Stakeholders must monitor how NEOM and Red Sea Project spillover demand reshapes buyer expectations for sustainability credentials and experiential amenities in conventional urban luxury offerings.
Market Dynamics
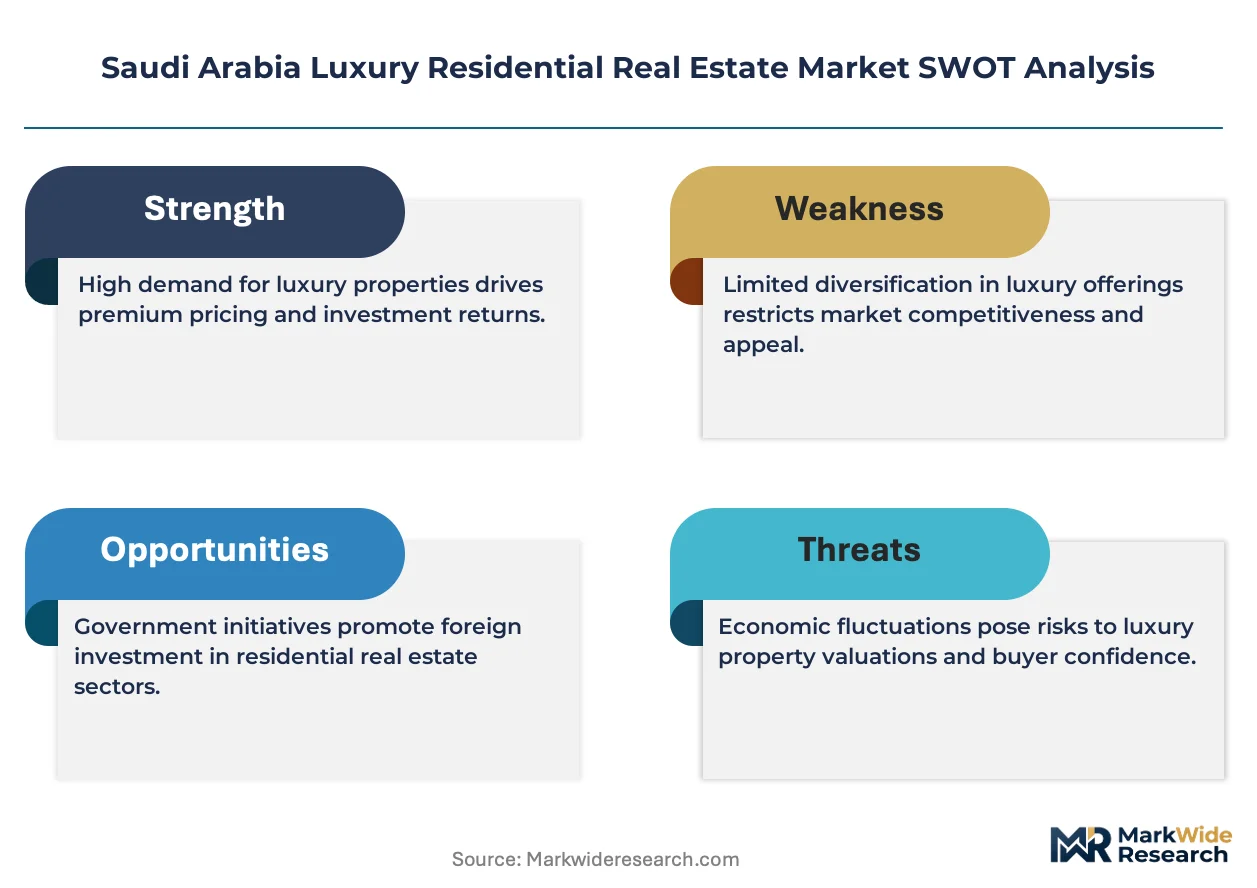
SFDA-aligned construction quality mandates and Saudi Building Code seismic specifications are compressing developer margins while filtering subscale competitors from Riyadh and Jeddah's premium pipeline.
Growth Catalysts
- Ultra-high-net-worth expatriate capital flows:Finance and energy sector buyers from Europe and Asia are concentrating acquisition activity in Riyadh's Diplomatic Quarter and King Abdullah Economic City master-plans.
- NEOM spillover effect:Sustainability and experiential amenity benchmarks set by giga-projects are elevating buyer expectations for conventional urban luxury developments.
- Smart home technology bundling:IoT infrastructure and building automation systems are creating new margin pools as developers justify premium pricing tiers through integrated technology packages.
Market Restraints
- Construction input cost volatility:Specialized seismic-grade materials and energy-efficient systems mandated by the Saudi Building Code are elevating baseline development costs.
- Land access concentration:State-controlled land release mechanisms limit independent developer entry and reinforce ROSHN Group's anchored position in premium segments.
- Financing accessibility friction:Saudi Central Bank mortgage regulations create qualification barriers for domestic investor buyers seeking leverage on luxury acquisitions.
Strategic Opportunities
- Jeddah waterfront corridor expansion:Red Sea Project infrastructure spillover is opening premium development zones along the Jeddah Corniche and northern coastal districts.
- Branded community management convergence:International hospitality operators are partnering with developers to deliver serviced villa concepts that capture recurring revenue streams.
- Green building certification tailwinds:Ministry of Municipal and Rural Affairs and Housing energy efficiency incentives are accelerating demand for LEED and Mostadam-certified residential assets.
Industry Challenges
- Specialized project management talent scarcity:Master-planned community delivery requires expertise in phased infrastructure coordination that outstrips current Saudi construction management capacity.
- Legacy system integration complexity:Retrofitting smart building automation into existing premium stock creates technical friction and warranty exposure for developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Luxury Residential Real Estate Market |
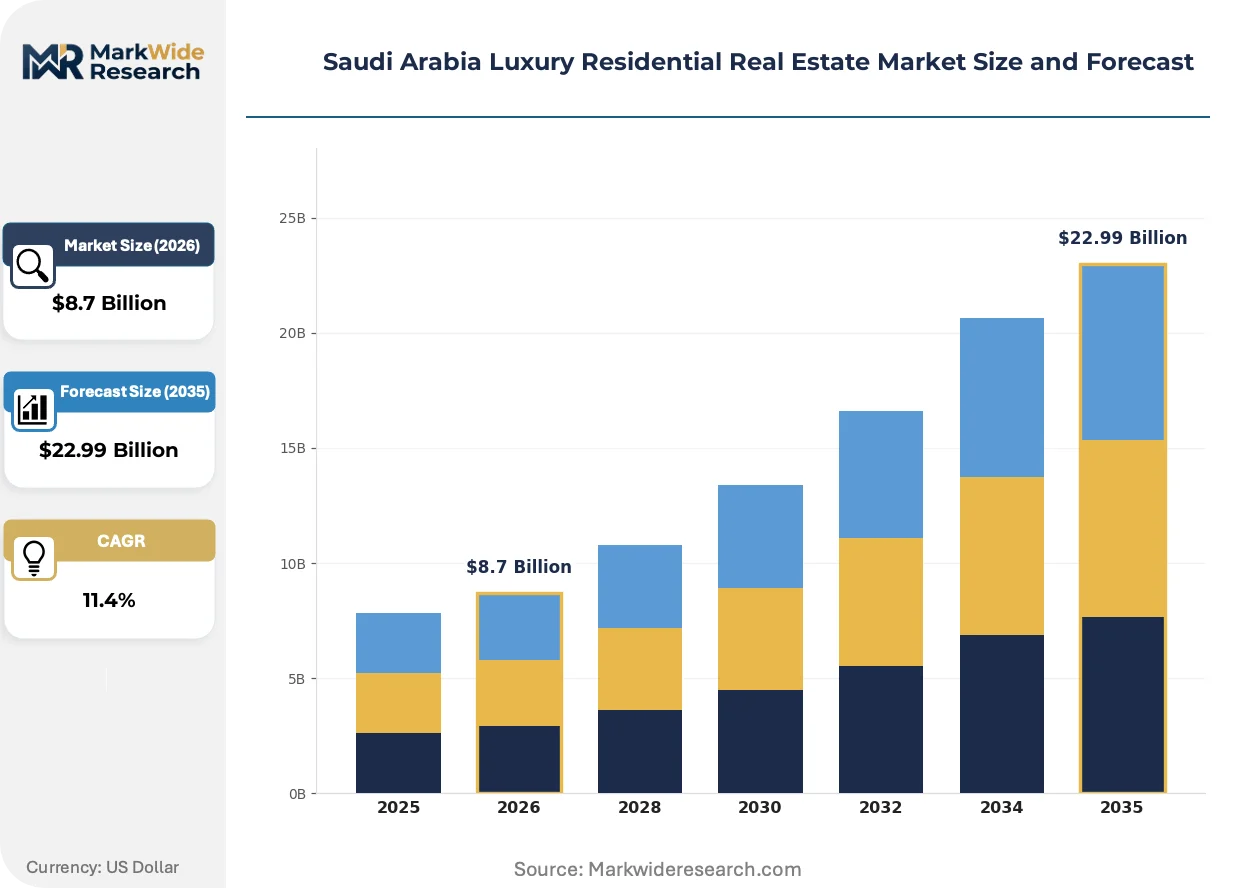
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Villas, Apartments, Penthouses, Gated Communities Buyer Type: Investors, Expats, Local Buyers, Luxury Seekers Payment Structure: Cash Purchase, Mortgage, Installments, Leasing Amenities: Swimming Pool, Gym, Concierge, Smart Home Features |
| Companies Covered | Jabal Omar Development Company, Emaar The Economic City, ROSHN Group, Midad Real Estate, Alandalus Property, Dar Al Arkan Real Estate Development, Al Akaria, Sumou Real Estate, DarGlobal, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Luxury Residential Real Estate Market Evolving Landscape
Technology convergence and regulatory stringency are compressing traditional development timelines while fragmenting buyer segmentation across experiential, sustainable, and digitally-integrated housing preferences.
Integrated building automation platforms are collapsing the distinction between core construction and technology infrastructure in luxury residential delivery. Ultra-high-net-worth buyers now expect pre-installed IoT ecosystems controlling climate, security, and energy management as standard. This compression is forcing developers to source technology partnerships earlier in design phases, eroding traditional subcontractor boundaries.
The Saudi Building Code's seismic resilience and energy efficiency chapters are mandating structural engineering upgrades that filter development participation. Ministry of Municipal and Rural Affairs and Housing enforcement is elevating material certification requirements and inspection protocols. Premium villa and gated community segments absorb these compliance costs most readily, widening the capability gap between established master-planners and opportunistic entrants.
Buyer preference is rotating toward experiential amenity packages that extend beyond traditional leisure facilities. Wellness infrastructure, curated retail, and co-working integration are displacing standalone clubhouse models in Riyadh and Jeddah's premium developments. This shift is most visible in King Abdullah Economic City, where institutional investor capital now prioritizes lifestyle-concept differentiation over pure location premiums.
Saudi Arabia Luxury Residential Real Estate Market Segmentation
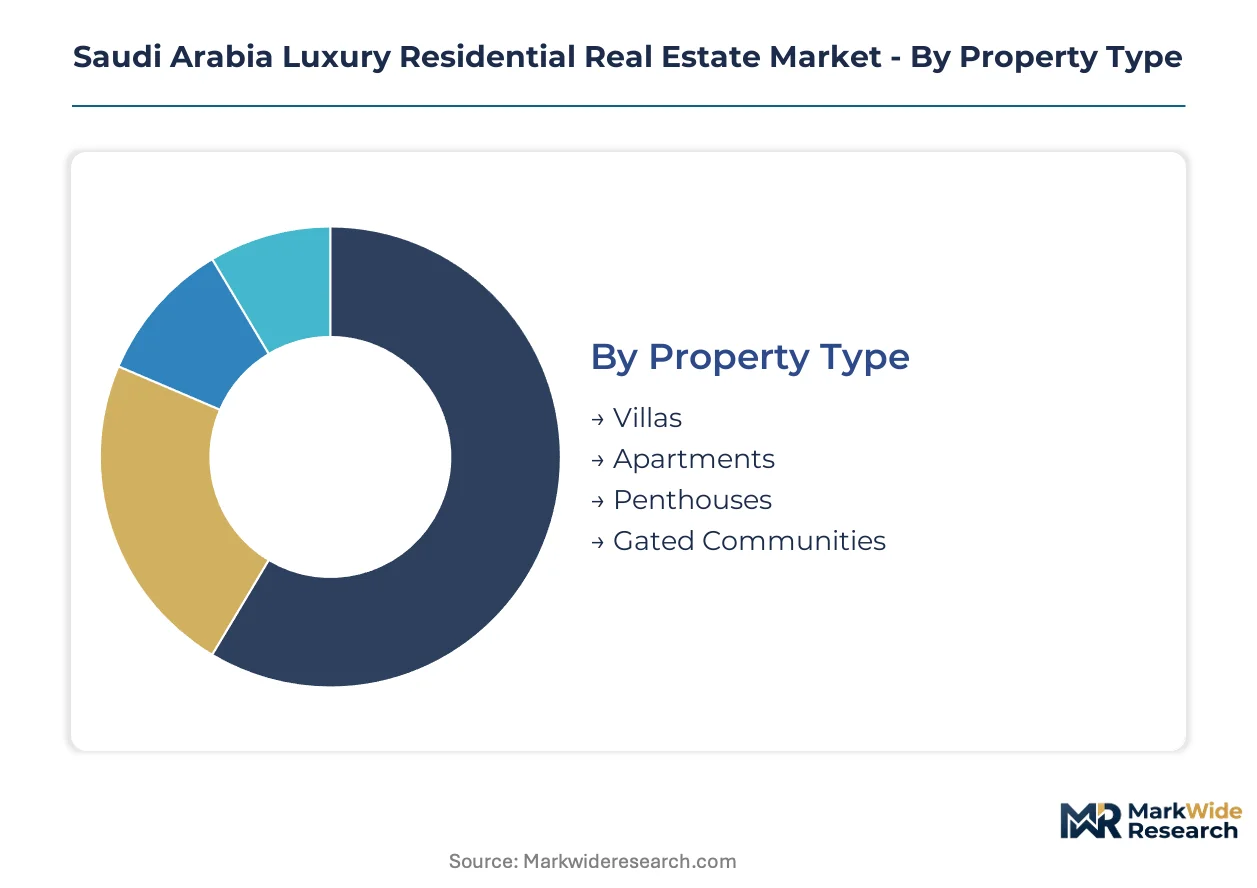
Property type and buyer composition determine pricing architecture in Saudi Arabia's luxury residential sector. Payment structure and amenity bundling separate premium developments from aspirational entrants competing on specification rather than location.
Property Type:
Cost tier stratification across dwelling formats creates distinct margin profiles and construction complexity requirements for developers operating in Riyadh and Jeddah.
- Villas:Standalone structures exceeding 400 square meters with private plots dominate transaction value in Riyadh's Diplomatic Quarter. Land scarcity and Ministry of Municipal and Rural Affairs and Housing zoning restrictions compress supply, sustaining price premiums for freehold villa stock.
- Gated Communities:Master-planned enclaves with integrated security, landscaping, and shared infrastructure attract institutional investor capital. King Abdullah Economic City developments leverage this format to bundle lifestyle amenities with capital appreciation potential.
- Apartments:High-rise units in urban cores serve expatriate finance sector buyers seeking proximity to commercial districts.
- Penthouses:Top-floor configurations with panoramic views and exclusive elevator access command the highest per-square-meter pricing in Jeddah's Corniche corridor.
Villas hold installed capacity. Gated Communities is rotating up the share rankings.
Buyer Type:
Customer type segmentation reveals divergent acquisition motives, financing preferences, and sensitivity to Saudi Central Bank mortgage qualification thresholds.
- Investors:Domestic and regional capital deploys into luxury residential for wealth preservation and rental yield capture. These buyers absorb off-plan inventory during pre-construction phases, providing developers with construction finance de-risking.
- Expats:Ultra-high-net-worth individuals from European and Asian energy and finance sectors concentrate activity in Riyadh's Diplomatic Quarter. Visa reform and quality-of-life initiatives are expanding eligible buyer pools beyond traditional diplomatic and corporate assignee categories.
- Local Buyers:Saudi nationals leverage family office capital and intergenerational wealth transfers for trophy asset acquisition.
- Luxury Seekers:Lifestyle-motivated purchasers prioritize experiential amenities and branded community management over pure investment return metrics.
Investors anchor current transaction volume. Expats are climbing the fastest among buyer categories.
Payment Structure:
Financing modality shapes developer cash flow timing and buyer accessibility barriers across Saudi Arabia's premium residential pipeline.
- Cash Purchase:Full upfront settlement dominates villa and penthouse transactions, eliminating Saudi Central Bank mortgage qualification friction and accelerating closing timelines.
- Mortgage:Regulated financing products face down payment minimums and debt-service-ratio caps that filter domestic investor buyer participation.
- Installments:Developer-backed payment plans spread construction-phase contributions across 24-to-48-month structures, expanding accessibility for aspirational luxury buyers.
- Leasing:Long-term leasehold arrangements in designated foreign investment zones serve expatriate buyers restricted from freehold ownership.
Cash Purchase maintains dominant share. Installments is gaining traction fastest among payment modalities.
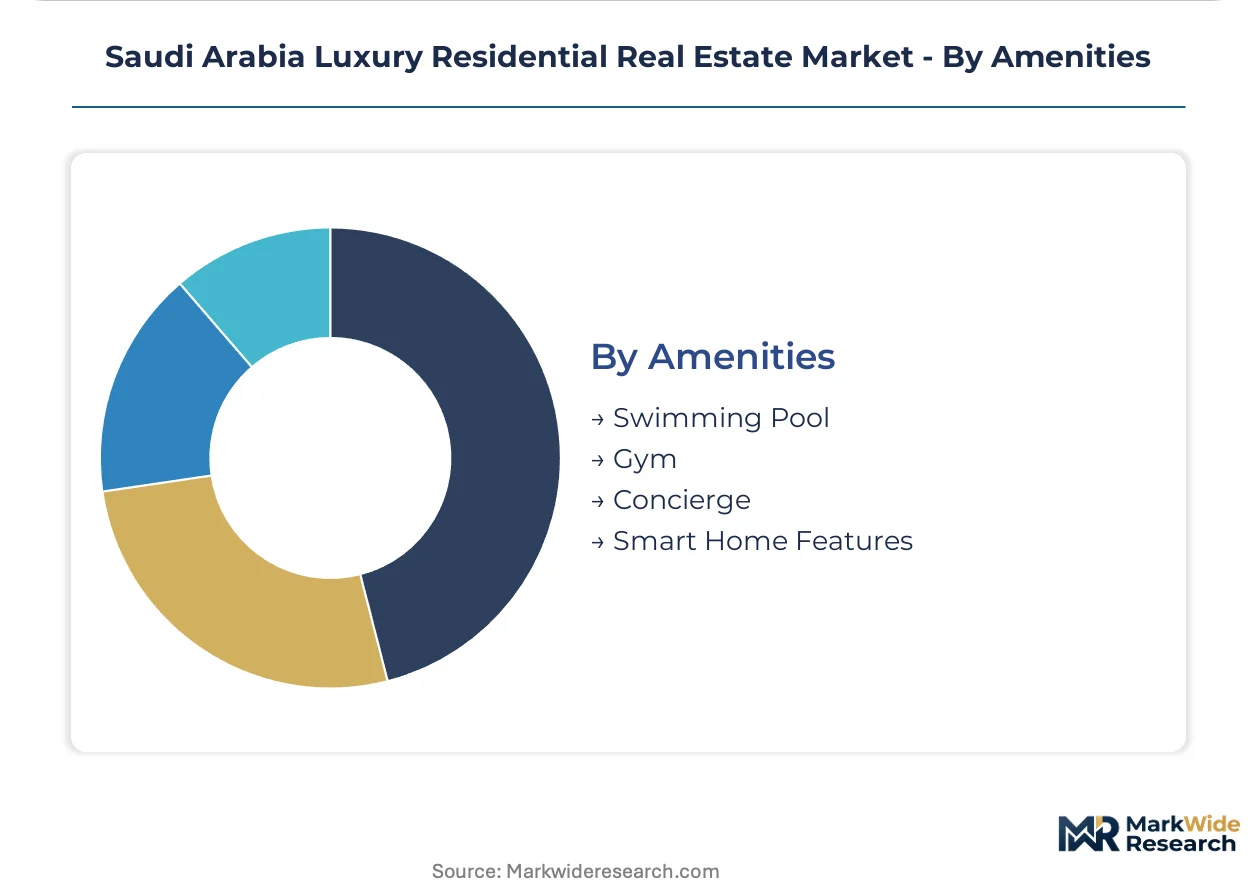
Amenities:
Amenity bundling now functions as primary differentiation mechanism as location premiums compress in competitive submarkets.
- Smart Home Features:Pre-installed IoT ecosystems controlling climate, security, and energy management represent the steepest expansion trajectory. Developers partner with technology integrators earlier in design phases to justify premium pricing tiers.
- Concierge:Dedicated lifestyle management services including travel coordination, event planning, and household staffing attract institutional investor capital seeking operational yield enhancement.
- Swimming Pool:Private and communal aquatic facilities remain baseline expectations in villa and gated community segments.
- Gym:Fitness infrastructure specification tiers separate premium developments from mid-market competitors.
Swimming Pool holds baseline ubiquity. Smart Home Features is rotating up the margin contribution rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ultra-high-net-worth expatriate buyers from European finance and Asian energy sectors concentrate acquisition activity in Riyadh's Diplomatic Quarter and King Abdullah Economic City. Domestic investor capital flows into trophy villa assets for wealth preservation. The Ministry of Municipal and Rural Affairs and Housing steers development patterns through land release mechanisms and building code enforcement.
Riyadh
Diplomatic Quarter villa transactions absorb the bulk of institutional investor capital seeking freehold privacy and proximity to government districts. The Saudi Building Code's seismic resilience mandates elevate construction specifications for premium developments. King Abdullah Financial District spillover demand is reshaping northern corridor master-plans with integrated smart home infrastructure.
Jeddah
Red Sea Project infrastructure investment is unlocking northern coastal districts for waterfront luxury communities targeting expatriate buyers. The Saudi Central Bank's mortgage regulations filter domestic leverage access, privileging cash purchasers in penthouse and villa segments. Jeddah Economic City anchors institutional capital deployment through golf-integrated lifestyle concepts.
Eastern Province
Energy sector executives drive demand for gated compounds near Dhahran and Al Khobar corporate headquarters. SFDA-aligned construction quality mandates enforce material certification standards that compress developer margins. King Abdullah Economic City's master-planned communities capture recurring revenue through branded management services.
NEOM Northwest
Giga-project sustainability benchmarks are elevating buyer expectations for experiential amenities and green building credentials in conventional luxury offerings. The Ministry of Municipal and Rural Affairs and Housing channels development rights through state-controlled land mechanisms. Trojena and Sindalah island concepts are drawing international architectural partnerships that reshape premium housing design standards.
Tabuk and Northern Borders
Red Sea coastal access is opening secondary luxury development zones as primary markets face land scarcity constraints. The Saudi Building Code's energy efficiency chapters mandate specialized glazing and insulation systems that elevate baseline costs. NEOM logistics and workforce housing spillover is creating adjacent premium residential demand clusters.
Saudi Arabia Luxury Residential Real Estate Market Competitive Landscape
Channel-controlling players compete with product-specialist players across Saudi Arabia's luxury residential pipeline. State-backed land access concentrates delivery capacity among established master-planners with Ministry of Municipal and Rural Affairs and Housing relationships. Three archetypes dominate: vertically integrated developers with captive material supply, state-affiliated platforms with preferential land allocations, and international partnership vehicles importing branded lifestyle concepts. Competitive moves center on technology partnership formations for smart home bundling and hospitality operator alliances for serviced villa revenue streams.
Within the state-affiliated tier, ROSHN Group anchors land-access advantages through standardized premium product lines. Dar Al Arkan Real Estate Development exemplifies manufacturing-scale players controlling material costs across large community footprints. Emaar The Economic City occupies a position among lifestyle-concept developers leveraging waterfront and golf integration to attract institutional capital. These three represent the competitive spectrum from state-enabled scale to experiential differentiation.
| Leading Market Players |
|---|
| Jabal Omar Development Company |
| Emaar The Economic City |
| ROSHN Group |
| Midad Real Estate |
| Alandalus Property |
| Dar Al Arkan Real Estate Development |
| Al Akaria |
| Sumou Real Estate |
| DarGlobal |
| Others |
Value Network & Pricing Analysis
Regulatory chokepoint exposure through Saudi Building Code seismic-grade material mandates determines both pricing tier spreads and supply chain shape across the Kingdom's luxury residential pipeline. Cost-plus contracts with steel and cement indexation compress margins for subscale developers while reinforcing ROSHN Group's anchored position through captive procurement scale.
Pricing Analysis
Cost-plus contracts with Saudi Building Code-mandated material indexation dominate villa and gated community transactions. Price differentiation rests on seismic certification tier and smart home technology bundling depth. Pricing pressure stems from specialized glazing and insulation system mandates elevating baseline specifications. Domestic investor buyers exhibit highest price sensitivity to construction-phase payment structures, while ultra-high-net-worth expatriates absorb premium tiers with minimal friction.
Supply Chain Analysis
Tariff exposure between Saudi Arabia and GCC aluminum and steel suppliers dominates construction input cost volatility for premium developments. Supply concentration centers on UAE, China, and Turkey for seismic-grade structural components and IoT infrastructure systems. Raw material dependencies hinge on high-performance concrete additives, low-emissivity glass, and integrated building automation controllers. Single-source vulnerability persists for specialized seismic engineering consultants certified under Ministry of Municipal and Rural Affairs and Housing protocols. Distribution runs through state-controlled land release mechanisms and master-planned community procurement hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's luxury residential market sits in early-cycle recovery, with NEOM spillover demand and expatriate visa reform driving absorption velocity. Capital deployment timing favors developers with pre-secured land positions and technology partnership pipelines.
For Market Incumbents: Insulate margin structures through backward integration into precast concrete manufacturing and captive smart home technology sourcing. Accelerate LEED and Mostadam certification investment ahead of Ministry of Municipal and Rural Affairs and Housing incentive expansion. Lock in multi-year seismic-grade steel offtake agreements before commodity volatility intensifies.
For New Entrants and Emerging Players: Build out branded community management capabilities through hospitality operator partnerships targeting Jeddah's northern coastal corridor. The Red Sea Project spillover zone offers lowest land access barriers for experiential amenity-focused concepts. Lead with serviced villa revenue models rather than pure development plays.
For Investors and Strategic Acquirers: Saudi Central Bank mortgage regulation relaxation reshapes the acquisition landscape toward domestic investor-facing developers with installment plan infrastructure. Five-to-ten year viability favors master-planners with state land allocations and standardized product platforms. Monitor NEOM workforce housing spillover as inflection signal for adjacent premium demand clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| Smart Home Technology Partnership | IoT infrastructure bundling justifies premium pricing tiers through integrated climate and security ecosystems. |
| Green Building Certification Program | LEED and Mostadam credentials unlock Ministry of Municipal and Rural Affairs and Housing energy efficiency incentives. |
| Hospitality Operator Alliance | Branded community management captures recurring revenue streams from institutional investor capital deployment. |
| Seismic-Grade Material Backward Integration | In-house precast production controls cost volatility under Saudi Building Code enforcement expansion. |
| Red Sea Coastal Land Assembly | Jeddah northern corridor positioning captures infrastructure spillover from giga-project development timelines. |
Research Methodology
Initial hypotheses were tested against primary input from master-planned community development executives, Ministry of Municipal and Rural Affairs and Housing regulatory affairs leads, institutional investor asset managers, and hospitality operator partnership directors and refined through secondary validation against SEC filings, Saudi Central Bank mortgage market reports, customs construction material import data, and building permit issuance databases. Bottom-up project pipeline assessment and top-down macroeconomic absorption modeling were triangulated to establish market sizing.
Demand-supply-balance framing anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass property type, buyer archetype, payment structure modality, and amenity bundling tier alongside regional regulatory cluster differentiation. CAGRs were derived from phased absorption curves and construction completion timelines. Forecast inputs incorporated expatriate visa policy trajectory and NEOM workforce housing pipeline spillover assumptions.
Practitioners should monitor Saudi Central Bank mortgage qualification threshold adjustments and Ministry of Municipal and Rural Affairs and Housing land release schedule revisions for early signals of demand elasticity shifts. Forecasts reflect assumptions regarding giga-project delivery timelines and seismic code enforcement intensity. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Luxury Residential Real Estate Market
China Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Ready-To-Move-In Luxury Homes Market
Luxury Residential Real Estate Market
Netherlands Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Europe Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
GCC Luxury Market
Luxury Residential Real Estate Market
North America Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Switzerland Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Vietnam Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Denmark Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Singapore Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Australia Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Sweden Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Canada Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
Bahrain Luxury Residential Real Estate Market
Luxury Residential Real Estate Market
China Residential Real Estate Market
Luxury Residential Real Estate Market
Italy Luxury Residential Real Estate Market