

Aircraft Pylon and Strut Fairing Retrofit Kits Market Size, Share, and Industry Trends Forecast 2026-2036
Aircraft Pylon and Strut Fairing Retrofit Kits Market Insights
Skilled composite technician availability is reorganizing production capacity across the retrofit supply chain. Spirit AeroSystems leverages its Wichita manufacturing base to sustain high-volume pylon kit output. GKN Aerospace anchors European demand through specialized aerodynamic optimization capabilities. Safran competes on integrated structural reinforcement modules spanning multiple aircraft platforms.
Aircraft pylon and strut fairing retrofit kits are aftermarket assemblies engineered to replace or upgrade engine mounting structures and wing-to-fuselage strut coverings, typically fabricated from carbon fiber reinforced polymer or aluminum-lithium alloys through resin transfer molding or automated fiber placement to reduce drag and extend airframe service life. Commercial jetliners dominate application demand as carriers pursue fuel burn reductions without full fleet replacement. Composite reinforcement technology leads product development while vibration damping solutions represent the fastest-growing technology segment as operators address noise compliance and passenger comfort requirements simultaneously.
FAA airworthiness directives and EASA Part 21 certification standards shape retrofit kit design validation and installation approval pathways, with both regulators tightening structural inspection intervals for aircraft exceeding twenty years in service. The EU Green Deal aviation emissions framework is forcing operators to document fuel efficiency improvements from aerodynamic modifications. Stakeholders must monitor evolving MRO qualification requirements and dual-certification demands as regulatory divergence between North American and European authorities complicates kit standardization strategies.
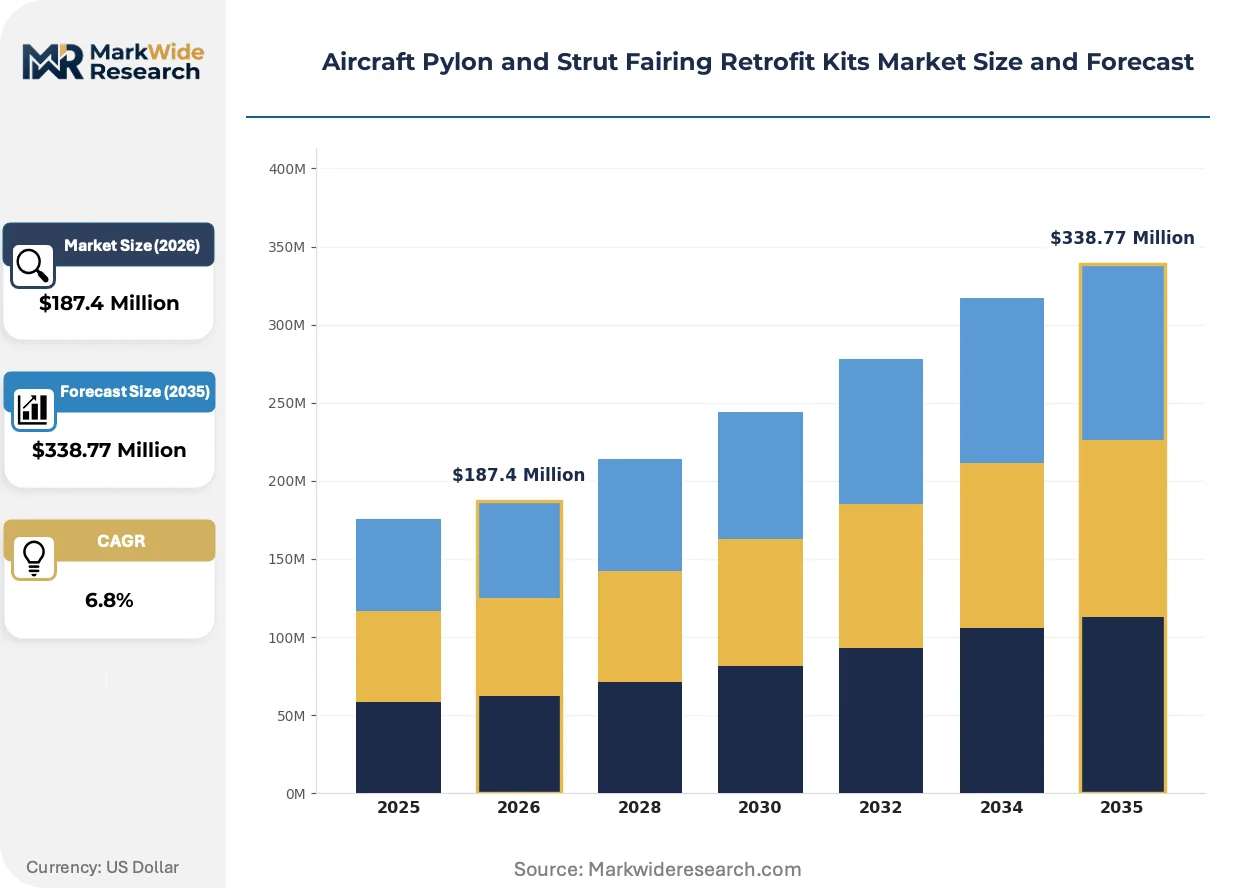
Market Dynamics
Commercial airline fleet age profiles are compressing retrofit decision cycles as fuel efficiency mandates from the EU Green Deal and FAA airworthiness directives force simultaneous compliance across multiple regulatory jurisdictions.
Growth Catalysts
- FAA Airworthiness Directives:Aging narrowbody fleets in the United States face mandatory structural inspection intervals, accelerating pylon replacement schedules.
- Carbon Fiber Reinforced Polymer:Composite manufacturing advances reduce kit weight by fifteen to twenty percent versus legacy aluminum-lithium assemblies.
- EU Green Deal Aviation Emissions Framework:European operators must document quantified fuel burn improvements from aerodynamic modifications to retain operating certificates.
Market Restraints
- Titanium and Epoxy Resin Volatility:Raw material price swings compress kit margins during long production cycles.
- Specialized Composite Technician Scarcity:Concentrated labor pools in Wichita and Toulouse create regional production bottlenecks.
- EASA Part 21 Certification Complexity:Dual-validation requirements with FAA standards extend approval timelines for cross-Atlantic operators.
Strategic Opportunities
- China Narrowbody Retrofit Wave:Domestic fleet expansion creates demand for localized pylon kit assembly capacity.
- Vibration Damping Technology Convergence:Integration of acoustic dampening with structural reinforcement addresses passenger comfort and noise compliance simultaneously.
- Resin Transfer Molding Automation:Automated fiber placement reduces labor content and cycle time for high-volume programs.
Industry Challenges
- NDT Certification Bottlenecks:Qualified ultrasonic inspection technicians for composite damage assessment remain scarce across MRO networks.
- Legacy Aircraft Documentation Gaps:Incomplete as-built records for pre-1990 airframes complicate kit engineering and fit verification.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aircraft Pylon and Strut Fairing Retrofit Kits Market Trends and Innovations
Retrofit kit engineering is pivoting toward modular architectures that separate structural reinforcement from aerodynamic surfaces, enabling faster installation and reduced aircraft downtime.
Automated fiber placement systems are fragmenting traditional hand-layup composite manufacturing. Tier-one suppliers adopt robotic tape laying for pylon skin panels. MRO facilities struggle to justify capital investment, ceding complex geometries to original equipment manufacturers.
EASA Part 21 certification standards are tightening design validation requirements for structural modifications. Kit developers must submit full-scale fatigue test data rather than analysis-based approvals. Narrowbody operators in Germany and France face extended grounding periods for compliance.
Airline technical procurement teams are consolidating vendor relationships around integrated structural modules. Single-source contracts for pylon-strut-fairing bundles displace component-level purchasing. US legacy carriers lead this consolidation, pressuring mid-tier suppliers to merge capabilities or exit.
Aircraft Pylon and Strut Fairing Retrofit Kits Market Segmentation
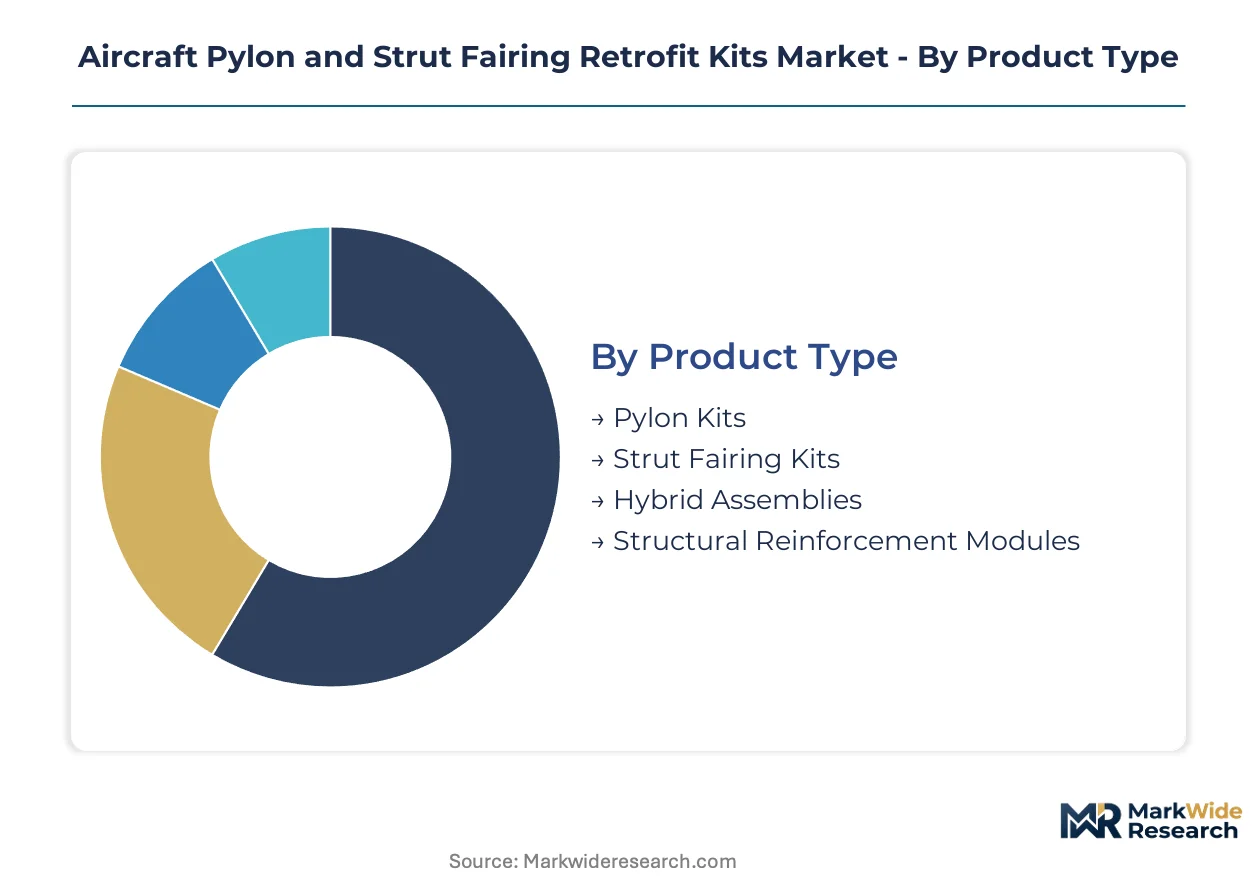
Segmentation reveals how fuel efficiency mandates and regulatory compliance reshape procurement patterns across retrofit kit categories. Margin pools concentrate where composite manufacturing complexity intersects with airworthiness certification requirements.
Product Type:
Margin concentration follows manufacturing sophistication, with advanced composite assemblies commanding premium positioning over metallic alternatives.
- Pylon Kits:Engine mounting structures fabricated from carbon fiber reinforced polymer through resin transfer molding, replacing legacy aluminum-lithium assemblies. Demand clusters with United States narrowbody operators facing FAA airworthiness directive compliance deadlines for aging fleet structural integrity.
- Strut Fairing Kits:Wing-to-fuselage aerodynamic coverings engineered to reduce form drag and interference drag. German and French carriers pursuing EU Green Deal emissions documentation drive adoption for quantified fuel burn improvements.
- Hybrid Assemblies:Integrated pylon-fairing combinations reducing installation downtime through unified structural interfaces.
- Structural Reinforcement Modules:Standalone load-bearing components extending airframe service life without full pylon replacement.
The dominant share belongs to Pylon Kits, while Hybrid Assemblies are closing the gap fastest.
Technology:
Application intensity varies by operational profile, with high-cycle commercial fleets prioritizing durability over acquisition cost.
- Composite Reinforcement:Carbon fiber and epoxy matrix systems replacing metallic structures for fifteen to twenty percent weight reduction. Automated fiber placement adoption in Wichita and Toulouse production clusters addresses skilled technician scarcity constraining output expansion.
- Vibration Damping:Acoustic attenuation materials integrated with structural elements to address passenger comfort and noise compliance simultaneously. Commercial jetliners in China expanding retrofit programs represent concentrated demand for dual-function solutions.
- Aerodynamic Optimization:Computational fluid dynamics-refined surface geometries minimizing boundary layer separation.
- Corrosion Protection:Barrier coatings and galvanic isolation systems extending service intervals in maritime climates.
- Lightweight Alloys:Aluminum-lithium and titanium alternatives where composite repair infrastructure remains limited.
Composite Reinforcement holds the installed base majority, yet Vibration Damping is expanding most quickly as regulatory noise thresholds tighten.
Application:
Procurement scale diverges sharply between high-utilization commercial fleets and sporadic military upgrade cycles.
- Commercial Jetliners:Narrowbody and widebody aircraft subject to fuel efficiency mandates and structural aging protocols. United States legacy carriers consolidating vendor relationships around integrated pylon-strut-fairing bundles to reduce procurement complexity and installation downtime.
- Military Aircraft:Defense platforms requiring airframe life extension without platform replacement. Specialized corrosion protection and battle damage repair capabilities differentiate military-specification kits from commercial equivalents.
- Business Jets:Fractional ownership fleets balancing retrofit investment against residual value considerations.
- Cargo Planes:Freighter conversions driving demand for structural reinforcement modules supporting increased maximum takeoff weights.
- Unmanned Aerial Vehicles:Emerging segment with simplified certification pathways but limited kit standardization.
Commercial Jetliners generate the dominant revenue share, though Cargo Planes are gaining share fastest with e-commerce logistics fleet expansion.
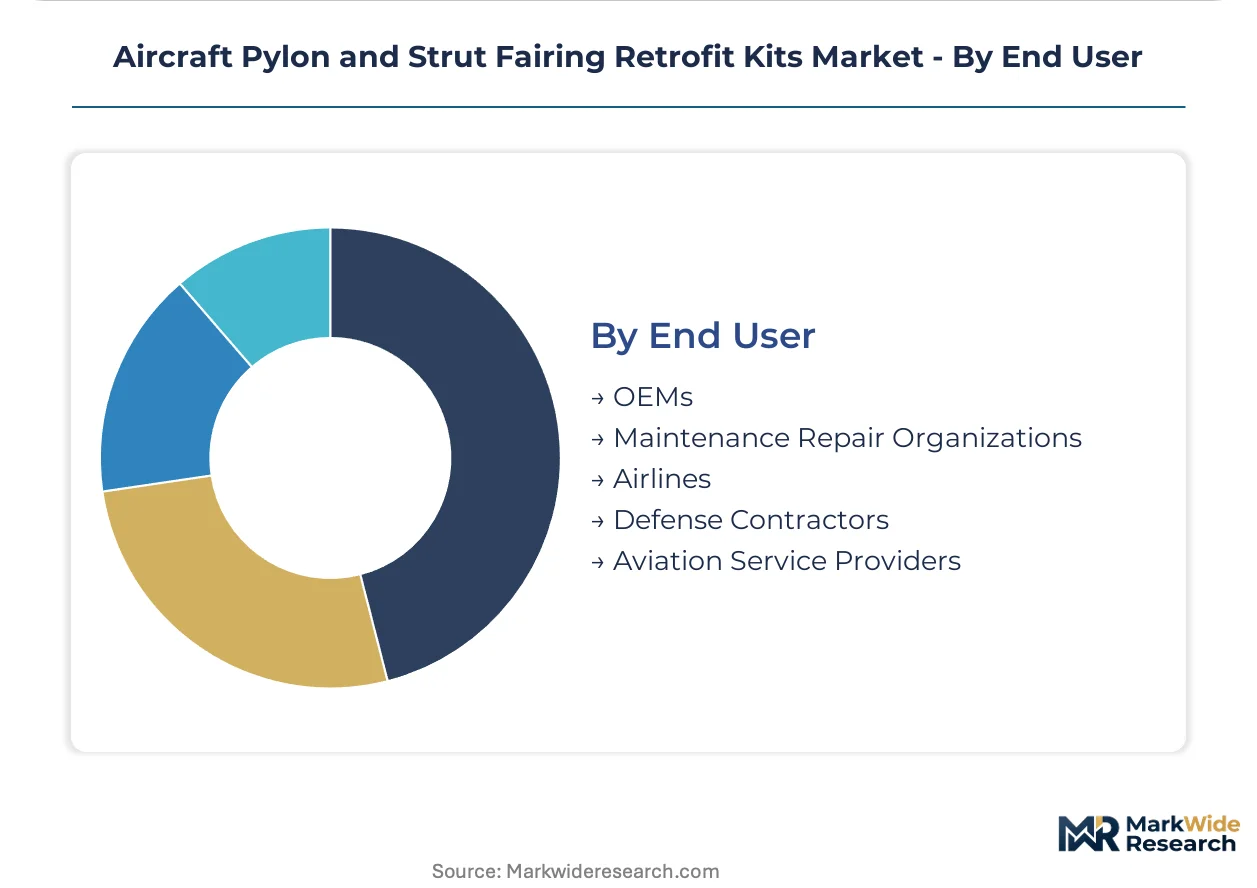
End User:
Technical capability and regulatory access permissions fragment the buyer landscape across installation authorization tiers.
- Maintenance Repair Organizations:FAA Part 145 and EASA Part 145 certified facilities performing structural modifications during scheduled checks. NDT certification bottlenecks for composite damage assessment constrain capacity expansion across MRO networks.
- Airlines:Technical procurement teams consolidating single-source contracts for integrated structural modules. US carriers lead vendor consolidation, pressuring mid-tier suppliers to merge capabilities or exit the retrofit kit segment.
- OEMs:Original equipment manufacturers leveraging manufacturing scale for high-volume pylon kit output.
- Defense Contractors:Military platform integrators requiring specialized airworthiness qualification pathways.
- Aviation Service Providers:Leasing companies and asset managers coordinating fleet-wide retrofit programs across multiple operator clients.
Maintenance Repair Organizations command the largest procurement volume, while Airlines are climbing the fastest through direct technical procurement team expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA airworthiness directives anchor United States demand as aging narrowbody fleets face compressed retrofit timelines. Regulatory divergence between Washington and Brussels reshapes kit standardization strategies across the Atlantic.
United States
Legacy carriers consolidate vendor relationships around integrated pylon-strut-fairing bundles to reduce procurement complexity. FAA airworthiness directives mandate structural inspection intervals for aircraft exceeding twenty years in service. Wichita manufacturing clusters sustain high-volume pylon kit output through automated fiber placement adoption.
Germany
Narrowbody operators pursue EU Green Deal emissions documentation through quantified fuel burn improvements from aerodynamic modifications. EASA Part 21 certification standards tighten design validation requirements for structural modifications. Hamburg and Munich MRO facilities face extended grounding periods for compliance with full-scale fatigue test data submissions.
China
Domestic fleet expansion creates demand for localized pylon kit assembly capacity as narrowbody retrofit programs accelerate. The country's national aviation regulator tightens structural integrity protocols for aging commercial aircraft. Shanghai and Tianjin production hubs attract composite manufacturing investment from tier-one suppliers.
France
Carriers prioritize dual-function solutions addressing passenger comfort and noise compliance simultaneously through vibration damping technology. EASA certification complexity extends approval timelines for cross-Atlantic operators. Toulouse maintains concentrated labor pools for specialized composite technician deployment.
United Kingdom
Maintenance repair organizations confront NDT certification bottlenecks for composite damage assessment across their networks. The national aviation authority aligns inspection protocols with evolving MRO qualification requirements. Southeast England technical procurement teams coordinate fleet-wide retrofit programs for leasing company clients.
Aircraft Pylon and Strut Fairing Retrofit Kits Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the retrofit kit supply chain. The market structure consolidates around tier-one aerospace manufacturers with captive airline relationships and specialized composite fabricators with aerodynamic optimization capabilities. Three strategic archetypes dominate: integrated structural module suppliers, high-volume pylon kit producers, and vibration damping technology specialists. Competitive moves concentrate on automated manufacturing adoption and strategic partnerships bridging certification expertise with production scale.
Among North American-based fabricators, Spirit AeroSystems and Collins Aerospace exemplify the scale-driven archetype with Wichita and Midwest manufacturing concentration. GKN Aerospace represents the European aerodynamic optimization specialist tier. Safran occupies a position within the integrated structural module segment spanning multiple aircraft platforms. These three anchors illustrate how geographic clustering around regulatory hubs and composite technician labor pools shapes competitive positioning without requiring identical capability stacks.
| Leading Market Players |
|---|
| Aero Design Labs |
| Aviation Partners |
| Spirit AeroSystems |
| GKN Aerospace |
| Collins Aerospace |
| Safran |
| FACC AG |
| Triumph Group |
| McFarlane Aviation |
| Others |
Pricing and Supply Chain Analysis
Ninety-to-one-hundred-twenty-day kit fabrication lead times concentrate pricing power with Spirit AeroSystems in Wichita and GKN Aerospace in Bristol, where automated fiber placement capacity constraints create order backlogs that sustain premium positioning for FAA-EASA dual-certified assemblies.
Pricing Analysis
North American pylon kit quotations run fifteen to twenty percent above European equivalents due to Wichita labor premiums and expedited FAA certification pathways. Three-tier pricing structure across premium, standard, and economy levels separates EASA Part 21-validated bundles from single-jurisdiction kits and basic structural reinforcement modules. Price differentiation hinges on certification grade and after-sales engineering support intensity. Cost compression in standard-tier offerings is intensifying because Chinese domestic suppliers are scaling resin transfer molding capacity. Cargo plane operators exhibit highest price sensitivity, while US legacy carriers prioritize installation downtime reduction over acquisition cost.
Supply Chain Analysis
Raw carbon fiber preform inventory cycles stretching sixty to seventy-five days expose kit fabricators to epoxy resin price volatility that feeds directly into margin compression during titanium spike periods. Manufacturing gravity centers on the United States, Germany, and China, with Wichita, Hamburg, and Shanghai production hubs drawing from Japanese and South Korean carbon fiber feedstock. The supply chain rests on aerospace-grade epoxy resin, titanium fasteners, and specialized NDT equipment as critical inputs. Single-source vulnerability concentrates in qualified ultrasonic inspection technician pools across MRO networks. Distribution runs through FAA Part 145 and EASA Part 145 certified facilities with direct airline technical procurement teams capturing growing volume share.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as EU Green Deal aviation emissions documentation requirements force quantified fuel burn improvements from aerodynamic modifications, accelerating retrofit program adoption ahead of full fleet replacement cycles.
For Market Incumbents: Fortify automated fiber placement capacity in Wichita and Toulouse to defend against emerging Chinese domestic suppliers scaling localized assembly. Lock in long-term carbon fiber supply agreements with Toray and Hexcel before commodity volatility intensifies. Prioritize EASA-FAA dual-certification investment to maintain premium positioning as regulatory divergence complicates kit standardization.
For New Entrants and Emerging Players: NDT certification bottlenecks for composite damage assessment represent the most penetrable service-layer gap, with MRO facilities struggling to justify capital investment in ultrasonic inspection equipment. Target cargo plane retrofit programs in China where e-commerce logistics fleet expansion outpaces incumbent capacity. Pursue vibration damping technology licensing partnerships with acoustic materials specialists to differentiate hybrid assembly offerings.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance play because FAA airworthiness directives and EASA Part 21 standards structurally mandate recurring retrofit expenditure regardless of fuel price cycles. Acquisition targets should display integrated structural module capabilities spanning multiple aircraft platforms with captive airline relationships. Watch for inflection in Chinese narrowbody retrofit program acceleration as the signal that localized production economics are tilting competitive dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fiber Placement Scale-Up | Robotic tape laying in Wichita reduces labor content and cycle time for high-volume pylon programs. |
| EASA-FAA Dual Certification Investment | Full-scale fatigue test data submissions extend approval timelines but lock out single-jurisdiction competitors. |
| Vibration Damping Technology Licensing | Acoustic attenuation integration addresses passenger comfort and noise compliance simultaneously for Chinese carriers. |
| Resin Transfer Molding Localization | Shanghai and Tianjin production hubs attract tier-one supplier investment to serve domestic narrowbody retrofit demand. |
| Integrated Structural Module Bundling | Single-source pylon-strut-fairing contracts reduce procurement complexity for US legacy carrier technical teams. |
Research Methodology
Cross-validation between primary interviews with MRO facility directors, airline technical procurement managers, composite manufacturing engineers, and FAA certification specialists and secondary validation through EASA Part 21 design validation databases, FAA airworthiness directive filings, and aerospace composite trade flow data anchors the qualitative findings. Bottom-up kit shipment analysis triangulates against top-down fleet age profile modeling and retrofit penetration assumptions across narrowbody and widebody operator segments.
Sensitivity analysis around carbon fiber price trajectories, skilled technician wage inflation, and regulatory inspection interval tightening shapes the analytical framework. Segmentation dimensions modeled include product type, technology category, application platform, and end-user authorization tier across the projection horizon. CAGRs derive from installed base aging curves, mandatory compliance deadlines, and fuel efficiency improvement documentation requirements. Forecast inputs incorporate fleet utilization rates, ETS carbon pricing exposure, and MRO capacity expansion plans.
Underlying assumptions cover stable FAA-EASA regulatory convergence, with deviation risk concentrated in raw material commodity volatility and qualified composite technician availability constraints. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.