

Air Taxi Exterior Component Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Air Taxi Exterior Component Systems Market Insights
A capital-intensity divergence between legacy aerospace suppliers and emerging eVTEL specialists is bifurcating competitive dynamics in exterior component procurement. Spirit AeroSystems leverages decades of automated fiber placement capacity to dominate large structural assemblies for next-generation airframes. Joby Aviation sustains in-house composite fabrication to control propulsion cover tolerances and accelerate design iteration cycles.
Air taxi exterior component systems encompass the structural and aerodynamic shell elements that enclose passenger cabins, landing gear bays, propulsion units, and control surfaces on electric vertical take-off and landing aircraft, typically manufactured through resin transfer molding or automated fiber placement to achieve strength-to-weight ratios exceeding 200 MPa per kg/m³ while ensuring electromagnetic interference shielding for distributed electric propulsion architectures. Carbon Fiber Reinforced Polymers command premium positioning in wing structures and fuselage segments where fatigue resistance under cyclic loading determines airworthiness qualification timelines. Aluminum Alloys retain cost advantages in access panels and non-structural fairings where part complexity remains low and machining throughput drives unit economics.
FAA Part 23 rewrite and EASA SC-VTOL special conditions are reshaping material qualification protocols and crashworthiness testing requirements for composite-intensive air taxi architectures. EPA noise standards and EU Green Deal aviation emissions benchmarks are forcing acoustic liner integration into propulsion covers and nacelle assemblies. Stakeholders must monitor certification reciprocity negotiations between regulators to anticipate where assembly localization requirements will redirect component sourcing decisions.
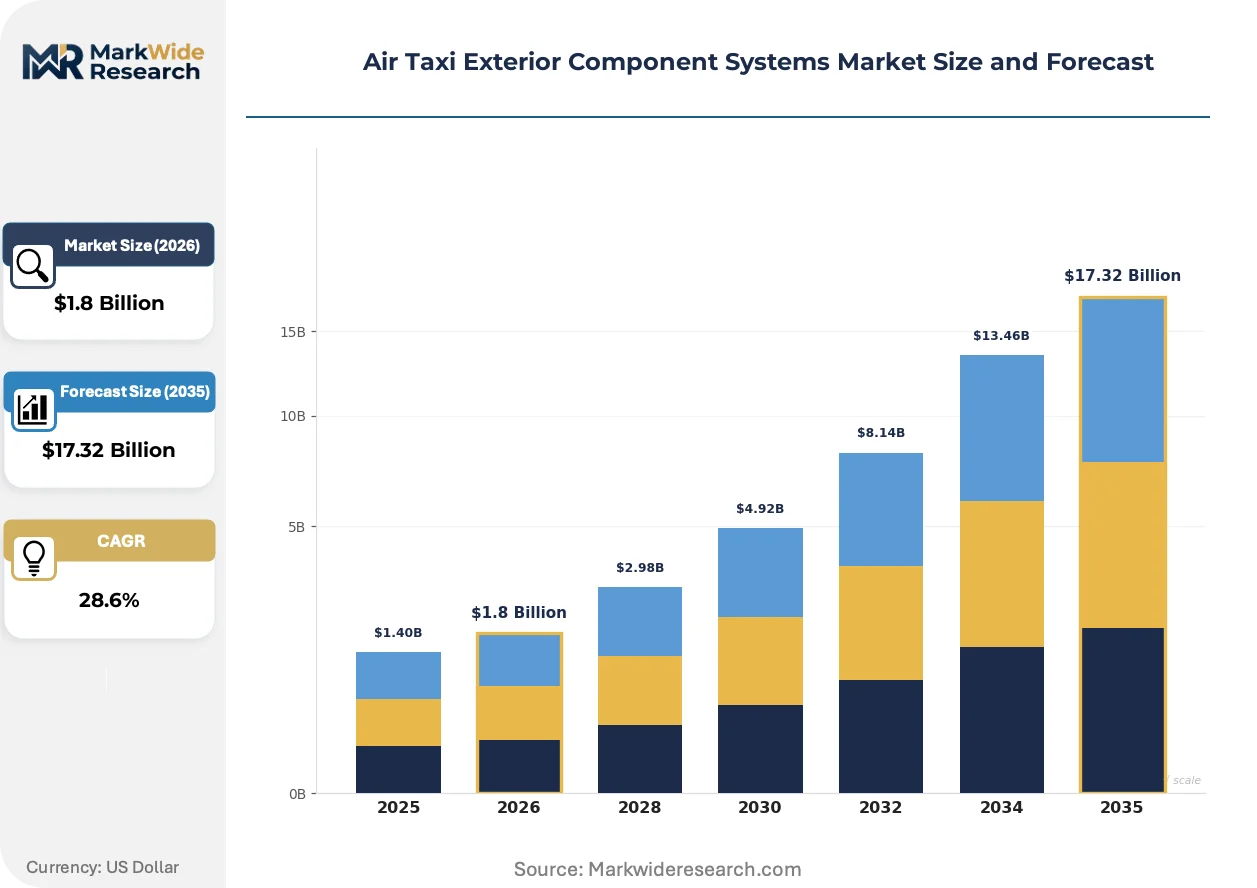
Market Dynamics
Certification reciprocity negotiations between FAA and EASA are fragmenting supply chain localization decisions, forcing component suppliers to dual-qualify manufacturing sites across California and Bavaria while awaiting harmonized airworthiness standards.
Growth Catalysts
- FAA Part 23 Rewrite:Streamlined certification pathways for composite-intensive airframes accelerate type approval timelines for electric vertical take-off aircraft, reducing regulatory friction for exterior system suppliers.
- Automated Fiber Placement:Legacy aerospace manufacturers deploy capital-intensive automated layup systems to achieve strength-to-weight ratios exceeding 200 MPa per kg/m³ in fuselage assemblies.
- Bavaria Manufacturing Cluster:Concentrated supplier ecosystems around Munich anchor advanced composite supply chains, reducing logistics costs for nacelle and propulsion cover producers.
Market Restraints
- Carbon Fiber Feedstock Volatility:Aerospace-grade precursor supply concentrates among Japanese and US chemical conglomerates, exposing component costs to petrochemical price swings.
- Electromagnetic Interference Shielding Complexity:Distributed electric propulsion architectures demand integrated EMI protection in composite shells, adding material qualification cycles without parallel weight reduction.
- Aluminum Alloy Substitution Pressure:Machined access panels and non-structural fairings face displacement risk from thermoplastic composites in cost-sensitive procurement categories.
Strategic Opportunities
- Acoustic Liner Integration:EPA noise standards and EU Green Deal aviation emissions benchmarks mandate sound-dampening propulsion covers, creating premium tier demand for engineered nacelle assemblies.
- Resin Transfer Molding Scale-Up:Mid-volume air taxi programs favor RTM cycle times over autoclave curing, rewarding suppliers with in-house tool fabrication capabilities.
- Urban Air Mobility Route Expansion:Vertiport infrastructure deployment in Dubai and Singapore generates aftermarket demand for quick-change exterior panels and damage-tolerant leading edges.
Industry Challenges
- Composite Repair Technician Scarcity:Damage tolerance assessment and field repair of carbon fiber reinforced polymer structures require specialized certification not yet standardized across MRO networks.
- Crashworthiness Testing Burden:EASA SC-VTOL special conditions impose occupant protection standards for composite fuselage segments that lack established automotive-equivalent test protocols.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air Taxi Exterior Component Systems Market Trends and Innovations
Material-process combinations are splintering along certification-grade boundaries, with automated fiber placement dominating primary structures while resin transfer molding captures secondary assemblies. This divergence reshapes supplier capability requirements and capital deployment strategies.
Automated fiber placement is bifurcating the structural tier of exterior component supply. Tier-1 aerospace suppliers deploy multi-tow robotic layup systems to achieve precise fiber orientation in wing spars and fuselage barrels. Urban air mobility specialists lacking comparable capital depth rely on outsourced preform supply or hybrid thermoplastic processing. The technology gap is compressing margin structures for mid-tier fabricators unable to amortize equipment across sufficient program volumes.
REACH substance restrictions and EU Green Deal aviation emissions benchmarks are tightening material qualification protocols for epoxy resin systems and surface treatments. European suppliers face accelerated substitution timelines for chromated primer chemistries historically standard in aerospace bonding applications. Component manufacturers serving EASA certification pathways are reformulating surface preparation workflows to maintain airworthiness qualification schedules.
Buyer consolidation around California and Bavaria vertiport operators is compressing supplier negotiation cycles and unbundling traditional aftermarket service packages. Fleet operators now specify component-level mean-time-between-replacement metrics rather than accepting standard manufacturer warranties. This specification shift is most visible in propulsion cover procurement, where acoustic liner durability guarantees have become primary selection criteria alongside unit pricing.
Air Taxi Exterior Component Systems Market Segmentation
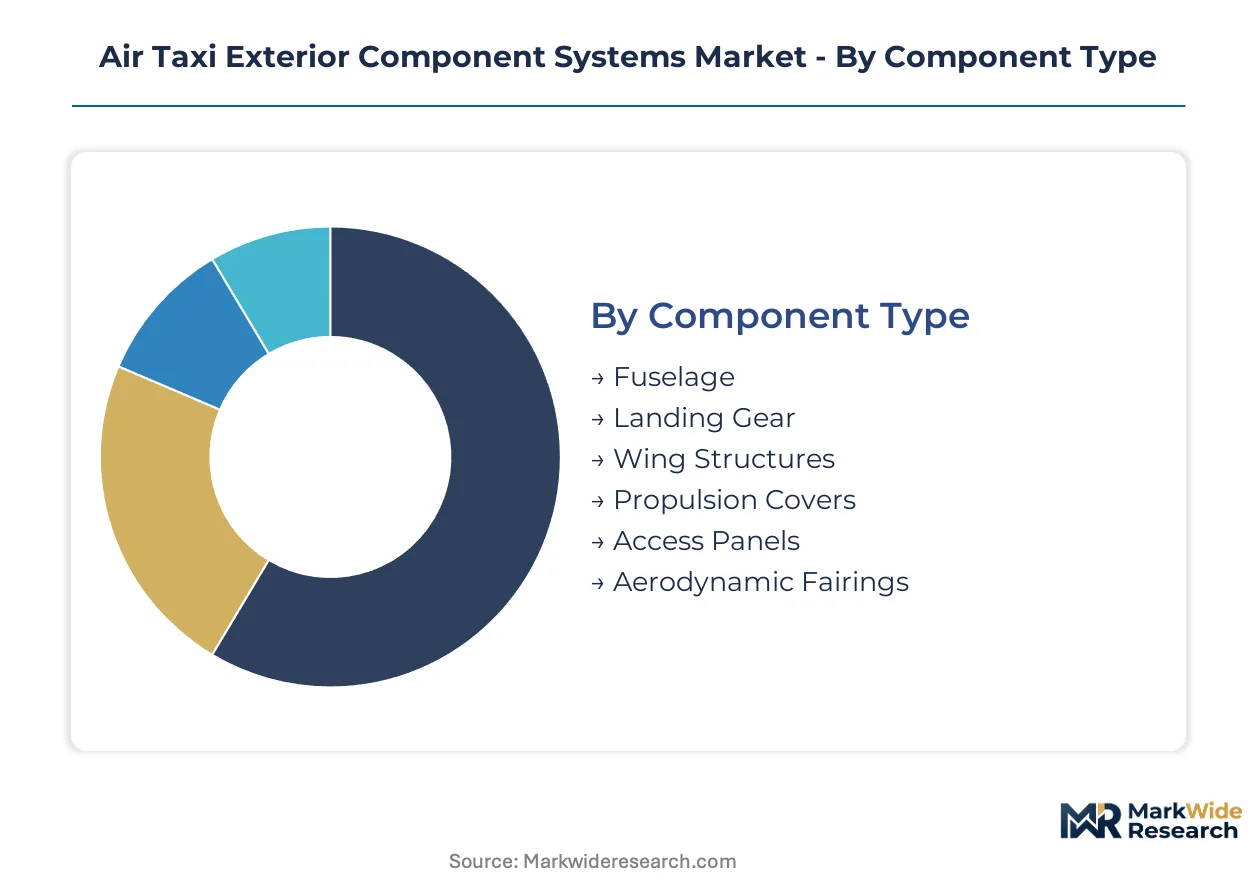
Segmentation in air taxi exterior systems reveals how certification pathways and manufacturing capabilities fragment procurement decisions across structural tiers. Component complexity, material qualification cycles, and operator business models create distinct competitive arenas with divergent margin profiles.
Component Type:
Fuselage and wing structures concentrate demand in California and Bavaria where automated fiber placement capacity anchors domestic supply chains, while propulsion covers and access panels attract export-oriented suppliers from Japan and South Korea seeking EASA and FAA dual qualification.
- Fuselage:Primary load-bearing shell assemblies enclose passenger cabins and avionics bays, demanding automated fiber placement to achieve strength-to-weight ratios exceeding 200 MPa per kg/m³. California-based Joby Aviation and Bavaria-based Lilium anchor procurement clusters here, with FAA Part 23 rewrite accelerating type approval timelines for composite-intensive architectures.
- Propulsion Covers:Nacelle assemblies shield distributed electric propulsion units while integrating acoustic liners for EPA noise compliance. Demand concentrates among urban air mobility operators in Dubai and Singapore where vertiport infrastructure deployment mandates quick-change panel specifications and damage-tolerant leading edges.
- Landing Gear:Structural bays and fairings for retractable undercarriage systems.
- Wing Structures:Spars, ribs, and skin panels forming lift-generating surfaces.
- Access Panels:Removable covers for maintenance access to avionics and power distribution.
- Aerodynamic Fairings:Non-structural surface treatments reducing form drag.
Fuselage holds the largest share; momentum sits with propulsion covers.
Material:
Cost tiers separate aerospace-grade carbon fiber systems from machined aluminum alternatives, with qualification-grade boundaries determining which suppliers capture primary versus secondary structure contracts.
- Carbon Fiber Reinforced Polymers:Aerospace-grade prepregs dominate wing spars and fuselage barrels where fatigue resistance under cyclic loading determines airworthiness timelines. Japanese and US chemical conglomerates control precursor supply, exposing component costs to petrochemical volatility while EASA SC-VTOL special conditions impose crashworthiness testing burdens without established automotive-equivalent protocols.
- Aluminum Alloys:Machined 7xxx and 2xxx series alloys retain cost advantages in access panels and non-structural fairings where part complexity remains low and machining throughput drives unit economics. REACH substance restrictions are accelerating substitution timelines for chromated primer chemistries, forcing European suppliers to reformulate surface preparation workflows.
- Titanium Alloys:High-temperature fasteners and firewall assemblies requiring corrosion resistance.
- Composites:Glass-fiber and hybrid matrices for secondary structures and interior panels.
- Kevlar Laminates:Ballistic-resistant leading edges and debris shields for low-altitude operations.
Carbon fiber reinforced polymers command premium positioning; aluminum alloys face displacement pressure from thermoplastic composites in cost-sensitive procurement categories.
Use Case:
Application urgency varies dramatically, with emergency medical transport demanding damage-tolerant designs and air tourism operators prioritizing acoustic comfort over structural redundancy.
- Urban Air Mobility:Scheduled passenger services between vertiports in congested metropolitan corridors. Fleet operators in California and Germany now specify component-level mean-time-between-replacement metrics rather than accepting standard manufacturer warranties, compressing supplier negotiation cycles around propulsion cover durability guarantees.
- Emergency Medical Transport:Air ambulance configurations requiring rapid patient loading and EMI-shielded medical equipment bays. Dubai and Singapore infrastructure deployment is generating aftermarket demand for quick-change exterior panels that minimize aircraft downtime during critical missions.
- Corporate Shuttle:Premium cabin finishes and noise-dampening interiors for executive transport.
- Law Enforcement:Surveillance sensor integration and extended loiter time aerodynamics.
- Air Tourism:Scenic flight operations with panoramic window configurations and low-altitude debris protection.
Urban air mobility holds the largest share; emergency medical transport is expanding most quickly as vertiport networks mature.
End User:
Customer type determines procurement sophistication, with aircraft manufacturers driving material qualification protocols and fleet operators unbundling traditional aftermarket service packages.
- Air Taxi Operators:Fleet-scale buyers consolidating around California and Bavaria vertiport networks. These operators are unbundling traditional aftermarket service packages and demanding acoustic liner durability guarantees as primary selection criteria alongside unit pricing.
- Aircraft Manufacturers:OEMs like Joby Aviation sustaining in-house composite fabrication to control propulsion cover tolerances and accelerate design iteration cycles. Spirit AeroSystems leverages automated fiber placement capacity to dominate large structural assemblies for next-generation airframes.
- Maintenance Providers:MRO networks facing composite repair technician scarcity as damage tolerance assessment and field repair of carbon fiber reinforced polymer structures require specialized certification not yet standardized.
- Fleet Management Companies:Third-party asset managers optimizing component life-cycle costs across mixed operator portfolios.
Aircraft manufacturers hold the largest share; air taxi operators are gaining procurement leverage fastest as fleet scales materialize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Bavaria and California where automated fiber placement capacity anchors supply chains, while procurement leverage shifts toward Dubai and Singapore vertiport operators demanding quick-change panel specifications.
United States
FAA Part 23 rewrite accelerates type approval timelines for composite-intensive airframes. EPA noise standards mandate acoustic liner integration into propulsion covers. California hosts Joby Aviation's manufacturing cluster, consolidating fuselage assembly procurement around Santa Cruz and Marina.
Germany
EASA SC-VTOL special conditions impose crashworthiness testing requirements for composite fuselage segments. REACH substance restrictions accelerate substitution timelines for chromated primer chemistries. Bavaria's Munich-centered supplier ecosystem reduces logistics costs for nacelle producers serving Lilium's assembly operations.
Japan
Aerospace-grade carbon fiber precursor supply concentrates among domestic chemical conglomerates, exposing component costs to petrochemical volatility. METI standards govern material qualification protocols for epoxy resin systems. Tokyo-Osaka industrial corridors anchor Toray Advanced Composites' prepreg manufacturing capacity.
Singapore
Vertiport infrastructure deployment generates aftermarket demand for damage-tolerant leading edges and quick-change exterior panels. The Civil Aviation Authority of Singapore coordinates urban air mobility integration with existing airspace management. Seletar Aerospace Park attracts composite component suppliers seeking EASA-FAA dual qualification pathways.
United Arab Emirates
Dubai's vertiport network expansion drives fleet-scale procurement of propulsion covers with acoustic liner durability guarantees. The General Civil Aviation Authority streamlines certification for electric vertical take-off aircraft operations. Dubai South's aviation district concentrates MRO capabilities for composite repair technician training.
Air Taxi Exterior Component Systems Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a bifurcated market structure. Legacy aerospace suppliers deploy capital-intensive automated layup systems to capture primary structural assemblies. Emerging urban air mobility specialists sustain in-house fabrication to control design iteration cycles. Strategic moves center on certification reciprocity positioning and resin transfer molding scale-up for mid-volume programs.
Within the legacy tier, Spirit AeroSystems and GKN Aerospace occupy positions defined by automated fiber placement capacity and large-assembly qualification histories. Among materials specialists, Toray Advanced Composites and Hexcel exemplify the precursor supply concentration that shapes cost structures across downstream tiers. Joby Aviation represents the vertically integrated archetype, sustaining captive composite fabrication to accelerate propulsion cover tolerance control.
| Leading Market Players |
|---|
| Toray Advanced Composites |
| Hexcel |
| Solvay |
| Spirit AeroSystems |
| GKN Aerospace |
| PPG Industries |
| Airbus |
| Boeing |
| Joby Aviation |
| Others |
Pricing and Supply Chain Analysis
Thermoplastic composite substitution for aluminum access panels is redrawing procurement geography toward Bavaria and California while compressing margin structures for legacy machined component suppliers. This material transition simultaneously concentrates pricing power with automated fiber placement operators and erodes cost advantages for machining-centric fabricators serving non-structural fairing segments.
Pricing Analysis
Configured-to-order propulsion cover assemblies command substantial premiums over standard access panel configurations. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation, with FAA Part 23 qualified fuselage segments pricing above EASA SC-VTOL provisional approvals. Cost compression in machined aluminum tiers is intensifying because thermoplastic composite throughput improvements are narrowing the unit economics gap. Fleet operators in California exhibit highest price sensitivity, while Dubai vertiport procurement teams prioritize acoustic liner durability guarantees over unit cost minimization.
Supply Chain Analysis
Extended lead times for aerospace-grade carbon fiber precursor now stretch eighteen to twenty-four months, forcing component fabricators to hold strategic resin inventory positions. Supply concentrates in Japan, the United States, and Germany, with Toray Advanced Composites and Hexcel anchoring upstream precursor capacity. Downstream fabrication draws from Bavaria and California clusters, with resin transfer molding equipment sourcing from Italian and Swiss machinery specialists. Single-source vulnerability in Japanese precursor supply exposes component costs to petrochemical volatility. Distribution runs through Tier-1 aerospace integrators holding long-term offtake agreements with vertiport fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Air taxi exterior component procurement is approaching a platform-economics inflection where standardized quick-change panel interfaces will determine supplier lock-in, mirroring the interoperability shifts that restructured commercial aviation MRO networks. EASA-FAA certification reciprocity negotiations represent the critical ecosystem coordination point that will either accelerate or fragment this standardization trajectory.
For Market Incumbents: Shield automated fiber placement capacity utilization through exclusive long-term supply agreements with California and Bavaria fleet operators facing FAA Part 23 type approval deadlines. Deepen backward integration into carbon fiber precursor supply through offtake partnerships with Japanese chemical conglomerates, reducing exposure to petrochemical price volatility that threatens margin stability in fuselage assembly contracts. For New Entrants and Emerging Players: Composite repair technician training and certification services represent a service-layer gap where incumbents under-serve MRO networks struggling with EASA SC-VTOL damage tolerance protocols. Target Dubai and Singapore vertiport infrastructure deployment zones for aftermarket quick-change panel provisioning contracts. Pursue resin transfer molding tool fabrication capabilities as the go-to-market angle, capturing mid-volume air taxi programs below the minimum efficient scale for automated fiber placement investment. For Investors and Strategic Acquirers: The market sits at a certification-ramp phase that favors vertically integrated component suppliers with captive composite fabrication and established regulator relationships. Five-to-ten year viability hinges on positioning ahead of harmonized FAA-EASA standards that will consolidate procurement around dual-qualified manufacturing footprints. Acquisition target archetype: mid-tier resin transfer molding specialists with in-house tool design capabilities serving emerging urban air mobility OEMs. Monitor EASA SC-VTOL special conditions finalization timing as the inflection signal indicating when fleet-scale procurement volumes will materialize.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Fiber Placement Capacity Expansion | Secures structural tier dominance as FAA Part 23 rewrite accelerates composite-intensive type approvals. |
| Resin Transfer Molding Tool Fabrication In-Housing | Captures mid-volume air taxi programs with cycle time advantages over autoclave curing. |
| Acoustic Liner Integration Partnership | Addresses EPA noise standards and EU Green Deal aviation emissions benchmarks for propulsion covers. |
| Dual-Qualification Manufacturing Footprint | Positions suppliers for EASA-FAA certification reciprocity outcomes across California and Bavaria clusters. |
| Composite Repair Technician Certification Program | Resolves MRO network scarcity for carbon fiber reinforced polymer damage tolerance assessment. |
Research Methodology
Cross-validation between primary interviews with air taxi OEM procurement directors, composite fabrication plant managers, and EASA certification engineers anchors the qualitative findings in operational reality. Secondary validation draws from FAA type certificate filings, EASA SC-VTOL special condition drafts, carbon fiber trade flow data from Japanese customs authorities, and vertiport infrastructure deployment announcements from Dubai South and Singapore Seletar Aerospace Park. Bottom-up build from component-level bill-of-materials analysis and top-down triangulation against fleet operator procurement forecasts ensures methodological robustness.
Sensitivity analysis around certification timeline assumptions and precursor price volatility scenarios frames the forecast confidence intervals across the projection horizon. Segmentation dimensions modeled include component type, material grade tier, use case urgency, and end-user procurement sophistication. CAGRs derive from installed base projections for electric vertical take-off aircraft and replacement cycle assumptions for damage-tolerant exterior panels. Industry-specific inputs incorporate automated fiber placement equipment capacity utilization rates and resin transfer molding cycle time improvements.
Underlying assumptions cover EASA-FAA certification reciprocity progression, carbon fiber precursor supply stability, and vertiport infrastructure deployment pacing, with deviation risk concentrated in regulatory harmonization delays and composite repair technician certification standardization failures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.