
 Liquid Rocket Engine Market | 2026-2036
Liquid Rocket Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Rocket Engine Market Insights
Recurring engine refurbishment and flight-proven hardware certification is rebalancing how value gets captured across the liquid rocket engine value chain. SpaceX leverages its vertical integration from propellant production to launch operations to compress turnaround cycles between flights. Aerojet Rocketdyne sustains long-term cost-plus contracts with NASA and the U.S. Department of Defense that anchor revenue visibility across multi-year development programs. Northrop Grumman dominates solid-liquid hybrid architectures through its OmegA heritage and strategic positioning in national security launch.
A liquid rocket engine burns liquid propellants—typically a fuel such as RP-1 or liquid hydrogen and an oxidizer such as liquid oxygen—through a combustion chamber at chamber pressures exceeding 100 bar to generate thrust via a converging-diverging nozzle. Its primary purpose is to power launch vehicles and upper stages that deliver payloads to precise orbital trajectories with throttleable thrust profiles. Staged combustion cycle architectures command premium engineering margins due to their superior specific impulse and closed-cycle efficiency, while gas generator cycle engines retain cost advantages for expendable medium-lift missions. Orbital launch vehicles absorb the dominant share of propulsion procurement, though space tourism applications are attracting development capital for human-rated engine variants.
The FAA Office of Commercial Space Transportation regulates U.S. launch licensing and environmental review under the National Environmental Policy Act, while the EPA enforces Clean Air Act provisions affecting propellant manufacturing and test firing emissions. NASA's human-rating requirements and the U.S. Space Force's National Security Space Launch certification standards further constrain which engine designs qualify for high-value government missions. Stakeholders must monitor how evolving methane-oxygen propulsion architectures and reusable certification frameworks reshape competitive qualification pathways.
Market Dynamics
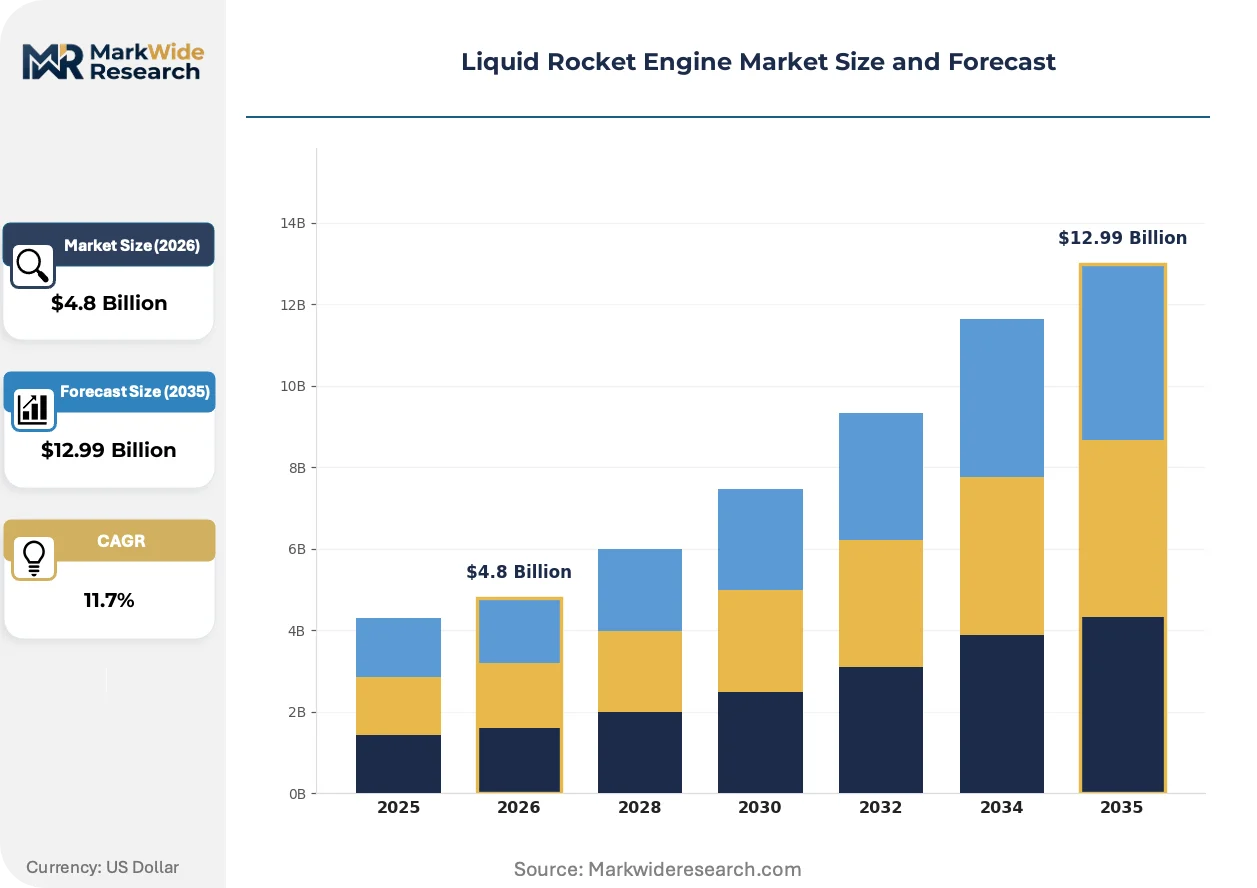
Reusable engine architectures are compressing procurement cycles and forcing suppliers to absorb refurbishment risk rather than deliver single-use hardware. This shift reallocates value capture from initial manufacturing toward flight-proven certification and rapid turnaround services.
Growth Catalysts
- Constellation Deployment Mandates:Commercial satellite operators in the United States are accelerating bulk engine orders to meet deployment deadlines for broadband networks. This creates sustained procurement visibility for throttleable upper-stage propulsion systems.
- FAA Streamlined Licensing:The FAA Office of Commercial Space Transportation has reduced environmental review timelines for qualified reusable launch vehicles. Faster certification pathways incentivize investment in human-rated engine variants.
- Methane-Oxygen Combustion:Full-flow staged combustion architectures achieve superior specific impulse while simplifying ground handling versus hydrogen systems. Propellant density advantages enable smaller tankage and higher mass fractions.
Market Restraints
- Turbopump Supply Concentration:Precision turbomachinery fabrication remains concentrated among a handful of specialized machine shops in the United States and Europe. Limited qualified suppliers create bottlenecks during production ramps.
- Clean Air Act Compliance Costs:EPA enforcement of test firing emissions limits requires extensive abatement infrastructure at development facilities. Small engine developers face disproportionate capital burdens for environmental controls.
- Solid Booster Substitution:Military payload customers retain preference for solid-liquid hybrid architectures in specific mission profiles. This segments addressable demand away from pure liquid propulsion systems.
Strategic Opportunities
- Space Tourism Certification:Human-rating requirements for suborbital and orbital passenger vehicles create demand for engine variants with enhanced safety margins. This application commands premium pricing over cargo-only configurations.
- In-Space Propulsion Convergence:Deep-space transfer stages require restartable liquid engines with extended coast capability. Mars cargo missions and lunar lander programs represent emerging procurement channels.
- Domestic Content Incentives:National Security Space Launch certification standards favor U.S.-manufactured propulsion systems. Qualified suppliers gain preferential access to Department of Defense launch contracts.
Industry Challenges
- Combustion Instability Expertise Scarcity:High-frequency oscillation suppression in full-flow architectures requires specialized acoustic modeling talent. The limited pool of experienced combustion engineers constrains development timelines.
- Hardware Qualification Capital Intensity:Flight-proven certification demands multiple test articles and extensive hot-fire campaigns. Development programs require sustained funding across multi-year validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Rocket Engine Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Propellant Type: Liquid Oxygen, Liquid Hydrogen, Kerosene, Hypergolic Propellants, Green Propellants Engine Cycle: Gas Generator Cycle, Staged Combustion Cycle, Expander Cycle, Pressure-fed Cycle, Electric Pump-fed Cycle Application: Orbital Launch Vehicles, Suborbital Spaceflight, Tactical Missiles, Scientific Research, Space Tourism End User: Government Space Agencies, Private Aerospace Firms, Defense Organizations, Research Institutions |
| Companies Covered | SpaceX, Aerojet Rocketdyne, Northrop Grumman, Safran, Mitsubishi Heavy Industries, Blue Origin, L3Harris Technologies, Rocket Lab USA, CASC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Rocket Engine Market Trends and Innovations
Additive manufacturing is reshaping how engine components move from design to qualified hardware. Topology-optimized thrust chambers and regeneratively cooled nozzles now emerge from powder-bed fusion systems with reduced part counts and consolidated supply chains.
Printed superalloy thrust chambers is converging with traditional regenerative cooling circuits to eliminate longitudinal weld seams and reduce pressure drop losses. Launch vehicle integrators in the United States are qualifying these components for reuse cycles exceeding ten flights. The technology is compressing lead times for complex coolant channel geometries while enabling iterative design optimization between test campaigns.
REACH chemical registration requirements in Europe are restricting legacy propellant additives and surface treatment chemistries used in combustion devices. Manufacturers must reformulate coatings and seal materials to maintain export compliance for European satellite customers. Small engine suppliers without dedicated regulatory affairs functions face particular disadvantage in navigating substance authorization timelines.
Long-term service agreements are displacing transactional engine sales for reusable launch systems. Operators now procure propulsion as flight-hour capacity rather than capital equipment, transferring refurbishment risk and residual value uncertainty to original manufacturers. This pattern is most visible in the United States, where SpaceX and Blue Origin have established captive maintenance infrastructure and are extending similar terms to third-party vehicle developers.
Liquid Rocket Engine Market Segmentation
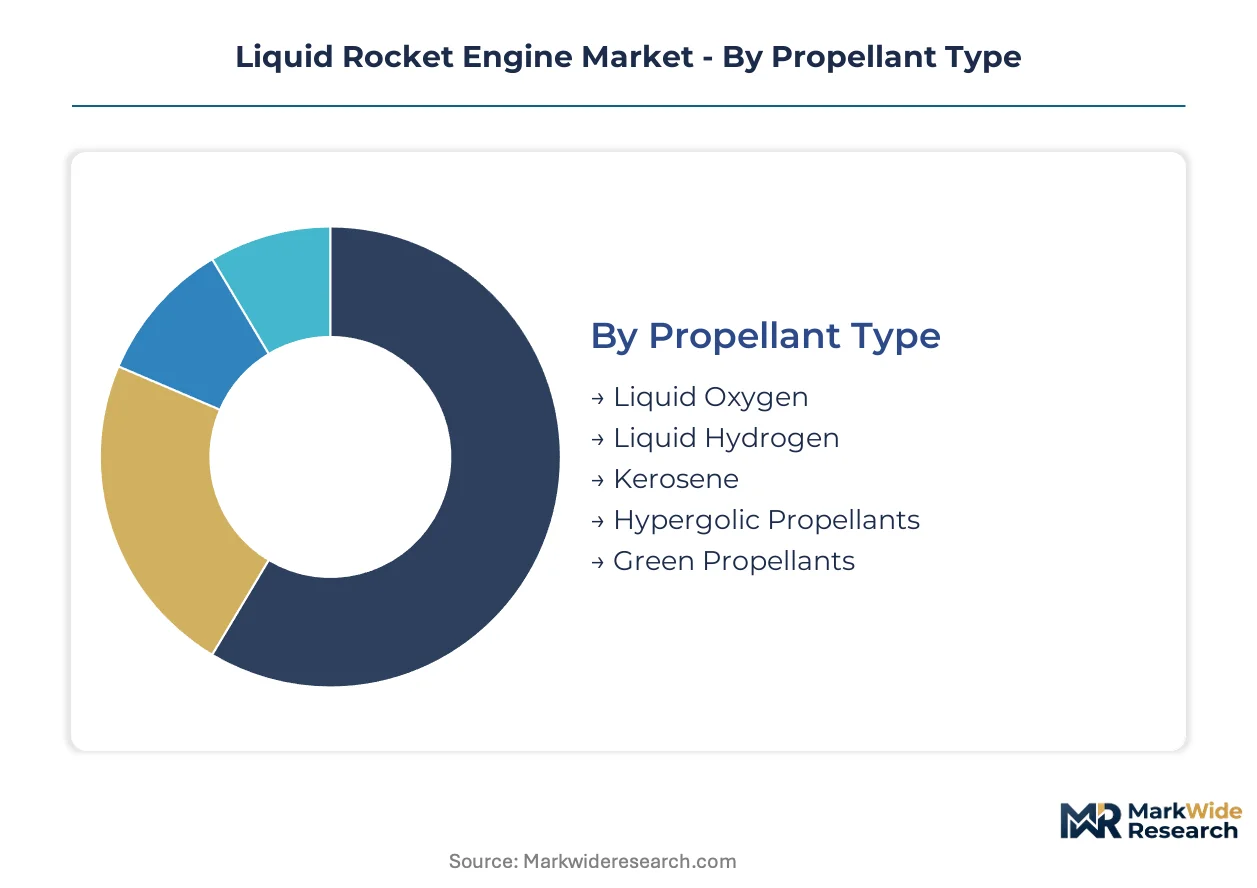
Liquid rocket engine procurement patterns diverge sharply across propellant chemistry, thermodynamic cycle architecture, and mission application. Understanding these segment boundaries clarifies where development capital concentrates versus where operational scale dominates revenue capture.
Propellant Type:
Propellant selection determines ground infrastructure requirements, storage complexity, and combustion chamber design margins. Cryogenic systems demand insulated tankage and rapid loading protocols; storable alternatives trade performance for operational flexibility.
- Liquid Oxygen:The dominant oxidizer across reusable launch architectures, stored at 90K with density advantages that reduce tankage mass. SpaceX and Blue Origin both anchor their booster stages on liquid oxygen combined with methane or kerosene, driving procurement volume in the United States.
- Liquid Hydrogen:Delivers the highest specific impulse among chemical propellants through its low molecular weight exhaust, though boil-off losses and volumetric inefficiency constrain applications. NASA's Space Launch System core stage and United Launch Alliance's Delta IV Heavy sustain demand for hydrogen-fueled upper-stage engines.
- Kerosene:RP-1 and refined petroleum derivatives offer benign handling characteristics and high propellant density, simplifying first-stage engineering. The segment retains cost advantages for expendable medium-lift missions where reusability is not required.
- Hypergolic Propellants:Self-igniting combinations of hydrazine derivatives and nitrogen tetroxide eliminate ignition system complexity for in-space propulsion. Crewed spacecraft and satellite propulsion systems in the United States and Europe maintain steady procurement for reaction control thrusters.
- Green Propellants:Low-toxicity alternatives such as ammonium dinitramide formulations reduce ground handling hazards and simplify launch site operations. European satellite manufacturers under REACH chemical registration requirements are accelerating qualification timelines for these replacements.
Volume placements concentrate in liquid oxygen and kerosene combinations; the faster expansion belongs to green propellants as regulatory pressure intensifies.
Engine Cycle:
Cycle architecture governs the trade-off between specific impulse, chamber pressure capability, and turbomachinery complexity. Each configuration embeds distinct manufacturing footprints and refurbishment economics that reshape supplier margins.
- Gas Generator Cycle:A portion of propellant burns separately to drive turbopumps, with exhaust dumped overboard. This open-cycle approach retains manufacturing simplicity and dominates expendable launch vehicle procurement in the United States.
- Staged Combustion Cycle:Pre-burner exhaust routes into the main combustion chamber for complete propellant utilization, achieving closed-cycle efficiency. The full-flow variant developed by SpaceX for its Raptor engine commands premium engineering margins through superior specific impulse.
- Expander Cycle:Regenerative cooling of the thrust chamber drives turbine work without separate combustion hardware. Upper-stage engines from Japanese and European manufacturers exploit this simplicity for restartable in-space applications.
- Pressure-fed Cycle:Helium or autogenous pressurization eliminates turbomachinery entirely, constraining chamber pressure but enabling extreme reliability. Satellite propulsion and reaction control systems in commercial constellations absorb this segment's output.
- Electric Pump-fed Cycle:Battery-powered pumps decouple turbomachinery from combustion thermodynamics, enabling throttleable deep-throttling for lunar lander descent stages. NASA's Human Landing System program and commercial lunar logistics initiatives are qualifying these architectures.
Production scale clusters on gas generator hardware; staged combustion systems are climbing the fastest as reusability mandates intensify.
Application:
Mission velocity requirements and atmospheric flight regimes segment engine specifications into distinct procurement channels. Orbital insertion demands throttleable thrust profiles and vacuum-optimized nozzles absent from tactical applications.
- Orbital Launch Vehicles:First and upper stages delivering payloads to precise orbital trajectories absorb the dominant share of propulsion procurement. Satellite constellation deployment programs from commercial operators in the United States are accelerating bulk engine orders.
- Suborbital Spaceflight:Trajectories below orbital velocity require shorter burn durations and less aggressive mass fraction optimization. Blue Origin's New Shepard and emerging point-to-point hypersonic concepts sustain demand for human-rated variants.
- Tactical Missiles:Solid-liquid hybrid architectures retain preference for rapid-response military payloads, segmenting demand away from pure liquid systems. The U.S. Department of Defense and allied defense organizations specify storable propellants for operational readiness.
- Scientific Research:Sounding rockets and technology demonstration missions demand specialized engines for atmospheric sampling and microgravity platforms. NASA's Wallops Flight Facility and European Space Agency's Esrange operations anchor this procurement channel.
- Space Tourism:Human-rating requirements for passenger vehicles create demand for engine variants with enhanced safety margins and abort capability. FAA streamlined licensing for qualified reusable launch vehicles is compressing certification timelines.
Contract value aggregates in orbital launch; space tourism applications are gaining share fastest as commercial human spaceflight matures.
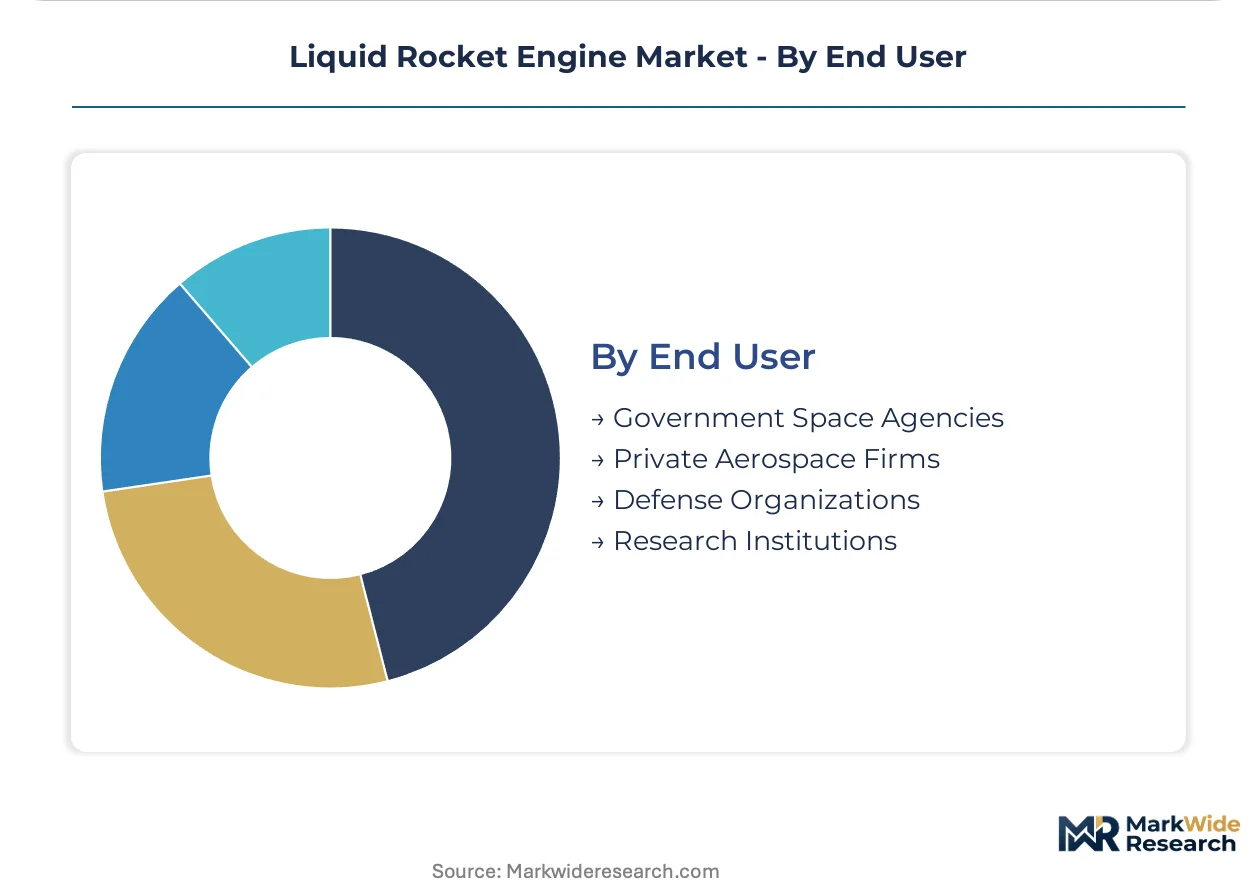
End User:
Customer procurement models diverge between cost-plus development contracts and fixed-price commercial competitions. Government anchor demand provides revenue visibility; private operators drive cost reduction and reusability investment.
- Government Space Agencies:NASA's Artemis program and deep-space exploration initiatives sustain multi-year development contracts for high-performance cryogenic engines. Cost-plus contracting structures absorb technical risk across extended qualification campaigns.
- Private Aerospace Firms:SpaceX, Blue Origin, and emerging launch vehicle developers procure propulsion through vertical integration or strategic supplier partnerships. These operators transfer refurbishment risk to original manufacturers through flight-hour service agreements.
- Defense Organizations:The U.S. Space Force's National Security Space Launch certification standards constrain which engine designs qualify for high-value government missions. Domestic content incentives favor U.S.-manufactured propulsion systems for national security payloads.
- Research Institutions:Universities and government laboratories acquire subscale engines and test hardware for fundamental combustion research and workforce development. Limited procurement scale constrains supplier engagement beyond specialized component vendors.
Program volume concentrates with government space agencies; private aerospace firms are expanding procurement most aggressively as launch cadence multiplies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Huntsville, Alabama anchors North American liquid rocket engine activity through NASA's Marshall Space Flight Center and the concentrated defense aerospace corridor along the Tennessee River. The United States, France, China, Japan, and India concentrate distinct competitive advantages across propulsion development, manufacturing scale, and launch infrastructure.
United States
SpaceX and Blue Origin drive reusable engine procurement cycles through vertical integration from propellant production to launch operations. The FAA Office of Commercial Space Transportation imposes launch licensing and environmental review timelines that compress certification pathways for qualified reusable vehicles. The Greater Los Angeles industrial basin concentrates precision turbomachinery fabrication and hot-fire test facilities.
France
Safran sustains European cryogenic engine leadership through Ariane program heritage and full-flow staged combustion development. ECHA REACH chemical registration requirements restrict legacy propellant additives and surface treatment chemistries used in combustion devices. The Paris-Saclay aerospace cluster coordinates research institutions and specialized suppliers for next-generation propulsion architectures.
China
CASC and commercial spin-offs accelerate methane-oxygen engine qualification for reusable launch vehicle programs. MIIT and SAMR enforce GB standards for propellant manufacturing and test facility emissions that shape domestic certification frameworks. The Xi'an aerospace industrial base concentrates liquid propellant rocket engine design bureaus and high-pressure combustion test infrastructure.
Japan
Mitsubishi Heavy Industries sustains expander-cycle upper-stage engine production for H3 launch vehicle deployment. METI coordinates national space development policy that prioritizes restartable in-space propulsion for lunar exploration missions. The Nagoya aerospace manufacturing corridor integrates precision casting facilities with JAXA's Tanegashima launch range operations.
India
ISRO's commercial arm and emerging private launch vehicle developers procure cryogenic and semi-cryogenic engines for constellation deployment. The CEA regulates electrical infrastructure and safety standards affecting propellant production and test facility operations. The Sriharikota spaceport and Bengaluru aerospace cluster concentrate engine assembly, integration, and static test capabilities.
Liquid Rocket Engine Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the liquid rocket engine value chain. The market structure concentrates among vertically integrated launch vehicle operators and specialized propulsion contractors serving government anchor demand. Three archetypes dominate: captive engine developers owning full production-to-launch pipelines; cost-plus contractors sustaining multi-year development programs; and emerging suppliers qualifying novel cycle architectures. Strategic moves center on backward integration into precision turbomachinery and long-term service agreements displacing transactional hardware sales.
Among U.S.-based integrated operators, SpaceX exemplifies the captive development archetype through closed-loop control from propellant to reuse certification. Aerojet Rocketdyne occupies a position within the established defense contractor tier, while Blue Origin represents the privately funded vertical integration model. These three anchors illustrate how funding structure—public cost-plus versus private capital—determines competitive positioning across refurbishment economics and certification risk allocation.
| Leading Market Players |
|---|
| SpaceX |
| Aerojet Rocketdyne |
| Northrop Grumman |
| Safran |
| Mitsubishi Heavy Industries |
| Blue Origin |
| L3Harris Technologies |
| Rocket Lab USA |
| CASC |
| Others |
Pricing and Supply Chain Analysis
Government space agencies and defense procurement programs anchor demand for liquid rocket engines, locking in long-term cost-plus contracts that insulate prime contractors from spot-market volatility while compressing margins for component suppliers.
Pricing Analysis
Flight-proven certification and rapid turnaround capacity anchor value-based pricing for reusable engine architectures. Three-tier pricing structure across premium, standard, and economy levels separates human-rated variants with enhanced safety margins from cargo-only configurations and expendable gas-generator hardware. Cost compression in expendable kerosene-fueled segments is intensifying because constellation operators prioritize procurement scale over performance optimization. Commercial satellite constellation developers exhibit highest price sensitivity; government human-spaceflight programs demonstrate lowest sensitivity due to mission-critical reliability requirements.
Supply Chain Analysis
Domestic content mandates under the U.S. Space Force's National Security Space Launch certification standards are reshaping sourcing toward U.S.-based precision turbomachinery fabricators. Supply concentration clusters in the United States, France, and China, with specialized machine shops in the Greater Los Angeles industrial basin and Paris-Saclay aerospace cluster dominating high-pressure combustion component production. Raw material dependencies draw from nickel-based superalloys, high-purity oxygen and methane propellants, and precision-machined turbopump impellers. Single-source vulnerability in qualified turbomachinery suppliers creates bottlenecks during production ramps. Distribution runs through captive vertical integration at SpaceX and Blue Origin, with strategic supplier partnerships sustaining Aerojet Rocketdyne and legacy defense contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liquid rocket engine market functions as a cost-of-compliance arena where EPA Clean Air Act enforcement and FAA launch licensing create regulatory moats that reward incumbents with established environmental abatement infrastructure and qualified certification pathways.
For Market Incumbents: Acquire specialized combustion instability modeling talent pools to defend against full-flow staged combustion entrants. Secure backward integration into powder-bed fusion additive manufacturing capacity to compress thrust chamber lead times and capture refurbishment economics from emerging reusable launch vehicle developers. Lock in long-term propellant supply agreements with domestic oxygen and methane producers to insulate against commodity volatility. For New Entrants and Emerging Players: Begin with electric pump-fed cycle architectures for lunar lander descent stages, where NASA's Human Landing System program offers penetrable qualification pathways absent from established booster engine competitions. Target restartable in-space propulsion for deep-space transfer stages, a white-space segment where expander-cycle heritage from Japanese and European manufacturers has not fully addressed Mars cargo mission requirements. Pursue qualification partnerships with university research institutions to access subscale test infrastructure and workforce pipelines. For Investors and Strategic Acquirers: The window for entry favors specialized turbomachinery fabricators with established hot-fire test relationships and EPA-permitted facilities. Long-term viability hinges on positioning upstream of the flight-hour service agreement transition, where engine OEMs absorb refurbishment risk and residual value uncertainty from launch vehicle operators. Watch for FAA streamlined licensing decisions on reusable vehicle certification as the inflection signal for human-rated engine variant demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Turbomachinery Acquisition | Consolidates supply control for high-pressure combustion components serving SpaceX and Blue Origin. |
| Additive Manufacturing Qualification | Enables topology-optimized thrust chambers with reduced part counts for ten-flight reuse cycles. |
| Flight-Hour Service Agreement Expansion | Transfers refurbishment risk from launch operators to original manufacturers under long-term contracts. |
| Green Propellant Formulation Investment | Addresses ECHA REACH chemical registration requirements for European satellite constellation customers. |
| Domestic Test Facility Infrastructure | Secures EPA-permitted hot-fire capacity required for full-flow staged combustion qualification campaigns. |
Research Methodology
SEC filings from publicly traded aerospace contractors, FAA launch licensing databases, and EPA emissions compliance records formed the secondary backbone for market sizing and competitive positioning. Primary interviews with propulsion engineering directors, turbomachinery procurement leads at launch vehicle integrators, hot-fire test facility managers, and regulatory affairs specialists at engine OEMs validated technical assumptions and refurbishment economics. Bottom-up segmentation by propellant type, cycle architecture, and application combined with top-down triangulation against government procurement budgets and commercial launch manifests.
Historical trendline analysis of engine delivery schedules, hot-fire test campaigns, and qualification milestones established baseline growth trajectories across the projection horizon. The analytical framework modeled propellant chemistry segments, thermodynamic cycle tiers, mission applications, and end-user procurement structures. CAGRs derived from satellite constellation deployment timelines, reusable launch vehicle flight rates, and human-spaceflight program milestones. Industry-specific inputs included turbopump production capacity constraints, Clean Air Act compliance cost curves, and National Security Space Launch certification timelines.
Combustion instability modeling talent scarcity, turbopump supply concentration events, and REACH chemical registration timeline delays are the dominant revision risks that could compress or extend forecast outputs. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aircraft and Aerospace Components
Low-Noise Landing Gear Fairing Composite Designs Market
Aircraft and Aerospace Components
Composite Wing-to-Body Fairing Structures for Wide-Body Aircraft Market
Aircraft and Aerospace Components
Aviation Connector Market
Aircraft and Aerospace Components
Commercial Aircraft Turbine Blades and Vanes Market
Aircraft and Aerospace Components
Composite Pylon Fairing Systems for New Engine Options Market
Aircraft and Aerospace Components
Global Aerospace Wiring Harness Market
Aircraft and Aerospace Components
Commercial Airframe Component Market
Aircraft and Aerospace Components
Commercial Aircraft Aftermarket Parts Market
Aircraft and Aerospace Components
Helicopter Blades Market
Aircraft and Aerospace Components
Aircraft Brackets Market
Aircraft and Aerospace Components
Advanced Turbine Blade Design Market
Aircraft and Aerospace Components
Advanced Composite Fuselage Panel Systems for Next-Gen Narrow-Bodies Market
Aircraft and Aerospace Components
Aircraft Brake Calipers Market
Aircraft and Aerospace Components
Global Commercial Aircraft Airframe Materials Market
Aircraft and Aerospace Components
Aircraft Wiring Harness Market
Aircraft and Aerospace Components
Aircraft Nacelle Components Market