
 Global Endocrine Testing Market | 2026-2036
Global Endocrine Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Endocrine Testing Market Foresight
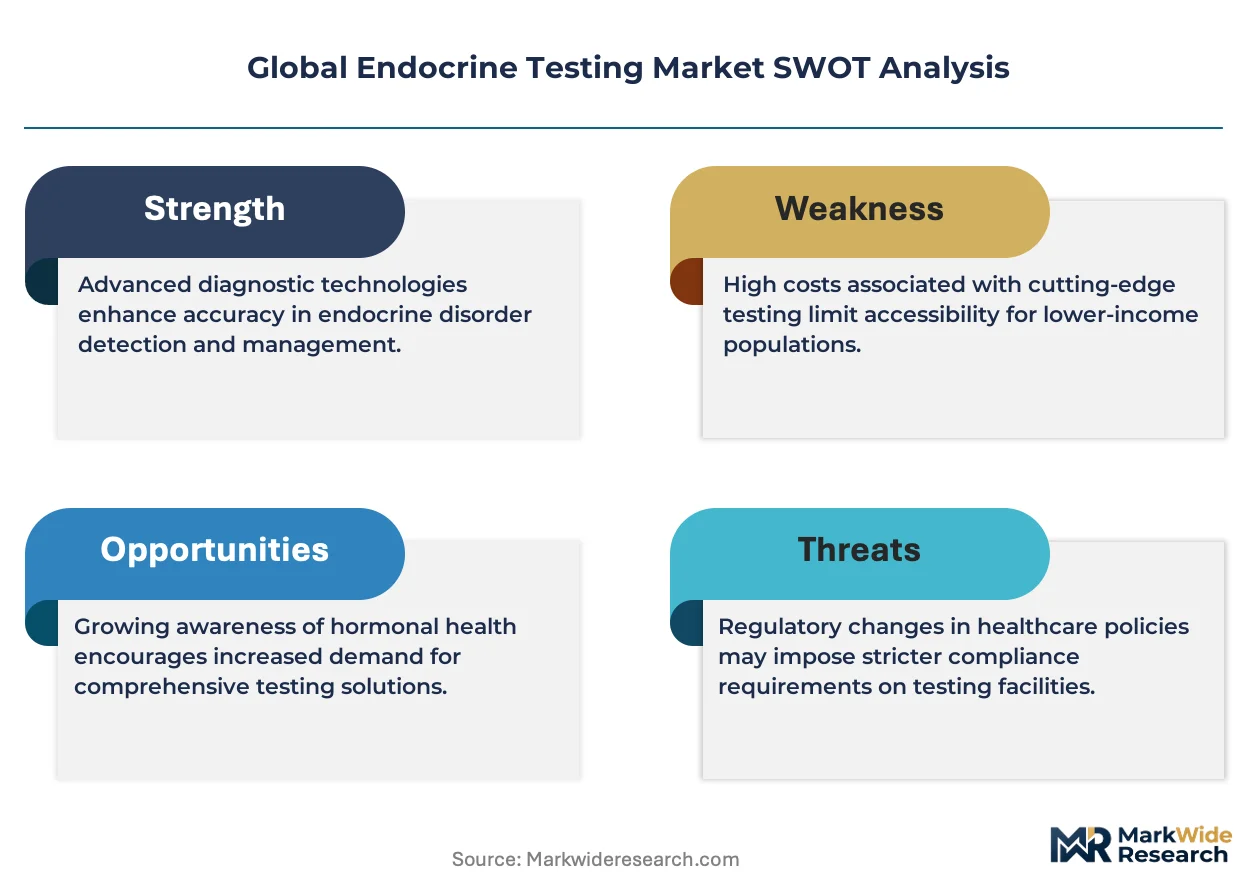
Recurring software-defined assay protocols is hardening into a distinct revenue layer, with vendors bundling algorithmic interpretation modules alongside hardware placements. Thermo Fisher Scientific leverages its ion chromatography-mass spectrometry integration to anchor high-complexity endocrine panels in reference laboratories. Abbott Laboratories competes through point-of-care immunoassay platforms that extend testing into physician office settings. bioMérieux specializes in automated electrochemiluminescence workflows that dominate European hospital laboratory contracts.
Endocrine testing encompasses analytical methods that quantify hormone concentrations, metabolite markers, and receptor activity in biological specimens, typically requiring detection sensitivities in the picogram-per-milliliter range for biologically active peptides. These diagnostics serve to characterize glandular dysfunction, monitor therapeutic interventions, and stratify metabolic disease risk across clinical populations. Thyroid function testing occupies the largest volume share within test type segmentation, reflecting the high prevalence of subclinical hypothyroidism in aging demographics. Mass spectrometry is displacing older immunoassay platforms for steroid hormone quantification where cross-reactivity historically compromised specificity. Diagnostic laboratories capture the dominant end-user channel position, though specialty clinics are building captive testing capacity to improve margin capture on repeat monitoring protocols.
FDA oversight of laboratory-developed tests and CLIA proficiency requirements shape analytical performance standards and market access conditions in the United States. EMA's In Vitro Diagnostic Regulation and REACH chemical compliance frameworks impose parallel conformity obligations on manufacturers serving European Union member states. WHO prequalification pathways influence procurement decisions in low-resource health systems. Stakeholders must monitor evolving reimbursement benchmarks for algorithm-augmented interpretation as payers scrutinize the clinical utility of software-embedded diagnostic outputs.
Market Dynamics
Mass spectrometry is consolidating analytical workflows across reference laboratories, compressing turnaround times for steroid hormone panels while forcing incumbent immunoassay vendors to defend installed bases through service bundling rather than hardware differentiation.
Growth Catalysts
- Subclinical hypothyroidism screening:Aging demographics in Germany, Japan, and the United States are expanding routine thyroid panel volumes in primary care settings.
- EMA In Vitro Diagnostic Regulation:Harmonized conformity assessment pathways are reducing technical barriers for manufacturers seeking multi-country European contracts.
- Algorithmic interpretation modules:Software-defined assay protocols are creating recurring revenue streams alongside instrument placements in integrated delivery networks.
Market Restraints
- Helium supply volatility:Gas chromatography-mass spectrometry operations face input cost pressure from concentrated Middle Eastern and North American helium production.
- FDA laboratory-developed test oversight:Evolving validation requirements for domestic manufacturers are extending time-to-market for novel biomarker assays.
- Cross-reactivity in polyclonal antibodies:Immunoassay specificity limitations for structurally similar steroid hormones drive false-positive rates in fertility panels.
Strategic Opportunities
- India's tier-two hospital laboratory buildout:Underpenetrated secondary cities present whitespace for automated electrochemiluminescence platform deployments.
- Continuous glucose monitoring integration:Convergence of wearable sensor data with laboratory HbA1c protocols is creating hybrid diabetes management workflows.
- Direct-to-consumer hormone testing:Regulatory tailwinds from Health Canada's progressive stance on consumer-initiated laboratory access are opening new channel structures.
Industry Challenges
- Mass spectrometry operator certification:Specialized technical training programs lag instrument deployment timelines in hospital laboratories.
- CLIA proficiency validation:Extended compliance timelines for high-complexity testing sites strain quality assurance staffing.
- Legacy immunoassay system integration:Middleware compatibility issues complicate algorithmic module deployment in multi-vendor instrument environments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Endocrine Testing Market |
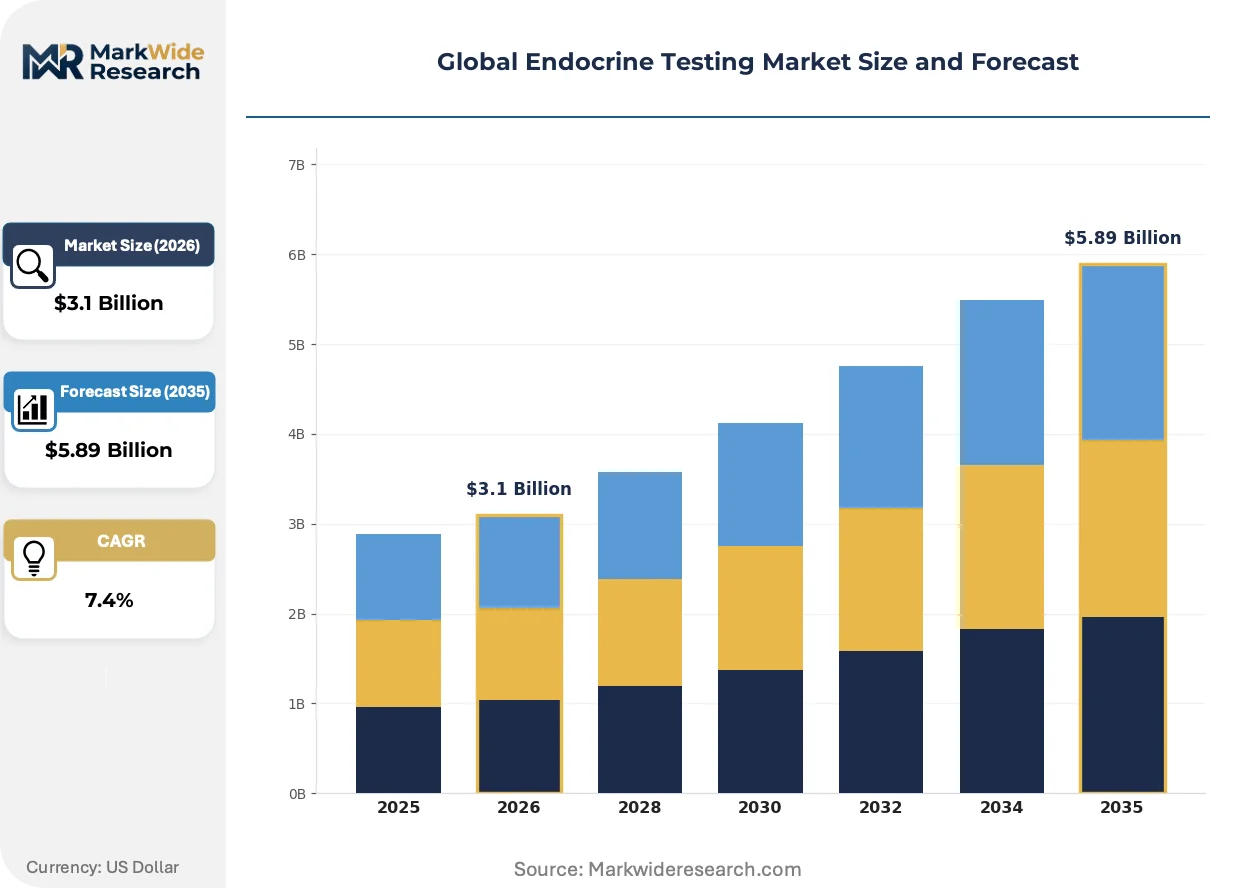
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.89 Billion |
| CAGR (2026 – 2036) | 7.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Test Type: Thyroid Function, Adrenal Function, Pituitary Function, Reproductive Hormones, Calcium Metabolism Technology: Immunoassay, Chromatography, Mass Spectrometry, Electrochemiluminescence, Fluorescence Immunoassay Application: Diabetes Monitoring, Osteoporosis Diagnosis, Infertility Evaluation, Growth Disorders, Metabolic Syndrome End User: Diagnostic Laboratories, Research Institutes, Specialty Clinics, Academic Centers, Independent Testing Facilities |
| Companies Covered | Thermo Fisher Scientific, Agilent Technologies, Roche Diagnostics, Beckman Coulter, Quest Diagnostics, Abbott Laboratories, Bio-Rad Laboratories, bioMérieux, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Endocrine Testing Market Shifts & Advancements
Workflow automation and software-embedded diagnostics are compressing the traditional separation between analytical instrumentation and clinical decision support, reshaping how laboratories capture value from endocrine testing services.
Liquid chromatography-tandem mass spectrometry is consolidating steroid hormone quantification workflows in reference laboratories. Academic medical centers and large health systems in the United States are replacing aging radioimmunoassay platforms with these systems at accelerated replacement cycles. The technology is consolidating analytical specificity advantages into centralized laboratory footprints while marginalizing point-of-care alternatives for complex endocrine panels.
REACH chemical compliance frameworks are reshaping reagent manufacturing supply chains for European Union market access. ECHA substance restriction proposals for certain plasticizers and stabilizers are forcing reformulation of assay consumables and control materials. In vitro diagnostic manufacturers serving Germany, France, and the Netherlands are accelerating alternative material qualification programs to maintain CE marking continuity.
Integrated delivery networks are consolidating laboratory purchasing decisions through centralized procurement committees in the United States. Specialty clinics seeking to reduce referral leakage are building captive immunoassay capacity for repeat monitoring protocols. This behavioral shift is most visible in metropolitan health systems where vertical integration between physician practices and hospital laboratories has advanced furthest.
Global Endocrine Testing Market Segmentation
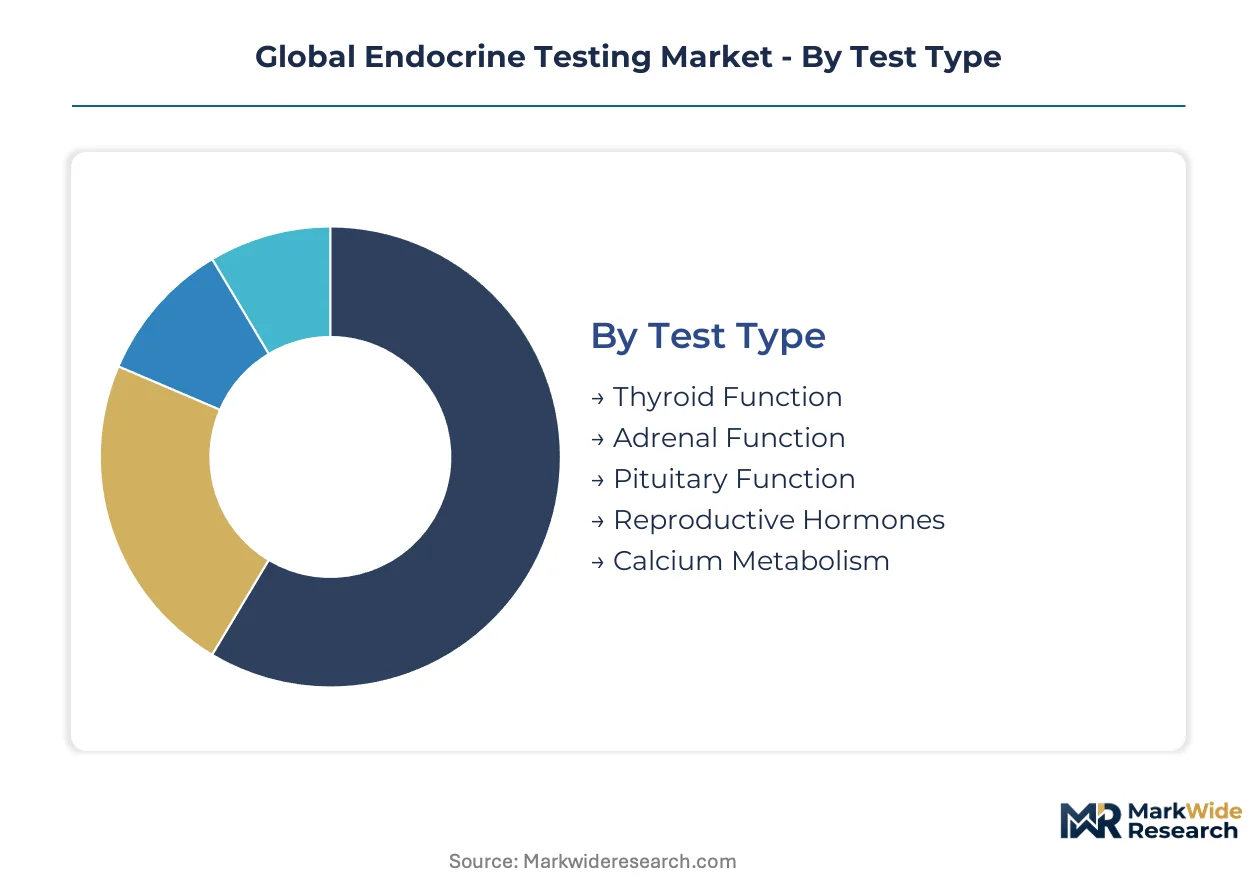
Endocrine testing segmentation reflects divergent technical requirements across hormone classes, with detection sensitivity thresholds and analytical specificity demands shaping instrument selection and workflow design. Test type and technology choices cascade into application priorities and end-user channel economics, creating distinct competitive battlegrounds for vendors.
Test Type:
Detection sensitivity requirements and clinical prevalence patterns determine volume distribution across hormone panels, with picogram-per-milliliter thresholds for biologically active peptides driving platform selection.
- Thyroid Function:TSH, free T4, and free T3 quantification dominates routine screening volumes. Aging populations in Germany, Japan, and the United States sustain high panel frequency in primary care settings where subclinical hypothyroidism detection drives preventive protocols.
- Adrenal Function:Cortisol, aldosterone, and DHEA-S testing requires diurnal sampling protocols and specialized collection handling. Reference laboratories in the United States capture complex panels where mass spectrometry displacement of immunoassay methods addresses historical cross-reactivity limitations.
- Pituitary Function:Growth hormone, prolactin, and ACTH measurements serve specialized endocrinology referrals with lower throughput requirements.
- Reproductive Hormones:Estradiol, progesterone, testosterone, and LH/FSH panels support fertility clinics and gynecological practices with cyclical monitoring demands.
- Calcium Metabolism:PTH and vitamin D testing anchors osteoporosis management and chronic kidney disease protocols in integrated delivery networks.
Thyroid function leads on scale; adrenal function panels gain share fastest as mass spectrometry penetration accelerates specificity advantages.
Technology:
Cost-performance tradeoffs and regulatory compliance burdens stratify adoption patterns, with capital intensity and operator certification requirements filtering market access.
- Immunoassay:Enzyme-linked and chemiluminescent methods retain installed base dominance in high-throughput hospital laboratories. Abbott Laboratories and Roche Diagnostics defend positions through reagent-locked consumable economics and CLIA-waived platform certifications.
- Mass Spectrometry:LC-MS/MS systems consolidate steroid hormone workflows in reference laboratories seeking analytical specificity advantages. Thermo Fisher Scientific's ion chromatography integration anchors high-complexity panel positioning where FDA laboratory-developed test oversight shapes validation timelines.
- Chromatography:HPLC methods serve niche vitamin D and catecholamine applications with moderate capital requirements.
- Electrochemiluminescence:bioMérieux automated workflows dominate European hospital contracts through CE marking continuity under EMA In Vitro Diagnostic Regulation harmonization.
- Fluorescence Immunoassay:Point-of-care platforms extend testing into physician office settings with waived complexity designations.
Immunoassay retains volume leadership; mass spectrometry climbs the fastest as reference laboratories replace aging radioimmunoassay infrastructure.
Application:
Chronic disease prevalence and therapeutic monitoring frequency determine panel economics, with reimbursement stability varying across clinical indications.
- Diabetes Monitoring:HbA1c and insulin testing combines laboratory protocols with continuous glucose monitor data convergence. Hybrid workflows in United States integrated delivery networks merge wearable sensor streams with centralized laboratory validation.
- Infertility Evaluation:Reproductive hormone panels require cyclical timing precision and rapid turnaround. Specialty clinics in metropolitan United States health systems build captive immunoassay capacity to reduce referral leakage on repeat monitoring.
- Osteoporosis Diagnosis:Vitamin D and bone turnover marker testing serves aging demographics with seasonal variation in deficiency patterns.
- Growth Disorders:IGF-1 and growth hormone stimulation testing remains concentrated in pediatric endocrinology referral centers.
- Metabolic Syndrome:Cortisol, insulin, and adipokine panels support cardiometabolic risk stratification with emerging algorithmic interpretation modules.
Diabetes monitoring leads on scale; infertility evaluation expands most quickly as specialty clinics capture repeat testing economics.
End User:
Purchasing consolidation and margin capture incentives reshape channel dynamics, with vertical integration between physician practices and laboratory assets altering competitive access.
- Diagnostic Laboratories:Centralized reference and hospital laboratory networks capture high-complexity panel volumes. United States integrated delivery networks consolidate procurement decisions through centralized committees, compressing vendor access points.
- Specialty Clinics:Endocrinology and fertility practices build captive testing capacity for routine monitoring protocols. This behavioral shift concentrates in metropolitan health systems where backward integration into laboratory assets has advanced furthest.
- Research Institutes:Academic medical centers drive mass spectrometry replacement cycles and novel biomarker assay development.
- Academic Centers:Training programs and proficiency testing operations sustain demand for multi-platform instrument installations.
- Independent Testing Facilities:Freestanding laboratories compete on turnaround time and direct-to-consumer channel access where Health Canada regulatory tailwinds enable consumer-initiated testing.
Diagnostic laboratories lead on scale; specialty clinics gain share fastest as in-house panel buildout reduces external referral dependency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints as vendors relocate production to jurisdictions with streamlined IVD conformity pathways. Cost-of-compliance gaps between the FDA's evolving LDT oversight and EMA's harmonized IVDR framework are accelerating facility investments in European contract manufacturing zones.
United States
Integrated delivery networks in Texas and Florida are consolidating laboratory procurement through centralized committees, compressing vendor access points to single decision nodes. FDA laboratory-developed test oversight is extending validation timelines for novel biomarker assays, particularly affecting reference laboratories in the Boston-Cambridge corridor. Academic medical centers in California are driving mass spectrometry replacement cycles at Stanford and UCLA Health systems.
Germany
Aging demographics in Bavaria and North Rhine-Westphalia are expanding routine thyroid panel volumes in primary care networks. EMA In Vitro Diagnostic Regulation harmonization is reducing technical barriers for manufacturers seeking multi-country European contracts. The Rhine-Main cluster around Frankfurt anchors automated electrochemiluminescence platform deployments serving hospital laboratory contracts across Central Europe.
Japan
Subclinical hypothyroidism screening protocols in Tokyo and Osaka metropolitan areas are sustaining high panel frequency in aging patient populations. METI industrial standards for in vitro diagnostics are shaping domestic manufacturing quality benchmarks. The Kansai region's medical device corridor, centered on Osaka, concentrates reagent production for thyroid and adrenal function assays.
India
Tier-two hospital laboratory buildouts in Maharashtra and Karnataka present whitespace for automated platform deployments. CDSCO medical device regulations are harmonizing with global standards through the PLI scheme for domestic manufacturing incentives. Hyderabad's diagnostic reagent cluster is attracting contract manufacturing investments from multinational IVD vendors seeking cost-competitive production bases.
Canada
Health Canada's progressive stance on consumer-initiated laboratory access is opening direct-to-consumer hormone testing channels in Ontario and British Columbia. PMRA oversight of medical devices maintains alignment with FDA quality standards while permitting faster market entry for algorithm-augmented diagnostics. Toronto's health technology corridor is incubating hybrid workflow platforms that merge wearable sensor data with centralized laboratory validation.
Global Endocrine Testing Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with full-platform vendors defending installed bases through reagent-locked consumable economics while modular specialists capture niche assay development. The vendor landscape organizes around three archetypes: diversified life sciences conglomerates with chromatography-mass spectrometry integration, point-of-care immunoassay platform specialists, and automated electrochemiluminescence workflow providers. Consolidation pressures favor acquisition of algorithmic interpretation module developers, while geographic expansion into India's secondary cities represents the dominant capacity-building move.
Among diversified instrumentation conglomerates, Thermo Fisher Scientific and Agilent Technologies occupy positions anchoring high-complexity reference laboratory workflows through mass spectrometry platform dominance. Roche Diagnostics and Abbott Laboratories exemplify the point-of-care and hospital laboratory immunoassay archetype, defending positions through CLIA-waived certifications and reagent supply continuity. bioMérieux represents the European automated workflow specialist, securing hospital contracts through CE marking continuity under EMA harmonization.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Agilent Technologies |
| Roche Diagnostics |
| Beckman Coulter |
| Quest Diagnostics |
| Abbott Laboratories |
| Bio-Rad Laboratories |
| bioMérieux |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
Integrated delivery network procurement committees in the United States have concentrated purchasing power into single decision nodes, forcing vendors toward reagent-locked consumable economics and algorithmic module bundling rather than standalone instrument sales. This buyer concentration tilts pricing power toward high-throughput hospital laboratories while squeezing margins for point-of-care platform specialists competing on waived-complexity certifications.
Pricing Analysis
Capacity additions in India's reagent manufacturing corridors are reshaping price floors for immunoassay consumables, pressuring legacy European suppliers. Three-tier pricing structure across premium, standard, and economy levels separates mass spectrometry-anchored reference laboratories from hospital immunoassay platforms and point-of-care fluorescence systems. Price differentiation hinges on CLIA complexity certification and algorithmic interpretation bundling. Cost compression in standard-tier electrochemiluminescence workflows is intensifying because bioMérieux and Roche Diagnostics defend European installed bases through service-lock contracts. Specialty clinics exhibit highest price sensitivity due to captive buildout economics, while academic medical centers prioritize analytical specificity over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with concentrated helium production in Qatar and the United States, which feeds gas chromatography-mass spectrometry operations. Manufacturing concentration clusters in Germany, the United States, and Japan for high-precision optical components and ion source assemblies. Raw material dependencies include rare earth elements for laser systems, specialized polymers for microfluidic cartridges, and high-purity solvents for chromatography. Tariff exposure runs through transatlantic instrument shipments facing evolving customs classifications under EMA-FDA regulatory divergence. Distribution runs through authorized distributor networks serving hospital laboratories and direct contracts with integrated delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EMA In Vitro Diagnostic Regulation harmonization reduces compliance costs relative to FDA laboratory-developed test oversight, favoring European contract manufacturing investments.
For Market Incumbents: Anchor high-complexity reference laboratory workflows through mass spectrometry platform dominance while algorithmic interpretation modules create recurring revenue insulation. Defend against Thermo Fisher Scientific's ion chromatography integration by accelerating CLIA-waived certifications for point-of-care immunoassay platforms. Prioritize backward integration into reagent manufacturing to offset helium supply volatility and REACH chemical compliance reformulation costs. For New Entrants and Emerging Players: Begin with automated electrochemiluminescence deployments in India's tier-two hospital laboratories, where CDSCO regulatory harmonization and PLI scheme incentives create whitespace beneath multinational incumbent coverage. Target Maharashtra and Karnataka secondary cities with cost-competitive platform economics. Pursue direct-to-consumer hormone testing channels in Canada where Health Canada's progressive laboratory access stance enables novel channel structures absent in the United States. For Investors and Strategic Acquirers: Diversified life sciences conglomerates are the most active acquirer in this space, consolidating algorithmic interpretation module developers to embed software-defined diagnostics alongside hardware placements. The five-to-ten year viability window favors vendors with dual FDA-EMA regulatory pathways and captive reagent manufacturing. Acquisition target archetypes include modular assay developers with CLIA-waived platform certifications. Watch helium supply contract renegotiations as an inflection indicator for mass spectrometry platform economics.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Module Development | Software-defined protocols create recurring revenue streams alongside instrument placements in integrated delivery networks. |
| CLIA-Waived Platform Certification | Abbott Laboratories and Roche Diagnostics defend point-of-care positions through waived complexity designations. |
| REACH Chemical Compliance Reformulation | ECHA substance restrictions force reagent consumable redesigns for CE marking continuity in Germany and France. |
| Helium Supply Contract Diversification | Gas chromatography-mass spectrometry operations hedge against Qatar and United States production concentration. |
| India Tier-Two Laboratory Deployment | Automated electrochemiluminescence platforms capture whitespace in Maharashtra and Karnataka secondary cities. |
Research Methodology
Bottom-up endocrine testing volume modeling reconciled against top-down instrument placement tracking forms the analytical core of this study. Primary interviews with reference laboratory directors, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EMA IVDR technical documentation, CMS Medicare reimbursement databases, and hospital procurement records. Triangulation across stakeholder perspectives and regulatory filings ensures analytical robustness.
Input-output matrices map test volume projections across technology platforms, hormone panel types, and end-user channels throughout the forecast period. Segmentation dimensions include test type sensitivity thresholds, CLIA complexity tiers, and regional regulatory clusters. CAGRs derive from instrument replacement cycle analysis and reagent consumable attach rate modeling. Forecast inputs incorporate subclinical hypothyroidism screening protocol expansion and mass spectrometry displacement timelines for steroid hormone quantification.
Caveats apply where FDA laboratory-developed test oversight evolution or helium supply disruption could materially shift the outlook. Forecasts reflect documented assumptions about reimbursement stability for algorithm-augmented interpretation and EMA IVDR implementation timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Asia-Pacific Viral Clearance Market
Testing Services
Global CA 125 Test Market
Testing Services
Endocrine Peptides Test Market
Testing Services
Anticoagulant Therapeutic Drug Monitoring Assay Kits Market
Testing Services
Sickle Cell Anemia Testing and Screening Market
Testing Services
Global Sterility Testing Market
Testing Services
Global Rapid Test Market
Testing Services
Cerebrospinal Fluid (CSF) Testing Market
Testing Services
Adenovirus Testing Market
Testing Services
Global Direct to Consumer Laboratory Testing Market
Testing Services
Pyrogen Testing Market
Testing Services
Global Urinalysis Test Market
Testing Services
Skin Perfusion Pressure Testing Devices Market
Testing Services
Addison Disease Testing Market
Testing Services
Adiponectin Testing Market
Testing Services
Large Molecule Bioanalytical Testing Services Market