
 US Viral Clearance Market | 2026-2036
US Viral Clearance Market Size, Share, and Industry Trends Forecast 2026-2036
US Viral Clearance Market Insights
The US viral clearance landscape is restructuring around a sharp split between premium validated services for commercial-stage biologics and commodity testing for early-phase candidates. Charles River Laboratories leverages its integrated safety assessment platform to command premium positioning in gene therapy viral clearance. Thermo Fisher Scientific anchors the high-throughput filtration segment with manufacturing scale across multiple US sites. WuXi Biologics competes aggressively on turnaround speed for international sponsors seeking US regulatory submission support.
Viral clearance encompasses the validated removal or inactivation of adventitious agents from biopharmaceutical products using chromatography, filtration, or inactivation methods, typically achieving four to six log reduction of model viruses to meet safety margins for parenteral therapeutics. The process serves as a mandatory release criterion for monoclonal antibodies, recombinant proteins, and cell-derived gene therapy vectors under FDA guidance. Chromatography and filtration technologies dominate current revenue as established platforms with extensive regulatory precedent, while UV treatment represents the fastest-expanding segment as non-denaturing alternatives gain traction for fragile viral vector products. Application demand tilts heavily toward biopharmaceutical manufacturing where margin pools are deepest, though gene therapy applications show the steepest growth trajectory as AAV and lentiviral vector programs multiply.
FDA's ICH Q5A guidance and Points to Consider documents establish the viral safety framework that shapes testing volume and method selection, while OSHA bloodborne pathogen standards influence containment infrastructure investment at contract testing facilities. The US Department of Agriculture and EPA maintain parallel oversight for certain animal-derived raw materials and waste streams, adding compliance layers to facility design. Stakeholders must monitor emerging FDA guidance on advanced therapy products and next-generation sequencing-based adventitious agent detection as these developments will reshape method qualification requirements and capital allocation priorities.
Market Dynamics
FDA's tightening guidance on advanced therapy products is compressing validation timelines while forcing biopharmaceutical sponsors to front-load viral safety investment before Phase I initiation.
Growth Catalysts
- Gene therapy pipeline expansion:AAV and lentiviral vector programs in Massachusetts and California are multiplying IND submissions, creating sustained demand for validated clearance studies ahead of clinical manufacturing.
- ICH Q5A harmonization:FDA alignment with international viral safety standards reduces redundant testing for sponsors pursuing simultaneous US-EU filings, accelerating contract study volume.
- Next-generation sequencing adoption:NGS-based adventitious agent detection is displacing traditional in vivo and in vitro methods, opening qualification pathways for novel clearance validation approaches.
Market Restraints
- Specialized facility scarcity:BSL-3 containment infrastructure concentrates in Boston-Cambridge and San Diego clusters, creating geographic access bottlenecks for sponsors outside these zones.
- Plasma-derived raw material volatility:Supply constraints on human serum albumin and recombinant growth factors inflate input costs for clearance study cell culture media.
- Retrovirus-like particle quantification limits:Current electron microscopy and PCR methods struggle to detect defective viral particles below 10^6 per mL, leaving residual uncertainty in gene therapy vector safety margins.
Strategic Opportunities
- Texas and North Carolina biomanufacturing corridors:Emerging cell therapy hubs in Houston and Research Triangle Park lack local viral clearance capacity, creating first-mover positioning for contract testing expansion.
- Continuous processing integration:Perfusion bioreactor adoption enables real-time viral clearance monitoring, allowing sponsors to embed validation within manufacturing rather than treating it as discrete release testing.
- UV-C and short-wavelength UV technologies:Non-denaturing inactivation methods for fragile viral vectors represent unclaimed white space between established filtration and chemical inactivation platforms.
Industry Challenges
- Viral clearance scientist recruitment:The specialized intersection of virology, bioprocessing, and regulatory science commands premium salaries that strain mid-sized CRO operating models.
- Legacy chromatography platform obsolescence:Protein A and ion exchange resins validated under 1990s FDA guidance require expensive requalification to meet current bracketing and robustness expectations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Viral Clearance Market |
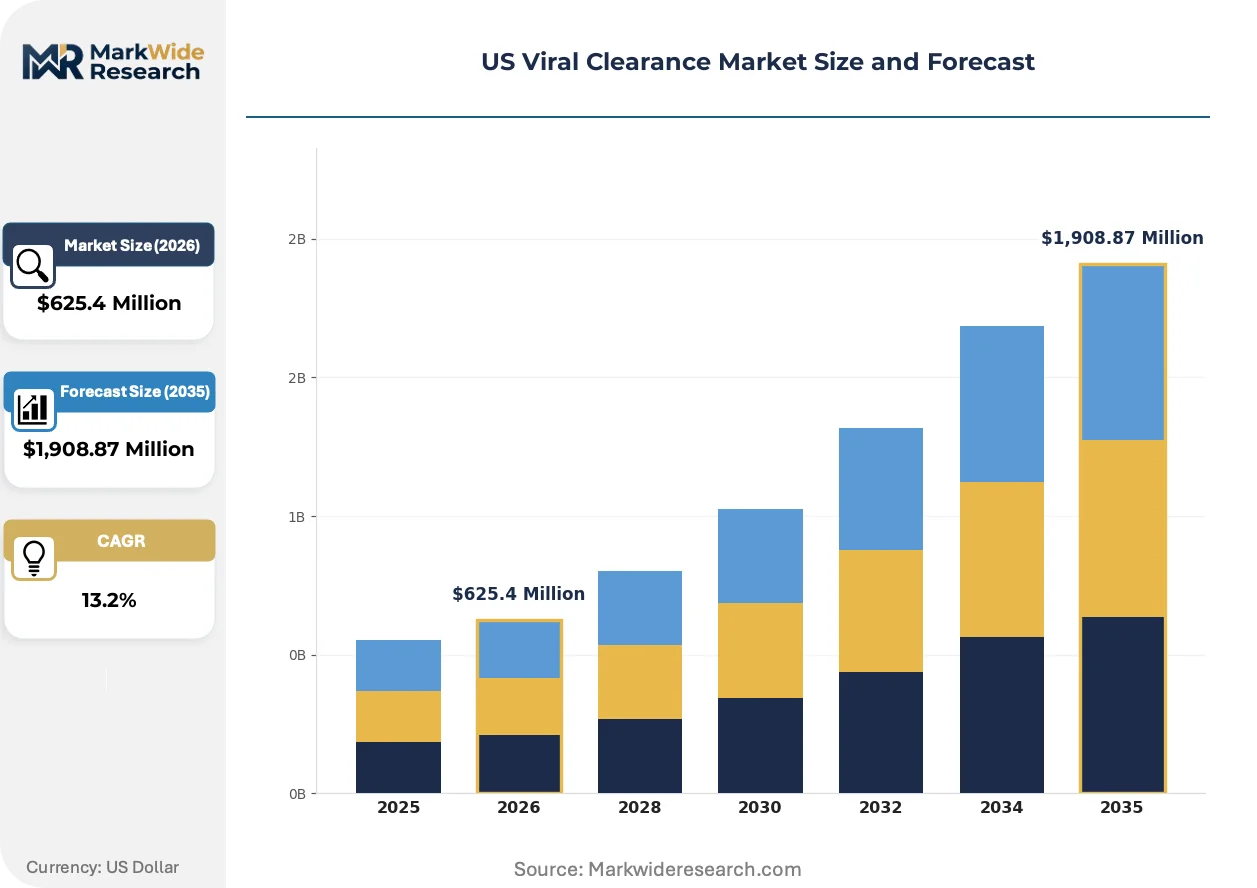
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $1,908.87 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Chromatography, Filtration, Heat Inactivation, UV Treatment, Chemical Inactivation Application: Biopharmaceutical Manufacturing, Blood Safety, Vaccine Production, Gene Therapy, Diagnostic Products End User: Contract Development Organizations, Biotech Companies, Research Institutes, Pharmaceutical Manufacturers Product Type: Membrane Filters, Viral Removal Filters, Viral Inactivation Reagents, Chromatographic Media |
| Companies Covered | Charles River Laboratories, WuXi Biologics, Merck KGaA, Sartorius AG, Thermo Fisher Scientific, Texcell, Eurofins Scientific, Syngene International, Clean Cells, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Viral Clearance Market Trends and Innovations
Single-use technologies and platform analytical methods are collapsing the traditional boundary between process development and viral validation, compressing timelines from 18 months to under 6 months for standard monoclonal antibodies.
Modular single-use filtration skids is modularizing viral clearance operations across multi-product facilities. Biopharmaceutical sponsors in California are deploying these systems to eliminate cross-contamination risks between gene therapy vectors and monoclonal antibody campaigns. The approach enables rapid changeover without fixed equipment validation, compressing facility capital deployment by 40% versus stainless steel infrastructure.
FDA's emerging guidance on advanced therapy products is mandating orthogonal viral clearance strategies for cell and gene therapies with limited or no terminal sterilization options. Sponsors must now demonstrate clearance across multiple mechanisms—typically combining nanofiltration with chemical inactivation—rather than relying on single-method validation. The requirement most acutely affects early-stage gene therapy developers in Massachusetts who previously optimized for speed over redundancy.
Consolidated vendor relationships are displacing fragmented procurement of clearance studies across multiple CROs. Large biopharmaceutical manufacturers in New Jersey and Pennsylvania are negotiating master service agreements spanning viral safety testing, cell line characterization, and release assays. The shift concentrates volume with integrated providers capable of cross-study data packages, marginalizing specialized single-service laboratories.
US Viral Clearance Market Segmentation
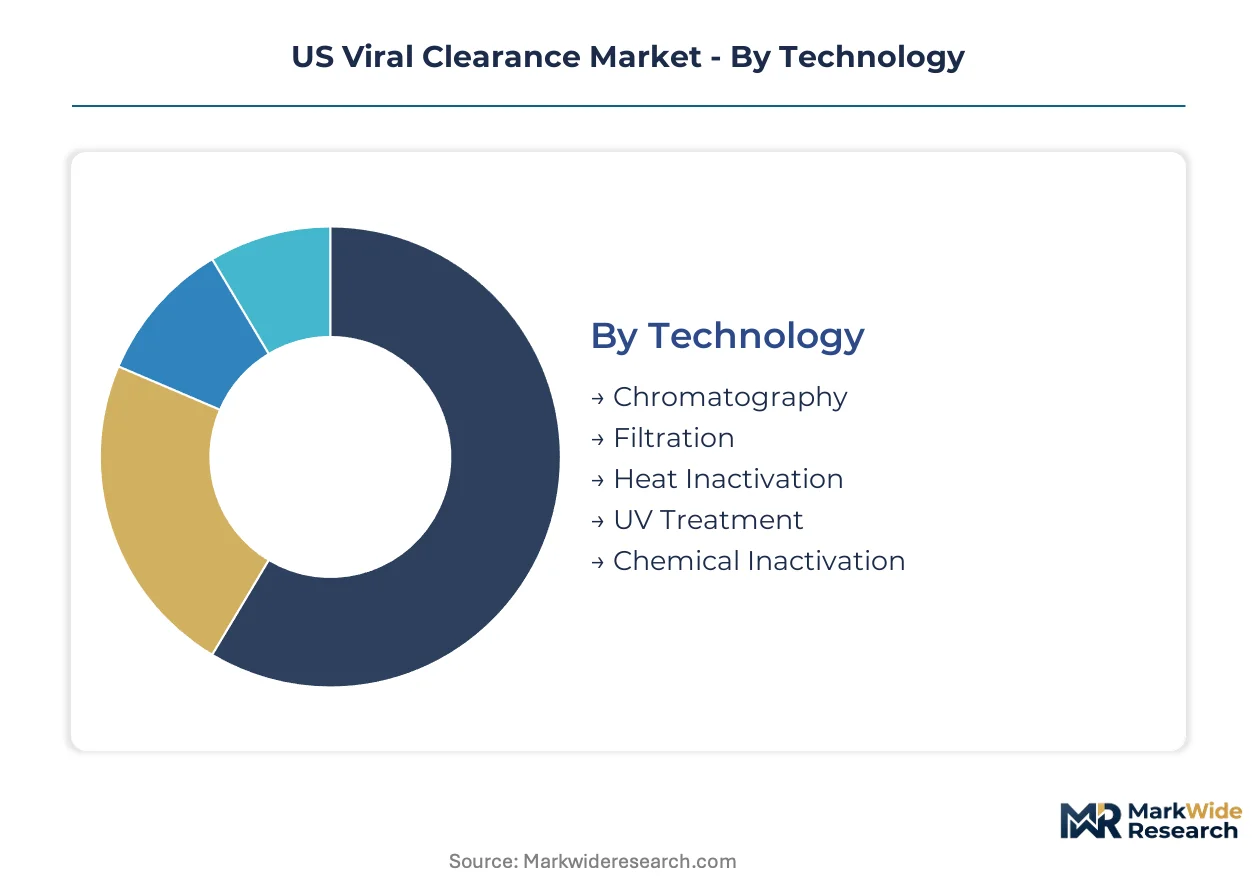
Viral clearance procurement splits sharply across technology platforms and end-user risk profiles. Sponsors match validation depth to regulatory pathway—commercial biologics demand full bracketed studies while early-phase candidates accept platform methods.
Technology:
FDA's ICH Q5A guidance mandates specific log-reduction thresholds that vary by clearance mechanism, with chromatography and filtration carrying the most extensive regulatory precedent for commercial filings.
- Chromatography:Protein A and ion exchange resins achieve selective virus partitioning through binding affinity differentials. Massachusetts gene therapy developers favor this platform for its established validation templates and FDA submission history.
- Filtration:Nanofiltration membranes physically exclude viral particles by size exclusion, typically delivering 4-6 log reduction for parvovirus surrogates. California biomanufacturing clusters drive volume for this technology given its compatibility with continuous processing architectures.
- Heat Inactivation:Thermal denaturation protocols suit plasma-derived products with robust protein stability profiles.
- UV Treatment:Short-wavelength irradiation preserves fragile viral vector infectivity while inactivating adventitious agents.
- Chemical Inactivation:Solvent-detergent and low-pH methods target enveloped viruses in antibody formulations.
Chromatography sits at the top of the volume ranking, with UV Treatment climbing the fastest.
Application:
Margin concentration follows therapeutic complexity—gene therapy commands premium pricing per study while blood safety operates on commoditized contract terms.
- Biopharmaceutical Manufacturing:Monoclonal antibody and recombinant protein campaigns generate the bulk of contract study volume, with New Jersey and Pennsylvania facilities requiring release testing for every commercial lot.
- Gene Therapy:AAV and lentiviral vector programs in Boston-Cambridge and San Diego demand orthogonal clearance strategies combining filtration with chemical or UV inactivation.
- Vaccine Production:Cell culture-based influenza and COVID-19 manufacturing requires clearance validation for adventitious agent safety.
- Blood Safety:Plasma fractionation facilities apply standardized clearance protocols with limited customization.
- Diagnostic Products:Cell-derived reagents for clinical assays need clearance documentation under FDA in vitro diagnostic regulations.
Biopharmaceutical Manufacturing captures the deepest revenue pool, though Gene Therapy shows the steepest expansion trajectory.
End User:
Procurement authority shifts based on pipeline stage—virtual biotechs outsource entirely while large pharma retains strategic capabilities in-house.
- Pharmaceutical Manufacturers:Pfizer, Merck, and Bristol Myers Squibb maintain captive viral clearance groups for core platforms while contracting specialized gene therapy studies.
- Biotech Companies:Early-stage developers in Cambridge and South San Francisco purchase discrete validation packages tied to IND-enabling milestones.
- Contract Development Organizations:CDMOs like Lonza and Catalent bundle clearance services with manufacturing campaigns to capture integrated spend.
- Research Institutes:Academic cell therapy programs at Stanford and Harvard access shared BSL-3 facilities for preclinical vector characterization.
Pharmaceutical Manufacturers dominate current procurement volume, with Biotech Companies expanding most quickly as IND submissions accelerate.
Product Type:
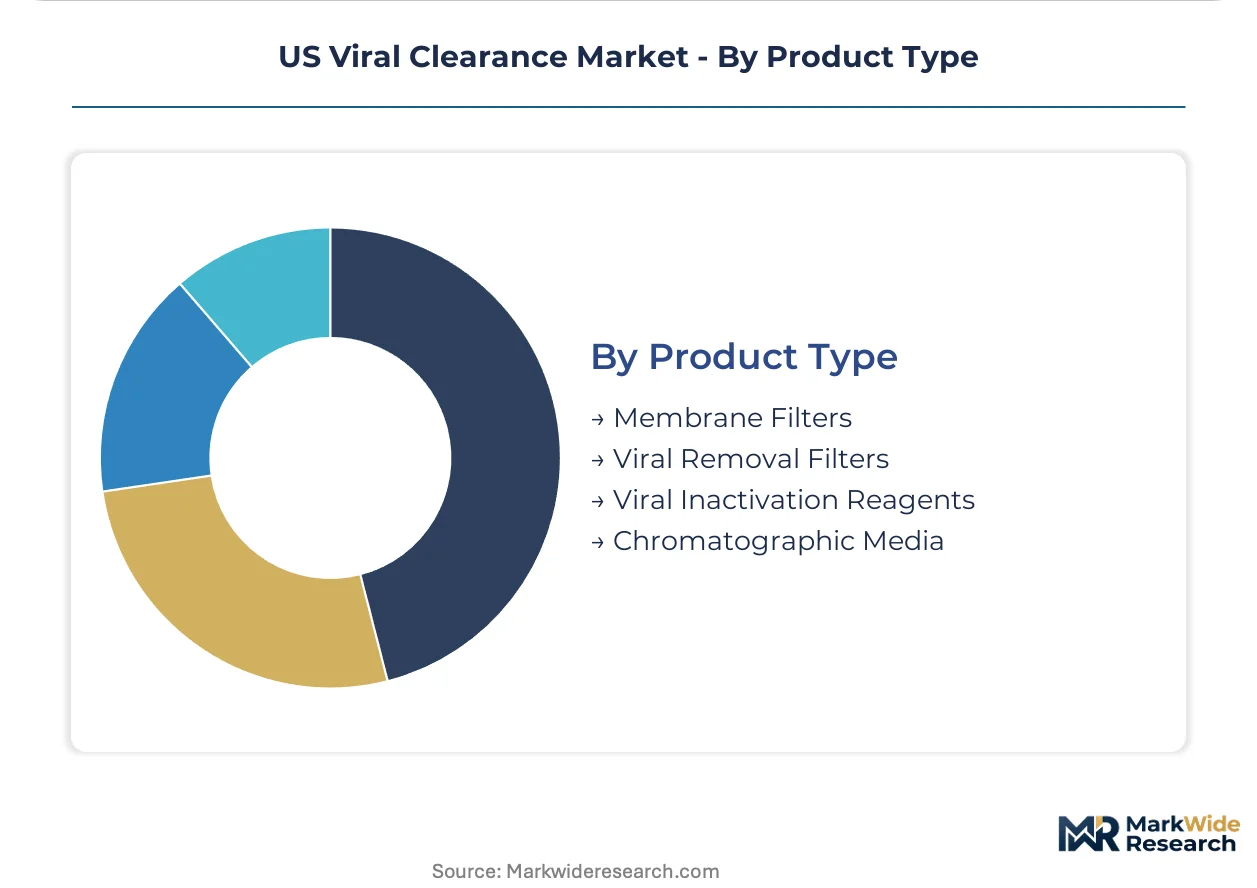
Supply concentration varies by technical complexity—membrane filters consolidate among three dominant suppliers while chromatographic media fragments across specialty resin houses.
- Membrane Filters:Polyethersulfone and regenerated cellulose membranes in 0.1-0.2 micron ratings serve as the workhorse for nanofiltration applications.
- Viral Removal Filters:Asymmetric pore structures engineered for parvovirus retention command premium pricing in gene therapy vector processing.
- Viral Inactivation Reagents:Solvent-detergent cocktails and low-pH buffers for enveloped virus inactivation in antibody manufacturing.
- Chromatographic Media:Protein A resins and mixed-mode sorbents with validated viral clearance profiles for platform processes.
Membrane Filters lead unit shipments, with Viral Removal Filters gaining share fastest on gene therapy demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized virology talent concentrates in the Boston-Cambridge corridor and San Diego, anchoring viral clearance capacity within established biopharmaceutical clusters. FDA's ICH Q5A guidance enforcement tightens validation requirements across all major manufacturing zones. Geographic expansion into emerging cell therapy hubs reshapes regional service demand.
Massachusetts
Gene therapy vector developers in Cambridge and Waltham drive orthogonal clearance study volume for AAV and lentiviral programs. FDA's Points to Consider documents for advanced therapy products mandate redundant viral safety validation before IND submission. The Route 128 corridor hosts the densest concentration of BSL-3 contract testing facilities serving commercial biologics release.
California
South San Francisco and San Diego biotech clusters generate sustained demand for nanofiltration validation compatible with continuous processing architectures. OSHA bloodborne pathogen standards enforce containment infrastructure investment at multi-product CDMO facilities. The Bay Area leads adoption of UV-C inactivation methods for fragile viral vector products.
New Jersey and Pennsylvania
Large pharmaceutical manufacturers in Rahway, Kenilworth, and Collegeville maintain captive viral clearance groups for monoclonal antibody platforms. FDA lot release testing requirements drive recurring contract volume for commercial manufacturing campaigns. The I-95 corridor between Princeton and Philadelphia anchors integrated safety assessment outsourcing.
North Carolina
Research Triangle Park cell therapy developers lack local BSL-3 viral clearance capacity, forcing sponsorship to out-of-state CROs. The state's biomanufacturing training initiatives through NC State University address virology workforce pipeline constraints. RTP's emerging gene therapy hub creates first-mover positioning for contract testing facility expansion.
Texas
Houston's Texas Medical Center cell therapy programs access limited regional viral clearance infrastructure for preclinical vector characterization. The state's medical center lacks dedicated BSL-3 containment for clearance validation studies. Houston Methodist and MD Anderson sponsors currently ship samples to Massachusetts and California facilities.
US Viral Clearance Market Competitive Landscape
Top-tier vendors anchor integrated safety assessment platforms, while mid-tier specialists compete on turnaround speed and geographic proximity. The market structure consolidates around three strategic archetypes: diversified life science conglomerates with captive viral clearance divisions, specialized contract research organizations with BSL-3 infrastructure, and equipment manufacturers bundling consumables with validation services. M&A activity concentrates on acquiring BSL-3 facility assets in underserved geographies. Strategic partnerships between CDMOs and testing laboratories bundle manufacturing campaigns with clearance validation.
Within the diversified conglomerate tier, Thermo Fisher Scientific and Merck KGaA exemplify scale-driven positioning across multiple US manufacturing sites. Charles River Laboratories occupies a position representing the specialized CRO archetype with integrated gene therapy safety assessment capabilities. These three anchors demonstrate how vendor selection criteria split between platform breadth and therapeutic-area depth.
| Leading Market Players |
|---|
| Charles River Laboratories |
| WuXi Biologics |
| Merck KGaA |
| Sartorius AG |
| Thermo Fisher Scientific |
| Texcell |
| Eurofins Scientific |
| Syngene International |
| Clean Cells |
| Others |
Pricing and Supply Chain Analysis
FDA's ICH Q5A guidance tightening and sponsor demands for orthogonal clearance validation are forcing contract testing providers to layer redundant capabilities into service bundles, compressing standalone study margins while inflating integrated package pricing. Supply concentration in BSL-3 containment infrastructure creates geographic pricing premiums for sponsors outside Boston-Cambridge and San Diego clusters.
Pricing Analysis
Bundled service packages versus discrete validation studies split pricing structures across the US viral clearance market. Integrated safety assessment contracts spanning viral clearance, cell line characterization, and release assays command premium positioning against single-study procurement. Price differentiation rests on BSL-3 certification tier and turnaround speed guarantees, with gene therapy sponsors showing lowest price sensitivity due to regulatory timeline pressures. Cost compression in early-phase platform methods intensifies as CROs compete for IND-enabling volume, while commercial-stage bracketed studies maintain pricing resilience.
Supply Chain Analysis
Reverse-logistics flows for used filtration membranes and chromatography resins remain underdeveloped, creating single-use consumables dependency without refurbishment economies. Supply concentrates in Germany, Japan, and the USA for nanofiltration membranes and protein A resins. Raw material inputs draw from specialized polymer suppliers and recombinant protein feedstock providers. Single-source vulnerability runs through viral surrogate strain repositories maintained by ATCC and European collection centers. Distribution runs through direct OEM channels to CDMO facilities and contract testing laboratories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US viral clearance market functions as a stable compounder anchored by FDA's non-negotiable safety testing mandates for biologics commercialization. Gene therapy pipeline expansion sustains demand visibility regardless of broader biotech funding cycles.
For Market Incumbents: Deploy capacity addition in Texas and North Carolina to capture emerging cell therapy hub demand before regional BSL-3 infrastructure matures. Consolidate position by acquiring specialized gene therapy safety assessment capabilities to defend against Thermo Fisher Scientific's manufacturing-scale bundling. FDA's emerging advanced therapy product guidance threatens legacy platform obsolescence—accelerate requalification investment for 1990s-era chromatography validations. For New Entrants and Emerging Players: Launch via UV-C and short-wavelength UV technology specialization to exploit white space between established filtration and chemical inactivation platforms. Target Houston's Texas Medical Center and Research Triangle Park cell therapy developers lacking local viral clearance capacity. Penetrate through rapid-turnaround service models for international sponsors seeking US regulatory submission support, matching WuXi Biologics' speed positioning without competing on scale. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-sized CROs holding BSL-3 assets in underserved geographies—Texas and North Carolina facilities command scarcity premiums as gene therapy manufacturing migrates southward. Long-term viability frames around 5-10 year FDA guidance continuity rather than technology disruption risk. Watch for NGS-based adventitious agent detection qualification as inflection signal reshaping method validation requirements and capital allocation priorities.| Strategic Initiative | Industry Significance |
|---|---|
| BSL-3 Facility Expansion | Captures gene therapy demand in Texas and North Carolina corridor where local containment infrastructure is absent. |
| NGS Platform Qualification | Positions providers ahead of FDA's emerging guidance on sequencing-based adventitious agent detection methods. |
| Continuous Processing Integration | Enables real-time viral clearance monitoring for perfusion bioreactor architectures advancing in California clusters. |
| Orthogonal Method Bundling | Meets FDA's redundant clearance mandate for cell and gene therapies with limited terminal sterilization options. |
| Master Service Agreement Negotiation | Concentrates volume with integrated providers capable of cross-study data packages for New Jersey and Pennsylvania pharma. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs leads at contract testing organizations, viral clearance scientists at CDMOs, and procurement managers at gene therapy developers with secondary validation from FDA guidance documents, ICH Q5A harmonization records, and OSHA bloodborne pathogen enforcement data. Bottom-up triangulation across technology platform adoption rates and top-down validation against biopharmaceutical manufacturing capacity expansion ensured cross-verified outputs.
Segment-weighting approaches distributed analytical emphasis across chromatography, filtration, and UV treatment technologies while modeling gene therapy, monoclonal antibody, and vaccine application demand separately. CAGRs derived from bracketed study volume trends, IND submission trajectories in Massachusetts and California, and contract testing capacity utilization rates across the projection horizon. Forecast inputs incorporated BSL-3 facility buildout pipelines and FDA advanced therapy product guidance evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory timeline acceleration or gene therapy clinical failure waves. Forecasts reflect documented assumptions on ICH Q5A enforcement continuity and BSL-3 workforce availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Europe Newborn Screening Market
Testing Services
In-Vitro Toxicology Testing Market
Testing Services
Legionnaire Disease Testing Market
Testing Services
Vaginal Panel Testing Market
Testing Services
Global Diagnostic Testing Market
Testing Services
Global Mycoplasma Testing Market
Testing Services
United States Testing, Inspection, and Certification (TIC) Market
Testing Services
Aerospace and Life Science Testing Certification Market
Testing Services
Global Endocrine Testing Market
Testing Services
Global Mosquito Borne Infections Testing Market
Testing Services
Urine Testing Cups Market
Testing Services
Solid Tumor Testing Market
Testing Services
Global Specimen Validity Testing Market
Testing Services
Home Care Testing Market
Testing Services
Monkeypox Testing Market
Testing Services
Infusion Toxicology Services Market