
 Medical Device Testing, Inspection, and Certification Market | 2026-2036
Medical Device Testing, Inspection, and Certification Market Size, Share, and Industry Trends Forecast 2026-2036
Medical Device Testing, Inspection, and Certification Market Insights
German notified body capacity is repositioning toward higher-risk device classes under the EU MDR transition. SGS SA leverages its expanded biocompatibility testing footprint across Central Europe to anchor large implant manufacturers. Bureau Veritas competes through specialized EMC and electrical safety laboratories serving diagnostic equipment makers in the Netherlands and Belgium. TÜV SÜD differentiates with integrated quality auditing and certification workflows that reduce manufacturer time-to-market for Class III devices.
Medical device testing, inspection, and certification encompasses the technical verification of safety, performance, and regulatory conformity for instruments, apparatus, and software intended for human medical use, employing biocompatibility assays per ISO 10993, electrical safety protocols per IEC 60601, and electromagnetic compatibility screening to prevent interference in clinical environments. Testing services dominate revenue as manufacturers face expanded premarket submission requirements under stricter notified body oversight. Certification for implantable devices commands premium pricing due to prolonged clinical evaluation periods and higher liability exposure. Quality auditing is gaining share as firms seek proactive compliance management rather than reactive remediation before regulatory inspections.
The FDA enforces 21 CFR Part 820 quality system requirements while the EU MDR mandates notified body involvement for most device classes above Class I, creating dual-track compliance burdens for multinational manufacturers. BSI Group and DEKRA navigate this complexity by maintaining parallel accreditation under both frameworks, allowing single-source testing for US and European market access. Stakeholders must monitor evolving harmonization gaps between FDA and EU MDR clinical evidence standards when selecting testing partners and geographic certification strategies.
Market Dynamics
The FDA's updated Quality System Regulation and the EU Medical Device Regulation are compressing manufacturer timelines while concentrating demand around specialized testing clusters in Germany, the Netherlands, and Belgium.
Growth Catalysts
- EU MDR notified body mandates:The expanded scope of Class IIa through Class III device reviews under the Medical Device Regulation is pulling manufacturers toward third-party testing partnerships rather than in-house compliance teams.
- Orthopedic implant clusters:Concentrated device production around Tübingen and Freiburg is generating localized demand for biocompatibility and mechanical testing services.
- Software-as-a-medical-device:The FDA's evolving guidance on SaMD classification is creating new verification requirements for algorithm-based diagnostic tools.
Market Restraints
- Notified body capacity bottlenecks:European accreditation backlogs for higher-risk device classes are extending certification timelines by 12-18 months for manufacturers without established laboratory relationships.
- Specialized talent scarcity:The shallow pool of auditors qualified under both FDA 21 CFR Part 820 and EU MDR frameworks limits laboratory scaling capacity in Central Europe.
- Capital intensity of EMC infrastructure:Shielded chamber investments for IEC 60601 electrical safety testing require multi-million-euro commitments that deter market entry.
Strategic Opportunities
- Software validation services:The FDA's draft guidance on artificial intelligence-enabled devices opens white space for algorithm verification and continuous monitoring protocols.
- Integrated quality auditing:Bundled testing-certification-audit workflows that compress Class III device time-to-market represent underdeveloped service architecture.
- Swiss and UK market access:Post-Brexit UKCA marking requirements and Swissmedic's independent regulatory pathway create demand for parallel certification capabilities.
Industry Challenges
- Biocompatibility assay standardization:ISO 10993-1 implementation inconsistencies across notified bodies generate retesting requirements and documentation friction.
- Legacy quality system migration:Manufacturers with entrenched FDA 21 CFR Part 820 processes face workflow redesign costs to accommodate EU MDR technical documentation structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Medical Device Testing, Inspection, and Certification Market |
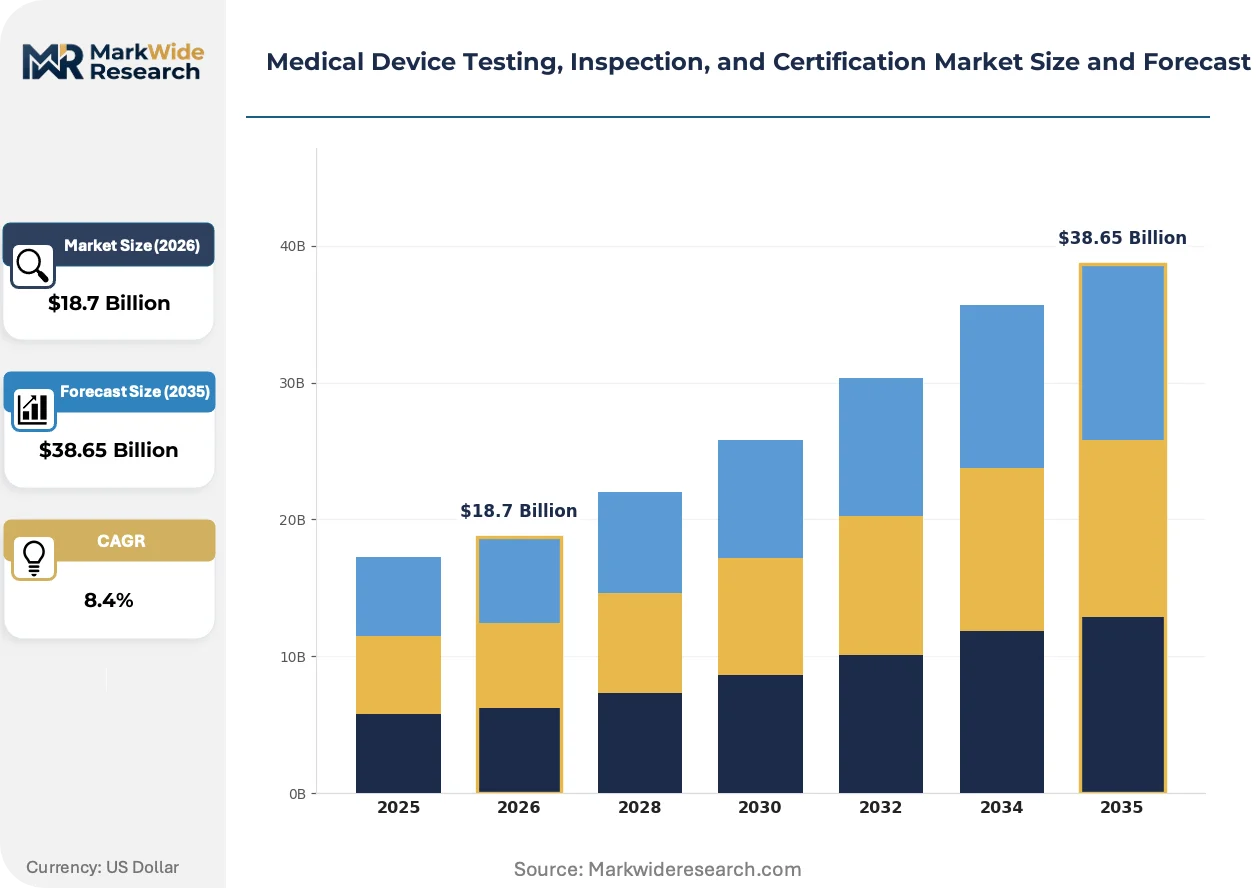
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Testing, Inspection, Certification, Quality Auditing Technology: Biocompatibility, Electrical Safety, EMC, Performance Testing End User: Manufacturers, Laboratories, Regulatory Bodies, R&D Institutions Product Type: Implants, Diagnostic Equipment, Surgical Instruments, Consumables |
| Companies Covered | SGS SA, Intertek Group plc, TÜV SÜD, Bureau Veritas, Eurofins Scientific, TÜV Rheinland, UL Solutions, BSI Group, DEKRA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Medical Device Testing, Inspection, and Certification Market Trends and Innovations
Digitalization of testing protocols and regulatory harmonization pressures are restructuring how laboratories deliver verification services and how manufacturers select geographic certification strategies.
Automated biocompatibility screening platforms are consolidating multiple ISO 10993 assay workflows into single-instrument suites. Large implant manufacturers in Germany are adopting these systems at pilot scale. The technology is consolidating previously fragmented testing steps into continuous processing pipelines that compress preclinical evaluation timelines.
The EU Medical Device Regulation's Unique Device Identification requirements are mandating enhanced traceability infrastructure. Manufacturers must now embed testing documentation into device lifecycle records accessible to notified bodies. Class III cardiovascular device producers in the Netherlands and Belgium are responding by integrating quality management systems directly with laboratory data platforms.
Hospital procurement departments are unbundling compliance verification from device acquisition contracts. Third-party testing laboratory selection is migrating from manufacturer discretion to purchaser specification in Dutch and Belgian diagnostic equipment supply agreements. This shift is most visible in radiology and patient monitoring device categories where electrical safety certification carries liability weight.
Medical Device Testing, Inspection, and Certification Market Segmentation
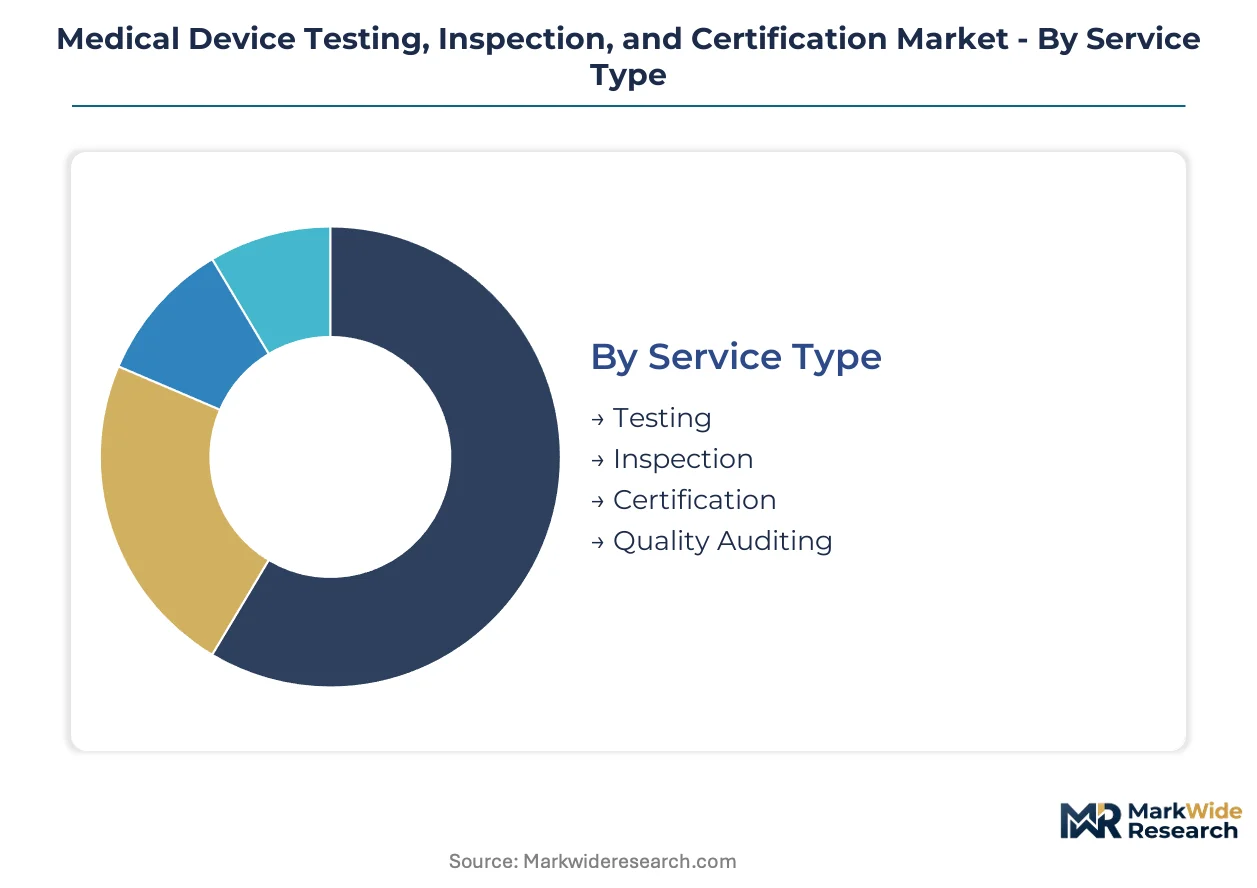
Service differentiation in medical device compliance hinges on whether manufacturers seek discrete technical verification or integrated regulatory pathways. Segmentation reveals where laboratory investments concentrate and which verification protocols command premium positioning.
Service Type:
Customization intensity varies from commoditized batch testing to bespoke certification orchestration across notified body relationships.
- Testing:Technical verification of biocompatibility, electrical safety, and electromagnetic compatibility against ISO 10993 and IEC 60601 protocols. German orthopedic manufacturers around Tübingen drive demand for mechanical load and fatigue testing of implantable joints.
- Inspection:Physical examination of device conformity against design dossiers and technical documentation. Dutch hospital procurement departments now mandate third-party inspection certificates before contract execution for diagnostic equipment.
- Certification:Formal attestation of regulatory compliance enabling market access. EU MDR notified body mandates for Class IIa through III devices compress timelines and elevate certification to strategic partnership status.
- Quality Auditing:Proactive assessment of manufacturer quality systems against FDA 21 CFR Part 820 and EU MDR requirements. Belgium-based diagnostic equipment producers adopt recurring audits to preempt regulatory inspection findings.
Most installed capacity flows through Testing. Expansion is steepest in Quality Auditing.
Technology:
Capital requirements and technical specialization create tiered entry barriers across verification domains.
- Biocompatibility:Cytotoxicity, sensitization, and irritation assays per ISO 10993-1 for implantable device safety. Freiburg cardiovascular device clusters generate concentrated demand for hemocompatibility and systemic toxicity evaluation.
- Electrical Safety:Verification of protection against electric shock, mechanical hazards, and fire risks per IEC 60601-1. Patient monitoring equipment manufacturers in the Netherlands require specialized defibrillation protection testing.
- EMC:Electromagnetic compatibility screening to prevent interference in clinical environments. Shielded chamber infrastructure investments limit laboratory scaling in Central Europe.
- Performance Testing:Functional verification of device output against labeled specifications. Software-as-a-medical-device producers seek algorithm validation under FDA draft guidance.
Biocompatibility anchors revenue concentration. EMC infrastructure scarcity creates the steepest pricing gradient.
End User:
Procurement sophistication separates volume purchasers from specialized compliance orchestrators.
- Manufacturers:Device producers outsourcing verification to compress internal compliance team overhead. Large implant manufacturers leverage multi-service laboratory partnerships for Class III device submissions.
- Laboratories:Contract research organizations seeking accredited subcontracting for specialized assay capabilities. Biocompatibility testing networks in Germany absorb overflow from capacity-constrained notified bodies.
- Regulatory Bodies:Notified bodies and competent authorities requiring independent verification for conformity assessment. EU MDR designation pressures concentrate demand on laboratories with parallel FDA accreditation.
- R&D Institutions:Academic and clinical research centers validating prototype safety before regulatory pathway selection. Early-stage orthopedic device development in Tübingen university hospitals drives preclinical testing demand.
Manufacturers command the deepest laboratory relationships. R&D Institutions are expanding most quickly as university spin-offs proliferate.
Product Type:
Regulatory risk stratification and clinical exposure differentiate service pricing across device categories.
- Implants:Long-duration exposure devices requiring extensive biocompatibility and mechanical testing. Cardiovascular and orthopedic implants in Germany command the longest certification timelines and highest liability-adjusted pricing.
- Diagnostic Equipment:Imaging and patient monitoring devices with intensive electrical safety and EMC requirements. Dutch radiology procurement contracts now specify third-party EMC certification as a condition of purchase.
- Surgical Instruments:Reusable and single-use devices with sterilization validation and material compliance needs. Belgian surgical device producers prioritize ISO 10993-5 cytotoxicity screening for instrument surface coatings.
- Consumables:Single-use disposables with batch-release testing and packaging validation protocols. Freiburg-area manufacturers of wound care consumables drive demand for sterility assurance and shelf-life testing.
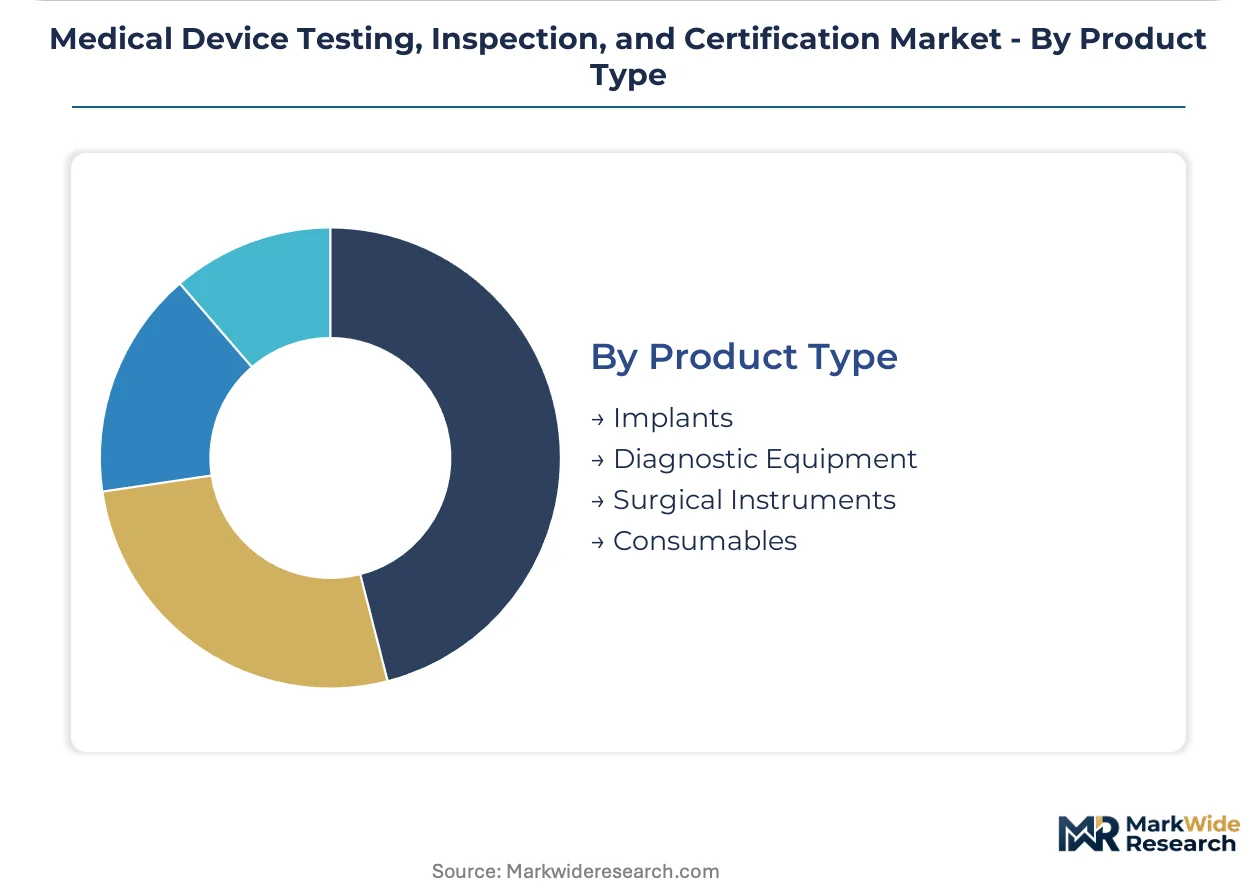
Implants concentrate the highest-value certification workflows. Diagnostic Equipment is gaining share fastest as software-enabled devices proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping device manufacturing footprints as manufacturers relocate production to jurisdictions with streamlined notified body access and lower compliance verification costs. The EU MDR transition has compressed certification timelines unevenly across member states, creating geographic pockets where testing laboratory proximity confers measurable time-to-market advantages.
Germany
The Tübingen-Freiburg medical technology corridor concentrates Europe's highest density of orthopedic and cardiovascular device producers. BfArM's implementation of EU MDR technical documentation requirements has accelerated notified body partnerships among Mittelstand manufacturers. Freiburg-area contract testing laboratories now absorb overflow biocompatibility demand from capacity-constrained Stuttgart facilities.
United States
FDA 21 CFR Part 820 quality system enforcement drives outsourcing among mid-tier device manufacturers seeking to compress internal compliance overhead. The agency's evolving Software-as-a-Medical-Device guidance is generating specialized verification demand in Boston and Minneapolis medical device clusters. Third-party testing partnerships are migrating from discretionary cost centers to strategic procurement specifications.
Netherlands
Dutch hospital procurement departments now mandate third-party EMC and electrical safety certification before diagnostic equipment contract execution. The Health and Youth Care Inspectorate's alignment with EU MDR notified body mandates has concentrated testing demand around Eindhoven's high-tech systems corridor. Philips' supply base is driving tier-one laboratory accreditation requirements downstream.
Switzerland
Swissmedic's independent regulatory pathway outside EU MDR formal structures creates parallel certification demand for manufacturers seeking Alpine market access. Basel's pharmaceutical-device convergence zone generates specialized combination product testing requirements. Zurich-area laboratories are positioning for UKCA-equivalent recognition post-Brexit.
Belgium
The FAMHP's stringent implementation of EU MDR clinical evaluation requirements has elevated quality auditing to recurring contractual obligations among diagnostic equipment producers. Leuven's health technology cluster is integrating laboratory data platforms directly into manufacturer quality management systems. Brussels-based notified bodies are repositioning toward higher-risk device class specialization.
Medical Device Testing, Inspection, and Certification Market Competitive Landscape
Swiss and German testing conglomerates anchor the premium certification tier; UK and French specialists hold differentiated positions in quality auditing and software validation. Market structure exhibits moderate consolidation around pan-European laboratory networks with parallel FDA-EU accreditation. Three archetypes dominate: integrated multi-service platforms, specialized biocompatibility or EMC boutiques, and quality auditing pure-plays. Capacity expansion through automated assay platforms and strategic partnerships with orthopedic implant clusters represent the dominant competitive vectors.
Among integrated multi-service platforms, SGS SA exemplifies the pan-European archetype through its Central European biocompatibility footprint, while TÜV SÜD occupies a position emphasizing integrated quality auditing workflows. Bureau Veritas represents the specialized testing vector with its Benelux-focused EMC and electrical safety capabilities. These three anchors illustrate how geographic certification strategies and service bundling architecture differentiate positioning under tightening EU MDR and FDA quality system enforcement.
| Leading Market Players |
|---|
| SGS SA |
| Intertek Group plc |
| TÜV SÜD |
| Bureau Veritas |
| Eurofins Scientific |
| TÜV Rheinland |
| UL Solutions |
| BSI Group |
| DEKRA |
| Others |
Pricing and Supply Chain Analysis
Outsourced laboratory partnerships anchor both supply positioning and pricing power for device manufacturers navigating EU MDR and FDA dual-track compliance. German orthopedic clusters around Tübingen concentrate demand for biocompatibility verification, while Dutch hospital procurement mandates for third-party EMC certification compress channel margins for diagnostic equipment suppliers.
Pricing Analysis
Distributor markups on Class III implant certification services widen as notified body capacity bottlenecks extend lead times. Project-based pricing dominates high-risk device submissions, with premium tiers commanded by laboratories holding parallel FDA-EU accreditation. Cost compression runs through standard biocompatibility batch testing as automated ISO 10993 platforms displace manual assay workflows. Small implant manufacturers exhibit highest price sensitivity, while multinational device producers prioritize time-to-market over per-test economics.
Supply Chain Analysis
Refurbishment flows for EMC shielded chambers create secondary equipment markets that lower capital barriers for laboratory entrants. Supply concentrates in Germany, the Netherlands, and Belgium where notified body proximity accelerates certification turnaround. Testing infrastructure draws from specialized chamber manufacturing in Switzerland, reagent supply chains in France, and software validation platforms in the United States. Single-source vulnerability sits with shielded chamber fabricators serving Central Europe. Distribution runs through direct manufacturer-laboratory contracts rather than intermediary channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
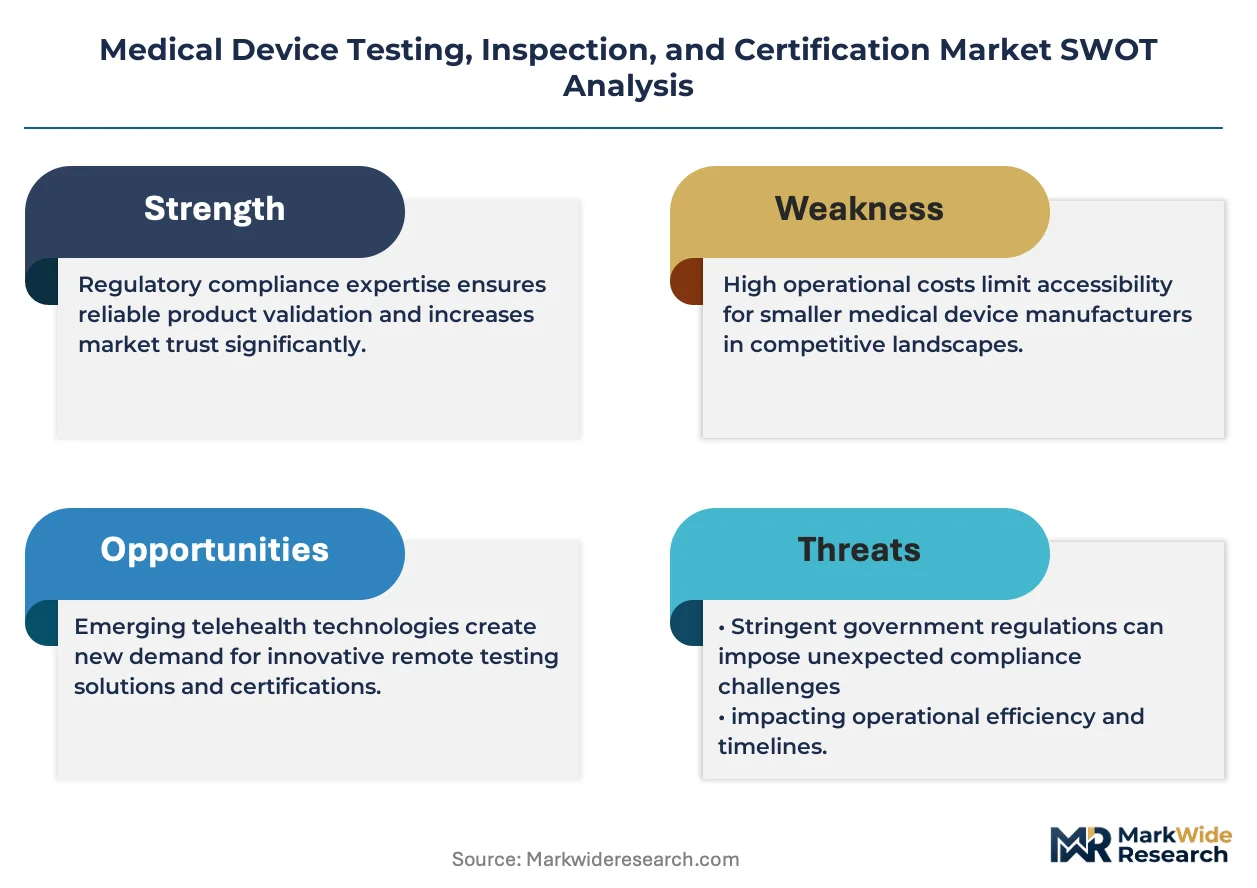
Margin expansion opportunities concentrate in software-as-a-medical-device validation and integrated quality auditing bundles. Automated biocompatibility platforms and AI-enabled diagnostic tool verification represent premium-tier shifts that offset commoditization pressure in standard electrical safety testing.
For Market Incumbents: Anticipate notified body capacity constraints by securing long-term capacity reservations with German and Benelux laboratories ahead of EU MDR transition deadlines. Defensive consolidation moves include acquiring specialized EMC boutiques in the Netherlands and integrating quality auditing workflows to compress Class III device time-to-market. Vertical integration into automated ISO 10993 assay platforms anchors cost position against emerging laboratory entrants. For New Entrants and Emerging Players: Launch via software validation services targeting Boston and Minneapolis medical device clusters where FDA SaMD guidance creates white-space demand. Algorithm verification for AI-enabled diagnostic tools represents the most penetrable segment, with hospital procurement specification of third-party testing creating entry pathways. Go-to-market positioning should emphasize rapid turnaround on IEC 60601 electrical safety for patient monitoring equipment. For Investors and Strategic Acquirers: Roll-up economics work for specialized biocompatibility boutiques because EU MDR notified body mandates concentrate demand on accredited laboratories with limited organic scaling capacity. Five-to-ten year viability hinges on software validation capability integration and Swiss-UK parallel certification positioning. Acquisition target archetype: mid-cap laboratories with dormant FDA accreditation and underutilized EMC infrastructure. Monitor notified body designation backlogs for Class IIa through III devices as inflection indicator for pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Notified Body Partnership | Secures capacity reservations for Class III cardiovascular implant submissions in Germany. |
| Software-as-a-Medical-Device Validation Platform | Captures FDA draft guidance demand for algorithm verification in diagnostic tools. |
| Automated Biocompatibility Assay Investment | Compresses ISO 10993 timelines for Freiburg orthopedic implant manufacturers. |
| Swiss-UK Parallel Certification Capability | Addresses post-Brexit UKCA and Swissmedic independent pathway requirements. |
| Integrated Quality Auditing Bundle | Reduces manufacturer time-to-market through bundled testing-certification workflows. |
Research Methodology
Bottom-up device manufacturer modeling reconciled against top-down laboratory capacity tracking forms the analytical core. Primary interviews with notified body auditors, hospital procurement managers, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract registries, and laboratory accreditation records. Triangulation between demand-side outsourcing patterns and supply-side capacity expansion announcements ensures consistency.
Input-output matrices map testing service demand by device class against laboratory throughput by geography and capability. Segmentation dimensions modeled include service type, technology protocol, end-user archetype, and product risk class across the projection horizon. CAGRs derive from regression analysis of historical outsourcing rates against regulatory enforcement intensity. Industry-specific forecast inputs incorporate EU MDR transition timeline assumptions and FDA SaMD guidance evolution.
Forecast precision tightens around the base case; tail outcomes carry wider variance under notified body accreditation delays or harmonization gaps between FDA and EU MDR clinical evidence standards. Forecasts reflect documented assumptions regarding regulatory enforcement continuity and laboratory scaling capacity. Practitioners should monitor Class III device submission backlogs and automated assay platform adoption rates for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Testing and Analysis Services Market
Testing Services
At-Home Celiac Testing Market
Testing Services
Friability Tester Market
Testing Services
Europe Newborn Screening Market
Testing Services
Helicobacter Pylori Testing Market
Testing Services
Adenovirus Testing Market
Testing Services
Urine Sediment Testing Market
Testing Services
Healthcare Testing, Inspection, and Certification Outsourcing Market
Testing Services
Drug Tester Market
Testing Services
Irradiation Sterilization Services Market
Testing Services
North America Antimicrobial Susceptibility Testing Market
Testing Services
Global Efficacy Testing Market
Testing Services
Global Creatinine Assay Kits Market
Testing Services
Self-Urinary Infection Testing Market
Testing Services
Global Nitric Oxide Test Market
Testing Services
Global Bioburden Testing Market