
 Healthcare Testing, Inspection, and Certification Outsourcing Market | 2026-2036
Healthcare Testing, Inspection, and Certification Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Healthcare Testing, Inspection, and Certification Outsourcing Market Intelligence
EU Medical Device Regulation is broadening the cost-of-entry calculus for healthcare certification outsourcing across European markets. SGS SA leverages its pan-European laboratory network to sustain competitive positioning in notified body services. Eurofins Scientific SE anchors its growth through specialized biologics testing capabilities. TÜV SÜD differentiates via deep integration with German medical device manufacturing clusters.
Healthcare Testing, Inspection, and Certification Outsourcing encompasses the delegation of quality verification, regulatory compliance validation, and product conformity assessment to independent third-party organizations operating under ISO 17025-accredited laboratory frameworks and notified body designations. These services functionally substitute captive in-house quality departments for pharmaceutical and medical device manufacturers seeking to manage fixed-cost exposure against volatile regulatory workloads. Quality Assurance services command the largest revenue share within service type segmentation due to recurring batch-release obligations. Compliance Testing represents the fastest-expanding category as FDA's Quality Management System Regulation and EU MDR impose novel documentation burdens. Medical Devices dominates end-user demand, though Biologics is reshaping growth trajectories through cell-and-gene therapy complexity.
FDA, EMA, and ISO collectively govern market access through divergent but converging standards frameworks that elevate third-party certification from optional efficiency tool to operational necessity. FDA's updated Quality Management System Regulation explicitly references risk management alignment with ISO 14971, while EMA's intensified pharmacovigilance inspections drive outsourcing of periodic safety update report preparation. Stakeholders must monitor regulatory harmonization negotiations between FDA and EU competent authorities, as mutual recognition agreements would compress duplicative testing requirements and redistribute geographic demand for certification services.
Market Dynamics
Pharmaceutical and medical device manufacturers are dismantling captive quality departments in favor of variable-cost outsourcing models as FDA's Quality Management System Regulation and EU MDR impose simultaneous compliance escalations. This structural shift toward third-party validation partners is compressing fixed-cost exposure against volatile regulatory workloads.
Growth Catalysts
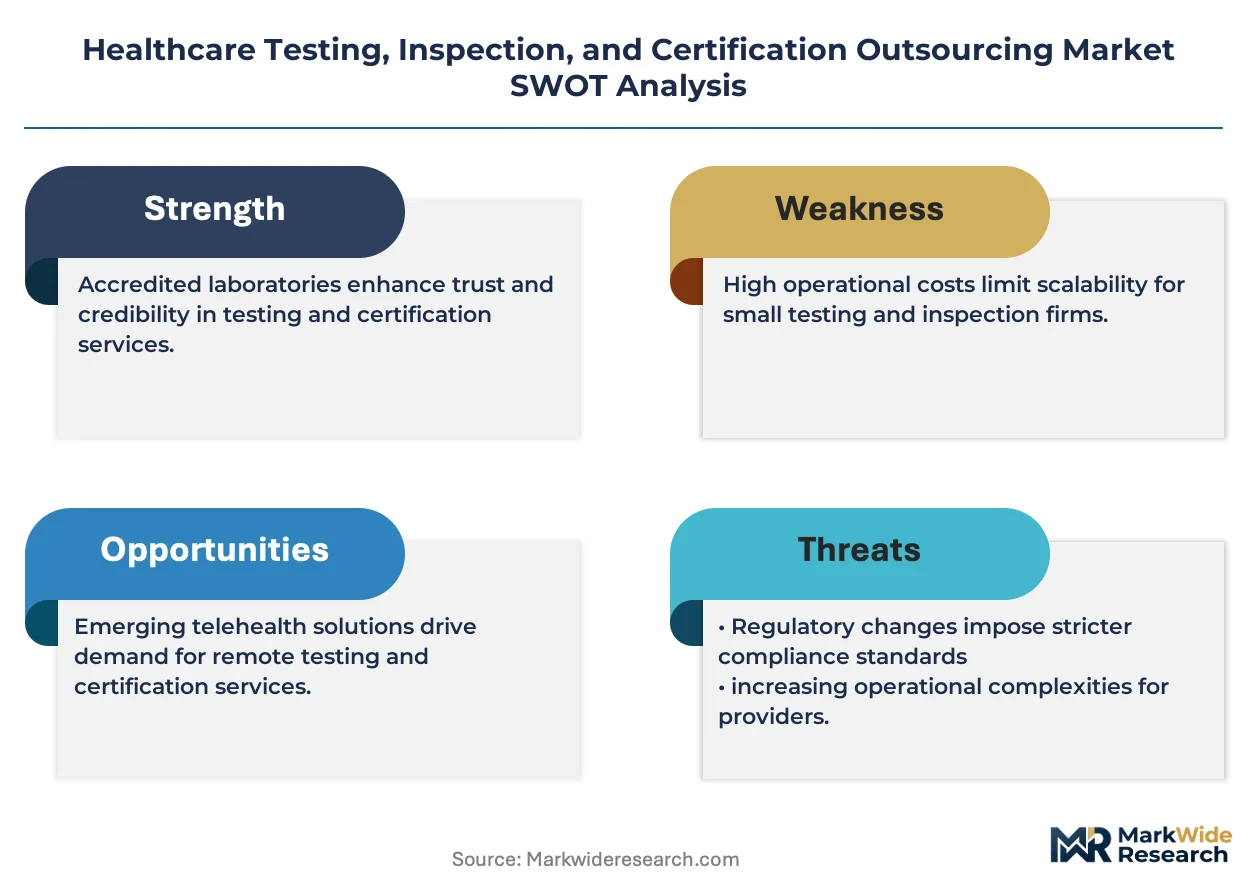
- FDA Quality Management System Regulation:The updated QSR mandates explicit ISO 14971 risk management alignment, forcing device manufacturers to seek external expertise for documentation and validation protocols.
- Cell-and-gene therapy complexity:Biologics developers face novel analytical challenges for autologous therapies that exceed in-house laboratory capabilities, accelerating demand for specialized CRO partnerships.
- Notified body capacity constraints:EU MDR's expanded scope has created bottlenecks in CE marking availability, driving manufacturers toward pan-European laboratory networks with multiple designations.
Market Restraints
- Specialized labor scarcity:ISO 17025-accredited analytical chemists and regulatory affairs specialists command premium compensation, inflating service provider cost structures.
- Single-source equipment dependencies:Chromatography and mass spectrometry platforms from dominant suppliers create procurement vulnerability for testing laboratories.
- REACH chemical registration burdens:European analytical service providers face escalating compliance costs for reagent inventory management and substance tracking.
Strategic Opportunities
- Indian pharmaceutical manufacturing expansion:CDSCO's alignment with ICH guidelines is opening inspection and certification demand from USFDA-registered export facilities in Hyderabad and Ahmedabad clusters.
- Real-time release testing adoption:Process analytical technology integration enables continuous manufacturing validation, creating service white space for PAT implementation specialists.
- EMA-FDA mutual recognition negotiations:Procedural harmonization would eliminate duplicative stability studies and bioanalytical testing, redistributing geographic demand toward consolidated validation hubs.
Industry Challenges
- Data integrity remediation:FDA warning letters citing ALCOA+ violations in laboratory information management systems demand costly system overhauls and retrospective data reconstruction.
- Legacy equipment validation:Computerized system validation for 21 CFR Part 11 compliance requires extensive documentation of aging chromatography data stations and standalone workstations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Healthcare Testing, Inspection, and Certification Outsourcing Market |
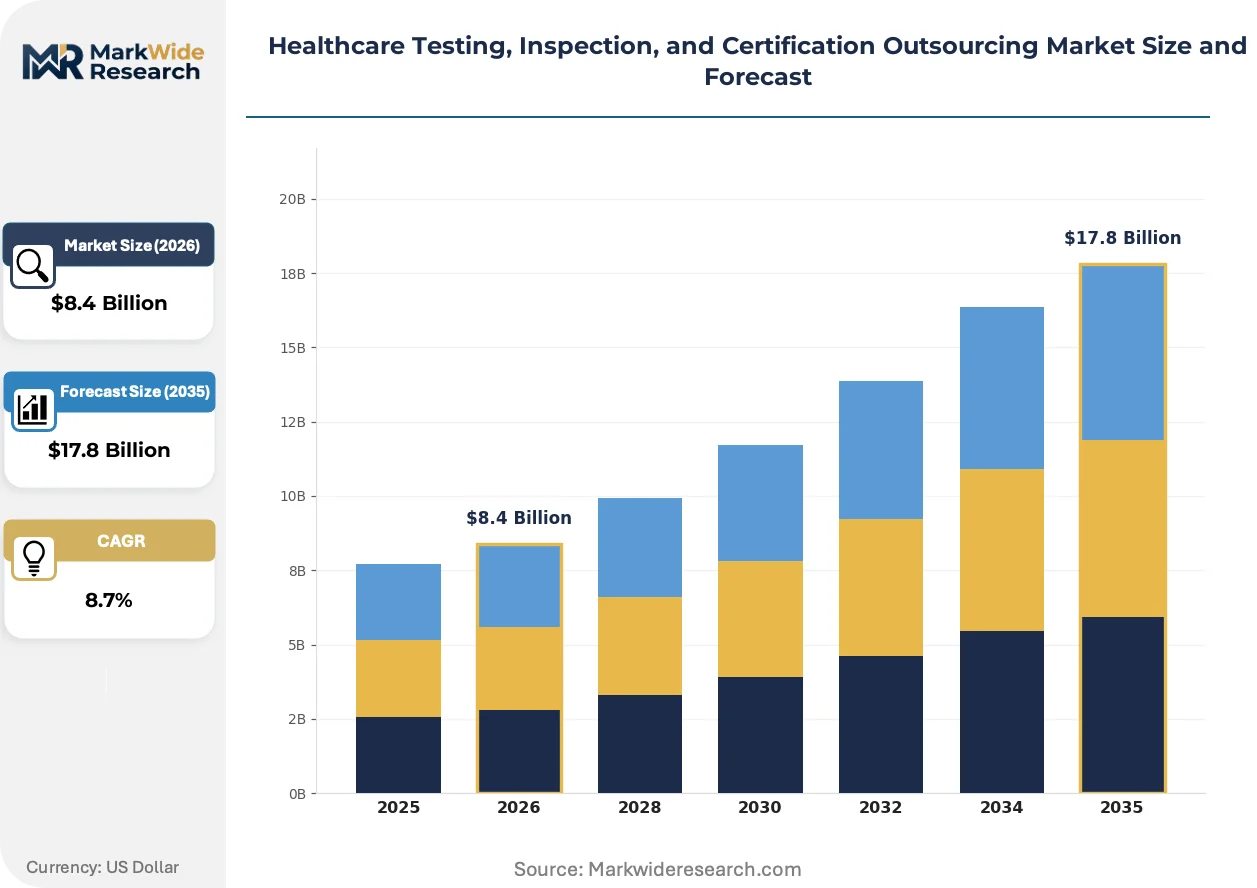
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $17.8 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Quality Assurance, Compliance Testing, Environmental Testing, Product Certification End User: Pharmaceuticals, Medical Devices, Diagnostics, Biologics Technology: Laboratory Testing, Radiography, Ultrasonography, Automated Inspection Industry Vertical: Life Sciences, Healthcare, Food Safety, Biotechnology |
| Companies Covered | SGS SA, Intertek Group plc, Eurofins Scientific SE, DEKRA CERTIFICATION B.V., UL Solutions Inc., TÜV SÜD, ALS Limited, CSA Group Testing & Certification Inc., Applus+ Technologies, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Healthcare Testing, Inspection, and Certification Outsourcing Market Strategic Shifts & Innovations
Digitalization of quality management systems is compressing documentation cycles and enabling remote audit capabilities that reshape geographic service delivery models. These shifts are converging with regulatory data integrity mandates to redefine competitive differentiation among outsourcing providers.
Automated laboratory execution systems are consolidating fragmented analytical workflows into unified platforms that integrate sample tracking, instrument control, and regulatory reporting. Pharmaceutical quality departments are adopting these systems to reduce manual transcription errors and accelerate batch release timelines. This consolidation is compressing the competitive advantage of smaller regional laboratories lacking capital for platform deployment.
EU MDR's Unique Device Identification requirements are mandating serialized traceability systems that extend from manufacturing through post-market surveillance. Device manufacturers must now maintain electronic records linking each unit to its complete testing and certification history. European notified bodies are expanding their software validation capabilities to audit these integrated quality management systems.
Biologics developers are unbundling traditional full-service contracts in favor of modular engagement structures that separate analytical method development from routine release testing. This purchasing pattern is compressing contract durations and intensifying price transparency across service tiers. The shift is most visible among mid-cap gene therapy developers in Massachusetts and North Carolina research triangles seeking to preserve capital runway.
Healthcare Testing, Inspection, and Certification Outsourcing Market Segmentation
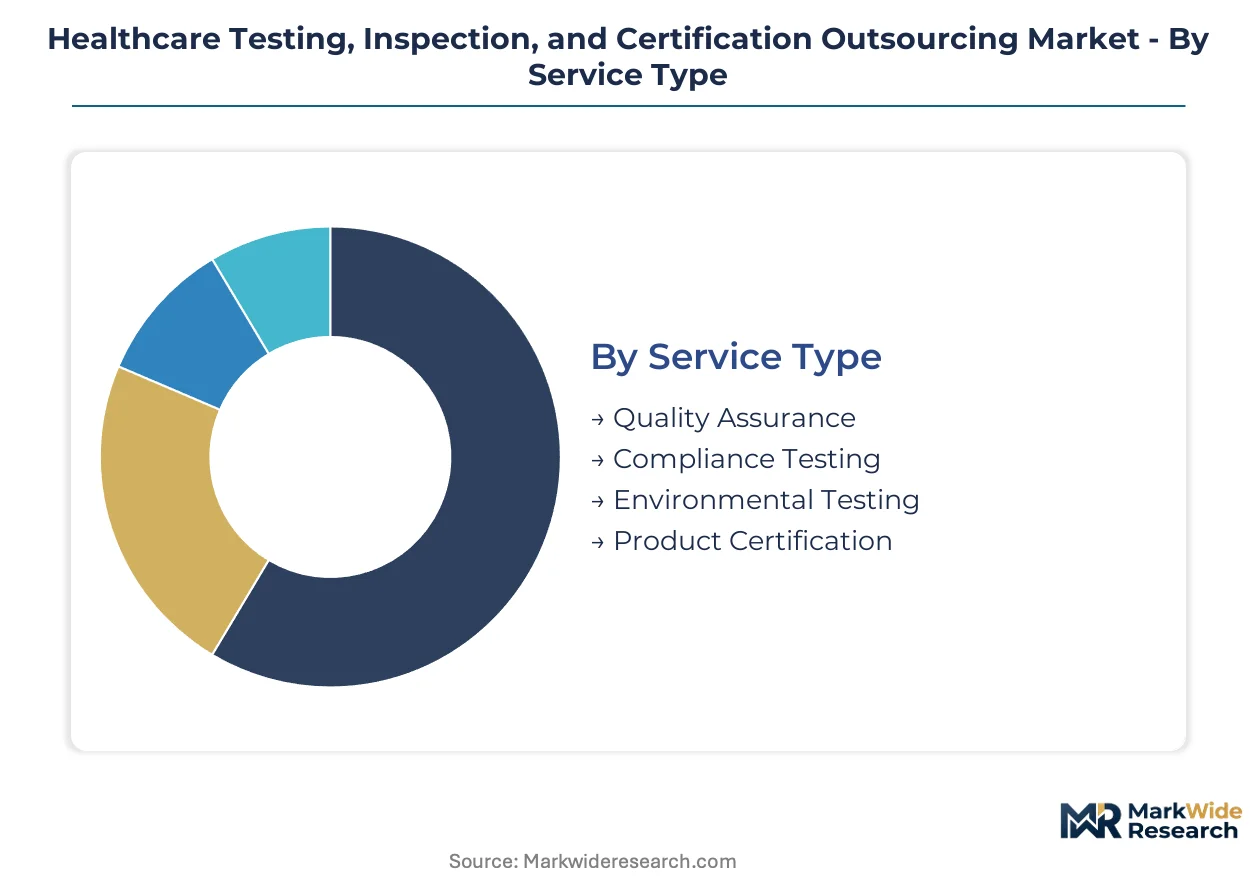
Segmentation in healthcare TIC outsourcing reveals how regulatory complexity fragments service demand across distinct technical and customer dimensions. Manufacturers select validation partners based on the intersection of their product modality, compliance jurisdiction, and analytical technology requirements.
Service Type:
Technical sophistication and documentation burden define the specification hierarchy across outsourced validation services.
- Quality Assurance:Recurring batch-release protocols and stability monitoring constitute the operational backbone of pharmaceutical manufacturing partnerships. QA contracts concentrate among large molecule developers in Massachusetts and North Carolina facing FDA's intensified pre-approval inspection schedules.
- Compliance Testing:Novel documentation requirements under EU MDR and FDA's updated QSR are accelerating external procurement of risk management validation and clinical evaluation report preparation. Cell-and-gene therapy developers in Cambridge and Research Triangle Park drive fastest adoption of modular compliance engagements.
- Environmental Testing:Cleanroom validation and sterility assurance monitoring support aseptic manufacturing operations.
- Product Certification:Notified body engagement for CE marking and FDA 510(k) clearance pathways.
Mature deployment sits with Quality Assurance. Newer deployment is concentrated in Compliance Testing.
End User:
Customer type determines the regulatory intensity and analytical complexity of outsourcing relationships.
- Medical Devices:EU MDR's expanded scope and Unique Device Identification mandates are compressing manufacturer timelines for technical documentation and post-market surveillance. German and Irish device clusters are driving notified body capacity expansion across pan-European laboratory networks.
- Biologics:Autologous cell therapies and gene editing platforms exceed in-house analytical capabilities for potency assay development and vector characterization. Massachusetts biotech corridors are unbundling full-service contracts into discrete method development and release testing modules.
- Pharmaceuticals:Small molecule developers leverage outsourcing for stability studies and impurity profiling.
- Diagnostics:IVD manufacturers face parallel FDA and EU IVDR compliance pathways.
Established volume concentrates in Medical Devices. Steepest expansion trajectory is visible in Biologics.
Technology:
Capital equipment requirements and data integrity standards differentiate technical approaches to validation.
- Laboratory Testing:Chromatography, mass spectrometry, and cell-based bioassays form the analytical foundation for biologics release. ISO 17025-accredited facilities in Basel and Boston command premium positioning for complex method validation.
- Automated Inspection:Machine vision systems and robotic sampling are compressing manual transcription errors in batch release workflows. Indian pharmaceutical manufacturing clusters in Hyderabad are adopting PAT-enabled continuous manufacturing validation.
- Radiography:Non-destructive testing for implantable device integrity verification.
- Ultrasonography:Weld inspection and packaging seal validation for sterile barrier systems.
Capital intensity peaks with Laboratory Testing. Automation adoption is climbing fastest in Automated Inspection.
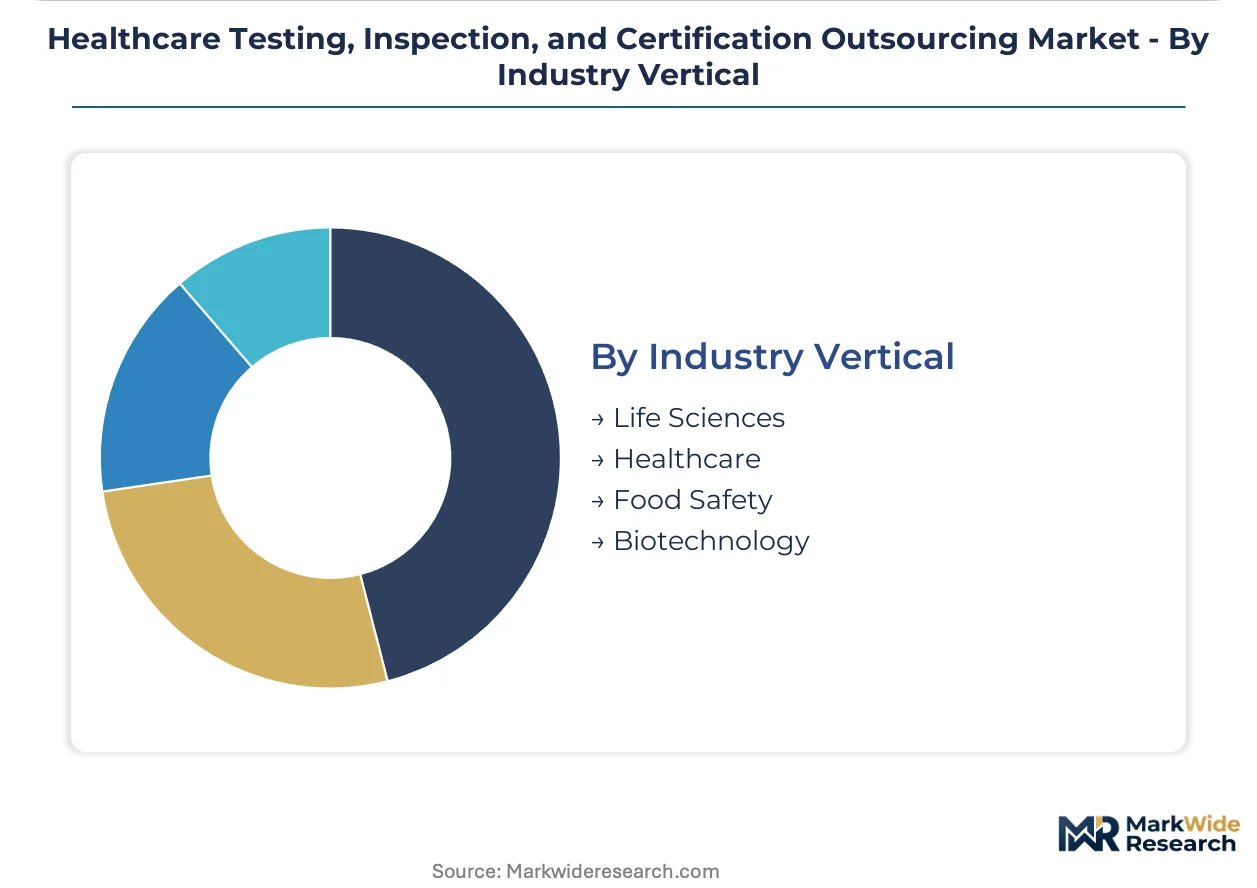
Industry Vertical:
End-market regulatory frameworks shape the geographic and capability requirements of certification partnerships.
- Life Sciences:Pharmaceutical and biologics manufacturers face converging FDA-EMA inspection protocols that favor outsourcing partners with dual jurisdiction experience. Swiss and German quality consultancies are consolidating method transfer capabilities across Atlantic regulatory boundaries.
- Healthcare:Hospital-acquired infection control and sterilization validation services are expanding with centralized sterile processing department outsourcing.
- Food Safety:Nutraceutical manufacturers leverage pharmaceutical-grade testing infrastructure for contaminant screening.
- Biotechnology:Research tool and reagent suppliers require ISO 13485 quality system certification for diagnostic-grade material production.
Regulatory complexity concentrates in Life Sciences. Cross-vertical capability expansion is gaining share fastest in Food Safety.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts biotechnology tax credits and North Carolina's research investment incentives are concentrating biologics TIC demand in specialized coastal corridors. German medical device manufacturing subsidies and Swiss pharmaceutical R&D zones further anchor European outsourcing gravity.
United States
FDA's intensified pre-approval inspection schedules and Quality Management System Regulation updates are driving external validation procurement. Massachusetts biotech corridors in Cambridge and Waltham are unbundling full-service contracts into modular method development and release testing engagements. North Carolina's Research Triangle Park hosts expanding gene therapy developers seeking ISO 17025-accredited partners for autologous therapy characterization.
Germany
EU MDR's expanded technical documentation requirements and Unique Device Identification mandates are compressing manufacturer certification timelines. TÜV SÜD's deep integration with Baden-Württemberg and Bavaria medical device clusters exemplifies regional laboratory network expansion. Berlin-Brandenburg's notified body capacity constraints are redirecting manufacturers toward pan-European validation partnerships.
Switzerland
Swissmedic's convergence with EMA inspection protocols and Basel's pharmaceutical manufacturing density are elevating dual-jurisdiction capability requirements. Swiss quality consultancies are consolidating method transfer capabilities across Atlantic regulatory boundaries. Zurich and Geneva laboratories command premium positioning for complex biologics method validation under ICH guidelines.
India
CDSCO's alignment with ICH guidelines and USFDA-registered export facility expansion are opening inspection and certification demand. Hyderabad and Ahmedabad pharmaceutical manufacturing clusters are adopting process analytical technology-enabled continuous manufacturing validation. Telangana's life sciences special economic zones are attracting outsourced quality assurance partnerships from multinational developers.
United Kingdom
MHRA's post-Brexit regulatory divergence from EMA frameworks and intensified pharmacovigilance obligations are reshaping certification procurement patterns. London and Southeast England's contract research organizations are adapting to dual UK-EU conformity assessment requirements. Cambridge's cell therapy developers are seeking modular compliance engagements for novel analytical method qualification.
Healthcare Testing, Inspection, and Certification Outsourcing Market Key Industry Players
Swiss and German producers anchor the premium-tier validation segment; US-based specialists hold modular biologics testing capabilities. The vendor base concentrates around pan-European laboratory networks with multiple notified body designations and ISO 17025-accredited facilities spanning dual FDA-EMA jurisdictions. Three archetypes dominate: full-service conglomerates with geographic breadth, specialized biologics analytical shops, and regional compliance boutiques. Competitive moves center on notified body capacity expansion and strategic partnerships for cell-and-gene therapy method development.
Within the full-service tier, SGS SA leverages its pan-European laboratory network to sustain positioning in notified body services. Eurofins Scientific SE anchors growth through specialized biologics testing capabilities. TÜV SÜD occupies a position defined by deep integration with German medical device manufacturing clusters. These three exemplify how geographic origin and structural form signal strategic archetype without requiring operational specifics.
| Leading Market Players |
|---|
| SGS SA |
| Intertek Group plc |
| Eurofins Scientific SE |
| DEKRA CERTIFICATION B.V. |
| UL Solutions Inc. |
| TÜV SÜD |
| ALS Limited |
| CSA Group Testing & Certification Inc. |
| Applus+ Technologies, Inc. |
| Others |
Cost & Logistics Intelligence
Captive in-house quality department dismantling anchors both supply positioning and pricing power across healthcare TIC outsourcing, as pharmaceutical and medical device manufacturers substitute fixed-cost laboratory infrastructure for variable-cost third-party validation partnerships under FDA's updated Quality Management System Regulation.
Pricing Analysis
Premium pricing for expedited lead times compresses standard-tier margins, while spot inventory availability commands discount structures for non-urgent batch release. The dominant pricing model runs through project-based engagements for method development and routine testing contracts, with differentiation driven by ISO 17025 accreditation tier and geographic proximity to Massachusetts biotech corridors. Cost compression in standard-tier services intensifies as Indian pharmaceutical manufacturing clusters adopt process analytical technology-enabled validation. Mid-cap gene therapy developers in North Carolina research triangles exhibit highest price sensitivity, while large molecule developers in Basel and Boston demonstrate lowest sensitivity due to regulatory risk aversion.
Supply Chain Analysis
Dual-sourcing requirements for critical analytical instrumentation mandate multi-supplier qualification across chromatography and mass spectrometry platforms, as testing laboratories hedge against single-source dependencies from dominant equipment vendors. Geographic supply concentration centers on Germany, Switzerland, and the United States for ISO 17025-accredited facilities and notified body designations. Raw material dependencies rest on specialized reagents, reference standards, and cell culture media subject to REACH chemical registration burdens. Single-source equipment vulnerability creates structural supply risk. Distribution runs through direct laboratory partnerships and GPO-negotiated contracts with hospital systems and pharmaceutical manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Healthcare TIC outsourcing functions as a cost-of-compliance market where FDA's Quality Management System Regulation and EU MDR erect barrier-to-entry moats for ISO 17025-accredited players with dual jurisdiction capabilities.
For Market Incumbents: Hedge against modular contract unbundling by consolidating method transfer capabilities across Atlantic regulatory boundaries, while adding notified body capacity in Berlin-Brandenburg to capture redirected manufacturer demand from capacity-constrained German laboratories. Cell-and-gene therapy complexity threatens full-service contract retention, making biologics analytical specialization the priority investment lever.
For New Entrants and Emerging Players: The price-point gap between premium Swiss-German validation services and economy-tier Indian offerings creates white-space opportunity in Hyderabad and Ahmedabad pharmaceutical clusters, where CDSCO-aligned facilities serve USFDA-registered export manufacturers. Target real-time release testing implementation for continuous manufacturing validation as the most penetrable service tier, with go-to-market positioning as PAT-enabled specialists.
For Investors and Strategic Acquirers: Exit pathways concentrate in pan-European laboratory networks with multiple notified body designations and dual FDA-EMA jurisdiction experience. Long-term viability over the next decade hinges on biologics testing capability depth and software validation expertise for EU MDR Unique Device Identification mandates. Watch EMA-FDA mutual recognition negotiation progress as the inflection signal for geographic demand redistribution toward consolidated validation hubs.
| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Capacity Expansion | EU MDR bottlenecks redirect manufacturer demand toward multi-designation laboratory networks. |
| Cell-and-Gene Therapy Method Development | Autologous therapy complexity exceeds in-house capabilities, creating specialized CRO partnerships. |
| PAT-Enabled Continuous Manufacturing Validation | Process analytical technology integration opens service white space for implementation specialists. |
| Dual Jurisdiction Quality Consultancy Consolidation | FDA-EMA inspection protocol convergence favors Atlantic-spanning method transfer capabilities. |
| Software Validation Capability Buildout | EU MDR Unique Device Identification mandates extend testing into electronic record audit systems. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, while primary interviews with regulatory affairs directors, quality assurance managers, biomedical engineers, and GPO contracts managers validated demand-side assumptions. FDA 510(k) clearance databases, EMA notified body registers, ISO 17025 accreditation listings, and hospital procurement contract disclosures supplied quantitative foundations. Bottom-up service provider revenue aggregation and top-down pharmaceutical R&D spending allocation models were reconciled through iterative triangulation.
Data-stream reconciliation across service type, end-user modality, analytical technology, and geographic regulatory cluster dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate synthesis anchored in regulatory workload intensity and outsourcing penetration trajectories. Cell-and-gene therapy pipeline expansion and EU MDR implementation timelines served as industry-specific forecast inputs.
Inputs from FDA warning letter databases and EMA inspection outcome reports were available through the study window; gaps in private contract research organization financial disclosures introduce uncertainty bands around market share estimates. Forecasts reflect documented assumptions regarding regulatory harmonization progress and notified body capacity expansion timelines. A model refresh is warranted upon material change in EMA-FDA mutual recognition agreement negotiations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Viral Vector Integrity and Potency Analytics Test Instruments Market
Testing Services
Specific Protein Testing Market
Testing Services
Asia Pacific Pregnancy and Ovulation Testing Market
Testing Services
Metabolic Biomarker Testing Market
Testing Services
North America Testing Inspection and Certification (TIC) Market
Testing Services
Rapid Coagulation Testing Market
Testing Services
Global HPV Testing and Pap Test Market
Testing Services
Nucleic Acid Amplification Testing Market
Testing Services
Asia-Pacific Antimicrobial Susceptibility Testing Market
Testing Services
Europe Medical Device Testing Market
Testing Services
Urodynamic Testing Market
Testing Services
Global GI Stool Testing Market
Testing Services
Comprehensive Metabolic Panel (CMP) Testing Market
Testing Services
United States Testing, Inspection, and Certification (TIC) Market
Testing Services
Global Coagulation Testing Market
Testing Services
Dengue Testing Market