
 Electromagnetic and Radio Frequency Interference Coating Market | 2026-2036
Electromagnetic and Radio Frequency Interference Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Electromagnetic and Radio Frequency Interference Coating Market Intelligence
A scarcity of materials science expertise in conductive polymer formulation is redrawing the competitive landscape for EMI/RFI shielding. Henkel AG leverages its deep chemical formulation knowledge to develop specialized conductive coatings for consumer electronics. PPG Industries competes on its ability to scale production of spray coatings for large-volume automotive applications. 3M Company differentiates through its broad portfolio of both conductive and absorptive materials.
Electromagnetic and radio frequency interference coatings are functional layers applied to surfaces to attenuate unwanted electromagnetic energy. These coatings typically contain conductive or magnetic fillers, such as silver, nickel, or ferrite, suspended in a polymer binder to achieve specific shielding effectiveness levels. Conductive coatings represent the largest product segment due to their widespread use in plastic electronics enclosures. Spray coating methods dominate for their cost-effectiveness and applicability to complex geometries, especially in the automotive sector.
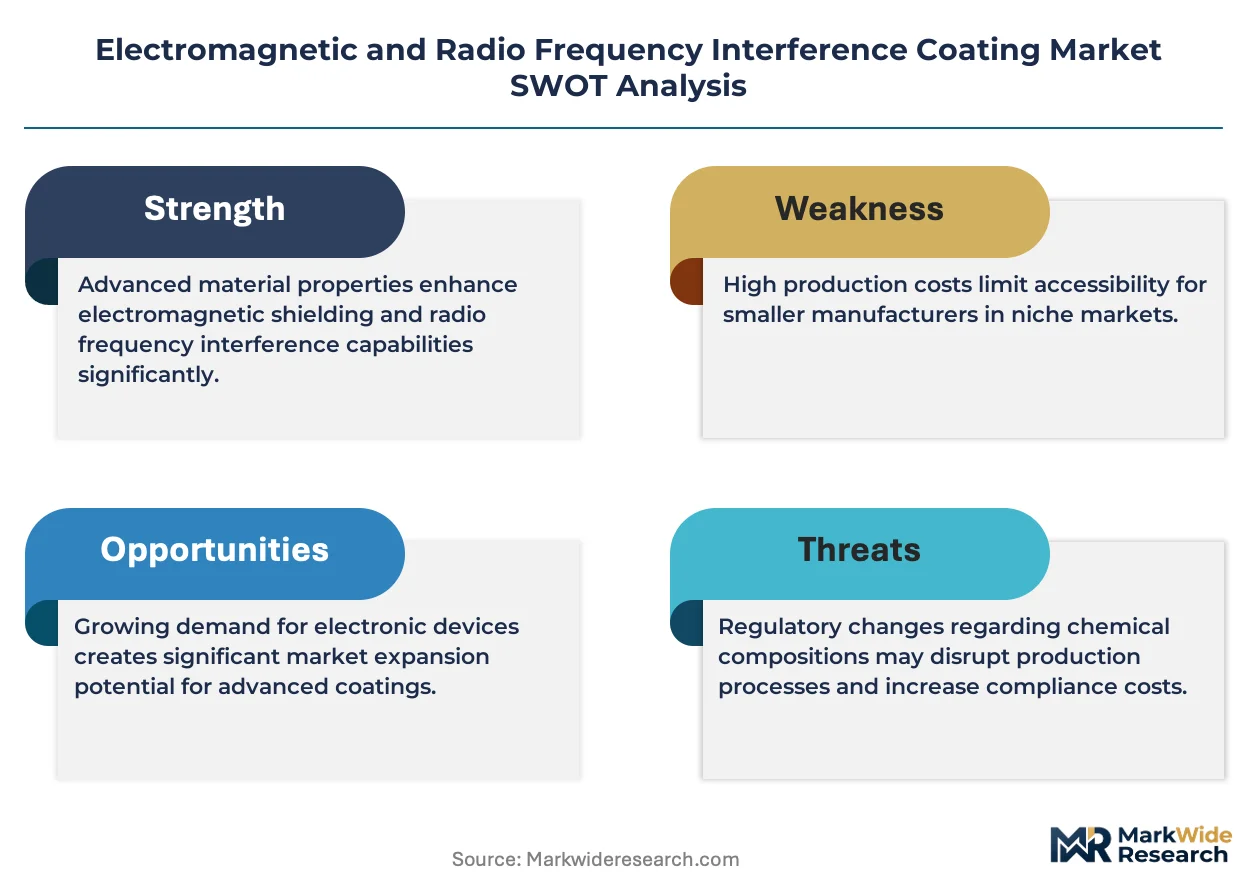
Regulatory frameworks like the U.S. FCC's Part 15 rules and the European Union's EMC Directive set strict limits on unintentional emissions from electronic devices. Compliance with these standards, along with China's GB standards for electronic product safety, directly necessitates the use of effective EMI/RFI shielding solutions. Decisions on material selection, balancing cost against shielding effectiveness and environmental compliance, will define supplier success.
Market Dynamics
The proliferation of sensitive electronics in electric vehicles and consumer devices creates a denser electromagnetic environment. This, combined with stricter emissions standards from regulators like the EU and FCC, is the central force demanding higher-performance and more reliable EMI/RFI shielding coatings across multiple industries.
Growth Catalysts
- Electric Vehicle Production:Expanding EV manufacturing in Germany and South Korea requires shielding for ADAS and battery systems, driving demand for automotive coatings.
- Regulatory Mandates:The EU's Radio Equipment Directive and FCC Part 15 rules require effective shielding, making coatings a prerequisite for electronics market access.
- 5G Technology:The rollout of 5G networks requires superior RFI shielding to maintain signal integrity, creating demand for coatings effective at high frequencies.
Market Restraints
- Raw Material Volatility:Price fluctuations in key conductive fillers like silver and nickel create cost instability and margin pressure for coating manufacturers.
- Substrate Adhesion:Achieving durable adhesion on new composite and bio-based polymers used in lightweighting presents a persistent technical formulation challenge.
- Alternative Shielding Solutions:Competition from metal housings, conductive gaskets, and board-level shielding limits the market for coatings in certain applications.
Strategic Opportunities
- Medical Wearables:The market for connected medical wearables requires lightweight, flexible, and biocompatible EMI shielding, creating a high-value opportunity for specialized coatings.
- Multifunctional Coatings:Formulations combining EMI shielding with thermal management offer a path to product differentiation in compact electronic devices.
- Southeast Asian Expansion:Growth in electronics assembly in Vietnam and Malaysia creates an untapped market for localized coating production and technical support.
Industry Challenges
- Formulation Expertise Scarcity:A shortage of materials scientists with expertise in conductive polymer formulation and filler dispersion hinders new product development across the industry.
- Navigating Global Regulations:Ensuring compliance with a complex and evolving patchwork of environmental rules, such as the EU's REACH regulation, is a significant operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electromagnetic and Radio Frequency Interference Coating Market |
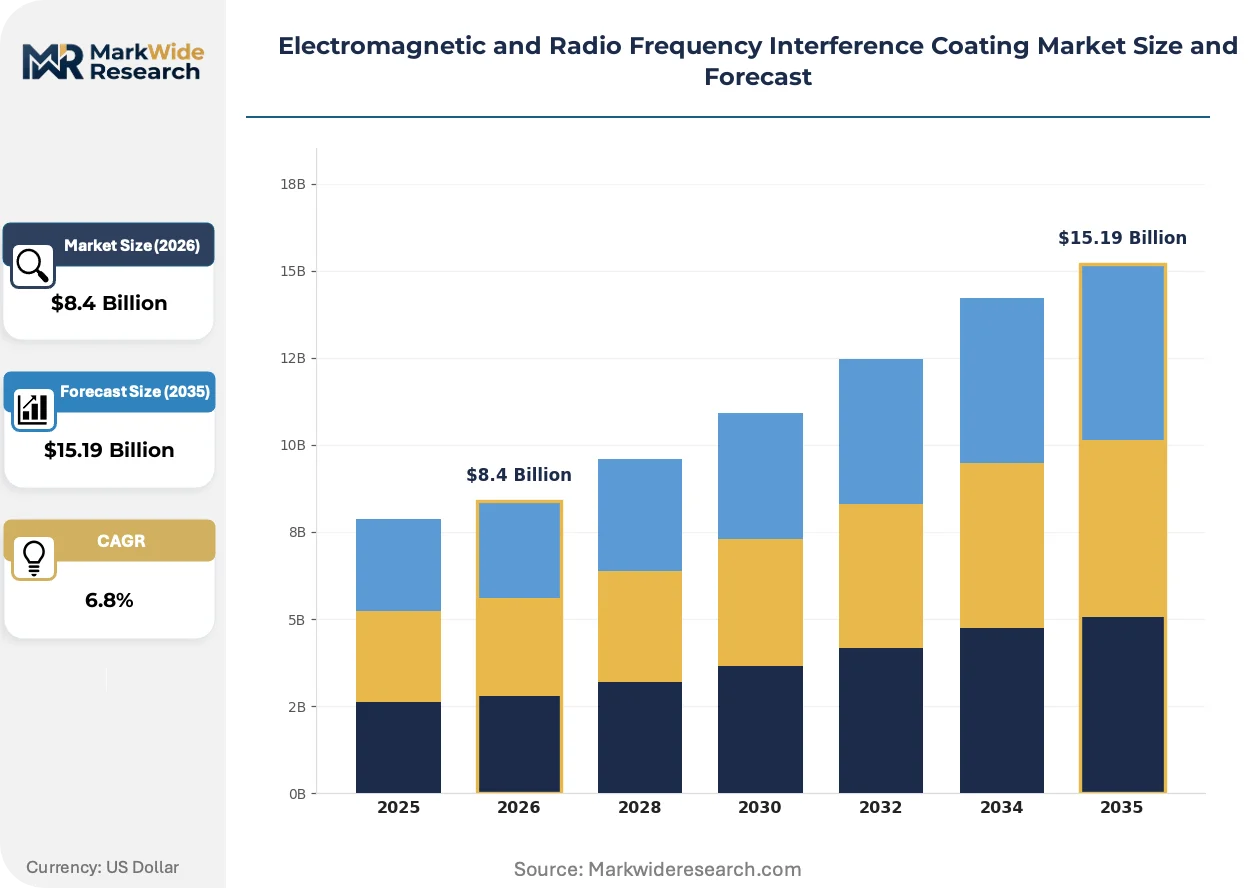
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.19 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
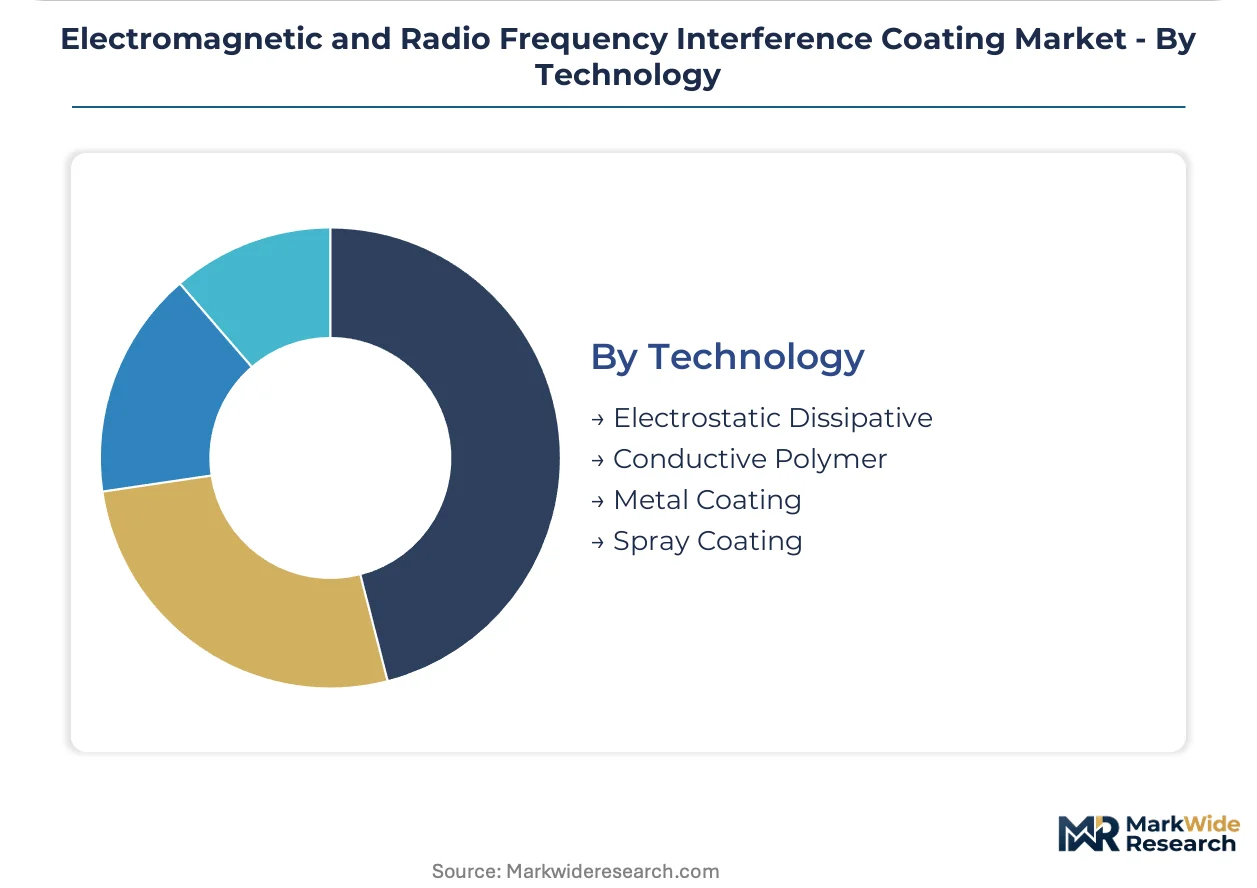
| Segmentation | Product Type: Conductive Coating, Absorptive Coating, Hybrid Coating, Reflective Coating Application: Aerospace, Consumer Electronics, Automotive, Telecommunications End User: Manufacturers, OEMs, System Integrators, Suppliers Technology: Electrostatic Dissipative, Conductive Polymer, Metal Coating, Spray Coating |
| Companies Covered | Parker Hannifin, PPG Industries, Henkel AG, 3M Company, Nanotech Energy, MG Chemicals, Sono-Tek, Leader Tech, Electroninks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electromagnetic and Radio Frequency Interference Coating Market Strategic Shifts & Innovations
The drive for material efficiency and sustainability is transforming EMI/RFI coating development. Innovations focus on creating thinner, lighter, and more environmentally benign formulations that also deliver enhanced performance characteristics for next-generation electronics.
Advanced carbon-based coatings using graphene and carbon nanotubes provide lightweight, flexible EMI shielding. The aerospace and portable electronics sectors are early adopters for applications where weight is critical. This nanotechnology-based approach is displacing traditional, heavier metal-flake coatings in high-performance and weight-sensitive designs.
China's "dual carbon" goals and stricter GB standards for electronics are pushing for greener materials. This pressures manufacturers to reduce volatile organic compounds (VOCs), favoring water-based coating systems over solvent-based ones. The vast consumer electronics supply chain in China is most affected, accelerating R&D into compliant, low-VOC conductive coatings.
A significant demand-side shift involves OEMs specifying shielding performance at the final device level, not just the component level. This model disrupts traditional procurement, forcing coating suppliers to provide early-stage design and application engineering support. The trend is most prominent within the automotive and medical device sectors of Germany and the United States.
Electromagnetic and Radio Frequency Interference Coating Market Segmentation
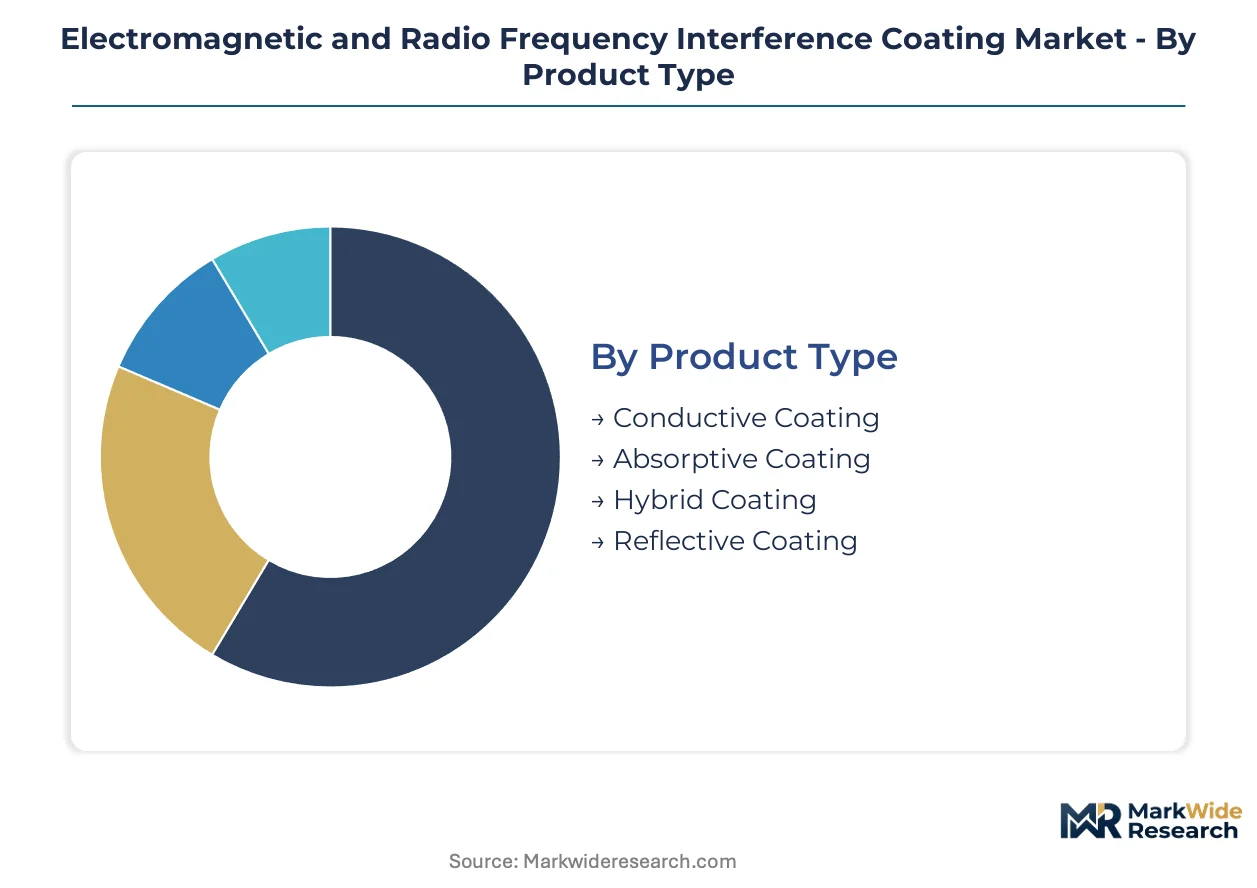
The Electromagnetic and Radio Frequency Interference (EMI/RFI) coating market segmentation reflects the diverse technical demands and regulatory compliance needs across electronic devices. Different product types, applications, and technologies address specific shielding effectiveness requirements for various industries. This granular view clarifies market dynamics.
Product Type:
Regulatory frameworks worldwide differentiate the performance requirements for EMI/RFI coatings, influencing the selection of specific product types.
- Conductive Coating:These coatings incorporate conductive fillers like silver, nickel, or carbon to form a continuous conductive layer, effectively reflecting and absorbing electromagnetic waves. The consumer electronics and automotive sectors generate significant demand for these coatings, especially for plastic enclosures.
- Absorptive Coating:Absorptive coatings utilize magnetic fillers such as ferrites to convert electromagnetic energy into heat, preventing reflection and re-radiation. The aerospace sector requires these coatings for stealth applications and sensitive avionics where reflection must be minimized.
- Hybrid Coating:Hybrid coatings combine conductive and absorptive properties, offering balanced shielding effectiveness across a wide frequency range for complex interference scenarios.
- Reflective Coating:Reflective coatings primarily use highly conductive metallic particles to bounce electromagnetic waves away from sensitive components, preventing internal interference.
Conductive Coating handles the majority of throughput; Absorptive Coating is the fastest mover on share.
Application:
The scale and complexity of electronic systems within various applications dictate the volume and specificity of EMI/RFI coating requirements.
- Automotive:The automotive sector applies EMI/RFI coatings to protect sensitive electronic control units, ADAS sensors, and battery systems from electromagnetic interference. Germany and South Korea's expanding EV production drives significant demand for these specialized coatings.
- Consumer Electronics:Consumer electronics devices, including smartphones and laptops, rely on EMI/RFI coatings to ensure electromagnetic compatibility and prevent self-interference. China's vast manufacturing base for these devices creates a large volume market.
- Aerospace:Aerospace applications demand high-performance, lightweight EMI/RFI coatings for avionics, communication systems, and satellite components, ensuring reliable operation in harsh environments.
- Telecommunications:Telecommunications infrastructure, especially 5G equipment, requires robust RFI shielding to maintain signal integrity and system reliability in high-frequency operations.
The automotive segment experiences the steepest expansion trajectory, while consumer electronics maintain consistent volume.
End User:
Different end-user types exhibit distinct procurement patterns and technical collaboration requirements for EMI/RFI coating solutions.
- Manufacturers:Manufacturers integrate EMI/RFI coatings directly into their production lines for various electronic components and devices. They often seek standardized, high-volume coating solutions that are easy to apply.
- OEMs:Original Equipment Manufacturers (OEMs) specify EMI/RFI coating performance at the device level, requiring close partnership with coating suppliers for design and application engineering support. This is prominent in automotive and medical device sectors.
- System Integrators:System integrators apply EMI/RFI coatings to ensure compatibility and performance when assembling complex electronic systems from multiple components.
- Suppliers:Suppliers provide coated components or raw coating materials to manufacturers and OEMs, often specializing in specific material formulations and technical expertise.
OEMs define the critical performance benchmarks, pushing innovation, while Manufacturers drive the bulk of material consumption.
Technology:
The maturity and performance characteristics of various coating technologies determine their suitability for specific EMI/RFI shielding challenges.
- Spray Coating:Spray coating methods offer cost-effectiveness and applicability to complex geometries, making them dominant in high-volume applications like the automotive sector. This technology enables efficient application over large surfaces.
- Conductive Polymer:Conductive polymer technology utilizes intrinsically conductive polymers or polymer matrices with dispersed conductive fillers, offering flexibility and lightweight properties. This approach is gaining traction in medical wearables and portable electronics.
- Electrostatic Dissipative:Electrostatic dissipative coatings prevent static charge buildup, which can interfere with sensitive electronics, particularly in manufacturing environments.
- Metal Coating:Metal coating technologies apply thin layers of highly conductive metals, such as copper or nickel, to substrates for robust EMI shielding in demanding applications.
Spray Coating technology sees widespread adoption due to its versatility, while Conductive Polymer technology is rapidly expanding its market presence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European Union's Radio Equipment Directive anchors demand for EMI/RFI coatings by mandating strict electromagnetic compatibility. This regulatory push, combined with rapid electrification in automotive and consumer electronics, drives market growth. Key manufacturing hubs in Asia and Europe are experiencing significant demand for advanced shielding solutions.
Germany
Electric vehicle production and advanced medical device manufacturing drive significant demand for EMI/RFI coatings in Germany. The KBA (Federal Motor Transport Authority) mandates stringent EMC standards for automotive electronics. Bavaria's automotive cluster and Berlin's medtech innovators require high-performance, specialized shielding solutions.
South Korea
Rapid expansion in electric vehicle manufacturing and consumer electronics production fuels the need for EMI/RFI shielding in South Korea. The MFDS (Ministry of Food and Drug Safety) also influences medical device shielding requirements. The Gyeonggi Province, a hub for both automotive and electronics, sees high coating consumption.
China
China's vast consumer electronics manufacturing base and surging electric vehicle market create substantial demand for EMI/RFI coatings. The national GB standards for electronic product safety directly necessitate effective shielding. The Yangtze River Delta region, with its dense electronics supply chain, experiences robust coating adoption.
United States
The aerospace sector and medical wearables drive demand for specialized EMI/RFI coatings across the United States. The FCC's Part 15 rules establish strict limits on unintentional emissions from electronic devices. Silicon Valley's tech companies and the Midwest's automotive suppliers require advanced shielding solutions.
Japan
Advanced automotive electronics and 5G telecommunications infrastructure bolster demand for high-frequency EMI/RFI coatings in Japan. METI (Ministry of Economy, Trade and Industry) promotes innovation in materials science for electronics. The Kanto region, including Tokyo, remains a critical center for electronics R&D and manufacturing.
Electromagnetic and Radio Frequency Interference Coating Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, defining the competitive landscape for EMI/RFI coatings. This market exhibits a tiered structure, with large chemical companies and diversified industrial conglomerates competing with niche material science firms. Strategic archetypes include high-volume solution providers, specialized performance innovators, and broad portfolio suppliers. Companies focus on portfolio diversification and strategic partnerships to enhance their market presence.
Among established chemical formulators, PPG Industries and Henkel AG exemplify the strength of large-scale production and deep chemical expertise. PPG Industries, a US-based corporation, represents a leader in scaling spray coating solutions for high-volume automotive applications, leveraging its global manufacturing footprint. Henkel AG, a German multinational, occupies a position anchored by its advanced chemical formulation knowledge, developing specialized conductive coatings for consumer electronics. 3M Company, another US-based conglomerate, differentiates through its broad portfolio of both conductive and absorptive materials, serving diverse industrial needs across multiple sectors.
| Leading Market Players |
|---|
| Parker Hannifin |
| PPG Industries |
| Henkel AG |
| 3M Company |
| Nanotech Energy |
| MG Chemicals |
| Sono-Tek |
| Leader Tech |
| Electroninks |
| Others |
Cost & Logistics Intelligence
Typical lead times for custom EMI/RFI coating formulations often extend beyond 8-12 weeks, directly impacting supply chain responsiveness and influencing project-based pricing for specialized applications.
Pricing Analysis
Geographic price spreads for EMI/RFI coatings vary significantly, reflecting regional manufacturing costs and regulatory compliance requirements. The dominant pricing structure combines project-based contracts for custom formulations with per-unit transactional pricing for high-volume standard products. Price differentiation stems from shielding effectiveness levels and the required environmental compliance certifications, such as EU REACH. Pricing softness runs through commodity-grade coatings due to competition from alternative shielding solutions. Manufacturers focusing on high-volume consumer electronics exhibit the highest price sensitivity, while aerospace and medical device OEMs prioritize performance over cost.
Supply Chain Analysis
Inventory levels for specialized conductive fillers remain tight due to concentrated global mining and processing. The supply chain for EMI/RFI coatings draws from key manufacturing hubs in Germany, South Korea, and China for finished products. Raw material dependencies include silver, nickel, and specialized polymer resins. A structural risk involves commodity price volatility for conductive fillers, creating margin pressure for coating manufacturers. Distribution runs through direct sales channels to large OEMs and manufacturers, supplemented by specialized distributors for smaller volume integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Electromagnetic and Radio Frequency Interference Coating Market represents an early-cycle expansion story, driven by the increasing integration of sensitive electronics across critical industries.
For Market Incumbents:
Consolidate market leadership by addressing core technical challenges like substrate adhesion on new composite materials. Invest in advanced materials science R&D to develop flexible, lightweight, and biocompatible coatings, countering the threat from emerging carbon-based alternatives. Expand localized production capabilities in high-growth electronics assembly regions like Southeast Asia to support OEM partners and control distribution channels. This strategy helps mitigate raw material volatility by optimizing formulation efficiency.
For New Entrants and Emerging Players:
Differentiate on novel material science and application-specific solutions, targeting underserved niches. Focus on medical wearables and portable electronics, where demand for lightweight, flexible EMI shielding presents a penetrable segment. A go-to-market angle emphasizing nanotechnology-based carbon coatings can displace traditional heavier metal-flake solutions. Develop multifunctional coatings that integrate thermal management, providing a unique value proposition for compact electronic devices.
For Investors and Strategic Acquirers:
Long-term, this sits as a technology-driven growth play because stringent regulatory frameworks and electronics proliferation continue to expand shielding requirements. Acquisition targets should include specialized material science firms with proprietary conductive polymer formulations or advanced carbon-based coating technologies. The signal to watch is the commercialization success and widespread adoption of low-VOC, water-based coating systems, indicating a shift towards sustainable solutions.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Supports localized production for electronics assembly hubs in Vietnam and Malaysia. |
| R&D in Advanced Conductive Polymers | Addresses substrate adhesion challenges and enables flexible, lightweight solutions for new materials. |
| Strategic OEM Partnership Programs | Provides early-stage design and application engineering support for critical device integration. |
| Product Diversification into Multifunctional Coatings | Combines EMI shielding with thermal management for compact, high-performance electronics. |
| Investment in Water-Based Coating Systems | Aligns with global environmental compliance, particularly China's stricter GB standards. |
Research Approach
A spread of perspectives from materials scientists, automotive OEM engineers, regulatory compliance officers, and coating manufacturers' sales directors converged on the working assumptions for this market. This study combined qualitative insights from primary interviews with quantitative validation through secondary data sources, including regulatory body publications from the EU's RED and FCC Part 15, industry association reports, and company annual filings, employing both bottom-up and top-down triangulation.
Segmentation dimensions modeled include product type, application, end user, technology, and shielding effectiveness level. The analytical framework projected market size and growth across the analysis window by deriving compound annual growth rates from historical trends, market share evolution, and anticipated technological shifts. Key industry-specific forecast inputs included electric vehicle production forecasts and 5G network deployment schedules.
Material uncertainties — including raw material price volatility, evolving regulatory landscapes, and the emergence of disruptive shielding alternatives — sit outside the modeled envelope. Forecasts reflect assumptions documented at the time of publication. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aerospace and Aircraft Materials
Aerogel Market
Aerospace and Aircraft Materials
Global AFP/ATL Machines Market
Aerospace and Aircraft Materials
Aerospace Fasteners Market
Aerospace and Aircraft Materials
Aerographene Market
Aerospace and Aircraft Materials
Aircraft Carbon Brake Disc Market
Aerospace and Aircraft Materials
Asia-Pacific Aerospace Composites Market
Aerospace and Aircraft Materials
Ablative Coatings Market
Aerospace and Aircraft Materials
Aircraft Aluminium Plate Market
Aerospace and Aircraft Materials
Aerospace Raw Materials Market
Aerospace and Aircraft Materials
Europe Aerospace Composites Market
Aerospace and Aircraft Materials
Aircraft Coatings Market
Aerospace and Aircraft Materials
Aviation Carbon Fiber Market
Aerospace and Aircraft Materials
Commercial Aerospace Carbon Brakes Market
Aerospace and Aircraft Materials
Advanced Materials for Flying Cars Market
Aerospace and Aircraft Materials
Titanium Aerospace Forgings Market
Aerospace and Aircraft Materials
Coated Fabrics for Defense Market