
 Europe Drone Services Market | 2026-2036
Europe Drone Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Drone Services Market Foresight
The gap between premium certified operators and commodity photography providers is expanding across European airspace. Cyberhawk Innovations Limited leverages its offshore energy specialization to command premium pricing for confined-space inspection. Parrot SA sustains dual-use technology development spanning defense and civilian mapping applications. Delair anchors its position in large-scale agricultural analytics through fixed-wing drone deployment.
Europe drone services encompass remotely piloted and autonomous aerial systems delivering data acquisition, physical transport, and situational awareness functions, typically operating at altitudes below 120 meters with payloads ranging from optical sensors to cargo containers. These systems serve commercial and public-sector clients requiring geospatial intelligence, infrastructure monitoring, or last-mile logistics without manned aviation costs. Inspection services lead current revenue generation due to mandatory asset-integrity programs in energy and utilities. VTOL configurations represent the fastest-growing technology segment as operators seek runway-independent deployment for emergency response and remote-site access. Agricultural end users constitute a maturing but margin-diluted pool where equipment-as-a-service models are displacing pure flight-hour billing.
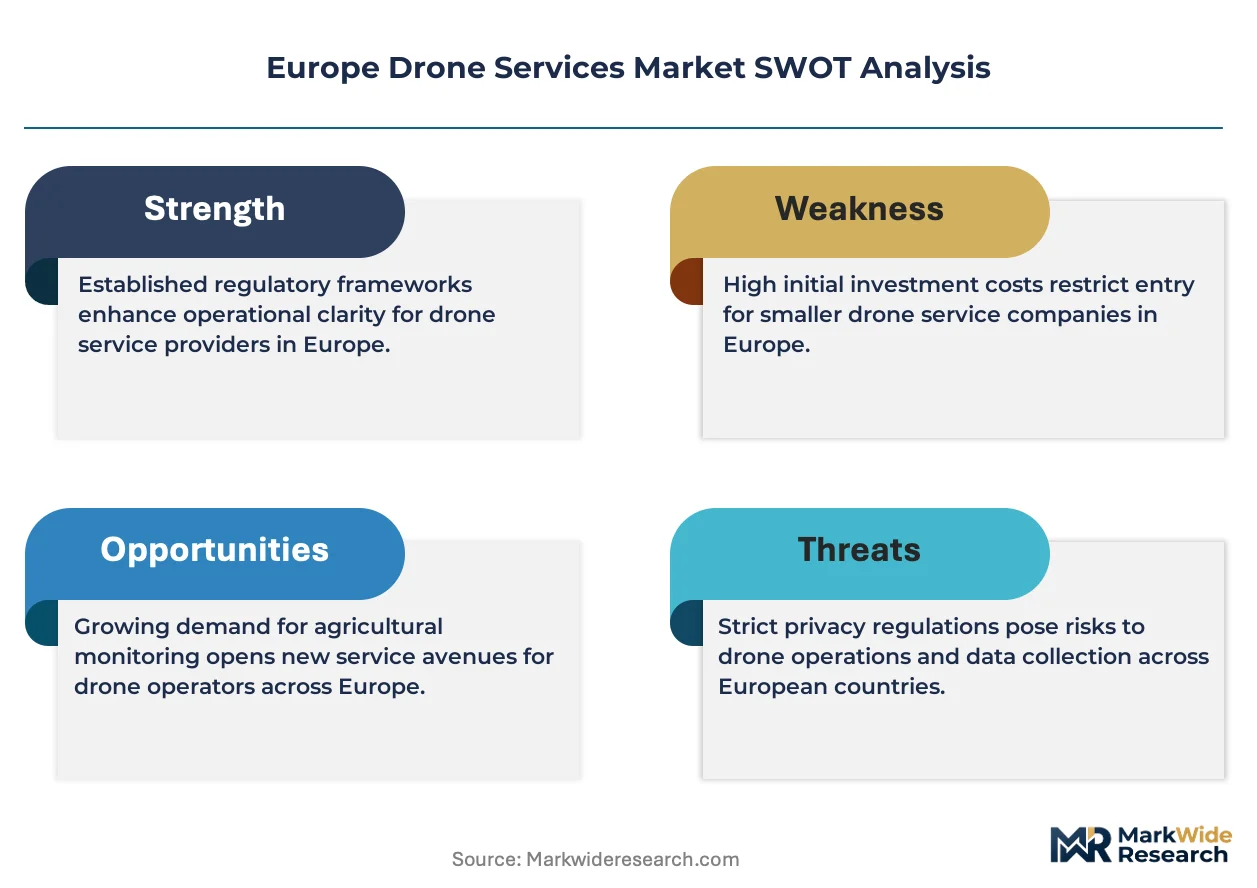
EASA's open and specific operational categories, supplemented by national BVLOS waivers from France's DGAC and Germany's LBA, shape competitive access across member states. The EU AI Act adds algorithmic accountability requirements for autonomous navigation systems, filtering which service providers can field fully automated fleets. Stakeholders must track regulatory divergence between EASA harmonization and member-state experimental corridors when allocating development resources.
Market Dynamics
EASA's specific-category certification requirements are fragmenting operator capabilities across member states, creating tiered competitive access where BVLOS authorization separates premium service providers from visual-line-of-sight-limited competitors.
Growth Catalysts
- EU AI Act compliance pathways:Algorithmic accountability frameworks for autonomous navigation systems are filtering qualified operators capable of fielding fully automated fleets, raising barriers for undercapitalized entrants.
- France DGAC corridor waivers:Designated experimental airspaces in agricultural regions accelerate precision farming fleet deployment under controlled risk parameters.
- Offshore wind installation:North Sea energy infrastructure mandates turbine blade inspection at scale, generating recurring revenue streams for certified maritime operators.
Market Restraints
- Lithium-polymer battery supply concentration:Cell production dependency on East Asian suppliers exposes European operators to input cost volatility and customs friction.
- Spectrum allocation delays:C-band and 5G-Aviation interference disputes between telecom regulators and aviation authorities stall beyond-visual-line-of-sight network infrastructure rollout.
- Manned aviation substitution:Helicopter operators in emergency medical services resist fleet replacement, preserving incumbent contracting relationships with public purchasers.
Strategic Opportunities
- Poland agricultural digitization:EU Common Agricultural Policy subsidy alignment creates funded entry points for equipment-as-a-service models in underpenetrated Central European farmland.
- Urban air mobility convergence:Passenger drone infrastructure trials in Germany and France create technology spillover for heavy-lift cargo applications.
- CSRD reporting mandates:Corporate sustainability disclosure requirements drive demand for emissions-monitoring aerial surveys across industrial facilities.
Industry Challenges
- Remote pilot licensing throughput:EASA theoretical examination capacity constraints create certification backlogs, limiting fleet expansion velocity for scaling operators.
- Legacy SCADA integration:Industrial asset owners require custom API development to feed drone-generated inspection data into existing maintenance management platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Drone Services Market |
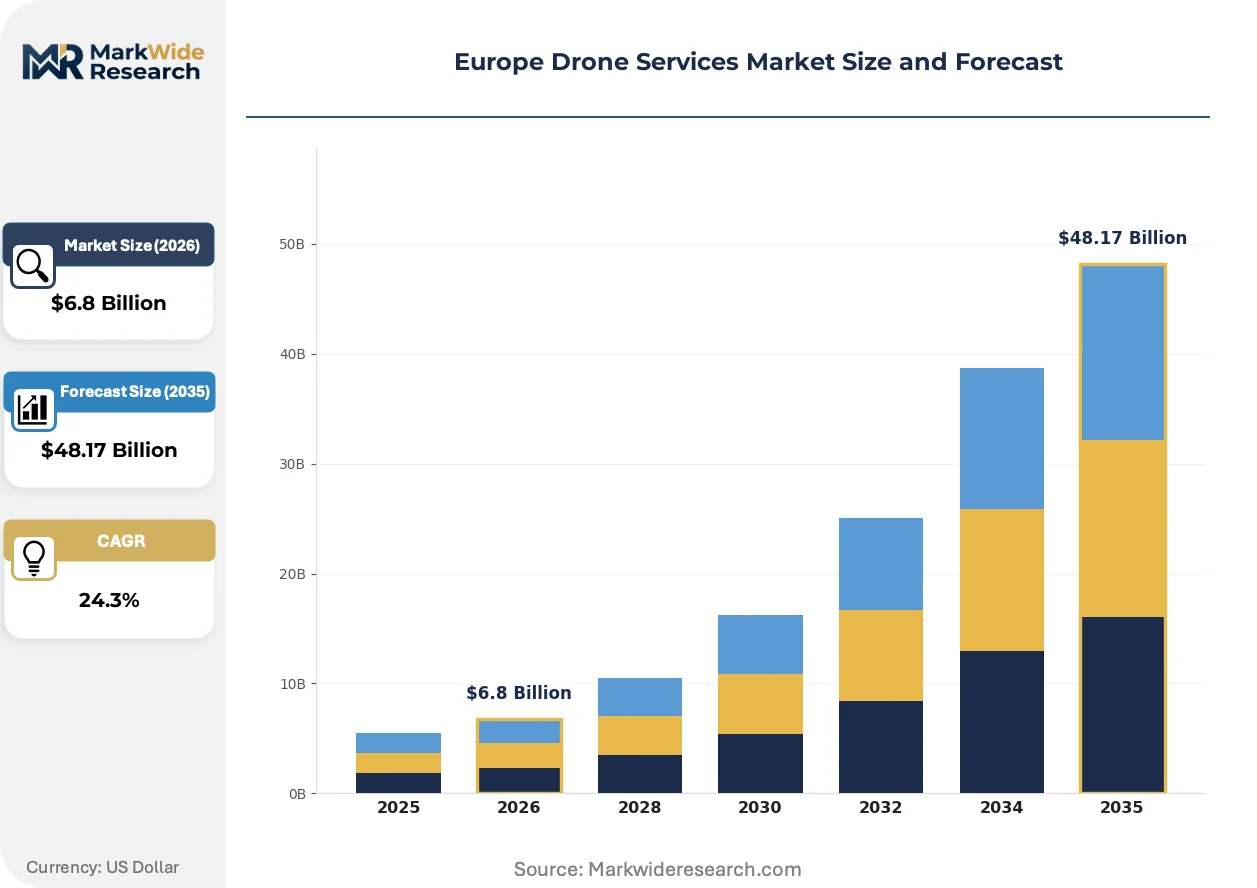
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $48.17 Billion |
| CAGR (2026 – 2036) | 24.3% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Aerial Photography, Surveying, Inspection, Delivery End User: Agriculture, Construction, Logistics, Defense Technology: Fixed-Wing, Quadrotor, Hexacopter, VTOL Application: Mapping, Monitoring, Emergency Response, Environmental Assessment |
| Companies Covered | Cyberhawk Innovations Limited, Sky Futures Partners Limited, DroneDeploy, Inc., Terra Drone Corporation, Aerodyne Group, Parrot SA, Delair, Quantum Systems, Flyability, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Drone Services Market Shifts & Advancements
Payload standardization and edge-computing architectures are compressing data-delivery timelines, while regulatory sandboxes in France and Germany accelerate operational-category migration for autonomous systems.
Swappable sensor payloads for multispectral imaging, thermal diagnostics, and gas detection are modularizing fleet economics. Agricultural cooperatives in the Netherlands adopt configurable gimbal systems to switch between crop-health and irrigation-infrastructure missions within single sorties. This modularity collapses capital requirements for multi-application service providers, enabling smaller operators to compete across verticals without dedicated airframe fleets.
EU AI Act algorithmic transparency requirements for autonomous navigation systems impose documentation burdens on machine-learning flight controllers. Drone service providers must maintain explainable decision logs for collision-avoidance algorithms, favoring rule-based systems over black-box neural networks in certification pathways. France's DGAC experimental corridors are testing compliant architectures ahead of 2025 enforcement deadlines.
Equipment-as-a-service contracts displace flight-hour billing in mature agricultural segments. French cereal cooperatives now lease sensor-equipped airframes with guaranteed data-delivery service levels, transferring obsolescence risk to operators. This preference shift compresses margins for pure-flight providers while rewarding vertically integrated hardware-software-service bundles in the Ile-de-France and Occitanie growing regions.
Europe Drone Services Market Segmentation
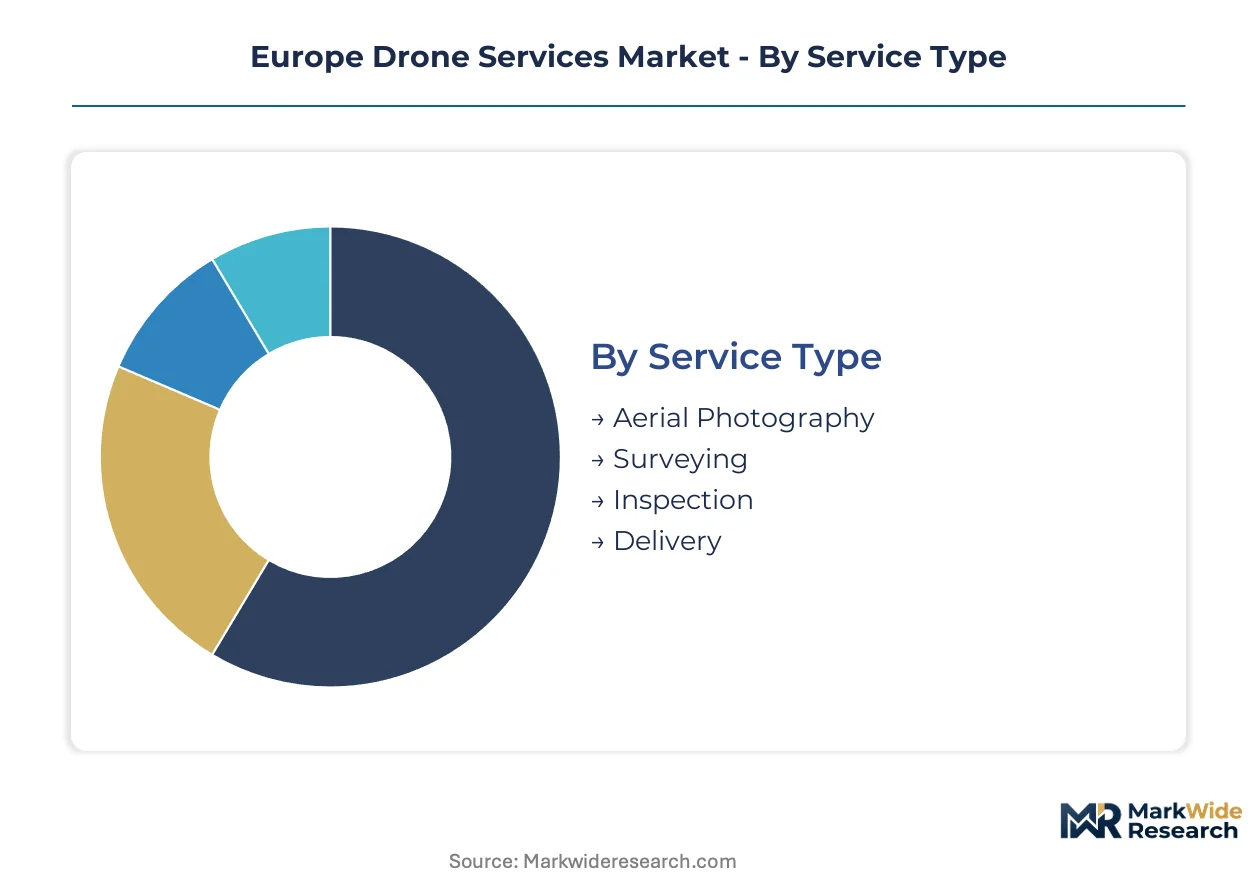
Service differentiation across the European drone market correlates directly with EASA operational-category certification requirements. Each segment carries distinct regulatory burdens that shape competitive entry costs and margin structures.
Service Type:
Inspection services demand EASA specific-category certification for BVLOS operations, while aerial photography operates under lighter open-category rules with geographic restrictions.
- Inspection:Confined-space diagnostics for offshore wind turbines and electrical transmission assets require EASA specific-category approval alongside national waivers from France's DGAC or Germany's LBA. North Sea energy operators mandate recurring blade assessments, generating contracted revenue streams for certified maritime specialists.
- Aerial Photography:Real estate and media capture functions under EASA open-category altitude and distance limits without mandatory pilot licensing beyond basic competency. French and Italian tourism boards concentrate seasonal demand, though margin compression intensifies from smartphone-camera substitution and entry-level operator saturation.
- Surveying:Geodetic-grade mapping demands RTK-GNSS integration and cadastral-registration compliance varying by member state.
- Delivery:Last-mile cargo trials in Germany and France face EU AI Act algorithmic accountability requirements for autonomous navigation.
Inspection sits at the top of the volume ranking, with Delivery climbing the fastest.
End User:
Customer procurement sophistication spans from subsidy-dependent agricultural cooperatives to defense ministries with classified-clearance requirements.
- Defense:Dual-use technology procurement under EU defense-funding instruments and national security classifications restricts vendor pools to cleared contractors. French and German military mapping programs drive demand for encrypted-data-chain systems with sovereign-cloud hosting requirements.
- Agriculture:French cereal cooperatives and Dutch horticulture collectives lease sensor-equipped fleets under equipment-as-a-service contracts with guaranteed data-delivery service levels. EU Common Agricultural Policy subsidy alignment funds precision-farming adoption, though equipment-as-a-service models displace pure flight-hour billing.
- Construction:German infrastructure megaprojects mandate drone-based progress monitoring for BIM integration.
- Logistics:E-commerce fulfillment trials in Poland and Spain concentrate urban air mobility corridor development.
Agriculture captures the largest installed base, while Defense shows the steepest expansion trajectory.
Technology:
Airframe selection determines runway dependency, payload capacity, and regulatory treatment under EASA noise and airworthiness directives.
- VTOL:Vertical-takeoff configurations eliminate runway requirements for emergency response and remote-site access, commanding premium deployment fees. France's DGAC experimental corridors accelerate operational-category migration for autonomous VTOL systems ahead of EU AI Act enforcement.
- Fixed-Wing:Extended endurance suits large-scale agricultural analytics and pipeline surveillance across Occitanie and Lower Saxony farmland. Delair anchors market position through fixed-wing deployment for cooperative-scale coverage.
- Quadrotor:Maneuverability dominates urban inspection and confined-space applications with shorter range limits.
- Hexacopter:Redundant rotor architectures appeal to heavy-lift cargo trials and cinematic production requiring payload stability.
Fixed-Wing maintains volume leadership in flight-hours, with VTOL gaining share fastest among new fleet acquisitions.
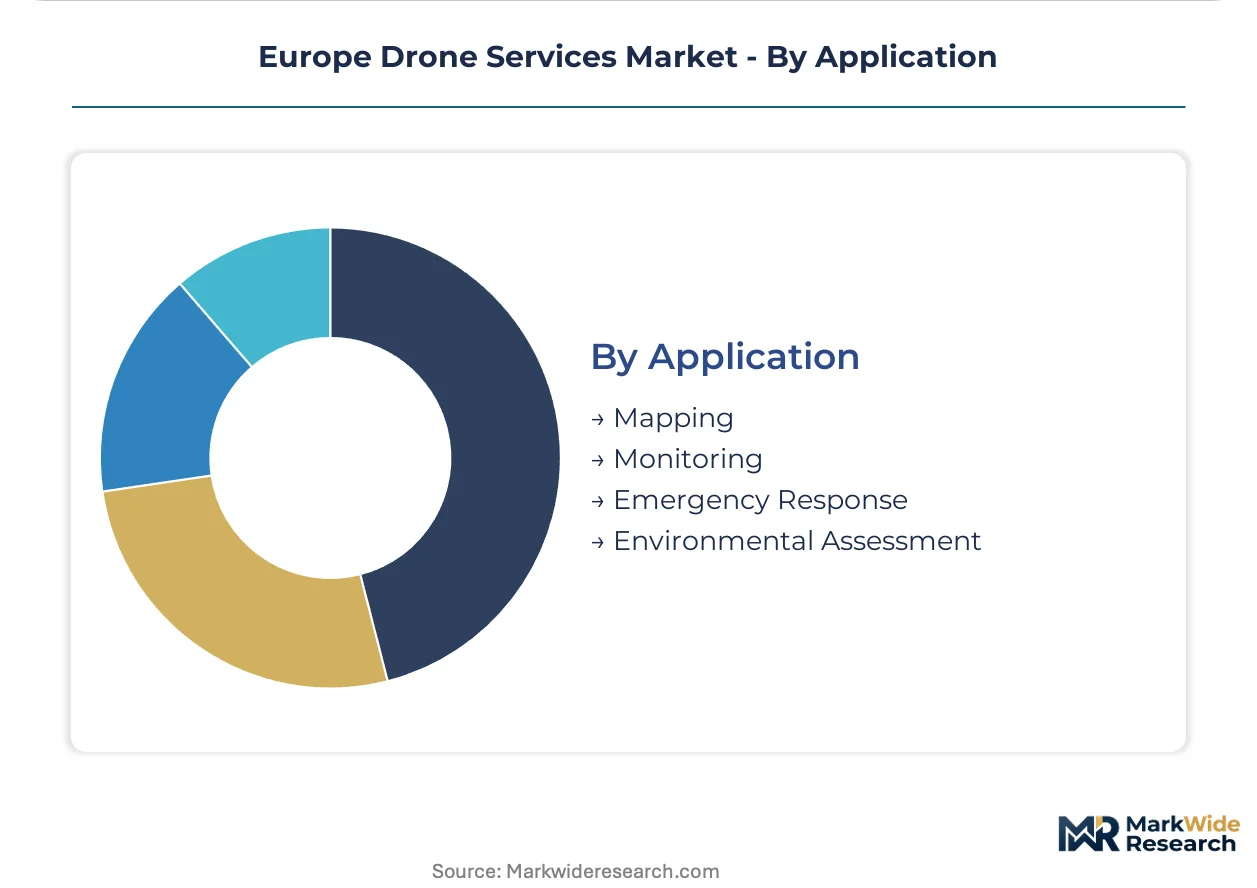
Application:
Use-case maturity varies from standardized mapping deliverables to emergent environmental-liability assessments under CSRD disclosure mandates.
- Monitoring:Continuous asset surveillance for utilities and renewable energy generates recurring subscription revenue with embedded sensor-maintenance contracts. German grid operators mandate thermal-inspection protocols for transformer stations and photovoltaic arrays.
- Mapping:Photogrammetric and LiDAR deliverables for cadastral updating and engineering design represent the most standardized service tier with compressed pricing. French IGN partnerships establish baseline demand for national topographic refresh cycles.
- Emergency Response:Search-and-rescue and wildfire coordination require real-time data links and priority airspace access negotiated with national aviation authorities.
- Environmental Assessment:CSRD reporting mandates drive emissions-monitoring aerial surveys across industrial facilities in the Ruhr and Antwerp port complexes.
Mapping holds the deepest penetration across member states, with Environmental Assessment expanding most quickly under sustainability disclosure requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Licensed remote pilots concentrate in France, Germany, and the United Kingdom, creating regulatory expertise clusters that shape service provider density across member states. EASA harmonization overlays national waiver regimes that fragment operational access. Member states with active experimental corridors pull fleet deployment decisions.
Germany
Industrial inspection demand from Ruhr manufacturing clusters and North Sea offshore wind drives BVLOS certification urgency. Germany's LBA issues specific-category approvals for maritime turbine specialists. Hamburg and Bremerhaven harbor zones concentrate maritime drone operators serving energy infrastructure.
France
Precision agriculture cooperatives in Île-de-France and Occitanie scale multispectral fleet deployment under subsidized equipment-as-a-service contracts. France's DGAC designates experimental airspace corridors accelerating autonomous navigation trials. Toulouse and Bordeaux agricultural technology clusters host fixed-wing analytics providers.
United Kingdom
Offshore energy inspection contracts from North Sea oil and wind assets generate premium revenue for certified maritime operators. The UK Civil Aviation Authority maintains post-Brexit alignment with EASA open and specific categories. Aberdeen and Great Yarmouth harbor infrastructure supports turbine blade assessment sorties.
Netherlands
Horticulture collectives in Randstad and Brabant adopt configurable payload systems switching between crop-health and irrigation missions. Dutch human-centric AI guidelines supplement EU AI Act requirements for autonomous flight controllers. Wageningen agricultural research corridors test compliant algorithmic architectures.
Poland
EU Common Agricultural Policy subsidy alignment funds equipment-as-a-service entry in underpenetrated Central European farmland. Poland's civil aviation authority adapts EASA frameworks with simplified registration for agricultural cooperatives. Greater Warsaw and Lower Silesia logistics corridors trial urban air mobility for e-commerce fulfillment.
Europe Drone Services Market Competitive Landscape
Top-tier vendors anchor EASA specific-category certification, while open-category photography providers compete on price and geographic coverage. The vendor base stratifies across BVLOS-authorized specialists, dual-use defense contractors, and software-integrated analytics platforms. Three archetypes dominate: offshore energy inspectors with maritime waivers, agricultural fleet operators with hardware-service bundles, and autonomous navigation developers with AI Act compliance pathways. Competitive moves concentrate on strategic partnerships for sensor integration and geographic expansion through national waiver acquisition.
Among inspection specialists, Cyberhawk Innovations Limited and Sky Futures Partners Limited occupy positions within the offshore energy tier, exemplifying premium-service archetypes built around confined-space certification. Parrot SA and Delair anchor dual-use and agricultural analytics segments respectively, representing European-headquartered players with hardware-software integration strategies. These named entities illustrate how certification depth and vertical application focus separate pricing power across the competitive map.
| Leading Market Players |
|---|
| Cyberhawk Innovations Limited |
| Sky Futures Partners Limited |
| DroneDeploy, Inc. |
| Terra Drone Corporation |
| Aerodyne Group |
| Parrot SA |
| Delair |
| Quantum Systems |
| Flyability |
| Others |
Supply & Pricing Matrix
Lithium-polymer cell costs from East Asian suppliers cascade through three distinct service tiers, with BVLOS-certified operators capturing premium positioning while open-category photography providers absorb commodity pressure from smartphone substitution and entry-level saturation.
Pricing Analysis
Bundled hardware-software-service contracts now dominate agricultural segments, displacing unbundled flight-hour billing as French cereal cooperatives lease sensor-equipped airframes with guaranteed data-delivery service levels. Three-tier pricing structure across premium, standard, and economy levels separates EASA specific-category BVLOS operators from visual-line-of-sight-limited competitors and basic photography providers. Pricing pressure stems from equipment-as-a-service margin compression in mature agricultural regions. Agricultural cooperatives exhibit highest price sensitivity, while offshore energy operators demonstrate lowest sensitivity due to mandatory asset-integrity program requirements.
Supply Chain Analysis
Certification gating under EASA's specific-category framework fragments supplier pools, with BVLOS-authorized component vendors commanding preferential procurement relationships from scaling fleet operators. Lithium-polymer cell production concentrates in China, South Korea, and Japan, while carbon-fiber airframe manufacturing centers on Germany and France. Critical dependencies include GNSS modules, thermal imaging sensors, and edge-computing processors. Single-source vulnerability in solid-state battery development exposes European operators to technology transition risk. Distribution runs through authorized service centers and direct OEM partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's drone services market has entered a late-cycle quality phase where procurement shifts toward EASA specific-category certification and EU AI Act compliance favor operators with documented algorithmic transparency and sovereign-cloud hosting capabilities.
For Market Incumbents: Lock in maritime BVLOS waivers through Germany's LBA and France's DGAC corridor acquisitions, insulating recurring revenue from offshore wind inspection mandates. Deepen backward integration into sensor payload manufacturing to control modular gimbal supply for agricultural multispectral contracts. Counter emerging equipment-as-a-service entrants by embedding obsolescence guarantees into long-term turbine blade assessment agreements. For New Entrants and Emerging Players: Launch via Poland's EU Common Agricultural Policy subsidy alignment, targeting underpenetrated Central European farmland with simplified registration pathways. Exploit white-space in CSRD-mandated emissions-monitoring aerial surveys across Ruhr and Antwerp industrial complexes. Prioritize urban air mobility corridor trials in Greater Warsaw and Lower Silesia logistics networks over saturated Western European photography markets. For Investors and Strategic Acquirers: Consolidation pressure builds where EASA examination backlogs constrain fleet expansion velocity for scaling operators. Frame five-to-ten-year viability around algorithmic accountability compliance rather than hardware commoditization. Target acquisition profiles emphasizing DGAC experimental corridor access and dual-use defense clearance pathways. Monitor France's AI Act enforcement deadline as inflection signal for autonomous navigation valuation premiums.| Strategic Initiative | Industry Significance |
|---|---|
| BVLOS Certification Acquisition | Germany's LBA maritime waivers unlock recurring North Sea turbine inspection revenue streams. |
| Sensor Payload Modularization | Swappable gimbal systems collapse capital requirements for multi-vertical service providers. |
| EU AI Act Compliance Pathway | Explainable algorithm documentation filters qualified autonomous fleet operators from black-box competitors. |
| Equipment-as-a-Service Transition | Guaranteed data-delivery contracts transfer obsolescence risk while compressing pure-flight margins. |
| Experimental Corridor Expansion | France's DGAC designated airspaces accelerate operational-category migration ahead of enforcement deadlines. |
Research Methodology
Direct dialogue with fleet operations directors, EASA certification consultants, agricultural cooperative procurement managers, and offshore energy asset integrity engineers grounded qualitative findings in operational reality. Secondary validation drew from EASA regulatory filings, DGAC corridor designations, LBA specific-category approvals, EU AI Act implementation guidance, and national aviation authority waiver databases. Bottom-up service provider capacity estimates triangulated against top-down end-user demand segmentation across member states.
Segmented outputs spanning service type, end user, technology configuration, and application use-case fed into analytical frameworks calibrated across the projection horizon. CAGRs derived from regression analysis against certified pilot throughput, BVLOS waiver issuance rates, and subsidy program enrollment trajectories. Forecast inputs incorporated lithium-polymer supply contract pricing, 5G-aviation spectrum allocation timelines, and CSRD disclosure mandate adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EASA regulatory divergence scenarios or East Asian battery supply disruptions. Model outputs reflect documented assumptions regarding certification backlog resolution and AI Act enforcement uniformity. A model refresh is warranted upon material change in DGAC experimental corridor expansion velocity or LBA maritime waiver processing capacity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Global Multirotor UAV Market
UAV
Electric Glider Market
UAV
North America Tactical UAV Market
UAV
Military Unmanned Aerial Vehicles Market
UAV
North America Small UAV Market
UAV
Drone Wireless Charging Station Market
UAV
Global Drone Analytics Market
UAV
Global Drone Services Market
UAV
North America Drone Software Market
UAV
Multirotor Drones Market
UAV
Global Target Drone Market
UAV
Drone Powered Business Solutions Market
UAV
North America Drone Services Market
UAV
Counter-UAS Market
UAV
Europe Commercial Drones Market
UAV
Drone Lens Market