
 North America Drone Services Market | 2026-2036
North America Drone Services Market Size, Share, and Industry Trends Forecast 2026-2036
North America Drone Services Market Analytics
FAA Part 107 remote pilot certification is collapsing the barrier between hobbyist operators and commercial service providers. Skydio, Inc. leverages autonomous flight stacks to dominate infrastructure inspection contracts across California and Texas. PrecisionHawk, Inc. anchors its position through specialized agricultural analytics that integrate multispectral imaging with variable-rate prescription maps.
Drone services encompass the commercial deployment of unmanned aerial systems to capture geospatial data, transport payloads, or execute remote sensing missions, typically operating at altitudes below 400 feet with payloads ranging from sub-kilogram sensors to multi-kilogram medical supplies. These platforms serve industrial clients seeking to reduce labor exposure in hazardous environments while accelerating data collection cycles. Aerial photography and surveillance command the largest revenue pools today, while package delivery represents the fastest-expanding service type as logistics operators trial autonomous last-mile fulfillment. Rotary-wing configurations lead technology adoption for their vertical takeoff precision in confined sites, though hybrid platforms are gaining traction for extended-range corridor missions.
The FAA governs airspace access through Part 107 and emerging beyond-visual-line-of-sight frameworks, while Transport Canada and Mexico's DGAC set parallel standards that shape cross-border operational compliance. NHTSA coordination on low-altitude traffic management and OSHA alignment for workplace drone deployment further constrain how service providers structure crew training and liability protocols. Stakeholders must monitor which regulator moves first on unified detect-and-avoid standards, as that jurisdiction will likely export its compliance template across North American operations.
Market Dynamics
The North America Drone Services Market is compressing around FAA Part 107 certification density and beyond-visual-line-of-sight rulemaking, as operators with compliant fleets capture multi-year infrastructure contracts while hobbyist entrants face escalating insurance and training costs.
Growth Catalysts
- Beyond-Visual-Line-of-Sight frameworks:The FAA's evolving BVLOS rules enable corridor inspections across Texas energy infrastructure and California utility networks, unlocking flight paths previously restricted to manned aviation.
- Variable-rate prescription mapping:Midwest agricultural operators deploy multispectral imaging to generate fertilizer and irrigation prescriptions, converting raw drone data into farm-management software inputs that lock in recurring service contracts.
- Medical supply logistics trials:Healthcare systems in North Carolina and Arizona test autonomous last-mile delivery for blood products and pharmaceuticals, creating demand for temperature-controlled payload systems and specialized pilot networks.
Market Restraints
- Lithium-polymer battery cost volatility:Energy-dense cell prices fluctuate with cobalt and nickel spot markets, compressing margins on rotary-wing platforms that require frequent battery replacement cycles.
- Detect-and-avoid standard fragmentation:Transport Canada, the FAA, and Mexico's DGAC maintain non-interoperable technical specifications, forcing operators to maintain separate equipment stacks for cross-border corridor missions.
- Manned aviation substitution:Helicopter services retain cost advantages for heavy-lift external cargo and emergency medical evacuation, capping drone penetration in payload classes above five kilograms.
Strategic Opportunities
- Mexican energy corridor expansion:Pemex pipeline networks and Yucatan Peninsula renewable installations lack mature inspection infrastructure, creating first-mover positioning for Part 107-certified operators extending southward.
- OSHA-aligned workplace safety mandates:Industrial facilities in Louisiana petrochemical clusters face intensified confined-space entry restrictions, accelerating substitution of drone-based tank and flare stack inspections for human rope-access teams.
- 5G network edge computing convergence:Real-time video analytics processing shifts from onboard GPUs to cellular base stations, enabling lighter airframes and extending flight endurance for persistent surveillance missions.
Industry Challenges
- Remote pilot certification throughput:FAA Part 107 testing center capacity constraints create six-to-eight-week backlogs, delaying fleet expansion timelines for operators bidding on seasonal agricultural contracts.
- Legacy SCADA integration complexity:Industrial clients in the Permian Basin require drone sensor outputs to feed directly into decades-old distributed control systems, demanding custom middleware development that extends deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Drone Services Market |
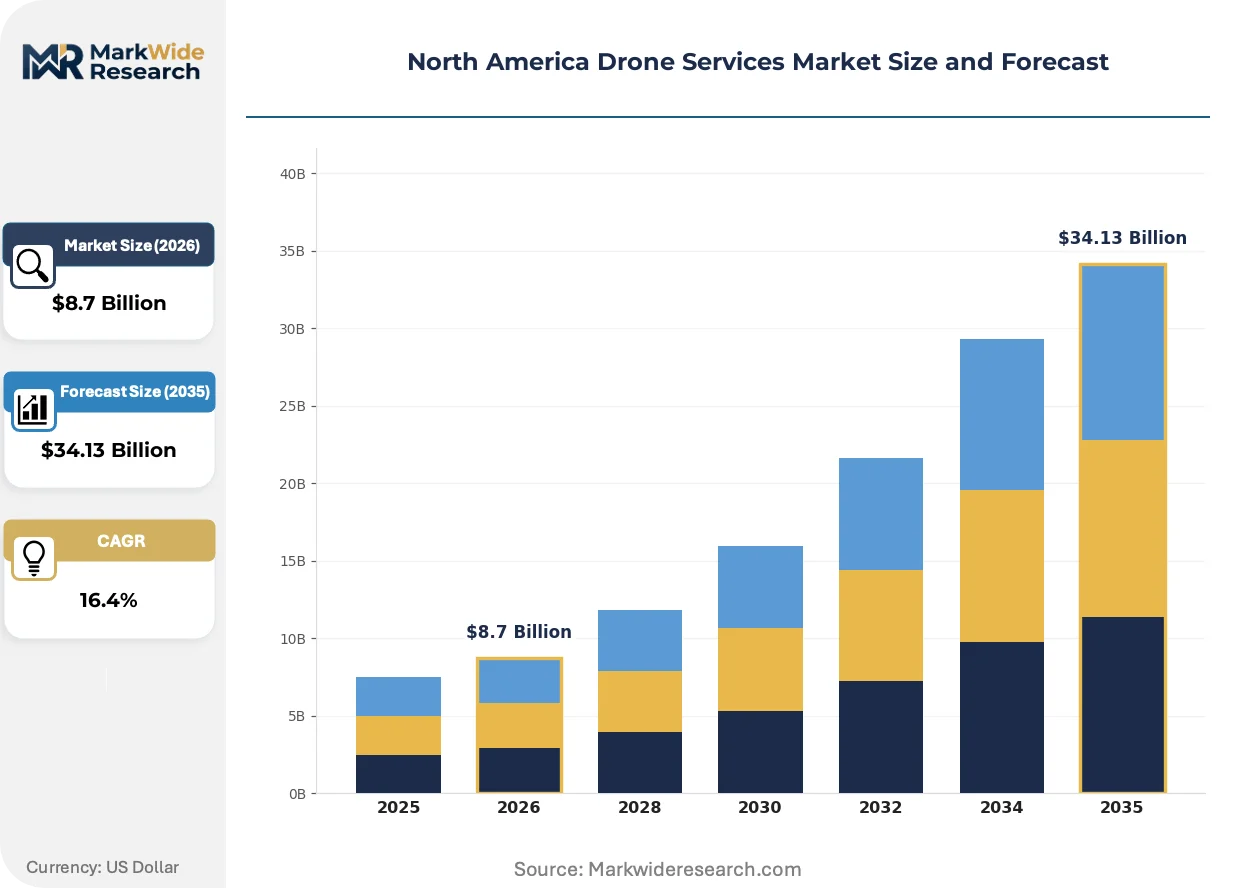
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Aerial Photography, Package Delivery, Surveillance, Agricultural Monitoring Technology: Fixed-Wing, Rotary-Wing, Hybrid, FPV End User: Construction, Agriculture, Entertainment, Emergency Services Application: Mapping, Inspection, Surveying, Disaster Management |
| Companies Covered | DroneDeploy, Inc., Skydio, Inc., PrecisionHawk, Inc., Cyberhawk Innovations Limited, Zipline International Inc., AgEagle Aerial Systems Inc., Aerodyne Group, Wing Aviation LLC, Phoenix Drone Services LLC, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Drone Services Market Evolving Landscape
Autonomous flight stacks and edge-computing architectures are redrawing competitive boundaries in drone services, compressing the advantage of scale operators while elevating software-native entrants. Three forces dominate current investment and contract allocation.
Artificial intelligence-based navigation systems enable collision avoidance without human remote-pilot intervention. Oil and gas majors in the Gulf Coast region deploy these systems for offshore platform inspection where satellite latency disrupts manual control. The technology is decomposing the traditional pilot-to-aircraft ratio, allowing single operators to supervise multiple simultaneous missions and collapsing labor costs per flight hour.
The FAA's forthcoming Remote ID mandate requires continuous broadcast of position, altitude, and control station location for most unmanned aircraft. Commercial operators in urban air mobility corridors must retrofit existing fleets or ground non-compliant hardware. Package delivery trials in Dallas-Fort Worth and Phoenix accelerate compliance investments, as logistics providers position for 2025-2026 operational scale.
Energy sector buyers now unbundle data capture from analytics interpretation, contracting flight hours to lowest-cost providers while retaining specialized firms for thermal anomaly detection and predictive maintenance modeling. This bifurcation concentrates margin in software layers and fragments hardware operators into commodity positioning. The pattern is most visible in California solar farm inspections, where asset owners maintain direct relationships with analytics platforms and treat drone services as interchangeable inputs.
North America Drone Services Market Segmentation
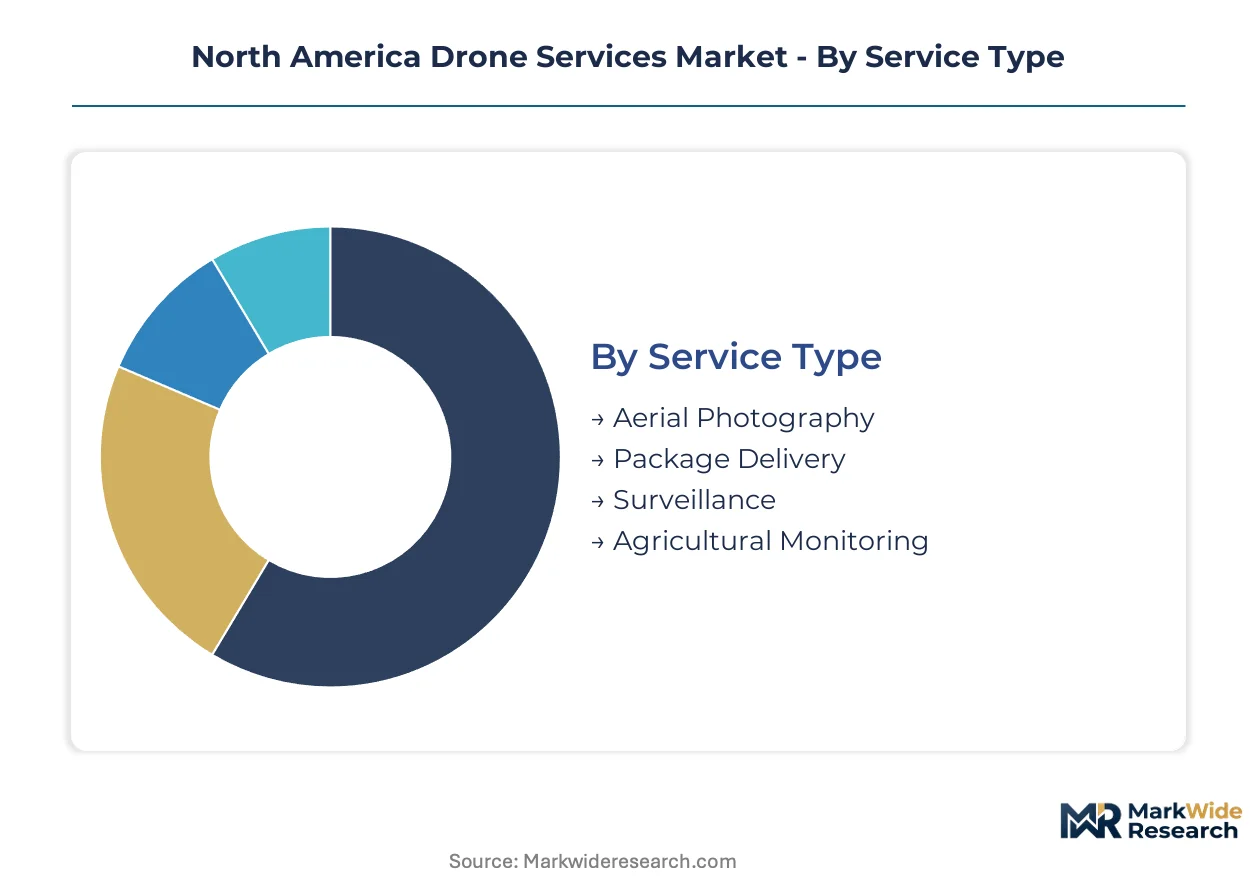
Service differentiation in North American drone operations hinges on payload capacity, endurance architecture, and regulatory clearance tiers. Segmentation reveals which configurations capture infrastructure contracts versus commodity photography work.
Service Type:
Aerial photography dominates domestic revenue pools across Texas real estate corridors and California film production zones. Package delivery trials concentrate in Dallas-Fort Worth and Phoenix logistics hubs under FAA waiver programs.
- Aerial Photography:High-resolution imaging services for real estate marketing, film production, and insurance documentation. Demand clusters in California entertainment districts and Texas property development corridors where visual asset libraries command recurring licensing fees.
- Package Delivery:Autonomous last-mile fulfillment for medical supplies and retail goods. Healthcare systems in North Carolina and Arizona pilot temperature-controlled blood product transport, creating specialized pilot network requirements and cold-chain payload certification.
- Surveillance:Persistent monitoring for border security and private facility protection.
- Agricultural Monitoring:Multispectral crop health assessment generating variable-rate prescription maps for Midwest fertilizer and irrigation decisions.
Aerial photography commands the established base. The steepest expansion runs through package delivery.
Technology:
Platform selection tracks mission endurance requirements and site access constraints. Cost tiers separate enterprise-grade hybrid systems from entry-level rotary units.
- Fixed-Wing:Extended-range platforms with efficient cruise aerodynamics for corridor mapping and pipeline inspection. Energy sector buyers in the Permian Basin deploy these for hundreds of linear miles per sortie, though runway or catapult launch requirements limit confined-site utility.
- Rotary-Wing:Vertical takeoff precision dominates infrastructure inspection contracts where obstacle-rich environments preclude fixed-wing approaches. Skydio autonomous stacks and DJI enterprise platforms anchor this tier through FAA Part 107-certified operator networks.
- Hybrid:VTOL transition systems combining rotary launch with fixed-wing cruise efficiency.
- FPV:First-person-view racing-style platforms for entertainment and specialized close-proximity inspection.
Rotary-wing systems anchor current fleet deployment. Hybrid platforms are climbing the fastest as BVLOS corridor rules mature.
End User:
Customer type determines contract duration and data integration depth. Agricultural buyers lock in seasonal recurring revenue while emergency services demand on-call surge capacity.
- Construction:Progress monitoring and earthwork volumetrics for large-scale development. California highway contractors and Texas residential builders deploy weekly flight schedules to document milestone completion and dispute resolution archives.
- Agriculture:Precision crop management through multispectral index mapping. Midwest operators in Iowa and Illinois convert NDVI outputs into farm-management software prescriptions, embedding drone services within annual input procurement cycles.
- Entertainment:Dynamic cinematography and live event coverage.
- Emergency Services:Search-and-rescue and post-disaster damage assessment.
Construction commands the established base. Agriculture shows the steepest expansion trajectory through prescription map integration.
Application:
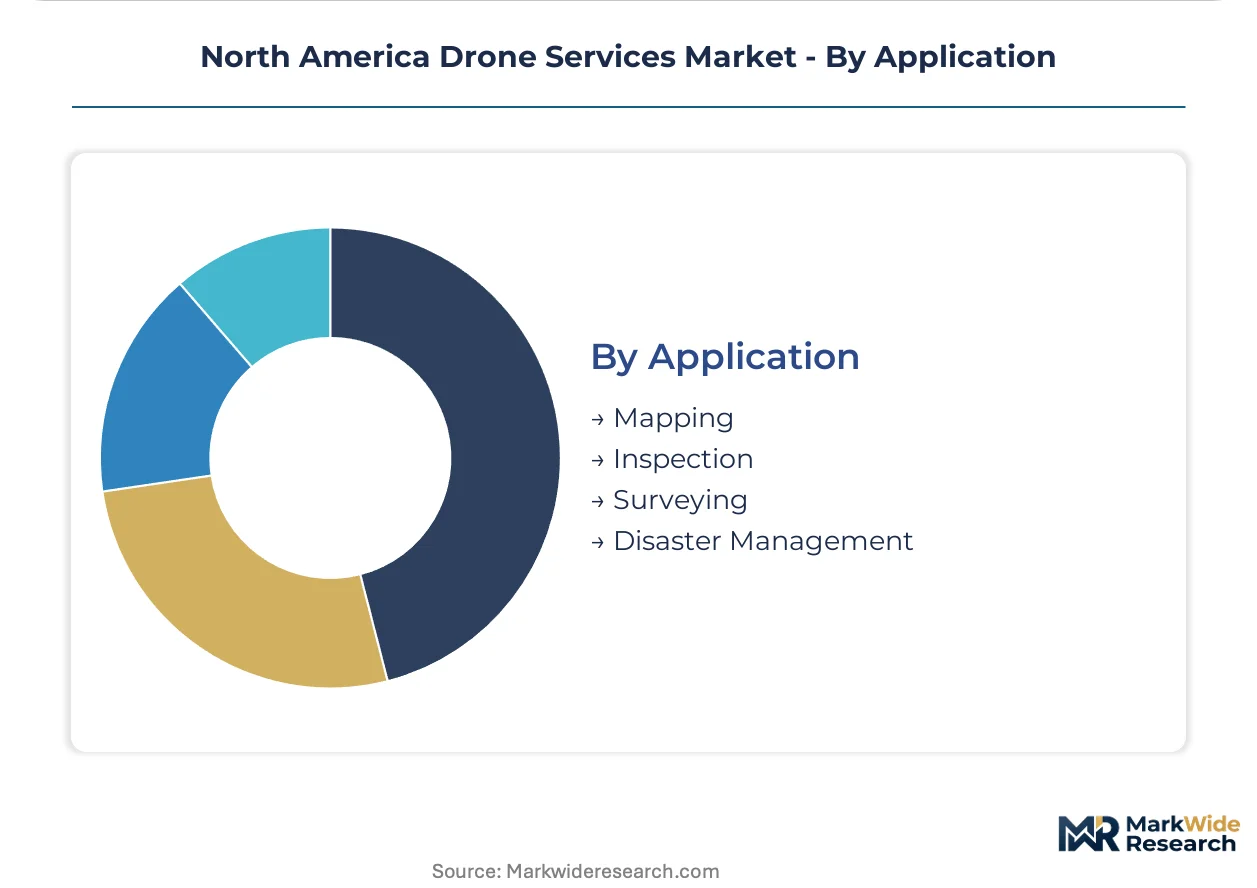
Use-case maturity separates standardized deliverables from custom analytics engagements. Volume concentration sits in repeatable inspection workflows.
- Mapping:Topographic survey and orthomosaic generation for engineering design. Surveyors in Colorado and British Columbia resource extraction zones rely on drone photogrammetry to replace ground crew exposure in steep terrain.
- Inspection:Asset condition assessment for energy and utility infrastructure. Gulf Coast offshore platforms and California solar farms unbundle flight services from thermal anomaly analytics, compressing hardware operator margins while elevating specialized interpretation layers.
- Surveying:Cadastral boundary and construction staking services.
- Disaster Management:Rapid damage documentation and supply chain restoration.
Inspection commands the established base. Mapping gains share fastest as survey-grade GPS and RTK correction networks expand coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Energy infrastructure buyers dominate procurement across the continent, with agricultural operators and logistics providers forming secondary demand clusters. FAA Part 107 certification density determines operator viability in each jurisdiction. Cross-border corridor missions face regulatory friction between national aviation authorities.
United States
Texas energy corridor inspections and California utility networks drive enterprise fleet deployment. FAA beyond-visual-line-of-sight rulemaking unlocks multi-mile pipeline missions previously restricted to manned helicopters. Dallas-Fort Worth logistics trials and Phoenix healthcare delivery pilots concentrate demand for autonomous payload systems.
Canada
British Columbia mining surveyors and Alberta oil sands operators deploy extended-range platforms for terrain mapping. Transport Canada RPAS regulations mandate visual-line-of-sight compliance for most commercial operations, compressing contract scope relative to US counterparts. Toronto-area infrastructure inspection firms leverage proximity to US border zones for cross-border service extension.
Mexico
Pemex pipeline networks and Yucatan Peninsula renewable installations lack mature inspection infrastructure. DGAC operational specifications diverge from FAA standards, forcing equipment stack duplication for north-south corridor missions. Northern border states attract first-mover positioning from Part 107-certified operators extending service southward.
North America Drone Services Market Competitive Landscape
Player mix skews toward software-native autonomous stack providers and specialized agricultural analytics firms. Market structure concentrates around FAA certification density, with compliant operators capturing multi-year infrastructure contracts while uncertified entrants face escalating insurance and training barriers. Two strategic archetypes dominate: autonomous flight stack developers and prescription mapping specialists. Competitive moves center on BVLOS regulatory positioning and farm-management software integration partnerships.
Within the autonomous infrastructure tier, Skydio, Inc. and DroneDeploy, Inc. exemplify the flight-stack-to-analytics convergence. PrecisionHawk, Inc. anchors the agricultural specialization vector. These three occupy positions that straddle hardware deployment and software layer capture, reflecting the broader industry bifurcation between commodity flight services and margin-retaining analytics interpretation.
| Leading Market Players |
|---|
| DroneDeploy, Inc. |
| Skydio, Inc. |
| PrecisionHawk, Inc. |
| Cyberhawk Innovations Limited |
| Zipline International Inc. |
| AgEagle Aerial Systems Inc. |
| Aerodyne Group |
| Wing Aviation LLC |
| Phoenix Drone Services LLC |
| Others |
Value Network & Pricing Analysis
FAA Part 107 certification density gates both supplier qualification and price differentiation simultaneously. Operators holding compliant fleets command premium positioning for multi-year infrastructure contracts while uncertified entrants face escalating insurance and training barriers that compress their pricing power. The resulting bifurcation concentrates margin in certified operator networks and fragments commodity photography providers into price-takers.
Pricing Analysis
Cost-plus contracts with cobalt and nickel spot market indexation dominate rotary-wing platform procurement. Three-tier pricing structure across premium, standard, and economy levels separates BVLOS-certified operators from visual-line-of-sight providers and hobbyist entrants. Pricing pressure stems from lithium-polymer battery cost volatility compressing hardware operator margins. Agricultural buyers in the Midwest exhibit highest price sensitivity due to seasonal contract concentration, while Gulf Coast energy majors demonstrate lowest sensitivity given hazard-pay substitution economics.
Supply Chain Analysis
China and South Korea anchor lithium-ion cell manufacturing for drone power systems. Taiwan feeds semiconductor components for flight control systems. The supply chain draws from cobalt extraction in the Democratic Republic of Congo and nickel refining in Indonesia. Single-source vulnerability concentrates in advanced battery management integrated circuits. Distribution runs through OEM direct channels for enterprise fleets and authorized dealer networks for commercial operator procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection as the FAA's Remote ID mandate forces interoperability investments that will reshape ecosystem control. The unbundling of flight services from analytics interpretation accelerates winner-take-most dynamics in software layers.
For Market Incumbents: Fortify autonomous flight stack differentiation against commodity hardware erosion. Skydio-type autonomous navigation capabilities must deepen to maintain pilot-to-aircraft ratio advantages. Invest in farm-management software API partnerships to lock agricultural customers into prescription map workflows that resist price competition.
For New Entrants and Emerging Players: FAA Part 107 fast-track certification programs unlock immediate contract eligibility. Mexican energy corridor inspection presents the most penetrable geography given Pemex infrastructure gaps and DGAC regulatory arbitrage opportunities. Lead with temperature-controlled payload specialization for North Carolina and Arizona healthcare delivery trials.
For Investors and Strategic Acquirers: Beyond-visual-line-of-sight rule finalization reshapes the acquisition landscape toward compliant fleet operators. Long-term viability centers on software-native analytics platforms rather than hardware-deploying service providers. Target acquisition archetypes combine prescription mapping engines with existing Part 107 operator networks. Monitor FAA detect-and-avoid standard harmonization with Transport Canada as the signal for cross-border scale economics.
| Strategic Initiative | Industry Significance |
|---|---|
| BVLOS Regulatory Certification | FAA waiver acquisition unlocks multi-mile corridor contracts previously restricted to manned aviation. |
| Farm-Management Software Integration | API partnerships with John Deere Operations Center embed drone services within annual input procurement cycles. |
| Autonomous Flight Stack Development | Collision-avoidance AI reduces pilot labor costs per flight hour in offshore platform inspections. |
| Mexican Market Expansion | DGAC compliance investment captures Pemex pipeline inspection demand lacking mature local operators. |
| Remote ID Fleet Retrofit | Broadcast module deployment positions operators for 2025-2026 urban air mobility scale trials. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews. Stakeholder roles included FAA Part 107 certified remote pilots, agricultural cooperative procurement managers, energy sector inspection coordinators, drone fleet operations directors, and insurance underwriters specializing in unmanned aviation liability. Secondary validation drew from FAA regulatory filings, Transport Canada RPAS advisories, SEC 10-K disclosures of publicly traded drone manufacturers, and EIA energy infrastructure databases. Bottom-up service provider revenue aggregation triangulated against top-down end-user procurement survey data.
Across the analysis window, volume and value outputs reflect segmentation modeling across service type, platform technology, end-user industry, and application use-case. CAGRs were derived from historical fleet deployment trajectories and regulatory milestone probability weighting. Forecast inputs incorporated FAA rulemaking timelines, lithium cell price elasticity coefficients, and agricultural input spending correlation patterns.
Decision-makers should treat outputs as directional under base assumptions of steady FAA regulatory progression and stable cobalt-nickel commodity ranges; material deviation would warrant model refresh. Specific risks include detect-and-avoid standard fragmentation prolonging cross-border operational constraints and battery chemistry disruptions altering platform economics. Recalibration cycles align with material shifts in FAA rulemaking pace and energy sector capital expenditure cycles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Military UAV Sensor Market
UAV
Solar Powered Drones Market
UAV
Drone Payload Market
UAV
Combat Drone Market
UAV
Drone Inspection Service Market
UAV
Small Drone Market
UAV
Drone Lens Market
UAV
Asia-Pacific Drone Light Shows Market
UAV
UAV Payload and Subsystems Market
UAV
Global Target Drone Market
UAV
Tactical UAV Market
UAV
Global Aerial Imaging Market
UAV
Global Electric Drone Market
UAV
GCC Drone Pilot Training Market
UAV
Bubble Drone Market
UAV
Global Drone Services Market