
 Advanced Digital Gaming Market | 2026-2036
Advanced Digital Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Digital Gaming Market Analysis
The gap between proprietary console architectures and cloud-native rendering pipelines is narrowing, forcing incumbents to retool their technology stacks. Sony Corporation leverages its semiconductor fabrication partnerships to sustain vertical control over custom SoC supply. Microsoft Corporation anchors its competitive position through backward integration into Azure cloud infrastructure for game streaming delivery. NVIDIA Corporation specializes in GPU virtualization technologies that dominate data center rendering workloads for cloud gaming services.
Advanced digital gaming encompasses interactive software environments rendered in real-time across distributed compute architectures, typically requiring sub-50 millisecond latency thresholds for competitive multiplayer synchronization and employing procedural content generation to scale asset libraries without linear production cost expansion. The primary commercial purpose is to monetize sustained user engagement through recurring revenue mechanics rather than one-time unit sales. Mobile platforms under the platform type dimension capture the largest addressable user base but face compressed average revenue per user, while cloud gaming represents the fastest-expanding segment as telecommunications infrastructure upgrades reduce latency barriers in emerging markets. The monetization model dimension shows free-to-play mechanics with in-game purchase layers now generating the dominant share of industry margin pools, displacing traditional pay-to-play unit economics across all major platform types.
The Federal Communications Commission in the United States shapes broadband quality benchmarks that directly determine cloud gaming service viability, while the European Union's GDPR and Digital Services Act impose data localization and algorithmic disclosure requirements on platform operators serving transnational user bases. China's National Press and Publication Administration maintains content approval frameworks that gate market access for foreign-developed titles. Stakeholders must monitor evolving spectrum allocation decisions and cross-border data flow restrictions as these regulatory variables increasingly determine where infrastructure investment yields playable latency thresholds.
Market Dynamics
Cloud gaming infrastructure is forcing platform operators to rebuild their technology stacks around GPU virtualization and edge compute nodes, collapsing the historical moat of proprietary console hardware.
Growth Catalysts
- 5G Network Deployment:Telecommunications infrastructure upgrades in South Korea and urban China reduce latency thresholds below 20 milliseconds, enabling competitive multiplayer synchronization on mobile devices without local rendering hardware.
- EU Digital Services Act:Algorithmic transparency mandates for content recommendation systems create compliance-driven demand for third-party moderation tools and audit-ready analytics platforms among European platform operators.
- Procedural Content Generation:AI-driven asset creation pipelines compress production timelines for open-world environments, allowing studios to scale content libraries without linear staffing expansion.
Market Restraints
- Semiconductor Supply Concentration:Custom SoC fabrication for premium consoles depends on a concentrated foundry base in Taiwan, exposing hardware release schedules to geopolitical disruption risks.
- Content Approval Friction:China's National Press and Publication Administration maintains discretionary licensing timelines for foreign-developed titles, creating unpredictable revenue recognition for publishers targeting that market.
- Data Localization Requirements:GDPR and emerging national privacy frameworks mandate regional server deployment, fragmenting cloud gaming infrastructure economics and raising fixed cost thresholds for market entry.
Strategic Opportunities
- India Broadband Expansion:Fiber-to-the-home rollout in Tier-2 cities creates first-mover advantage for low-latency game streaming services targeting price-sensitive mobile-first consumers.
- AI-NPC Convergence:Large language model integration with real-time rendering engines enables persistent, adaptive non-player characters that differentiate premium subscription tiers.
- Cross-Platform Progression:Unified save-state synchronization across console, PC, and mobile endpoints reduces platform lock-in and expands addressable lifetime value per user account.
Industry Challenges
- Real-Time Engine Expertise Scarcity:Demand for engineers proficient in distributed systems architecture and GPU compute shaders exceeds supply, compressing development timelines for cloud-native titles.
- Multi-Jurisdiction Compliance Burden:Platform operators must maintain parallel content moderation workflows for EU Digital Services Act, UK Online Safety Bill, and emerging US state-level requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Digital Gaming Market |
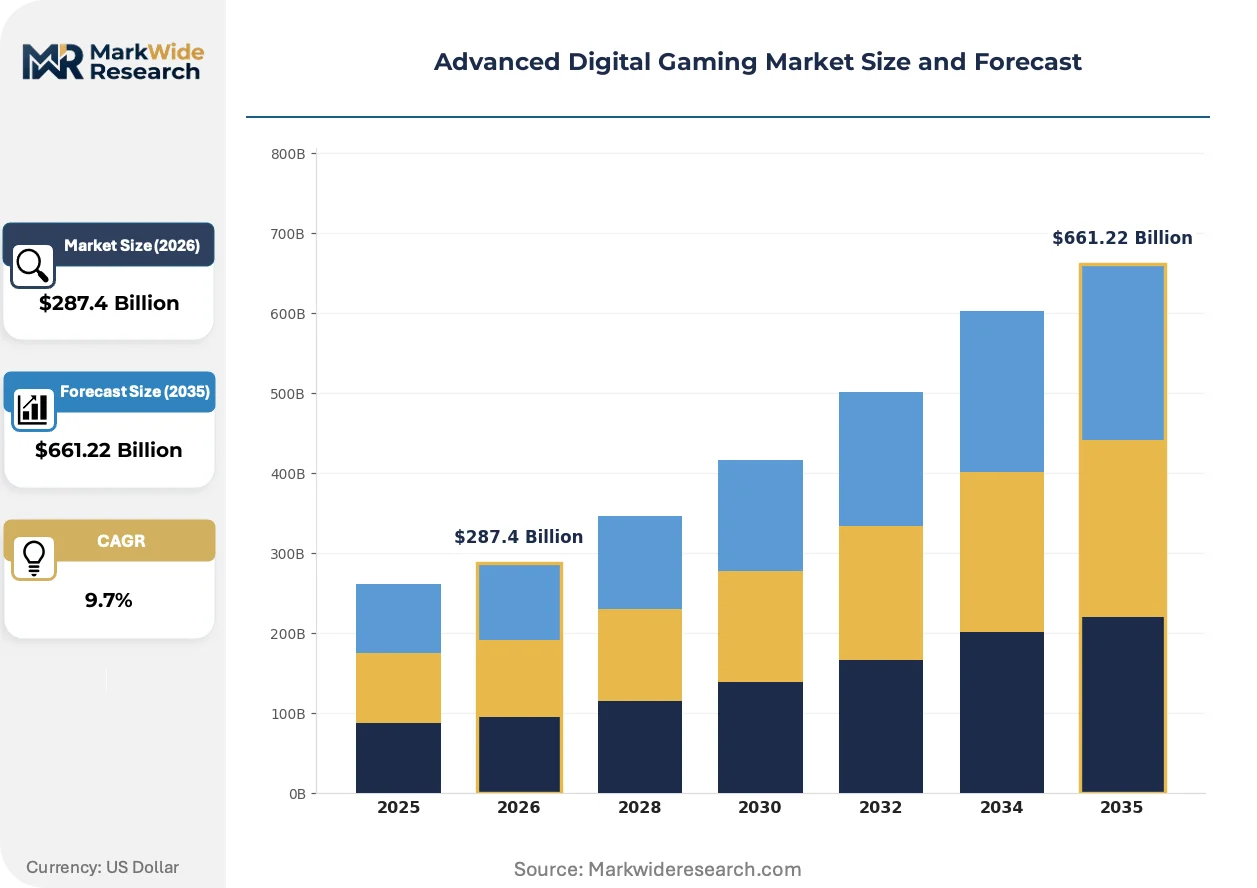
| Market Size in 2026 | $287.4 Billion |
| Market Size in 2035 | $661.22 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: PC, Console, Mobile, Cloud Gaming Game Genre: Action, Adventure, RPG, Simulation Monetization Model: Free-to-Play, Subscription, Pay-to-Play, In-Game Purchases Target Audience: Casual Gamers, Hardcore Gamers, Professional Esports Players, Streamers |
| Companies Covered | Sony Corporation, Microsoft Corporation, Nintendo Co., Ltd., Electronic Arts Inc., Tencent Holdings Limited, Zynga Inc., NVIDIA Corporation, Activision Blizzard, Take-Two Interactive Software, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Digital Gaming Market Emerging Trajectories
Generative AI is restructuring content production economics while regulatory pressure on algorithmic systems intensifies, and consumer expectations shift toward seamless cross-device continuity.
Neural radiance fields (NeRF) and Gaussian splatting techniques are digitizing photogrammetry workflows for environmental asset creation. Mid-size studios in Poland and Sweden adopt these tools to produce cinematic backgrounds without dedicated capture stages. This compression of production infrastructure is digitizing the traditional location-scouting and set-construction pipeline that previously required physical presence.
The European Union's AI Act imposes risk-tiered obligations on procedural content systems that generate personalized gameplay scenarios. Platform operators serving EU users must document training data provenance and maintain human oversight mechanisms for high-risk adaptive difficulty algorithms. Cloud gaming services with dynamic matchmaking engines face particular scrutiny under these transparency requirements.
Subscription fatigue among core gamers is fragmenting spending across multiple services rather than consolidating on single platforms. Publishers respond with hybrid monetization that preserves premium single-purchase options alongside battle pass mechanics. This behavioral shift is most pronounced in Germany and France, where consumer protection sentiment sustains resistance to exclusive content gating.
Advanced Digital Gaming Market Segmentation
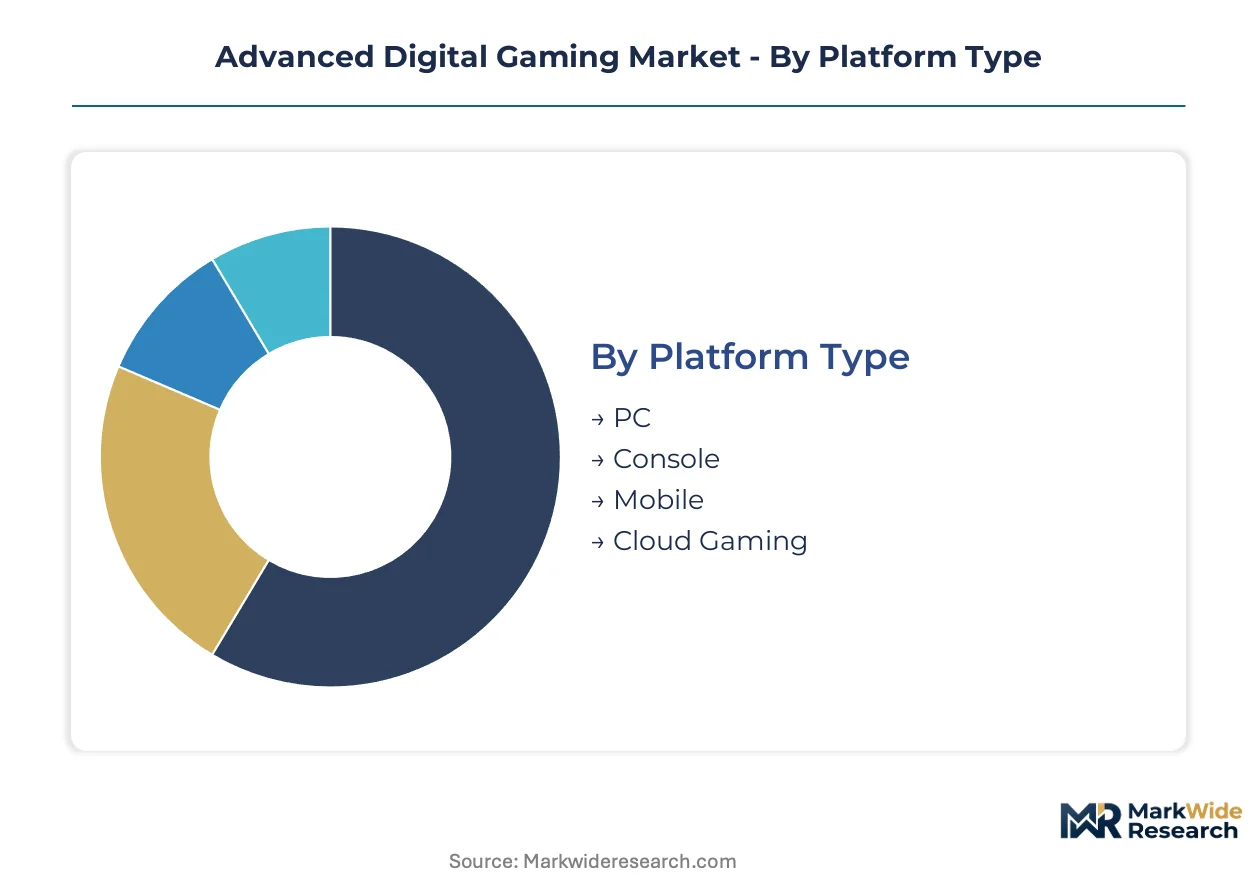
Platform architecture and monetization mechanics determine where capital deploys and margins accumulate in advanced digital gaming. Genre preferences and audience segmentation dictate content production priorities and regional go-to-market sequencing.
Platform Type:
Mobile platforms turn inventory fastest with 12-18 month hardware cycles, while console architectures sustain decade-long amortization curves.
- PC:Open hardware standards enable component-level upgrade paths that sustain engagement across multi-year release windows. Demand concentrates in Germany and South Korea where enthusiast communities drive premium peripheral attachment rates alongside GPU refresh cadences.
- Console:Proprietary SoC architectures lock users into controlled ecosystem experiences with standardized performance baselines. Japan and the United States anchor manufacturing partnerships that determine global hardware allocation during supply-constrained launch windows.
- Mobile:ARM-based chipsets and touchscreen interfaces democratize access across emerging market demographics with minimal upfront hardware investment.
- Cloud Gaming:GPU virtualization and edge node distribution eliminate local rendering requirements, collapsing the traditional hardware barrier entirely.
Mobile dominates installed base. Cloud Gaming is where expansion concentrates.
Game Genre:
Production cost tiers separate blockbuster development timelines from agile live-service operations.
- Action:High-frequency input mechanics demand sub-20 millisecond latency infrastructure and precision controller or mouse-keyboard interfaces. Competitive multiplayer synchronization requirements in South Korea and urban China sustain premium server hosting investment.
- RPG:Narrative depth and character progression systems generate extended session durations that maximize lifetime value per user account. Poland and Sweden leverage procedural content tools to compress open-world asset production timelines without linear staffing expansion.
- Adventure:Environmental storytelling and puzzle mechanics attract intermittent engagement patterns suited to subscription catalog rotation.
- Simulation:Physics fidelity and systems complexity appeal to niche enthusiast segments with high willingness-to-pay for expansion content.
Action titles command the highest production budgets. RPG is climbing the fastest as live-service mechanics extend monetization windows.
Monetization Model:
Revenue recognition velocity ranges from immediate unit sales to multi-year engagement curves.
- Free-to-Play:Zero-friction entry maximizes addressable audience scale while in-game purchase layers extract value from engaged user cohorts. Brazil and Southeast Asian markets demonstrate highest conversion efficiency on cosmetic and battle pass offerings.
- In-Game Purchases:Microtransaction infrastructure enables granular price discrimination across willingness-to-pay distributions without fragmenting the player base. China's National Press and Publication Administration mandates spending caps and probability disclosure for loot-based mechanics.
- Subscription:Recurring revenue pools fund content library expansion and reduce customer acquisition cost volatility.
- Pay-to-Play:Upfront unit economics preserve premium positioning and avoid regulatory scrutiny on randomized reward mechanisms.
Free-to-Play dominates revenue contribution. In-Game Purchases is gaining share fastest as hybrid models proliferate.
Target Audience:
Engagement intensity and content consumption patterns determine platform infrastructure requirements.
- Casual Gamers:Intermittent session patterns and low competitive stakes accommodate asynchronous mobile experiences with minimal latency sensitivity. India's Tier-2 fiber expansion targets this demographic with low-cost cloud streaming entry points.
- Hardcore Gamers:Extended session durations and performance optimization demands drive premium hardware investment and low-latency network prioritization. The FCC's broadband quality benchmarks directly determine service viability for this segment in the United States.
- Professional Esports Players:Sub-10 millisecond latency requirements and standardized tournament hardware sustain specialized infrastructure investment in South Korea.
- Streamers:Broadcast-quality capture and audience interaction tools create dual-use platform requirements spanning gameplay and content production.
Casual Gamers anchor volume scale. Hardcore Gamers is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea exports cloud gaming infrastructure expertise to Southeast Asian markets, while Japanese console hardware flows into North American retail channels. Taiwan's foundry capacity underpins global semiconductor supply for premium gaming SoCs.
United States
The FCC's broadband quality benchmarks determine cloud gaming service viability across metropolitan markets. Hardcore gamer communities in California and Texas drive premium GPU refresh cycles and peripheral attachment rates. Seattle and Austin anchor development clusters where distributed systems engineers concentrate.
China
The National Press and Publication Administration maintains discretionary licensing timelines that gate foreign title revenue recognition. 5G penetration in urban centers enables sub-20 millisecond mobile multiplayer synchronization. Shanghai and Shenzhen host domestic platform operators scaling cloud gaming infrastructure.
Germany
GDPR data localization requirements fragment cloud gaming server economics for EU user bases. Consumer protection sentiment in Berlin and Munich sustains resistance to exclusive content gating and subscription fragmentation. The country's federal structure shapes regional broadband deployment unevenness.
South Korea
Esports infrastructure investment and 5G network density sustain premium subscriber growth for low-latency services. The Ministry of Science and ICT shapes spectrum allocation decisions affecting competitive multiplayer viability. Seoul anchors professional tournament circuits that standardize hardware performance baselines.
India
Fiber-to-the-home rollout in Tier-2 cities creates first-mover opportunity for price-sensitive mobile-first cloud streaming entry. TRAI's net neutrality frameworks influence interconnection pricing for edge node deployment. Bangalore and Hyderabad concentrate engineering talent for real-time rendering pipeline development.
Advanced Digital Gaming Market Vendor Landscape
On the supply side, the industry is consolidating around platform operators with captive cloud infrastructure and semiconductor fabrication partnerships. Three archetypes dominate: vertically integrated console-hardware ecosystems, GPU virtualization specialists, and mobile-first free-to-play publishers. Competitive moves center on backward integration into cloud data centers and exclusive content licensing for subscription retention.
Among Asia-Pacific platform operators, Tencent Holdings Limited exemplifies mobile-first free-to-play monetization at scale, while Sony Corporation anchors premium console-hardware ecosystem control through custom SoC supply partnerships. Microsoft Corporation represents cloud infrastructure integration, leveraging Azure data center networks for game streaming delivery.
| Leading Market Players |
|---|
| Sony Corporation |
| Microsoft Corporation |
| Nintendo Co., Ltd. |
| Electronic Arts Inc. |
| Tencent Holdings Limited |
| Zynga Inc. |
| NVIDIA Corporation |
| Activision Blizzard |
| Take-Two Interactive Software, Inc. |
| Others |
Supply Flow & Price Mechanics
Taiwan's concentrated foundry capacity for custom gaming SoCs anchors margin distribution toward semiconductor fabricators, leaving downstream console assemblers and cloud platform operators negotiating volume commitments against allocation scarcity. This upstream bottleneck translates pricing power into multi-year supply agreements that lock in hardware release cadences and determine competitive entry timing.
Pricing Analysis
Current-generation console hardware commands premium positioning against prior-generation discount tiers and next-generation pre-announcement softness. The dominant pricing structure stratifies across hardware bundles, subscription tiers, and in-game purchase layers. Price differentiation rests on performance benchmarks and exclusive content libraries, with casual mobile segments exhibiting highest sensitivity while enthusiast PC builders show lowest elasticity. Pricing pressure intensifies in cloud gaming entry tiers as telecommunications operators bundle streaming services with 5G plans, compressing standalone subscription viability.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk assessment for gaming hardware distribution. Component sourcing concentrates in Taiwan, South Korea, and China, with advanced node GPU fabrication and memory module production anchoring in the first two while final assembly clusters in the third. Raw material dependencies span rare earth elements for magnet components, high-purity silicon for wafer substrates, and specialized substrates for chip packaging. Distribution runs through regional distribution centers serving retail channels and direct-to-consumer fulfillment networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering a cyclical recovery phase driven by console hardware refresh cycles and telecommunications infrastructure upgrade waves. The recovery trajectory depends on foundry capacity allocation and regional regulatory clarity.
For Market Incumbents: Pre-empt cloud-native platform erosion by securing captive GPU virtualization capacity in edge data centers and accelerating exclusive content pipeline investment. The threat of low-hardware-entry cloud competitors demands backward integration into rendering infrastructure, while regulatory fragmentation across EU Digital Services Act compliance and China's content approval timelines requires parallel legal technology investments. For New Entrants and Emerging Players: India's Tier-2 broadband expansion represents the most penetrable geographic white space for price-sensitive mobile-first cloud streaming services. Secondary opportunities sit in AI-NPC middleware licensing for mid-size studios seeking differentiation without internal machine learning teams. A partnership-first go-to-market with regional telecommunications operators minimizes customer acquisition costs. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed cloud infrastructure specialists holding edge node networks in Southeast Asian markets. Long-term viability favors platforms with demonstrated subscriber retention mechanics and regulatory compliance infrastructure across multiple jurisdictions. The signal to watch is foundry capacity allocation announcements affecting hardware supply predictability.| Strategic Initiative | Industry Significance |
|---|---|
| GPU Virtualization Scale-Up | Captive rendering capacity in Azure and AWS data centers secures latency-competitive streaming delivery. |
| Exclusive Content Licensing | First-party studio acquisitions lock catalog rotation for subscription retention against multi-service fatigue. |
| Edge Node Geographic Expansion | India and Southeast Asian fiber rollouts enable sub-50 millisecond thresholds for mobile competitive multiplayer. |
| AI-NPC Middleware Development | Large language model integration differentiates premium subscription tiers with persistent adaptive characters. |
| Cross-Platform Progression Infrastructure | Unified save-state synchronization reduces platform lock-in and expands lifetime value per user account. |
Methodological Framework
The analysis maps cloud gaming infrastructure, console hardware ecosystems, and mobile free-to-play monetization, each validated through platform engineering directors, content licensing executives, and telecommunications partnership leads. Primary interview data triangulates against secondary sources including hyperscaler capital expenditure disclosures, SEC filings from listed publishers, spectrum allocation decisions from national regulators, and trade flow data for semiconductor components. Bottom-up segment sizing and top-down macroeconomic anchoring converge through iterative stakeholder feedback.
Assumptions held fixed include prevailing regulatory frameworks for content approval and data localization, while variables tested encompass 5G deployment velocity, foundry capacity expansion timing, and generative AI adoption curves in content production. Segmentation dimensions modeled span platform architecture, monetization mechanics, genre category, and audience engagement intensity. CAGRs derive from logistic diffusion curves fitted to hardware replacement cycles and infrastructure investment patterns, with cloud gaming subscriber growth and in-game purchase conversion rates as primary industry-specific inputs.
Practitioners should monitor foundry allocation announcements, spectrum auction outcomes, and content licensing timeline shifts for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Europe Casino Gambling Market
Gaming
VR Racing Gaming Market
Gaming
Mobile Gaming Market
Gaming
Video Game Software Market
Gaming
Russia in-Game Advertising Market
Gaming
Social Gaming Market
Gaming
Latin America Gaming Headsets Market
Gaming
Videogames Market
Gaming
Global Subscription-Based Gaming Market
Gaming
Asia-Pacific Casino Gambling Market
Gaming
Australia Gaming Gadgets Market
Gaming
France Online Gambling Market
Gaming
South Korea Subscription-Based Gaming Market
Gaming
AAA Games Market
Gaming
Board Games Market
Gaming
Online Casual Games Market