
 Board Games Market | 2026-2036
Board Games Market Size, Share, and Industry Trends Forecast 2026-2036
Board Games Market Intelligence
Adult enthusiasts is rotating toward the center of purchasing gravity as family-centric buying loses relative share. Hasbro Inc. leverages its multi-brand portfolio to sustain shelf presence across mass retail and hobby channels simultaneously. Ravensburger AG anchors premium positioning through its long-standing reputation for component quality and narrative depth. CMON Limited specializes in miniatures-heavy Kickstarter campaigns that dominate enthusiast crowdfunding.
Board games constitute tabletop entertainment products combining printed components, cards, tokens, dice, and sometimes miniatures or electronic modules, manufactured through offset printing, injection molding, and hand-assembly processes, designed to facilitate structured social interaction through rule-bound play. Strategy Games and Cooperative Games command the deepest margin pools as enthusiast buyers accept premium price points for complex mechanics and narrative depth. Family Games and Party Games occupy higher volume tiers but face commoditization pressure from private-label alternatives in mass retail channels. The Distribution Channel dimension reveals Online Retailers capturing share from Specialty Stores as direct-to-consumer platforms and subscription boxes reshape discovery and replenishment patterns.
REACH in Europe governs chemical safety in printed materials and plastics, while the EU Toy Safety Directive mandates age-grading and small-parts testing that directly affects component design and labeling. The US Consumer Product Safety Commission enforces ASTM F963 standards that shape domestic product specifications and import compliance burdens. Stakeholders must monitor evolving extended producer responsibility frameworks and digital-physical hybrid formats that could redefine regulatory classification and market access requirements.
Market Dynamics
Adult hobbyist communities are pulling purchasing gravity away from mass-market family segments, forcing publishers to reconfigure component quality tiers and distribution channel investments toward direct-to-consumer platforms and specialty retail networks.
Growth Catalysts
- REACH compliance mandates:European chemical safety regulations for printed materials and plastics are accelerating material innovation among component suppliers, creating competitive differentiation for compliant publishers.
- Tabletop gaming cafes:Dense urban clusters in Germany and South Korea are normalizing board gaming as public leisure activity, expanding trial and discovery beyond traditional retail.
- Miniatures manufacturing:Advances in resin casting and 3D printing workflows are reducing per-unit production costs for high-detail figurines, unlocking premium tier accessibility for mid-tier publishers.
Market Restraints
- Paper pulp volatility:Offset printing substrates face input cost pressure from global fiber supply fluctuations, compressing margin pools for card-heavy game formats.
- Chinese injection molding concentration:Plastic component sourcing relies heavily on Guangdong province facilities, exposing publishers to geopolitical friction and shipping rate instability.
- EU Toy Safety Directive friction:Age-grading and small-parts testing requirements add 8-14 week certification timelines that conflict with Kickstarter fulfillment schedules.
Strategic Opportunities
- Brazilian market underpenetration:Latin America's largest economy lacks dedicated hobby distribution infrastructure, presenting first-mover advantage for localized Portuguese-language editions.
- Extended producer responsibility frameworks:Emerging EU packaging waste regulations will reward publishers with recyclable component designs and closed-loop takeback programs.
- App-integrated hybrid formats:NFC-enabled cards and companion smartphone applications are converging physical and digital gameplay, opening subscription revenue streams.
Industry Challenges
- Artisan miniature painter scarcity:Hand-painted prototype and promotional miniature production faces bottleneck constraints as demand outstrips skilled labor availability.
- ASTM F963 compliance complexity:US import testing for small parts and sharp edges creates documentation burdens that delay container releases at port.
- IP licensing fragmentation:Media property board game adaptations require navigation of multiple rights holders across film, literary, and merchandising domains.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Board Games Market |
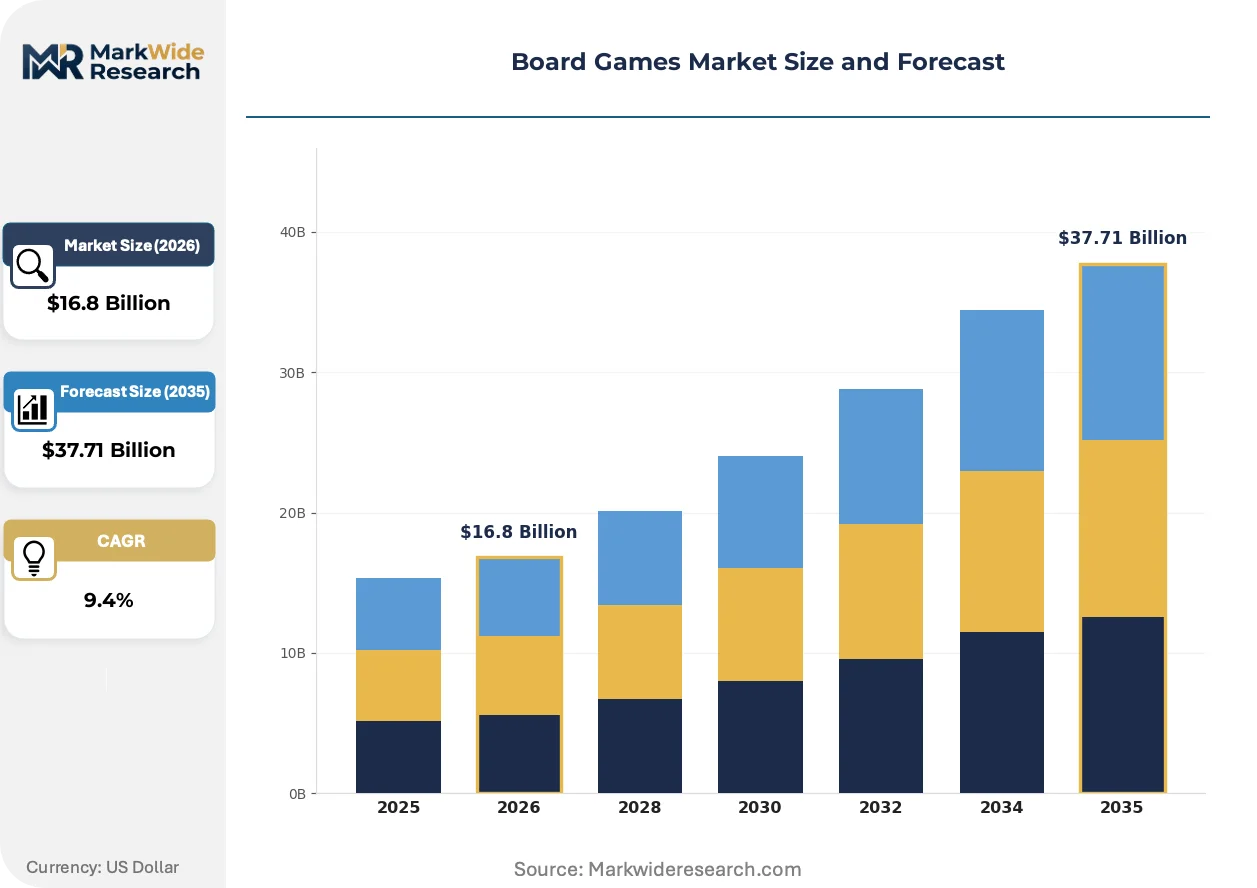
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $37.71 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strategy Games, Family Games, Party Games, Educational Games, Abstract Games, Cooperative Games Target Audience: Children, Teenagers, Adults, Senior Citizens, Casual Players, Enthusiasts Distribution Channel: Specialty Stores, Online Retailers, Toy Stores, Department Stores, Direct Sales, Hobby Shops Game Theme: Fantasy, Historical, Science Fiction, Mystery, Adventure, Puzzle |
| Companies Covered | Asmodee Group, Z-Man Games, Hasbro Inc., Spin Master Ltd., Goliath Games, Mattel Inc., Fantasy Flight Games, CMON Limited, Ravensburger AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Board Games Market Strategic Shifts & Innovations
Crowdfunding platforms are restructuring how games reach market, bypassing traditional gatekeepers while simultaneously elevating backer expectations for component fidelity and stretch goal complexity.
Resin miniature production workflows are displacing traditional PVC injection for limited-run collector editions. Adult enthusiast segments in Japan and Germany are absorbing these premium-priced releases within compressed pre-order windows. This shift is displacing mass-market plastic component economics from the premium tier entirely.
REACH authorization requirements for phthalate alternatives in printed materials are tightening across EU member states. Publishers sourcing from non-EU print houses face documentation audits and reformulation costs. Strategy game producers with complex card decks are absorbing the highest compliance burden and accelerating supplier consolidation.
Subscription box curation is altering discovery patterns for casual buyers. Mass-market channels are losing replenishment visits as monthly tabletop crates from specialized distributors capture family segment trial. This behavioral pivot is most visible in US and UK metropolitan suburbs where direct-to-door delivery density supports logistics economics.
Board Games Market Segmentation
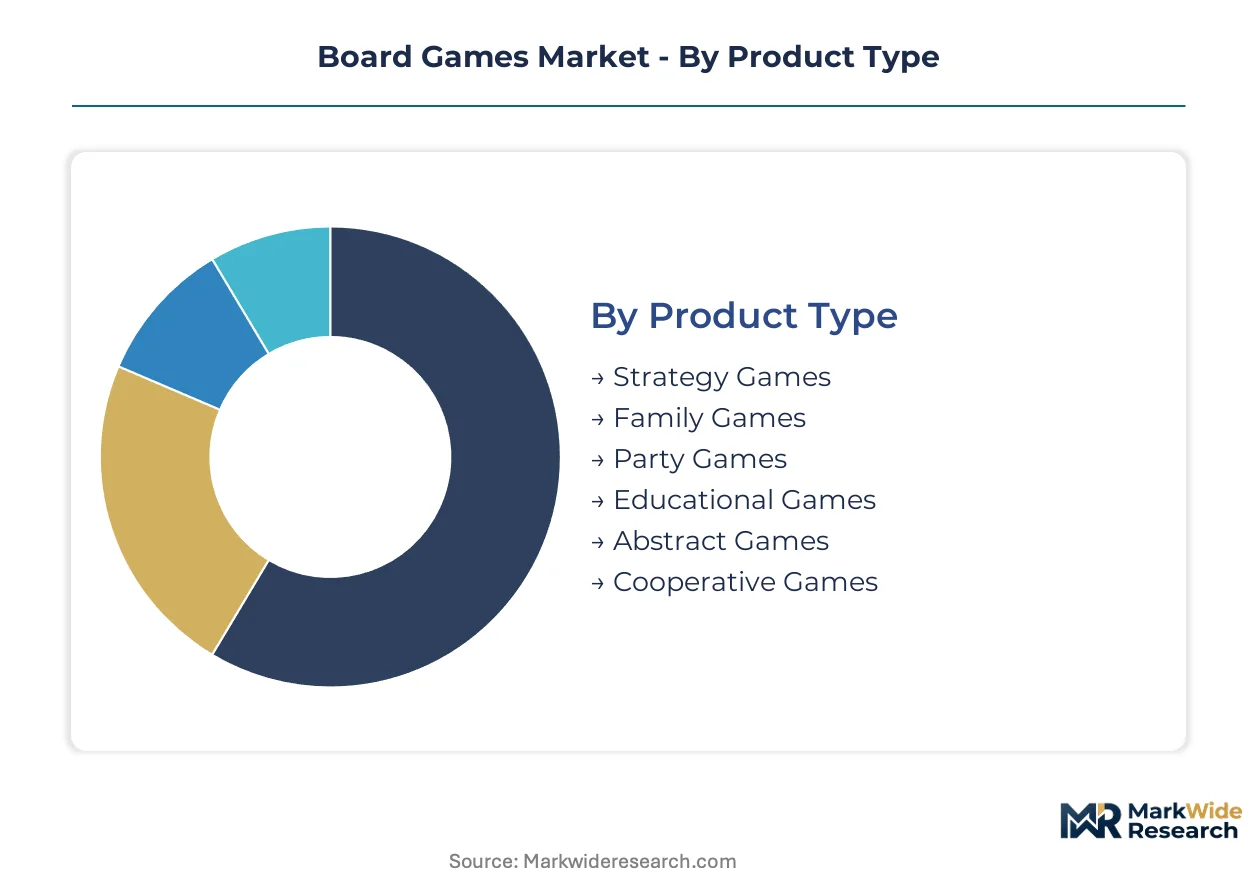
Segmentation in board games separates margin capture from volume rotation. Publishers must align component quality tiers and channel investments to the specific buyer profile each segment serves.
Product Type:
Margin pools concentrate deepest where complexity justifies premium pricing and enthusiast buyers accept extended playtimes.
- Strategy Games:These titles deploy multi-layered resource management mechanics and extended play sessions. German and Japanese enthusiast communities absorb the highest price points for titles with asymmetric player powers and modular boards.
- Cooperative Games:Players collaborate against the game system itself through hidden information and timed decision windows. South Korean tabletop cafes drive trial for these formats where social bonding outweighs competitive tension.
- Family Games:Accessible rule sets and 30-45 minute playtimes dominate holiday purchasing in US mass retail.
- Party Games:Large player counts and minimal setup requirements sustain replenishment cycles for casual gatherings.
- Educational Games:Curriculum-aligned mechanics target institutional procurement in Canadian and Australian school districts.
- Abstract Games:Minimal theming and pure spatial reasoning attract collector segments in Netherlands and Nordic markets.
Strategy Games command the dominant revenue share, while Cooperative Games are climbing the fastest as cafe culture normalizes shared experiences over competitive dominance.
Target Audience:
Volume flows through casual entry points, but profitability hinges on enthusiast retention and upgrade pathways.
- Adults:This cohort drives Kickstarter velocity and accepts resin miniature premiums. Dense urban clusters in Berlin, Seoul, and Toronto sustain dedicated hobby shop foot traffic for complex titles.
- Enthusiasts:Organized play participation and convention attendance define this segment. French and Italian communities demonstrate highest per-capita spending on limited collector editions.
- Children:Safety certification requirements and durability standards shape component specifications for this entry-level tier.
- Teenagers:Social media discovery and streaming content influence purchase timing for this digitally native cohort.
- Senior Citizens:Large print components and extended thinking time accommodations open accessibility-focused design opportunities.
- Casual Players:Gift purchasing and seasonal occasion buying concentrate this segment in department store and online channels.
Adults hold the established spending base, with Enthusiasts expanding most quickly through organized community infrastructure.
Distribution Channel:
Channel selection determines discovery mechanics and margin retention simultaneously.
- Online Retailers:Algorithmic recommendation engines and subscription crate curation reshape trial patterns. UK and US metropolitan suburbs show highest direct-to-door delivery density for family segment replenishment.
- Specialty Stores:Staff expertise and organized play events sustain enthusiast loyalty. German FLGS density remains unmatched for hands-on component evaluation before purchase.
- Toy Stores:Seasonal aisle placement and licensed property tie-ins drive impulse conversion for family formats.
- Department Stores:Holiday gift bundling and promotional calendar alignment concentrate volume in Q4 windows.
- Direct Sales:Publisher-owned platforms capture full margin on pre-orders and exclusive content unlocks.
- Hobby Shops:Miniature painting stations and tournament hosting build community stickiness for wargame-adjacent titles.
Online Retailers have seized the volume lead, though Specialty Stores defend the highest margin transactions through service differentiation.
Game Theme:
Thematic resonance determines pre-order velocity and collector edition sell-through rates.
- Fantasy:Established intellectual property adaptations and original high-fantasy settings dominate crowdfunding platforms. Polish and Spanish language editions show expanding localization demand.
- Historical:Period-accurate component design and bibliography inclusion attract academically inclined buyers. British and Italian markets demonstrate strongest absorption for ancient civilization and World War settings.
- Science Fiction:Space exploration and dystopian narratives align with miniature-heavy production workflows.
- Mystery:Deduction mechanics and narrative branching suit solo and two-player format experimentation.
- Adventure:Campaign progression systems and legacy component destruction create replayable narrative arcs.
- Puzzle:Spatial reasoning challenges and competitive speed-solving attract abstract game crossovers.
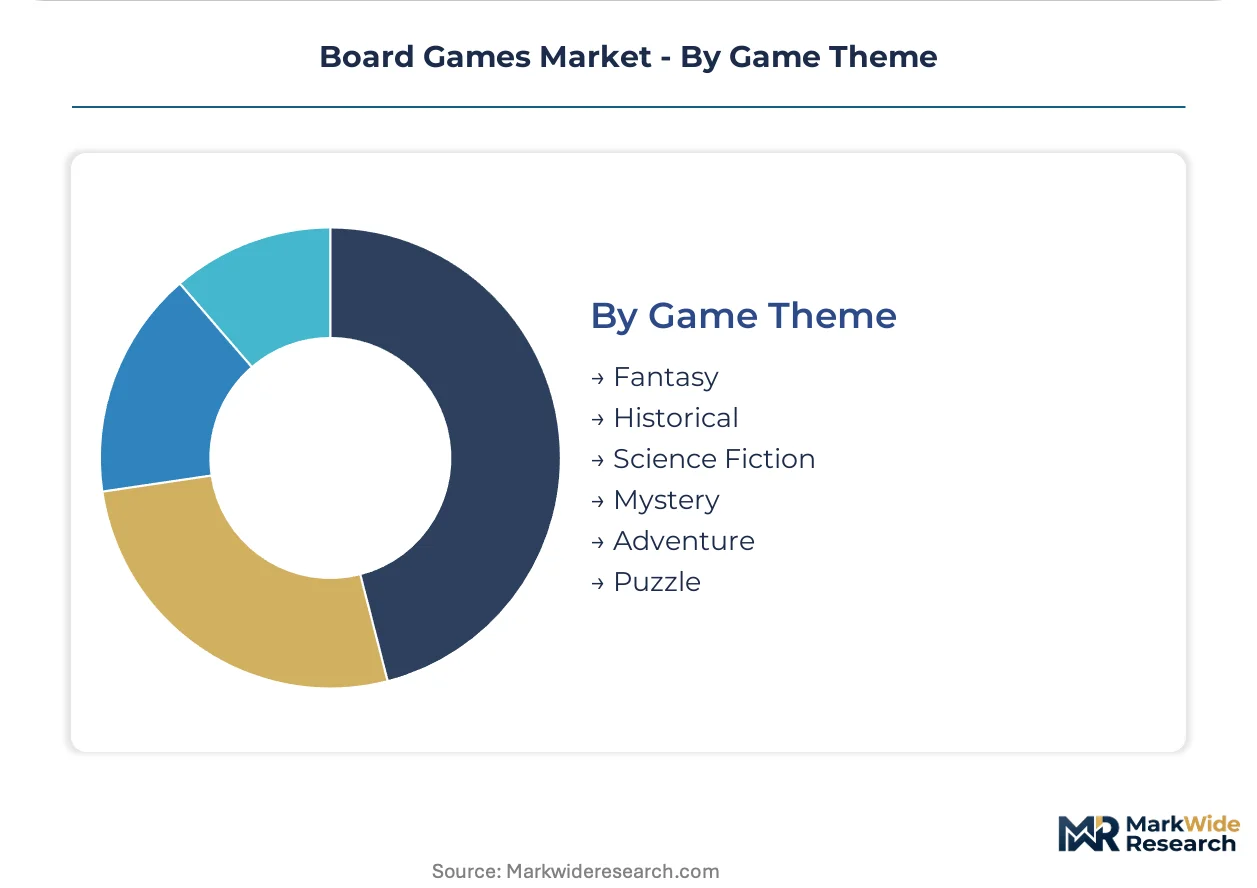
Fantasy maintains the entrenched preference position, with Historical themes gaining share fastest through documentary streaming cross-promotion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Adult hobbyist buyers concentrate purchasing power in Germany, South Korea, and the United States, while emerging clusters in Brazil and Japan reshape volume distribution. National regulations on chemical safety and toy certification create divergent compliance burdens that advantage localized production footprints.
Germany
Essen Spiel convention attendance and dense FLGS networks sustain the deepest enthusiast penetration globally. REACH authorization requirements for phthalate alternatives in printed materials impose reformulation costs on imported card decks. Bavaria and North Rhine-Westphalia host concentrated printing and distribution infrastructure serving EU-wide replenishment.
United States
Kickstarter velocity and subscription box curation drive discovery among metropolitan coastal buyers. ASTM F963 small-parts testing and documentation requirements delay container releases at West Coast ports. Seattle and Austin anchor tabletop cafe clusters that normalize public gaming as leisure activity.
South Korea
Seoul Capital Area tabletop cafes absorb cooperative game formats where social bonding outweighs competitive tension. MFDS toy safety standards align with EU directives but accelerate certification timelines through streamlined documentation. Busan-Ulsan corridor supports resin miniature finishing workshops for regional publishers.
Brazil
São Paulo and Rio de Janeiro exhibit underpenetrated hobby distribution infrastructure with minimal localized Portuguese-language edition availability. ANVISA toy safety regulations mirror ASTM frameworks but lack dedicated tabletop industry guidance. First-mover publishers establishing direct-to-consumer platforms capture unmet enthusiast demand.
Japan
Tokyo and Osaka collector segments absorb premium resin miniature releases within compressed pre-order windows. METI consumer product standards govern electronic module integration in app-hybrid formats. Kansai region hosts specialized component finishing ateliers serving domestic limited editions.
Board Games Market Key Industry Players
Player mix skews toward diversified toy conglomerates and enthusiast-focused specialists operating in parallel tiers. Mass-market publishers leverage multi-brand portfolios across retail channels while hobby specialists dominate crowdfunding velocity. Two strategic archetypes define competitive positioning: scale-driven manufacturers with captive distribution and design-forward boutiques with community-anchored release strategies. Portfolio diversification and direct-to-consumer platform investment constitute the dominant competitive moves.
Within the diversified conglomerate tier, Hasbro Inc. and Mattel Inc. occupy positions spanning mass retail and licensed property adaptations. Ravensburger AG and CMON Limited exemplify opposing specialization vectors—premium component quality anchoring family segment loyalty versus miniatures-heavy crowdfunding campaigns capturing enthusiast pre-order commitment. Asmodee Group sits within the portfolio-aggregator archetype, consolidating hobby brands under unified distribution infrastructure. Each represents a distinct path to margin retention: manufacturing scale, design premiumization, or community-locked release velocity.
| Leading Market Players |
|---|
| Asmodee Group |
| Z-Man Games |
| Hasbro Inc. |
| Spin Master Ltd. |
| Goliath Games |
| Mattel Inc. |
| Fantasy Flight Games |
| CMON Limited |
| Ravensburger AG |
| Others |
Cost & Logistics Intelligence
REACH authorization requirements for phthalate alternatives in printed materials and plastics simultaneously gate supplier qualification and enable price differentiation between compliant and non-compliant publishers across European distribution channels.
Pricing Analysis
Current-gen resin miniature editions command 3-4x premiums over prior-gen PVC injection-molded counterparts, while next-gen NFC-enabled hybrid formats are testing subscription-based recurring revenue models. Three-tier pricing structure across premium resin collector editions, standard card-and-board releases, and economy mass-market SKUs dominates transactional structures. Price differentiation hinges on component quality grade and CE marking tier for EU market access. Cost compression in card-heavy formats is intensifying because offset printing substrate volatility feeds directly into per-unit economics. Casual family buyers exhibit highest price sensitivity, while adult enthusiasts demonstrate lowest elasticity for limited-run miniature premiums.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes and West Coast port congestion are extending inbound logistics timelines for publishers sourcing from Guangdong province injection molding facilities. Manufacturing gravity centers on China for plastic components, Germany for precision printing and finishing, and South Korea for resin miniature workshops. Raw material dependencies span paper pulp for card stocks, petroleum-derived resins for miniatures, and rare earth elements for NFC module integration. Single-source vulnerability in Chinese injection molding concentration exposes publishers to geopolitical friction and shipping rate instability. Distribution runs through direct-to-consumer platforms, specialty retail networks, and mass-market wholesale tiers in descending margin order.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
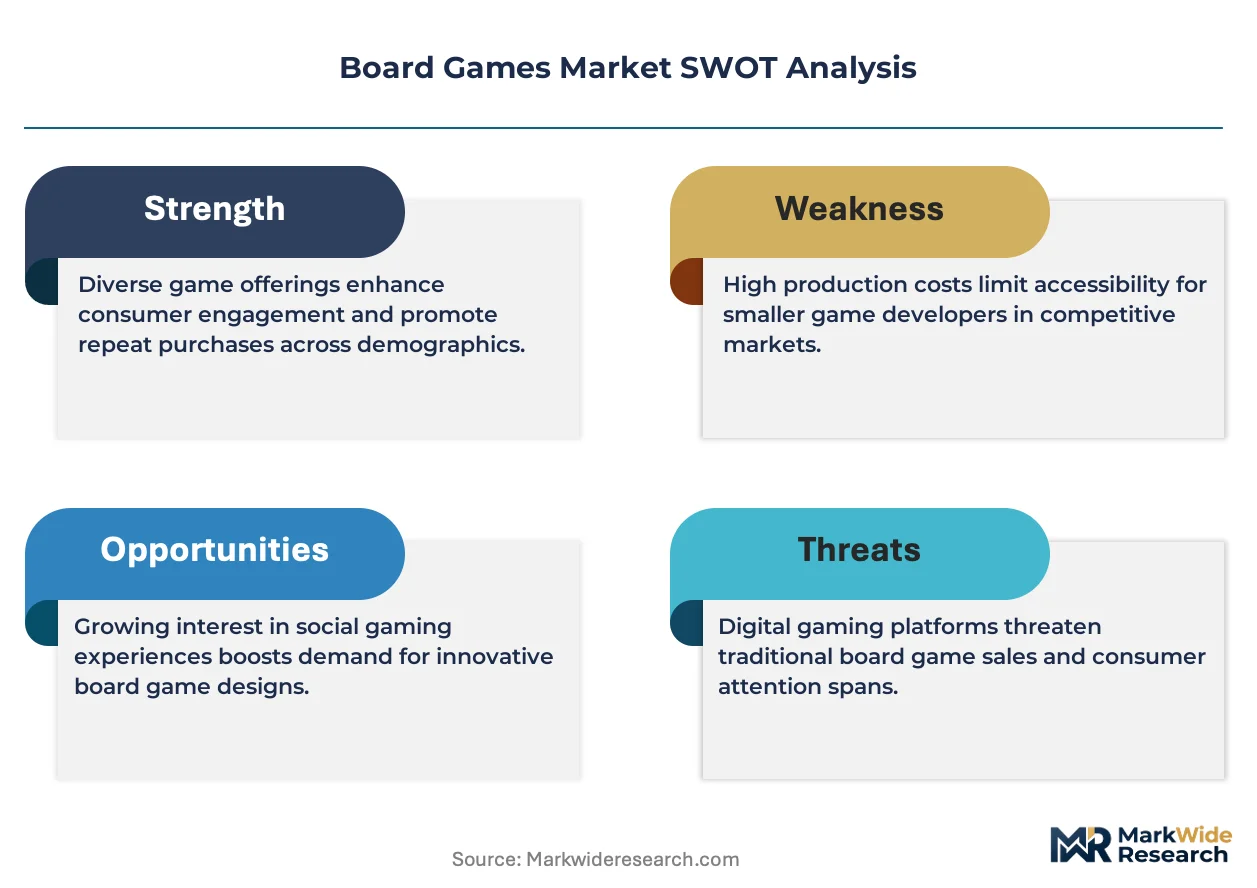
Digital entertainment substitutes—mobile gaming and streaming platforms—threaten tabletop engagement minutes, forcing incumbents to defend physical-social interaction value propositions that resist screen-based displacement.
For Market Incumbents: Fortify enthusiast community lock-in through organized play infrastructure and exclusive content unlocks on proprietary direct-to-consumer platforms. Invest in backward integration into resin miniature finishing capacity to capture premium tier margins and reduce dependency on artisan painter bottlenecks. Defend against crowdfunding-native entrants by accelerating pre-order window compression and stretch goal complexity matching. For New Entrants and Emerging Players: Differentiate on Brazilian market localization where Portuguese-language edition availability remains sparse and hobby distribution infrastructure is underdeveloped. Target São Paulo and Rio de Janeiro metropolitan clusters with direct-to-consumer platform launches bypassing fragmented wholesale channels. Penetrate through app-integrated hybrid formats that open subscription revenue streams unavailable to legacy publishers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified toy conglomerates seeking to divest hobby-focused subsidiaries with enthusiast community assets but misaligned mass-market corporate priorities. Long-term viability hinges on direct-to-consumer platform ownership and recurring revenue attachment rates rather than transactional wholesale dependence. Monitor Kickstarter fulfillment timeline compression as signal of operational maturity separating acquirable assets from integration risks.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Platform Launch | Captures full margin on pre-orders and enables exclusive content tiering for enthusiast retention. |
| Resin Miniature Production Integration | Reduces per-unit costs and unlocks premium tier accessibility for mid-tier publishers competing with CMON Limited. |
| Portuguese-Language Localization | Addresses underpenetrated Brazilian demand where ANVISA compliance frameworks lack dedicated tabletop guidance. |
| NFC-Enabled Hybrid Format Development | Converges physical and digital gameplay for METI-governed Japanese collector segments and subscription revenue. |
| Extended Producer Responsibility Program | Prepositions publishers for emerging EU packaging waste regulations rewarding recyclable component designs. |
Research Approach
A standing panel of game development executives, specialty retail buyers, crowdfunding campaign managers, and resin miniature production specialists provided ongoing calibration against secondary validation sources. Primary fieldwork combined structured interviews with component suppliers in Guangdong and Bavaria alongside trade show observation at Essen Spiel. Secondary sources encompassed customs records for board game imports, SEC 10-K filings from diversified toy conglomerates, and Kickstarter campaign performance databases. Bottom-up publisher revenue modeling triangulated against top-down category spending estimates from retail audit data.
Consistency checks validated volume and value outputs against external benchmarks including hobby channel sell-through reports and crowdfunding platform disclosure aggregates. The analytical framework modeled segmentation dimensions spanning product type complexity tiers, target audience engagement depth, distribution channel margin structures, and regional regulatory clusters across the projection horizon. CAGRs derived from fitted growth curves applied to per-segment spending intensity and population-adjusted penetration rates. Forecast inputs incorporated REACH compliance cost pass-through assumptions and resin miniature production learning curve effects.
The analysis sits within stated boundaries; outcomes outside sustained adult enthusiast community expansion, stable Asia-Europe shipping lanes, and unaltered EU toy safety directive timelines would require recalibration. Forecasts reflect documented assumptions regarding crowdfunding platform fee structures and retail channel shelf space allocation. Specific risk factors spanning paper pulp commodity volatility, Chinese manufacturing concentration, and digital entertainment substitution could materially revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
China in-Game Advertising Market
Gaming
Flat Gaming Monitors Market
Gaming
VR Gaming Market
Gaming
Puzzle Video Game Market
Gaming
H5 Games Market
Gaming
Mobile Gaming Market
Gaming
China Casino Tourism Market
Gaming
PC Games Market
Gaming
Traditional Casual Games Market
Gaming
Saudi Arabia Entertainment and Amusement Market
Gaming
Arcade Games Market
Gaming
Gaming Hardware Market
Gaming
Gaming Simulator Market
Gaming
Gaming Console Market
Gaming
Gaming Accessories Market
Gaming
Gaming As a Service Market