
 Russia in-Game Advertising Market | 2026-2036
Russia in-Game Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Russia in-Game Advertising Market Insights
Programmatic real-time bidding is rewriting how in-game inventory reaches advertisers in Russia. Yandex leverages its demand-side platform to control ad serving across domestic game networks. VK sustains vertical integration from social identity graphs to in-game placement delivery. Lesta Games anchors its monetization through proprietary ad tech built for naval combat titles.
In-game advertising inserts commercial messages into interactive entertainment environments through SDK integrations that render display units, video spots, or branded content without disrupting gameplay flow. The primary purpose is capturing engaged attention during immersion peaks when skip rates drop and brand recall rises. Video ads command premium CPMs across action and racing genres where session lengths support completion rates. Mobile dominates volume under freemium models where players exchange attention for virtual currency. PC and console segments retain higher per-user value in ad-supported subscription tiers.
Roskomnadzor enforces data localization rules that constrain foreign ad tech infrastructure, while the Federal Antimonopoly Service reviews platform dominance in digital advertising auctions. The Central Bank of Russia monitors payment flows for virtual goods tied to ad-reward systems. Stakeholders must track how sanctions compliance affects SDK availability from Western providers and whether domestic alternatives achieve parity in measurement and attribution.
Market Dynamics
Federal Law No. 242-FZ mandates that all user data processing for Russian gamers occurs on domestic servers, forcing foreign ad tech platforms to rebuild infrastructure or exit. This localization pressure is fragmenting SDK availability and elevating domestic platform control over inventory auctions.
Growth Catalysts
- Rewarded video mechanics:Mobile publishers embed opt-in video placements that exchange virtual currency for completed views, lifting engagement metrics above banner baselines.
- Federal Law No. 242-FZ:Data localization requirements create protected territory for domestic ad tech builders, accelerating substitution of Western measurement tools.
- Moscow-Saint Petersburg corridor:Developer studio clustering concentrates creative production and advertiser spending pools within two-hour flight radius.
Market Restraints
- Sanctions-driven SDK scarcity:Western attribution and analytics tools face availability constraints, forcing publishers toward unproven domestic alternatives.
- Ruble payment flow restrictions:Central Bank of Russia monitoring of virtual goods transactions complicates cross-border revenue recognition for foreign publishers.
- Attribution technology gaps:Domestic measurement tools lag on probabilistic matching and post-install event tracking, degrading campaign optimization.
Strategic Opportunities
- Kazan-Nizhny Novgorod corridor:Emerging developer clusters outside capital cities offer lower talent costs and untapped local advertiser relationships.
- Playable ad formats:Interactive mini-game advertisements that let users sample mechanics before install are penetrating mid-core genres.
- Cloud gaming infrastructure:5G rollout and edge computing convergence enable server-side ad insertion without SDK dependency on player devices.
Industry Challenges
- Programmatic talent scarcity:Domestic labor pools lack depth in real-time bidding algorithm development and yield optimization.
- Creative asset localization:Cultural adaptation of global brand campaigns for Russian gameplay contexts demands specialized production pipelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia in-Game Advertising Market |
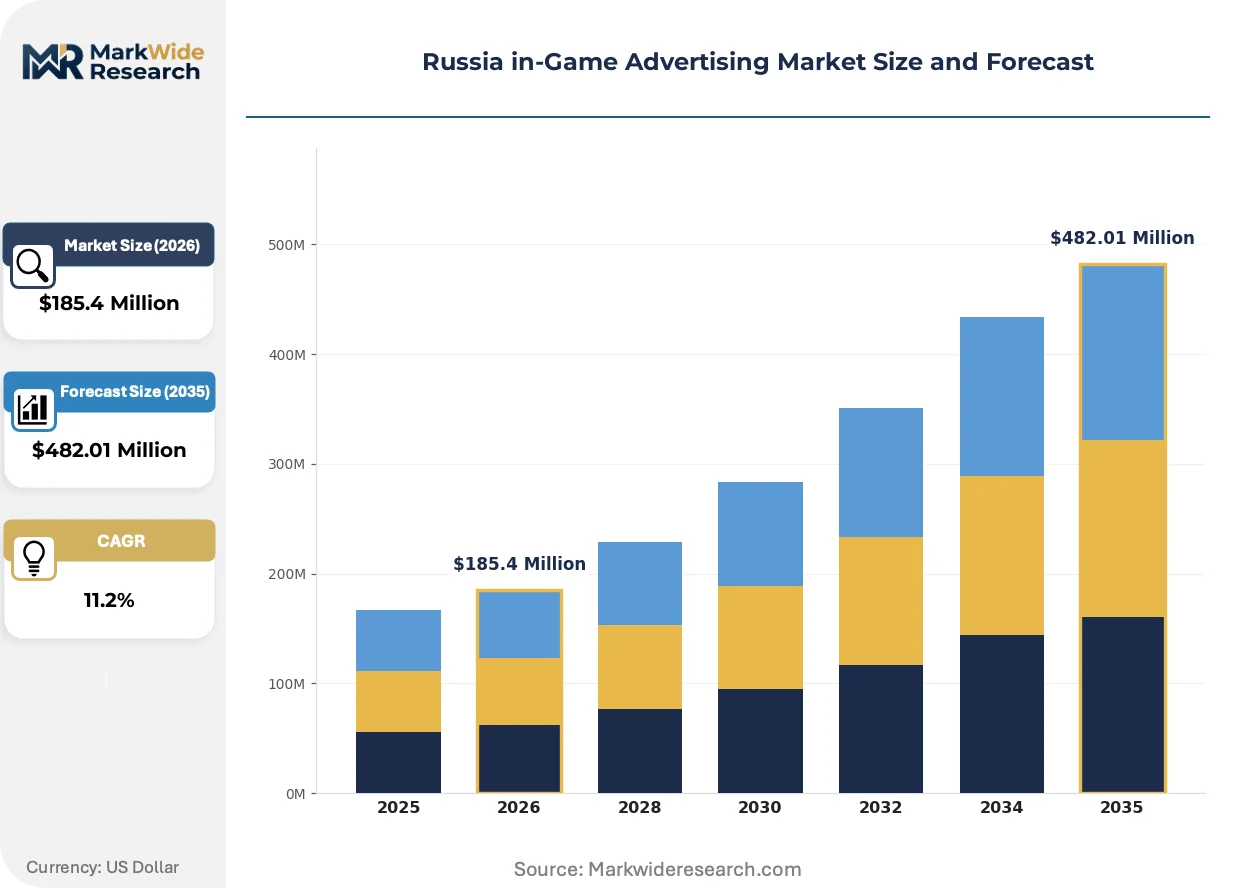
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $482.01 Million |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ad Format: Display Ads, Video Ads, Interstitials, Sponsored Content Game Genre: Action, Puzzle, Racing, Role-Playing Device Type: Mobile, Console, PC, VR Monetization Model: Freemium, Subscription, Pay-to-Play, Ad-Supported |
| Companies Covered | Yandex, VK, Lesta Games, Mail.ru Group, Odnoklassniki, Astrum Entertainment, SoftClub, Innova, Buka, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia in-Game Advertising Market Trends and Innovations
Ad serving infrastructure is splitting along geopolitical lines as domestic platforms capture inventory that Western tools cannot legally process. Publishers are rebuilding tech stacks around localized identity graphs and measurement frameworks.
Server-side ad insertion is collapsing the distinction between client-rendered and cloud-streamed placements. Mid-size publishers in Yekaterinburg and Novosibirsk are adopting this architecture to bypass device-level SDK dependencies. The technology is collapsing competitive moats that previously favored platforms with deep device graph integrations.
Roskomnadzor enforcement of Federal Law No. 242-FZ is hardening data residency requirements for all user behavioral signals. Foreign demand-side platforms must license domestic infrastructure or forfeit access to Russian inventory. Mobile game publishers with hybrid monetization models are most affected, accelerating migration to Yandex and VK ad serving stacks.
Brand safety verification is displacing pure viewability metrics as the primary campaign planning criterion. Advertisers in FMCG and financial services now demand pre-campaign placement audits across game genre taxonomies. This shift is most visible in Moscow, where media agencies bundle creative services with inventory access to justify premium pricing.
Russia in-Game Advertising Market Segmentation
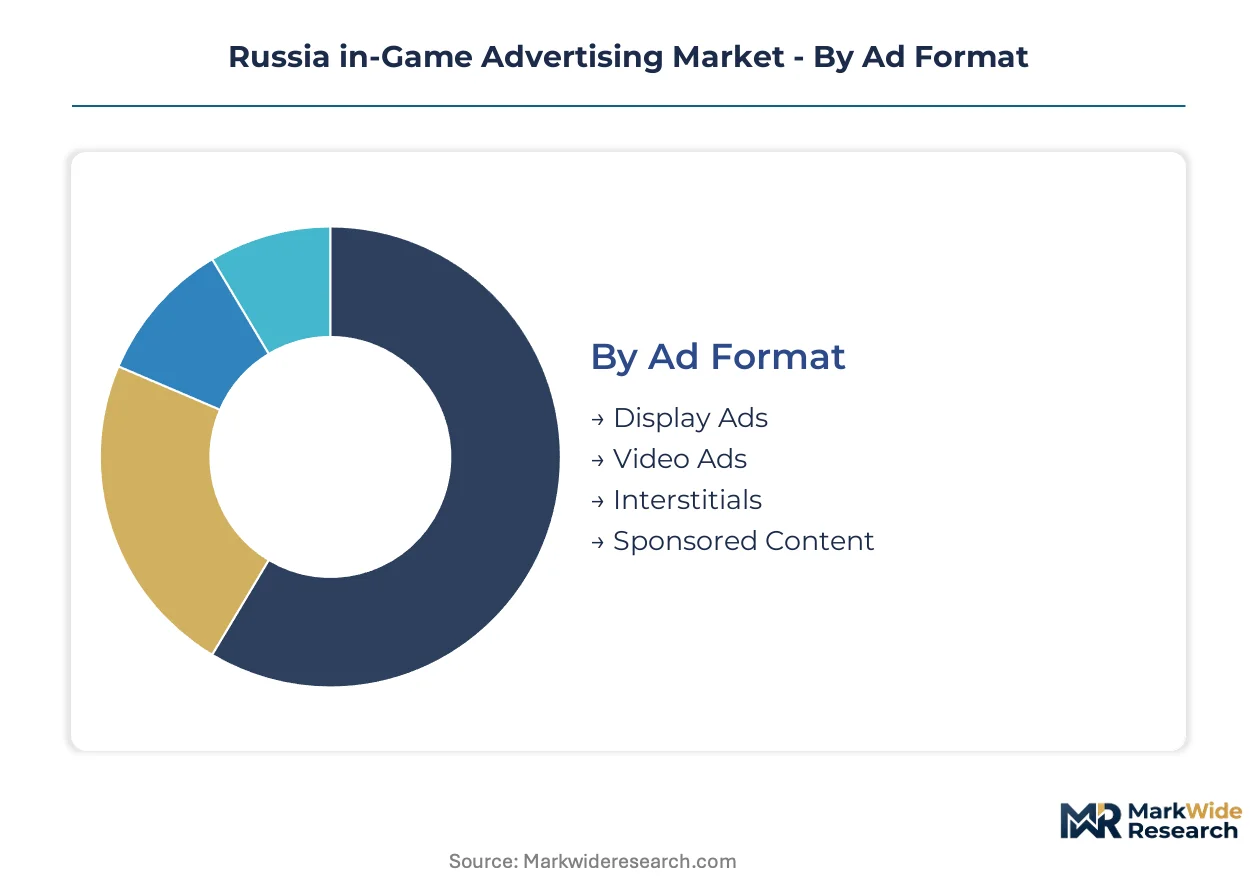
Segmentation in the Russia in-Game Advertising Market reveals how advertiser spending, publisher inventory, and player engagement fragment across technical formats, gameplay contexts, and device ecosystems. Each dimension carries distinct monetization mechanics and regulatory exposure under Federal Law No. 242-FZ.
Ad Format:
Cost tier differentiation separates high-production video inventory from lightweight display units, with pricing power concentrated in completion-guaranteed formats.
- Display Ads:Static or animated banner units rendered through SDK overlays at natural gameplay breakpoints. Demand concentrates in hyper-casual titles from Saint Petersburg studios where session frequency compensates for low per-impression yields. Banner blindness and ad blocking constrain effectiveness in mid-core genres.
- Video Ads:Full-screen motion placements including rewarded opt-in and forced interstitial variants. Moscow-based media agencies prioritize these for FMCG clients seeking completion rate guarantees above 80 percent in action and racing titles. Premium CPMs reflect scarcity of brand-safe inventory and measurement verification.
- Interstitials:Full-page transitional units displayed at level completion or menu navigation. These capture attention during natural pause points in puzzle games from Kazan developers.
- Sponsored Content:Native brand integrations woven into game environments as billboards, character skins, or narrative elements. Lesta Games deploys these in naval combat titles for endemic advertiser categories.
Video Ads command the established base. The steepest expansion runs through Sponsored Content.
Game Genre:
Application context determines session length, emotional engagement intensity, and advertiser category fit.
- Action:Combat and shooter mechanics generating 15-25 minute sessions with high attention peaks. Yandex DSP prioritizes this inventory for automotive and energy drink campaigns targeting male demographics aged 18-34. Federal Antimonopoly Service scrutiny of platform dominance affects auction dynamics here.
- Puzzle:Match-three and logic mechanics with fragmented 3-5 minute sessions. Hyper-casual publishers in Nizhny Novgorod clusters monetize through high-frequency interstitial rotation. Female-skewing demographics attract FMCG and retail advertisers.
- Racing:Speed-focused mechanics with natural billboard placement opportunities and sustained visual attention. Moscow studios dominate production.
- Role-Playing:Narrative-driven progression systems with immersive world-building enabling deep brand integration. VK's social identity graphs support targeting in fantasy and historical subgenres.
Action titles anchor volume concentration. Role-Playing gains share fastest through deepening session economics.
Device Type:
Volume distribution across hardware ecosystems reflects infrastructure maturity and SDK availability under sanctions constraints.
- Mobile:Smartphone and tablet platforms commanding absolute impression volume through freemium distribution. Federal Law No. 242-FZ localization requirements fragment measurement stack options, pushing publishers toward Yandex and VK SDKs. 5G rollout in Moscow and Saint Petersburg enables richer creative payloads.
- Console:PlayStation and Xbox platforms with gated inventory through platform-holder ad networks. Premium CPMs reflect affluent user bases and limited supply.
- PC:Desktop and laptop gaming through standalone clients and browser-based titles. Steam distribution dominance complicates direct publisher-advertiser relationships.
- VR:Immersive headset platforms with experimental ad formats in early deployment. Yekaterinburg developers test server-side insertion to bypass device-level dependencies.
Mobile inventory dominates absolute scale. VR climbs fastest from negligible base through cloud gaming infrastructure convergence.
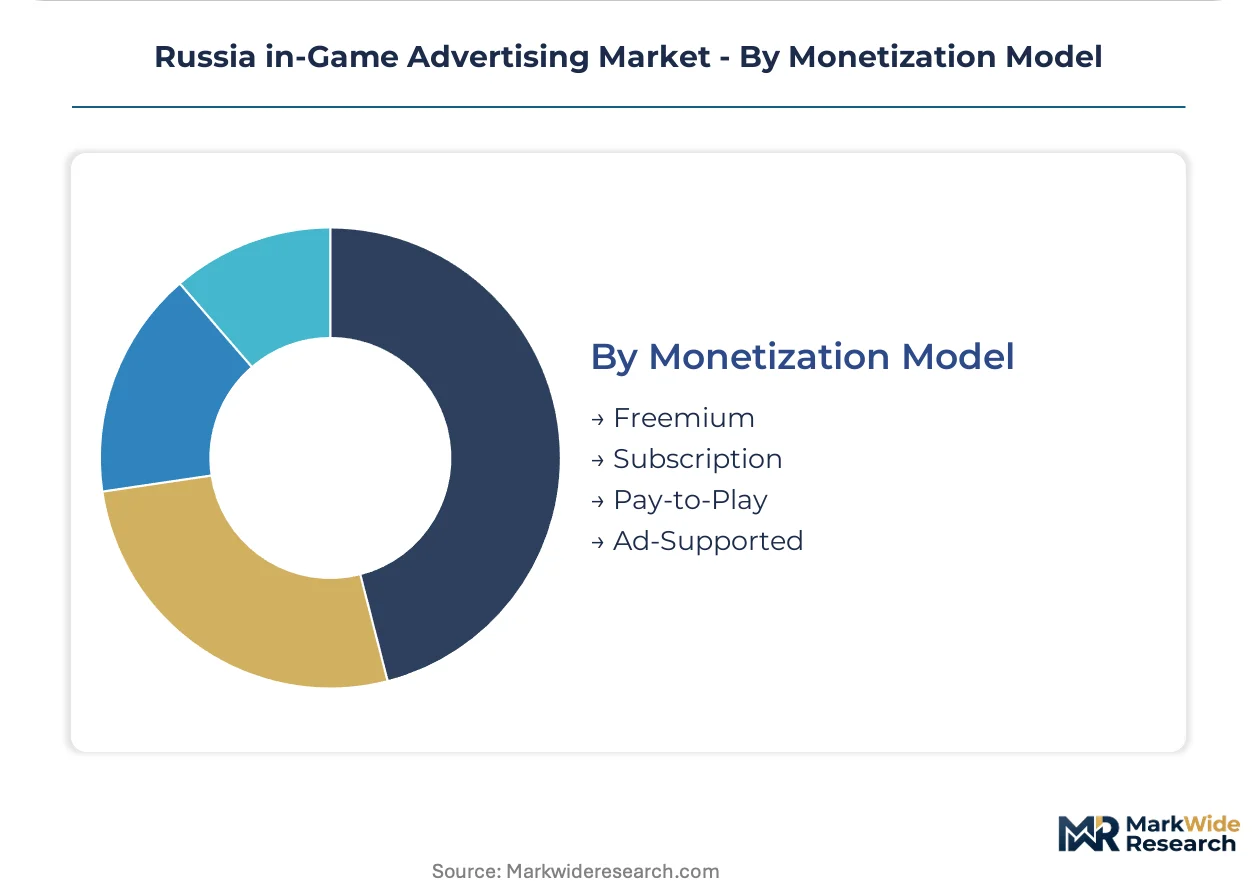
Monetization Model:
Customer type and payment psychology shape ad load tolerance and brand safety requirements.
- Freemium:Free-to-download titles monetizing through hybrid ad and in-app purchase revenue. Rewarded video mechanics dominate, with Central Bank of Russia monitoring virtual goods transaction flows. This model concentrates in mobile-first publishers across the Moscow-Saint Petersburg corridor.
- Subscription:Recurring fee models offering ad-free tiers or limited ad loads. PC and console platforms deploy these for brand safety-sensitive advertisers.
- Pay-to-Play:Upfront purchase models with minimal or no advertising. Premium positioning limits addressable inventory.
- Ad-Supported:Free access funded entirely through advertising revenue, common in emerging market mobile titles and cloud streaming services.
Freemium structures hold the installed base. Ad-Supported models expand most quickly through cloud gaming subscription tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Advertiser spending pools concentrate in Russia's two dominant metropolitan corridors where developer studios cluster and media agencies maintain specialized gaming divisions. Moscow and Saint Petersburg anchor absolute demand volume through co-located creative production and platform headquarters.
Moscow
FMCG and financial services advertisers drive premium inventory demand through media agencies bundling creative services with placement access. Roskomnadzor enforcement of Federal Law No. 242-FZ compels data localization infrastructure investment from domestic platforms. The Moscow-Saint Petersburg corridor concentrates Yandex and VK platform headquarters alongside action and racing genre studios.
Saint Petersburg
Hyper-casual publishers generate high-frequency interstitial inventory through fragmented session mechanics in match-three titles. Federal Antimonopoly Service scrutiny of digital advertising auction dominance affects platform pricing power here. Kazan-Nizhny Novgorod corridor developers source creative adaptation services from Saint Petersburg production houses.
Kazan
Puzzle genre specialists monetize through female-skewing demographics attracting retail and cosmetics advertisers. The country's national data protection regulator mandates server location certification for behavioral signal processing. Emerging developer clusters offer lower talent costs than capital cities while maintaining advertiser relationships through regional media buyers.
Yekaterinburg
Mid-size publishers adopt server-side ad insertion architectures to bypass device-level SDK dependencies under sanctions constraints. Central Bank of Russia monitoring of virtual goods transaction flows complicates cross-border revenue recognition for foreign publishers testing this market. Cloud gaming infrastructure trials converge with 5G rollout enabling richer creative payloads.
Novosibirsk
Experimental VR and cloud-streamed ad formats attract developers seeking to circumvent Western attribution tool scarcity. Domestic measurement alternatives lag on probabilistic matching, degrading campaign optimization for advertisers entering through regional agencies. Technical universities supply programmatic talent to local publishers rebuilding tech stacks around localized identity graphs.
Russia in-Game Advertising Market Competitive Landscape
Channel-controlling players compete with product-specialist players for inventory access and advertiser relationships across Russia's fragmented ad tech infrastructure. Domestic platforms leverage vertical integration from identity graphs to placement delivery while foreign providers face regulatory exclusion. Three archetypes dominate: vertically integrated domestic platforms, genre-specialist publishers with proprietary ad tech, and regional distributors rebuilding around localized SDKs. Competitive moves center on infrastructure localization partnerships and measurement stack substitution.
Within the platform tier, Yandex and VK occupy positions shaped by regulatory protection under data localization mandates. Lesta Games exemplifies the genre-specialist archetype through captive ad tech development. These three entities anchor the competitive structure as foreign demand-side platforms forfeit inventory access absent domestic server infrastructure.
| Leading Market Players |
|---|
| Yandex |
| VK |
| Lesta Games |
| Mail.ru Group |
| Odnoklassniki |
| Astrum Entertainment |
| SoftClub |
| Innova |
| Buka |
| Others |
Pricing and Supply Chain Analysis
Ad tech infrastructure concentration in Moscow and Saint Petersburg developer clusters funnels margin pools toward platforms controlling localized identity graphs and measurement stacks under Federal Law No. 242-FZ compliance requirements. SDK licensing fees and server-side insertion technology costs cascade through publisher monetization decisions, compressing yields for mid-size studios outside capital corridors.
Pricing Analysis
CPM-plus-performance contracts with completion-rate indexation dominate video inventory transactions, with Moscow-based media agencies negotiating guarantees above eighty percent in action and racing titles. Price differentiation rests on brand safety verification depth and post-campaign attribution granularity, with FMCG advertisers paying premiums for audited placement taxonomies. Pricing pressure stems from sanctions-driven scarcity of Western measurement tools forcing publishers toward unproven domestic alternatives with degraded optimization. Hyper-casual publishers in Nizhny Novgorod clusters exhibit highest price sensitivity due to thin per-session economics, while console platform-holders maintain lowest sensitivity through gated inventory scarcity.
Supply Chain Analysis
Supply-chain finance facilities from domestic banks extend payment terms for Yekaterinburg and Novosibirsk publishers rebuilding tech stacks around localized SDKs. Hardware supply draws from China for edge computing infrastructure, South Korea for display panel components in VR headset development, and domestic Russian foundries for server fabrication under import substitution mandates. Single-source vulnerability concentrates in cloud gaming edge nodes where 5G rollout dependencies create chokepoints. Distribution runs through programmatic auction layers controlled by Yandex and VK demand-side platforms, with direct publisher-advertiser relationships fragmenting outside Moscow-Saint Petersburg corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
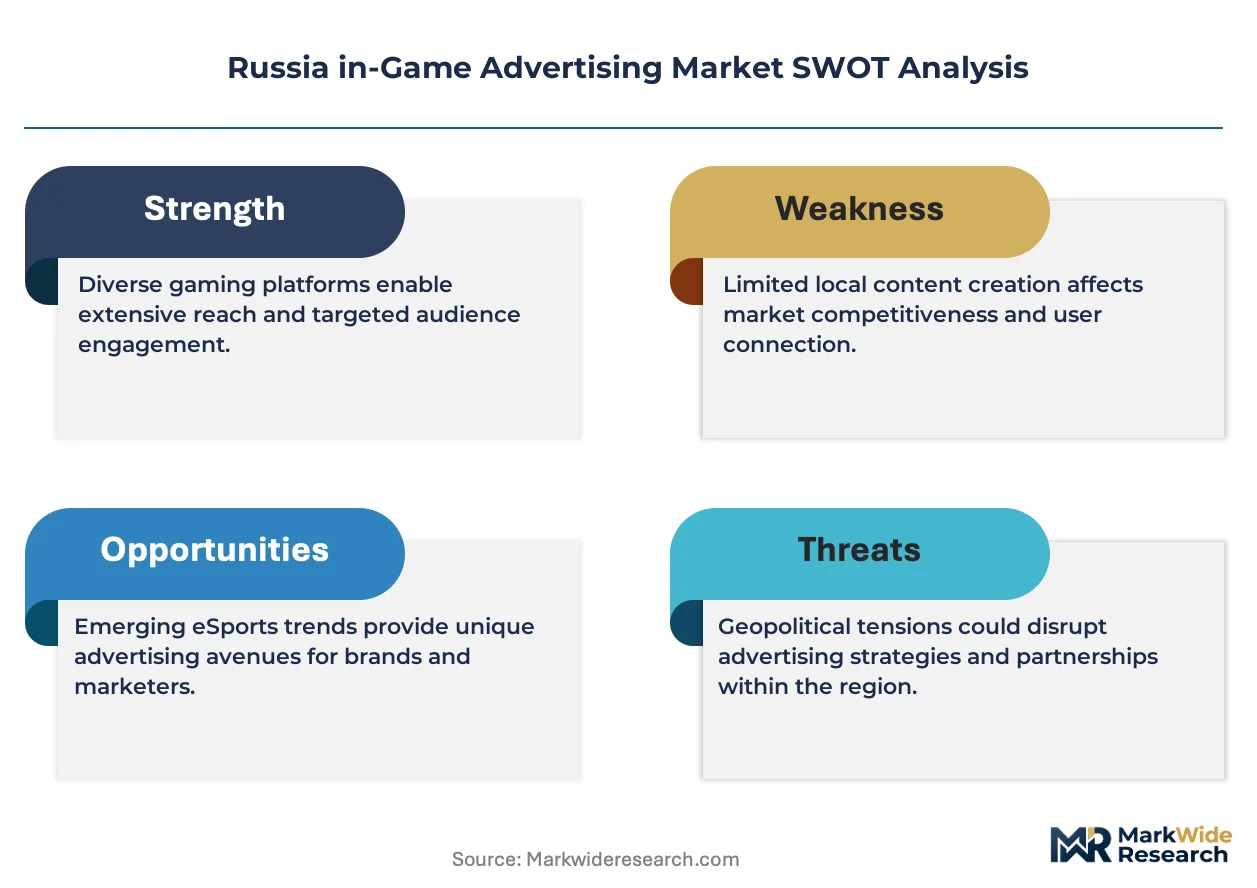
Russia's in-game advertising landscape fragments along regulatory and technical fault lines, with Federal Law No. 242-FZ data localization creating protected territory for domestic platform builders while foreign competitors forfeit inventory access. Advertiser demand for brand safety verification and completion-guaranteed video formats generates niche openings for specialized measurement providers.
For Market Incumbents: Build captive ad serving infrastructure moats through proprietary SDK development and server-side insertion patents. Yandex and VK should deepen backward integration into cloud gaming infrastructure to capture emerging ad-supported subscription tiers. Lesta Games must defend genre-specialist positioning through endemic advertiser category lock-in for naval combat titles. Threat from attribution technology gaps in domestic alternatives demands urgent investment in probabilistic matching R&D. For New Entrants and Emerging Players: Kazan-Nizhny Novgorod corridor underpenetration offers white-space access to puzzle genre specialists serving female-skewing retail and cosmetics advertisers. Yekaterinburg cloud gaming infrastructure trials present second entry point for server-side ad insertion architects circumventing device-level SDK dependencies. Novosibirsk technical university partnerships supply programmatic talent pipelines for publishers rebuilding around localized identity graphs. Go-to-market angle should emphasize creative asset localization services bundled with placement access. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-core genre publishers possessing proprietary ad tech but lacking measurement stack parity. Long-term viability hinges on five-to-ten year regulatory protection durability under data localization mandates. Acquisition target archetype: developer studios with captive advertiser relationships in endemic categories and server-side insertion capability. Signal to watch is Roskomnadzor enforcement intensity against foreign platform workarounds.| Strategic Initiative | Industry Significance |
|---|---|
| SDK Localization Partnership | Yandex and VK platforms capture inventory that Western tools cannot legally process under Federal Law No. 242-FZ. |
| Server-Side Ad Insertion Deployment | Mid-size publishers in Yekaterinburg bypass device-level dependencies collapsing competitive moats of deep device graph integrations. |
| Creative Asset Localization Pipeline | Saint Petersburg production houses bundle adaptation services with inventory access justifying premium pricing for Moscow FMCG clients. |
| Cloud Gaming Infrastructure Investment | 5G rollout convergence enables richer creative payloads without SDK dependency on player devices in Novosibirsk trials. |
| Measurement Stack Substitution Program | Domestic alternatives accelerate substitution of Western attribution tools under sanctions-driven scarcity constraints. |
Research Methodology
The analysis maps mobile, console, PC, and VR platform sub-sectors, each validated through mobile game publishers, media agency trading desks, ad tech platform engineers, and Roskomnadzor compliance officers. Primary interviews combined with secondary validation from SEC filings of listed gaming companies, Sensor Tower mobile revenue estimates, customs records of server hardware imports, and Federal Antimonopoly Service digital advertising market reviews. Bottom-up publisher revenue aggregation triangulates against top-down advertiser spending estimates from media agency billing disclosures.
The assumption-set holds Federal Law No. 242-FZ enforcement intensity, sanctions regime durability, and 5G infrastructure rollout pace as fixed baseline conditions while varying mobile versus console platform mix and freemium versus subscription monetization model penetration. Segmentation dimensions span ad format type, game genre taxonomy, device ecosystem, and monetization model architecture across the projection horizon. CAGRs derive from installed base growth curves, session length trend extrapolation, and CPM trajectory modeling incorporating brand safety premium expansion.
The forecast holds incumbent behavior within observed patterns; aggressive infrastructure localization moves by foreign platform archetypes or accelerated domestic alternative development would shift outcomes. Macroeconomic ruble volatility, intensified Roskomnadzor enforcement, or breakthrough cloud gaming technology adoption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Mobile MOBA Games Market
Gaming
North America Casino Gambling Market
Gaming
North America Gaming Market
Gaming
Global NFT Gaming Market
Gaming
Mobile Shooter Market
Gaming
Mobile Gaming Market
Gaming
3D Gaming Technology Market
Gaming
Japan Virtual Reality Gaming Market
Gaming
VR Gaming Controller Market
Gaming
Asia-Pacific Casino Gambling Market
Gaming
Game Engine Management Market
Gaming
Virtual Sports Market
Gaming
Global Tarot Cards Market
Gaming
China Gaming Headsets Market
Gaming
Playstation Network (PSN) Market
Gaming
Online Casino Market