
 Videogames Market | 2026-2036
Videogames Market Size, Share, and Industry Trends Forecast 2026-2036
Videogames Market Analysis
The education and enterprise training vertical is broadening as immersive simulations replace traditional learning modules. Sony Interactive Entertainment leverages its proprietary hardware ecosystem to control premium console experiences. Tencent Interactive Entertainment anchors its position through dominant mobile publishing networks across Asia. Microsoft Gaming competes via cloud infrastructure integration that extends reach beyond device ownership.
Videogames constitute interactive software applications rendered through dedicated hardware or general-purpose computing devices, requiring real-time graphics processing, networked multiplayer architecture, and persistent content delivery systems designed for entertainment, competition, or simulation purposes. Mobile Games now capture the largest revenue pool due to frictionless distribution and microtransaction models, while VR Games represent the fastest-expanding segment as headset costs decline and haptic feedback improves. Subscription Services within distribution channels concentrate recurring revenue and reduce customer acquisition volatility for publishers.
The ESRB rating system and China's NPPA approval process govern content accessibility and release timing, directly shaping product localization investments and market entry sequencing for international studios. GDPR and the EU AI Act impose consent frameworks and algorithmic transparency requirements on player data analytics and matchmaking systems. Stakeholders must monitor regulatory divergence between major markets when architecting global live-service strategies and compliance budgets.
Market Dynamics
Cloud gaming infrastructure is compressing hardware ownership requirements while GDPR and the EU AI Act impose algorithmic transparency mandates on live-service matchmaking and player analytics systems.
Growth Catalysts
- Cloud streaming protocols:Low-latency edge computing eliminates download friction for casual players, expanding addressable audiences beyond console households.
- China's tier-one city clusters:Mobile esports viewership in Shanghai, Beijing, and Shenzhen drives live-streaming monetization innovations that publishers replicate across Asia.
- EU AI Act compliance frameworks:Mandatory algorithmic disclosure for recommendation engines creates competitive differentiation for transparent publishers in European markets.
Market Restraints
- GPU supply concentration:Foundry capacity constraints in Taiwan and South Korea limit hardware availability for VR headset production.
- NPPA approval timelines:China's content review process delays international studio releases by 6-18 months, compressing monetization windows.
- Substitution by short-form video:TikTok and YouTube Shorts capture fragmented attention spans that previously sustained mobile game sessions.
Strategic Opportunities
- Enterprise simulation contracts:Defense contractors and medical device manufacturers procure Unreal Engine-based training environments at premium licensing rates.
- India's PLI scheme for electronics:Manufacturing incentives attract assembly operations for controllers and peripherals serving domestic mobile gaming growth.
- Neural haptic convergence:Integration of EMG sensors with force-feedback gloves enables proprioceptive control schemes for rehabilitation gaming applications.
Industry Challenges
- Live-service engineering talent scarcity:Backend infrastructure specialists capable of million-concurrent-player architectures command compensation premiums that mid-size studios cannot match.
- Cross-platform certification complexity:Sony, Microsoft, and Nintendo maintain divergent technical requirement checklists that extend QA cycles for multi-platform releases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Videogames Market |
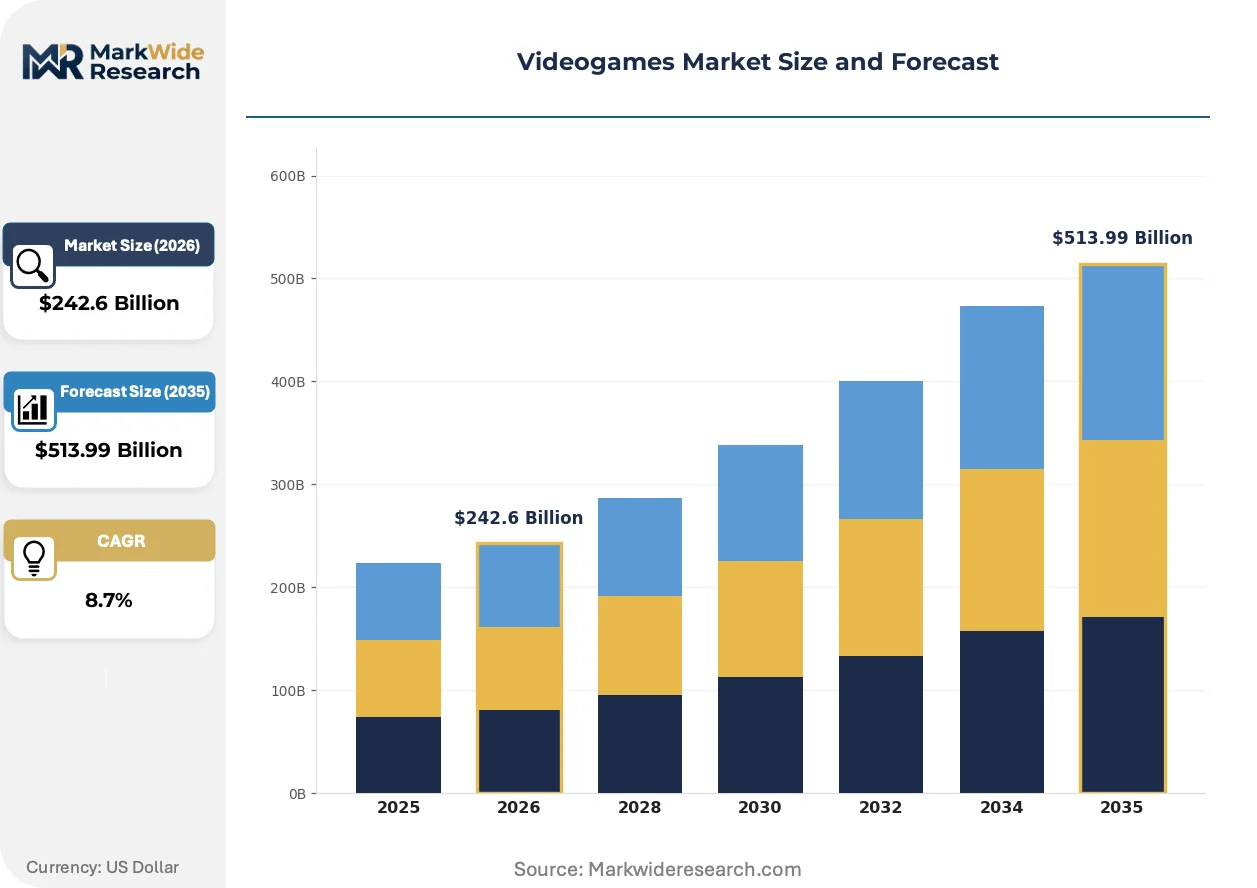
| Market Size in 2026 | $242.6 Billion |
| Market Size in 2035 | $513.99 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Console Games, PC Games, Mobile Games, VR Games End User: Casual Gamers, Hardcore Gamers, Professional Players, Streamers Distribution Channel: Digital Downloads, Retail Stores, Subscription Services, In-Game Purchases Game Genre: Action, Adventure, RPG, Simulation |
| Companies Covered | Sony Interactive Entertainment, Tencent Interactive Entertainment, Microsoft Gaming, NetEase Games, Nintendo, Electronic Arts, Valve Corporation, Epic Games, Take-Two Interactive, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Videogames Market Emerging Trajectories
Generative AI tools are compressing asset production pipelines while regulatory scrutiny of loot box mechanics forces monetization model reinvention across premium and free-to-play segments.
Neural radiance fields (NeRF) are electrifying environmental rendering by converting 2D reference photography into explorable 3D spaces without manual modeling. Indie studios in Poland and Czechia adopt NeRF workflows to produce open-world density previously achievable only by AAA teams. This democratization is electrifying competitive pressure on established publishers to reduce production headcounts or accelerate output frequency.
The EU AI Act's risk classification system mandates human oversight for matchmaking algorithms that profile player behavior patterns. Publishers serving European markets must document decision logic for automated content recommendations and implement opt-out mechanisms. Live-service titles with sophisticated engagement optimization face immediate compliance costs, while smaller studios with simpler systems gain relative regulatory agility.
Subscription fatigue among core gamers is fragmenting spending across multiple services rather than consolidating loyalty. Xbox Game Pass, PlayStation Plus, and Netflix Games compete for fixed monthly budgets, forcing publishers to negotiate revenue-share terms that prioritize catalog breadth over exclusive depth. This behavior shift is most pronounced in Germany and France, where household entertainment subscriptions already saturate disposable income allocations.
Videogames Market Segmentation
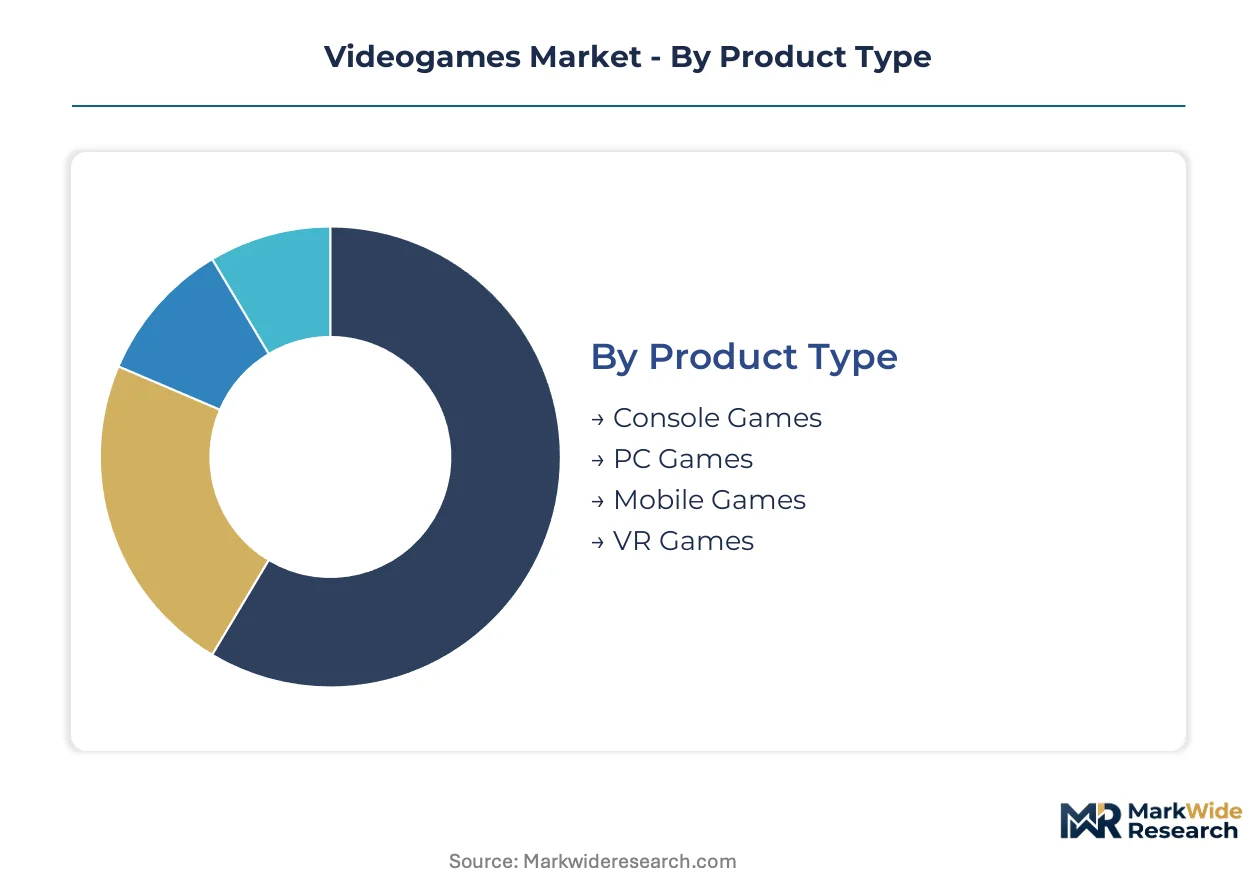
Videogames segmentation reveals how hardware form factors, player motivation, and monetization mechanics fragment revenue capture across the industry. Publishers calibrate development budgets and distribution strategies against these axes to optimize lifetime value per player cohort.
Product Type:
Rendering architecture and input modality define technical requirements and addressable audience scale for each hardware platform.
- Console Games:Closed-system optimization for Sony, Microsoft, and Nintendo hardware enables consistent performance targets that reduce QA complexity. Demand concentrates in North American and Japanese households where premium upfront pricing sustains AAA production budgets and exclusive content licensing.
- Mobile Games:Touch-based interfaces and ARM processor constraints drive asynchronous multiplayer designs and gacha monetization systems. China's tier-one cities anchor revenue concentration, where WeChat and TikTok integration accelerates viral distribution and microtransaction conversion rates.
- PC Games:Open hardware configurations support modding ecosystems and esports competitive integrity through standardized peripherals. Steam and Epic Games Store distribution eliminates physical retail margins while enabling direct developer-player relationships.
- VR Games:Spatial computing requirements and motion controller tracking demand specialized engine optimization for presence preservation. Enterprise training contracts in German automotive and Japanese healthcare sectors subsidize consumer headset affordability improvements.
Mature deployment sits with Console Games. Newer deployment is concentrated in VR Games.
End User:
Session length tolerance and social motivation stratify monetization potential across player commitment levels.
- Casual Gamers:Fragmented attention spans and low switching costs favor hyper-casual titles with rewarded video advertising and minimal tutorial friction. India's Tier-2 and Tier-3 cities drive volume expansion as affordable smartphones penetrate first-time gamer demographics.
- Hardcore Gamers:Deep system mastery preferences and community identity formation sustain premium pricing for complex RPGs and competitive shooters. Discord server integration and content creator co-development programs lock in engagement duration that supports live-service roadmaps.
- Professional Players:Tournament prize pools and streaming revenue dependency create hardware sponsorship ecosystems around peripheral manufacturers. Korean PC bang culture and Chinese esports academies institutionalize skill development pipelines that feed organized competition circuits.
- Streamers:Audience retention metrics and platform algorithm favorability dictate game selection that balances visual spectacle with narrative accessibility. Twitch and YouTube revenue-share negotiations increasingly influence publisher marketing allocation toward streamer-exclusive content drops.
Revenue per user peaks with Professional Players. Volume expansion is accelerating fastest among Casual Gamers.
Distribution Channel:
Customer acquisition cost and lifetime value predictability vary sharply across ownership and access models.
- Digital Downloads:Direct storefront relationships capture full margin while enabling dynamic pricing and regional differentiation. Steam's recommendation algorithm and seasonal sale events concentrate discovery power that shapes indie studio viability.
- Retail Stores:Physical inventory risk and shelf space negotiation favor established franchises with predictable sell-through velocity. Collector's edition packaging and preorder incentive structures sustain premium pricing for dedicated fanbases in Japanese and North American markets.
- Subscription Services:Recurring revenue aggregation reduces customer acquisition volatility while compressing per-title revenue share for publishers. Xbox Game Pass and PlayStation Plus catalog competition forces exclusivity negotiations that prioritize day-one availability over back catalog depth.
- In-Game Purchases:Battle pass systems and cosmetic economies extend monetization beyond initial transaction through progression-gated content release. Fortnite and Genshin Impact demonstrate how seasonal content cadences sustain concurrent player peaks that drive viral acquisition.
Margin stability favors Subscription Services. Transaction volume concentrates in In-Game Purchases.
Game Genre:
Mechanical complexity and narrative ambition determine team size requirements and production timeline risk.
- Action:Reflex-based combat systems and spectacle-driven set pieces demand animation polish and physics simulation investment that extends development cycles. FromSoftware's Elden Ring demonstrates how difficulty reputation builds franchise loyalty that sustains premium pricing without multiplayer infrastructure.
- Adventure:Environmental storytelling and puzzle design prioritize art direction and level scripting over systems engineering. Nintendo's Zelda franchise anchors this segment through hardware-selling exclusivity that justifies decade-long development timelines.
- RPG:Branching narrative trees and character progression systems require writing team scale and localization coordination that fragments release timing across regions. Larian Studios' Baldur's Gate 3 illustrates how early access funding models de-risk production while building community investment prior to full launch.
- Simulation:Systems fidelity and emergent behavior design attract modding communities that extend commercial lifespan without ongoing developer support. Farming Simulator and Microsoft Flight Simulator leverage licensed equipment partnerships that reinforce authenticity credentials for enthusiast demographics.
Production maturity sits with Action. Creative risk tolerance is expanding fastest in Simulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Hengqin New Area tax-incentive zone concentrates cloud gaming infrastructure investment, while Japan's Kansai Innovation International Strategic Special Zone subsidizes VR training simulator development. These designated economic zones accelerate publisher clustering through preferential corporate tax rates and import duty exemptions on development hardware.
United States
Console hardware demand concentrates in suburban households with disposable entertainment budgets exceeding three hundred dollars annually. The FTC scrutinizes subscription service cancellation flows under click-to-cancel rulemaking, forcing storefront interface redesigns. Austin and Los Angeles anchor development studio clusters where Unreal Engine technical artists command premium compensation.
China
Mobile esports viewership in Shanghai, Beijing, and Shenzhen drives live-streaming monetization innovations that publishers replicate across Asia. The NPPA approval process delays international studio releases by six to eighteen months, compressing monetization windows. Chengdu's Tianfu Software Park hosts middleware specialists serving domestic RPG localization pipelines.
Japan
Hardware-software integration expertise sustains premium pricing for exclusive franchise releases. METI's Cool Japan Fund subsidizes cultural content export initiatives that reduce overseas marketing costs for domestic publishers. Tokyo's Shibuya and Osaka's Umeda districts concentrate arcade location-test facilities where mechanics undergo pre-release refinement.
Germany
Subscription fatigue fragments spending across multiple services rather than consolidating loyalty in core gamer demographics. The EU AI Act mandates algorithmic disclosure for recommendation engines, creating compliance differentiation for transparent publishers. Hamburg and Munich host simulation specialists supplying automotive and medical training contracts at premium licensing rates.
South Korea
PC bang culture institutionalizes skill development pipelines feeding organized esports competition circuits. The Korea Creative Content Agency provides export financing for publishers targeting Southeast Asian mobile markets. Seoul's Gangnam district concentrates streaming talent agencies negotiating revenue-share terms with platform operators.
Videogames Market Vendor Landscape
Top-tier vendors anchor hardware-software integration, while mid-tier publishers compete through genre specialization and regional licensing deals. The vendor base stratifies across platform holders controlling distribution infrastructure, multinational publishers with diversified genre portfolios, and independent studios leveraging accessible engine tools. Three archetypes dominate: ecosystem gatekeepers monetizing through store commissions, content aggregators negotiating subscription catalog placement, and live-service specialists optimizing engagement mechanics. Competitive moves concentrate on exclusive content acquisition and cloud infrastructure partnerships that extend reach beyond device ownership.
Within the ecosystem gatekeeper tier, Sony Interactive Entertainment and Microsoft Gaming represent contrasting hardware-cloud strategies, while Tencent Interactive Entertainment anchors mobile publishing networks across Asia. These three entities exemplify how platform control, infrastructure leverage, and regional distribution dominance constitute distinct competitive vectors. Their positioning illustrates the market's structural tension between closed-system optimization and open-access expansion.
| Leading Market Players |
|---|
| Sony Interactive Entertainment |
| Tencent Interactive Entertainment |
| Microsoft Gaming |
| NetEase Games |
| Nintendo |
| Electronic Arts |
| Valve Corporation |
| Epic Games |
| Take-Two Interactive |
| Others |
Supply Flow & Price Mechanics
EU AI Act algorithmic disclosure mandates gate qualified supply partnerships and premium-tier pricing access for publishers serving European markets. Publishers lacking transparent matchmaking documentation face exclusion from revenue-sharing negotiations with subscription platforms, compressing margins for non-compliant studios.
Pricing Analysis
Short lead-time certification for NPPA approval commands premium pricing from international studios seeking simultaneous global launches, while spot inventory of unapproved titles trades at distressed valuations in gray markets. Three-tier pricing structure across premium, standard, and economy levels stratifies by content rating tier and localization depth. Pricing pressure stems from subscription service revenue-share compression as Xbox Game Pass and PlayStation Plus consolidate buyer power. Casual mobile gamers exhibit highest price sensitivity through ad-supported tolerance, while hardcore PC players sustain premium pricing for mod-compatible releases.
Supply Chain Analysis
Backend engineering talent scarcity in Taiwan and South Korea constrains foundry capacity allocation for VR headset GPU production. Semiconductor fabrication draws from TSMC and Samsung foundries, while rare earth magnet supply for haptic controllers rests on Chinese processing facilities. Single-source vulnerability concentrates in advanced node lithography equipment subject to export control restrictions. Distribution runs through cloud edge nodes operated by Microsoft Azure and Amazon Web Services, bypassing physical retail infrastructure for streaming titles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The videogames market sits in a technology-transition phase where cloud streaming infrastructure replaces legacy hardware-ownership models as the primary access mechanism.
For Market Incumbents: Extend exclusive content licensing windows to defend against subscription catalog commoditization threatening franchise monetization. Fortify first-party studio acquisitions to secure IP pipelines as Netflix Games and Amazon Luna emerge as distribution threats. Deepen backward integration into cloud edge infrastructure to reduce platform dependency for live-service delivery. For New Entrants and Emerging Players: India's Tier-2 and Tier-3 city casual gamers represent the most penetrable buyer archetype for hyper-casual titles with rewarded video monetization. Enterprise simulation contracts in German automotive and Japanese healthcare sectors offer premium licensing white space outside saturated consumer markets. Deploy NeRF-based asset pipelines to compress production timelines and compete with established publisher output frequency. For Investors and Strategic Acquirers: NPPA approval queue acceleration is the leading indicator that Chinese market access premiums will compress for international publishers. Long-term viability across the analysis window favors studios with diversified genre portfolios and regional licensing flexibility. Monitor live-service engineering talent migration patterns as inflection signals for backend infrastructure acquisition targets.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Infrastructure Partnership | Microsoft Azure integration extends reach beyond console households into browser-based casual audiences. |
| Exclusive Content Acquisition | Day-one Game Pass placement secures subscriber retention against PlayStation Plus catalog competition. |
| NeRF Asset Pipeline Deployment | Polish and Czechia indie studios leverage automated 3D generation to match AAA open-world density. |
| Enterprise Simulation Licensing | Unreal Engine training contracts with defense contractors subsidize consumer VR headset affordability. |
| Regulatory Compliance Certification | EU AI Act algorithmic documentation enables European subscription platform revenue-share negotiations. |
Methodological Framework
SEC 10-K filings, NPPA approval databases, and hyperscaler capex disclosures formed the secondary backbone for publisher revenue attribution and infrastructure investment tracking. Primary interviews with live-service engineering directors, platform partnership leads, and esports tournament operators combined with secondary validation through Steam player concurrency data and App Annie mobile revenue estimates. Bottom-up title-level monetization modeling and top-down regional market sizing were triangulated for consistency.
Historical trendline analysis of console hardware cycle lengths and mobile esports viewership growth rates informed projection assumptions across the modeling period. Segmentation dimensions modeled include hardware platform, player motivation archetype, distribution channel, and monetization mechanic. CAGRs were derived from regression analysis of installed base expansion and average revenue per user trajectories, incorporating cloud streaming adoption curves and regulatory approval timeline volatility as industry-specific inputs.
Revisions become necessary when NPPA approval timelines extend beyond historical ranges or EU AI Act enforcement intensity escalates beyond documented frameworks. Forecasts reflect assumptions regarding GPU foundry capacity allocation and subscription service pricing power consolidation. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Global Battle Royale Games Market
Gaming
Global Subscription-Based Gaming Market
Gaming
Mobile Game Software Market
Gaming
Video Game Software Market
Gaming
Global Esports Market
Gaming
North America in-Game Advertising Market
Gaming
Global Gaming Market
Gaming
Global Electronic Table Games (ETG) Market
Gaming
United Kingdom Online Gambling Market
Gaming
Gaming Gadgets Market
Gaming
South Korea Virtual Reality Gaming Market
Gaming
Social Gaming Market
Gaming
RPG Games Market
Gaming
Global NFT Gaming Market
Gaming
Australia Gaming Gadgets Market
Gaming
Southeast Asia Gaming Market