
 Global Subscription-Based Gaming Market | 2026-2036
Global Subscription-Based Gaming Market Size, Share, and Industry Trends Forecast 2026-2036
Global Subscription-Based Gaming Market Foresight
Cloud infrastructure engineering talent scarcity is unwinding capacity expansion timelines for several platform operators. Microsoft anchors its competitive position through Azure-powered cloud delivery networks spanning multiple continents. Sony Interactive Entertainment differentiates via exclusive content pipelines and proprietary console ecosystems. Nintendo specializes in family-oriented subscription tiers that leverage decades of intellectual property depth.
Subscription-based gaming delivers interactive entertainment through recurring payment models, typically requiring broadband throughput exceeding 25 Mbps for seamless cloud streaming and low-latency multiplayer synchronization. The primary commercial purpose centers on converting transactional game purchases into predictable recurring revenue streams while reducing customer acquisition costs. Console and PC platform types currently dominate revenue contribution, though cloud infrastructure is expanding addressable markets beyond hardware ownership barriers. Monthly subscription models sustain the largest subscriber bases, while freemium architectures capture emerging market segments with limited upfront payment capacity.
FCC broadband infrastructure standards in the United States, EU Digital Services Act transparency requirements, and China's MIIT content licensing protocols collectively shape market access conditions and operational compliance burdens across major territories. GDPR data residency rules and emerging AI Act provisions on algorithmic content curation are forcing platform operators to restructure backend architectures and user consent frameworks. Stakeholders must monitor regulatory fragmentation between data sovereignty regimes and content classification systems as they evaluate geographic expansion sequencing and partnership structures.
Market Dynamics
Cloud gaming infrastructure investments by telecommunications providers are compressing latency thresholds and expanding addressable markets beyond traditional console ownership barriers. Platform operators now compete on network edge placement and streaming codec efficiency rather than hardware exclusivity alone.
Growth Catalysts
- EU Digital Services Act transparency mandates:The regulation forces platform operators to disclose recommendation algorithms and content moderation practices, accelerating consumer trust formation in cross-border subscription services.
- 5G network densification in South Korea:Telecommunications infrastructure upgrades in metropolitan gaming clusters enable sub-20ms streaming latency, unlocking cloud-native multiplayer experiences previously confined to local hardware.
- Family-oriented content pipelines:Multi-generational intellectual property libraries attract household-wide subscription commitments, converting single-player purchases into recurring household revenue streams.
Market Restraints
- Cloud infrastructure engineering scarcity:Specialized talent shortages in distributed systems architecture unwind platform capacity expansion timelines and inflate compensation costs for critical hires.
- GDPR data residency fragmentation:Cross-border data handling requirements force redundant backend infrastructure deployments, raising operational complexity for services spanning multiple EU member states.
- Input cost volatility in semiconductor supply:GPU and specialized encoding chip pricing instability compresses hardware procurement margins for cloud data center operators.
Strategic Opportunities
- India's underpenetrated broadband markets:Fiber-to-the-home rollout acceleration in Tier-2 and Tier-3 cities creates first-mover positioning for localized cloud gaming infrastructure partnerships.
- EU AI Act algorithmic curation provisions:Compliance-driven transparency investments differentiate platforms in privacy-conscious European markets and preempt regulatory enforcement actions.
- Edge computing and AI upscaling convergence:Neural network-based frame generation at network edge nodes reduces bandwidth requirements, enabling streaming quality previously impossible at equivalent bitrates.
Industry Challenges
- Distributed systems engineering skill gaps:Platform operators struggle to hire sufficient talent capable of optimizing real-time packet routing across multi-continent server meshes.
- Content licensing complexity across territories:Fragmented intellectual property rights force redundant negotiation cycles and release window misalignment between regional markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Subscription-Based Gaming Market |
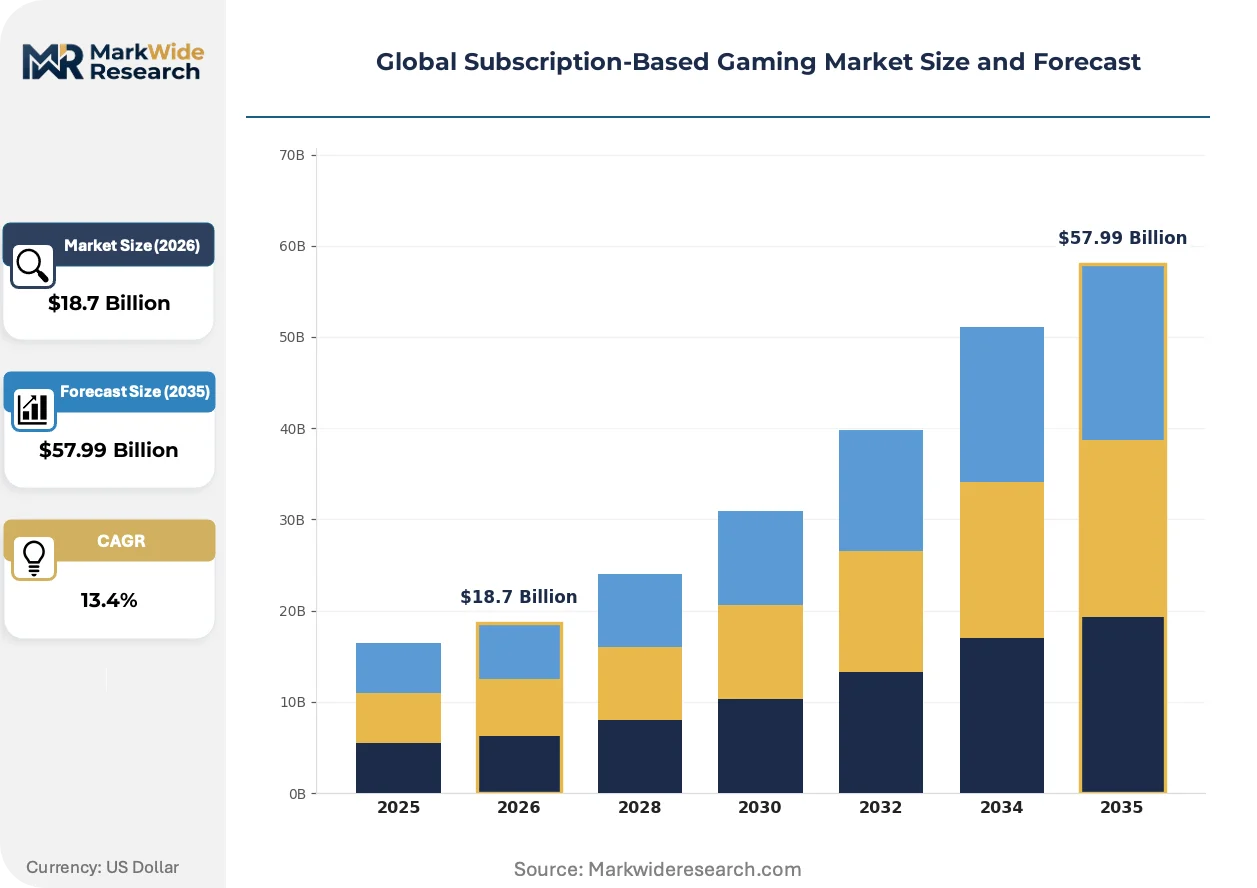
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $57.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Console, PC, Mobile, Cloud, Smart TV Subscription Model: Monthly, Annual, Freemium, Pay-as-You-Go, Lifetime Game Genre: Action, Role-Playing, Strategy, Sports, Simulation Customer Segment: Casual Players, Competitive Players, Streamers, Influencers, Collectors |
| Companies Covered | NetEase Games, Nintendo, Microsoft, Take-Two Interactive, Electronic Arts, Sony Interactive Entertainment, Roblox, Riot Games, Tencent, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Subscription-Based Gaming Market Shifts & Advancements
Streaming technology architectures are compressing the gap between cloud-rendered and locally-processed visual fidelity. Platform differentiation now centers on predictive input buffering and dynamic bitrate adaptation rather than raw server capacity.
AI-driven neural upscaling is miniaturizing bandwidth requirements for equivalent visual quality. Mid-tier internet service providers in Brazil and Mexico are adopting the technology to compete with fiber incumbents. The compression is expanding addressable subscriber bases into markets previously excluded by infrastructure constraints.
GDPR's algorithmic transparency provisions are forcing platform operators to restructure content recommendation engines. Backend engineering teams must now document decision logic for regulatory audit trails. Services targeting Germany and France face the steepest compliance retrofit costs.
Household subscription consolidation is displacing individual account proliferation. Family plan structures now bundle parental controls and usage analytics as standard features. Japan's console-centric urban markets exhibit the fastest migration toward multi-profile household billing.
Global Subscription-Based Gaming Market Segmentation
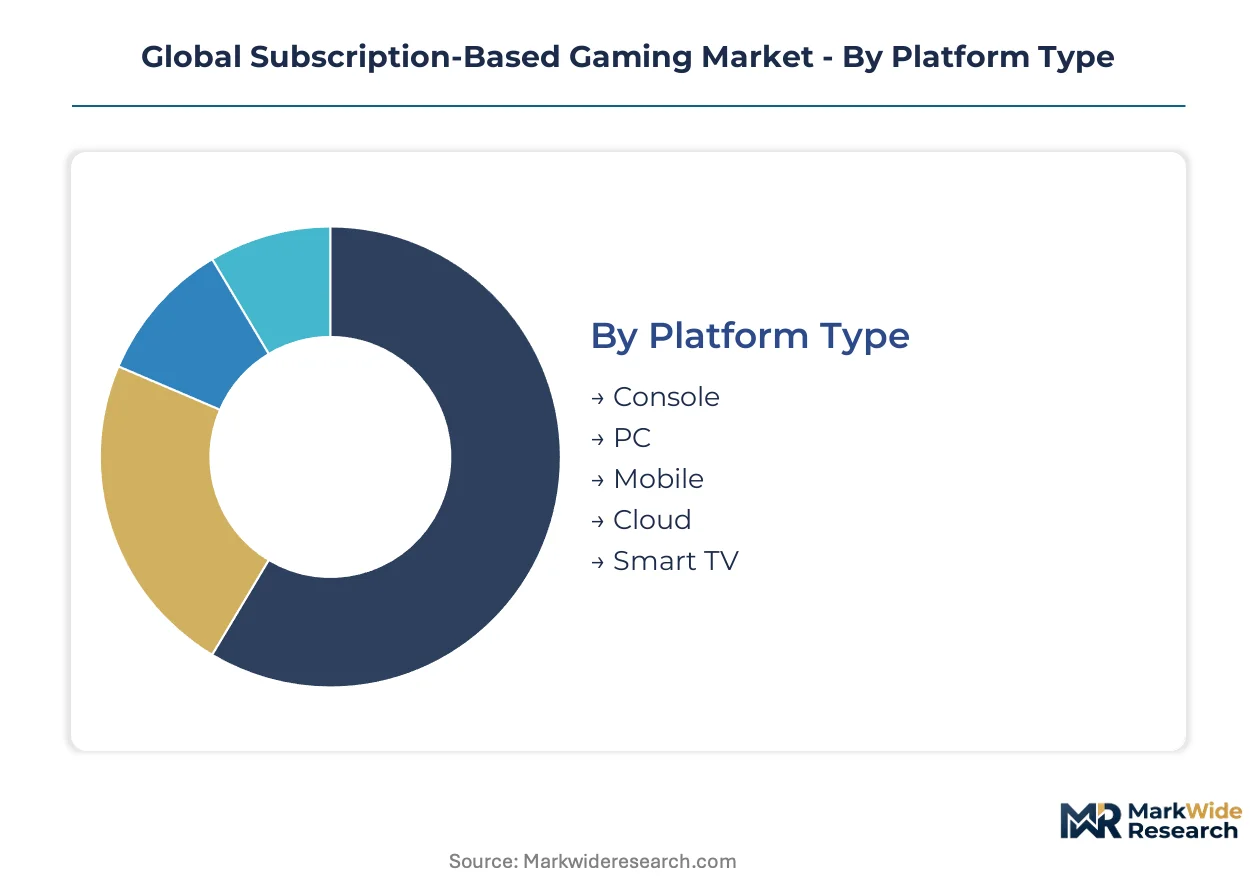
Platform type and subscription model configurations determine infrastructure investment requirements and margin profiles across operator portfolios. Genre preferences and customer segment behaviors shape content licensing strategies and churn prediction algorithms.
Platform Type:
Console and PC segments anchor developed-market revenue concentration, while cloud and mobile platforms unlock emerging-market expansion through reduced hardware ownership barriers.
- Console:Proprietary hardware ecosystems from Sony Interactive Entertainment and Microsoft Xbox sustain premium subscription attach rates through exclusive content pipelines. Demand concentrates in Japan's metropolitan gaming clusters and South Korea's console-adjacent living room setups, driven by household-wide entertainment consolidation and multi-generational intellectual property familiarity.
- Cloud:Browser-based and native app streaming eliminates upfront hardware procurement, expanding addressable markets to broadband-equipped households without dedicated gaming devices. Demand concentrates in Brazil and Mexico where telecommunications providers are deploying edge computing nodes to compress latency thresholds below 40ms.
- PC:Steam and Epic Games Store integrations support modding communities and esports tournament infrastructures, sustaining high-engagement subscriber cohorts with above-average session durations.
- Mobile:Touch-optimized control schemes and asynchronous multiplayer architectures capture commuter and fragmented attention contexts across India and Southeast Asian metropolitan corridors.
- Smart TV:Embedded application ecosystems from Samsung Tizen and LG webOS reduce friction for casual players seeking big-screen experiences without console investment.
Console commands the established base. The steepest expansion runs through Cloud.
Subscription Model:
Pricing architecture directly determines customer lifetime value curves and platform cash flow predictability across geographic markets with varying payment instrument penetration.
- Monthly:Low-commitment entry points minimize subscriber acquisition friction and support rapid experimentation with multiple platform catalogs. This structure dominates North American and Western European markets where credit card recurring billing infrastructure is mature.
- Freemium:Zero-cost onboarding with cosmetic and convenience microtransactions funds content pipeline investments in markets with limited disposable entertainment budgets. This model accelerates adoption across India's Tier-2 and Tier-3 cities where upfront payment capacity remains constrained.
- Annual:Prepaid commitments improve revenue visibility and reduce quarterly churn volatility for platform operators with established content release calendars.
- Pay-as-You-Go:Hourly or session-based billing aligns costs with actual usage for intermittent players seeking specific title access without subscription overhead.
- Lifetime:Single-payment perpetual access appeals to collector psychology and long-tail intellectual property preservationists in Japan's dedicated enthusiast communities.
Monthly subscriptions anchor current revenue stability. Freemium architectures are climbing the fastest in emerging-market penetration metrics.
Game Genre:
Genre mix shapes server infrastructure requirements, content update cadences, and community moderation staffing levels across platform operator organizations.
- Action:High-fidelity graphics pipelines and precise input latency requirements drive cloud edge placement investments and GPU allocation prioritization. Competitive multiplayer variants sustain esports viewership ecosystems in South Korea's PC bang culture and North American streaming platforms.
- Role-Playing:Narrative depth and character progression systems generate extended session durations and social sharing behaviors that reduce subscriber churn. Japanese developers leverage decades of intellectual property accumulation to differentiate subscription catalogs.
- Strategy:Asynchronous and real-time tactical gameplay attracts analytical player demographics with above-average age profiles and disposable income.
- Sports:Annual release cycles and licensed athlete rosters create predictable content refresh patterns aligned with broadcast sports calendars.
- Simulation:Creative toolsets and user-generated content pipelines extend platform engagement beyond commercial release schedules through community-driven expansion.
Action titles command the established base. Role-Playing is gaining share fastest through narrative-driven subscriber retention mechanics.
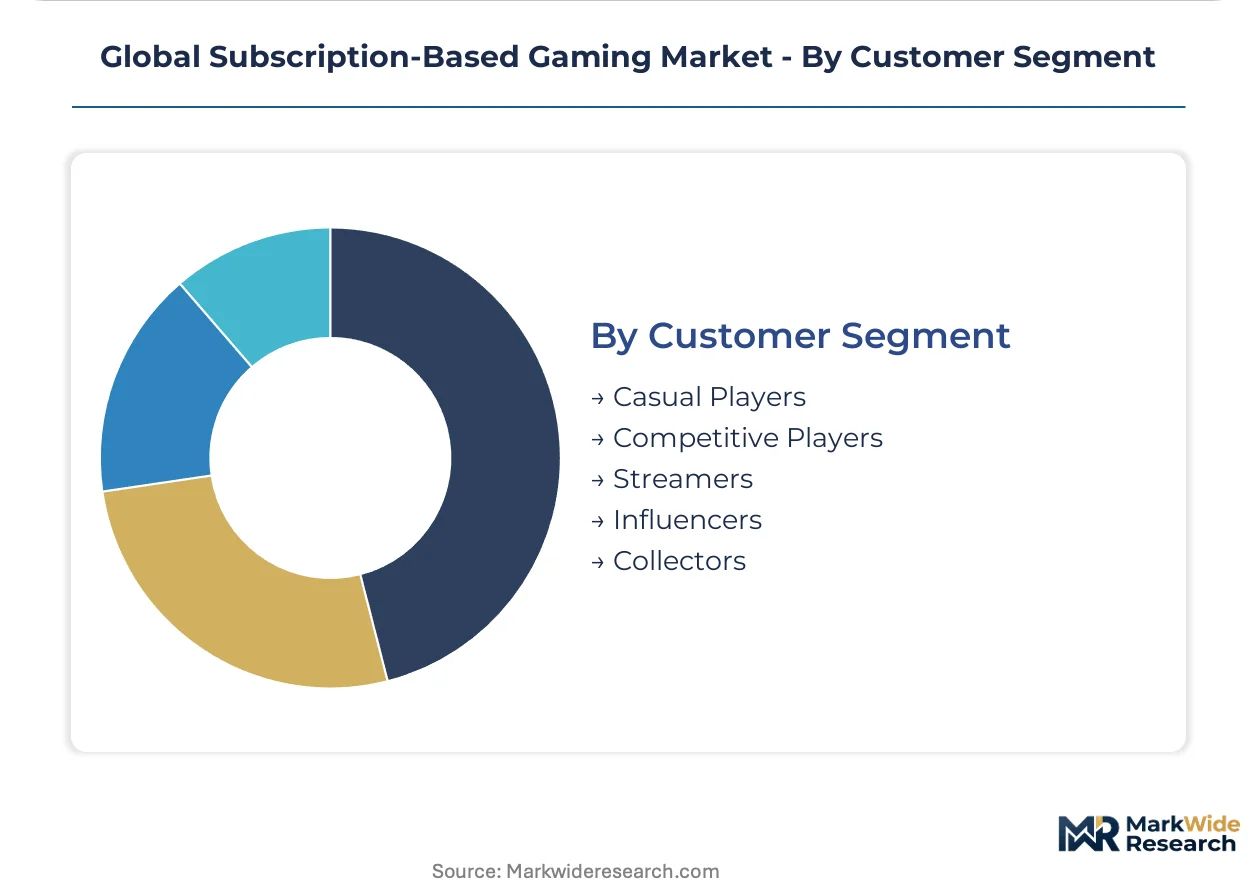
Customer Segment:
Behavioral segmentation determines content recommendation algorithm training data and personalized marketing automation triggers across platform CRM systems.
- Casual Players:Intermittent session patterns and genre-agnostic discovery preferences prioritize low-friction onboarding and instant save-state resumption. This cohort concentrates among mobile and Smart TV platform users in India's expanding broadband markets.
- Competitive Players:Ranked ladder systems and tournament infrastructure investments sustain engagement through skill validation and monetary prize pools. This segment drives premium subscription tier adoption in South Korea and North American metropolitan clusters.
- Streamers:Content creators require broadcast-quality capture integration and audience interaction tooling that platforms monetize through revenue-sharing arrangements.
- Influencers:Early access programs and exclusive cosmetic items leverage social proof mechanics to accelerate title adoption curves among follower networks.
- Collectors:Achievement systems and limited-edition digital asset ownership satisfy completionist psychology and secondary market speculation interests.
Casual Players command the established base. Competitive Players show the steepest expansion trajectory through esports ecosystem maturation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Japan's console-centric metropolitan clusters while cloud infrastructure investments compress margins in Brazil's emerging broadband corridors. Regulatory fragmentation between GDPR data residency regimes and FCC broadband standards forces divergent platform architectures across Atlantic markets. Telecommunications partnerships determine competitive positioning in each territory.
United States
Household subscription consolidation drives recurring revenue predictability in metropolitan gaming corridors. FCC broadband infrastructure standards mandate minimum throughput thresholds that shape cloud service eligibility criteria. Seattle and Redmond anchor Microsoft's Azure-powered delivery network expansion across North American edge nodes.
Japan
Multi-generational intellectual property familiarity sustains premium subscription attach rates among family-oriented demographics. METI content classification protocols influence platform operator compliance investments and release window sequencing. Tokyo and Osaka metropolitan clusters exhibit the fastest migration toward multi-profile household billing structures.
South Korea
PC bang culture and esports tournament infrastructures sustain high-engagement competitive player cohorts. 5G network densification by telecommunications providers enables sub-20ms streaming latency in Seoul and Busan metropolitan gaming clusters. MFDS digital content frameworks shape cross-border service compliance obligations.
Germany
GDPR algorithmic transparency provisions force recommendation engine documentation for regulatory audit trails. EU Digital Services Act mandates reshape data handling obligations for platform operators targeting privacy-conscious consumer segments. Berlin and Munich anchor compliance-driven backend infrastructure investments.
Brazil
Mid-tier internet service providers adopt AI-driven neural upscaling to compete with fiber incumbents in São Paulo and Rio de Janeiro corridors. Edge computing node deployment by telecommunications providers compresses latency thresholds below 40ms. ANVISA digital service frameworks influence content licensing negotiation cycles.
Global Subscription-Based Gaming Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Cloud infrastructure operators and proprietary hardware ecosystem builders occupy distinct strategic positions with limited direct overlap. Three archetypes dominate: telecommunications-integrated platform operators, exclusive content pipeline owners, and family-oriented intellectual property specialists. Dominant competitive moves center on network edge placement investments and exclusive content acquisition negotiations.
Within the cloud infrastructure tier, Microsoft and Sony Interactive Entertainment occupy positions that exemplify divergent strategic approaches to platform differentiation. Nintendo represents the family-oriented intellectual property archetype, leveraging decades of character franchise depth to sustain household-wide subscription commitments. Tencent anchors the Asia-Pacific competitive vector through integrated social platform and gaming service convergence. These three companies illustrate how geographic origin and corporate structure shape divergent paths to subscription revenue generation.
| Leading Market Players |
|---|
| NetEase Games |
| Nintendo |
| Microsoft |
| Take-Two Interactive |
| Electronic Arts |
| Sony Interactive Entertainment |
| Roblox |
| Riot Games |
| Tencent |
| Others |
Supply & Pricing Matrix
Capacity reservation agreements with telecommunications providers lock in cloud edge node access and stabilize bandwidth cost visibility across multi-year platform deployment cycles. These contractual structures anchor pricing predictability for operators expanding into India's Tier-2 and Tier-3 broadband corridors while insulating against GPU procurement volatility.
Pricing Analysis
The customization-premium spread separates configured-to-order family plan bundles from standard individual subscriptions. Three-tier pricing structure across premium, standard, and economy levels segments by content library depth and concurrent stream allowances. Price differentiation hinges on exclusive IP access and geographic delivery cost variations. Pricing pressure stems from semiconductor input cost volatility compressing cloud data center margins. Casual mobile players in Southeast Asian markets exhibit highest price sensitivity; competitive esports subscribers in South Korea show lowest.
Supply Chain Analysis
Inbound logistics costs through transpacific container lanes from Taiwan and South Korea shape GPU and specialized encoding chip delivery timelines. Manufacturing concentration in Taiwan, South Korea, and China feeds cloud server assembly. Component dependencies center on NVIDIA data center GPUs, high-bandwidth memory modules, and custom ASICs. Single-source vulnerability in advanced node semiconductor fabrication poses structural risk. Distribution runs through hyperscale cloud provider direct procurement and telecommunications-integrated edge deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents early-cycle expansion as cloud infrastructure investments by telecommunications providers compress latency thresholds and unlock subscriber bases beyond hardware ownership barriers.
For Market Incumbents: Compound exclusive content pipeline depth through IP acquisition negotiations and accelerate edge node co-location partnerships with South Korean and Brazilian telecommunications providers. Defend against emerging cloud-native entrants by securing multi-year capacity reservation agreements that lock in bandwidth pricing. Prioritize backward integration into proprietary streaming codec development to reduce third-party licensing exposure. For New Entrants and Emerging Players: Lead with freemium architecture targeting India's underpenetrated Tier-2 and Tier-3 cities where fiber-to-the-home rollout accelerates addressable market formation. White-space concentration sits in localized content licensing for Southeast Asian mobile-first demographics. Go-to-market execution should anchor on telecommunications partnership structures that bundle subscription access with broadband service contracts. For Investors and Strategic Acquirers: Cloud infrastructure engineering specialists with distributed systems optimization capabilities represent the most defensible acquisition target archetype. Long-term viability favors operators with demonstrated regulatory compliance architecture across GDPR and EU AI Act transparency mandates. Signal to monitor: sub-20ms streaming latency achievement in metropolitan clusters as inflection indicator for platform technical readiness.| Strategic Initiative | Industry Significance |
|---|---|
| Edge Node Co-location Partnership | Telecommunications partnerships in Brazil and Mexico compress latency below 40ms threshold. |
| Exclusive IP Acquisition | Japanese character franchises sustain multi-generational household subscription commitments. |
| Freemium Architecture Launch | Zero-cost onboarding captures India's Tier-2 and Tier-3 cities with constrained upfront payment capacity. |
| GDPR Compliance Retrofit | Algorithmic transparency investments differentiate platforms in privacy-conscious German markets. |
| Neural Upscaling Integration | AI-driven frame generation reduces bandwidth requirements for mid-tier Brazilian internet providers. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, hyperscaler capex disclosures, and telecommunications infrastructure deployment databases. Primary interviews engaged cloud platform engineering directors, content licensing executives, telecommunications partnership leads, and regulatory compliance officers across North America, Europe, and Asia-Pacific. Secondary sources included FCC broadband infrastructure reports, EU Digital Services Act implementation guidance, MIIT content licensing protocols, and customs trade data for semiconductor imports. Bottom-up subscriber modeling triangulated against top-down market sizing from platform operator disclosures.
Segmentation dimensions modeled span platform type, subscription model configuration, game genre mix, and customer behavioral segment across the projection horizon. CAGRs derived from trend extrapolation of cloud infrastructure investment cycles, broadband penetration curves, and content pipeline release calendars. Industry-specific inputs incorporated 5G network densification timelines and GDPR algorithmic transparency compliance cost structures.
Forecasts assume regulatory continuity in FCC broadband standards, EU Digital Services Act transparency mandates, and China's MIIT content licensing protocols; material policy shifts would require re-modeling. Specific risks include data residency fragmentation forcing redundant backend deployments and semiconductor supply volatility disrupting GPU procurement. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
PC Games Market
Gaming
South Asia Mobile Gaming Market
Gaming
United States Gaming Accessories Market
Gaming
Singapore Gaming Gadgets Market
Gaming
Gaming Hardware Market
Gaming
Online Strategy Games Market
Gaming
Game Engine Management Market
Gaming
Africa Gaming Market
Gaming
LAMEA in-Game Advertising Market
Gaming
Playstation Network (PSN) Market
Gaming
Global Trading Card Games Market
Gaming
Global Online Gambling and Betting Market
Gaming
Asia-Pacific in-Game Advertising Market
Gaming
Australia Gaming Gadgets Market
Gaming
Global Gaming Market
Gaming
Japan Virtual Reality Gaming Market