
 Asia-Pacific Casino Gambling Market | 2026-2036
Asia-Pacific Casino Gambling Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Casino Gambling Market Insights
The Philippines' Anti-Money Laundering Act is consolidating licensing requirements for integrated resorts, raising compliance thresholds for new entrants. Galaxy Entertainment Group anchors its position through massive integrated resort scale on Macau's Cotai Strip. Melco Resorts & Entertainment differentiates via premium entertainment and non-gaming amenities. Bloomberry Resorts competes in the Philippines through its Manila Bay property.
Casino gambling encompasses regulated wagering activities conducted in licensed venues, combining electronic gaming systems, table-based probability games, and hospitality infrastructure to extract house-edge revenue from patron spending. Slot machines generate the highest volume throughput per square meter of floor space, while VIP gamblers concentrate margin pools through high-stakes table play. E-wallet payment methods are displacing cash handling across newer integrated resorts, reducing operational friction and audit trail gaps.
Macau's Gaming Inspection and Coordination Bureau enforces concession renewal terms that mandate capital investment in non-gaming attractions. Singapore's Casino Regulatory Authority imposes strict entry levies on local residents to constrain problem gambling. China's Ministry of Public Security coordinates cross-border enforcement against unauthorized online gambling channels targeting mainland residents. Stakeholders must monitor regulatory divergence between jurisdictions that reward integrated resort investment versus those tightening local participation restrictions.
Market Dynamics
Integrated resort operators across Southeast Asia face escalating capital intensity as Macau's Gaming Inspection and Coordination Bureau mandates non-gaming investment quotas alongside concession renewals. This regulatory pressure compresses project timelines while expanding amenity requirements beyond traditional gaming floors.
Growth Catalysts
- Smart payment rails:E-wallet infrastructure is displacing cash handling across newer Philippine and Vietnamese integrated resorts, reducing operational friction while closing audit trail gaps that previously complicated compliance.
- ASEAN tourism corridors:Visa liberalization between Thailand, Vietnam, and Cambodia is funneling premium Chinese and South Korean visitor segments toward emerging gaming destinations outside Macau's saturated core.
- Singapore's Casino Control Act amendments:Tightened anti-money laundering protocols are professionalizing operator standards across the region, creating competitive differentiation for venues that achieve early compliance certification.
Market Restraints
- Construction input volatility:Steel and specialized glass supply concentration in Chinese manufacturing clusters exposes Philippine and Vietnamese resort developers to price swings and delivery uncertainty.
- Technical limitation of legacy surveillance:Analog CCTV infrastructure in older Macau properties cannot support real-time facial recognition integration required under updated junket operator monitoring rules.
- Substitution by cruise gaming:International cruise lines operating out of Shanghai and Singapore are capturing short-haul premium gamblers who previously fueled Macau's weekend volume.
Strategic Opportunities
- Vietnam's underpenetrated central coast:Da Nang and Hoi An lack integrated resort density despite proximity to East Asian source markets, presenting first-mover positioning for concessionaires willing to navigate complex local partnership structures.
- Japan's integrated resort implementation:Osaka and Yokohama licensing processes are creating demand for experienced Asia-Pacific operators to provide technical consultancy and management contracts without direct equity exposure.
- Technology convergence:Blockchain-based loyalty tokenization is enabling cross-property player tracking between Philippine, Cambodian, and Vietnamese venues that share backend infrastructure providers.
Industry Challenges
- Specialized compliance talent scarcity:Anti-money laundering investigation units require Mandarin and Cantonese fluency combined with forensic accounting certification, a skill combination concentrated in Macau and Singapore with limited regional mobility.
- Legacy system integration friction:Slot machine management systems from 1990s-era deployments in older Macau properties cannot interface with modern player tracking databases without expensive middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Casino Gambling Market |
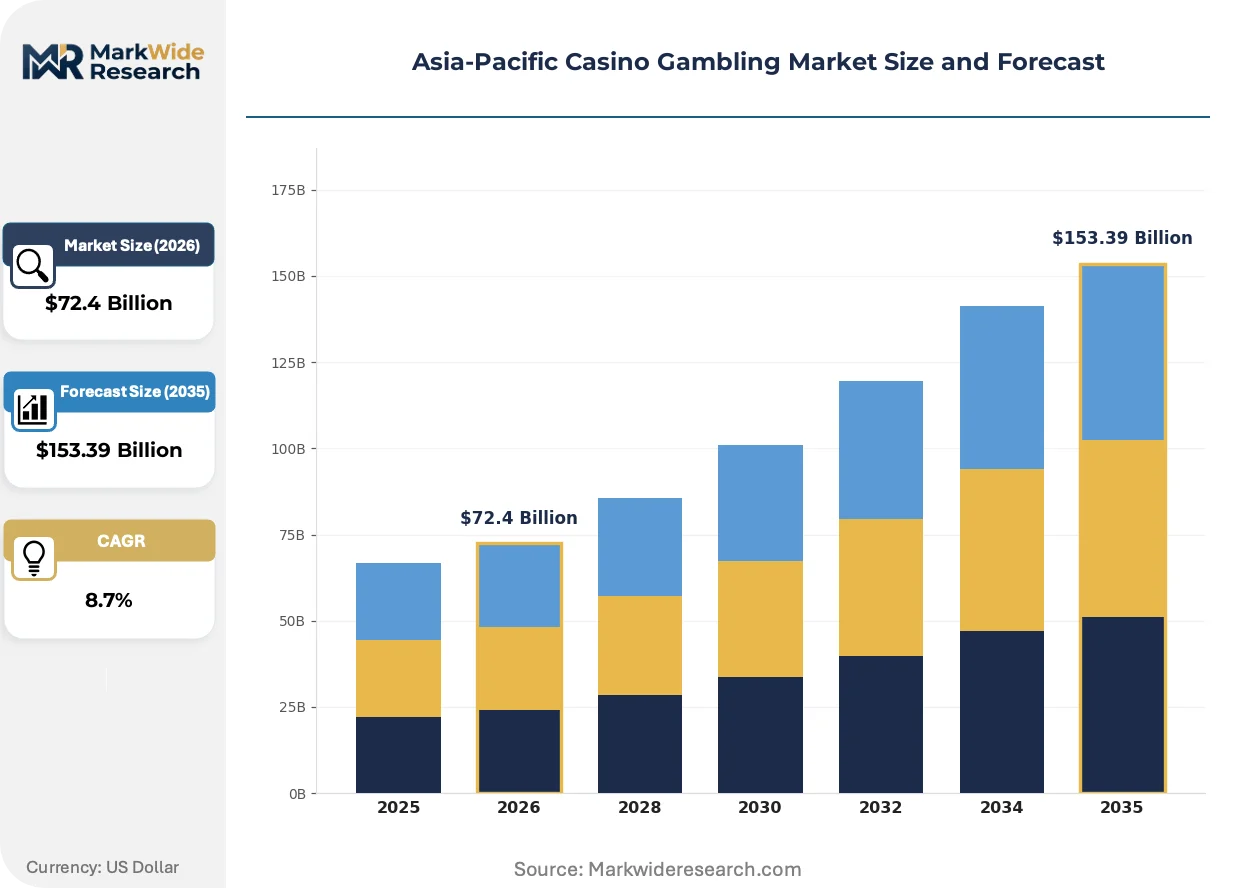
| Market Size in 2026 | $72.4 Billion |
| Market Size in 2035 | $153.39 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Game Type: Slot Machines, Table Games, Poker, Electronic Gaming Payment Method: Credit Card, E-Wallets, Cash, Cryptocurrency Customer Type: Tourists, Locals, VIP Gamblers, Online Players Casino Size: Large Resorts, Small Establishments, Integrated Casinos, Riverboat Casinos |
| Companies Covered | Genting Berhad, Wynn Resorts, Galaxy Entertainment Group, Paradise Co, SJM Holdings, Las Vegas Sands Corp, Melco Resorts & Entertainment, Bloomberry Resorts, MGM China Holdings, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Casino Gambling Market Trends and Innovations
Digital payment infrastructure and biometric surveillance are converging to reshape operational compliance requirements across Asia-Pacific gaming venues. These technologies are compressing the gap between regulatory mandate and implementation capability.
RFID-enabled chip tracking is expanding into high-stakes baccarat pits across Macau and Singapore properties, replacing manual dealer verification with automated wager recording. Premium mass-market segments are adopting this technology fastest as operators seek to replicate VIP table yield monitoring without junket intermediary involvement. The structural consequence is expanding into direct relationship management between resorts and high-value players, disintermediating traditional commission-based facilitator networks.
China's Ministry of Public Security coordinates cross-border enforcement against unauthorized online gambling channels targeting mainland residents, pressuring land-based venues to demonstrate physical presence verification for all significant transactions. This policy compresses the operational window for gray-market digital intermediaries while elevating compliance documentation burdens for legitimate operators. VIP segments in Macau and Singapore properties are most affected, responding by shifting transaction verification to in-person cage settlements with biometric identity confirmation.
Buyer concentration is reshaping procurement patterns as Philippine integrated resort operators consolidate vendor relationships following the Anti-Money Laundering Act's licensing consolidation. Equipment suppliers that previously served fragmented provincial casino markets now face consolidated tender processes dominated by Manila Bay and Entertainment City developments. This concentration is most visible in the electronic gaming machine category, where three operators now account for the majority of new unit deployments and are demanding outcome-based performance guarantees rather than standard purchase terms.
Asia-Pacific Casino Gambling Market Segmentation
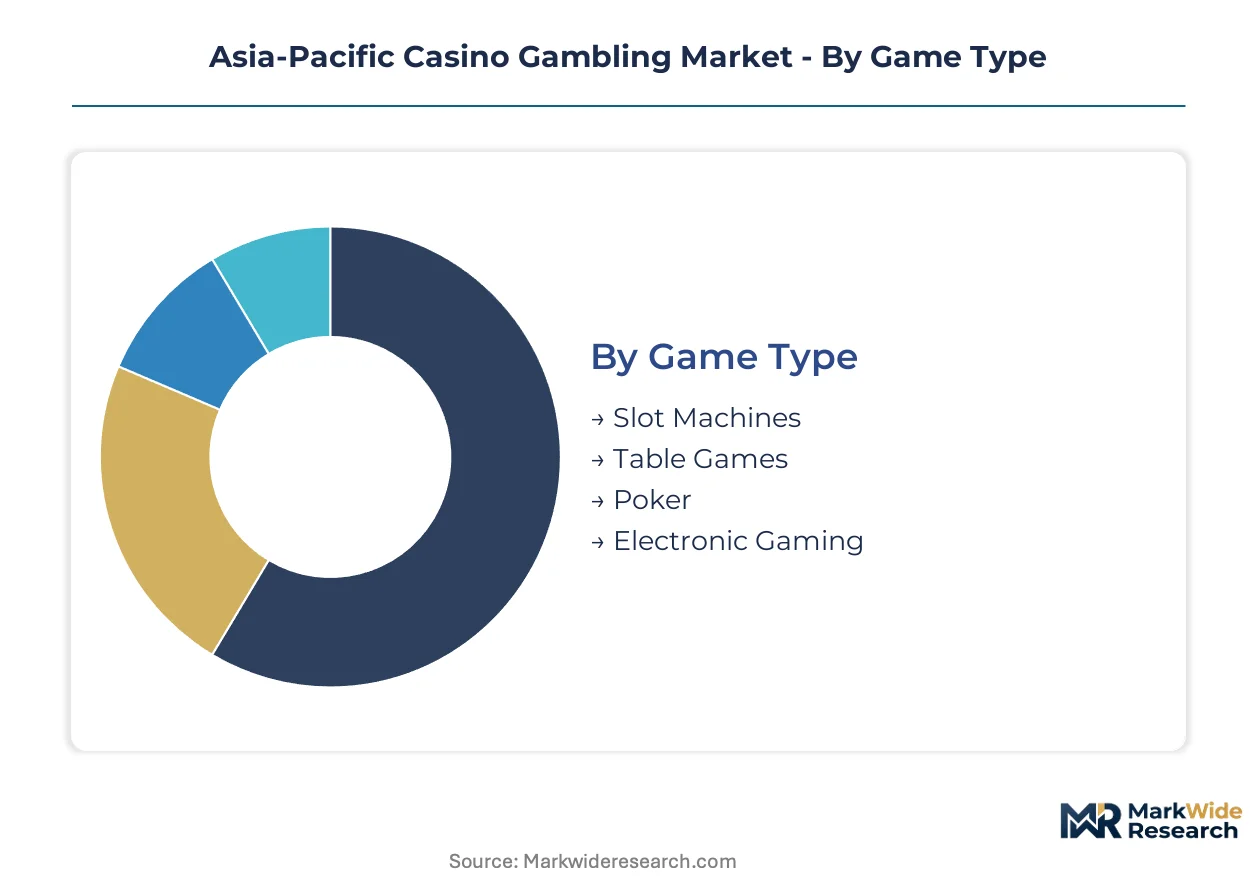
Asia-Pacific casino operators deploy distinct segmentation strategies to optimize floor yield and regulatory compliance across fragmented jurisdictional requirements. Game mix and payment infrastructure decisions directly shape capital allocation and revenue stability in markets with divergent local participation rules.
Game Type:
Slot machine refresh cycles now compress to 5-7 years as operators compete for premium mass-market attention with immersive display technology and linked progressive jackpots.
- Slot Machines:Electronic gaming terminals with RNG-based outcomes and multi-denomination wagering dominate floor space allocation across Philippine and Vietnamese integrated resorts. Demand concentrates in Manila's Entertainment City cluster where operators deploy high-volatility themed cabinets to capture weekend tourist volume from South Korea and China.
- Table Games:Baccarat, blackjack, and roulette conducted with live dealers and physical cards/chips generate the highest revenue per square meter in Macau's VIP pits. Singapore's Marina Bay Sands and Resorts World Sentosa prioritize automated shufflers and RFID-enabled tables to satisfy Casino Regulatory Authority audit requirements while maintaining throughput.
- Poker:Texas Hold'em and Omaha cash games attract dedicated player pools in Australian and Filipino venues with lower house-edge economics than house-banked alternatives.
- Electronic Gaming:Server-based terminals offering simulated table games and video poker reduce staffing costs in Cambodia's border casinos serving Thai day-trippers.
Volume placements concentrate in Slot Machines; the faster expansion belongs to Electronic Gaming as labor costs rise across Southeast Asia.
Payment Method:
Cost tier differentiation separates legacy cash-dependent operations from integrated resorts investing in digital wallet infrastructure to reduce cage congestion and improve audit precision.
- Credit Card:Card-present transactions at casino cages and hotel front desks dominate Singapore and Australian markets with mature banking infrastructure and chargeback dispute frameworks.
- E-Wallets:Alipay, WeChat Pay, and regional alternatives like GCash and MoMo are displacing cash across Vietnam's Ho Tram Strip and Philippine Entertainment City properties. Demand concentrates in venues targeting Chinese and Vietnamese millennial segments who abandoned physical wallets during the pandemic-era digital acceleration.
- Cash:Physical currency handling persists in Cambodia's Poipet cluster and Myanmar's border zones where banking penetration remains limited and regulatory oversight is fragmented.
- Cryptocurrency:Blockchain-based settlement experiments operate in restricted VIP rooms within Philippine offshore gaming hubs, though central bank warnings in Thailand and Vietnam constrain mainstream adoption.
Transaction velocity peaks with E-Wallets; steepest expansion trajectory belongs to Cryptocurrency in regulatory gray zones seeking to bypass traditional correspondent banking.
Customer Type:
Application-based segmentation separates fly-in premium segments requiring hospitality packaging from local participation constrained by entry levies and exclusion programs.
- Tourists:International visitors from China, South Korea, and Japan drive occupancy and gaming revenue in Macau, Singapore, and emerging Vietnamese destinations. Singapore's $150 daily entry levy on citizens deliberately funnels locals toward social safeguards while preserving tourist accessibility.
- Locals:Domestic participation faces strictest constraints in Singapore and Australia with self-exclusion registers and loss limits, while Philippine integrated resorts actively market to Manila's affluent resident base without comparable restrictions.
- VIP Gamblers:High-net-worth individuals wagering minimum thresholds of $100,000 per visit historically channeled through junket operators now shift toward direct resort relationships in Macau's post-concession renewal environment.
- Online Players:Cross-border digital wagering on Philippines-licensed platforms targets mainland Chinese users despite Ministry of Public Security enforcement, creating regulatory arbitrage pressure on land-based venues.
Revenue concentration remains with VIP Gamblers; gaining share fastest is Online Players as mobile penetration deepens across Indonesia and Vietnam.
Casino Size:
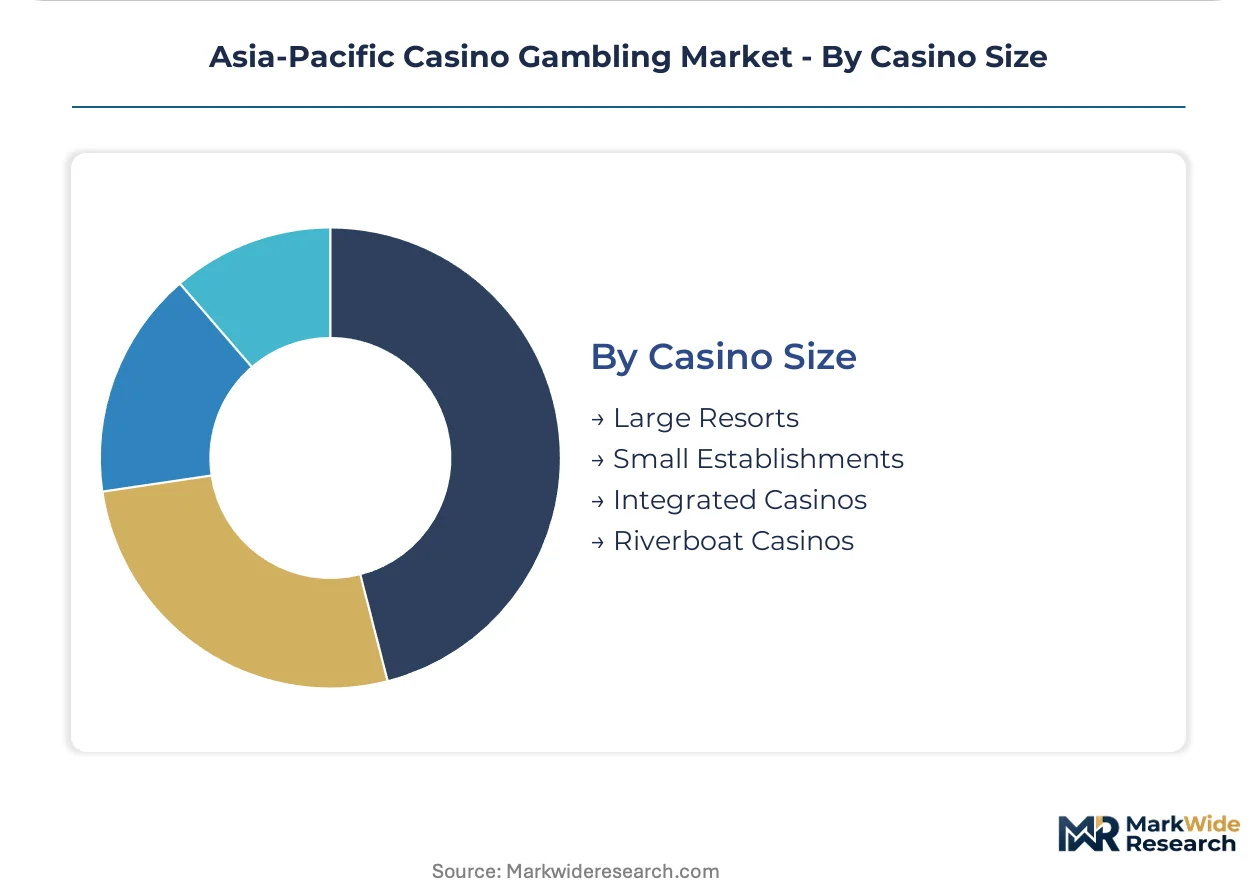
Scale-based segmentation reflects capital intensity thresholds and regulatory licensing tiers that determine competitive positioning in saturated versus emerging markets.
- Large Resorts:Standalone destination properties with 500+ rooms and extensive convention facilities anchor competitive positioning in Australia's Gold Coast and Queensland markets.
- Small Establishments:Limited-scale venues with under 50 gaming tables serve provincial markets in the Philippines and Cambodia with lower compliance burdens and faster licensing timelines.
- Integrated Casinos:Mixed-use developments combining gaming with retail, entertainment, and hospitality dominate Singapore's Marina Bay and Sentosa precincts where Gaming Inspection and Coordination Bureau mandates non-gaming investment quotas alongside concession renewals.
- Riverboat Casinos:Floating gaming facilities on the Mekong and other waterways operate in Cambodian border zones, exploiting jurisdictional ambiguity to serve Thai and Vietnamese patrons without land-based licensing.
Investment flows concentrate in Integrated Casinos; climbing the fastest is Riverboat Casinos as Mekong Delta infrastructure improves and enforcement gaps persist.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Macau's Cotai Strip special gaming zone concentrates integrated resort investment through concession-mandated non-gaming quotas. Tax incentives for foreign operators anchor capital flows toward this Chinese-administered territory.
China (Macau)
Macau's Gaming Inspection and Coordination Bureau enforces concession renewal terms requiring capital diversion into non-gaming attractions. China's Ministry of Public Security coordinates cross-border enforcement against unauthorized online channels targeting mainland residents. The Cotai Strip cluster sees Galaxy Entertainment Group and Melco Resorts & Entertainment expanding hospitality infrastructure beyond traditional gaming floors.
Singapore
Marina Bay Sands and Resorts World Sentosa draw premium tourist segments from East Asian source markets through convention and entertainment packaging. Singapore's Casino Regulatory Authority imposes strict entry levies on local residents to constrain problem gambling participation. The Marina Bay precinct anchors integrated resort density with RFID-enabled tables satisfying audit requirements.
Philippines
Manila's Entertainment City cluster targets South Korean and Chinese weekend tourist volume through high-volatility electronic gaming deployments. The Anti-Money Laundering Act consolidates licensing requirements for integrated resorts, raising compliance thresholds for new entrants. Bloomberry Resorts competes through its Manila Bay property while provincial markets operate smaller establishments with faster licensing timelines.
Vietnam
Da Nang and Hoi An on the central coast lack integrated resort density despite proximity to East Asian source markets. Ho Tram Strip properties adopt Alipay, WeChat Pay, and MoMo e-wallets to capture millennial segments who abandoned physical wallets during pandemic-era digital acceleration. Complex local partnership structures constrain first-mover positioning for foreign concessionaires.
Australia
Queensland and Gold Coast markets anchor competitive positioning through standalone destination properties with 500-plus rooms and extensive convention facilities. Australia's mature banking infrastructure supports credit card-present transactions at casino cages with established chargeback dispute frameworks. Self-exclusion registers and loss limits constrain domestic participation compared to Philippine integrated resorts.
Asia-Pacific Casino Gambling Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across concession-based licensing environments. Market structure tilts toward consolidated holding companies operating multiple properties under single regulatory umbrellas. Three archetypes dominate: integrated resort conglomerates with hospitality diversification, pure-play gaming operators with regional concentration, and diversified Malaysian-Chinese conglomerates with cross-sector holdings. Competitive moves center on concession renewal positioning through non-gaming capital commitments and direct VIP relationship management displacing junket intermediaries.
Within the integrated resort tier, Galaxy Entertainment Group and Melco Resorts & Entertainment exemplify operators navigating Macau's post-concession renewal environment. Genting Berhad represents the diversified conglomerate archetype with Malaysian origins and cross-sector holdings spanning hospitality and energy. These three companies occupy positions defined by their responses to regulatory mandates for non-gaming investment and direct player relationship development.
| Leading Market Players |
|---|
| Genting Berhad |
| Wynn Resorts |
| Galaxy Entertainment Group |
| Paradise Co |
| SJM Holdings |
| Las Vegas Sands Corp |
| Melco Resorts & Entertainment |
| Bloomberry Resorts |
| MGM China Holdings |
| Others |
Pricing and Supply Chain Analysis
Integrated resort procurement consolidation following the Philippines' Anti-Money Laundering Act licensing consolidation is forcing equipment suppliers to restructure pricing models around performance guarantees rather than standard purchase terms, compressing margins for vendors unable to demonstrate outcome-based value.
Pricing Analysis
Lead-time premiums dominate electronic gaming machine procurement as Philippine and Vietnamese operators demand compressed delivery windows for property expansions. Pricing stratifies across premium certified tiers with ISO-compliant surveillance integration, standard legacy-compatible units, and economy-grade refurbished cabinets for provincial markets. Cost compression in the economy tier is intensifying because Chinese steel and specialized glass supply concentration exposes developers to input volatility. Provincial casino operators in Cambodia and Myanmar's border zones exhibit highest price sensitivity, while Singapore's Marina Bay integrated resorts prioritize certification-grade equipment with minimal cost elasticity.
Supply Chain Analysis
Certification gating through Macau's Gaming Inspection and Coordination Bureau concession requirements restricts supplier eligibility to vendors with demonstrated compliance documentation and regional installation track records. Manufacturing concentrates in China for electronic gaming terminals and surveillance hardware, South Korea for premium display technology, and Japan for precision automated shufflers and RFID chip systems. Component dependencies include specialized gaming-grade LCD panels, steel-reinforced security glass, and biometric sensor arrays. Single-source vulnerability runs through Chinese steel fabrication clusters serving Southeast Asian construction pipelines. Distribution feeds from direct manufacturer relationships with Manila Entertainment City and Macau Cotai Strip operators, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
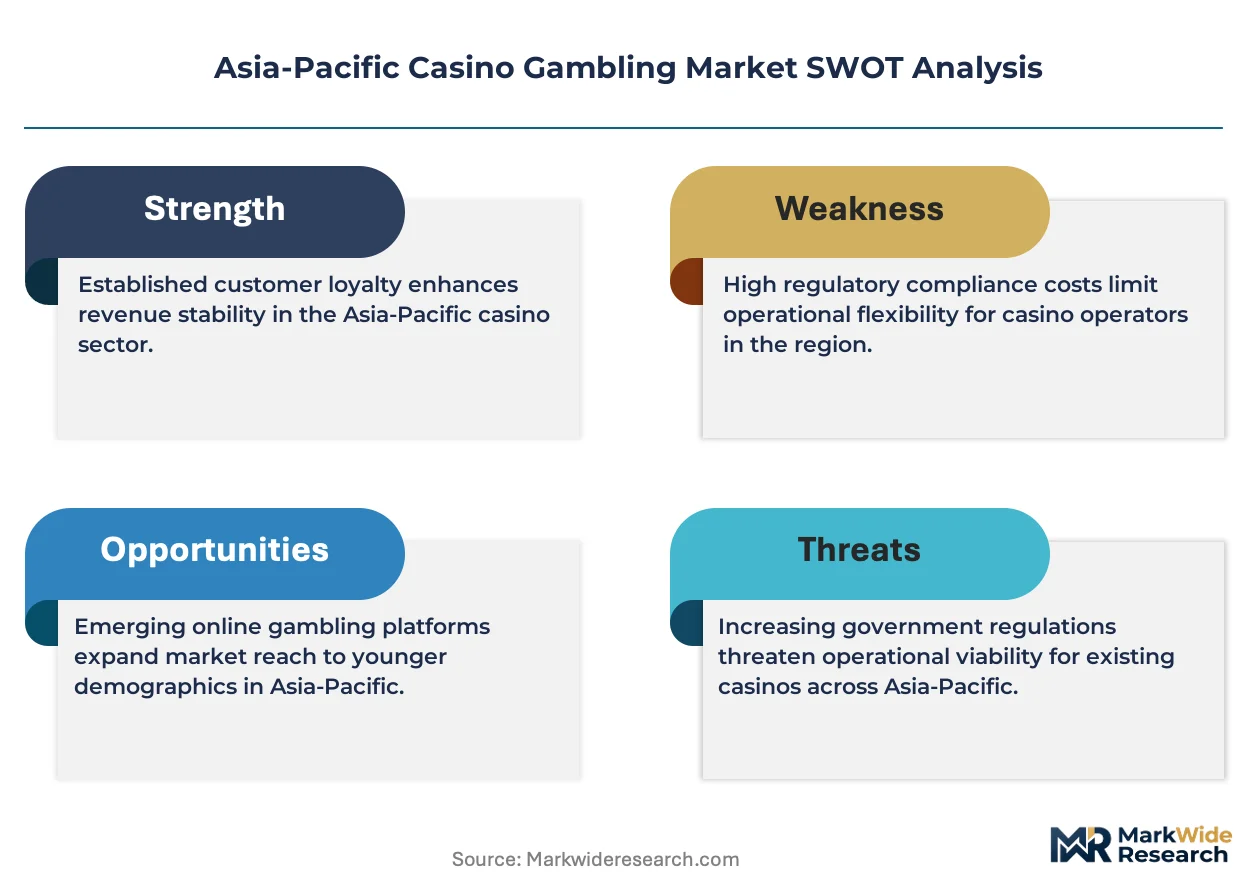
The Asia-Pacific casino gambling market operates as a cost-of-compliance story where Singapore's Casino Control Act amendments and the Philippines' Anti-Money Laundering Act licensing consolidation erect barrier-to-entry moats favoring operators with established certification infrastructure and capital reserves for non-gaming investment quotas.
For Market Incumbents: To counter direct VIP relationship displacement of traditional junket intermediaries, Galaxy Entertainment Group and Melco Resorts & Entertainment should deepen backward integration into hospitality amenity development rather than outsourcing non-gaming attractions. Incumbents must accelerate RFID-enabled table deployment across premium mass-market floors to satisfy Macau's updated junket operator monitoring rules before concession renewal deadlines compress implementation timelines further. For New Entrants and Emerging Players: Vietnam's Casino Law amendments allowing limited local participation open a window for foreign concessionaires willing to navigate complex partnership structures in Da Nang and Hoi An's underpenetrated central coast. New entrants should target Cambodia's Mekong Delta riverboat casino segment where enforcement gaps persist and licensing timelines outpace land-based alternatives. A go-to-market angle anchored in e-wallet infrastructure partnerships with Alipay, WeChat Pay, and regional alternatives captures millennial segments who abandoned physical wallets during pandemic-era digital acceleration. For Investors and Strategic Acquirers: The window for entry favors diversified conglomerates with cross-sector hospitality holdings capable of absorbing non-gaming investment mandates without equity dilution. Long-term viability hinges on operators demonstrating direct VIP relationship management capabilities independent of junket commission structures. The signal to monitor is cross-border enforcement intensity from China's Ministry of Public Security against unauthorized online channels, which would elevate physical presence verification burdens and favor land-based venues with robust cage settlement infrastructure.| Strategic Initiative | Industry Significance |
|---|---|
| Non-Gaming Amenity Diversification | Macau's Gaming Inspection and Coordination Bureau mandates capital diversion into convention and entertainment infrastructure alongside concession renewals. |
| Direct VIP Relationship Platform | RFID-enabled chip tracking and biometric cage settlements disintermediate junket intermediaries while satisfying China's Ministry of Public Security verification requirements. |
| E-Wallet Infrastructure Integration | Alipay, WeChat Pay, and regional alternatives reduce operational friction across Philippine and Vietnamese properties targeting Chinese and South Korean millennial segments. |
| Regulatory Compliance Certification | Singapore's Casino Regulatory Authority audit requirements professionalize operator standards and create competitive differentiation for early compliance achievers. |
| Emerging Market First-Mover Positioning | Vietnam's central coast and Cambodia's Mekong Delta present positioning opportunities before integrated resort density saturates these corridors. |
Research Methodology
Multi-period observation of concession renewal timelines, regulatory amendment trajectories, and integrated resort capital deployment patterns anchored the trend analysis, supplemented by interviews with casino operations directors, compliance officers at Gaming Inspection and Coordination Bureau-licensed properties, junket operator relationship managers, and surveillance technology procurement leads. Secondary validation drew from Macau Gaming Inspection and Coordination Bureau concession filings, Singapore Casino Regulatory Authority enforcement bulletins, Philippine Amusement and Gaming Corporation licensing records, and customs data on electronic gaming machine imports. Bottom-up property-level revenue modeling triangulated against top-down regional market sizing.
Segment-weighting across game type, payment method, customer type, and casino size dimensions informed the analytical framework over the projection horizon. Deployment intensity of RFID-enabled tables, e-wallet transaction penetration rates, and non-gaming revenue mix served as industry-specific forecast inputs. CAGRs derived from regression analysis of historical concession investment cycles and regulatory compliance cost escalations.
The model assumes continued technology adoption path toward biometric surveillance and digital payment infrastructure; alternative pathways emphasizing cash-dependent legacy operations would alter the outlook for audit trail compliance and operational efficiency. Forecasts reflect assumptions regarding cross-border enforcement coordination and concession renewal timing. A model refresh is warranted upon material change in China's Ministry of Public Security enforcement intensity or Macau's non-gaming investment quota calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Gaming
Animation, VFX & Game Market
Gaming
Gaming Simulation Market
Gaming
Virtual Sports Market
Gaming
Shooter Game Market
Gaming
South Korea Subscription-Based Gaming Market
Gaming
North America Casino Gambling Market
Gaming
Gaming As a Service Market
Gaming
South Korea Gaming Peripherals Market
Gaming
LAMEA Gaming Posters Market
Gaming
Chinese Gaming Industry Market
Gaming
United States Gaming Market
Gaming
Galgames Market
Gaming
Puzzle Video Game Market
Gaming
Global Electronic Table Games (ETG) Market
Gaming
Mobile Game Software Market
Gaming
Video Game Software Market