
 Surgical Chips Market | 2026-2036
Surgical Chips Market Size, Share, and Industry Trends Forecast 2026-2036
Surgical Chips Market Outlook
Capital-intensity divergence between wafer-scale foundry operators and fabless design houses is redrawing competitive boundaries in surgical chips. Medtronic leverages captive semiconductor fabrication to secure supply continuity for implantable neuromodulation platforms. Abbott Laboratories anchors its cardiac rhythm management portfolio through backward integration into custom sensor die production. Thermo Fisher Scientific competes via specialized diagnostic sensor foundry services that bridge biocompatibility requirements with semiconductor process nodes.
Surgical chips constitute miniaturized semiconductor devices engineered for in-body or perioperative deployment, typically fabricated on biocompatible substrates such as silicon-on-insulator or polyimide with hermetic encapsulation achieving moisture ingress rates below medical-grade thresholds. These components enable real-time physiological signal acquisition, closed-loop therapeutic modulation, and secure data telemetry in sterile environments. Implantable devices command the dominant value share due to extended regulatory validation cycles and premium pricing associated with long-term biostability requirements. Wireless communication technologies, particularly ultra-wideband and proprietary near-field protocols, represent the fastest-expanding technology segment as surgical workflows demand higher data throughput with minimal electromagnetic interference. Diagnostic sensors applied to patient monitoring accumulate the deepest margin pools through recurring calibration service contracts and disposable electrode attachments.
FDA premarket notification pathways and EU MDR conformity assessment procedures impose stringent biocompatibility and electromagnetic compatibility validation burdens that filter market entrants by capital availability. ISO 13485 quality management systems and IEC 60601 electrical safety standards function as baseline gating requirements for original equipment manufacturer qualification. Stakeholders must monitor evolving FDA guidance on cybersecurity premarket submissions and EU AI Act risk classification frameworks as algorithm-enabled surgical chips advance toward autonomous decision-support capabilities.
Market Dynamics
Implantable neuromodulation platforms are compressing product development cycles as FDA breakthrough device designation pathways accelerate clinical validation timelines for closed-loop therapeutic systems.
Growth Catalysts
- FDA Breakthrough Device Designation:Expedited review pathways compress premarket approval timelines for novel surgical chip platforms addressing unmet neurological conditions. Orthopedic surgical centers in Germany's Ruhr corridor accelerate adoption of sensor-integrated implants.
- EU MDR Conformity Assessment Harmonization:Streamlined biocompatibility validation frameworks reduce redundant testing burdens for hermetic encapsulation technologies. Switzerland's precision manufacturing corridor attracts concentrated foundry investment.
- Silicon-on-insulator substrate maturation:Advanced biocompatible wafer processing enables sub-micron feature sizes with moisture ingress rates below medical-grade thresholds. Implantable device manufacturers leverage these substrates for extended biostability.
Market Restraints
- Platinum-iridium electrode cost volatility:Precious metal price swings in catalytic materials directly impact implantable neuromodulation device bill-of-materials. Supply concentration in South African mining operations amplifies input cost uncertainty.
- Hermetic sealing yield constraints:Laser-weld encapsulation processes achieve only moderate first-pass yields at medical-grade moisture ingress specifications. Technical limitations in titanium-ceramic interface bonding extend production ramp timelines.
- EU AI Act risk classification friction:Algorithm-enabled surgical chips with autonomous decision-support capabilities face uncertain conformity assessment pathways. Regulatory ambiguity delays product launch cycles for AI-integrated diagnostic sensors.
Strategic Opportunities
- Underpenetrated ambulatory surgical center channel:Wireless communication-enabled diagnostic sensors create recurring revenue pools through disposable electrode attachments. United States outpatient facilities represent untapped deployment volume for perioperative monitoring chips.
- Ultra-wideband telemetry convergence:Integration of proprietary near-field protocols with standard wireless infrastructure enables higher data throughput in sterile environments. Technology convergence between medical device and consumer electronics semiconductor processes reduces foundry switching costs.
- Japan METI medical device innovation subsidy:Government-backed R&D funding accelerates domestic production capacity for biocompatible sensor die fabrication. Regulatory tailwinds support localized supply chain development for implantable cardiac rhythm management platforms.
Industry Challenges
- Biomedical-semiconductor cross-functional talent scarcity:Device physics expertise combined with ISO 13485 quality management fluency remains exceptionally shallow. Recruitment friction extends engineering team buildout timelines for fabless design houses.
- IEC 60601-1-2 electromagnetic compatibility retest cycles:Iterative validation against evolving immunity test levels consumes substantial certification bandwidth. Compliance timeline compression demands parallel regulatory track management.
- Legacy hospital IT infrastructure integration complexity:Proprietary data telemetry protocols require custom middleware development for electronic health record connectivity. Health system procurement committees prioritize backward-compatible wireless communication standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Surgical Chips Market |
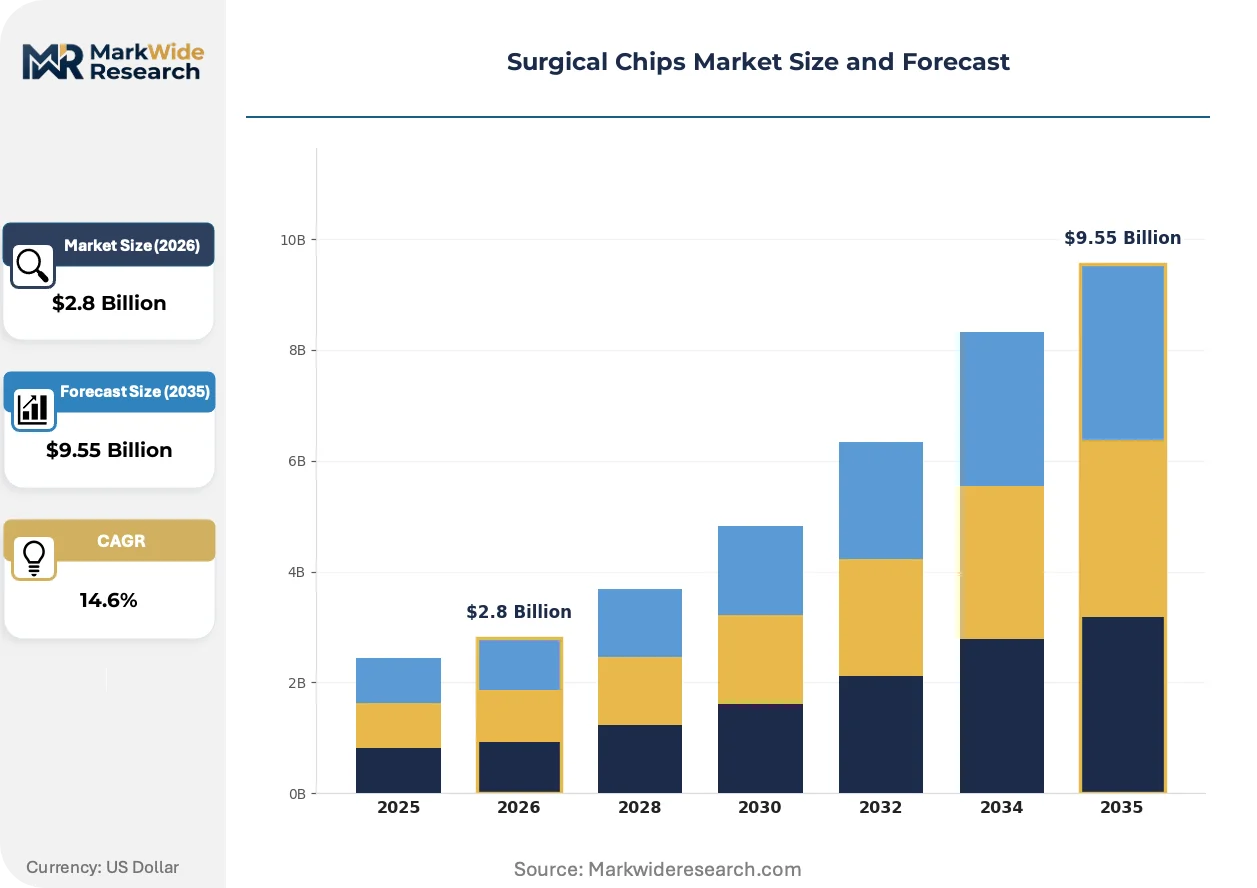
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wearable Chips, Implantable Devices, Portable Units, Diagnostic Sensors Technology: Wireless Communication, RFID, Bluetooth, Near Field Communication End User: Surgical Centers, Hospitals, Clinics, Research Institutions Application: Patient Monitoring, Surgical Intervention, Drug Delivery, Data Collection |
| Companies Covered | Medtronic, Boston Scientific, Abbott Laboratories, Johnson & Johnson, Stryker Corporation, B. Braun Melsungen AG, Agilent Technologies, Thermo Fisher Scientific, GE Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Surgical Chips Market Strategic Shifts
Wireless communication architectures are displacing tethered interfaces across perioperative and implantable applications, while regulatory frameworks co-evolve with algorithmic capabilities in diagnostic sensor platforms.
Ultra-wideband telemetry is bifurcating surgical chip connectivity architectures. This low-power, high-data-rate wireless protocol enables real-time physiological streaming with minimal electromagnetic interference in operating theater environments. Ambulatory surgical centers adopt ultra-wideband-enabled diagnostic sensors at accelerating pace as disposable electrode business models mature. The technology is bifurcating procurement specifications between premium implantable platforms requiring proprietary protocols and standard-compatible perioperative devices.
EU AI Act risk classification frameworks are recalibrating algorithm validation requirements for surgical chips with embedded decision-support capabilities. Medical device manufacturers must demonstrate clinical performance transparency for machine learning-enabled diagnostic sensors. Implantable neuromodulation platforms with adaptive stimulation algorithms face elevated conformity assessment scrutiny. European notified bodies are expanding technical documentation requirements for training data provenance and algorithm update governance.
After-sales service unbundling is fragmenting traditional equipment procurement contracts. Diagnostic sensor manufacturers now separate hardware acquisition from recurring calibration service agreements. Ambulatory surgical centers in the United States increasingly favor per-procedure consumable pricing over capital-intensive platform purchases. This consumption-pattern shift compresses vendor switching costs while deepening margin pools for disposable electrode attachments and wireless communication module replacements.
Surgical Chips Market Segmentation
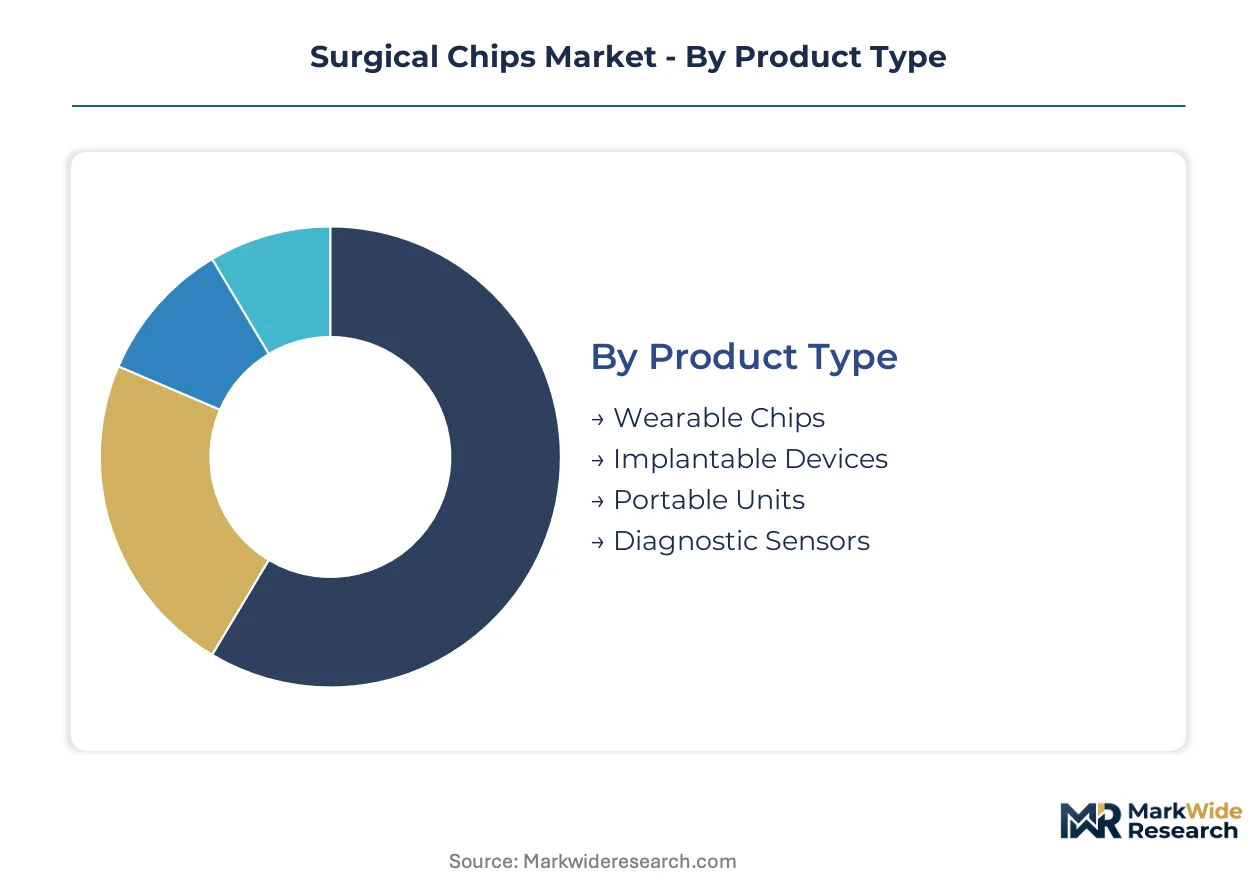
Surgical chip procurement channels diverge sharply by product durability and reimbursement pathway. Implantable platforms flow through hospital value analysis committees with extended capital cycles, while disposable diagnostic sensors penetrate ambulatory surgical centers via consumable distribution networks.
Product Type:
Channel economics separate capital-intensive implantable platforms from high-velocity disposable sensors, with procurement committees weighing biostability warranties against per-procedure cost models.
- Implantable Devices:Hermetically sealed semiconductor assemblies on silicon-on-insulator substrates achieve moisture ingress rates below medical-grade thresholds for multi-year biostability. Germany's Ruhr medical technology cluster concentrates demand from orthopedic surgical centers pursuing sensor-integrated joint replacement platforms. Premium pricing reflects FDA premarket approval pathway costs and extended regulatory validation timelines.
- Diagnostic Sensors:Disposable electrode assemblies with wireless telemetry modules enable real-time perioperative monitoring through recurring calibration service contracts. United States ambulatory surgical centers drive volume through unbundled procurement separating hardware acquisition from consumable attachments. Disposable business models compress vendor switching costs while deepening margin pools.
- Wearable Chips:Adhesive-mounted semiconductor patches for postoperative monitoring leverage consumer electronics manufacturing scale.
- Portable Units:Handheld diagnostic platforms bridge inpatient and outpatient settings with modular sensor cartridge architectures.
By volume, Diagnostic Sensors leads. By growth pace, Implantable Devices is ahead.
Technology:
Cost tiers stratify by electromagnetic compatibility certification burden and protocol licensing fees, with proprietary near-field implementations commanding premium positioning over standards-based alternatives.
- Wireless Communication:Ultra-wideband telemetry architectures deliver high-data-rate physiological streaming with minimal electromagnetic interference in sterile operating theater environments. Ambulatory surgical centers in Switzerland's precision manufacturing corridor adopt these platforms as disposable electrode business models mature. Integration with standard wireless infrastructure reduces foundry switching costs.
- Near Field Communication:Proprietary low-power protocols enable secure data exchange between implantable neuromodulation platforms and external programmers. FDA cybersecurity premarket submission requirements drive validation costs for algorithm-enabled surgical chips with autonomous decision-support capabilities. EU AI Act risk classification frameworks impose additional conformity assessment burdens.
- RFID:Passive identification tags for surgical instrument tracking and sterilization cycle management.
- Bluetooth:Standards-based connectivity for perioperative patient monitoring with consumer electronics ecosystem compatibility.
By installed base, Bluetooth dominates. By expansion trajectory, Wireless Communication gains share fastest.
End User:
Customer type determines regulatory engagement intensity, with hospital procurement committees demanding ISO 13485 quality management documentation that surgical centers rarely require.
- Hospitals:Integrated delivery networks with captive biomedical engineering departments manage multi-year capital cycles for implantable cardiac rhythm management platforms. FDA breakthrough device designation pathways accelerate clinical validation timelines for closed-loop therapeutic systems within these accounts. Electronic health record integration requirements drive proprietary middleware development costs.
- Surgical Centers:Ambulatory facilities prioritize per-procedure consumable pricing over capital-intensive platform purchases through unbundled service agreements. United States outpatient facilities represent untapped deployment volume for wireless communication-enabled diagnostic sensors. Procurement committees favor backward-compatible wireless standards to minimize legacy IT infrastructure integration complexity.
- Clinics:Physician office laboratories deploying point-of-care diagnostic chips with simplified regulatory pathways.
- Research Institutions:Academic medical centers piloting preclinical algorithm-enabled surgical chips under investigational device exemptions.
By revenue concentration, Hospitals leads. By adoption velocity, Surgical Centers is expanding most quickly.
Application:
Maturity gradients separate established patient monitoring modalities from emerging drug delivery applications facing unresolved biocompatibility validation frameworks.
- Patient Monitoring:Real-time physiological signal acquisition through implantable or perioperative sensors enables closed-loop therapeutic modulation with secure data telemetry. Diagnostic sensor manufacturers accumulate deepest margin pools through recurring calibration service contracts and disposable electrode attachments. EU MDR conformity assessment harmonization streamlines biocompatibility validation for hermetic encapsulation technologies.
- Surgical Intervention:Sensor-integrated instruments providing haptic feedback and tissue characterization data to operating surgeons. Germany's orthopedic surgical centers accelerate adoption of implantable devices with embedded force and pressure sensing capabilities. Japan METI medical device innovation subsidies support domestic production capacity for biocompatible sensor die fabrication.
- Drug Delivery:Closed-loop infusion systems with physiological feedback control for precision dosing applications.
- Data Collection:Post-market surveillance platforms aggregating real-world performance data for regulatory submissions.
By deployment scale, Patient Monitoring leads. By development priority, Surgical Intervention is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ambulatory surgical centers in the United States exhibit the highest price elasticity, squeezing margins on disposable diagnostic sensors, while German orthopedic clinics absorb premium pricing for implantable neuromodulation platforms with minimal volume sensitivity. Japan's cardiac rhythm management segment occupies a middle position, balancing cost discipline with technology premiums.
United States
FDA breakthrough device designation pathways accelerate clinical validation for closed-loop therapeutic systems, compressing premarket approval timelines. The agency's evolving cybersecurity premarket submission requirements filter entrants by capital availability. Greater Boston's medical technology corridor concentrates fabless design houses developing algorithm-enabled surgical chips for autonomous decision-support applications.
Germany
Orthopedic surgical centers in the Ruhr corridor accelerate adoption of sensor-integrated joint replacement platforms with embedded force sensing capabilities. EU MDR conformity assessment harmonization streamlines biocompatibility validation for hermetic encapsulation technologies. The country's precision manufacturing ecosystem anchors captive semiconductor fabrication for implantable neuromodulation devices.
Switzerland
Swissmedic maintains stringent biocompatibility and electromagnetic compatibility validation burdens that reinforce premium positioning for precision-manufactured surgical chips. The precision manufacturing corridor attracts concentrated foundry investment from implantable device manufacturers. Geneva-Lausanne medical technology clusters specialize in silicon-on-insulator substrate processing for extended biostability requirements.
Japan
METI medical device innovation subsidies accelerate domestic production capacity for biocompatible sensor die fabrication. PMDA regulatory tailwinds support localized supply chain development for implantable cardiac rhythm management platforms. The Kanto region around Tokyo concentrates demand from integrated delivery networks managing multi-year capital cycles for closed-loop therapeutic systems.
United Kingdom
Academic medical centers pilot preclinical algorithm-enabled surgical chips under investigational device exemptions, bridging research and commercial pathways. MHRA post-Brexit regulatory autonomy enables tailored conformity assessment timelines for novel wireless communication architectures. London-Southeast biomedical engineering departments drive electronic health record integration requirements for proprietary data telemetry protocols.
Surgical Chips Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence redrawing competitive boundaries between wafer-scale foundry operators and fabless design houses. The upper tier secures supply continuity through captive semiconductor fabrication, while mid-tier players compete via specialized diagnostic sensor foundry services. Strategic archetypes include backward-integrated device manufacturers, biocompatibility-focused foundry specialists, and algorithm-centric fabless designers. Dominant competitive moves encompass strategic partnerships bridging medical device and consumer electronics semiconductor processes, plus portfolio diversification into wireless communication-enabled diagnostic sensors.
Among integrated medical technology conglomerates, Medtronic and Abbott Laboratories exemplify the backward-integration archetype through in-house production of custom sensor die for implantable platforms. Thermo Fisher Scientific occupies a position within the specialized foundry tier, representing biocompatibility-focused contract manufacturing capabilities that bridge ISO 13485 quality requirements with semiconductor process nodes. These three entities collectively illustrate the market's vertical stratification between captive supply strategies and outsourced precision fabrication.
| Leading Market Players |
|---|
| Medtronic |
| Boston Scientific |
| Abbott Laboratories |
| Johnson & Johnson |
| Stryker Corporation |
| B. Braun Melsungen AG |
| Agilent Technologies |
| Thermo Fisher Scientific |
| GE Healthcare |
| Others |
Value Chain & Pricing Dynamics
Wafer-scale foundry utilization rates above 85% in Taiwan and South Korea compress margin flexibility for fabless surgical chip designers while elevating price floors for implantable device manufacturers. This capacity tightness concentrates pricing power among captive semiconductor fabricators like Medtronic and Abbott Laboratories, forcing mid-tier players toward specialized diagnostic sensor foundry services with biocompatibility premiums.
Pricing Analysis
After-sales calibration service contracts and disposable electrode attachments generate the deepest lifetime value pools for diagnostic sensor manufacturers. Three-tier pricing structure across premium implantable platforms, standard perioperative devices, and economy-grade disposable sensors reflects FDA premarket approval tier differentiation and ISO 13485 certification grade. Cost compression in economy-grade disposable sensors intensifies as United States ambulatory surgical centers squeeze per-procedure pricing through unbundled procurement. Hospital value analysis committees exhibit lowest price sensitivity for multi-year biostability warranties on hermetically sealed neuromodulation platforms.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg ports constrain just-in-time delivery for silicon-on-insulator substrates sourced from East Asian foundries. Taiwan, South Korea, and Japan anchor wafer processing capacity for medical-grade semiconductor fabrication, drawing from platinum-iridium electrode supplies concentrated in South African mining operations. Single-source vulnerability in titanium-ceramic hermetic sealing equipment amplifies production ramp risk for implantable device manufacturers. Distribution runs through hospital value analysis committees for capital platforms and consumable distribution networks for disposable sensors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Surgical chip incumbents face substitution pressure from algorithm-enabled diagnostic platforms that displace hardware-centric perioperative monitoring. Incumbents must navigate this threat through defensive capability investments that preserve margin pools in implantable neuromodulation.
For Market Incumbents: Shield proprietary near-field protocol ecosystems through backward integration into custom sensor die production, denying fabless competitors access to biocompatible wafer processing. Fortify FDA breakthrough device designation pipelines to accelerate clinical validation timelines against emerging algorithm-enabled substitutes. Prioritize captive semiconductor fabrication capacity expansion in Switzerland's precision manufacturing corridor to secure supply continuity during foundry allocation constraints.
For New Entrants and Emerging Players: Differentiate on ultra-wideband telemetry integration for ambulatory surgical center channels where incumbent footprint remains shallow. Target United States outpatient facilities with per-procedure consumable pricing models that compress hospital procurement committee influence. Penetrate through disposable electrode business models with unbundled hardware acquisition and recurring calibration service agreements.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diagnostic sensor manufacturers with established calibration service contracts and disposable attachment ecosystems. Five-to-ten year viability favors biocompatibility-focused foundry specialists bridging ISO 13485 quality requirements with sub-micron semiconductor process nodes. Monitor FDA cybersecurity premarket submission guidance evolution as inflection indicator for algorithm-enabled surgical chip valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Designation | Expedited review compresses premarket timelines for closed-loop neuromodulation platforms addressing unmet neurological conditions. |
| EU MDR Conformity Assessment Harmonization | Streamlined biocompatibility validation reduces redundant testing burdens for hermetic encapsulation technologies. |
| Hospital System Partnership | Electronic health record integration agreements secure multi-year capital cycles for implantable cardiac rhythm management platforms. |
| Software Companion Development | Algorithm-enabled diagnostic sensors with autonomous decision-support capabilities face elevated EU AI Act risk classification scrutiny. |
| Reimbursement Strategy | Coverage determination alignment with CMS Medicare pathways accelerates ambulatory surgical center adoption of wireless perioperative monitors. |
Study Parameters
A standing panel of biomedical engineers, hospital purchasing committee chairs, GPO contracts managers, and regulatory affairs specialists provided ongoing calibration across primary interview rounds. Secondary validation drew from FDA premarket notification databases, EU MDR conformity assessment records, hospital procurement databases, and ISO 13485 certification registries. Bottom-up surgical chip volume estimates triangulated against top-down medical device semiconductor consumption benchmarks.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type segmentation by durability tier, technology segmentation by electromagnetic compatibility certification burden, end user segmentation by procurement committee structure, and application segmentation by maturity gradient. CAGRs derived from surgical intervention adoption velocity and patient monitoring replacement cycles, with inputs from platinum-iridium price volatility indices and foundry capacity utilization reports.
The analysis sits within stated boundaries; outcomes outside FDA premarket approval pathway stability, EU AI Act risk classification finalization, or hermetic sealing yield recovery would require recalibration. Forecasts reflect assumptions regarding biocompatibility validation timeline compression and wireless communication protocol standardization. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Data Processing Neuromorphic Chip Market
Chipset and Processors
India Data Center Processor Market
Chipset and Processors
Global Graphic Processors Market
Chipset and Processors
Microserver Market
Chipset and Processors
Europe 8- Bit Microcontroller Market
Chipset and Processors
Nano Chip Market
Chipset and Processors
Global Merchant Embedded Computing Market
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
Data Center Chip Market
Chipset and Processors
Machine Learning Chip Market
Chipset and Processors
Europe Wi-Fi Chipset Market
Chipset and Processors
Smartwatch Chips Market
Chipset and Processors
DNA Sequencing Chip Market
Chipset and Processors
Envelope Tracking Chips Market
Chipset and Processors
Chiplet Technology Market
Chipset and Processors
Application Processor Market