
 France Data Center Processor Market | 2026-2036
France Data Center Processor Market Size, Share, and Industry Trends Forecast 2026-2036
France Data Center Processor Market Insights
Modular chiplet packaging is repositioning procurement patterns across French data center operators. Intel Corporation leverages its foundry partnerships to sustain x86 dominance in enterprise rack deployments. NVIDIA Corporation anchors GPU-heavy AI training configurations in the Paris region. Kalray differentiates through its Massively Parallel Processor Array architecture for edge-to-core data flows.
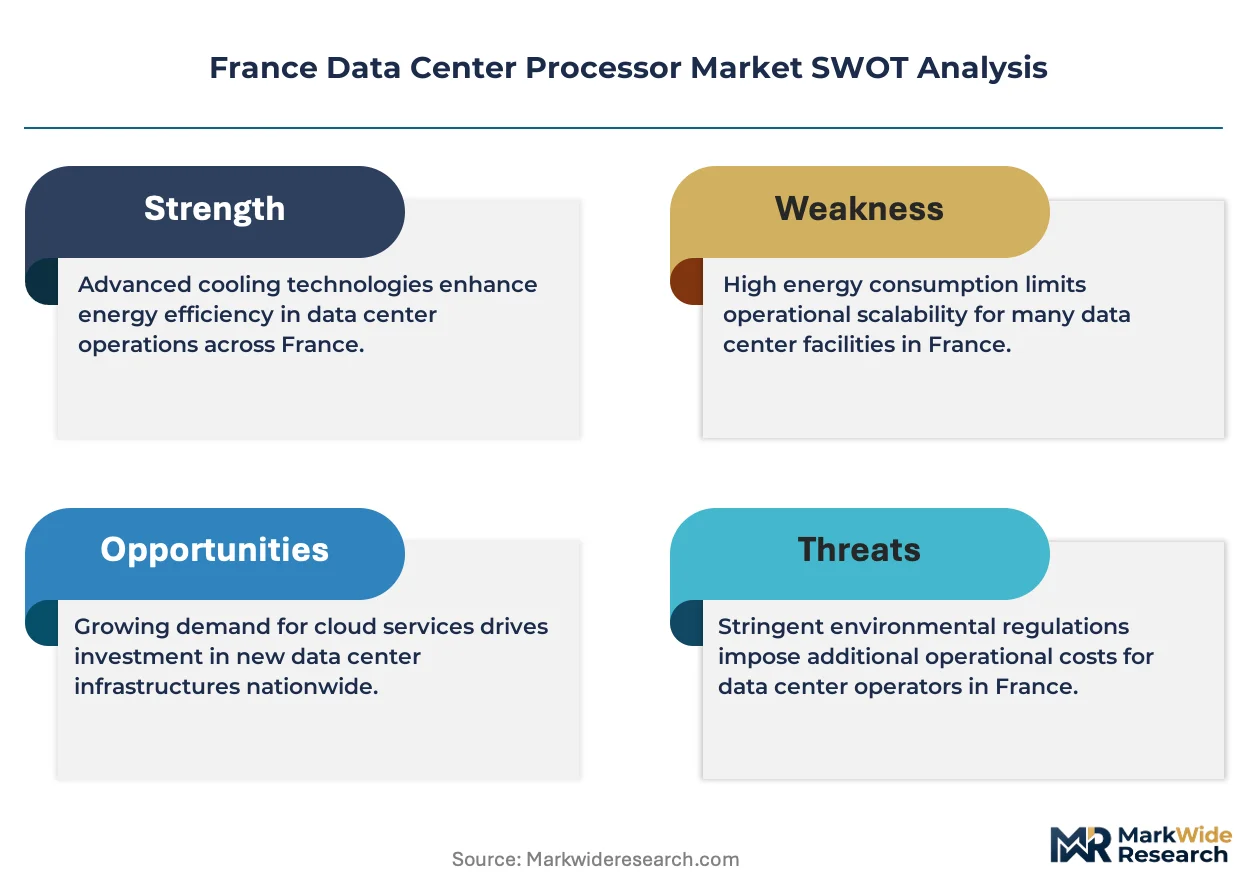
A data center processor is a silicon integrated circuit designed to execute computational workloads within server infrastructure, typically fabricated on process nodes between 3nm and 7nm with thermal design power ratings from 150W to 500W. Its primary purpose is to process transactions, run virtualized environments, and accelerate machine learning inference at scale. Multi-core configurations lead volume shipments for virtualization and cloud computing workloads, while ARM architecture gains traction among cloud service providers seeking performance-per-watt optimization. AI Processing represents the fastest-growing application segment as French enterprises deploy large language models on domestic sovereign cloud infrastructure.
The CNIL enforces GDPR-aligned data localization requirements that shape processor procurement for sensitive workloads, while the EU AI Act mandates risk-classification documentation for high-risk automated decision systems. France's adherence to REACH and RoHS directives constrains material composition in semiconductor packaging, pushing suppliers toward lead-free substrates and reduced rare-earth content. Stakeholders must monitor how the EU Chips Act's France-based fabrication incentives alter domestic supply security versus import dependency for advanced node processors.
Market Dynamics
France's data center processor procurement is restructuring around sovereign AI infrastructure mandates and the EU AI Act's risk-classification requirements for high-risk automated systems. Cloud operators in the Paris-Saclay corridor are reconfiguring rack architectures to accommodate CNIL-mandated data localization for sensitive workloads.
Growth Catalysts
- EU AI Act risk-tier documentation:High-risk processing workloads require algorithmic transparency documentation, creating specialized demand for traceable compute architectures in French sovereign cloud deployments.
- Nuclear-powered hyperscale concentration:Low-carbon baseload power at Gravelines and Magny-Cours anchors energy-intensive AI training clusters under France's national cloud strategy.
- Chiplet modularity:Disaggregated processor packaging enables French operators to mix compute, memory, and I/O dies from heterogeneous suppliers within unified rack designs.
Market Restraints
- Advanced node import dependency:France lacks domestic EUV lithography capacity, forcing reliance on Taiwan and South Korea for sub-5nm processor fabrication.
- CNIL-GDPR compliance friction:Data localization requirements for sensitive workloads fragment processor procurement across sovereign and non-sovereign infrastructure tiers.
- Rare-earth supply concentration:Semiconductor packaging materials face sourcing constraints under REACH and RoHS directive restrictions on lead-free substrate alternatives.
Strategic Opportunities
- Occitanie edge-to-core corridor:Underdeveloped data center capacity in southern France offers greenfield deployment potential for latency-sensitive AI inference at the network edge.
- EU Chips Act fabrication incentives:France-based advanced packaging subsidies could reduce import dependency for processor assembly and test operations.
- ARM architecture penetration:Cloud service providers are evaluating RISC-V and ARM alternatives to x86 for performance-per-watt optimization in nuclear-powered facilities.
Industry Challenges
- AI infrastructure talent scarcity:Shortage of technicians qualified in liquid-cooled rack deployment and high-density power distribution constrains deployment velocity at Ile-de-France campuses.
- Legacy virtualization stack integration:Enterprise data centers face forklift upgrades to accommodate GPU-heavy training configurations alongside existing x86 virtualization estates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Data Center Processor Market |
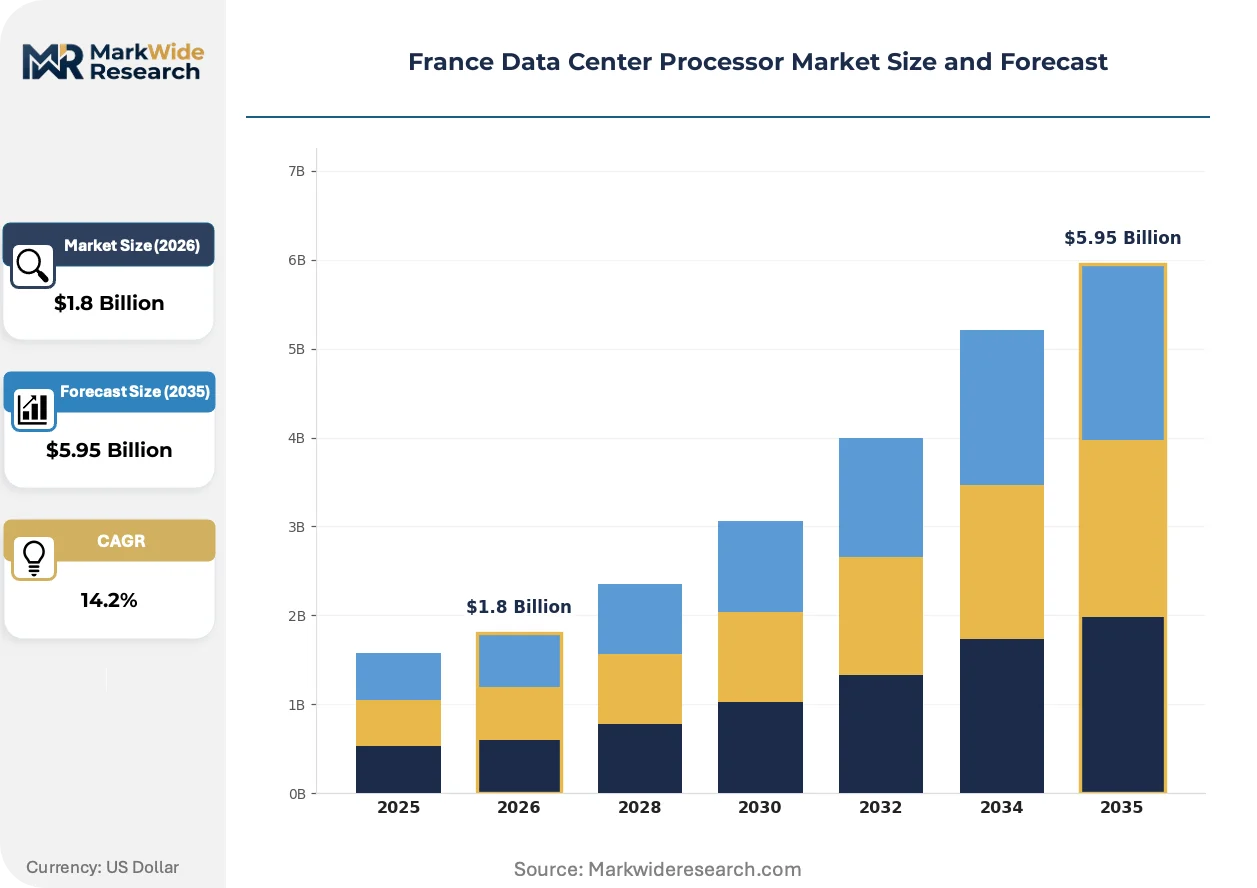
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Processor Type: Single-Core, Multi-Core, Dual-Core, Quad-Core Architecture: x86, ARM, RISC, PowerPC End User: SMEs, Large Enterprises, Cloud Service Providers, Government Agencies Application: Data Analytics, Virtualization, Cloud Computing, AI Processing |
| Companies Covered | Broadcom Inc., Cisco Systems, Intel Corporation, Hewlett Packard Enterprise, Dell Technologies, Advanced Micro Devices Inc., Kalray, IBM, NVIDIA Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Data Center Processor Market Trends and Innovations
Processor architectures in French data centers are fragmenting across workload-specific optimizations. Sovereign cloud requirements, thermal density constraints, and heterogeneous compute demands are forcing rack-level redesigns rather than incremental server replacements.
Chiplet-based processor disaggregation is absorbing packaging complexity previously managed at the monolithic die level. French hyperscale operators are adopting multi-vendor chiplet ecosystems to customize memory bandwidth and compute ratios for AI training versus inference workloads. This modularity is absorbing margin pressure from foundry capacity constraints by enabling yield optimization across smaller die footprints.
The EU AI Act's risk-classification framework is mandating documentation trails for high-risk automated decision systems. Processor deployments in French financial and healthcare sectors must now maintain algorithmic transparency logs, driving demand for traceable compute hardware with immutable firmware attestation. CNIL enforcement of these provisions is accelerating procurement cycles for certified sovereign infrastructure.
Cloud service providers are consolidating processor procurement around direct-foundry relationships, bypassing traditional distribution channels. Large French operators are negotiating volume commitments with TSMC and Samsung for advanced node allocation, compressing intermediary margins in the semiconductor supply chain. This disintermediation is most visible among Paris-Saclay corridor tenants building domestic AI training capacity under national cloud strategy mandates.
France Data Center Processor Market Segmentation
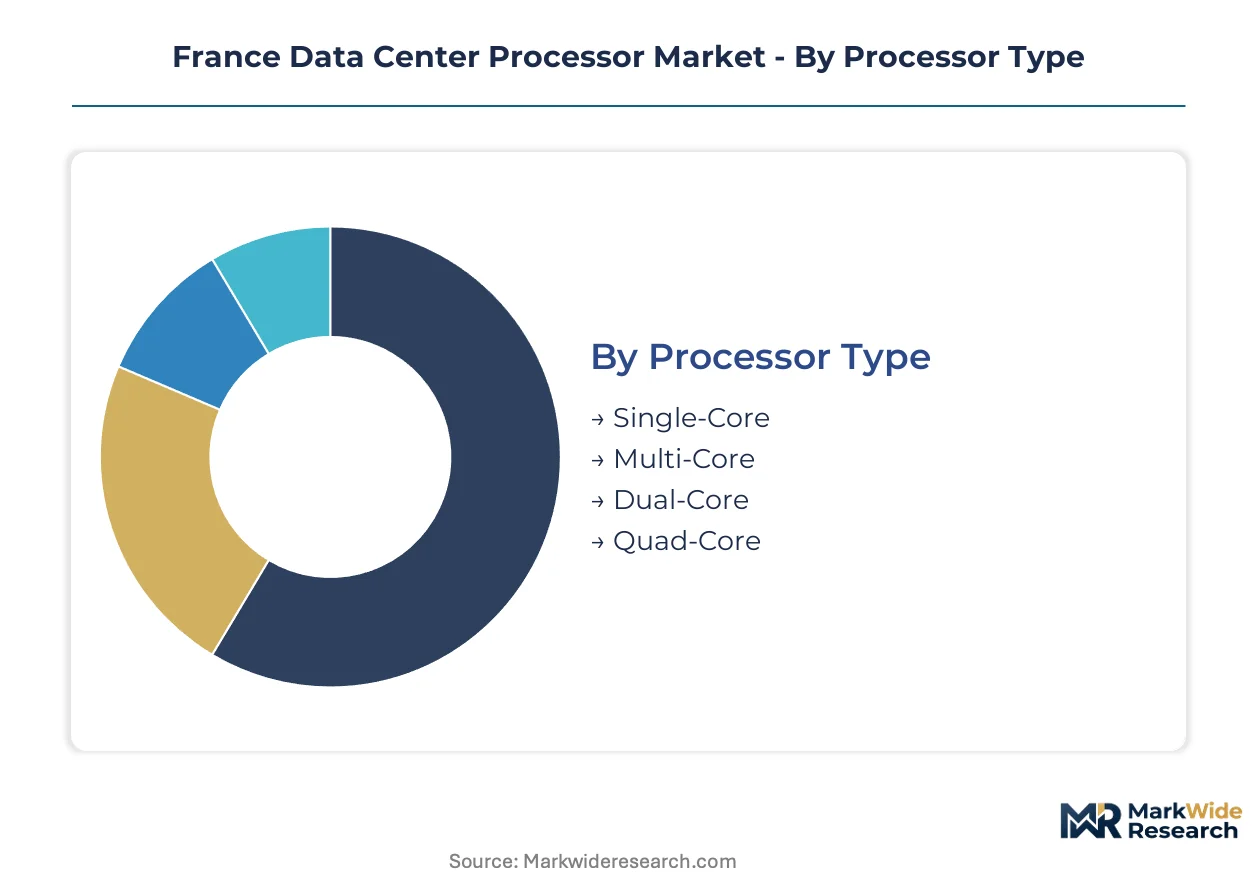
Processor segmentation in France reflects divergent compliance burdens across workload types. CNIL-mandated data localization and EU AI Act risk tiers create procurement fragmentation where certification requirements vary sharply by deployment context.
Processor Type:
Certification intensity scales with core density, as multi-core configurations face stricter thermal and electromagnetic compliance testing under EU CE marking directives.
- Multi-Core:Silicon integrating 8 to 64 cores on a single die enables parallel execution of containerized workloads. Demand concentrates at Ile-de-France hyperscale campuses where virtualization density requirements drive procurement. These configurations face elevated scrutiny under France's nuclear facility proximity regulations for electromagnetic interference.
- Dual-Core:Two-core designs balance legacy software compatibility with modest power envelopes. French SMEs in Occitanie and Auvergne-Rhône-Alpes favor these units for on-premise ERP systems where upgrade cycles lag cloud-native adoption. REACH substrate restrictions affect packaging costs disproportionately here.
- Quad-Core:Mid-range four-core processors serve departmental servers in regional healthcare networks.
- Single-Core:Legacy embedded controllers persist in industrial edge gateways.
Multi-Core sits at the top of the volume ranking, with Dual-Core climbing the fastest as regional enterprises modernize legacy estates.
Architecture:
Cost tier stratification separates premium x86 licenses from emerging ARM alternatives where total cost of ownership drives cloud provider evaluation.
- x86:Dominant instruction set architecture from Intel and AMD underpins enterprise virtualization stacks. French financial institutions in Paris-La Défense maintain x86 hegemony for risk-classified workloads requiring immutable firmware attestation under EU AI Act documentation rules.
- ARM:Reduced instruction set designs from Ampere and AWS Graviton gain traction in Gravelines nuclear-powered facilities where performance-per-watt optimization reduces cooling capital expenditure. Cloud service providers evaluate these for inference-heavy AI pipelines.
- RISC:Open instruction set architectures attract sovereign cloud pilots.
- PowerPC:Legacy deployments persist in defense and aerospace compute clusters.
x86 maintains volume leadership, though ARM gains share fastest among Paris-Saclay corridor operators reconfiguring for sustainability targets.
End User:
Application criticality varies by customer type, with government agencies facing mandatory Common Criteria certification that elongates procurement cycles.
- Cloud Service Providers:Hyperscale operators including OVHcloud and Scaleway drive demand for disaggregated chiplet configurations. These buyers negotiate direct-foundry relationships with TSMC and Samsung, bypassing distribution channels to secure advanced node allocation for AI training clusters.
- Government Agencies:Ministries and public hospitals require ANSSI-certified processors with hardware root-of-trust features. CNIL enforcement of GDPR Article 44 restricts cross-border data flows, mandating domestic sovereign infrastructure with traceable compute architectures.
- Large Enterprises:CAC 40 corporations in banking and pharmaceuticals balance hybrid cloud strategies.
- SMEs:Mid-market firms in regional cities favor refurbished x86 servers.
Cloud Service Providers dominate procurement volume, with Government Agencies expanding most quickly under national cloud strategy mandates.
Application:
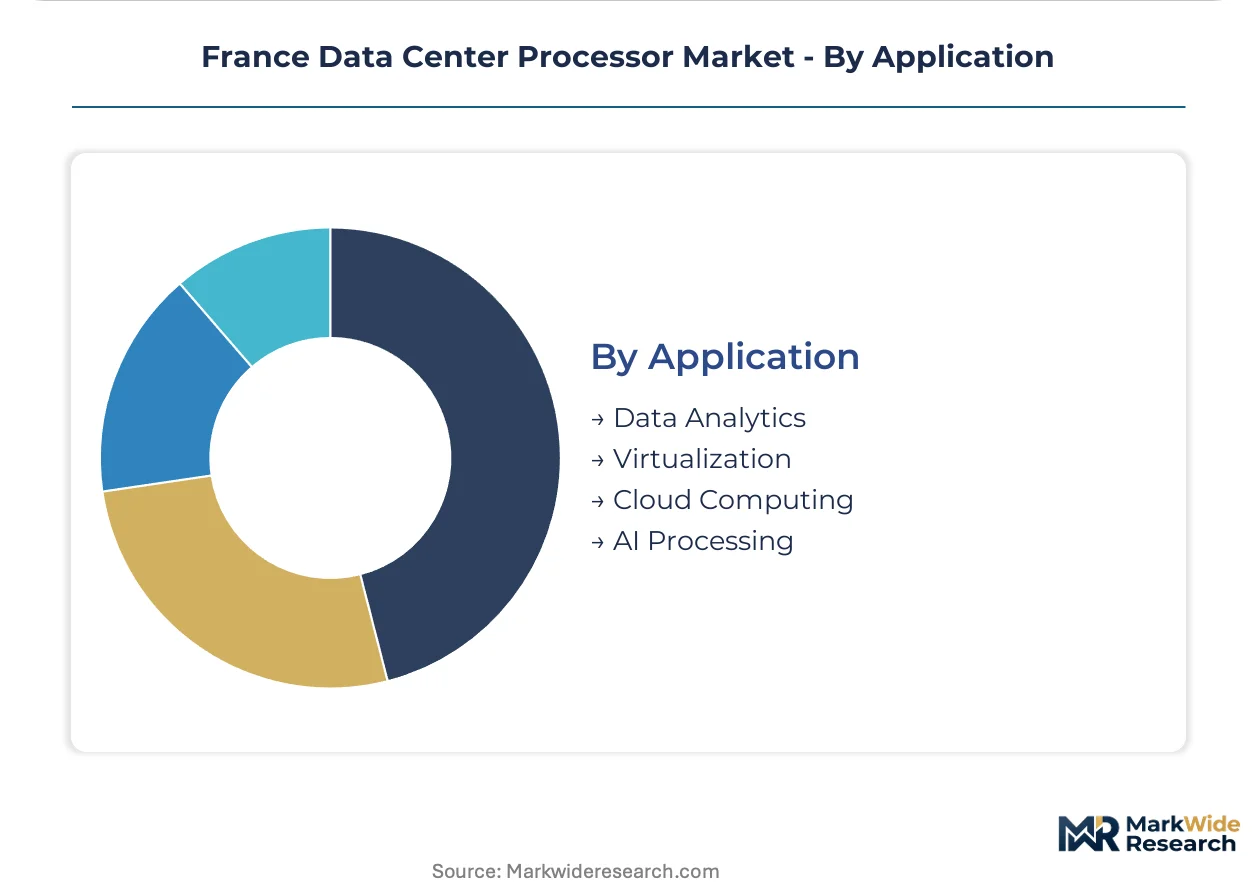
Margin profiles diverge sharply by workload, with AI Processing commanding premium pricing against commoditized virtualization.
- AI Processing:Tensor-optimized silicon with matrix multiplication accelerators executes large language model training and inference. French sovereign AI infrastructure in the Paris-Saclay corridor requires these processors to maintain algorithmic transparency logs under EU AI Act high-risk system documentation.
- Virtualization:Hypervisor-optimized processors with extended page tables enable dense multi-tenant server consolidation. Legacy enterprise data centers in Lyon and Marseille face forklift upgrade cycles to accommodate GPU-heavy configurations alongside existing estates.
- Cloud Computing:General-purpose compute for elastic workload orchestration.
- Data Analytics:Memory-bandwidth-intensive configurations for batch processing.
Virtualization retains volume leadership, while AI Processing follows the steepest expansion trajectory as domestic LLM deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The data center processor industry traces its commercial scaling to Silicon Valley's semiconductor fabrication advances of the 1970s, with European demand consolidation following France's nuclear electrification programs and Germany's industrial automation push.
Île-de-France
Hyperscale campuses at Gravelines and Magny-Cours anchor domestic AI training capacity under France's national cloud strategy. The CNIL enforces GDPR Article 44 data localization for sensitive workloads processed in Paris-Saclay corridor facilities. OVHcloud and Scaleway negotiate direct-foundry relationships for advanced node allocation.
Auvergne-Rhône-Alpes
Lyon hosts enterprise data centers facing forklift upgrade cycles to accommodate GPU-heavy configurations alongside legacy x86 virtualization estates. REACH and RoHS directives constrain packaging materials for regional semiconductor assembly operations. Grenoble's microelectronics cluster supplies packaging expertise to domestic processor integrators.
Provence-Alpes-Côte d'Azur
Marseille's submarine cable landing stations position the region for Mediterranean data transit hub status. The EU AI Act's high-risk system documentation requirements affect financial services processors deployed in Sophia Antipolis technology parks. Edge-to-core latency optimization drives ARM architecture evaluation for inference workloads.
Hauts-de-France
Gravelines nuclear facility proximity enables carbon-neutral compute deployments for energy-intensive AI training clusters. ANSSI certification requirements elongate procurement cycles for government agency processors in Lille's administrative centers. Low-carbon baseload power attracts cloud service provider concentration.
Occitanie
Toulouse's aerospace compute clusters sustain legacy PowerPC deployments for defense applications. Greenfield data center capacity offers latency-sensitive AI inference potential at France's southern network edge. Regional SMEs favor refurbished x86 servers for on-premise ERP systems.
France Data Center Processor Market Competitive Landscape
Premium-margin players sit above commodity-margin players across sovereign certification and advanced node access vectors. The vendor base concentrates around three tiers: direct-foundry negotiators securing TSMC allocation, domestic packaging specialists serving ANSSI requirements, and distribution-channel players serving SME refurbishment cycles. Archetypes include hyperscale-integrated silicon vendors, sovereign-cloud certification specialists, and modular chiplet ecosystem assemblers. Competitive moves center on strategic partnerships with nuclear-powered facility operators and portfolio diversification into ARM-based inference configurations.
Within the direct-foundry tier, Intel Corporation and NVIDIA Corporation exemplify hyperscale-integrated positioning through their Paris-Saclay corridor presence. Kalray occupies a specialist position as a France-based S.A. exemplifying domestic sovereign-cloud certification capabilities. These three anchors represent divergent strategic responses to CNIL-mandated data localization and EU AI Act documentation requirements.
| Leading Market Players |
|---|
| Broadcom Inc. |
| Cisco Systems |
| Intel Corporation |
| Hewlett Packard Enterprise |
| Dell Technologies |
| Advanced Micro Devices Inc. |
| Kalray |
| IBM |
| NVIDIA Corporation |
| Others |
Pricing and Supply Chain Analysis
Silicon wafer spot prices at the 300mm grade cascade through French data center processor procurement, compressing margins for distributors serving SME refurbishment cycles while amplifying pricing power for direct-foundry negotiators in the Paris-Saclay corridor. This commodity benchmark feeds into a supply chain where advanced node access determines tier placement and sovereign certification requirements add fixed-cost premiums.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates ANSSI-certified processors with hardware root-of-trust features from uncertified volume units and refurbished legacy stock. Price differentiation rests on certification grade and volume scale, with hyperscale operators commanding double-digit discounts through direct TSMC allocation commitments. Cost compression in the economy tier intensifies because SME buyers prioritize refurbished x86 servers over new ARM deployments. Cloud service providers exhibit lowest price sensitivity, while regional healthcare networks face budget constraints that elongate procurement cycles.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for sub-5nm EUV lithography capacity, constraining French operators' access to leading-edge silicon. Raw material dependencies draw from neon gas supplies, high-purity silicon ingots, and lead-free substrate materials compliant with REACH directives. Tariff exposure on semiconductor packaging equipment elevates risk for domestic assembly operations in Grenoble. Distribution runs through direct-foundry relationships for hyperscale buyers and authorized distributors serving government agency certification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The France Data Center Processor Market compounds steadily as sovereign AI infrastructure mandates under the national cloud strategy create durable demand for traceable compute architectures. Nuclear-powered baseload electrification at Gravelines and Magny-Cours anchors energy-intensive deployment economics.
For Market Incumbents: Hedge against ARM architecture displacement by securing packaging partnerships for chiplet modularity in Auvergne-Rhône-Alpes. Incumbents should deepen backward integration into advanced test operations to capture margin from ANSSI certification bottlenecks. Capacity addition in Île-de-France hyperscale corridors defends position against emerging domestic packaging specialists. For New Entrants and Emerging Players: The EU AI Act in France opens a window for sovereign-cloud certification specialists serving CNIL-mandated data localization requirements. New entrants should target Occitanie's greenfield edge-to-core corridor for latency-sensitive AI inference deployments. A go-to-market angle emphasizing hardware root-of-trust features penetrates government agency procurement cycles most effectively. For Investors and Strategic Acquirers: Consolidation pressure builds where ANSSI certification capabilities concentrate among domestic packaging specialists with Grenoble microelectronics cluster proximity. Acquisition target archetypes include modular chiplet ecosystem assemblers serving heterogeneous compute demand. The signal to watch is direct-foundry relationship announcements from Paris-Saclay corridor operators, indicating volume commitment credibility.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-Foundry Relationship Establishment | Bypasses distribution margins and secures TSMC allocation for AI training clusters. |
| ANSSI Certification Investment | Unlocks government agency procurement cycles under CNIL data localization mandates. |
| Chiplet Modularity Partnership | Enables yield optimization across smaller die footprints amid foundry capacity constraints. |
| Nuclear-Powered Facility Colocation | Reduces cooling capital expenditure through proximity to Gravelines baseload power. |
| ARM Architecture Portfolio Expansion | Captures performance-per-watt optimization demand from sustainability-targeted cloud operators. |
Research Methodology
Multiple input streams — hyperscale procurement officer interviews, semiconductor distribution channel assessments, and regulatory filing analysis — were reconciled to construct market estimates. Primary conversations engaged data center infrastructure directors, CNIL compliance consultants, foundry sales executives, and ANSSI certification auditors. Secondary validation drew from EU Chips Act implementation documents, CNIL algorithmic transparency enforcement records, and hyperscaler capex disclosures. Bottom-up unit shipment estimates and top-down value aggregation were cross-checked for consistency.
Data-stream reconciliation anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include processor type, architecture, end user category, and application workload, with regional regulatory cluster as an additional dimension. CAGRs were derived from slope analysis of historical shipment trajectories and forward-looking capacity commitment announcements. Industry-specific forecast inputs encompass nuclear facility proximity premiums and sovereign certification cycle durations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EU AI Act enforcement intensity shifts and Taiwan Strait logistics disruptions. Forecasts reflect documented assumptions about foundry capacity allocation and CNIL interpretation consistency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Accelerated Processing Unit (APU) Market
Chipset and Processors
Application Processor Market
Chipset and Processors
Smart Meters Chipset Market
Chipset and Processors
United Kingdom Data Center Processor Market
Chipset and Processors
Envelope Tracking Chips Market
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
Global ARM Microcontrollers Market
Chipset and Processors
Asia Pacific Data Center Processor Market
Chipset and Processors
Europe MPU Market
Chipset and Processors
Neuromorphic Chip Market
Chipset and Processors
China Edge AI Processor Market
Chipset and Processors
Nano Chip Market
Chipset and Processors
Microcontroller Unit (MCU) Market
Chipset and Processors
PC Processor Market
Chipset and Processors
Coprocessor Market
Chipset and Processors
Edge Artificial Intelligence Chips Market