
 Halitosis Treatment Market | 2026-2036
Halitosis Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Halitosis Treatment Market Outlook
Multi-source procurement of active ingredients is expanding as formulators seek supply resilience against botanical extract volatility. GlaxoSmithKline leverages its pharmaceutical heritage to sustain clinical credibility in therapeutic mouthwash formulations. Colgate-Palmolive anchors retail shelf presence through integrated oral care portfolios that span prevention and treatment. Procter & Gamble competes via brand architecture that extends consumer trust from mainstream toothpaste into specialized breath-care segments.
Halitosis treatment encompasses pharmaceutical and cosmetic interventions designed to neutralize volatile sulfur compounds, inhibit anaerobic bacterial proliferation, and restore oral microbiome balance, typically delivered through formulations containing cetylpyridinium chloride, zinc salts, or essential oil blends in alcohol-free or ethanol-based vehicles. The primary commercial purpose is to address chronic malodor through daily consumer regimens or professional-grade protocols administered under dental supervision. Mouthwash formulations capture the largest margin pool due to higher per-unit pricing and repeat purchase frequency, while toothpaste maintains volume leadership through habitual integration with brushing behavior. Pharmacy distribution channels are gaining structural importance as consumers shift toward pharmacist-curated recommendations over unguided supermarket selection.
The FDA regulates oral health product claims in the United States, distinguishing between cosmetic breath freshening and therapeutic antigingivitis indications, while the EPA oversees manufacturing discharge standards for chemical synthesis facilities producing active ingredients. EMA guidelines in Europe enforce substantiation requirements for microbiome-modulating claims, creating compliance barriers for entrants lacking clinical trial infrastructure. Stakeholders must monitor evolving regulatory distinctions between drug and cosmetic classification, as reclassification risk threatens existing distribution models and demands proactive formulation documentation strategies.
Market Dynamics
Pharmacy distribution channels are consolidating recommendation authority as consumers abandon unguided retail selection in favor of pharmacist-curated halitosis interventions, restructuring how therapeutic mouthwashes reach end-users.
Growth Catalysts
- EMA microbiome substantiation requirements:European regulatory pressure is elevating clinical trial infrastructure as a competitive moat, advantaging established formulators with documented efficacy data over commodity breath-freshening entrants.
- Dental clinic preventive service expansion:Professional channel growth in the United States and Germany is creating institutional prescription pathways for prescription-strength oral rinses beyond over-the-counter accessibility.
- Zinc salt formulation innovation:Advances in chelation chemistry are improving volatile sulfur compound neutralization without the astringency that limits consumer compliance with earlier therapeutic generations.
Market Restraints
- Botanical extract supply volatility:Essential oil feedstock concentration in Mediterranean and Southeast Asian growing regions exposes formulators to climate-driven harvest variability and price instability.
- FDA therapeutic-cosmetic classification friction:Ambiguous boundary enforcement between antigingivitis drug claims and cosmetic breath freshening creates compliance risk and marketing restriction uncertainty for multi-functional products.
- Alcohol-free vehicle substitution pressure:Consumer preference migration away from ethanol-based mouthwashes is compressing margins on legacy formulations while requiring costly reformulation cycles.
Strategic Opportunities
- Subscription pharmacy channels:Recurring delivery models through CVS Caremark and Walgreens Boots Alliance platforms are capturing adherence-driven replenishment revenue with higher lifetime value than episodic retail purchase.
- India CDSCO pathway acceleration:Streamlined domestic manufacturing registration for ayurvedic oral care hybrids is opening regulatory arbitrage for botanical-therapeutic combination products targeting price-sensitive volume markets.
- Connected oral health device convergence:Integration of halitosis detection sensors with smartphone applications is creating diagnostic-treatment feedback loops that drive product recommendation algorithms.
Industry Challenges
- Clinical microbiology talent scarcity:Shortage of oral microbiome specialists with regulatory documentation experience is extending trial timelines and inflating contract research organization fees.
- Multi-jurisdiction claim harmonization:Divergent FDA, EMA, and Health Canada evidentiary standards for volatile sulfur compound reduction claims forces redundant study designs and fragmented marketing assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Halitosis Treatment Market |
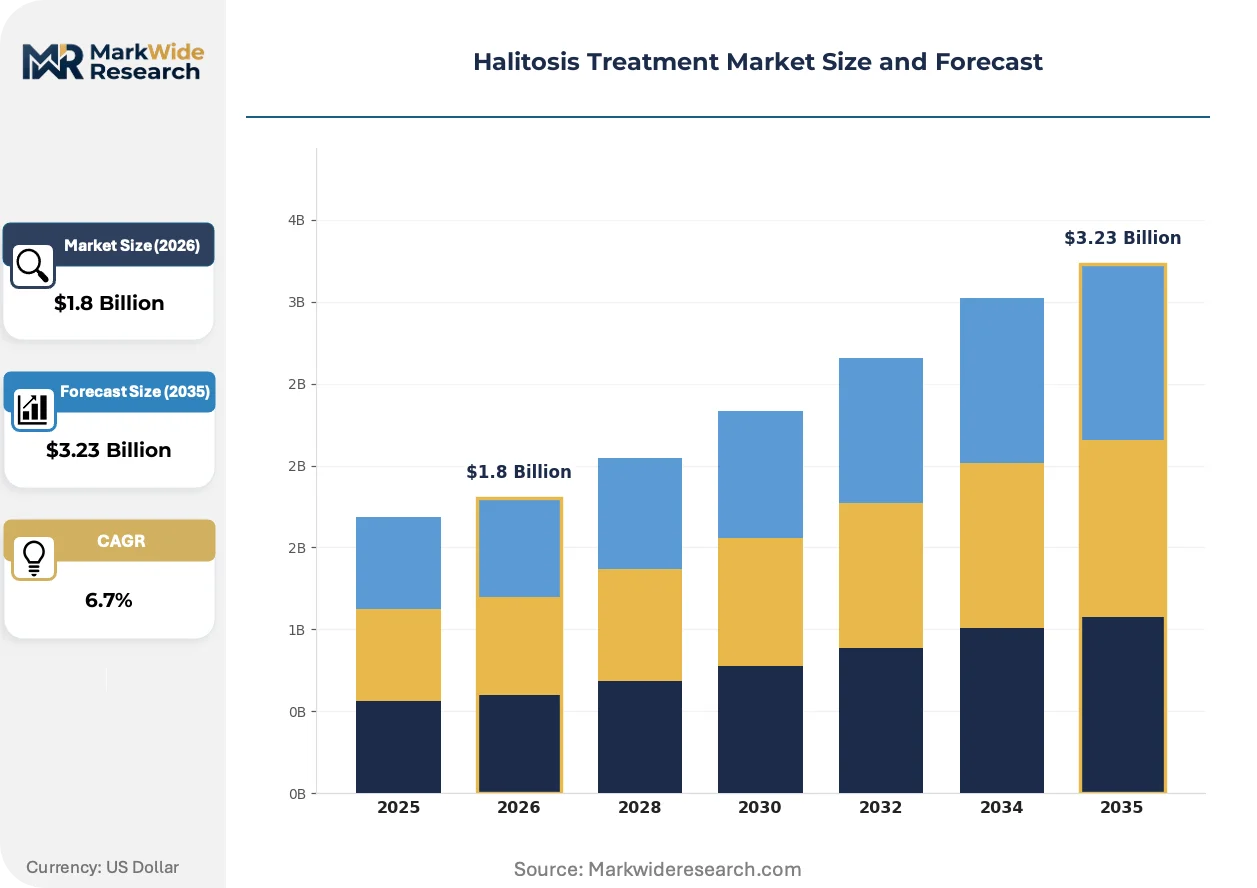
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mouthwash, Toothpaste, Chewing Gum, Sprays Application: Personal Care, Dental Clinics, Home Care, Pharmacy End User: Adults, Children, Seniors, Healthcare Professionals Distribution Channel: Online Retail, Supermarkets, Pharmacies, Direct Sales |
| Companies Covered | GlaxoSmithKline, Rowpar Pharmaceuticals, Colgate-Palmolive Company, Listerine, Dr. Harold Katz, Procter & Gamble, Church & Dwight, Abbott, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Halitosis Treatment Market Strategic Shifts
Formulation science and distribution architecture are converging to redefine how therapeutic oral care products demonstrate efficacy and reach consumers, with implications for competitive positioning across pharmacy, dental, and direct channels.
Probiotic bacterial strain technology is integrating live culture delivery into mouthwash and lozenge formats to competitively displace antiseptic approaches through microbiome restoration claims. Dental clinics in Germany and the Netherlands are piloting these formulations for chronic halitosis patients who have failed conventional antiseptic protocols. The structural consequence is a bifurcation between chemical suppression and biological rebalancing therapeutic paradigms, with the latter commanding premium positioning.
REACH substance restriction expansions are pressuring formulators to eliminate residual ethanol content and certain preservative systems from European-market products. Manufacturers serving EMA jurisdictions are accelerating alcohol-free vehicle development and submitting updated safety dossiers for cetylpyridinium chloride alternatives. This regulatory compression is most acute in mass-market retail segments where reformulation economics threaten margin structures.
Pharmacist consultation protocols are displacing self-directed shelf selection as the dominant halitosis product acquisition mode in United States retail pharmacy. CVS and Walgreens are deploying dedicated oral health counseling stations where staff recommend clinically validated rinses over cosmetic alternatives. This channel shift concentrates volume with formulary-approved brands and erodes impulse purchase dynamics that previously sustained secondary market entrants.
Halitosis Treatment Market Segmentation
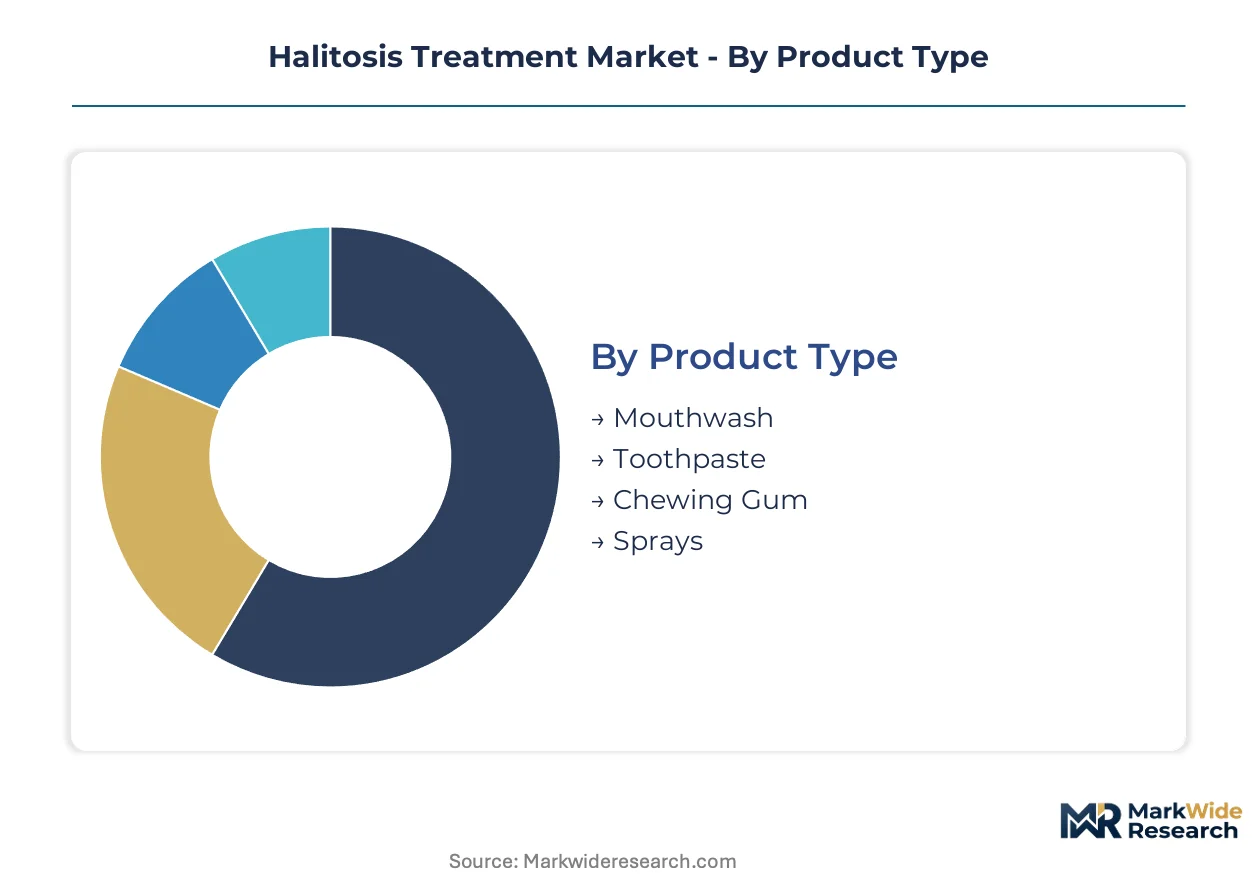
Halitosis treatment segmentation reveals divergent margin structures across delivery formats and channel economics. Product formulation choices determine clinical positioning authority, while distribution architecture governs consumer access patterns and repeat purchase mechanics.
Product Type:
Volume leadership concentrates in habitual-use formats, while premium capture accrues to specialized therapeutic vehicles requiring professional validation.
- Mouthwash:Liquid formulations containing cetylpyridinium chloride, zinc salts, or essential oil blends in alcohol-free or ethanol-based vehicles. Demand concentrates in pharmacy and dental clinic channels across the United States and Germany, where professional recommendation drives selection of therapeutic over cosmetic variants. Margin structures here exceed other formats due to higher per-unit pricing and subscription-enabled replenishment cycles.
- Toothpaste:Semi-solid delivery systems integrating breath-freshening actives with abrasive cleaning bases. Volume leadership stems from habitual integration with twice-daily brushing behavior, though therapeutic positioning requires FDA or EMA substantiation for antigingivitis claims that cosmetic breath-freshening formulations cannot access.
- Chewing Gum:Masticatory formats releasing flavor and active compounds through mechanical action. Brief functional duration limits clinical credibility despite convenience advantages in transient masking applications.
- Sprays:Aerosol or pump-dispensed solutions for portable, on-demand application. Niche positioning targets social and professional settings where discrete use takes priority over sustained therapeutic effect.
Today's leader: Mouthwash. Tomorrow's challenger: Toothpaste with validated therapeutic claims.
Application:
Channel authority is shifting from self-directed retail selection toward curated professional recommendation, restructuring how efficacy claims reach end-users.
- Personal Care:Individual consumer purchase for daily hygiene integration. CVS and Walgreens oral health counseling stations in the United States are displacing unguided supermarket selection with pharmacist-validated recommendations.
- Dental Clinics:Professional administration and prescription pathways for chronic halitosis protocols. Germany and Netherlands clinics pilot probiotic formulations for patients failing conventional antiseptic approaches.
- Home Care:Residential use without professional supervision. EMA microbiome substantiation requirements are elevating clinical documentation as a competitive barrier for entrants lacking trial infrastructure.
- Pharmacy:Retail pharmacy distribution with staff consultation. Recurring delivery models through CVS Caremark and Walgreens Boots Alliance platforms capture adherence-driven replenishment revenue.
Professional channels command premium positioning. Mass retail sustains volume scale.
End User:
Demographic targeting determines formulation tolerability requirements and clinical communication strategies.
- Adults:Primary commercial target with established purchasing autonomy and chronic condition awareness. Zinc salt formulation innovation addresses compliance barriers from astringency in earlier therapeutic generations.
- Children:Pediatric formulations requiring alcohol-free vehicles and palatability engineering. Safety dossier requirements for cetylpyridinium chloride alternatives intensify under REACH substance restriction expansions.
- Seniors:Age-associated xerostomia and polypharmacy interactions demand specialized vehicle chemistry. This segment gains share fastest as population aging concentrates in developed markets.
- Healthcare Professionals:Institutional procurement for clinical deployment. Prescription-strength oral rinses bypass over-the-counter accessibility limitations.
Adult consumers anchor current revenue. Senior-specific formulations expand the addressable base.
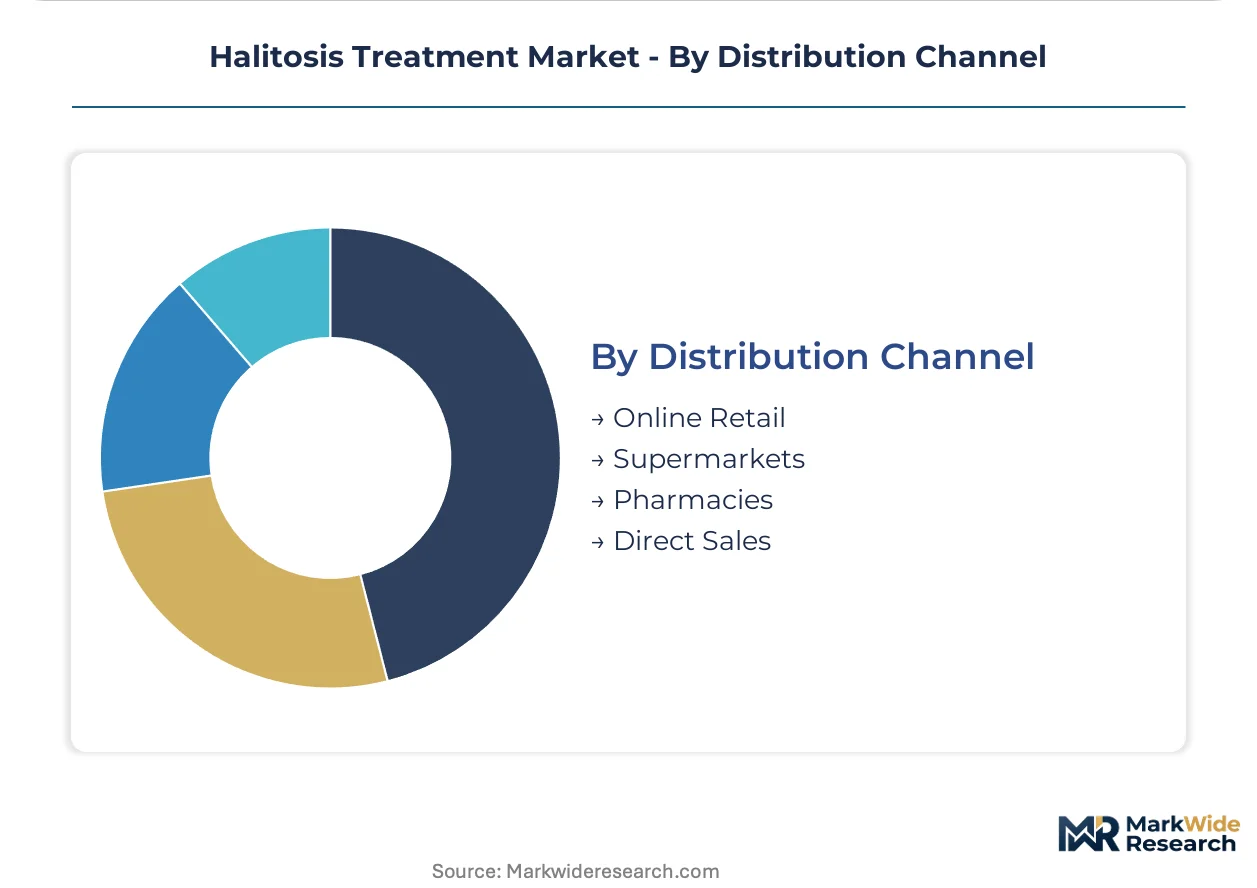
Distribution Channel:
Digital and physical channels are bifurcating between convenience-driven replenishment and validation-dependent initial selection.
- Online Retail:E-commerce platforms enabling subscription scheduling and direct-to-consumer education. Connected oral health device convergence creates diagnostic-treatment feedback loops driving algorithmic recommendations.
- Supermarkets:Mass retail with impulse purchase dynamics eroding as consumers abandon unguided selection. Margin compression from alcohol-free reformulation costs hits legacy brand structures hardest here.
- Pharmacies:Pharmacist-curated recommendation authority consolidating across North America and Europe. Formulary approval requirements concentrate volume with established clinical brands.
- Direct Sales:Manufacturer-controlled channels bypassing retail margin extraction. Limited penetration outside specialized therapeutic and professional-grade segments.
Pharmacy channels capture recommendation authority. Online retail scales replenishment efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping manufacturing footprints as formulators relocate active ingredient synthesis to jurisdictions with streamlined environmental compliance and lower documentation burdens for botanical extract processing.
United States
FDA therapeutic-cosmetic classification friction is elevating compliance costs for multi-functional mouthwash brands, yet pharmacy channel consolidation in CVS and Walgreens networks sustains premium pricing power for clinically validated formulations. The EPA oversees discharge standards for zinc salt production facilities concentrated in New Jersey and Ohio chemical corridors.
Germany
EMA microbiome substantiation requirements are extending trial timelines for probiotic oral care entrants, advantaging established players with existing clinical documentation infrastructure. REACH substance restrictions on residual ethanol content are accelerating alcohol-free vehicle development in Frankfurt-Rhine-Main pharmaceutical clusters.
India
CDSCO pathway acceleration for ayurvedic-therapeutic hybrids is attracting contract manufacturing investment from multinational formulators seeking cost-competitive botanical extraction. Maharashtra and Gujarat house the dominant essential oil processing facilities serving domestic and export markets.
Japan
PMDA stringent safety dossier requirements for pediatric formulations are compressing margin structures for alcohol-free vehicle development. The Kanto region around Tokyo concentrates distribution infrastructure for pharmacy and dental clinic channels.
Brazil
ANVISA harmonization delays with FDA evidentiary standards are fragmenting marketing assets for multinational brands operating across Latin America. São Paulo state anchors formulation and packaging operations for regional supply.
Halitosis Treatment Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue microbiome restoration claims and connected device integration. The vendor base stratifies across pharmaceutical heritage players, integrated consumer goods conglomerates, and specialized therapeutic formulators. Three archetypes dominate: clinical credibility builders leveraging regulatory documentation, retail shelf architects optimizing pharmacy formulary placement, and technology convergents embedding diagnostic feedback loops. Competitive moves concentrate on portfolio diversification into probiotic formats and strategic partnerships with pharmacy benefit managers for subscription channel access.
Within the pharmaceutical heritage tier, GlaxoSmithKline and Abbott exemplify clinical credibility positioning through therapeutic antigingivitis substantiation. Colgate-Palmolive occupies the integrated consumer goods archetype, anchoring retail presence through oral care portfolio breadth. Procter & Gamble sits within the brand architecture extension vector, translating toothpaste consumer trust into specialized breath-care segments.
| Leading Market Players |
|---|
| GlaxoSmithKline |
| Rowpar Pharmaceuticals |
| Colgate-Palmolive Company |
| Listerine |
| Dr. Harold Katz |
| Procter & Gamble |
| Church & Dwight |
| Abbott |
| Johnson & Johnson |
| Others |
Value Chain & Pricing Dynamics
Family-owned Mediterranean botanical extract processors anchor upstream supply, transmitting harvest volatility directly into formulation cost structures while pharmacy channel consolidation downstream extracts margin through formulary gatekeeping.
Pricing Analysis
Distributor margin layers in pharmacy channels compress net realized prices by 15-25 points versus direct dental clinic procurement. Three-tier pricing structure across premium therapeutic, standard cosmetic, and economy private-label levels stratifies by FDA substantiation status and professional endorsement depth. Pricing pressure stems from alcohol-free reformulation cycles mandated by REACH substance restrictions, with supermarket buyers exhibiting highest price sensitivity and dental clinic procurement showing lowest elasticity due to institutional protocol requirements.
Supply Chain Analysis
Essential oil feedstock supply rests on concentrated cultivation in Spain, Morocco, and Indonesia, with chelated zinc salt production anchored in Chinese and German chemical corridors. Formulators draw from Mediterranean botanical harvests, Southeast Asian spice extracts, and pharmaceutical-grade zinc oxide from Korean smelters. Single-source vulnerability concentrates in climate-exposed growing regions, while distribution runs through pharmacy benefit manager networks and dental supply cooperatives rather than traditional wholesale.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The halitosis treatment market functions as a stable compounder, with recurring replenishment mechanics in subscription pharmacy channels generating predictable revenue streams resistant to economic cyclicality.
For Market Incumbents: Acquire clinical trial documentation archives from distressed probiotic oral care entrants to preempt EMA microbiome substantiation requirements. Consolidate zinc salt chelation IP through targeted asset purchases, defending against commodity breath-freshening private-label erosion at supermarket retail. Channel control through CVS Caremark and Walgreens Boots Alliance formulary positioning remains the critical defensive lever. For New Entrants and Emerging Players: Capture white-space in senior-specific xerostomia formulations, where age-associated dry mouth creates underserved demand with premium pricing tolerance. Target India's CDSCO accelerated pathway for ayurvedic-therapeutic hybrids, leveraging Maharashtra extraction infrastructure for cost-competitive botanical sourcing. Go-to-market execution should prioritize direct-to-consumer education via connected oral health device partnerships rather than retail shelf competition. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap contract manufacturers with captive botanical extraction and existing FDA drug master files. Long-term viability over a 5-10 year horizon hinges on regulatory documentation moats deepening as EMA and FDA evidentiary standards diverge. Watch FDA therapeutic-cosmetic classification enforcement actions as the primary inflection signal for portfolio rebalancing between cosmetic and therapeutic positioning.| Strategic Initiative | Industry Significance |
|---|---|
| Probiotic Formulation Development | EMA microbiome substantiation requirements elevate clinical trial infrastructure as competitive barrier. |
| Subscription Pharmacy Channel Partnership | CVS Caremark and Walgreens Boots Alliance platforms capture adherence-driven replenishment revenue. |
| Alcohol-Free Vehicle Reformulation | REACH substance restrictions on residual ethanol compress margin structures for legacy formulations. |
| India CDSCO Registration Acceleration | Streamlined domestic manufacturing approval opens regulatory arbitrage for botanical-therapeutic hybrids. |
| Connected Device Integration | Halitosis detection sensor convergence with smartphone applications enables diagnostic-treatment feedback loops. |
Study Parameters
Direct dialogue with dental clinic procurement officers, pharmacy benefit manager formulary directors, oral microbiome researchers, and contract manufacturing executives grounded qualitative findings, validated against FDA 510(k) filings, EMA scientific advice letters, ClinicalTrials.gov protocol registrations, and pharmacy retail audit data from Nielsen and Circana. Bottom-up and top-down triangulation reconciled product-level volume estimates with national healthcare expenditure aggregates.
Bottom-up modeling segmented volume and value across mouthwash, toothpaste, chewing gum, and spray formats, further disaggregated by personal care, dental clinic, home care, and pharmacy applications, with end-user splits across adults, children, seniors, and healthcare professionals. CAGRs were derived from trend extrapolation of pharmacy channel data and dental service utilization patterns, incorporating zinc salt innovation cycles and probiotic clinical trial readouts as industry-specific demand drivers across the projection horizon.
Regulatory reclassification actions, botanical harvest failures, and pharmacist consultation protocol adoption rates are the dominant revision risks to modeled outcomes. Forecasts embed assumptions about EMA evidentiary standard stability and FDA enforcement consistency that warrant sensitivity testing. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oral Care
Kids Toothpaste Market
Oral Care
Xerostomia Treatment Market
Oral Care
Herbal Toothpaste Market
Oral Care
Oral Care Market
Oral Care
Europe Oral Care Market
Oral Care
United States Oral Hygiene Market
Oral Care
LED Oral Care Kits Market
Oral Care
Mouthwash Market
Oral Care
Asia-Pacific Oral Care Market
Oral Care
China Oral Care Market
Oral Care
Global Oral Care Products Market
Oral Care
Global Oral Hygiene Market
Oral Care
South America Oral Care Market
Oral Care
Manual Toothbrush Market
Oral Care
Toothcare Market
Oral Care
Dry Mouth Relief Market