
 Indonesia Data Center Cooling Market | 2026-2036
Indonesia Data Center Cooling Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Data Center Cooling Market Insights
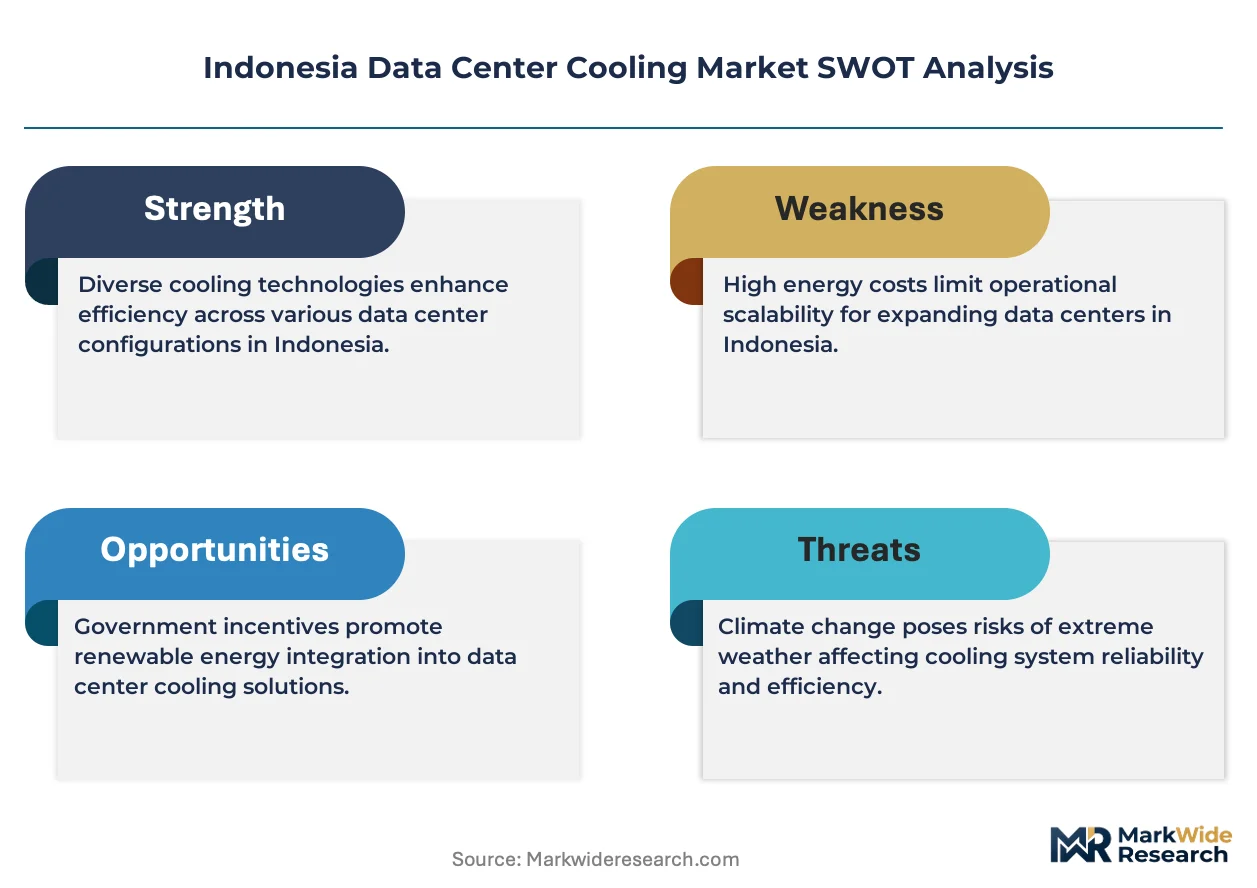
Indonesia's national energy efficiency mandates for data centers is hardening the cost-of-entry calculus for new facilities. Schneider Electric leverages its integrated power and cooling portfolio to anchor large-scale deployments across the archipelago. Vertiv Group competes through specialized thermal management systems designed for tropical humidity conditions. Stulz GmbH sustains its position with precision air conditioning engineered for high-density server environments.
Indonesia data center cooling encompasses engineered thermal management systems that regulate temperature, humidity, and air quality within server environments, typically operating within 18-27°C temperature bands and 40-60% relative humidity ranges to prevent hardware degradation and ensure continuous uptime. Liquid-based systems are capturing disproportionate investment as hyperscale operators confront rack densities exceeding 30 kW per cabinet. Air-based systems still dominate installed base economics across legacy enterprise facilities, though hybrid architectures are emerging as the fastest-growing configuration for brownfield retrofits. The maintenance services segment concentrates recurring revenue pools as tropical corrosion cycles compress equipment replacement intervals.
Indonesia's Ministry of Energy and Mineral Resources enforces building energy codes that directly constrain power usage effectiveness ratios, while BIS-aligned standards govern equipment safety certification for imported cooling infrastructure. The country's national data center sovereignty policies, administered through the Ministry of Communication and Informatics, mandate domestic data residency that expands local cooling capacity requirements. Stakeholders must monitor how upcoming carbon accounting rules from the national environmental regulator reshape capital allocation between air-cooled and liquid-cooled architectures.
Market Dynamics
Rack power densities exceeding 30 kW per cabinet are forcing Indonesian operators to abandon traditional air-cooled architectures in favor of liquid-based thermal management systems, compressing deployment timelines for hyperscale facilities across Java and Sumatra.
Growth Catalysts
- Ministry of Energy and Mineral Resources efficiency mandates:Building energy codes constrain power usage effectiveness ratios, accelerating capital flows into advanced cooling infrastructure that meets compliance thresholds.
- Hyperscale cloud expansion:Global cloud service providers are building dedicated facilities in Jakarta's corridor and Batam's cable landing zones, creating concentrated demand for high-capacity thermal systems.
- Submarine cable investments:New intercontinental fiber routes terminating in Batam and Jakarta elevate data sovereignty requirements, mandating local server capacity that requires domestic cooling solutions.
Market Restraints
- Copper and aluminum price volatility:Heat exchanger materials face commodity market swings that compress equipment margins and destabilize project budgeting for facility developers.
- Imported component dependency:Precision cooling equipment relies on supply chains concentrated in East Asian manufacturing hubs, exposing Indonesian deployments to extended lead times and tariff exposure.
- Tropical humidity corrosion cycles:Equipment degradation rates in coastal Indonesian climates exceed temperate-zone benchmarks, accelerating replacement intervals and inflating total cost of ownership calculations.
Strategic Opportunities
- East Kalimantan digital corridor:The Nusantara capital relocation project is seeding greenfield data center zones where liquid-cooled designs can deploy without legacy retrofit constraints.
- Hybrid architecture retrofits:Brownfield enterprise facilities in Surabaya and Bandung present conversion opportunities combining air and liquid systems for incremental density upgrades.
- Maintenance service unbundling:Compressed equipment lifecycles from tropical operating conditions create recurring revenue pools for predictive maintenance and corrosion-monitoring service contracts.
Industry Challenges
- Liquid cooling technician scarcity:Specialized skills for coolant loop installation and leak detection remain concentrated among a limited pool of certified professionals, constraining deployment velocity for hyperscale projects.
- BIS certification timelines:Equipment safety validation for imported cooling infrastructure extends procurement cycles, delaying facility commissioning schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Data Center Cooling Market |
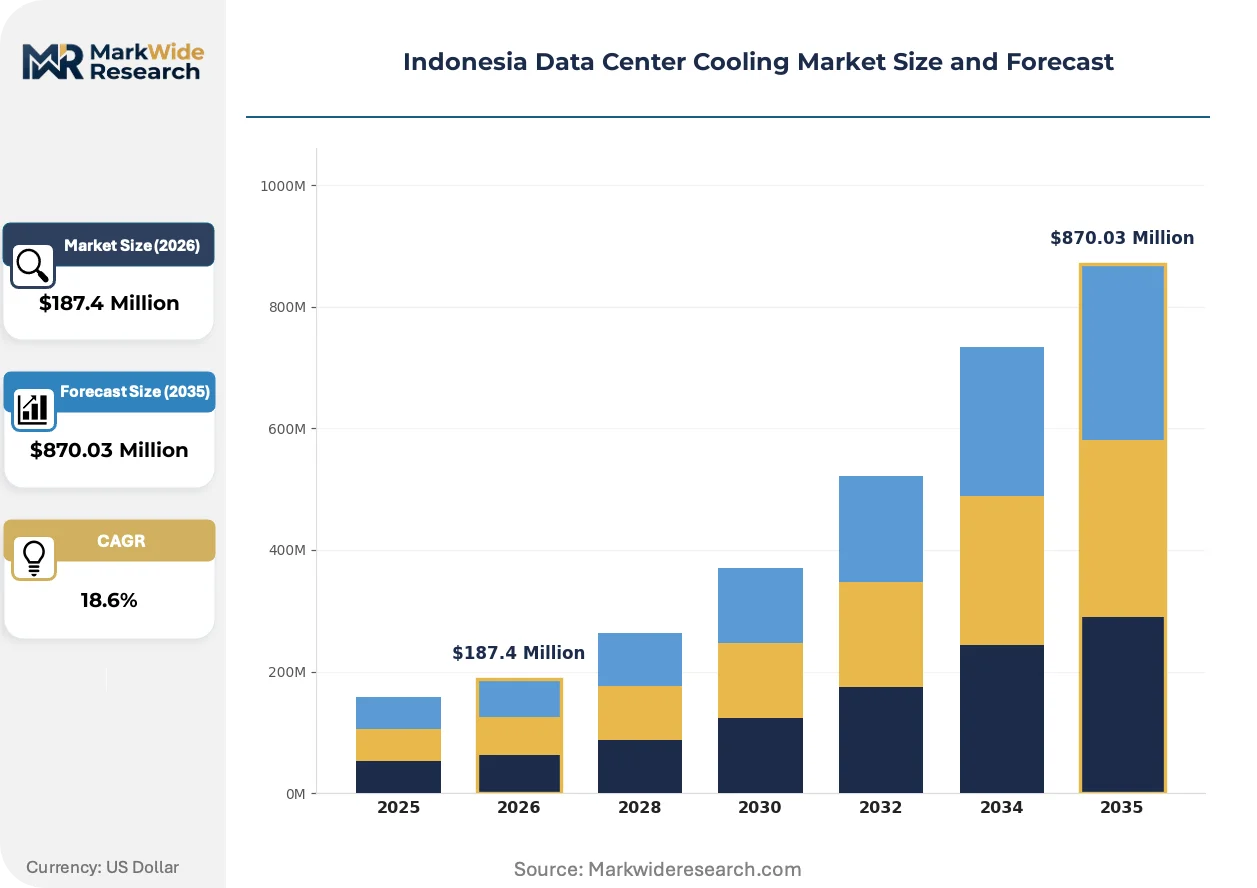
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $870.03 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-based Systems, Liquid-based Systems, Hybrid Systems, Immersion Cooling End User: Telecommunications, BFSI, IT & Telecom, Government Cooling Technique: In-row Cooling, Chiller-based Cooling, Direct Expansion Cooling, Raised Floor Cooling Service Type: Installation Services, Maintenance Services, Consulting Services, Data Analysis Services |
| Companies Covered | Schneider Electric, Vertiv Group, Johnson Controls International, Stulz GmbH, Emerson Electric, Mitsubishi Electric, Daikin, Carrier, Danfoss, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Data Center Cooling Market Trends and Innovations
Direct-to-chip liquid cooling is migrating from niche hyperscale applications toward mainstream enterprise adoption as rack densities render conventional air handling economically unviable across Indonesian facilities.
Immersion cooling systems using dielectric fluids are expanding into high-performance computing clusters operated by financial services and research institutions in Jakarta. These installations target 50-100 kW rack densities that exceed air-cooled practical limits. The technology is expanding into secondary Indonesian markets as equipment suppliers establish local service partnerships to address tropical humidity challenges.
Indonesia's Ministry of Communication and Informatics is tightening data residency enforcement through revised sovereignty policies that mandate domestic server location for specific data categories. This regulatory pressure is redirecting foreign cloud provider investment toward local facility construction rather than regional hub reliance. Cooling infrastructure vendors are responding by pre-certifying equipment to BIS-aligned standards to accelerate deployment timelines.
Hyperscale operators are consolidating vendor relationships to secure dedicated manufacturing capacity and priority service response. This concentration is displacing fragmented procurement patterns where facilities sourced cooling, power, and monitoring systems through separate channels. The shift is most visible among Batam-based facilities serving Singapore and Malaysian latency requirements.
Indonesia Data Center Cooling Market Segmentation
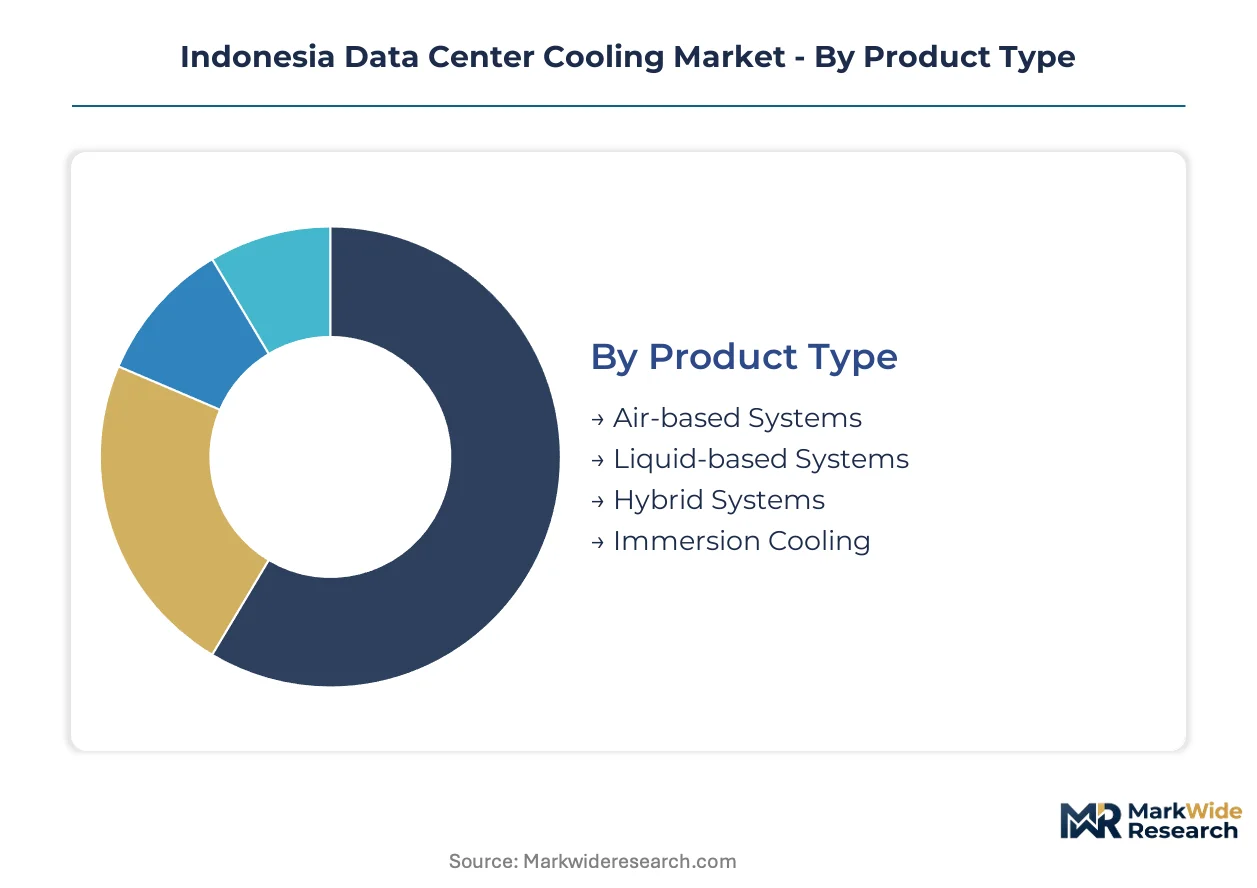
Indonesia's data center cooling market fragments across four distinct dimensions that each carry unique certification burdens and deployment economics. Equipment suppliers must navigate BIS-aligned safety standards differently depending on product architecture, while service providers face varying technical competency requirements across end-user verticals.
Product Type:
BIS certification timelines stretch longest for liquid-based and immersion systems due to pressure vessel safety protocols, while air-based equipment clears import validation faster under standard HVAC equipment categories.
- Air-based Systems:Conventional precision air conditioning units utilizing chilled water or direct expansion refrigerant cycles. Demand concentrates in legacy enterprise facilities across Surabaya and Bandung where retrofit economics favor incremental upgrades over full infrastructure replacement.
- Liquid-based Systems:Coolant distribution units and cold plate assemblies engineered for rack densities exceeding 30 kW. Hyperscale deployments in Jakarta's corridor and Batam's cable landing zones are absorbing capacity as cloud operators abandon air-cooled architectures.
- Hybrid Systems:Combined air and liquid thermal management architectures. Brownfield retrofits in secondary Indonesian markets present conversion opportunities for incremental density upgrades without full infrastructure replacement.
- Immersion Cooling:Dielectric fluid submersion systems for high-performance computing clusters. Financial services and research institutions in Jakarta deploy these for 50-100 kW rack densities exceeding practical air-cooled limits.
Air-based Systems sits at the top of the volume ranking, with Liquid-based Systems climbing the fastest.
End User:
Telecommunications and IT & Telecom verticals dominate procurement volume, though BFSI and Government segments command premium pricing tiers due to stricter uptime and data residency compliance requirements.
- Telecommunications:Domestic carriers and tower operators building edge computing infrastructure. Deployment concentrates in Java and Sumatra where subscriber density justifies distributed processing capacity.
- BFSI:Banking, financial services, and insurance institutions operating high-frequency trading and core banking platforms. Regulatory mandates from Indonesia's financial services authority drive investment in redundant cooling architectures.
- IT & Telecom:Cloud service providers and colocation operators. Global hyperscalers expanding dedicated facilities in Jakarta's corridor generate concentrated demand for high-capacity thermal systems.
- Government:Public sector data centers supporting national digital infrastructure. The Nusantara capital relocation project is seeding greenfield facility construction in East Kalimantan with sovereignty-compliant cooling requirements.
IT & Telecom captures the largest revenue share, with Government expanding most quickly on Nusantara project momentum.
Cooling Technique:
Installation complexity and commissioning timelines vary sharply across techniques, with chiller-based systems requiring extended civil works and direct expansion units deploying faster in modular configurations.
- In-row Cooling:Proximate air handling units positioned between server racks. Colocation facilities in Jakarta deploy these for targeted thermal management without building-wide HVAC renovation.
- Chiller-based Cooling:Centralized chilled water plants distributing cooling through raised floor plenums. Large-scale hyperscale campuses in Batam favor this architecture for operational efficiency at scale.
- Direct Expansion Cooling:Self-contained refrigerant systems eliminating water distribution infrastructure. Edge computing sites across Indonesia's outer islands prefer these for simplified maintenance logistics.
- Raised Floor Cooling:Underfloor air distribution through perforated tiles. Legacy enterprise facilities maintain these systems though operators increasingly supplement with in-row units for hot spot remediation.
Chiller-based Cooling holds the installed base advantage, with In-row Cooling gaining share fastest among retrofit projects.
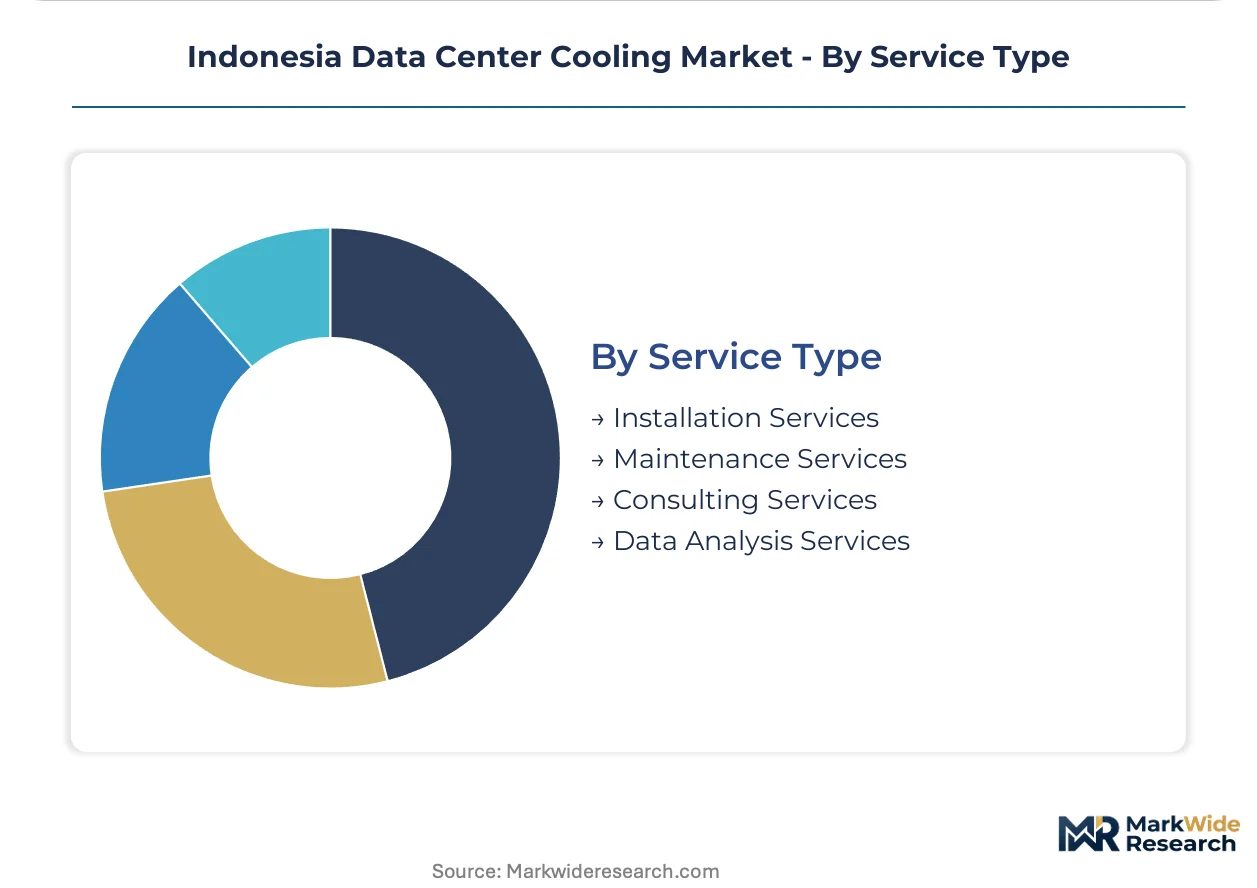
Service Type:
Recurring revenue concentration differs across service categories, with maintenance contracts generating predictable cash flows while installation and consulting remain project-dependent.
- Installation Services:Mechanical and electrical commissioning of cooling infrastructure. Tropical humidity conditions in coastal Indonesian climates compress installation windows and accelerate corrosion protection protocols.
- Maintenance Services:Predictive upkeep and equipment replacement programs. Compressed equipment lifecycles from tropical operating conditions create recurring revenue pools for corrosion-monitoring service contracts.
- Consulting Services:Thermal design optimization and energy efficiency audits. Operators navigating Ministry of Energy and Mineral Resources efficiency mandates seek third-party validation for compliance documentation.
- Data Analysis Services:Thermal monitoring analytics and predictive failure modeling. Facilities with high-density liquid cooling deployments require continuous coolant loop performance surveillance.
Maintenance Services generates the steadiest revenue streams, with Data Analysis Services showing the steepest expansion trajectory as monitoring platforms proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized liquid cooling technicians cluster around Jakarta's hyperscale corridor, creating a talent bottleneck that shapes deployment velocity across the archipelago's emerging data center zones.
Java
Hyperscale cloud operators concentrate capacity in Jakarta's corridor and Surabaya's industrial zones. The Ministry of Energy and Mineral Resources enforces building energy codes that constrain power usage effectiveness ratios, accelerating liquid cooling adoption. Batam's submarine cable landing zones attract cross-border latency-sensitive deployments serving Singapore and Malaysian markets.
Sumatra
Medan and Palembang host edge computing infrastructure for domestic telecommunications carriers. National data center sovereignty policies mandate domestic data residency, expanding local cooling requirements beyond Java-centric concentration. New intercontinental fiber routes elevate Batam's position as a secondary hyperscale hub with dedicated thermal system demand.
East Kalimantan
The Nusantara capital relocation project seeds greenfield data center zones without legacy retrofit constraints. Government procurement prioritizes sovereignty-compliant cooling architectures for public sector facilities. Liquid-cooled designs deploy natively in purpose-built campuses unconstrained by existing air-cooled infrastructure.
Sulawesi
Makassar anchors distributed processing capacity for eastern Indonesia's subscriber base. Tropical humidity corrosion cycles compress equipment replacement intervals, inflating total cost of ownership calculations for coastal deployments. Edge computing sites prefer direct expansion cooling for simplified maintenance logistics across fragmented island geography.
Bali and Nusa Tenggara
Tourism-driven digital service demand supports smaller-scale colocation facilities in Denpasar and Mataram. BIS-aligned equipment safety certification extends procurement cycles for imported cooling infrastructure. Modular direct expansion units dominate deployment economics in these secondary markets with limited technician density.
Indonesia Data Center Cooling Market Competitive Landscape
The competitive structure tilts toward integrated power and cooling portfolio providers with established tropical climate engineering capabilities. Market concentration reflects the dominance of multinational industrial conglomerates with dedicated data center infrastructure divisions alongside specialized thermal management firms. Three archetypes define positioning: integrated infrastructure platforms, precision climate specialists, and diversified industrial conglomerates. Capacity expansion and strategic partnerships constitute the dominant competitive moves as operators secure dedicated manufacturing allocation and priority service response.
Within the integrated infrastructure tier, Schneider Electric anchors large-scale deployment economics through combined power and cooling system offerings. Vertiv Group occupies a position emphasizing specialized thermal management architectures engineered for high-humidity operating conditions. Stulz GmbH exemplifies the precision climate specialist archetype with focused engineering for high-density server environments. These three firms represent distinct approaches to addressing Indonesia's regulatory efficiency mandates and tropical corrosion challenges.
| Leading Market Players |
|---|
| Schneider Electric |
| Vertiv Group |
| Johnson Controls International |
| Stulz GmbH |
| Emerson Electric |
| Mitsubishi Electric |
| Daikin |
| Carrier |
| Danfoss |
| Others |
Pricing and Supply Chain Analysis
Hyperscale cloud operators consolidating procurement across Jakarta's corridor and Batam's cable landing zones anchor pricing power in volume-based contract structures with extended service bundling. The concentration of rack densities exceeding 30 kW per cabinet tilts negotiations toward liquid-cooled system suppliers capable of delivering integrated thermal management with predictive maintenance commitments.
Pricing Analysis
Bundled installation-and-maintenance contracts dominate hyperscale deployments while unbundled equipment-only sales persist among legacy enterprise retrofits. Three-tier pricing structure across premium liquid-cooled, standard hybrid, and economy air-based configurations reflects certification grade and tropical climate engineering intensity. Cost compression in air-cooled segments intensifies because copper and aluminum commodity volatility destabilizes heat exchanger margins. Colocation operators in secondary Indonesian markets exhibit highest price sensitivity; hyperscale cloud providers with dedicated facility investments demonstrate lowest sensitivity due to total-cost-of-ownership optimization priorities.
Supply Chain Analysis
Certified coolant loop technicians cluster in South Korea, Japan, and Singapore manufacturing hubs, constraining Indonesian deployment velocity for liquid-based systems. Precision cooling equipment draws from East Asian component ecosystems with concentrated sourcing of copper tubing, aluminum heat exchangers, and dielectric fluids. Single-source vulnerability in BIS-aligned safety certification creates procurement cycle extensions that delay facility commissioning. Distribution runs through integrated power-and-cooling portfolio providers with established Jakarta service partnerships rather than fragmented channel structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's data center cooling market operates as a regulatory compounder where Ministry of Energy and Mineral Resources efficiency mandates harden compliance thresholds and reshape capital allocation between cooling architectures.
For Market Incumbents: Acquire specialized liquid cooling technician training programs to address capability scarcity constraining hyperscale deployment timelines. Consolidate vendor relationships with Batam-based facilities serving Singapore and Malaysian latency requirements to secure dedicated manufacturing allocation. Threat substitution from immersion cooling systems in financial services HPC clusters demands accelerated direct-to-chip liquid cooling R&D investment. For New Entrants and Emerging Players: Direct-to-chip liquid cooling retrofit kits for brownfield enterprise facilities in Surabaya and Bandung offer the most penetrable entry vector. Target East Kalimantan's Nusantara greenfield zones where liquid-cooled designs deploy without legacy infrastructure constraints. Go-to-market positioning should emphasize predictive corrosion-monitoring service contracts addressing tropical humidity degradation cycles. For Investors and Strategic Acquirers: Integrated power and cooling portfolio providers are the most active acquirer in this space, consolidating fragmented thermal management specialists. Long-term viability centers on 5-10 year service revenue capture from compressed equipment replacement intervals in coastal Indonesian climates. Watch hyperscale operator consolidation of vendor relationships as the inflection signal indicating manufacturing capacity allocation priority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coolant Loop Components | Captive supply of precision heat exchangers mitigates copper price volatility exposure for Jakarta hyperscale deployments. |
| Local Service Partnership Establishment | Certified technician density in Batam accelerates commissioning timelines for submarine cable landing zone facilities. |
| BIS Pre-Certification Investment | Pre-validated equipment safety documentation compresses procurement cycles for Ministry of Communication and Informatics sovereignty-compliant projects. |
| Predictive Maintenance Platform Launch | Continuous corrosion monitoring addresses tropical humidity degradation cycles in coastal Indonesian data center operations. |
| Hybrid Architecture Product Line Expansion | Combined air-liquid systems capture brownfield retrofit demand in Surabaya and Bandung enterprise facilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with data center facility operators, thermal management procurement leads, BIS certification specialists, and Ministry of Energy and Mineral Resources policy officers with secondary validation. SEC filings from listed infrastructure providers, hyperscaler capital expenditure disclosures, Indonesian customs import records for precision cooling equipment, and BIS safety certification databases anchored supply-side estimates. Bottom-up facility deployment tracking and top-down national energy efficiency mandate impact modeling triangulated market sizing across the analysis window.
Historical reference periods anchored the projection horizon through installed base depreciation curves and hyperscale expansion pipeline tracking. Segmentation dimensions modeled include product architecture, end-user vertical, cooling technique, and service type alongside regional deployment clustering across Java, Sumatra, and East Kalimantan. CAGRs derived from equipment replacement interval compression in tropical climates and liquid cooling adoption velocity at rack densities exceeding 30 kW. Forecast inputs incorporated Ministry of Communication and Informatics data residency enforcement intensity and Nusantara capital relocation project procurement schedules.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to copper and aluminum commodity volatility, BIS certification timeline extensions, and hyperscale operator vendor consolidation patterns. Forecasts reflect documented assumptions regarding tropical corrosion cycle benchmarks and liquid cooling technician training pipeline expansion. Material deviation in Ministry of Energy and Mineral Resources carbon accounting rule implementation warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Data Center Cooling
Philippines Data Center Cooling Market
Data Center Cooling
Indonesia Study of Data Center Water Consumption Market
Data Center Cooling
Sweden Data Center Cooling Market
Data Center Cooling
Germany Data Center Cooling Market
Data Center Cooling
Canada Data Center Cooling Market
Data Center Cooling
South Africa Data Center Cooling Market
Data Center Cooling
Middle East District Cooling Market
Data Center Cooling
New Zealand Data Center Cooling Market
Data Center Cooling
Uk Data Center Cooling Market
Data Center Cooling
North America Data Center Cooling Market
Data Center Cooling
Mexico Data Center Cooling Market
Data Center Cooling
Denmark Data Center Cooling Market
Data Center Cooling
Chile Data Center Cooling Market
Data Center Cooling
Singapore Data Center Cooling Market
Data Center Cooling
Ireland Data Center Cooling Market
Data Center Cooling
Nigeria Data Center Cooling Market