
 Packing Paper Market | 2026-2036
Packing Paper Market Size, Share, and Industry Trends Forecast 2026-2036
Packing Paper Market Analytics
Recycled fiber processing technology is narrowing the performance gap between virgin and secondary kraft grades for heavy-duty shipping applications. WestRock Company leverages its integrated containerboard and recycling infrastructure to secure cost-advantaged feedstock across North American corrugated operations. Mondi Group anchors its European position through specialty kraft mills optimized for e-commerce void-fill and wrap-around formats. DS Smith competes by embedding circular design protocols directly into retailer packaging briefs, converting plastic-intensive supply chains to paper-based alternatives.
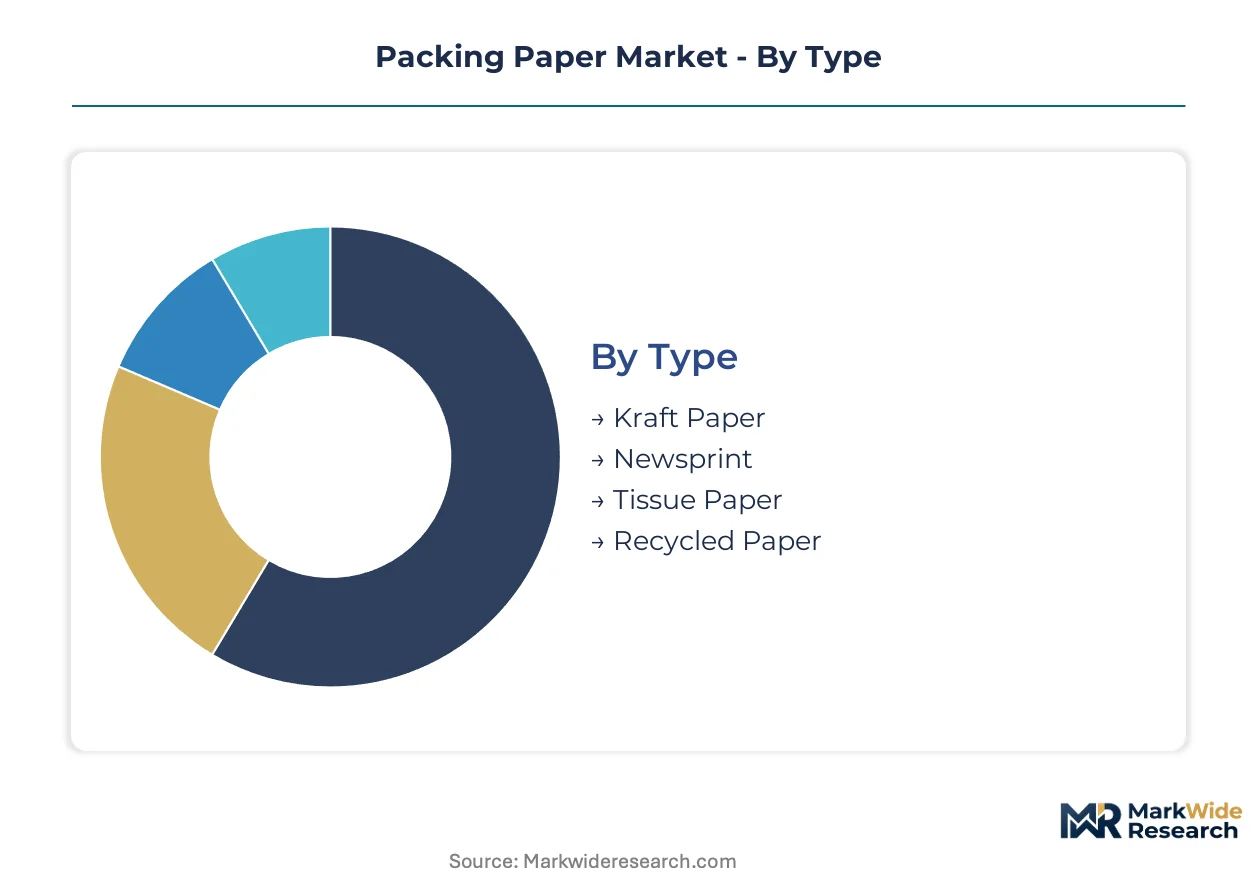
Packing paper comprises unbleached or bleached wood pulp sheets, typically ranging from 30 to 400 grams per square meter, engineered for cushioning, interleaving, and surface protection during transit and storage. Kraft paper dominates the type landscape due to superior tensile strength and tear resistance in humid logistics environments, while recycled paper represents the fastest-growing feedstock category as post-consumer collection systems mature. The e-commerce end-user segment commands premium pricing for customized roll and sheet formats, whereas manufacturing buyers favor heavyweight grades in bulk pallet configurations where unit economics favor scale over flexibility.
The EPA governs recycled content claims under its Comprehensive Procurement Guidelines, while the EU F-Gas Regulation indirectly channels industrial packaging spend toward fiber substrates by restricting foam-in-place insulation alternatives. China's GB standards for packaging material heavy metal content further shape export-oriented product specifications. Stakeholders must monitor how extended producer responsibility schemes in California and France alter cost allocation between paper converters and brand owners.
Market Dynamics
Single-use plastic bans across Germany, France, and California are redirecting industrial packaging spend toward fiber substrates faster than supply chains can adapt. E-commerce fulfillment networks now specify paper-based void-fill in vendor scorecards, compressing conversion timelines for converters.
Growth Catalysts
- EU Green Deal packaging mandates:Germany's single-use plastic ban and France's extended producer responsibility schemes redirect brand owners toward kraft-based alternatives for protective shipping applications.
- E-commerce fulfillment center expansion:Amazon, Alibaba, and regional logistics operators specify customized roll formats in procurement contracts, pulling specialized capacity online.
- Recycled fiber processing advances:Post-consumer collection maturation in North America and Europe enables 100% secondary feedstock for heavy-duty shipping grades without tensile strength penalties.
Market Restraints
- Recovered paper price volatility:OCC and mixed paper indices swing with Chinese import policy shifts, compressing converter margins when resin prices simultaneously spike.
- Scandinavian pulp supply concentration:Bleached kraft pulp for premium protective grades concentrates among Nordic integrated producers, creating single-source vulnerability for specialty converters.
- Silicone release liner substitution:Pressure-sensitive adhesive applications in electronics shipping increasingly specify film-based liners for moisture-critical environments, displacing paper in high-value segments.
Strategic Opportunities
- India's industrial packaging corridor:PLI scheme incentives for domestic manufacturing and BIS standards harmonization create first-mover advantage for integrated kraft producers establishing regional mills.
- Curbside-compostable barrier coatings:Water-based polymer treatments that pass ASTM D6400 certification unlock fresh produce and cold-chain applications previously reserved to plastic.
- Direct-to-fulfillment distribution:Amazon Vendor Central and Walmart Supplier Portal onboarding protocols favor converters with regional slitting and sheeting capabilities, disintermediating traditional merchant distributors.
Industry Challenges
- Wet-end chemistry expertise scarcity:Formulation chemists capable of optimizing starch-based strength additives for high-speed corrugators command premium compensation, constraining brownfield expansion.
- Extended producer responsibility compliance timelines:California's SB 54 implementation and France's Citeo fee structures require retroactive packaging database registration, delaying product launches for non-EU exporters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Packing Paper Market |
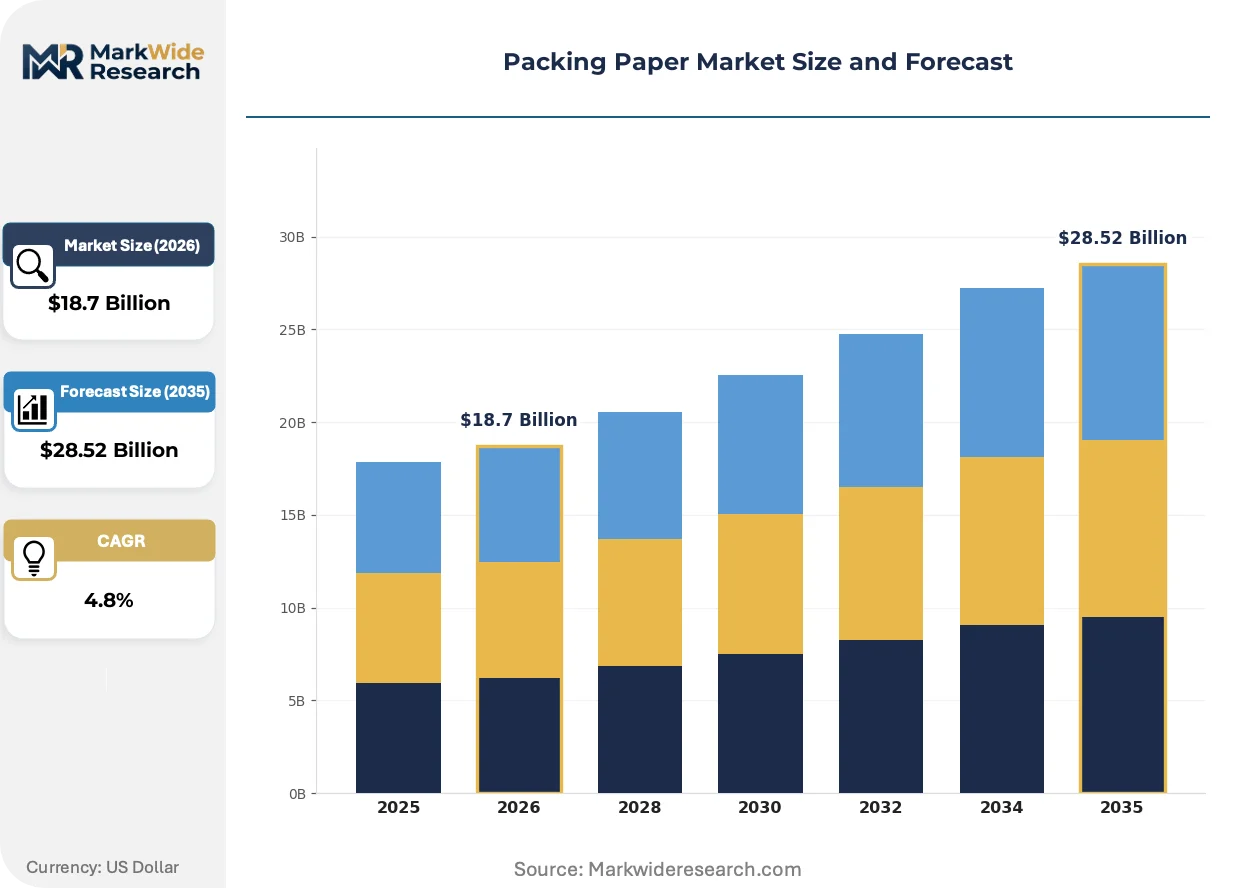
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Kraft Paper, Newsprint, Tissue Paper, Recycled Paper Application: Packaging, Insulation, Protection, Shipping Thickness: Lightweight, Medium, Heavyweight, Extra Heavyweight End User: E-Commerce, Retail, Manufacturing, Logistics |
| Companies Covered | International Paper Company, WestRock Company, Smurfit Kappa Group, Mondi Group, DS Smith, Packaging Corporation of America, Stora Enso, Oji Holdings, Nine Dragons Paper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Packing Paper Market Evolving Landscape
Moisture-resistant barrier technologies and automated fulfillment integration are compressing the performance gap between commodity kraft and engineered films. Converters now compete on line-speed compatibility and print registration precision rather than basis weight alone.
Microfibrillated cellulose barrier treatments are collapsing the technical boundary between paper and plastic protective formats. Amazon's packaging engineering team has adopted MFC-lined void-fill for electronics shipments across humid Southeast Asian corridors. The technology is collapsing premium pricing for polyethylene bubble alternatives in consumer electronics logistics.
REACH restrictions on per- and polyfluoroalkyl substances are eliminating fluorochemical grease barriers from food-contact paper specifications. EU-based converters must reformulate with bio-based alternatives before 2025 sunset dates. Bakery and ready-meal exporters to the Netherlands and Belgium are accelerating qualification timelines for PFAS-free interleaving papers.
Vendor-managed inventory programs now dominate procurement for high-volume e-commerce operators. Amazon's Packaging Certification Network and Walmart's Sustainable Packaging Playbook specify pre-approved converter lists, consolidating purchase authority among tier-one suppliers. This concentration is most visible in the automated packaging equipment integration segment, where line-speed compatibility determines contract awards.
Packing Paper Market Segmentation
Packing paper specifications diverge sharply between automated fulfillment lines and manual packing stations. Converters must align product portfolios with distinct technical requirements across substrate types, application intensities, and end-user operational speeds.
Type:
After-sales service intensity varies dramatically by substrate chemistry, with kraft grades demanding minimal technical support while recycled fiber formulations require ongoing strength optimization consultation.
- Kraft Paper:Unbleached wood pulp sheets deliver superior tensile strength and tear resistance in humid logistics corridors. Demand concentrates in Germany's automotive component export sector, where BMW and Volkswagen supplier mandates specify virgin kraft for corrosion-sensitive parts.
- Recycled Paper:Post-consumer fiber processing now achieves heavy-duty shipping performance without tensile penalties. France's extended producer responsibility schemes accelerate brand owner conversion from plastic, pulling specialized de-inking capacity online near Paris logistics clusters.
- Newsprint:Groundwood pulp basis weights suit low-cost void-fill for non-fragile consumer goods. Amazon's vendor scorecards in India specify newsprint interleaving for textile shipments.
- Tissue Paper:Bleached sulfite grades provide premium surface protection for electronics and luxury goods. California's cosmetic exporters drive specification tightening for silicon wafer shipping.
By volume, kraft paper leads. By growth pace, recycled paper is expanding most quickly.
Application:
Cost tier differentiation separates commodity cushioning from engineered protective systems requiring formulation chemistry expertise.
- Protection:Surface-interleaving papers prevent abrasion during multi-modal transit. China's electronics manufacturing corridor in Shenzhen specifies anti-static kraft for semiconductor wafer shipments.
- Shipping:Void-fill and wrap-around formats dominate e-commerce fulfillment center procurement. Amazon's Packaging Certification Network mandates line-speed compatibility testing for all shipping-grade suppliers.
- Packaging:Primary containment wraps for palletized goods favor heavyweight grades. German chemical exporters require REACH-compliant barrier treatments.
- Insulation:Thermal buffering applications in cold-chain logistics compete with foam alternatives. EU F-Gas Regulation restrictions on synthetic insulation redirect pharmaceutical spend toward fiber substrates.
Protection commands premium pricing per ton. Shipping handles the largest absolute volumes.
Thickness:
Customer type segmentation aligns basis weight selection with operational constraints across manual, semi-automated, and fully automated packing lines.
- Heavyweight:200-400 gsm grades withstand puncture in palletized industrial shipments. Manufacturing buyers in China's Pearl River Delta specify bulk roll formats for steel component exports.
- Lightweight:30-80 gsm sheets suit high-speed void-fill dispensers in e-commerce fulfillment. Alibaba's Cainiao network drives specification for ultra-light kraft in Southeast Asian hubs.
- Medium:80-150 gsm balances flexibility with structural integrity for mixed freight. European third-party logistics operators standardize on this range for cross-border retail distribution.
- Extra Heavyweight:Above 400 gsm grades serve specialized machinery and automotive part protection. German industrial packaging corridors require custom slitting for just-in-time supplier sequences.
Heavyweight dominates manufacturing procurement. Lightweight is gaining share fastest in fulfillment center specifications.
End User:
Supply concentration shapes converter sales force deployment, with e-commerce and logistics demanding dedicated technical account management while retail and manufacturing tolerate distributor relationships.
- E-Commerce:Customized roll and sheet formats with print registration precision command premium positioning. Amazon Vendor Central onboarding protocols favor converters with regional slitting capabilities.
- Logistics:Third-party operators specify standardized grades across multi-client facilities. DHL and FedEx procurement teams in Germany consolidate purchasing through pre-approved supplier lists.
- Retail:Private-label packaging teams require seasonal flexibility in basis weight and print design. French supermarket chains accelerate PFAS-free interleasing paper qualification.
- Manufacturing:Bulk pallet configurations prioritize unit economics over flexibility. China's industrial packaging corridor favors heavyweight grades in jumbo reel formats.
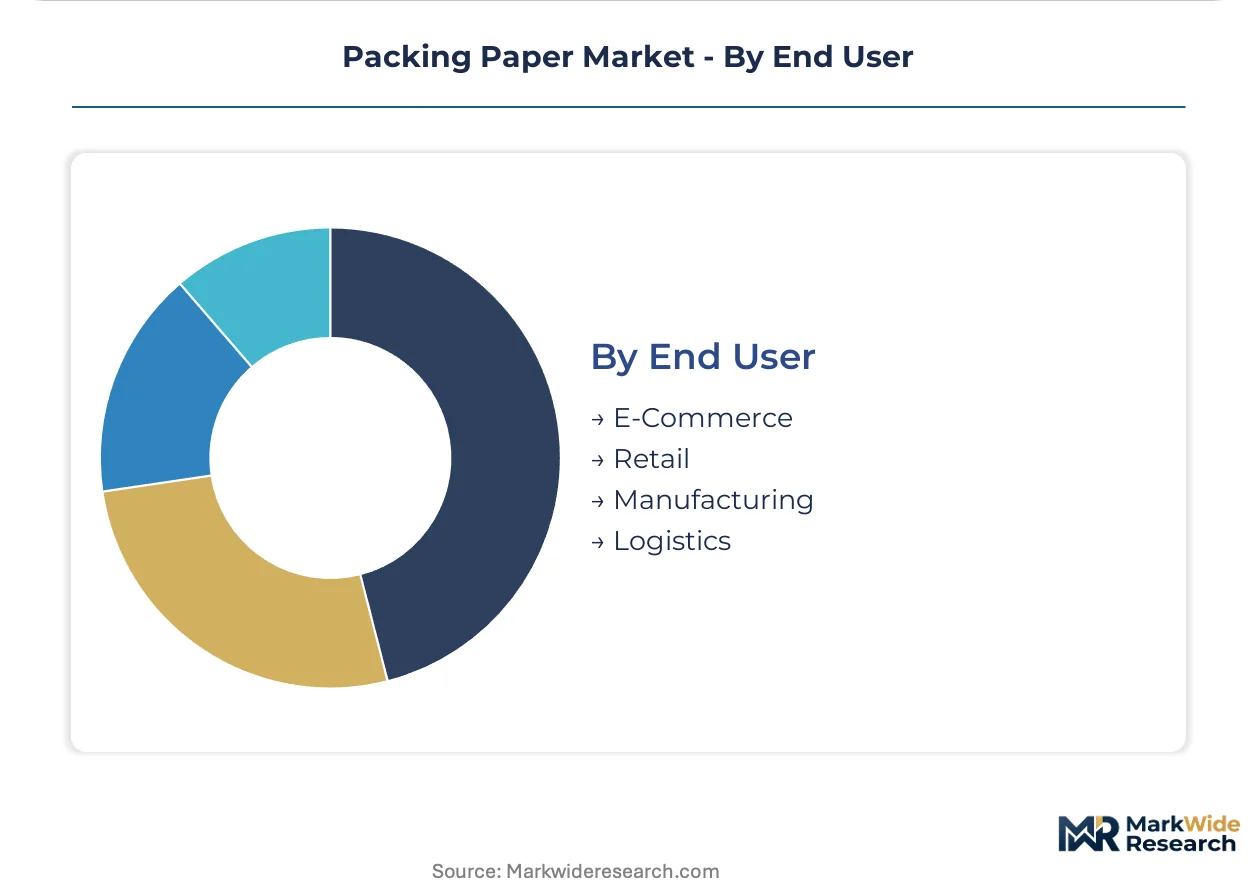
E-commerce leads by revenue per ton. Logistics shows the steepest expansion trajectory in absolute volume terms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Amazon Vendor Central procurement specifications concentrate buyer power in the United States and Germany, while China's industrial packaging corridor anchors manufacturing demand for heavyweight kraft grades.
United States
California's SB 54 extended producer responsibility scheme redirects brand owners toward fiber-based protective formats faster than domestic converters can expand capacity. The EPA's Comprehensive Procurement Guidelines govern recycled content claims for federal contractors. E-commerce fulfillment clusters in the Inland Empire and Dallas-Fort Worth specify customized roll formats with line-speed compatibility mandates.
Germany
BMW and Volkswagen supplier mandates specify virgin kraft for corrosion-sensitive automotive component exports to humid logistics corridors. The single-use plastic ban under the EU Green Deal channels industrial packaging spend toward fiber substrates. Bavaria's industrial packaging corridor requires custom slitting capabilities for just-in-time supplier sequences.
China
Shenzhen's electronics manufacturing corridor specifies anti-static kraft for semiconductor wafer shipments to Southeast Asian assembly hubs. GB standards for packaging material heavy metal content shape export-oriented product specifications. The Pearl River Delta favors heavyweight grades in jumbo reel formats for steel component exports.
India
Alibaba's Cainiao network drives specification for ultra-light kraft in fulfillment hubs across Maharashtra and Karnataka. BIS standards harmonization and PLI scheme incentives for domestic manufacturing create first-mover advantage for regional mill establishment. Textile exporters in Gujarat accelerate newsprint interleaving adoption for cost-sensitive shipments.
France
Citeo fee structures under extended producer responsibility schemes alter cost allocation between paper converters and supermarket private-label packaging teams. REACH restrictions on PFAS eliminate fluorochemical grease barriers from food-contact specifications by 2025. Paris logistics clusters pull specialized de-inking capacity online for post-consumer fiber processing.
Packing Paper Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven integrated producers hold procurement leverage with e-commerce operators while regional converters defend niche positions through slitting and sheeting proximity. The vendor base separates into three strategic archetypes: North American integrated containerboard producers with captive recycling infrastructure, European specialty kraft mills optimized for e-commerce formats, and Asia-Pacific volume producers serving industrial bulk applications. Dominant competitive moves include backward integration into recovered paper collection networks and geographic expansion through regional slitting facility establishment.
Within the integrated producer tier, WestRock Company and Mondi Group exemplify archetypes that anchor competitive positioning through control of containerboard and specialty kraft capacity respectively. DS Smith occupies a position representing circular design protocol embedding, converting plastic-intensive supply chains toward paper-based alternatives. These three entities represent the strategic spectrum from North American corrugated integration through European specialty optimization to retailer-facing circular economy services.
| Leading Market Players |
|---|
| International Paper Company |
| WestRock Company |
| Smurfit Kappa Group |
| Mondi Group |
| DS Smith |
| Packaging Corporation of America |
| Stora Enso |
| Oji Holdings |
| Nine Dragons Paper |
| Others |
Value Network & Pricing Analysis
Scandinavian bleached kraft pulp concentration among Nordic integrated producers anchors margin capture at the specialty converter tier, with downstream pricing power flowing to converters commanding wet-end chemistry expertise for strength optimization.
Pricing Analysis
Cost-plus contracts indexed to OCC and mixed paper indices dominate converter procurement, with three-tier pricing structure across premium, standard, and economy levels differentiating by basis weight precision and line-speed compatibility certification. Price differentiation hinges on wet-end formulation expertise and regional slitting proximity to fulfillment clusters. Pricing pressure stems from simultaneous resin spikes and recovered paper volatility, compressing margins for non-integrated converters. E-commerce fulfillment centers show lowest price sensitivity, while bulk manufacturing buyers prioritize unit economics over performance premiums.
Supply Chain Analysis
Contract manufacturing concentration sits with integrated containerboard producers in the United States, specialty kraft mills in Germany and Finland, and volume producers in China. The supply chain draws from Scandinavian pulp, post-consumer recovered paper streams, and starch-based strength additives. Single-source vulnerability concentrates in Nordic bleached kraft for premium protective grades. Distribution runs through regional slitting facilities serving Amazon Vendor Central and Walmart Supplier Portal specifications, disintermediating traditional merchant distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The packing paper market represents a high-growth disruption as single-use plastic bans under the EU Green Deal force fiber substitution faster than supply chains can adapt, compressing conversion timelines and consolidating procurement authority.
For Market Incumbents: Entrench position through backward integration into recovered paper collection networks and captive recycling infrastructure, defending against margin compression from OCC price volatility. Prioritize wet-end chemistry R&D investments to maintain performance differentiation as recycled fiber processing narrows quality gaps. Establish regional slitting facilities near Inland Empire and Dallas-Fort Worth fulfillment clusters to lock in Amazon and Walmart supplier status. For New Entrants and Emerging Players: India's industrial packaging corridor offers the most penetrable white-space, with PLI scheme incentives and BIS standards harmonization reducing barriers to integrated mill establishment. Target Maharashtra and Karnataka fulfillment hubs with ultra-light kraft specifications for Alibaba's Cainiao network. Pursue direct-to-fulfillment distribution models bypassing traditional merchant channels. For Investors and Strategic Acquirers: Capital is best deployed toward specialty converters with established Amazon Packaging Certification Network status and regional sheeting capabilities, as vendor-managed inventory programs consolidate purchase authority among tier-one suppliers. Long-term viability favors entities controlling both containerboard capacity and recycling infrastructure. Monitor California SB 54 implementation timelines and France Citeo fee structure adjustments as inflection indicators for cost allocation shifts between converters and brand owners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recovered Paper Collection | WestRock's captive recycling infrastructure secures cost-advantaged OCC feedstock across North American corrugated operations. |
| Regional Slitting Facility Establishment | Mondi Group's European specialty kraft mills optimize proximity to e-commerce void-fill demand in German logistics corridors. |
| Curbside-Compostable Barrier Coating Development | DS Smith's circular design protocols unlock fresh produce applications previously reserved to plastic under EU F-Gas restrictions. |
| Microfibrillated Cellulose Treatment Scale-Up | Amazon's adoption of MFC-lined void-fill for humid Southeast Asian corridors collapses premium pricing for polyethylene bubble alternatives. |
| PFAS-Free Formulation Qualification | EU-based converters must reformulate interleaving papers before REACH sunset dates to maintain bakery and ready-meal export access to Benelux markets. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with paper mill operations directors, e-commerce procurement leads at Amazon and Alibaba, corrugated plant managers, and recycling facility operators; and secondary validation through SEC 10-K filings of integrated producers, OCC and mixed paper price indices, EPA Comprehensive Procurement Guidelines, and EU Green Deal regulatory texts. Bottom-up capacity and consumption modeling triangulated against top-down trade flow analysis.
Forecast inputs include substrate type segmentation across kraft, recycled, newsprint, and tissue grades; application intensity across protection, shipping, packaging, and insulation; thickness tiers from lightweight to extra heavyweight; and end-user operational constraints spanning manual, semi-automated, and fully automated packing lines. CAGRs were derived through regression analysis of historical capacity expansion, e-commerce fulfillment center buildout rates, and regulatory mandate implementation timelines across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive capacity additions by Asian volume producers or accelerated PFAS regulatory timelines would shift outcomes. Quarterly review of Chinese import policy shifts, Amazon Vendor Central onboarding protocol changes, and Scandinavian pulp supply disruptions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Coated White Board Paper Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Paperboard Partition Market
Paper & Paperboard Packaging
Honeycomb Mailers Market
Paper & Paperboard Packaging
Tissue and Hygiene Paper Packaging Market
Paper & Paperboard Packaging
Italy Honeycomb Paper Market
Paper & Paperboard Packaging
Push-Up Paperboard Tube Market
Paper & Paperboard Packaging
Malaysia Corrugated Boxes Market
Paper & Paperboard Packaging
SCK Paper Market
Paper & Paperboard Packaging
Paper Cup Machine Market
Paper & Paperboard Packaging
Waxing Base Paper Market
Paper & Paperboard Packaging
Italy Paper Packaging Market
Paper & Paperboard Packaging
Butchers Paper Market
Paper & Paperboard Packaging
Asia-Pacific Paper Bags Market
Paper & Paperboard Packaging
Global Food Contact Papers Market
Paper & Paperboard Packaging
Ultraflute Paper Market