
 Paper Cushion Systems Market | 2026-2036
Paper Cushion Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Paper Cushion Systems Market Analytics
E-commerce fulfillment channels is rewriting procurement patterns for protective packaging across North America and Europe. Ranpak Inc. leverages its North American manufacturing footprint to supply major third-party logistics providers with on-demand paper cushioning equipment. Storopack, Inc. anchors its position through dual material expertise spanning paper and foam systems. Sealed Air Corporation competes by extending its automation portfolio into paper-based void-fill systems for high-velocity distribution centers.
Paper cushion systems employ kraft paper substrates processed through mechanical crimping, fan-folding, or inflation techniques to create compressible void-fill structures that absorb impact energy during transit. Typical formulations utilize recycled content between 70% and 100%, with basis weights ranging from 40 to 90 grams per square meter depending on protection class. Bulk rolls dominate industrial procurement for high-volume automated lines, while custom fit configurations capture premium margins in electronics and automotive applications where dimensional precision reduces material waste. Pre-inflated formats lead in small-parcel e-commerce due to immediate deployment without capital equipment.
FDA guidelines for indirect food contact materials, EPA recycled content procurement preferences, and EU REACH chemical compliance frameworks collectively shape material specifications and market access conditions for paper cushion suppliers. The EU Green Deal's packaging reduction targets are forcing reformulation of sizing agents and adhesives used in paper cushion manufacturing. Stakeholders must monitor evolving extended producer responsibility schemes and decide between regional production investments or cross-border supply consolidation.
Market Dynamics
The EU Packaging and Packaging Waste Regulation is forcing material substitution across fulfillment networks, compressing plastic void-fill demand while expanding automated paper cushion deployment in high-velocity distribution centers.
Growth Catalysts
- E-commerce fulfillment density:Third-party logistics providers in Germany and the Netherlands are retrofitting automated lines with on-demand paper cushioning equipment to eliminate plastic dependency.
- REACH chemical compliance:Reformulation of sizing agents under EU chemical frameworks is accelerating migration toward bio-based adhesives in kraft paper substrates.
- Automotive parts distribution:German automotive networks require high-volume protective packaging for precision components, driving bulk roll procurement for automated void-fill systems.
Market Restraints
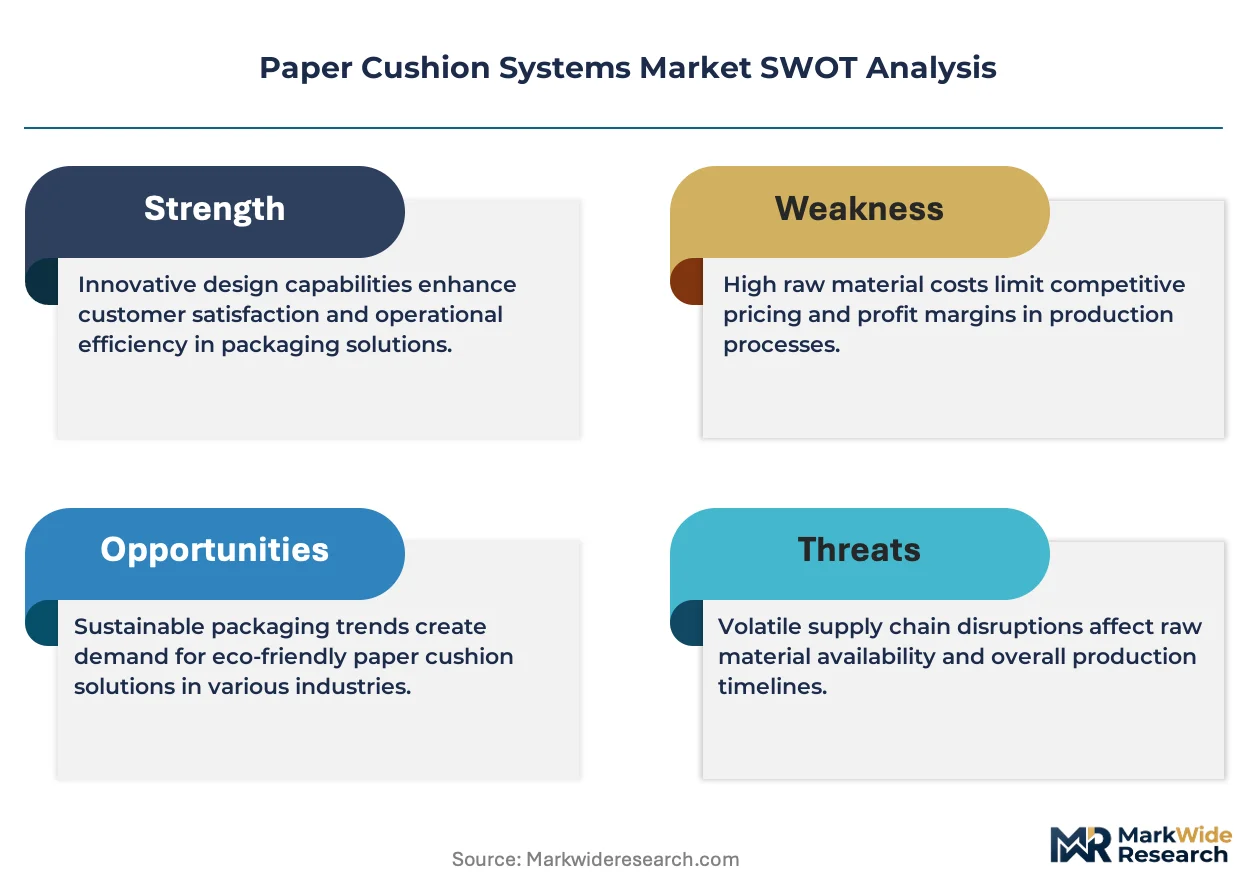
- Recycled fiber cost volatility:Old corrugated containerboard pricing swings directly compress margin structures for cushion manufacturers dependent on 70-100% recycled content formulations.
- Capital equipment intensity:Automated crimping and fan-folding lines require substantial upfront investment, creating adoption barriers for mid-tier fulfillment operations.
- Pre-inflated format limitations:Shelf-stable paper cushion alternatives face storage volume constraints that limit their displacement of on-demand systems in high-throughput environments.
Strategic Opportunities
- Electronics precision packaging:Custom-fit configurations for semiconductor and consumer electronics shipments command premium positioning through dimensional accuracy that reduces material waste.
- Extended producer responsibility schemes:France and Italy are advancing packaging fee structures that penalize plastic alternatives, creating structural preference for paper-based systems.
- Food-contact certification expansion:FDA indirect food contact compliance pathways enable paper cushion penetration into grocery and meal-kit distribution channels previously reserved for foam.
Industry Challenges
- Automation integration complexity:Legacy warehouse management systems require costly middleware development to synchronize paper cushion equipment with existing pick-and-pack workflows.
- Material certification timelines:EU REACH dossier preparation for novel bio-based sizing agents extends commercialization cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Paper Cushion Systems Market |
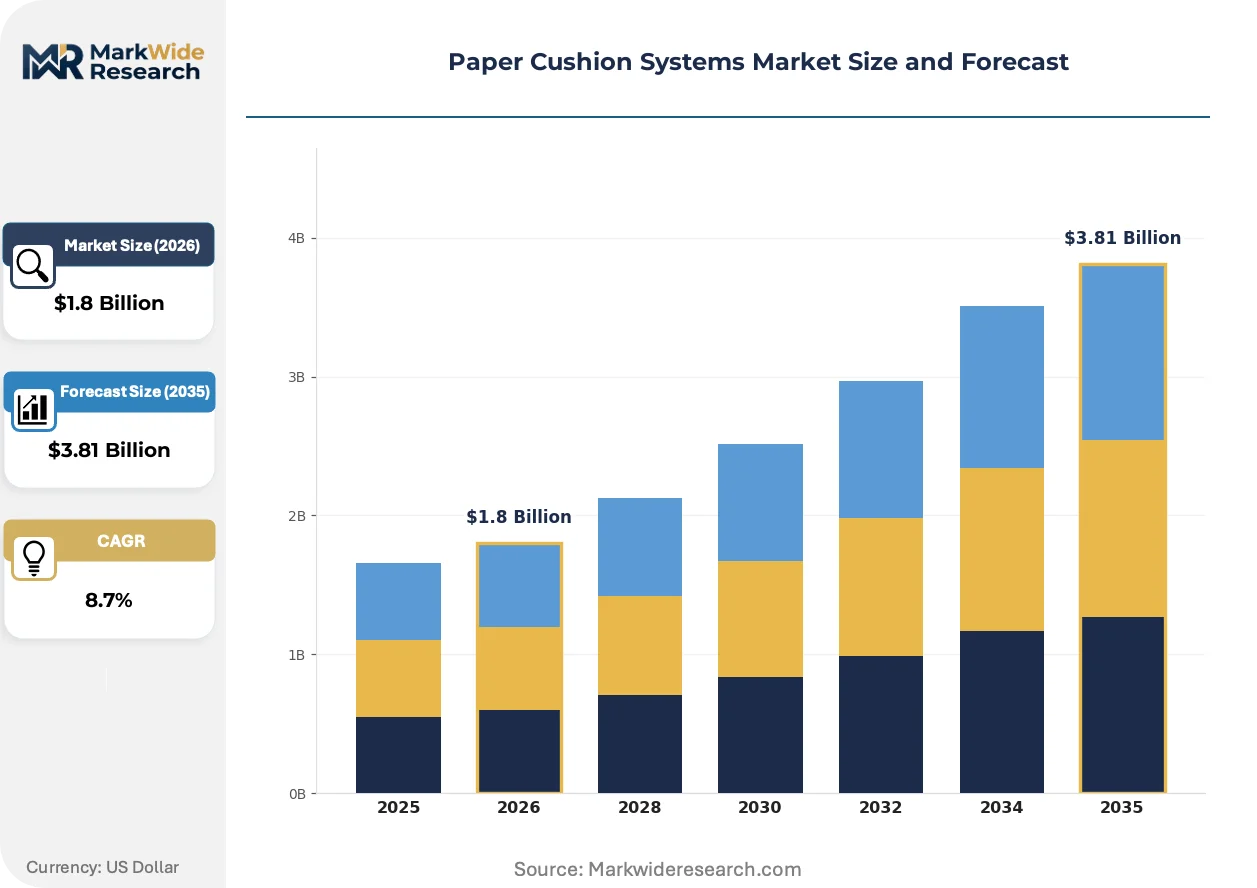
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pre-inflated, Custom Fit, Bulk Rolls, Flat Sheets Application: Automotive, Electronics, Home Goods, Industrial Packaging Type: Boxes, Mailers, Pallets, Bags Distribution Channel: Online Retail, Wholesalers, Direct Sales, Distributors |
| Companies Covered | Ranpak Inc., Storopack, Inc., Pregis Paper Packaging Systems, Sealed Air Corporation, FP International, Shanghai Greentide Packing Material Co., Ltd., The Protective Packaging Company, Papier Sprick, Protega Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Paper Cushion Systems Market Evolving Landscape
Mechanical processing techniques for kraft paper substrates are advancing rapidly, with equipment manufacturers embedding sensors and predictive maintenance modules to minimize downtime in continuous-operation fulfillment environments.
Fan-fold paper cushion technology is migrating from manual packing stations to fully automated void-fill lines. Major third-party logistics providers in the United States are deploying these systems at throughput rates exceeding 500 packages per hour. The technology is migrating from standalone equipment toward integrated modules within end-to-end warehouse automation suites.
The EU Green Deal's packaging reduction targets are forcing reformulation of chemical additives used in paper cushion manufacturing. Industrial consequence includes accelerated R&D spending on starch-based binders and elimination of synthetic wet-strength agents. German automotive parts distributors are responding fastest, specifying certified cradle-to-cradle formulations in procurement tenders.
Buyer concentration among mega-fulfillment networks is compressing supplier negotiation cycles and demanding outcome-based service agreements. Equipment-as-a-service models are displacing traditional capital purchase arrangements in North American e-commerce channels. This pattern is most visible in California and Texas, where Amazon, Walmart, and Target operate dense distribution clusters driving standardization around interoperable paper cushion formats.
Paper Cushion Systems Market Segmentation
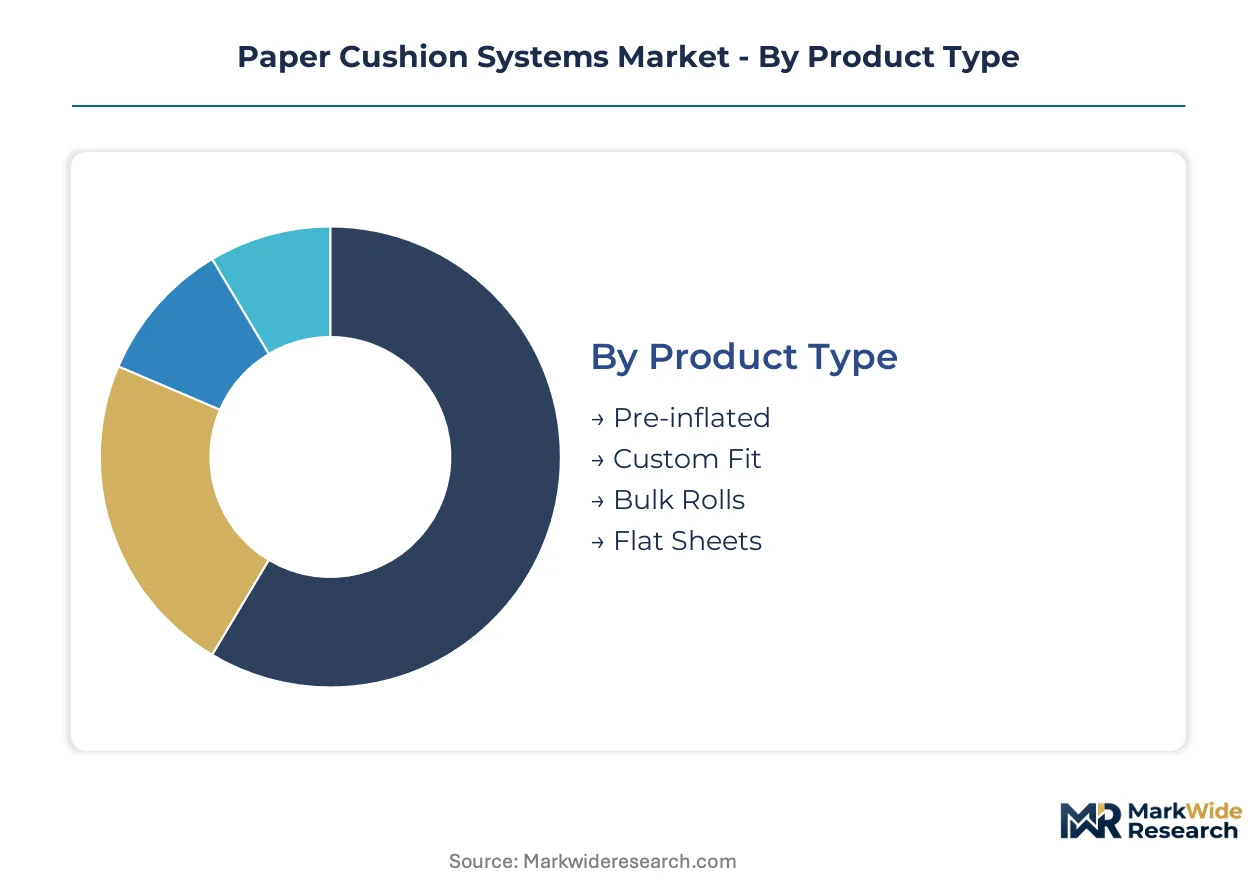
Paper cushion systems serve divergent operational requirements across fulfillment velocity tiers, from manual packing stations to automated high-throughput lines. Segmentation reveals how material format, application criticality, and channel structure determine procurement patterns and margin capture.
Product Type:
Use-case spectrum spans immediate deployment without capital equipment through precision-engineered protection for high-value components.
- Pre-inflated:Shelf-stable cushions arrive ready for immediate stuffing into small parcels, eliminating equipment investment. E-commerce fulfillment centers in Germany and the Netherlands favor this format for seasonal volume spikes where capital deployment timelines compress.
- Custom Fit:Engineered dimensional precision reduces material waste through exact cavity matching for semiconductor and automotive electronics shipments. German automotive parts distributors specify certified cradle-to-cradle formulations in procurement tenders, commanding premium positioning through waste reduction metrics.
- Bulk Rolls:Continuous feedstock for automated crimping and fan-folding lines serving high-velocity distribution networks.
- Flat Sheets:Manual conversion flexibility for mixed-SKU operations with variable protection requirements.
The dominant share belongs to Bulk Rolls, while Custom Fit is closing the gap fastest.
Application:
Protection intensity varies sharply by component value density and damage tolerance thresholds.
- Automotive:Precision components require high-compression recovery and dimensional stability during multi-modal transit. German distribution networks drive bulk procurement for automated void-fill systems serving just-in-sequence parts delivery.
- Electronics:Semiconductor and consumer device shipments demand electrostatic-dissipative substrates and contamination-free surfaces. Custom-fit configurations capture premium margins through material waste reduction in high-value product flows.
- Home Goods:Moderate protection class for furniture and décor with lower compression cycle requirements.
- Industrial:Heavy machinery components needing high-basis-weight substrates for impact absorption.
Automotive commands volume leadership, though Electronics exhibits the steepest expansion trajectory.
Packaging Type:
Container geometry dictates cushion architecture and deployment mechanism selection.
- Boxes:Standardized rectangular cavities suit fan-fold and crimped void-fill with automated dispensing. Third-party logistics providers in the United States deploy these systems at throughput rates exceeding 500 packages per hour.
- Mailers:Flexible envelopes with constrained interior volume favor pre-inflated formats for immediate deployment without equipment footprint.
- Pallets:Unit-load stabilization requires perimeter bracing and top-sheet protection for bulk shipments.
- Bags:Irregular cavity geometries demand conformable cushion structures with high compression recovery.
Boxes anchor procurement volume, yet Mailers are gaining share fastest in direct-to-consumer channels.
Distribution Channel:
Channel structure determines service intensity, technical support requirements, and contract terms.
- Online Retail:Digital procurement platforms with standardized specifications and rapid replenishment cycles. Equipment-as-a-service models displace traditional capital purchase arrangements in North American e-commerce channels.
- Wholesalers:Inventory aggregation for mid-tier fulfillment operations lacking direct manufacturer relationships.
- Direct Sales:Manufacturer-managed accounts with embedded technical service and automation integration support.
- Distributors:Regional stockholding with localized logistics for time-sensitive replenishment.
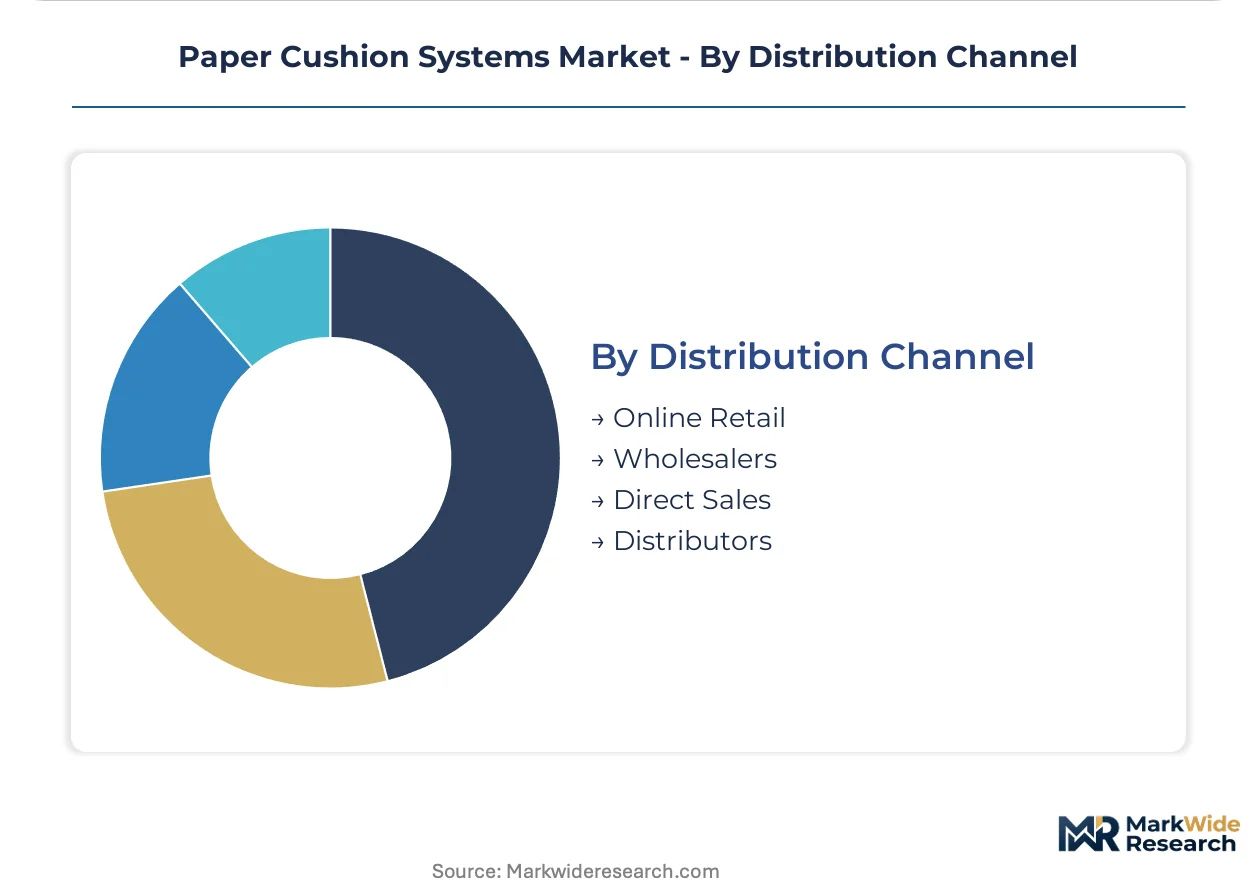
Direct Sales holds the dominant position, while Online Retail is climbing the fastest as procurement digitization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive parts distributors command pricing premiums through cradle-to-cradle certification requirements, while mid-tier fulfillment operators in Poland and Spain absorb margin compression from recycled fiber cost volatility. This asymmetry shapes procurement patterns across the European market.
Germany
Automotive parts distribution networks and e-commerce fulfillment density drive bulk roll procurement for automated void-fill systems. The EU Packaging and Packaging Waste Regulation accelerates material substitution mandates across member states. Bavaria and Baden-Württemberg host precision component manufacturers specifying certified paper cushion formulations for just-in-sequence delivery.
United States
Third-party logistics providers retrofit high-velocity distribution centers with on-demand paper cushioning equipment at throughput rates exceeding 500 packages per hour. EPA recycled content procurement preferences shape federal supply chain specifications. California and Texas distribution clusters standardize around interoperable paper cushion formats for Amazon, Walmart, and Target operations.
France
Extended producer responsibility schemes penalize plastic alternatives through packaging fee structures favoring paper-based systems. ANSM and environmental regulators enforce chemical compliance for indirect food contact materials. The Île-de-France region concentrates grocery and meal-kit distribution channels requiring FDA-compliant paper cushion penetration.
Netherlands
E-commerce fulfillment centers deploy pre-inflated formats for seasonal volume spikes where capital deployment timelines compress. REACH chemical compliance frameworks mandate reformulation of sizing agents toward bio-based adhesives. The Randstad logistics corridor anchors automated line retrofits eliminating plastic dependency across third-party provider networks.
China
Domestic e-commerce expansion and export manufacturing drive demand for both bulk roll automation and manual packing formats. MIIT standards and dual carbon goals pressure manufacturers toward recycled content formulations. The Yangtze River Delta and Pearl River Delta concentrate packaging equipment manufacturing and electronics export operations requiring protective cushioning systems.
Paper Cushion Systems Market Competitive Landscape
Integrated packaging conglomerates and specialized protective equipment fabricators split the market between scale-driven automation portfolios and application-specific material expertise. The vendor base concentrates around three strategic archetypes: North American equipment-as-a-service platforms, European dual-material specialists, and Asian substrate manufacturers. Competitive moves center on automation integration partnerships and regional production investments to satisfy extended producer responsibility compliance.
Among North American service-oriented platforms, Ranpak Inc. and Sealed Air Corporation occupy positions emphasizing automated equipment deployment and high-velocity distribution center integration. Storopack, Inc. exemplifies the European dual-material specialist archetype spanning paper and foam system expertise. Shanghai Greentide Packing Material Co., Ltd. represents Asian substrate manufacturing concentration serving both domestic consumption and export equipment supply chains.
| Leading Market Players |
|---|
| Ranpak Inc. |
| Storopack, Inc. |
| Pregis Paper Packaging Systems |
| Sealed Air Corporation |
| FP International |
| Shanghai Greentide Packing Material Co., Ltd. |
| The Protective Packaging Company |
| Papier Sprick |
| Protega Global |
| Others |
Value Network & Pricing Analysis
Overcapacity in recycled kraft paper mills across Germany and Poland compresses supplier leverage while automakers and e-commerce fulfillment networks exploit buyer concentration to extract configured-to-order concessions. This utilization imbalance feeds directly into margin structures, forcing equipment manufacturers to absorb cost volatility through service-attach pricing rather than hardware premiums.
Pricing Analysis
The customization-premium spread between bulk roll standard formats and cradle-to-cradle certified custom-fit configurations reaches three-to-one multiples in German automotive procurement. Three-tier pricing structure across premium, standard, and economy levels anchors the market, with certification grade and volume scale as primary differentiation drivers. Cost compression in standard bulk rolls intensifies because of old corrugated containerboard price swings, while electronics OEMs exhibit lowest price sensitivity due to damage-tolerance thresholds for precision components.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculations for substrate manufacturers serving dual-market equipment fabricators. Raw material sourcing draws from Swedish and Finnish pulp mills, German recycled fiber processors, and Chinese kraft paper converters, with mechanical crimping equipment components resting on Taiwanese electronics and German precision engineering. Single-source vulnerability in specialized fan-folding machinery creates chokepoint exposure. Distribution runs through direct manufacturer accounts for automated line integration, with regional distributors capturing manual packing format flows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment-as-a-service contracts represent the fastest-expanding recurring-revenue layer, outpacing hardware sales as third-party logistics providers demand outcome-based uptime guarantees rather than capital ownership.
For Market Incumbents: Pre-empt margin erosion in standard bulk roll segments by embedding predictive maintenance modules and consumable subscription tiers that lock in multi-year replenishment cycles. Bio-based adhesive certification investment creates defensible positioning against REACH chemical compliance acceleration. Channel control through embedded technical service teams raises switching costs for high-velocity distribution center accounts. For New Entrants and Emerging Players: Mid-tier fulfillment operators in Poland and Spain represent the most penetrable entry point, absorbing margin compression from recycled fiber cost volatility that incumbent equipment-as-a-service models overlook. Pre-inflated format penetration into seasonal e-commerce spikes offers lower capital barrier entry than automated line competition. Go-to-market execution should anchor on rapid replenishment cycle guarantees with distributor inventory aggregation partnerships. For Investors and Strategic Acquirers: Capital is best deployed toward dual-material specialists with paper and foam system expertise spanning multiple regulatory jurisdictions, capturing consolidation premiums as extended producer responsibility schemes fragment single-material pure-plays. Long-term viability across the analysis window rests on automation integration capabilities rather than substrate manufacturing scale. The signal to watch is equipment-as-a-service contract renewal rates in North American e-commerce clusters, indicating sticky revenue transition completion.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Model Expansion | Amazon and Walmart distribution clusters in California standardize around interoperable paper cushion formats with uptime-based contracts. |
| Bio-Based Adhesive Certification Investment | EU REACH dossier preparation for starch-based binders accelerates commercialization timelines for German automotive tenders. |
| Backward Integration into Recycled Fiber Supply | Captive sourcing from old corrugated containerboard processors insulates margin structures from OCC pricing volatility. |
| Automation Integration Partnership | Middleware development for legacy warehouse management synchronization captures high-velocity distribution center retrofits. |
| Extended Producer Responsibility Compliance Positioning | France and Italy packaging fee structures penalizing plastic alternatives create structural preference for paper-based systems. |
Research Methodology
The analysis maps kraft paper substrate grades, mechanical processing equipment tiers, and fulfillment channel configurations, each validated through packaging engineers at third-party logistics providers, procurement directors at automotive parts distributors, and sustainability compliance officers at e-commerce platforms. Primary interview intelligence triangulates against secondary validation from EU Packaging and Packaging Waste Regulation implementation documents, EPA recycled content procurement guidelines, SEC filings of integrated packaging conglomerates, and trade flow data from German mechanical engineering associations. Bottom-up equipment deployment counts and top-down material consumption estimates converge through iterative reconciliation.
Assumptions held fixed include EU Green Deal packaging reduction targets and REACH chemical compliance timelines, while variables span e-commerce fulfillment velocity growth rates and recycled fiber cost trajectories across the projection horizon. Segmentation dimensions modeled encompass product type, application criticality, packaging geometry, and distribution channel structure, with regional regulatory cluster as an additional industry-specific layer. CAGRs derive from regression analysis against historical equipment installation rates and material procurement volumes, incorporating automotive production schedules and semiconductor shipment forecasts as demand-side inputs.
Macroeconomic conditions sit as an overlay; deviation in interest rate environments affecting capital equipment investment cycles or pulp commodity price shocks would shift the trajectory. Forecasts reflect documented assumptions subject to revision from regulatory enforcement intensity variations or automation technology disruption. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Packaging
Middle East and Africa Protective Packaging Market
Protective Packaging
Molded Fiber Pulp Edge Protectors Market
Protective Packaging
Protective Packaging Market
Protective Packaging
Padded Mailers Market
Protective Packaging
South Africa Protective Packaging Market
Protective Packaging
Latin America Protective Packaging Market
Protective Packaging
Anti-Corrosive Packaging Market
Protective Packaging
Europe Protective Packaging Market
Protective Packaging
Anti-Static Foam Packaging Market
Protective Packaging
Fiber Cushioning Market
Protective Packaging
Global Air Cushion Packaging Market
Protective Packaging
Foam Packaging Inserts Market
Protective Packaging
Inflatable Packaging Market
Protective Packaging
Global Packaging Inserts and Cushions Market
Protective Packaging
Thermal Insulated Bubble Wrap Market
Protective Packaging
Foam Mesh Sleeves Market