
 Adenovirus Testing Market | 2026-2036
Adenovirus Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Adenovirus Testing Market Analytics
Multiplex respiratory panel bundling is shifting buyer choice toward combined adenovirus-influenza-RSV assays that reduce per-test operational overhead. Abbott Laboratories leverages its installed base of molecular platforms to sustain recurring reagent revenue across integrated delivery networks. Thermo Fisher Scientific anchors North American supply through direct distribution to hospital core laboratories. bioMérieux competes in European markets with automated sample-to-answer systems that minimize technician hands-on time.
Adenovirus testing encompasses nucleic acid amplification, antigen detection, and serological methods designed to identify human adenovirus species in clinical specimens, with polymerase chain reaction assays achieving analytical sensitivity down to 10-100 copies per reaction and serving as the reference standard for immunocompromised patient management. The primary commercial purpose centers on differential diagnosis of respiratory, gastrointestinal, and ocular infections where clinical presentation overlaps with other viral pathogens. Testing method segmentation shows polymerase chain reaction occupying the dominant margin pool due to reimbursement premiums for quantitative viral load monitoring in transplant populations. Sample type segmentation positions nasopharyngeal swabs as the highest-volume category during respiratory seasonality peaks, while blood specimens command superior pricing in hematology-oncology settings.
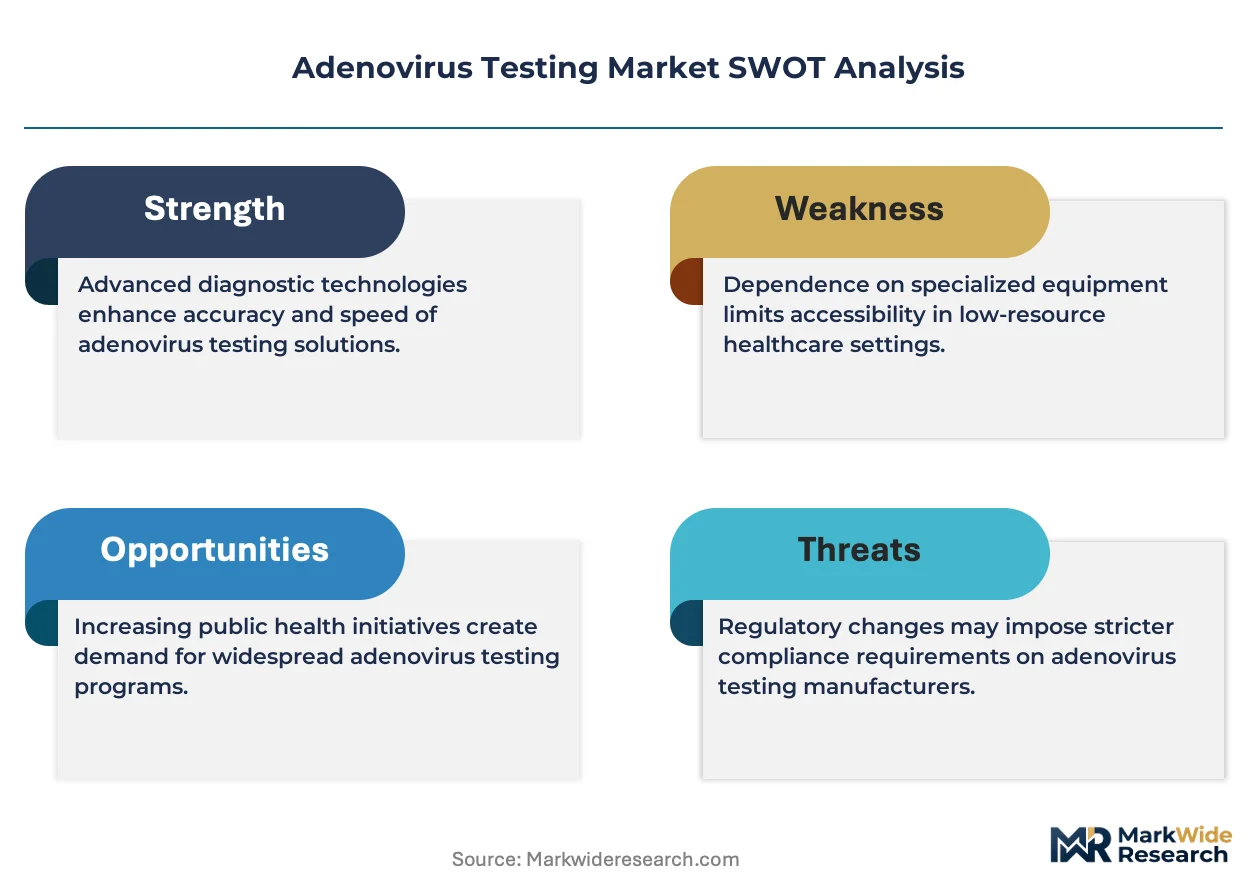
FDA clearance pathways for multiplex molecular diagnostics shape product development timelines and clinical claim expansion in the United States, while EMA oversight of in vitro diagnostic medical devices under the EU MDR transition forces European manufacturers to renew technical documentation and performance evidence. WHO prequalification standards influence procurement decisions in low-resource settings where centralized laboratory infrastructure remains limited. Stakeholders must monitor evolving CLIA complexity classifications and decentralized testing waivers that could redistribute testing volume from reference laboratories toward point-of-care settings.
Market Dynamics
Multiplex PCR platform consolidation is compressing assay menus into single-run respiratory panels, forcing hospital laboratories to retire legacy single-target systems and renegotiate long-term reagent contracts around bundled viral detection workflows.
Growth Catalysts
- Respiratory surveillance protocol expansion:Hospital laboratories in the United States are mandating comprehensive viral screening for immunocompromised admissions, creating institutional demand for quantitative adenovirus load monitoring in transplant wards.
- EU MDR transition:The European Medical Device Regulation is accelerating performance documentation renewals, pushing reference laboratories toward validated automated sample-to-answer systems that reduce technician hands-on time.
- Quantitative viral load standardization:Hematology-oncology departments now require copy-number precision for therapeutic decision-making, elevating nucleic acid amplification methods above antigen detection for blood specimen workflows.
Market Restraints
- Reagent supply concentration:North American distribution networks depend on a limited set of molecular platform manufacturers, creating vulnerability to logistics disruptions for PCR master mixes and extraction kits.
- CLIA complexity classification barriers:Moderate-complexity laboratory requirements restrict adenovirus testing to certified facilities, blocking deployment in rural clinics and decentralized point-of-care settings.
- Antigen detection substitution:Rapid lateral flow devices for influenza and RSV continue capturing low-acuity respiratory cases, diverting volume from molecular confirmation of adenovirus co-infections.
Strategic Opportunities
- Decentralized testing waiver expansion:CLIA complexity reclassification for waived molecular devices would redistribute testing volume from centralized reference laboratories toward urgent care clinics and physician office laboratories.
- Integrated delivery network consolidation:Health systems in Germany are standardizing core laboratory instrumentation across affiliated hospitals, creating single-vendor contract opportunities for multiplex respiratory panel suppliers.
- AI-assisted result interpretation:Machine learning algorithms for viral load trend analysis are converging with laboratory information systems, enabling automated flagging of adenovirus reactivation patterns in stem cell transplant recipients.
Industry Challenges
- Cross-training bottlenecks:Molecular diagnostics specialists with dual competency in virology and automation engineering command premium compensation, constraining laboratory expansion timelines.
- Legacy system integration friction:Hospital information systems built around single-target assay codes require middleware reconfiguration to accommodate multiplex panel result reporting structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Adenovirus Testing Market |
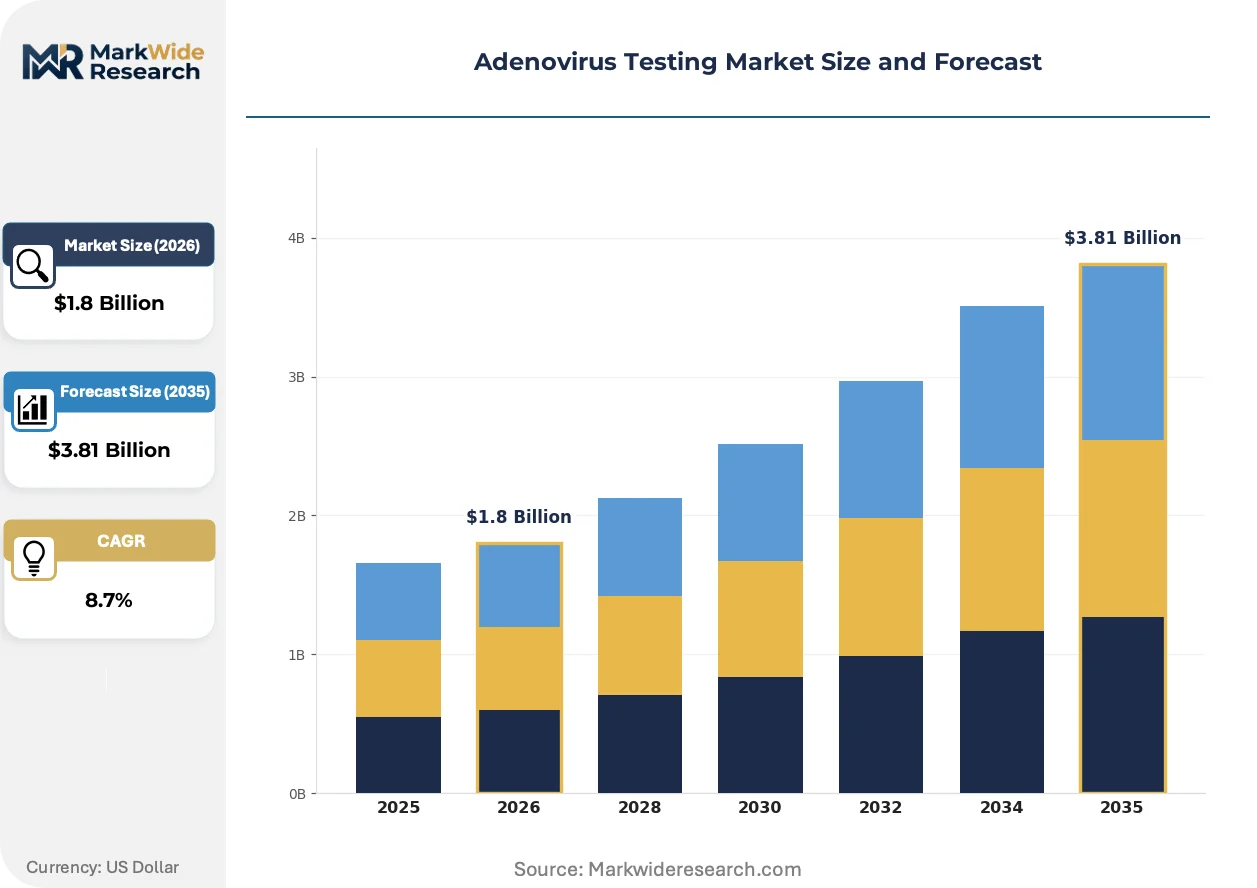
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Testing Method: Polymerase Chain Reaction, Antigen Detection, Serology, Nucleic Acid Amplification Sample Type: Throat Swab, Nasopharyngeal Swab, Blood, Stool End User: Hospitals, Clinical Laboratories, Diagnostic Centers, Research Institutions Product Type: Reagents, Kits, Instruments, Software |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, bioMérieux, Becton Dickinson and Company, Thermo Fisher Scientific, QIAGEN, DiaSorin, Bio-Rad Laboratories, Siemens Healthineers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Adenovirus Testing Market Evolving Landscape
Digital PCR platforms are fragmenting the quantitative viral load market, introducing absolute quantification methods that bypass calibration curve dependencies and reshape competitive positioning among nucleic acid amplification suppliers.
Digital PCR technology achieves single-molecule resolution without reference standards, enabling transplant centers to detect adenovirus reactivation at copy numbers below conventional quantitative PCR thresholds. Academic medical centers in Japan are piloting these systems for hematopoietic stem cell monitoring. The technology is converging with automated nucleic acid extraction workstations to compress turnaround times from specimen receipt to result reporting.
EMA oversight under the EU MDR transition is forcing European IVD manufacturers to renew technical documentation and clinical performance evidence for existing multiplex respiratory panels. This regulatory friction is extending product development timelines by twelve to eighteen months for claim expansions. German reference laboratories are responding by consolidating procurement around suppliers with completed MDR conformity assessments.
Hospital procurement departments are unbundling reagent contracts from instrument placement agreements, shifting toward volume-commitment pricing models that penalize underutilization of installed multiplex platforms. This contractual evolution is most visible in United States integrated delivery networks, where laboratory administrators now negotiate separate capital equipment and consumable agreements to optimize total cost-per-test metrics across respiratory seasonality fluctuations.
Adenovirus Testing Market Segmentation
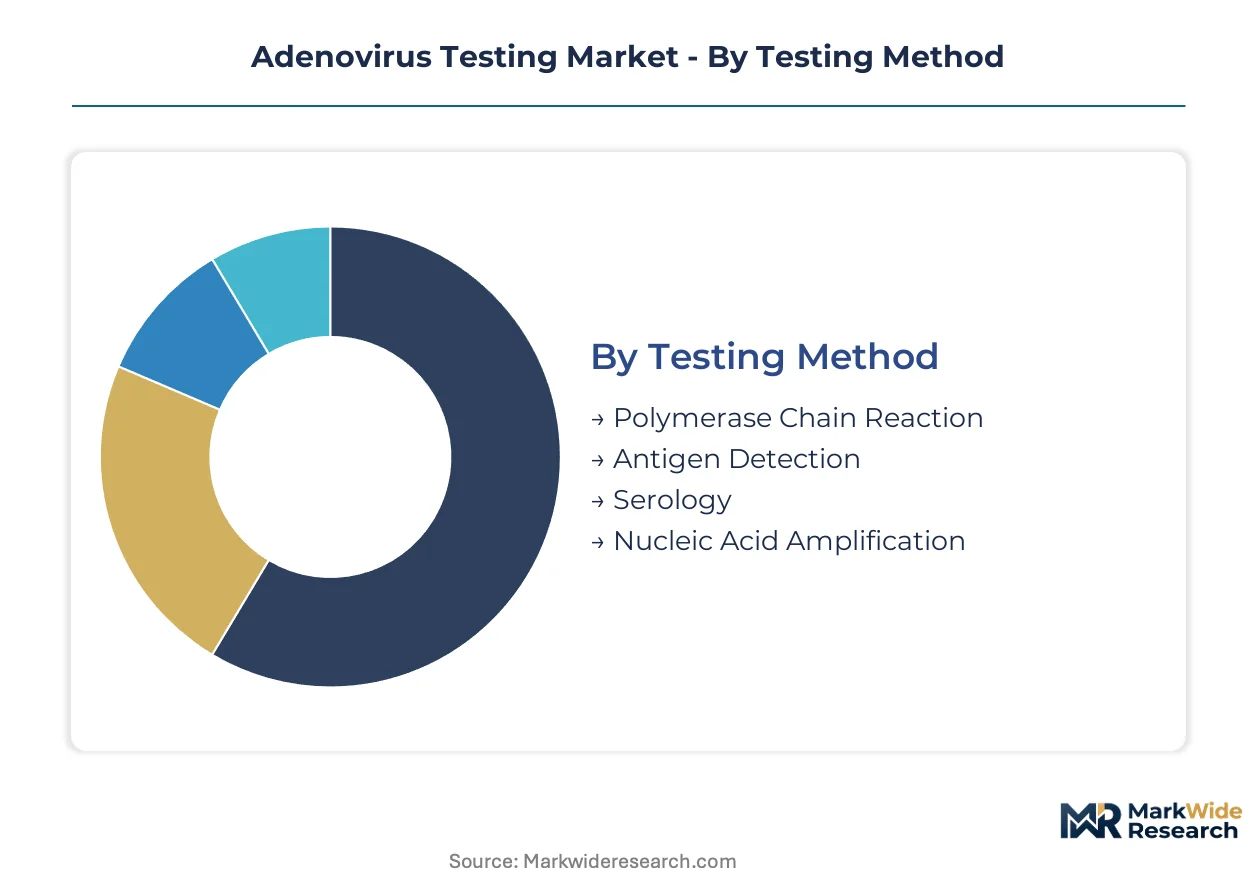
Adenovirus testing segmentation reveals distinct capital requirements across methods and settings. Method selection dictates instrumentation investment, while end-user type determines workflow automation depth and regulatory compliance burden.
Testing Method:
Polymerase chain reaction platforms demand the heaviest upfront capital outlay for thermal cyclers and extraction robotics.
- Polymerase Chain Reaction:Quantitative real-time assays achieve 10-100 copies per reaction sensitivity, serving as the reference standard for immunocompromised patient management in transplant wards across the United States, Germany, and Japan. Hematology-oncology departments in these markets mandate viral load precision for therapeutic decision-making.
- Nucleic Acid Amplification:Isothermal amplification methods reduce thermal cycler dependency while maintaining diagnostic sensitivity. Demand concentrates in European reference laboratories navigating EU MDR transition requirements for automated sample-to-answer validation.
- Antigen Detection:Lateral flow and immunochromatographic assays offer lower capital barriers for rapid screening.
- Serology:Enzyme-linked immunosorbent assays detect IgM and IgG antibodies for retrospective infection confirmation.
Polymerase chain reaction absorbs the bulk of installed capacity; nucleic acid amplification is expanding most quickly.
Sample Type:
Collection infrastructure and transport logistics shape segment economics more than processing technology.
- Nasopharyngeal Swab:Highest-volume category during respiratory seasonality peaks, processed through multiplex respiratory panels in hospital core laboratories. United States integrated delivery networks negotiate volume-commitment pricing around these specimens.
- Blood:Commands superior pricing in hematology-oncology settings where quantitative viral load monitoring guides stem cell transplant management. Japanese academic medical centers pilot digital PCR for copy-number resolution below conventional thresholds.
- Throat Swab:Alternative upper respiratory collection for outpatient and pediatric settings.
- Stool:Gastrointestinal adenovirus detection for enteric strain surveillance.
Blood specimens capture premium reimbursement tiers; nasopharyngeal swabs dominate absolute test volumes.
End User:
Certification requirements and reimbursement pathways create sharp operational distinctions across settings.
- Hospitals:Hospital laboratories represent the fastest-expanding buyer segment as respiratory surveillance protocols expand for immunocompromised admissions. CLIA moderate-complexity requirements restrict testing to certified facilities, blocking rural clinic deployment.
- Clinical Laboratories:Centralized reference laboratory networks in the United States, Germany, and Japan process the majority of confirmatory adenovirus diagnostics. These facilities drive multiplex PCR platform consolidation and legacy single-target system retirement.
- Diagnostic Centers:Independent laboratories competing on turnaround time for outpatient respiratory panels.
- Research Institutions:Academic medical centers piloting digital PCR and AI-assisted viral load trend analysis.
Hospital laboratories anchor procurement volume; diagnostic centers are gaining share fastest through urgent care network expansion.
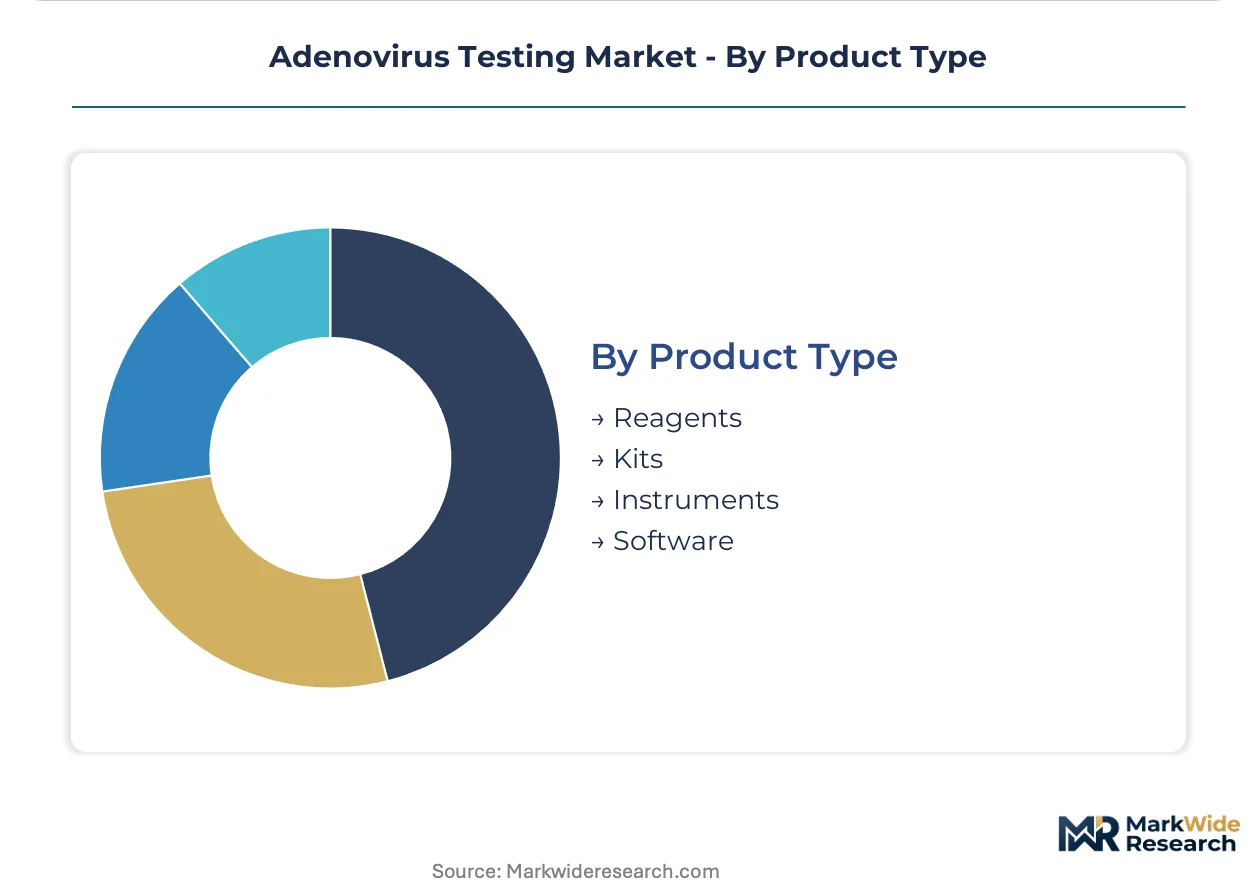
Product Type:
Recurring revenue models dominate as instrument placement gives way to unbundled consumable contracts.
- Reagents:PCR master mixes, extraction kits, and enzyme formulations generate sustained revenue across installed base expansion. North American distribution networks face supply concentration vulnerability for these consumables.
- Kits:Multiplex respiratory panels bundling adenovirus with influenza and RSV detection reduce per-test operational overhead. Abbott Laboratories leverages its installed molecular platform base for recurring reagent revenue.
- Instruments:Thermal cyclers, extraction workstations, and sample-to-answer systems face elongated procurement cycles.
- Software:Laboratory information system middleware for multiplex panel result reporting and AI-assisted interpretation.
Reagents and kits together capture the majority of recurring revenue; software is climbing the fastest as AI integration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic manufacturing concentrates in the United States, Germany, and Japan while clinical consumption spreads across hospital networks in these same markets. Production of molecular platforms and reagent kits flows from established hubs to regional reference laboratories.
United States
FDA clearance pathways shape product development timelines for multiplex molecular diagnostics entering hospital core laboratories. The agency's CLIA complexity classifications restrict adenovirus testing to moderate-complexity certified facilities, blocking rural clinic deployment. Boston and San Diego anchor the largest clusters of molecular diagnostic developers.
Germany
Reference laboratories in Bavaria and North Rhine-Westphalia drive procurement of automated sample-to-answer systems that reduce technician hands-on time. EMA oversight under the EU MDR transition forces manufacturers to renew technical documentation and performance evidence. Health systems in Baden-Württemberg are standardizing core laboratory instrumentation across affiliated hospitals.
Japan
Academic medical centers in Tokyo and Osaka pilot digital PCR platforms for hematopoietic stem cell transplant monitoring with copy-number resolution below conventional thresholds. PMDA regulatory frameworks govern in vitro diagnostic approvals for quantitative viral load assays. The Kanto region hosts the densest concentration of molecular diagnostics research institutions.
United Kingdom
London's integrated delivery networks negotiate volume-commitment pricing for multiplex respiratory panels bundling adenovirus with influenza and RSV detection. MHRA post-Brexit regulatory autonomy has accelerated divergence from EU MDR timelines for domestic manufacturers. The Southeast England corridor processes the majority of national reference laboratory volume.
China
NMPA regulatory pathways for molecular diagnostics are compressing approval timelines for domestic manufacturers of nucleic acid amplification platforms. Shanghai and Beijing house the largest installed bases of automated extraction robotics in Asia-Pacific hospital laboratories. Provincial health commissions in Guangdong and Jiangsu are mandating expanded respiratory surveillance for immunocompromised admissions.
Adenovirus Testing Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the adenovirus testing landscape. The market structure consolidates around three tiers: multinational life sciences conglomerates with broad molecular portfolios, dedicated diagnostic specialists with automated sample-to-answer platforms, and regional reagent suppliers serving price-sensitive reference laboratories. Strategic moves center on multiplex assay menu expansion and long-term reagent contract renegotiation around bundled viral detection workflows.
Among diversified life sciences conglomerates, Abbott Laboratories, Thermo Fisher Scientific, and bioMérieux exemplify contrasting geographic anchoring strategies. Abbott Laboratories represents the installed-base leverage archetype, converting molecular platform placements into recurring consumable revenue across United States integrated delivery networks. Thermo Fisher Scientific occupies a North American supply chain position, anchoring distribution to hospital core laboratories through direct logistics relationships. bioMérieux sits within the European automation specialist tier, competing on technician hands-on time reduction in German and French reference laboratory markets.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| bioMérieux |
| Becton Dickinson and Company |
| Thermo Fisher Scientific |
| QIAGEN |
| DiaSorin |
| Bio-Rad Laboratories |
| Siemens Healthineers |
| Others |
Value Network & Pricing Analysis
Polymerase chain reaction reagent spot prices on North American chemical exchanges cascade through three-tier pricing structures across hospital procurement tiers, with FDA-cleared master mixes commanding premium placement against research-use-only alternatives in integrated delivery network negotiations.
Pricing Analysis
Margin tightening in multiplex respiratory panels reflects unbundled instrument-reagent contracts and volume-commitment pricing penalties for underutilization. Three-tier pricing structure across premium, standard, and economy levels separates quantitative viral load assays from rapid antigen screens and bulk serological reagents. Cost compression accelerates in the antigen detection tier as lateral flow commoditization diverts low-acuity cases from molecular confirmation. Reference laboratories in Germany and Japan exhibit lowest price sensitivity; urgent care clinics in United States rural markets face acute budget constraints.
Supply Chain Analysis
CE marking and FDA 510(k) clearance gates concentrate validated reagent production in the United States, Germany, and Japan. Automated extraction robotics draw from precision-machined consumables, thermostable polymerase enzymes, and fluorophore-labeled probe chemistries. Single-source vulnerability persists for thermocycler optical modules sourced from specialized German component suppliers. Distribution runs through direct manufacturer-to-hospital contracts in North America and regional distributor networks in European reference laboratory markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The adenovirus testing market is consolidating around multiplex platform vendors with completed regulatory dossiers, as EU MDR transition costs force smaller reagent suppliers toward acquisition or exit.
For Market Incumbents: Hedge against digital PCR displacement by securing exclusive sample-to-answer placement contracts with Japanese academic medical centers piloting absolute quantification methods. Deepen backward integration into thermostable enzyme production to insulate margin structures from raw material volatility. Prioritize AI-assisted viral load interpretation software integration to lock in laboratory information system switching costs. For New Entrants and Emerging Players: CLIA complexity reclassification discussions in United States open a window for waived molecular device market entry at decentralized urgent care settings. Target underpenetrated diagnostic center networks in Baden-Württemberg health systems standardizing instrumentation across affiliated hospitals. Lead with rapid isothermal amplification platforms that bypass thermal cycler capital requirements for price-sensitive European reference laboratories. For Investors and Strategic Acquirers: Distressed-cycle entries favor automated sample-to-answer specialists with completed EU MDR technical documentation in German and French markets. Long-term viability hinges on recurring reagent revenue conversion from installed instrument bases rather than one-time capital equipment sales. Watch for CLIA waiver expansion signals as the inflection trigger for point-of-care volume redistribution.| Strategic Initiative | Industry Significance |
|---|---|
| Multiplex Assay Menu Expansion | Bundled adenovirus-influenza-RSV panels reduce per-test operational overhead in United States hospital core laboratories. |
| EU MDR Conformity Assessment Completion | Accelerated procurement consolidation in German reference laboratories favors suppliers with renewed technical documentation. |
| AI-Assisted Viral Load Software Development | Machine learning integration with laboratory information systems enables automated adenovirus reactivation flagging in transplant wards. |
| Decentralized Testing Waiver Pursuit | CLIA complexity reclassification would redistribute testing volume from centralized reference laboratories toward urgent care clinics. |
| Digital PCR Platform Pilot Programs | Japanese academic medical centers validate absolute quantification methods for copy-number resolution below conventional thresholds. |
Research Methodology
FDA 510(k) clearances, EMA MDR technical documentation filings, and hospital procurement database extracts formed the secondary backbone, cross-referenced against primary interviews with molecular diagnostics laboratory directors, biomedical automation engineers, GPO contracts managers, and transplant ward clinicians. Bottom-up and top-down triangulation validated segment-level estimates against instrument placement records and reagent shipment data.
Bottom-up modeling anchored volume projections to installed base expansion rates and consumable pull-through per thermal cycler, while top-down constraints applied macro healthcare expenditure patterns across the analysis window. Segmentation dimensions included testing method, sample type, end-user certification tier, and regional regulatory cluster. CAGRs derived from logistic diffusion curves fitted to multiplex platform adoption timelines and seasonal respiratory surveillance protocol expansion in hematology-oncology departments.
The model assumes a particular technology adoption path; alternative pathways for digital PCR absolute quantification would alter the outlook for conventional real-time PCR revenue trajectories. Forecasts reflect documented assumptions regarding CLIA complexity classification stability and EU MDR transition timeline adherence. A model refresh is warranted upon material change in decentralized testing waiver approvals or major logistics disruption to North American reagent distribution networks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Laboratory Proficiency Testing Market
Testing Services
Tuberculosis Testing Market
Testing Services
Lipase Testing Reagents Market
Testing Services
Global Mycoplasma Testing Market
Testing Services
Global Homocysteine Testing Market
Testing Services
Global Vitamin D Testing Market
Testing Services
Trichomonas Rapid Testing Market
Testing Services
Calprotectin Testing Market
Testing Services
Drug Tester Market
Testing Services
Over-The-Counter Tests Market
Testing Services
Global Immunoprecipitation Testing Market
Testing Services
Dengue Testing Market
Testing Services
Sickle Cell Anemia Testing and Screening Market
Testing Services
Urodynamic Testing Market
Testing Services
Esoteric Testing Market
Testing Services
West Nile Virus Testing Market