
 Pharmaceutical Analytical Testing Outsourcing Market | 2026-2036
Pharmaceutical Analytical Testing Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
Pharmaceutical Analytical Testing Outsourcing Market Intelligence
Adherence to GxP-compliant bioanalytical testing for large molecules is redrawing the competitive landscape for contract service providers. Charles River Laboratories leverages its extensive portfolio in preclinical services to offer integrated testing solutions. WuXi AppTec dominates the Asia-Pacific market with its large-scale capacity and end-to-end platform. Eurofins Scientific sustains its market position through a decentralized network of specialized laboratories.
Pharmaceutical analytical testing outsourcing refers to the practice of biopharma companies engaging third-party laboratories for drug substance and product analysis. This includes verifying identity, purity, and potency using techniques like high-performance liquid chromatography (HPLC) to meet release specifications. Bioanalytical testing services show significant expansion to support complex biologics, making it a high-growth service type. Among technologies, mass spectrometry is increasingly crucial for advanced applications, while biopharmaceutical companies remain the primary end-user segment.
Regulatory frameworks established by the US FDA, the European Medicines Agency (EMA), and China's NMPA mandate stringent analytical testing for drug approval. These requirements directly influence the scope and complexity of outsourced testing protocols, particularly for novel therapies. Sponsors must continually assess whether to partner with large, integrated contract research organizations or engage specialized niche providers for specific analytical needs.
Market Dynamics
The fundamental market dynamic is the structural shift in pharmaceutical R&D pipelines from chemically synthesized small molecules to complex, biologically derived large molecules. This transition necessitates a corresponding evolution in analytical testing, demanding more sophisticated techniques and expertise that many drug sponsors lack in-house.
Growth Catalysts
- Advanced Therapeutic Modalities:The proliferation of cell therapies, gene therapies, and other advanced therapy medicinal products (ATMPs) requires highly specialized analytical methods to characterize and ensure the safety and efficacy of these complex products.
- Regulatory Scrutiny:Stringent guidelines from the US FDA and European Medicines Agency (EMA) for biosimilar and biologic drug approvals mandate extensive analytical characterization, comparability studies, and GxP-compliant testing, directly increasing outsourcing volume.
- Biotech Funding Environment:Venture capital-backed emerging biopharma companies, particularly those concentrated in life science clusters like the Boston-Cambridge area, often operate with a virtual or semi-virtual model, relying heavily on outsourcing partners for all analytical testing needs.
Market Restraints
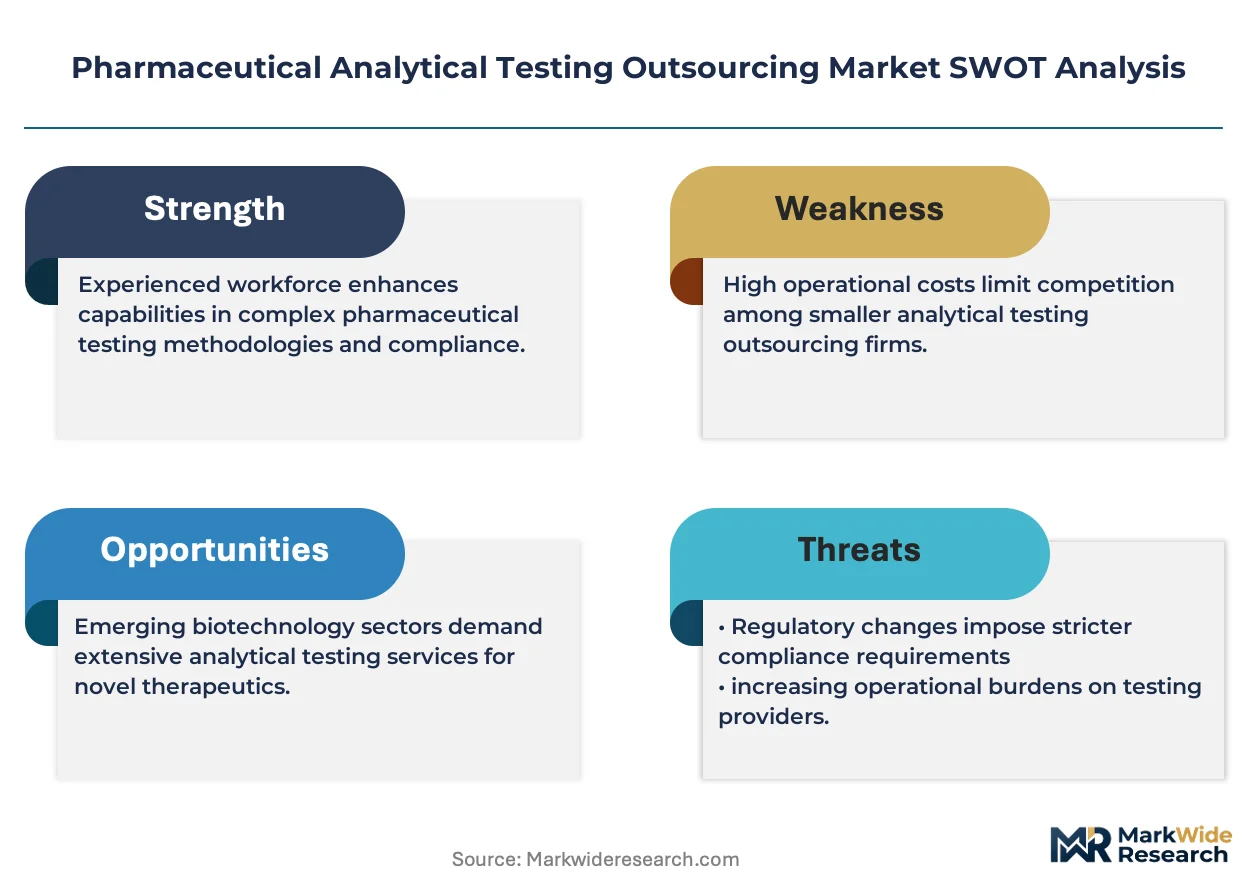
- Instrumentation Costs:The high capital expenditure required to acquire and maintain state-of-the-art analytical instruments, such as high-resolution mass spectrometers and next-generation sequencing platforms, creates a significant financial barrier for contract service providers.
- Talent Scarcity:A persistent shortage of experienced bioanalytical scientists, particularly those with expertise in method development for large molecules under GxP regulations, constrains the capacity of service providers to meet demand.
- Standardization Hurdles:The inherent variability of cell-based assays and other biological testing methods presents challenges in achieving cross-laboratory reproducibility and standardization, which can complicate regulatory submissions and technology transfer processes.
Strategic Opportunities
- Emerging Modalities Support:Developing specialized testing services for novel platforms like mRNA therapeutics and CRISPR-based gene editing presents a significant white-space opportunity, as these modalities have unique analytical requirements not fully addressed by traditional methods. *Geographic Expansion: Establishing GxP-compliant laboratory capacity in emerging biotechnology hubs across the Asia-Pacific region allows service providers to support local clinical trials and capture demand from regional drug developers.
- Data Analytics Integration:Offering advanced data analytics and bioinformatics services to interpret the complex, multi-dimensional datasets generated from modern analytical techniques provides a high-value, differentiated service beyond routine testing.
Industry Challenges
- Method Transfer Complexity:The technical and logistical challenges of transferring complex analytical methods from a sponsor to a contract laboratory, or between different labs, can lead to significant delays and project failures if not managed meticulously.
- Regulatory Divergence:Navigating differing and evolving analytical testing requirements across multiple regulatory jurisdictions, such as the US, Europe, and China, adds complexity and cost for sponsors conducting global clinical trials.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pharmaceutical Analytical Testing Outsourcing Market |
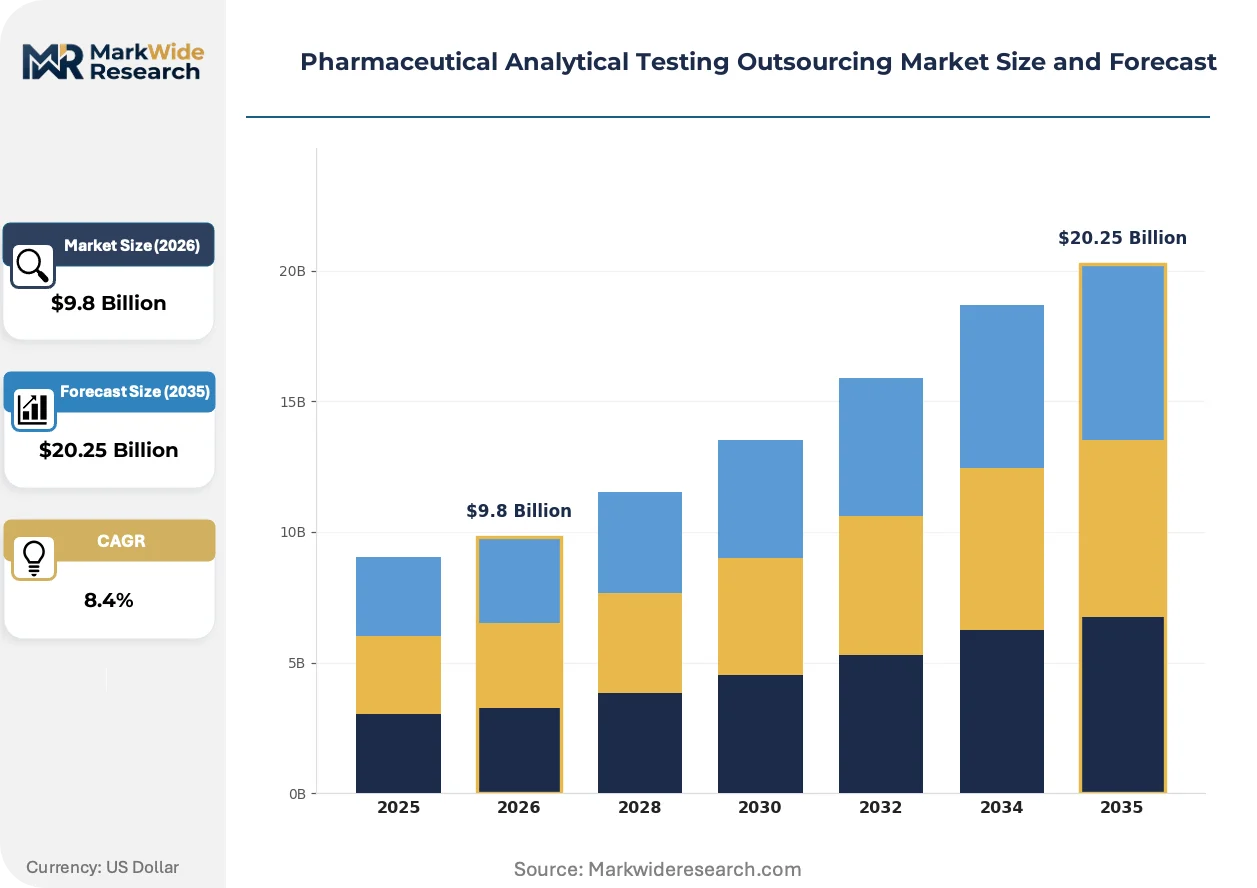
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Method Development, Validation, Stability Testing, Quality Control, Bioanalytical Testing End User: Biopharmaceutical Companies, Contract Research Organizations, Academic Institutions, Diagnostic Laboratories, Nutraceutical Manufacturers Technology: Chromatography, Mass Spectrometry, Spectroscopy, Electrophoresis, Microscopy Application: Drug Discovery, Clinical Trials, Manufacturing Support, Regulatory Compliance, Post-Market Surveillance |
| Companies Covered | Eurofins Scientific, SGS, Charles River Laboratories, WuXi AppTec, Intertek Group, Pace Analytical Services, Labcorp, Thermo Fisher Scientific, Boston Analytical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pharmaceutical Analytical Testing Outsourcing Market Strategic Shifts & Innovations
Automation and data integration are fundamentally transforming analytical workflows. The market is moving away from discrete, manual testing procedures toward industrialized platforms that combine robotics, advanced instrumentation, and sophisticated software to increase throughput and ensure data integrity for complex biologics.
High-resolution mass spectrometry (HRMS) provides unparalleled detail for the molecular characterization of proteins, monoclonal antibodies, and other biologics. Biopharmaceutical companies developing next-generation therapies are rapidly adopting HRMS for everything from clone selection to release testing. This adoption is bifurcating the service market between providers offering premium, in-depth characterization and those competing on price for routine QC testing with older HPLC-based methods.
The International Council for Harmonisation (ICH) Q14 guideline on Analytical Procedure Development is promoting a more scientific, risk-based approach. This framework encourages sponsors and their contract partners to establish a predefined objective and emphasize lifecycle management of analytical methods. Contract research organizations are most impacted, now needing to build robust method development and validation packages that demonstrate a deeper understanding of analytical performance.
A shift from transactional, project-based engagements to strategic, multi-year partnerships is redefining sponsor-CRO relationships. Drug developers are consolidating their outsourcing to a smaller number of preferred providers who can offer integrated services across the entire development lifecycle, from discovery bioanalysis to commercial batch release. This trend is most visible among mid-to-large biopharma companies in North America and Europe aiming to improve efficiency and oversight.
Pharmaceutical Analytical Testing Outsourcing Market Segmentation
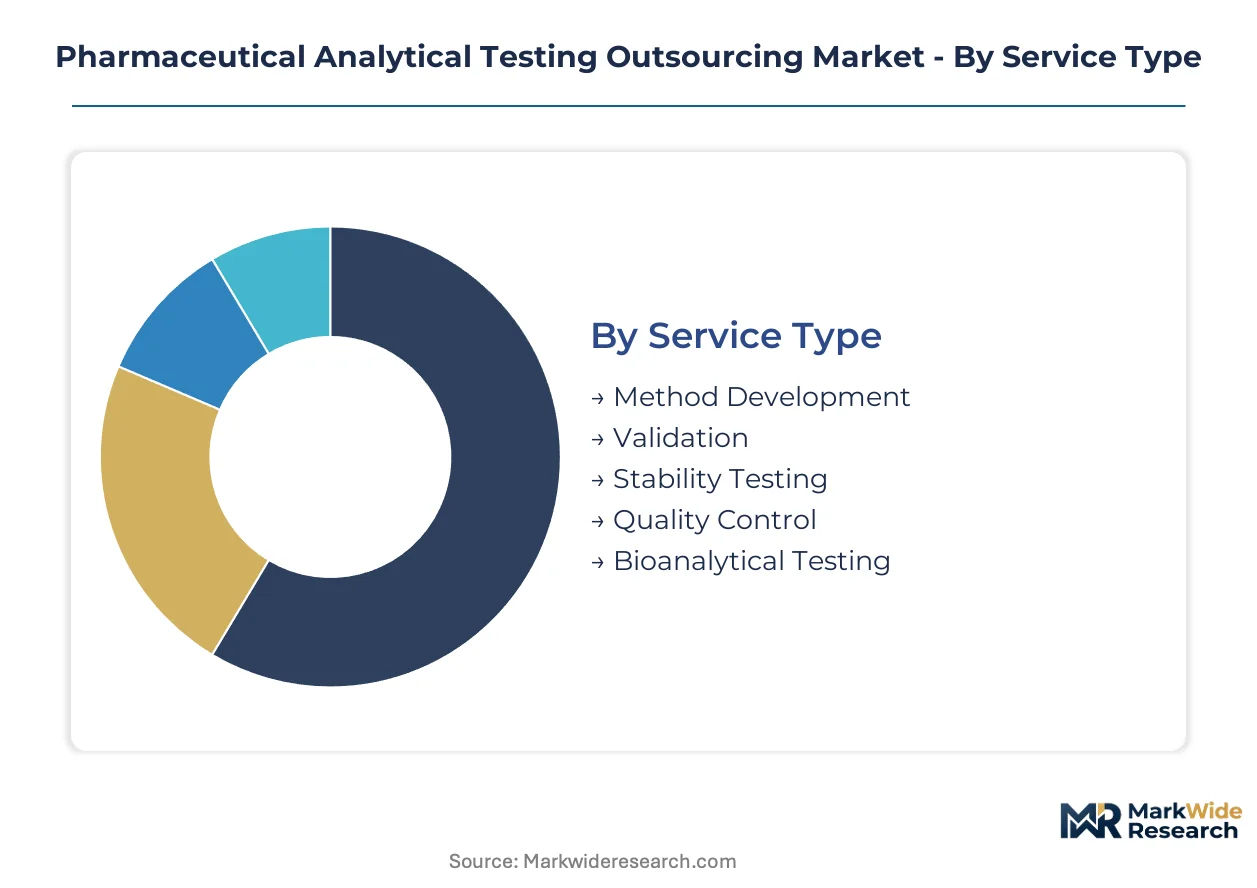
Market segmentation provides a granular understanding of the Pharmaceutical Analytical Testing Outsourcing industry, revealing where value is created and how various elements contribute to overall market dynamics. Analyzing these segments helps stakeholders identify key growth areas and allocate resources effectively within this specialized service sector.
Service Type:
Margin pools within service types are often highest for specialized, complex testing requiring advanced expertise and instrumentation.
- Bioanalytical Testing:This service quantifies drugs and metabolites in biological matrices, essential for pharmacokinetics and pharmacodynamics during drug development. Demand for bioanalytical testing concentrates in North America and Western Europe, driven by complex biologic and biosimilar development pipelines.
- Quality Control:Quality control testing verifies that drug substances and products meet predefined specifications throughout the manufacturing process. This service sees high volume demand globally, particularly from established pharmaceutical companies ensuring batch release compliance.
- Method Development:Developing robust analytical procedures to characterize novel drug candidates is a foundational service for new therapies.
- Validation:Analytical method validation ensures procedures are suitable for their intended purpose, crucial for regulatory submissions to agencies like the US FDA and EMA.
- Stability Testing:Stability studies assess drug product integrity over time under various environmental conditions, critical for shelf-life determination and regulatory approval.
The dominant share belongs to Quality Control, while Bioanalytical Testing is closing the gap fastest.
End User:
Demand volume across end-user segments dictates service provider specialization and capacity planning.
- Biopharmaceutical Companies:These companies, ranging from large pharmaceutical corporations to emerging biotechs, outsource extensively to gain access to specialized analytical expertise and advanced instrumentation. Their demand is particularly strong in life science clusters such as the Boston-Cambridge area.
- Diagnostic Laboratories:Diagnostic laboratories increasingly require outsourced analytical testing for complex biomarker analysis and companion diagnostics, supporting precision medicine initiatives. This segment experiences growth in countries with advanced healthcare infrastructure like Germany and Japan.
- Contract Research Organizations:CROs often subcontract highly specialized analytical testing, particularly for niche bioanalytical services, to manage project peaks or specific technical requirements.
- Academic Institutions:Academic research groups outsource complex analytical tasks to specialized laboratories, complementing in-house capabilities for drug discovery projects.
- Nutraceutical Manufacturers:These manufacturers utilize outsourced testing for ingredient verification and product quality assurance, adhering to food safety and dietary supplement standards.
Biopharmaceutical companies generate the largest revenue streams, with diagnostic laboratories showing strong expansion.
Technology:
Investment in advanced analytical instruments creates distinct cost tiers across technology platforms, influencing service pricing.
- Mass Spectrometry:Mass spectrometry provides detailed molecular characterization of proteins, peptides, and small molecules, crucial for advanced biologics and biosimilar development. Its adoption is accelerating among biopharmaceutical companies in regions like the United States and Switzerland.
- Chromatography:Chromatography, including high-performance liquid chromatography (HPLC) and gas chromatography (GC), separates and quantifies compounds, forming the backbone of routine purity and potency testing. This mature technology sees widespread application across all pharmaceutical markets, including China and India.
- Spectroscopy:Spectroscopy techniques like UV-Vis and FTIR analyze chemical structures and concentrations, supporting early-stage drug characterization.
- Electrophoresis:Electrophoresis separates biomolecules based on charge and size, important for protein characterization and purity assessment.
- Microscopy:Microscopy provides visual characterization of drug formulations and particulate matter, essential for quality control and formulation development.
Mass spectrometry commands premium pricing due to its advanced capabilities, while chromatography remains a high-volume, cost-effective option.
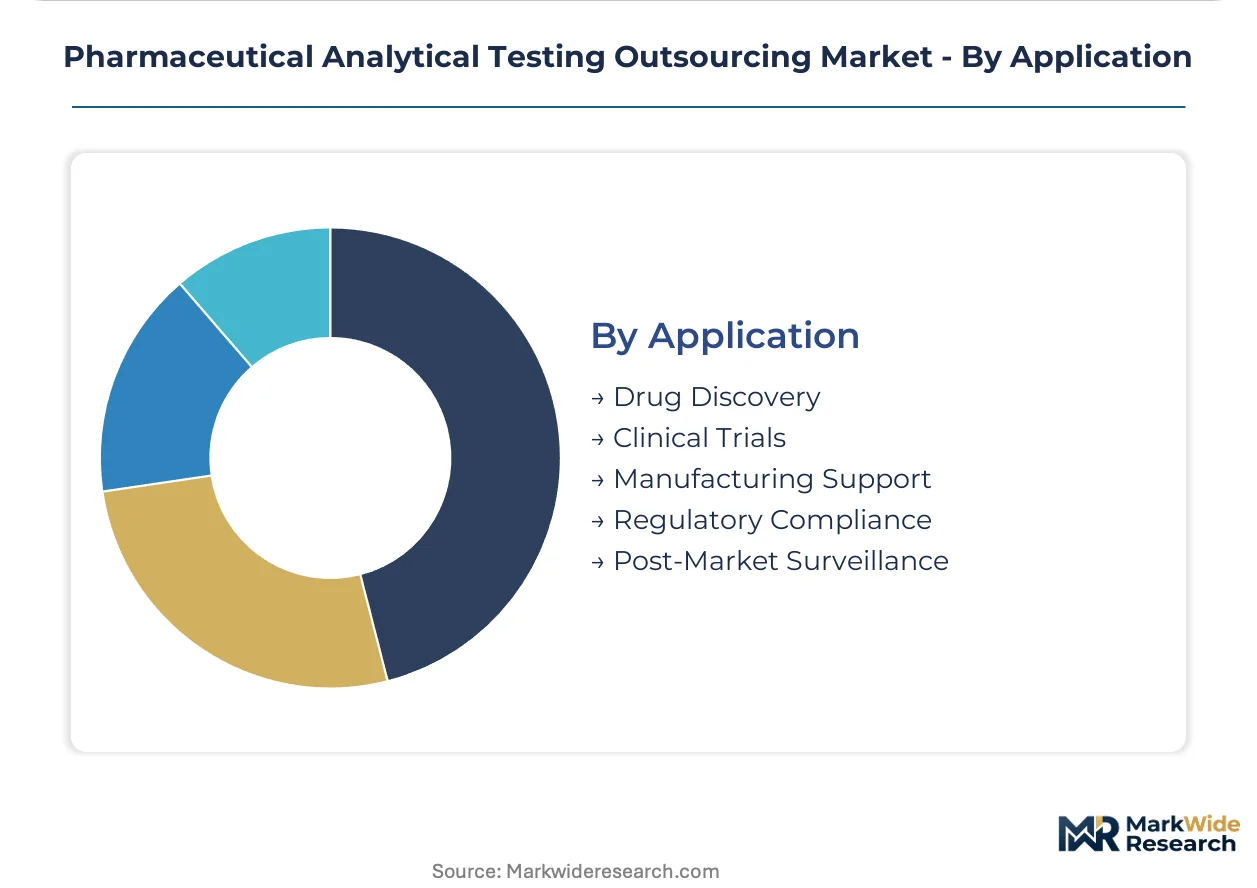
Application:
The criticality of analytical data varies significantly across drug development applications, impacting regulatory requirements and project timelines.
- Clinical Trials:Analytical testing during clinical trials supports drug safety and efficacy evaluation, including bioanalysis of drug levels in patient samples. Regulatory scrutiny from the EMA and US FDA mandates extensive testing for all phases of clinical development.
- Manufacturing Support:This application involves ongoing analytical testing to monitor raw materials, in-process samples, and finished products, ensuring consistent quality and GxP compliance. Demand for manufacturing support is stable across established pharmaceutical production hubs globally.
- Drug Discovery:Analytical services in drug discovery focus on compound screening, hit identification, and lead optimization, accelerating early-stage development.
- Regulatory Compliance:Ensuring adherence to global regulatory guidelines, such as those from China's NMPA, requires specialized analytical testing and comprehensive documentation.
- Post-Market Surveillance:Analytical testing supports post-market activities, including impurity profiling and stability monitoring, to ensure continued product safety and quality after commercial launch.
Clinical trials represent a critical high-value segment, with manufacturing support driving consistent, large-scale demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Where buyers are most price-sensitive, routine quality control testing often drives outsourcing decisions. Conversely, complex bioanalytical services for novel therapies command premium pricing due to specialized expertise. This demand elasticity shapes regional market dynamics, influencing service provider investments and geographic expansion strategies.
United States
The US market shows high demand for bioanalytical testing, driven by a robust pipeline of complex biologics. The US FDA mandates stringent analytical characterization for new drug approvals, increasing outsourcing volume. Life science clusters in Boston-Cambridge are key centers for emerging biopharma companies seeking specialized analytical support.
Germany
German biopharmaceutical companies require extensive analytical testing for advanced therapeutic medicinal products. The European Medicines Agency (EMA) guidelines for biosimilar and biologic approvals necessitate GxP-compliant testing. The Frankfurt-Rhine-Main region fosters pharmaceutical R&D, creating demand for sophisticated outsourced analytical services.
Japan
Japanese drug developers increasingly outsource analytical services for novel cell and gene therapies. Japan's PMDA requires comprehensive analytical data for drug registration, impacting testing protocols. Tokyo's biotech ecosystem supports specialized analytical laboratories, catering to advanced pharmaceutical research.
China
China's expanding biopharmaceutical industry generates significant demand for quality control and bioanalytical testing. The NMPA's evolving regulatory framework for drug approval influences the scope of outsourced testing. Shanghai's growing life science parks attract investment in analytical testing infrastructure, supporting local and international drug development.
India
Indian pharmaceutical manufacturers seek outsourced analytical testing for generic drugs and biosimilars to meet global standards. The CDSCO's focus on quality assurance for drug exports drives demand for compliant testing. Hyderabad's Pharma City is a hub for contract research and manufacturing organizations, requiring extensive analytical support.
Pharmaceutical Analytical Testing Outsourcing Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the pharmaceutical analytical testing outsourcing market. The market exhibits a tiered structure, with large, integrated contract research organizations coexisting with specialized niche providers. These archetypes include global full-service providers, regional specialists, and technology-focused innovators. Strategic partnerships and geographic expansion are dominant competitive moves as companies seek to broaden their service portfolios and reach new markets.
Global full-service providers, such as Charles River Laboratories, leverage extensive preclinical service portfolios to offer integrated testing solutions. WuXi AppTec, a prominent player, dominates the Asia-Pacific market through its large-scale capacity and end-to-end platform, exemplifying a regional specialist with global reach. Eurofins Scientific occupies a position as a diversified service provider, sustaining its market standing through a decentralized network of specialized laboratories across various geographies. These companies anchor different segments of the market, from early-stage development to routine quality control.
| Leading Market Players |
|---|
| Eurofins Scientific |
| SGS |
| Charles River Laboratories |
| WuXi AppTec |
| Intertek Group |
| Pace Analytical Services |
| Labcorp |
| Thermo Fisher Scientific |
| Boston Analytical |
| Others |
Cost & Logistics Intelligence
Typical turnaround times for complex bioanalytical testing directly influence pricing power for specialized providers and dictate the need for distributed laboratory networks. This metric reflects the efficiency of the supply chain in delivering time-sensitive analytical results to biopharmaceutical clients.
Pricing Analysis
Ongoing method validation services represent a significant after-sales revenue tier, driving lifetime value for contract analytical testing providers. The dominant pricing model involves project-based engagements for specific tests, often transitioning to long-term contract-based relationships with preferred providers. Price differentiation stems from expertise in novel therapeutic modalities like cell and gene therapies and the level of GxP compliance. Pricing pressure intensifies for routine quality control testing due to increased competition and commoditization. Emerging biopharmaceutical companies often exhibit the highest price sensitivity for standard assays, while large pharmaceutical corporations prioritize integrated solutions and robust quality systems.
Supply Chain Analysis
Strategic stockpiling of specialized reagents and reference standards is crucial for maintaining analytical capacity and mitigating supply disruptions. Geographic supply concentration for key analytical inputs includes the United States, Germany, and China, particularly for active pharmaceutical ingredients which require extensive testing. The industry relies heavily on high-purity solvents, mass spectrometry consumables, and specialized cell culture media. A structural risk involves single-source vulnerability for rare or proprietary reagents essential for advanced assays. Distribution runs through a network of regional laboratories, enabling direct service delivery to localized life science clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a buyer-power-shift story, driven by the consolidation of analytical testing needs among large biopharmaceutical companies seeking integrated, end-to-end service providers.
For Market Incumbents: Secure long-term strategic partnerships with large biopharma clients by offering integrated service portfolios across the entire drug development lifecycle. Invest in advanced instrumentation and specialized GxP-compliant capacity in high-growth regions like the Asia-Pacific to counter the threat from emerging niche providers. Certification investment in specific regulatory body approvals (e.g., US FDA, EMA) enhances competitive advantage and client trust.
For New Entrants and Emerging Players: Anchor in specialized analytical services for novel platforms such as mRNA therapeutics and CRISPR-based gene editing, which present significant white-space opportunities. Target emerging biotechs within focused life science clusters, like the Boston-Cambridge area, as the most penetrable segment. A go-to-market angle emphasizing rapid turnaround times and deep scientific expertise in niche areas can attract early adopters.
For Investors and Strategic Acquirers: Long-term, this sits as a specialized infrastructure play because biopharmaceutical R&D requires increasingly complex and capital-intensive analytical support. Acquisition targets should focus on vertically integrated mid-cap specialists possessing unique technology platforms or critical GxP certifications. The signal to watch is increased M&A activity for niche bioanalytical laboratories, indicating a consolidation phase for specialized capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Enhances service throughput and reduces lead times for critical testing. |
| Technology Licensing | Accesses proprietary analytical methods for advanced therapeutic modalities. |
| Platform Integration | Streamlines complex workflows and improves data integrity for clients. |
| Geographic Expansion | Supports local clinical trials and captures demand from regional drug developers. |
| Strategic Partnership | Provides integrated services across the drug development lifecycle for biopharma clients. |
Research Approach
Initial hypotheses were tested against primary input from drug development executives, regulatory affairs leads, laboratory directors, and procurement managers, then refined through iterative analysis. This involved combining insights from these expert interviews with rigorous secondary validation. Secondary data sources included US FDA filings, EMA submissions, scientific publications, and corporate financial reports, ensuring a comprehensive view. The approach employed both bottom-up and top-down triangulation to validate market size and growth projections.
Variance decomposition identified key drivers impacting service type, end-user, and technology segments across the analysis window. The analytical framework modeled segmentation dimensions including service type, end user, technology, application, and regional regulatory compliance. Compound annual growth rates were derived through regression analysis of historical data and projected market shifts. Biologic pipeline growth rates and regulatory approval rates for novel therapies served as critical industry-specific forecast inputs.
Material uncertainties — such as unforeseen regulatory changes, major technological breakthroughs, or significant shifts in biopharma R&D funding — sit outside the modeled envelope. The forecasts reflect assumptions documented at the time of analysis, but are subject to change. Revision becomes warranted when global economic downturns affecting R&D budgets cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Gastrointestinal Testing Panels Market
Testing Services
Sickle Cell Anemia Testing and Screening Market
Testing Services
Hospital Acquired Disease Testing Market
Testing Services
Special Coagulation Tests Market
Testing Services
North America Endotoxin and Pyrogen Testing Market
Testing Services
Influenza a/B Combo Testing Market
Testing Services
Pharmaceutical Sterility Testing Market
Testing Services
Biological Indicator Incubators Market
Testing Services
Global Cannabis Testing Market
Testing Services
US Bowie Dick Test Pack Market
Testing Services
Arbovirus Testing Market
Testing Services
Global Mycoplasma Testing Market
Testing Services
Asia Pacific Sterility Testing Market
Testing Services
Outsourced Testing Services Market
Testing Services
Global Mosquito Borne Infections Testing Market
Testing Services
Lab Screening Test Kit Market