
 Testing and Analysis Services Market | 2026-2036
Testing and Analysis Services Market Size, Share, and Industry Trends Forecast 2026-2036
Testing and Analysis Services Market Analysis
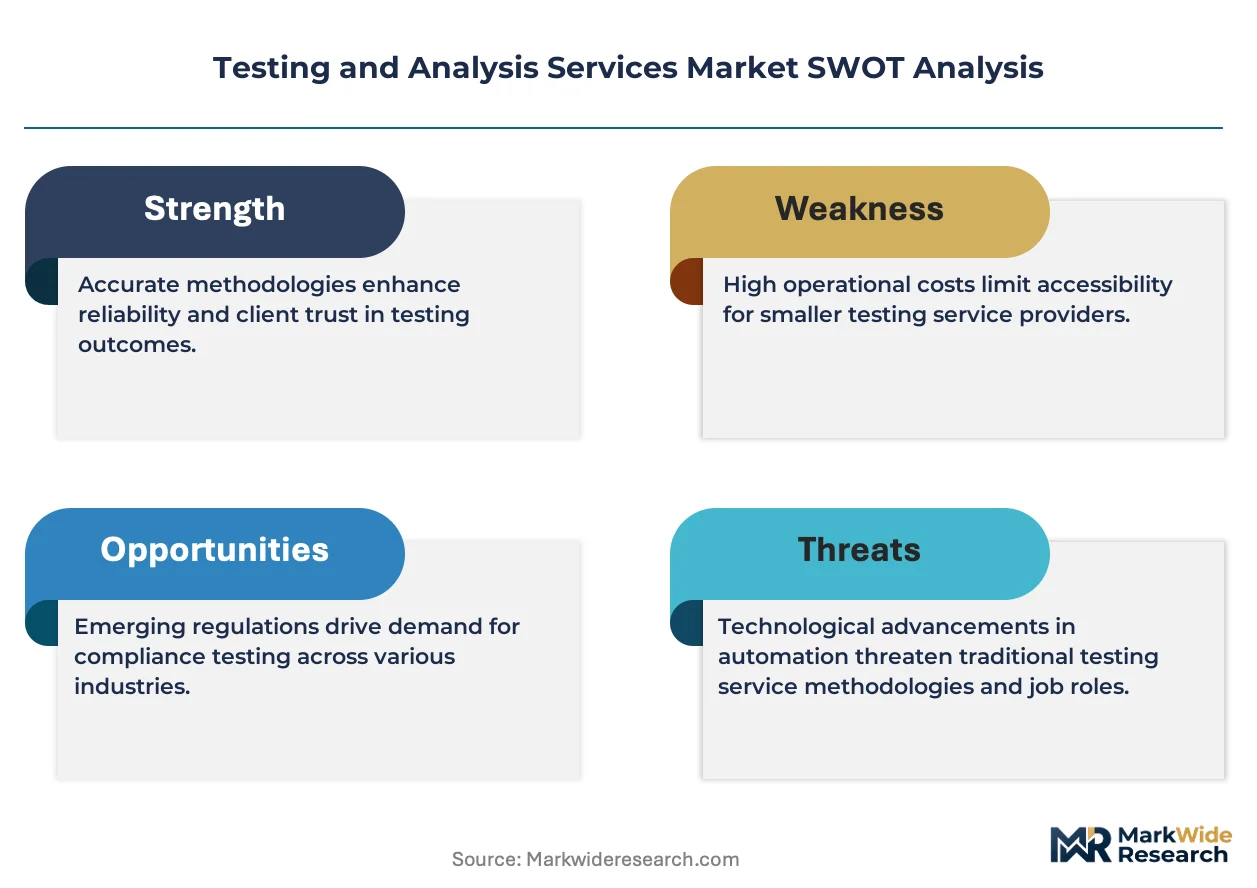
China is tilting toward domestic capacity in materials testing and environmental analysis, reducing reliance on foreign-certified laboratories for construction and electronics exports. Eurofins Scientific anchors its position through extensive laboratory networks across Asia-Pacific and Europe. ALS Limited leverages its mining and geochemistry heritage to compete in industrial minerals testing. Intertek Group differentiates through integrated assurance and product certification services alongside analytical testing.
Testing and analysis services encompass the systematic examination of materials, products, processes, and systems to verify conformance to specifications, safety standards, and regulatory requirements using chromatography, spectroscopy, mechanical stress analysis, and microbiological assay techniques. These services enable manufacturers to validate product integrity, ensure supply chain compliance, and satisfy mandatory pre-market approval conditions. Laboratory testing commands the largest share of service type revenue due to capital-intensive instrumentation requirements and accreditation barriers that limit new entrants. Remote services within the delivery model segment are expanding fastest as cloud-connected instrumentation and digital data reporting reduce client site visit frequency. The pharmaceuticals vertical maintains the deepest margin pools because batch release testing and stability studies require GMP-compliant facilities with specialized analytical capabilities.
FDA enforcement of current good manufacturing practice regulations and the EPA's Toxic Substances Control Act reporting obligations directly shape demand for third-party analytical validation in the United States. REACH compliance requirements administered by ECHA mandate extensive chemical characterization for substances imported into or manufactured within the European Economic Area. ISO 17025 accreditation serves as the baseline credential for cross-border recognition of test results, though national regulators including China's SAMR impose supplementary GB standards for domestic market access. Stakeholders must monitor how divergent digital data integrity requirements across FDA, EMA, and NMPA reshape the cost structure of multi-jurisdiction compliance programs.
Market Dynamics
Third-party laboratories face mounting pressure to integrate cloud-connected instrumentation with legacy quality management systems as pharmaceutical and medical device manufacturers consolidate vendor relationships under risk-based audit frameworks.
Growth Catalysts
- EU Medical Device Regulation:Batch release testing mandates for Class IIb and III devices drive demand for notified body partnerships across Germany, France, and the Netherlands.
- Pharmaceutical outsourcing:North American manufacturers are divesting in-house analytical capabilities to focus on core R&D, creating captive demand for specialized stability and extractables testing.
- Environmental monitoring:EPA Toxic Substances Control Act reporting obligations require industrial facilities to engage certified laboratories for PFAS and persistent organic pollutant screening.
Market Restraints
- Accreditation concentration:ISO 17025 certification bodies cluster in Western Europe and the United States, creating bottlenecks for Asian laboratories seeking cross-border recognition.
- Specialized instrumentation costs:High-resolution mass spectrometry and next-generation sequencing platforms require capital outlays that strain mid-tier service providers.
- Regulatory fragmentation:Divergent digital data integrity requirements between FDA 21 CFR Part 11, EMA Annex 11, and NMPA GMP guidelines inflate compliance overhead for multi-jurisdiction operators.
Strategic Opportunities
- Cell and gene therapy analytics:Viral vector potency assays and CAR-T characterization services remain underserved as biologics pipelines expand.
- India's PLI scheme:Domestic pharmaceutical manufacturing incentives create demand for local testing infrastructure to replace import-dependent validation workflows.
- Remote sensor networks:Continuous environmental monitoring systems paired with automated reporting platforms open subscription revenue streams beyond traditional sample-by-sample billing.
Industry Challenges
- Analytical talent scarcity:Chromatography and mass spectrometry specialists command premium compensation, constraining laboratory expansion timelines.
- Legacy LIS integration:Paper-based quality management systems in acquired facilities resist digitization, delaying unified data architecture deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Testing and Analysis Services Market |
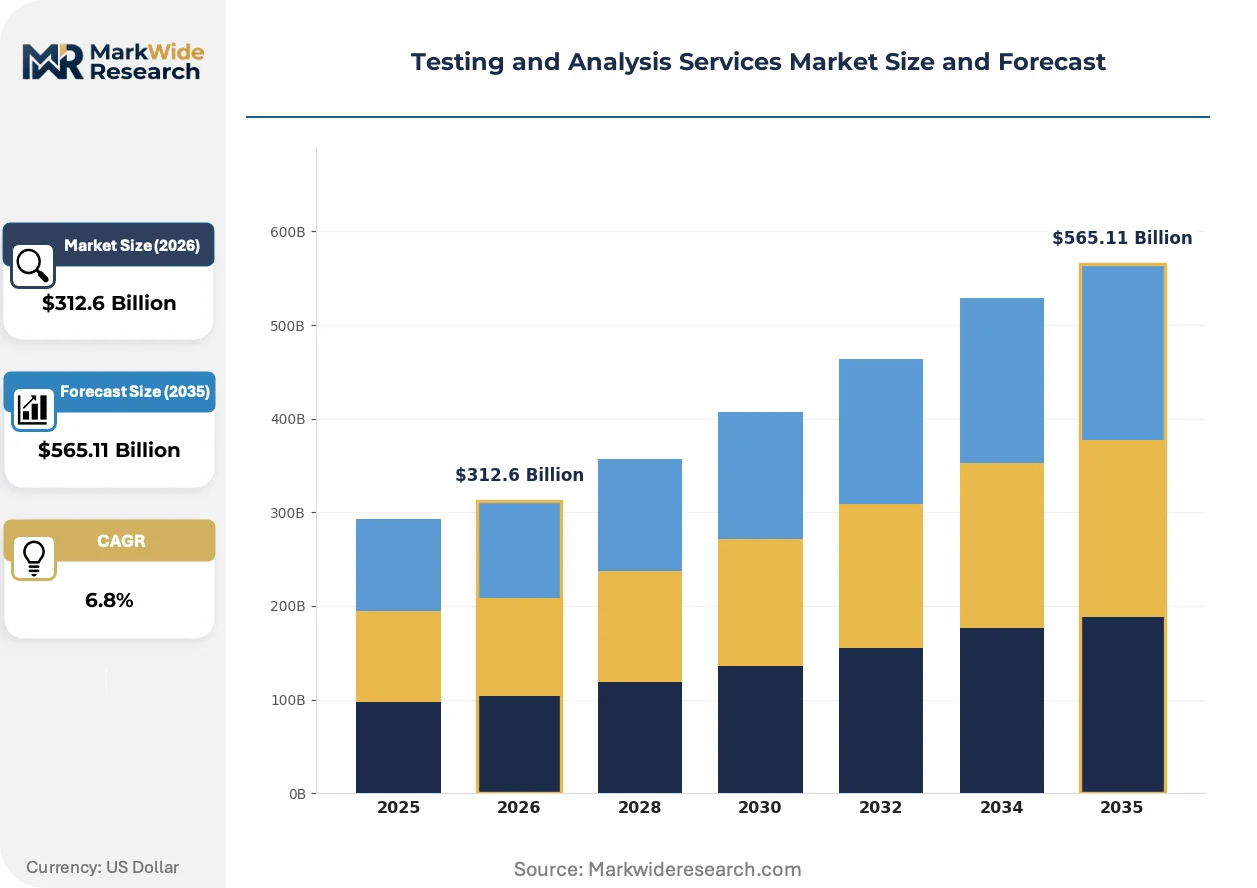
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $565.11 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Laboratory Testing, Field Testing, Quality Assurance, Compliance Testing Industry Vertical: Pharmaceuticals, Agriculture, Construction, Electronics Delivery Model: Onsite Services, Remote Services, Subscription Model, Project-Based Technology: Automated Testing, Manual Testing, Data Analysis Tools, Testing Software |
| Companies Covered | Accenture, Tata Consultancy Services, Infosys, Capgemini, ALS Limited, Eurofins Scientific, Element Materials Technology, IBM, Intertek Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Testing and Analysis Services Market Emerging Trajectories
Digitization of laboratory workflows is compressing turnaround times and enabling real-time client collaboration, while regulatory convergence pressures force strategic choices about geographic certification coverage.
Artificial intelligence-assisted spectral interpretation is migrating from experimental pilot programs to standard operating procedure in high-throughput pharmaceutical laboratories. Contract research organizations serving generic drug manufacturers have adopted machine learning algorithms for impurity profiling and structure elucidation. This migration from manual data review to automated flagging is compressing analytical method development cycles from weeks to days.
REACH authorization requirements for Substances of Very High Concern are forcing chemical manufacturers to commission extensive toxicological dossiers from specialized testing consortia. The European Chemicals Agency's expanding candidate list now covers over 230 substances, with sunset dates triggering pre-deadline analytical surges. Specialty chemical exporters to the European Economic Area are consolidating testing contracts with full-service laboratories capable of handling both physico-chemical characterization and ecotoxicology endpoints.
Long-term service agreements with annual minimum volume commitments are displacing transactional sample submission models in the food safety segment. Retail private-label suppliers facing repeated audit failures are embedding third-party laboratories into supplier quality agreements rather than engaging post-failure remediation testing. This shift is most visible in North American fresh produce and ready-to-eat meal categories, where buyer consolidation has concentrated negotiating leverage among a handful of national grocery chains.
Testing and Analysis Services Market Segmentation
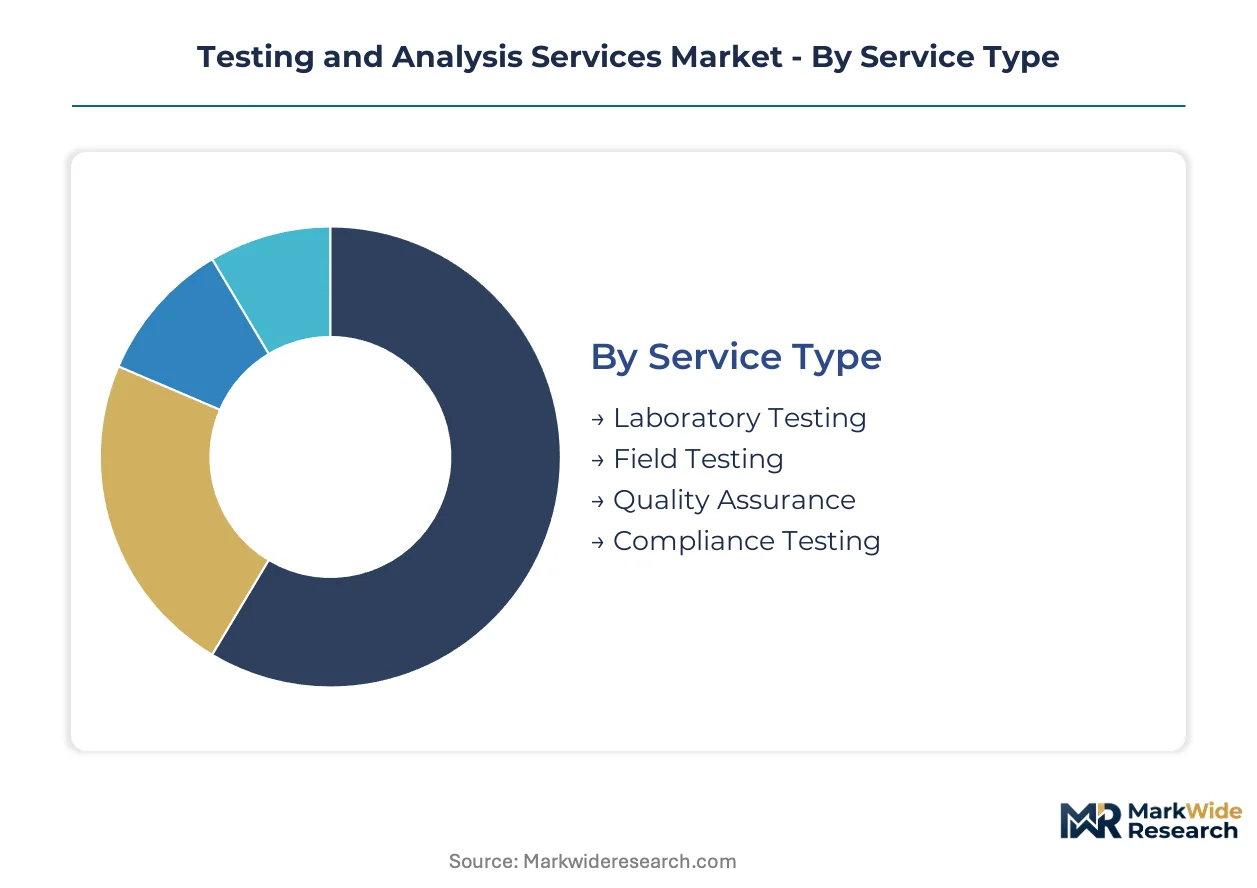
Testing and analysis services fragment across multiple dimensions that reshape procurement patterns and margin structures. Service type determines capital intensity and accreditation barriers. Delivery model governs client relationship tenure and revenue predictability.
Service Type:
After-sales service intensity varies dramatically across service types, with instrumentation-dependent segments requiring ongoing calibration support and method transfer consulting.
- Laboratory Testing:Capital-intensive chromatography, spectroscopy, and microbiological assay work performed in accredited facilities. Pharmaceutical batch release testing in Germany and stability studies for FDA submissions concentrate demand among GMP-compliant laboratories facing ISO 17025 renewal cycles.
- Field Testing:Mobile sampling and on-site analysis for environmental monitoring and construction materials verification. EPA-mandated PFAS screening at industrial facilities and geotechnical validation for German automotive supplier parks drive contract volumes.
- Quality Assurance:Process auditing and supplier qualification programs. Food safety audits for North American retail chains and medical device supplier assessments under EU MDR frameworks sustain recurring engagement models.
- Compliance Testing:Regulatory submission support and certification documentation. REACH dossier preparation for chemical exporters and RoHS verification for electronics manufacturers require specialized toxicological and materials characterization capabilities.
Laboratory Testing holds the largest share; momentum sits with Quality Assurance as risk-based audit frameworks deepen vendor integration.
Industry Vertical:
Cost tier stratification separates verticals, with life sciences commanding premium pricing for GMP compliance while construction and agriculture compete on throughput scale.
- Pharmaceuticals:Batch release, stability, and extractables testing for small molecules and biologics. CAR-T characterization and viral vector potency assays represent the steepest expansion trajectory as cell therapy pipelines mature.
- Agriculture:Soil composition, pesticide residue, and GMO verification services. EU Green Deal sustainability metrics and FSSAI import requirements for Indian spice exporters reshape testing protocols.
- Construction:Materials strength, environmental impact, and building code compliance testing. China's domestic capacity expansion in materials certification reduces foreign laboratory reliance for infrastructure exports.
- Electronics:RoHS substance screening, electromagnetic compatibility, and failure analysis. REACH Substances of Very High Concern list expansion forces component manufacturers to commission extensive supply chain characterization.
Pharmaceuticals holds the largest share; momentum sits with Electronics as regulatory substance restrictions multiply.
Delivery Model:
Customer type segmentation separates transactional project work from embedded strategic partnerships with diverging margin profiles.
- Onsite Services:Dedicated personnel embedded at client facilities for continuous monitoring. Pharmaceutical manufacturing sites in Switzerland and medical device production in Ireland deploy resident analytical teams for real-time batch decisions.
- Remote Services:Cloud-connected instrumentation with digital data reporting and virtual consultation. Environmental sensor networks with automated EPA reporting and remote pharmaceutical stability monitoring are climbing the fastest as instrumentation connectivity improves.
- Subscription Model:Annual testing volume commitments with preferential turnaround guarantees. North American fresh produce suppliers and ready-to-eat meal manufacturers embed laboratories into supplier quality agreements.
- Project-Based:Discrete analytical method development or regulatory submission support. REACH sunset date surges and FDA pre-approval inspection preparation create episodic demand spikes.
Onsite Services holds the largest share; momentum sits with Subscription Model as buyer consolidation concentrates procurement leverage.
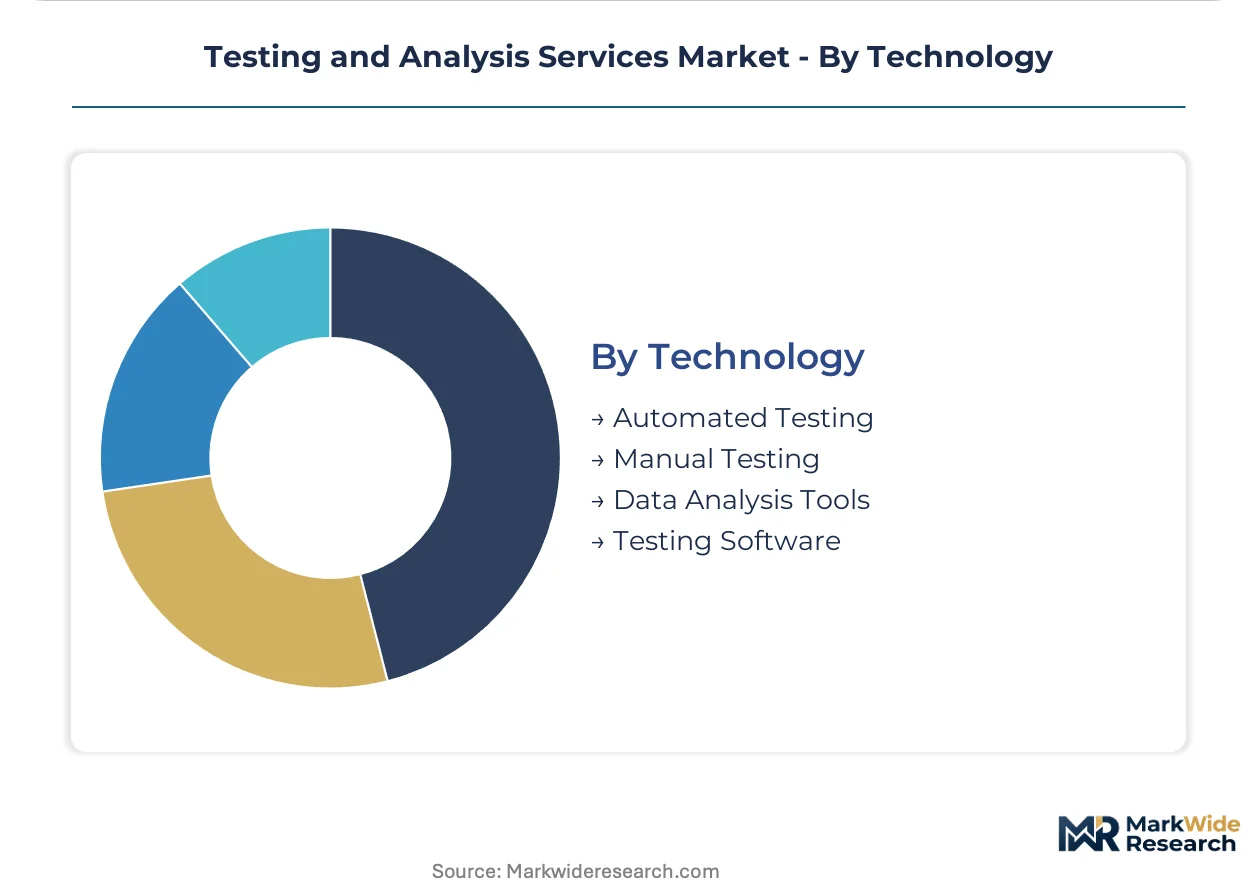
Technology:
Supply concentration in automated platforms is displacing manual methods as labor scarcity and throughput demands reshape laboratory economics.
- Automated Testing:Robotic sample handling and high-throughput analytical platforms. Machine learning-assisted impurity profiling in generic drug laboratories compresses method development cycles from weeks to days.
- Manual Testing:Technician-dependent microscopy, sensory evaluation, and specialized dissection. Artisanal food certification and certain forensic applications retain manual protocols despite automation pressure.
- Data Analysis Tools:Statistical software and spectral interpretation platforms. AI-assisted structure elucidation and regulatory submission document generation reduce analytical scientist review burden.
- Testing Software:Laboratory information systems and quality management platforms. Legacy LIS integration challenges delay unified data architecture deployment in acquired facilities.
Automated Testing holds the largest share; momentum sits with Data Analysis Tools as spectral interpretation algorithms mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Testing laboratory networks concentrate in jurisdictions with dense manufacturing bases and stringent regulatory enforcement. Germany, the United States, China, India, and Switzerland host the most accredited facilities serving cross-border compliance requirements.
United States
Pharmaceutical manufacturers in New Jersey and Massachusetts outsource batch release testing to third-party laboratories as FDA 21 CFR Part 11 enforcement intensifies. The EPA's Toxic Substances Control Act mandates PFAS screening at industrial facilities across the Rust Belt. Chicago and Houston sustain major laboratory clusters serving chemical and energy sector compliance.
Germany
Automotive supplier parks around Stuttgart and Munich demand continuous materials verification and environmental monitoring. ECHA REACH authorization deadlines for Substances of Very High Concern trigger analytical surges from chemical exporters. The country's notified body density under EU Medical Device Regulation supports Class III device testing concentration.
China
Domestic capacity expansion in materials testing reduces reliance on foreign-certified laboratories for construction and electronics exports. NMPA GMP guidelines and GB standards impose supplementary requirements for pharmaceutical market access. Yangtze River Delta industrial clusters around Shanghai sustain dense networks of SAMR-accredited facilities.
India
PLI scheme incentives for domestic pharmaceutical manufacturing create demand for local testing infrastructure. CDSCO import requirements and FSSAI spice export protocols reshape analytical protocols for agrochemical and food sectors. Maharashtra and Gujarat host expanding laboratory capacity serving generic drug manufacturers.
Switzerland
Swissmedic regulations and proximity to EU markets position Basel and Zurich as hubs for biologics stability studies. Pharmaceutical manufacturing sites deploy resident analytical teams for real-time batch release decisions. The country's dual EU-third country regulatory status attracts multi-jurisdiction compliance programs.
Testing and Analysis Services Market Vendor Landscape
Full-service networks and specialized boutiques split the market into distinct competitive tiers. Consolidation pressures favor laboratories with multi-jurisdiction accreditation portfolios and integrated assurance capabilities. Three archetypes dominate: global network operators with extensive geographic coverage, vertical specialists leveraging heritage expertise in mining or geochemistry, and technology-forward platforms emphasizing digital data integration. M&A activity targets mid-tier regional laboratories to fill geographic gaps, while strategic partnerships with pharmaceutical manufacturers deepen vendor integration under risk-based audit frameworks.
Within the network-operator tier, Eurofins Scientific and Intertek Group exemplify scale-driven positioning through extensive laboratory footprints across Asia-Pacific and Europe. ALS Limited occupies a specialist position anchored in mining and geochemistry heritage. These three entities represent contrasting strategic approaches to capability breadth versus depth in testing and analysis services.
| Leading Market Players |
|---|
| Accenture |
| Tata Consultancy Services |
| Infosys |
| Capgemini |
| ALS Limited |
| Eurofins Scientific |
| Element Materials Technology |
| IBM |
| Intertek Group |
| Others |
Supply Flow & Price Mechanics
Rotterdam-Antwerp laboratory reagent corridors channel specialized chromatography solvents and certified reference materials into German testing clusters, with freight cost volatility compressing margins for mid-tier providers while concentrating pricing power among ISO 17025-accredited facilities serving pharmaceutical batch release.
Pricing Analysis
EU REACH authorization requirements dictate the pricing tier structure across toxicological dossier preparation, with three-tier pricing separating GMP-certified pharmaceutical stability studies from industrial materials verification and routine environmental screening. Certification grade and volume scale drive price differentiation, with FDA-submission-grade extractables testing commanding substantial premiums over non-GMP analytical work. Cost compression in routine environmental PFAS screening is intensifying because China's domestic capacity expansion floods export markets with lower-cost alternatives. Generic drug manufacturers exhibit highest price sensitivity, while cell and gene therapy developers remain least sensitive due to viral vector potency assay complexity.
Supply Chain Analysis
Export-control restrictions on high-resolution mass spectrometry components limit instrument flows from Germany, Japan, and the United States to Chinese laboratory networks, constraining capacity expansion for SAMR-accredited facilities. Specialized chromatography columns, certified reference standards, and GMP-compliant reagents anchor raw material dependencies. Single-source vulnerability concentrates in precision optics manufacturing for spectroscopy platforms. Distribution runs through regional hub-and-spoke models centered on Frankfurt, Singapore, and Chicago, with consolidated procurement by pharmaceutical manufacturers reshaping vendor relationship economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized chromatography and mass spectrometry expertise constrains laboratory expansion timelines across all tiers, with talent scarcity reshaping competitive positioning and M&A target selection.
For Market Incumbents: Insulate margin pools by embedding resident analytical teams at pharmaceutical manufacturing sites in Switzerland and Ireland, locking in multi-year service agreements before generic drug manufacturers consolidate vendor panels. Acquire mid-tier regional laboratories in India's Maharashtra and Gujarat to capture PLI-scheme-driven demand for domestic pharmaceutical testing infrastructure. Accreditation bottlenecks for Asian laboratories seeking cross-border recognition present defensive moat opportunities. For New Entrants and Emerging Players: Pursue cell and gene therapy analytics as the most penetrable white-space segment, specifically viral vector potency assays and CAR-T characterization services where biologics pipelines outpace specialized laboratory capacity. Target India's domestic pharmaceutical testing infrastructure gap created by import substitution mandates under the PLI scheme. Position through cloud-connected remote monitoring platforms with automated regulatory reporting to bypass capital-intensive facility buildouts. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive testing divisions lacking ISO 17025 renewal discipline or digital data architecture integration. Long-term viability hinges on multi-jurisdiction accreditation portfolios spanning FDA, EMA, and NMPA frameworks. Monitor ECHA REACH sunset date surges as inflection indicators for specialty chemical testing demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Jurisdiction Accreditation Expansion | ISO 17025 renewal cycles across FDA, EMA, and NMPA frameworks secure cross-border test result recognition for pharmaceutical clients. |
| Cell Therapy Analytics Capability Buildout | Viral vector potency assays address underserved demand as CAR-T pipelines mature and batch release testing volumes surge. |
| Cloud-Connected Remote Monitoring Deployment | Environmental sensor networks with automated EPA reporting open subscription revenue streams beyond transactional sample billing. |
| India Laboratory Network Expansion | PLI scheme incentives for domestic pharmaceutical manufacturing create captive demand for local CDSCO-compliant testing infrastructure. |
| Legacy LIS Integration and Digitization | Unified data architecture deployment in acquired facilities accelerates AI-assisted spectral interpretation adoption and turnaround compression. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across laboratory directors, pharmaceutical regulatory affairs leads, third-party quality assurance managers, and environmental compliance officers at industrial facilities. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, ECHA REACH authorization databases, EMA GMP inspection reports, and SAMR GB standards filings. Bottom-up service-type segmentation modeling and top-down macroeconomic overlay triangulation anchored market size estimation.
Calibration against historical accreditation growth patterns and instrument installation base expansion informed trajectory modeling across the projection horizon. Segmentation dimensions spanned service type, industry vertical, delivery model, and technology tier, with regulatory framework clusters treated as cross-cutting modifiers. CAGRs derived from instrument capacity utilization trends and outsourcing penetration rates in pharmaceutical manufacturing, with environmental monitoring obligation expansion and cell therapy pipeline maturation serving as industry-specific demand inputs.
Macroeconomic conditions sit as an overlay; deviation in pharmaceutical R&D expenditure cycles or chemical manufacturing output would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement intensity and accreditation body capacity expansion. Material shifts in FDA data integrity guidance or ECHA SVHC list expansion velocity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Pneumonia Testing Market
Testing Services
Host Cell Protein Testing Market
Testing Services
Ferritin Testing Market
Testing Services
Europe Mass Spectrometry Market
Testing Services
Calprotectin Testing Market
Testing Services
Pharmaceutical Analytical Testing Market
Testing Services
Asia Pacific Pregnancy and Ovulation Testing Market
Testing Services
ATP Assays Market
Testing Services
Global Homocysteine Testing Market
Testing Services
Global Enzyme Linked Immunosorbent Assay (ELISA) Testing Market
Testing Services
Biological Safety Testing Products and Services Market
Testing Services
Sports Drug Testing Market
Testing Services
Arbovirus Testing Market
Testing Services
West Nile Virus Testing Market
Testing Services
Ige Allergy Blood Tests Market
Testing Services
Thailand Point-Of-Care Testing (POCT) Market