
 Apolipoprotein Testing Market | 2026-2036
Apolipoprotein Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Apolipoprotein Testing Market Insights
The capital-intensity divergence between fully automated platform manufacturers and boutique reagent suppliers is bifurcating competitive dynamics in apolipoprotein testing. Abbott Laboratories leverages its integrated immunoassay-architecture installed base across hospital core laboratories. Siemens Healthineers sustains R&D intensity in high-throughput chemistry-analyzer compatibility. Thermo Fisher Scientific differentiates through mass-spectrometry workflow standardization for reference-method laboratories.
Apolipoprotein testing measures specific protein constituents of lipoprotein particles—primarily ApoA-I, ApoB, ApoC-III, and ApoE—using immunoassay, electrophoresis, chromatography, or mass spectrometry methods with analytical sensitivity requirements typically below 0.1 mg/dL. These assays quantify biomarkers that predict atherosclerotic cardiovascular disease risk more precisely than standard lipid panels alone. Immunoassay dominates routine clinical volume due to throughput and automation compatibility, while mass spectrometry occupies the premium reference-laboratory segment where analytical specificity commands higher reimbursement. Cardiovascular risk assessment anchors application demand, though diabetes management represents the fastest-growing clinical indication as diabetic dyslipidemia protocols expand apolipoprotein profiling.
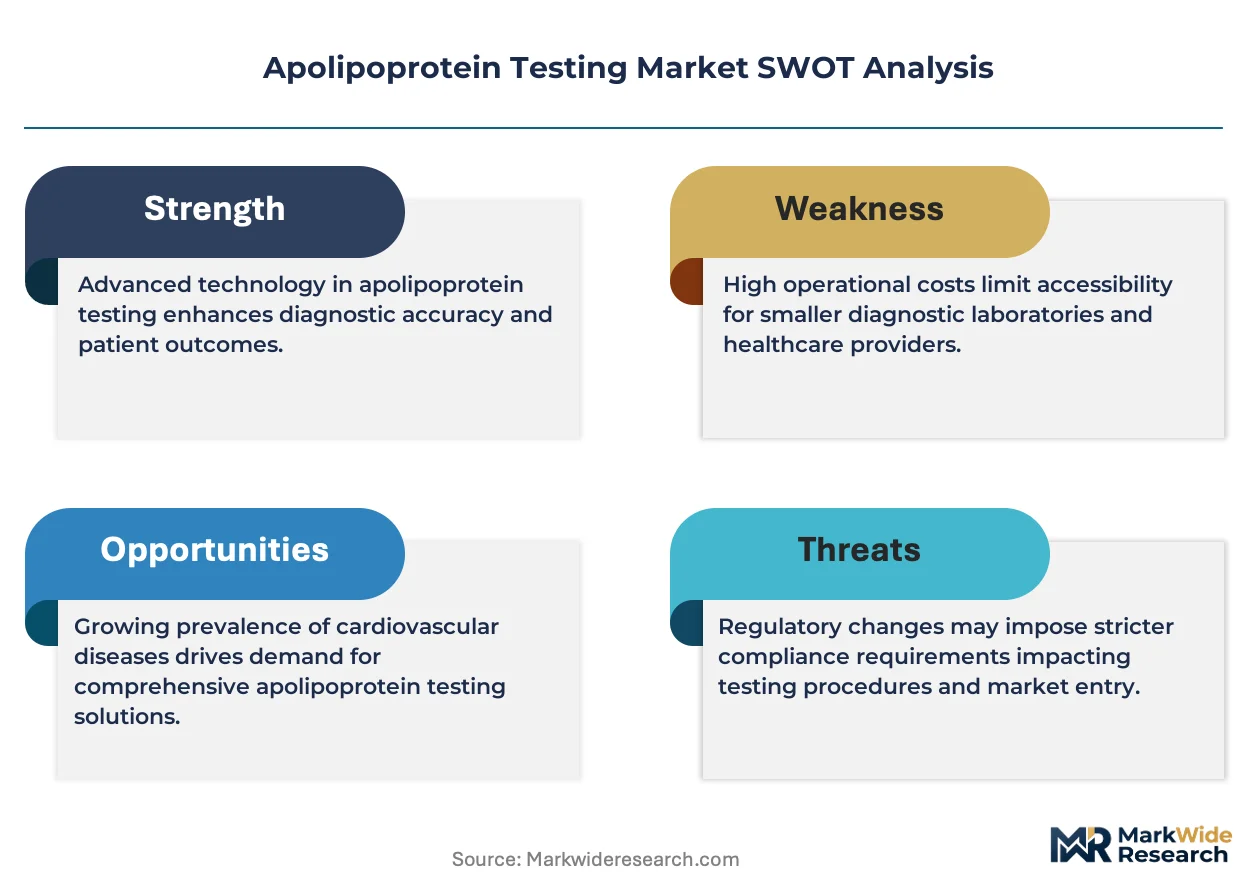
The US FDA regulates apolipoprotein assays as Class II medical devices under 21 CFR 862, requiring substantial equivalence demonstrations for new immunoassay platforms. The EU In Vitro Diagnostic Regulation imposes stricter clinical-evidence and post-market-surveillance obligations than its predecessor directive, elevating compliance costs for market entry. China's NMPA now mandates domestic clinical trials for imported IVD reagents, extending registration timelines. Stakeholders must monitor evolving payer-coverage decisions for ApoB/ApoA-I ratio testing as health technology assessments in Germany, England, and Japan recalibrate cardiovascular prevention guidelines.
Market Dynamics
The analytical performance tightening by the US FDA and EU IVDR is compressing competitive margins for immunoassay manufacturers while elevating reference-method laboratories that can demonstrate mass-spectrometry traceability. This regulatory divergence is forcing platform consolidation decisions across hospital core labs and commercial diagnostics chains.
Growth Catalysts
- Familial Hypercholesterolemia Screening Mandates:Germany's statutory health insurance now reimburses apolipoprotein profiling for cascade screening protocols, creating volume anchors for high-throughput immunoassay platforms in centralized laboratories.
- Diabetic Dyslipidemia Protocol Expansion:Endocrinology practices are integrating ApoB/ApoA-I ratio testing into diabetes management workflows as cardiovascular comorbidity protocols extend beyond standard lipid panels.
- Automated Immunoassay Architecture:Chemistry-analyzer compatibility investments by diagnostics manufacturers are reducing per-test labor costs and enabling 24-hour turnaround for emergency cardiovascular risk stratification.
Market Restraints
- EU IVDR Compliance Burden:The In Vitro Diagnostic Regulation's clinical-evidence and post-market-surveillance obligations are extending registration timelines and elevating fixed costs for reagent suppliers without established notified-body relationships.
- Reimbursement Uncertainty in England:NICE health technology assessments are recalibrating cardiovascular prevention guidelines, creating coverage volatility for ApoB/ApoA-I ratio testing that dampens capital-commitment confidence.
- Mass Spectrometry Capital Intensity:Reference-method laboratory certification requires seven-figure instrument investments and specialized technician training, constraining geographic accessibility for high-specificity testing.
Strategic Opportunities
- Point-of-Care Lipid Profiling:Miniaturized immunoassay platforms targeting physician office laboratories in Japan could capture cardiovascular risk assessment volume currently routed to hospital core labs.
- China NMPA Domestic Trial Pathway:The mandate for local clinical trials creates partnership opportunities for multinational diagnostics firms seeking to access the country's expanding hospital laboratory infrastructure.
- Pharmacogenomics Convergence:ApoE genotyping integration with protein quantification workflows opens precision-medicine positioning for statin response prediction in specialty reference laboratories.
Industry Challenges
- Cross-Platform Standardization Gaps:Immunoassay kit lot-to-lot variability across Abbott, Siemens, and Roche architectures complicates longitudinal patient monitoring and multi-site clinical trial data pooling.
- Mass Spectrometry Technician Scarcity:The specialized skill set required for LC-MS/MS method development and quality control limits reference-laboratory expansion velocity regardless of instrument availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Apolipoprotein Testing Market |
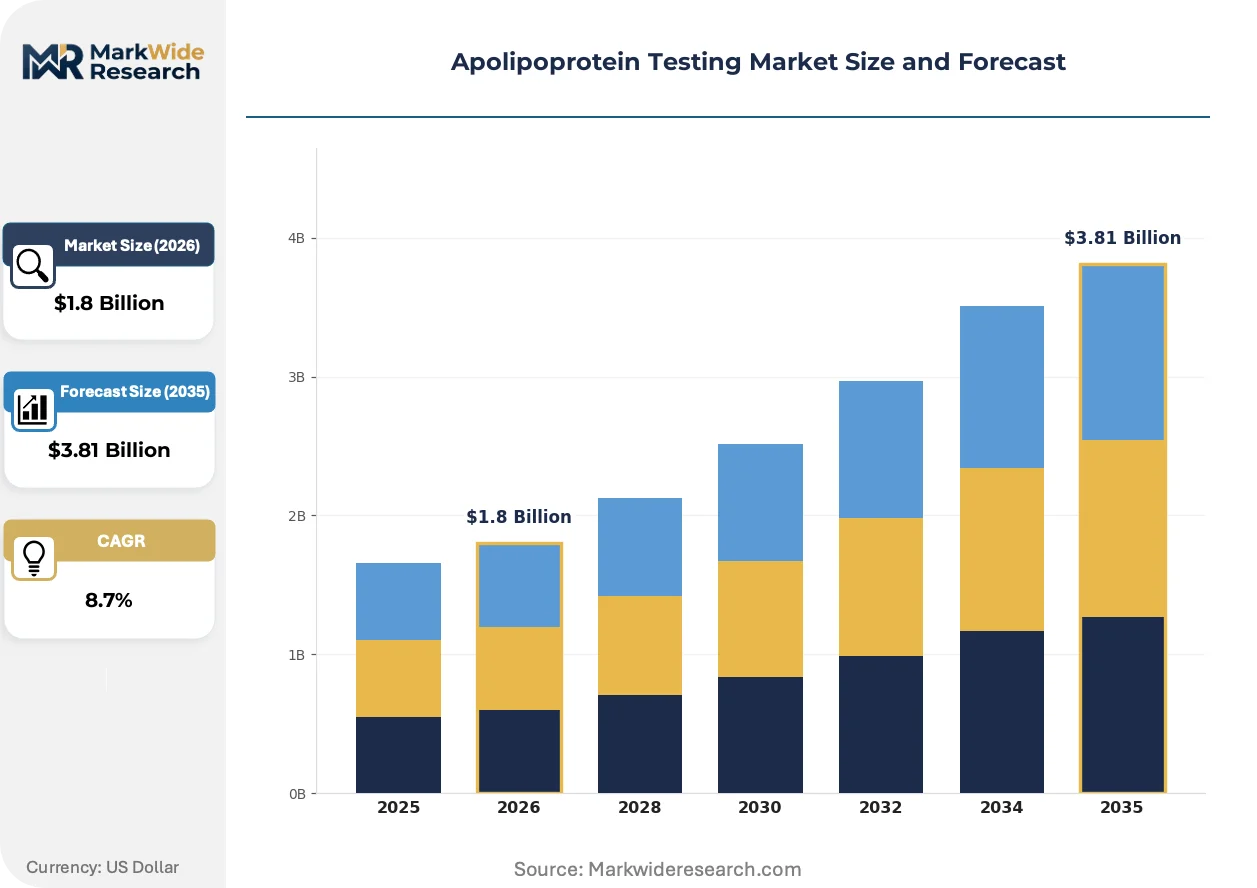
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ApoA-I, ApoB, ApoC-III, ApoE Test Method: Electrophoresis, Immunoassay, Chromatography, Mass Spectrometry Application: Cardiovascular Risk Assessment, Lipid Metabolism Disorders, Diabetes Management, Hepatic Disease Diagnosis End User: Hospitals, Diagnostic Laboratories, Research Institutions, Home Care Settings |
| Companies Covered | Abbott Laboratories, F. Hoffmann-La Roche Ltd, Siemens Healthineers, Thermo Fisher Scientific Inc, Bio-Rad Laboratories, Inc, Randox Laboratories Ltd, Quest Diagnostics Incorporated, DiaSorin S.p.A., Labcorp, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Apolipoprotein Testing Market Trends and Innovations
Multiplexed biomarker quantification and workflow miniaturization are converging to reshape competitive positioning across routine clinical and reference-laboratory segments. Platform manufacturers and reagent suppliers face divergent capital-allocation pressures.
Microfluidic immunoassay cartridges are integrating ApoA-I, ApoB, and ApoC-III detection onto single-use consumables with sub-microliter sample requirements. Point-of-care operators in cardiology clinics are piloting these systems for same-visit risk counseling. The technology is miniaturizing laboratory infrastructure requirements and compressing the addressable market for centralized high-throughput analyzers in community hospital settings.
The EU IVDR's stricter clinical-evidence requirements are elevating post-market surveillance obligations for Class C IVD devices. Manufacturers must now maintain systematic performance data collection across installed bases. Reagent suppliers without robust quality-management systems are exiting the European market, consolidating share among platform-integrated players with dedicated regulatory affairs functions.
Hospital procurement committees are unbundling reagent contracts from instrument placement agreements, forcing standalone pricing transparency for immunoassay consumables. Group purchasing organizations in the United States are aggregating cardiovascular panel volumes across health system networks. This behavioral shift is most visible in integrated delivery networks where laboratory directors now negotiate spot-market pricing for high-volume apolipoprotein tests rather than accepting bundled chemistry-menu terms.
Apolipoprotein Testing Market Segmentation
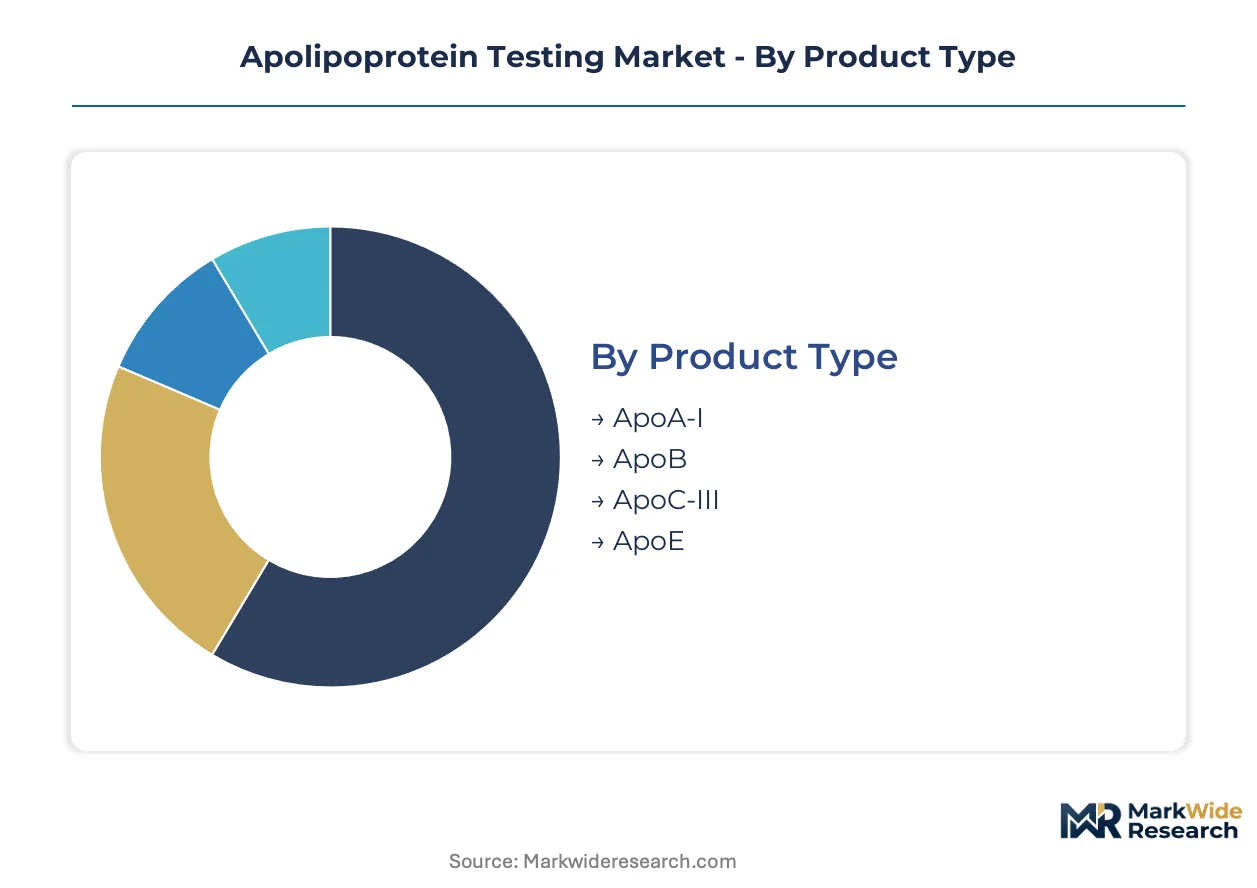
Apolipoprotein testing segmentation reveals divergent competitive dynamics across analytical platforms and clinical settings. Regulatory frameworks from the US FDA and EU IVDR impose distinct compliance burdens that reshape segment economics and technology adoption patterns.
Product Type:
Regulatory differentiation in analytical performance standards favors certain biomarkers over others in reimbursement decisions.
- ApoA-I:This high-density lipoprotein structural protein quantifies reverse cholesterol transport capacity. German statutory health insurance reimbursement for familial hypercholesterolemia screening concentrates demand in centralized laboratories performing cascade protocols.
- ApoB:Atherogenic lipoprotein particle count indicator with superior cardiovascular risk prediction versus LDL-C alone. The ApoB/ApoA-I ratio is gaining protocol inclusion in diabetes management workflows across endocrinology practices.
- ApoC-III:Triglyceride metabolism regulator increasingly profiled in hepatic steatosis assessment.
- ApoE:Lipoprotein remnant clearance mediator with emerging pharmacogenomics applications for statin response prediction.
ApoB handles the majority of throughput in high-volume cardiovascular panels; ApoE is gaining share fastest through precision medicine convergence.
Test Method:
Capital requirements and technician specialization create tiered accessibility across laboratory types.
- Immunoassay:Automated platform chemistry with throughput exceeding 1,000 tests per hour on core laboratory analyzers. Abbott, Siemens, and Roche architectures dominate hospital procurement in the United States and Germany through installed base leverage.
- Mass Spectrometry:Liquid chromatography-tandem mass spectrometry delivers reference-method specificity with traceability to primary standards. Seven-figure instrument investments and LC-MS/MS technician scarcity constrain geographic expansion regardless of analytical superiority.
- Electrophoresis:Labor-intensive separation technique retreating to niche confirmatory applications.
- Chromatography:High-performance liquid chromatography methods persist in specialized lipid reference laboratories.
Immunoassay commands the dominant share of clinical test volume; mass spectrometry is expanding most quickly in certified reference-method networks.
Application:
Clinical guideline evolution and comorbidity protocol expansion are redistributing demand across indication areas.
- Cardiovascular Risk Assessment:Primary indication anchoring reimbursement codes and laboratory menu placement. NICE health technology assessments in England and preventive cardiology guidelines in Japan determine coverage volatility for advanced lipid profiling.
- Diabetes Management:Diabetic dyslipidemia protocol expansion integrates ApoB/ApoA-I ratio testing beyond standard lipid panels. Endocrinology practices represent the steepest expansion trajectory as cardiovascular comorbidity protocols tighten glycemic control targets.
- Lipid Metabolism Disorders:Familial hypercholesterolemia and rare dyslipidemia diagnosis in specialty referral centers.
- Hepatic Disease Diagnosis:Non-alcoholic fatty liver disease staging through apolipoprotein profiling in hepatology clinics.
Cardiovascular risk assessment maintains the installed base anchor; diabetes management is climbing the fastest on clinical protocol adoption.
End User:
Procurement centralization and point-of-care miniaturization are bifurcating customer economics.
- Diagnostic Laboratories:High-throughput immunoassay platforms in commercial diagnostics chains and hospital core laboratories. Group purchasing organizations in United States integrated delivery networks now negotiate spot-market pricing for cardiovascular panel volumes.
- Hospitals:Emergency department turnaround requirements and 24-hour stat testing capabilities. Chemistry-analyzer compatibility investments reduce per-test labor costs for cardiovascular risk stratification.
- Research Institutions:Mass spectrometry reference-method development and clinical trial biomarker standardization.
- Home Care Settings:Nascent microfluidic cartridge pilots in cardiology clinic point-of-care configurations.
Diagnostic laboratories process the dominant share of reimbursable test volume; home care settings represent the fastest-moving frontier on miniaturization pilots.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates apolipoprotein testing volume through familial hypercholesterolemia screening mandates, while Japan and the United States diverge toward point-of-care miniaturization and reference-method laboratory networks respectively.
United States
Hospital core laboratories anchor immunoassay throughput for cardiovascular risk panels, with emergency department stat testing driving 24-hour turnaround requirements. The FDA regulates apolipoprotein assays as Class II medical devices under 21 CFR 862, tightening analytical performance demonstrations for new platform clearances. Greater Boston hosts reference-method laboratory clusters where mass spectrometry traceability commands premium reimbursement.
Germany
Statutory health insurance reimbursement for familial hypercholesterolemia cascade screening concentrates demand in centralized diagnostic laboratories. The EU IVDR imposes stricter clinical-evidence obligations than its predecessor directive, elevating compliance costs for reagent suppliers. Bavaria's hospital networks are unbundling reagent contracts from instrument placements, forcing standalone pricing transparency for cardiovascular panel volumes.
Japan
Endocrinology practices integrate ApoB/ApoA-I ratio testing into diabetic dyslipidemia protocols beyond standard lipid panels. METI oversees in vitro diagnostic regulatory frameworks as PMDA reviews clinical evidence for expanded biomarker claims. The Kanto region around Tokyo pilots microfluidic cartridge systems in cardiology clinics for same-visit risk counseling.
China
Hospital laboratory infrastructure expansion creates volume anchors for automated immunoassay platforms in tier-one cities. The NMPA mandates domestic clinical trials for imported IVD reagents, extending registration timelines for multinational diagnostics firms. The Yangtze River Delta concentrates commercial diagnostics chain consolidation as procurement centralization accelerates.
United Kingdom
NICE health technology assessments recalibrate cardiovascular prevention guidelines, generating coverage volatility for advanced lipid profiling. The NHS England commissioning framework creates uncertainty for ApoB/ApoA-I ratio testing reimbursement that dampens capital-commitment confidence. London's integrated delivery networks negotiate spot-market pricing for cardiovascular panel volumes across health system networks.
Apolipoprotein Testing Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in apolipoprotein testing, with platform manufacturers leveraging installed base economics against boutique reagent suppliers. The capital-intensity divergence between fully automated chemistry-analyzer architectures and mass spectrometry reference methods is bifurcating competitive dynamics. Strategic archetypes include integrated diagnostics conglomerates with hospital core laboratory relationships, precision reference laboratory specialists, and point-of-care miniaturization entrants. Dominant competitive moves center on chemistry-analyzer compatibility investments and regulatory compliance infrastructure expansion.
Among integrated diagnostics conglomerates, Abbott Laboratories and Siemens Healthineers occupy positions defined by installed base leverage across hospital core laboratory networks. Thermo Fisher Scientific exemplifies the reference-method specialist archetype, anchoring mass spectrometry workflow standardization for certified laboratories. These three entities represent distinct competitive vectors: platform-integrated throughput dominance, analyzer compatibility breadth, and analytical specificity premium positioning respectively.
| Leading Market Players |
|---|
| Abbott Laboratories |
| F. Hoffmann-La Roche Ltd |
| Siemens Healthineers |
| Thermo Fisher Scientific Inc |
| Bio-Rad Laboratories, Inc |
| Randox Laboratories Ltd |
| Quest Diagnostics Incorporated |
| DiaSorin S.p.A. |
| Labcorp |
| Others |
Pricing and Supply Chain Analysis
Long-term reagent supply contracts with instrument placement agreements lock in both consumable access and predictable per-test costs for hospital core laboratories negotiating cardiovascular panel pricing. This bundled contracting structure concentrates purchasing leverage among integrated delivery networks while squeezing standalone reagent suppliers into spot-market competition.
Pricing Analysis
After-sales consumable revenue from immunoassay reagent kits drives lifetime value for platform manufacturers, with per-test pricing stratifying across premium mass-spectrometry reference methods, standard automated immunoassay menus, and economy-tier electrophoresis alternatives. Price differentiation hinges on analytical specificity certification and throughput scale, with reference-method laboratories commanding premium reimbursement while high-volume hospital labs negotiate volume discounts. Pricing pressure stems from group purchasing organization aggregation of cardiovascular panel volumes across health system networks. Research institutions exhibit lowest price sensitivity due to grant-funded biomarker standardization requirements; community hospitals face highest sensitivity from bundled chemistry-menu procurement constraints.
Supply Chain Analysis
Monoclonal antibody production for immunoassay reagents concentrates in the United States, Germany, and China, creating single-source vulnerability for specialized ApoB and ApoE detection antibodies. Raw material dependencies include recombinant protein expression systems, chromatography resins, and mass spectrometry calibration standards. Supply chain risk centers on EU IVDR regulatory restriction extending reagent registration timelines and compressing supplier margins. Distribution runs through diagnostic equipment distributors and direct hospital procurement channels, with commercial diagnostics chains consolidating regional volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-integrated conglomerates and boutique reagent suppliers fragment competitive positioning, with point-of-care miniaturization and pharmacogenomics convergence creating service-layer niches for specialized entrants.
For Market Incumbents: Secure chemistry-analyzer compatibility certifications across Abbott, Siemens, and Roche architectures to defend installed base relationships against emerging mass-spectrometry reference laboratories. Deepen regulatory affairs infrastructure to navigate EU IVDR post-market surveillance obligations and compress registration timelines relative to reagent-only competitors. For New Entrants and Emerging Players: Pharmacogenomics workflow integration represents the most penetrable white-space target, with ApoE genotyping plus protein quantification services under-served by routine clinical laboratories. Target specialty reference laboratories in the Kanto region of Japan with statin response prediction protocols as the go-to-market angle. For Investors and Strategic Acquirers: Capital is best deployed toward precision reference laboratory specialists with mass spectrometry traceability certification and established payer relationships for premium reimbursement. Long-term viability rests on analytical specificity differentiation as regulatory tightening compresses immunoassay margins. Watch NICE health technology assessment recalibrations in England as the inflection signal for ApoB/ApoA-I ratio coverage expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EU IVDR Compliance Infrastructure Expansion | Accelerates market access for Class C IVD devices against competitors lacking notified-body relationships. |
| Mass Spectrometry Reference Method Certification | Commands premium reimbursement from Medicare and statutory health insurers in Germany. |
| Microfluidic Cartridge Miniaturization | Captures point-of-care volume in Japanese cardiology clinics currently routed to hospital core laboratories. |
| Pharmacogenomics Workflow Convergence | Opens precision medicine positioning for statin response prediction in specialty reference laboratories. |
| Group Purchasing Organization Volume Aggregation | Consolidates cardiovascular panel procurement leverage across United States integrated delivery networks. |
Research Methodology
Initial hypotheses were tested against primary input from clinical laboratory directors, hospital procurement managers, regulatory affairs specialists at IVD manufacturers, and reference method scientists, then refined against secondary validation from FDA 510(k) filings, EU IVDR technical documentation, CMS Medicare reimbursement databases, and hospital GPO contract records. Bottom-up test volume modeling triangulated with top-down market sizing across immunoassay, mass spectrometry, electrophoresis, and chromatography platform segments.
Variance decomposition across product type, test method, clinical application, and end-user setting informed the analytical framework over the projection horizon. CAGRs derived from instrument placement trajectories, reagent consumption curves, and reimbursement code evolution. Forecast inputs included EU IVDR registration timeline assumptions and NICE health technology assessment schedule recalibrations.
Forecasts assume regulatory continuity in FDA Class II device pathways and EU IVDR notified-body capacity; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Staphylococcus Aureus Testing Market
Testing Services
Drug Testing Systems Market
Testing Services
Irradiation Sterilization Services Market
Testing Services
Procalcitonin Reagent Test Kit Market
Testing Services
Arthropod-Borne Viral Infections Testing Market
Testing Services
D-Dimer Testing Market
Testing Services
Testing and Analysis Services Market
Testing Services
Mycological Testing Market
Testing Services
Global Anti Thrombin III Testing Market
Testing Services
Human Papilloma Virus Testing Market
Testing Services
Arbovirus Testing Market
Testing Services
Home DNA Testing Market
Testing Services
Pharmaceutical Dissolution Testing Services Market
Testing Services
Pharmaceutical Sterility Testing Market
Testing Services
Autoimmune Disease Testing Market
Testing Services
Biological Indicator Vials Market