
 Acute Lymphoblastic Leukemia Market | 2026-2036
Acute Lymphoblastic Leukemia Market Size, Share, and Industry Trends Forecast 2026-2036
Acute Lymphoblastic Leukemia Market Analysis
US biopharmaceutical manufacturing capacity is repositioning toward cell therapy production to meet rising demand for personalized leukemia treatments. Novartis leverages its FDA-approved CAR-T infrastructure to sustain leadership in relapsed pediatric cases. Pfizer anchors its portfolio through bispecific antibody platforms that compete across adult and pediatric lines. Bristol-Myers Squibb differentiates via integrated oncology networks that control access to combination regimens.
Acute lymphoblastic leukemia is a malignant hematologic disorder characterized by uncontrolled proliferation of immature lymphoid progenitor cells, typically defined by bone marrow involvement exceeding 20% blast cells and requiring multi-agent induction chemotherapy for remission. Its primary purpose centers on achieving durable disease-free survival through risk-stratified protocols that balance cytotoxic intensity against toxicity profiles. Immunotherapy now leads product type expansion as CAR-T and bispecific constructs capture the fastest-growing margin pools, while chemotherapy sustains volume dominance in frontline induction across both pediatric and adult therapy areas. Hospital end users concentrate the highest-value procedures, though homecare settings are gaining share for oral maintenance phases.
FDA breakthrough therapy designation and EMA PRIME eligibility are compressing development timelines for novel biologics, while WHO essential medicines criteria shape access negotiations in lower-income settings. The EU AI Act introduces compliance burdens for algorithm-driven diagnostic tools that stratify leukemia risk, potentially fragmenting digital health vendor participation. Stakeholders must monitor how reimbursement authorities in Germany and Japan calibrate value assessments for curative-intent therapies against maintenance regimens.
Market Dynamics
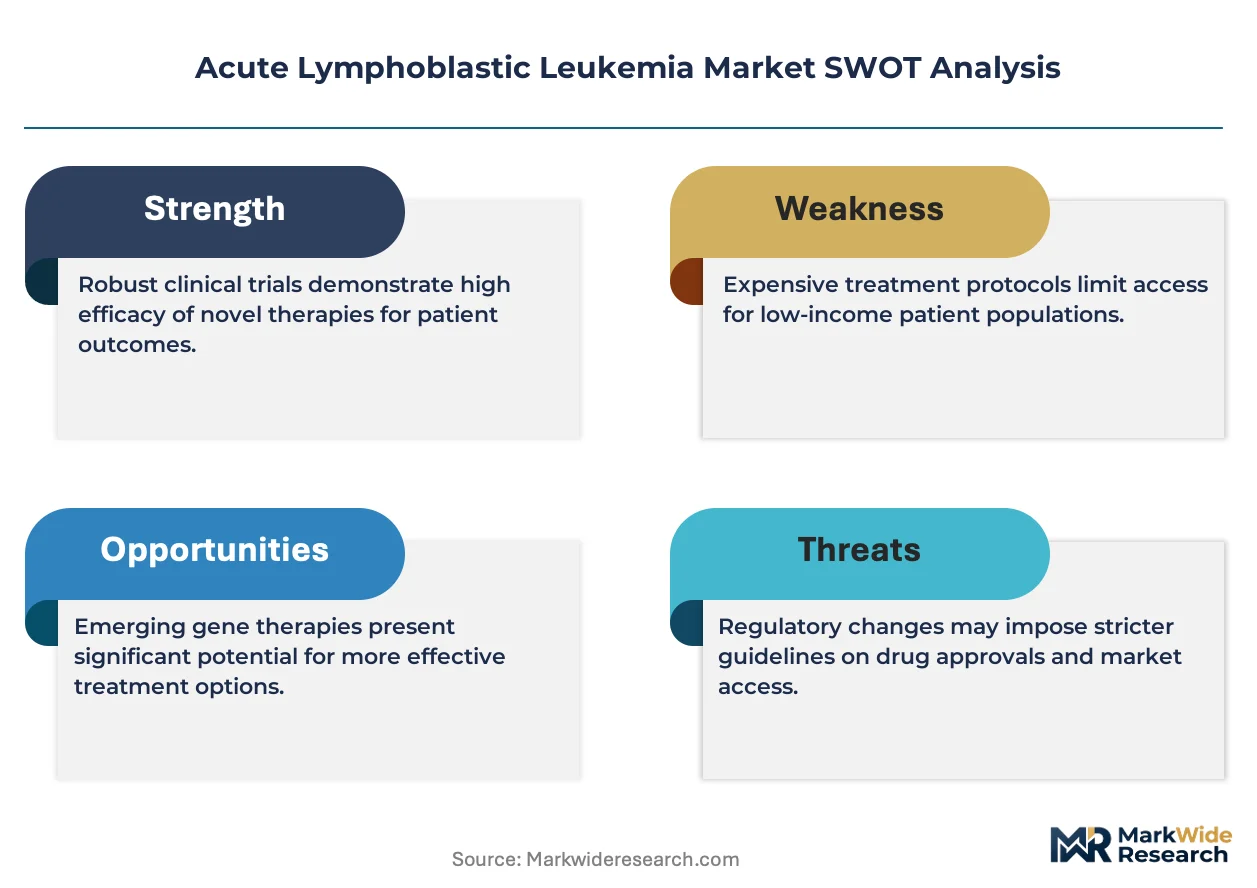
FDA breakthrough therapy designations and EMA PRIME eligibility are compressing development timelines for novel biologics, while hospital-based oncology departments reposition manufacturing capacity toward cell therapy production to capture premium immuno-oncology margins.
Growth Catalysts
- Accelerated approval frameworks:FDA breakthrough therapy and EMA PRIME pathways compress clinical development timelines for CAR-T and bispecific antibody candidates. Pediatric and adult oncology units prioritize these designations when allocating formulary slots.
- Cell therapy manufacturing infrastructure:Hospital-based oncology departments are scaling in-house production capabilities for personalized leukemia treatments. This expansion reduces cold-chain logistics burden and shortens vein-to-vein treatment intervals.
- Reimbursement favoring curative intent:German and Japanese health technology assessment bodies are recalibrating value frameworks to reward durable remission over chronic maintenance. This shift redirects R&D investment toward single-administration modalities.
Market Restraints
- Viral vector supply concentration:Lentiviral and retroviral vector production concentrates among a limited set of contract manufacturers. Yield variability and batch failure rates create bottlenecks for autologous cell therapy scale-up.
- Cytokine release syndrome management costs:Intensive care unit capacity requirements for CAR-T toxicity monitoring inflate total treatment costs. Payers in lower-income settings struggle to absorb these ancillary expenditures.
- Allogeneic CAR-T substitution threat:Off-the-shelf cell therapy platforms promise manufacturing standardization and reduced logistics complexity. Autologous product developers face margin compression if allogeneic candidates demonstrate comparable durability.
Strategic Opportunities
- Maintenance phase homecare transition:Oral tyrosine kinase inhibitors and minimal residual disease monitoring enable therapy administration outside hospital settings. Homecare providers in the United States and Germany are building oncology-certified nursing networks to capture this volume.
- Algorithm-driven risk stratification:Machine learning tools integrating genomic, immunophenotypic, and minimal residual disease data are refining relapse prediction. The EU AI Act creates compliance requirements that favor established diagnostic vendors with regulatory affairs capabilities.
- Pediatric-adult indication expansion:Biologics approved for relapsed pediatric ALL are migrating into young adult protocols through basket trial designs. Academic medical centers with dual pediatric-adult oncology departments control access to these crossover populations.
Industry Challenges
- Cell therapy workforce scarcity:GMP-compliant manufacturing technicians and apheresis specialists command premium compensation. Training program throughput limits expansion at contract development and manufacturing organizations.
- Legacy chemotherapy integration complexity:Novel immunotherapies require protocol redesign to optimize sequencing with established induction regimens. Cooperative oncology groups face coordination costs when harmonizing trial amendments across multiple institutional review boards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acute Lymphoblastic Leukemia Market |
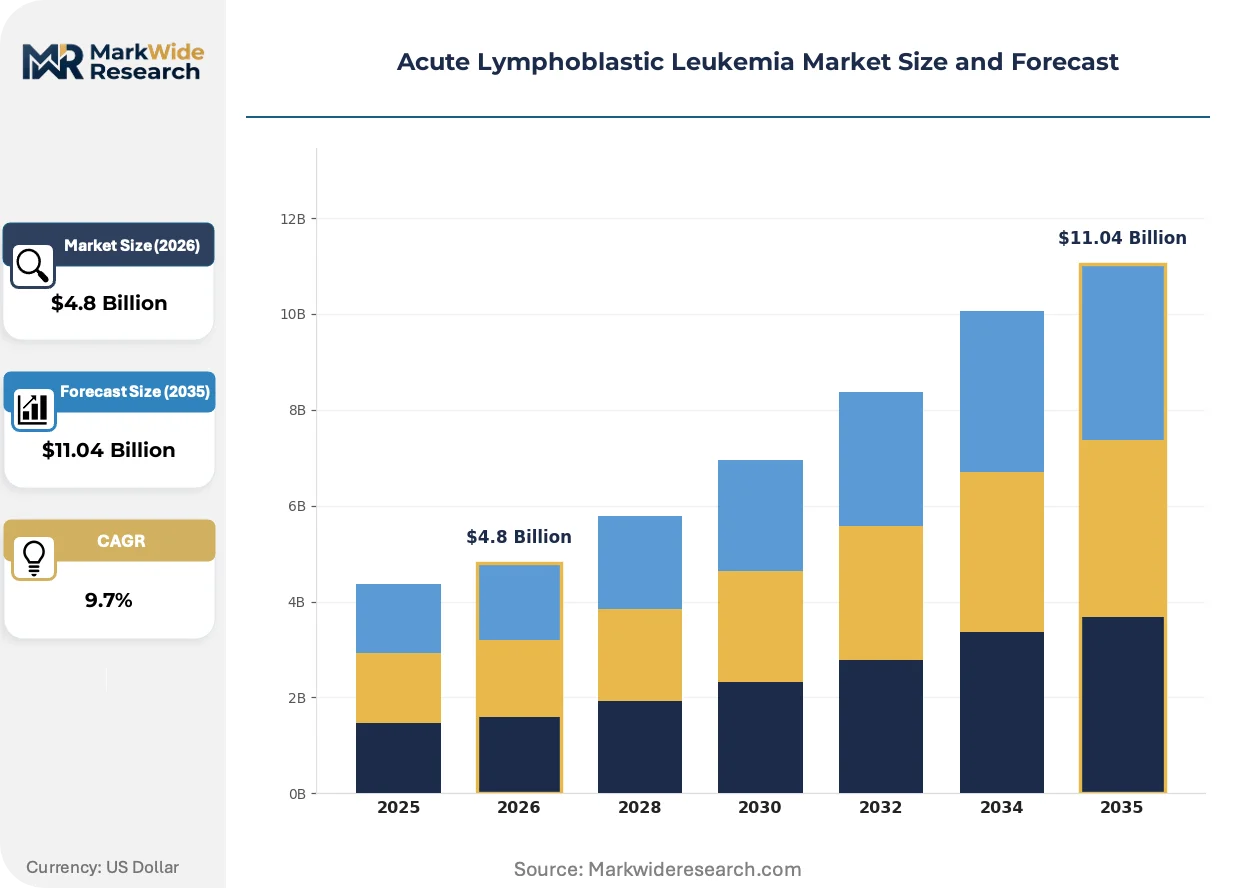
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Immunotherapy, Targeted Therapy, Stem Cell Transplantation End User: Hospitals, Clinics, Research Laboratories, Homecare Settings Delivery Mode: Intravenous, Oral, Subcutaneous, Intramuscular Therapy Area: Pediatric, Adult, Recurrent, Maintenance |
| Companies Covered | Novartis AG, Pfizer Inc., Amgen Inc., Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd, Gilead Sciences, Sanofi, Takeda Pharmaceutical Company, Jazz Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acute Lymphoblastic Leukemia Market Emerging Trajectories
Next-generation sequencing and real-world evidence platforms are compressing biomarker discovery timelines, while regulatory agencies adapt evidentiary standards to accommodate single-arm trials for rare hematologic malignancies.
Next-generation sequencing-based minimal residual disease monitoring is automating relapse detection at thresholds below morphologic assessment capability. Hospital laboratories in Germany and Japan are adopting clonoSEQ and equivalent platforms for routine surveillance. This automation is compressing the interval between molecular relapse and therapeutic intervention, shifting competitive advantage toward agents with rapid manufacturing turnaround.
The EU AI Act introduces conformity assessment requirements for algorithm-driven diagnostic tools that stratify leukemia risk. Vendors must demonstrate algorithmic transparency and bias mitigation to maintain market access in European Economic Area jurisdictions. Pediatric oncology networks are most affected, as they rely heavily on risk-stratification algorithms to allocate patients to standard versus intensified treatment arms.
Hospital procurement committees are consolidating supplier relationships for CAR-T and bispecific products into single-source or dual-source arrangements. Academic medical centers with integrated pharmacy and therapeutics committees are extracting volume-based discounts in exchange for formulary exclusivity. This concentration is most visible in the United States, where pharmacy benefit managers are extending oncology-specific contracting models into hospital outpatient settings.
Acute Lymphoblastic Leukemia Market Segmentation
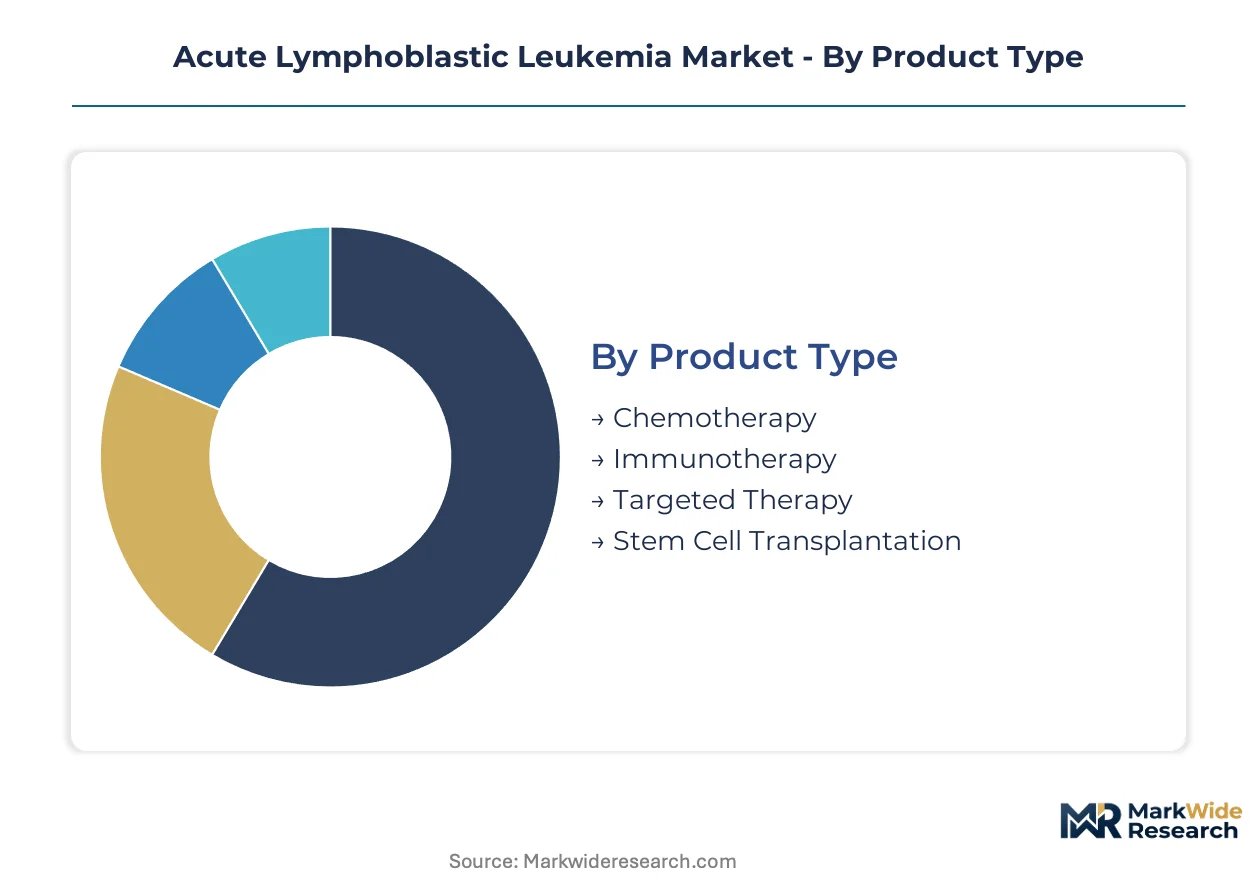
Acute lymphoblastic leukemia treatment modalities span distinct technical and commercial ecosystems, each commanding different manufacturing capabilities, reimbursement pathways, and clinical infrastructure requirements. Segmentation reveals where value concentrates across curative versus chronic management paradigms.
Product Type:
Integration depth varies sharply: chemotherapy operates as embedded infrastructure across all treatment lines, while immunotherapy and targeted agents function as standalone premium interventions requiring specialized manufacturing and administration protocols.
- Chemotherapy:Multi-agent cytotoxic regimens comprising vincristine, corticosteroids, and anthracyclines form the backbone of induction protocols. Demand concentrates in frontline pediatric and adult protocols across hospital-based oncology departments in the United States and Germany, where established reimbursement codes sustain volume dominance despite toxicity burdens.
- Immunotherapy:CAR-T cell therapies and bispecific antibodies represent engineered biological modalities requiring apheresis collection, viral vector transduction, and expansion protocols. Manufacturing capacity constraints in lentiviral vector supply create bottlenecks for autologous products, concentrating highest-value procedures at academic medical centers with integrated cell processing facilities.
- Targeted Therapy:Tyrosine kinase inhibitors and monoclonal antibodies directed at specific molecular aberrations.
- Stem Cell Transplantation:Allogeneic and autologous hematopoietic stem cell rescue following myeloablative conditioning.
Chemotherapy leads volumes today; immunotherapy is gaining share fastest.
End User:
Cost tier stratification separates high-acuity intervention sites from maintenance-phase delivery channels, with reimbursement differentials driving patient migration across settings.
- Hospitals:Academic medical centers and tertiary care facilities administer induction chemotherapy, CAR-T infusion, and stem cell transplantation under intensive monitoring protocols. These sites command premium reimbursement for inpatient stays and complex procedures, particularly in Japan where hospital-based oncology dominates regulatory approval pathways.
- Clinics:Community oncology practices and ambulatory infusion centers deliver maintenance chemotherapy and supportive care. These settings capture volume from stabilized patients seeking geographic convenience, though they lack CAR-T administration capabilities.
- Research Laboratories:Centralized reference laboratories perform minimal residual disease monitoring and pharmacogenomic testing.
- Homecare Settings:Oral maintenance therapy administration and nursing support for post-treatment surveillance.
Hospitals lead volumes today; homecare settings are gaining share fastest.
Delivery Mode:
Application context determines route selection: inpatient acute interventions favor parenteral administration, while outpatient maintenance shifts toward patient-administered oral regimens.
- Intravenous:Continuous infusion and bolus delivery of cytotoxic agents, monoclonal antibodies, and CAR-T cell products. This route dominates induction and consolidation phases across pediatric and adult protocols, requiring central venous access and infusion center capacity that concentrates in urban hospital clusters.
- Oral:Tyrosine kinase inhibitors, corticosteroids, and maintenance chemotherapy agents in tablet or liquid formulations. Patient preference and cost containment pressures in German statutory health insurance are accelerating formulary expansion for oral equivalents of previously intravenous drugs.
- Subcutaneous:Interferon and supportive growth factor administration.
- Intramuscular:Limited applications for specific supportive care agents.
Intravenous leads volumes today; oral is gaining share fastest.
Therapy Area:
Patient population maturity shapes protocol design: pediatric frameworks emphasize curative intensity with long-term toxicity monitoring, while adult and recurrent segments prioritize bridging to transplantation or novel modality access.
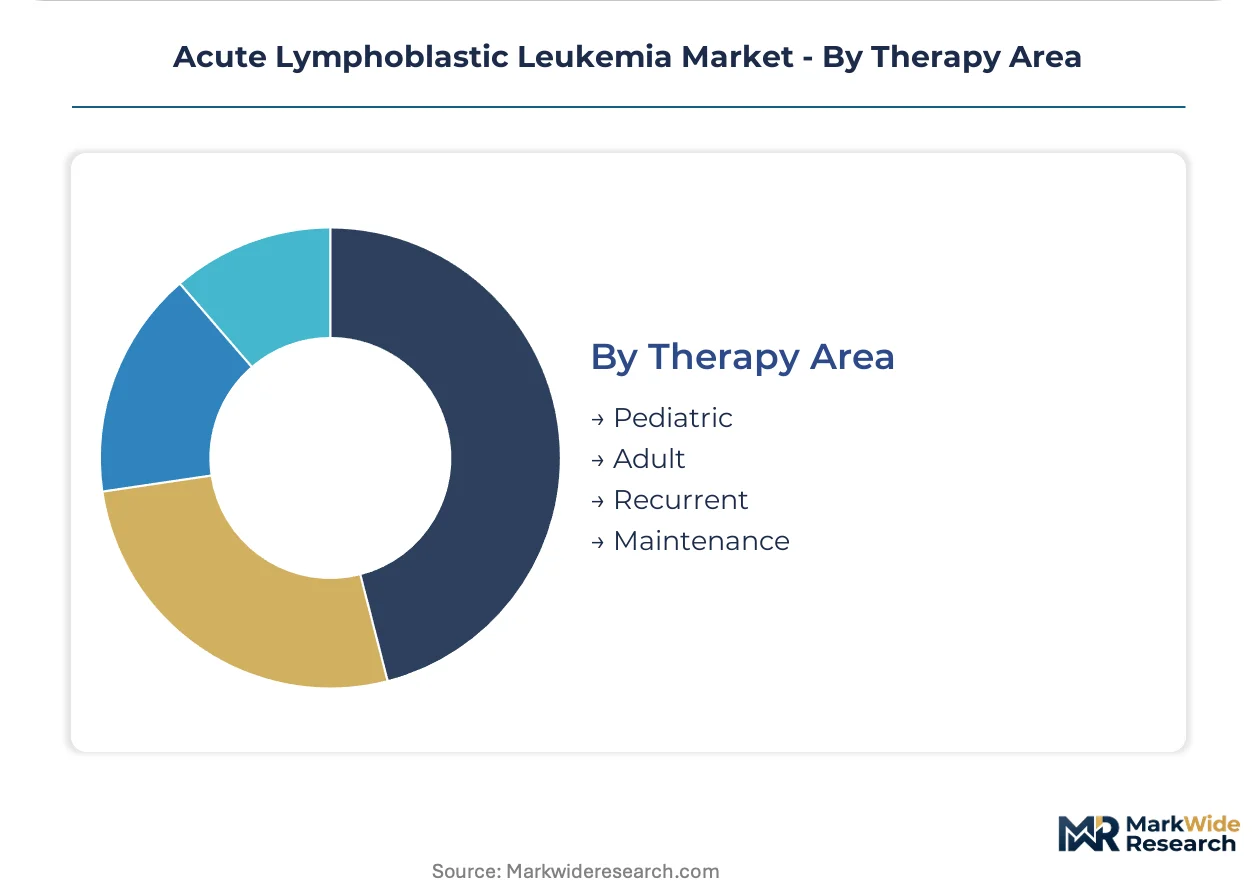
- Pediatric:Risk-stratified multi-agent protocols for patients under 18 years, with five-year event-free survival exceeding 85% in standard-risk cohorts. Cooperative oncology groups in the United States and Europe drive protocol harmonization, creating concentrated demand for age-appropriate formulations and long-term survivorship services.
- Adult:Philadelphia chromosome-positive and negative subtypes requiring distinct therapeutic approaches, with inferior outcomes driving Philadelphia-positive patients toward tyrosine kinase inhibitor combinations and transplantation referral.
- Recurrent:Salvage regimens for first or subsequent relapse, where CAR-T and bispecific antibodies are displacing chemotherapy-only approaches.
- Maintenance:Prolonged low-intensity therapy to sustain remission following consolidation.
Pediatric leads volumes today; recurrent is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping cell therapy production location decisions, with manufacturers gravitating toward jurisdictions where FDA and EMA accelerated pathways compress approval timelines while reimbursement frameworks absorb premium pricing for curative-intent modalities.
United States
FDA breakthrough therapy designations and orphan drug exclusivity anchor Novartis and Bristol-Myers Squibb manufacturing investments. The 21st Century Cures Act provisions sustain rapid commercialization for CAR-T platforms. Boston-Cambridge and San Diego biotech clusters concentrate viral vector production and apheresis processing capacity.
Germany
G-BA value assessments for blinatumomab and tisagenlecleucel establish European pricing benchmarks for bispecific and cell therapy modalities. EMA centralized procedures enable simultaneous market access across member states. Heidelberg and Munich academic medical centers operate integrated GMP facilities for autologous cell processing.
Japan
PMDA sakigake designation accelerates review timelines for pediatric ALL innovations, aligning with METI industrial policy for regenerative medicine commercialization. National health insurance price premiums for curative therapies sustain manufacturer margins. Tokyo and Osaka hospital networks control patient referral pathways for CAR-T eligible populations.
United Kingdom
NICE technology appraisals for CAR-T products establish cost-effectiveness thresholds that filter market entry. MHRA post-Brexit recognition pathways maintain EMA-aligned standards while enabling independent approval velocity. London and Manchester cellular therapy hubs coordinate NHS England specialized commissioning for tertiary leukemia services.
Switzerland
Swissmedic parallel review procedures with EMA compress time-to-market for hematologic oncology biologics. Federal health insurance mandatory benefit catalog inclusion decisions determine commercial viability. Basel and Zurich pharmaceutical manufacturing corridors host contract development organizations serving European cell therapy sponsors.
Acute Lymphoblastic Leukemia Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue allogeneic platform substitution and algorithm-driven patient stratification. Market structure concentrates around three archetypes: integrated biopharmaceutical conglomerates with cell therapy infrastructure, mid-cap immuno-oncology specialists, and contract manufacturing organizations capturing viral vector supply bottlenecks. Dominant competitive moves include horizontal consolidation to secure GMP manufacturing capacity and strategic partnerships with academic medical centers to control patient access.
Within the integrated conglomerate tier, Novartis AG and Pfizer Inc. exemplify divergent positioning strategies. Novartis anchors the autologous CAR-T segment through FDA-approved pediatric infrastructure. Pfizer occupies the bispecific antibody vector with platform investments spanning adult and pediatric indications. Bristol-Myers Squibb sits within the network-control archetype, leveraging integrated oncology delivery systems to manage combination regimen access.
| Leading Market Players |
|---|
| Novartis AG |
| Pfizer Inc. |
| Amgen Inc. |
| Bristol-Myers Squibb Company |
| F. Hoffmann-La Roche Ltd |
| Gilead Sciences |
| Sanofi |
| Takeda Pharmaceutical Company |
| Jazz Pharmaceuticals |
| Others |
Supply Flow & Price Mechanics
Autologous CAR-T manufacturing scale-up simultaneously compresses per-patient production costs and concentrates supply leverage among academic medical centers with captive GMP facilities. This dual effect reshapes how viral vector pricing power flows through to hospital procurement committees and payer reimbursement negotiations across the United States, Germany, and Japan.
Pricing Analysis
Hospital procurement committee consolidation extracts volume-based discounts from CAR-T and bispecific antibody suppliers in exchange for formulary exclusivity. Three-tier pricing structure across premium, standard, and economy levels separates innovator biologics from biosimilar candidates and generic chemotherapy backbones. Pricing pressure stems from allogeneic CAR-T platform development promising manufacturing standardization. Pediatric oncology networks demonstrate highest price sensitivity due to constrained reimbursement budgets, while adult relapsed segments absorb premium pricing for curative-intent therapies.
Supply Chain Analysis
FDA and EMA GMP certification requirements gate viral vector production to a limited contract manufacturing base in the United States, Switzerland, and Germany. Lentiviral vector supply draws from specialized bioreactor capacity and plasmid DNA feedstocks. Single-source vulnerability concentrates in gamma-retroviral vector production for early-generation CAR-T platforms. Distribution runs through hospital-based pharmacy and therapeutics committees controlling cold-chain logistics for patient-specific cell products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Acute Lymphoblastic Leukemia Market functions as a stable compounder anchored by durable biological innovation cycles and indication expansion across pediatric-adult boundaries. FDA breakthrough therapy designations and EMA PRIME eligibility sustain predictable commercialization timelines for novel modalities.
For Market Incumbents: Cement manufacturing capacity advantages through backward integration into viral vector production and apheresis processing infrastructure. Secure exclusive supply agreements with academic medical centers controlling patient referral pathways for CAR-T eligible populations. The allogeneic CAR-T substitution threat demands defensive patent estate expansion around manufacturing process trade secrets.
For New Entrants and Emerging Players: The pricing gap between premium autologous CAR-T and economy-tier chemotherapy maintenance creates white-space opportunity for oral tyrosine kinase inhibitor platforms in minimal residual disease positive surveillance settings. Target homecare-certified nursing networks in Germany and the United States for maintenance phase volume capture. Pursue algorithm-driven risk stratification partnerships with pediatric cooperative oncology groups to secure protocol amendment influence.
For Investors and Strategic Acquirers: Valuations sit cheapest among mid-cap bispecific antibody developers with pediatric indication expansion potential and established EMA regulatory affairs capabilities. The five-to-ten year viability window favors platforms demonstrating durability in Philadelphia chromosome-positive adult populations. Watch FDA allogeneic CAR-T approval velocity as the inflection signal for autologous product margin compression.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Basket trial designs accelerate pediatric-to-adult indication migration for approved biologics. |
| Regulatory Approval Pathway | FDA breakthrough therapy designation compresses development timelines for CAR-T candidates. |
| Manufacturing Scale-Up | In-house GMP facilities reduce vein-to-vein intervals and cold-chain logistics burden. |
| Pipeline Diversification | Bispecific antibody platforms hedge against allogeneic CAR-T substitution risk. |
| Strategic Partnership | Academic medical center alliances control patient access to combination regimens. |
Methodological Framework
Coverage spans the United States, Germany, Japan, the United Kingdom, and Switzerland, with primary inputs from each market's regulatory and reimbursement environment. The analysis combines primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient flow modeling and top-down revenue triangulation anchor market sizing across the projection horizon.
Granularity extends to treatment line, administration route, patient population maturity, and regional regulatory cluster dimensions throughout the forecast period. CAGRs derive from segment-level growth rate reconciliation against macroeconomic healthcare expenditure trends. Forecast inputs incorporate hospital bed capacity constraints for CAR-T toxicity monitoring, viral vector manufacturing yield assumptions, and reimbursement authority value assessment calibrations for curative versus chronic management paradigms.
The model assumes a particular technology adoption path; alternative pathways for allogeneic CAR-T platform maturation would alter the outlook for autologous product pricing power and manufacturing infrastructure investment. Forecasts reflect assumptions around FDA and EMA accelerated approval pathway sustainability, WHO essential medicines criteria influence on lower-income access negotiations, and EU AI Act compliance burden distribution among diagnostic vendors. A model refresh is warranted upon material change in allogeneic CAR-T durability data or German G-BA value assessment methodology revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hematology
Hemoglobin Analyzer Market
Hematology
Hemocytometer Market
Hematology
Hemoglobinopathies Treatment Market
Hematology
APAC Acute Myeloid Leukemia Treatment Market
Hematology
Radiation-Induced Myelosuppression Treatment Market
Hematology
Warm Autoimmune Hemolytic Anemia (WAIHA) Treatment Market
Hematology
AL Amyloidosis Therapeutics Market
Hematology
Graft Versus Host Disease (Gvhd) Treatment Market
Hematology
Hemostatic Spray Market
Hematology
Chemotherapy-Induced Myelosuppression Treatment Market
Hematology
Hemoglobinopathy Treatment Drug Market
Hematology
Small Lymphocytic Lymphoma Market
Hematology
Acute Myeloid Leukemia Treatment Market
Hematology
Lymphoproliferative Disorder Treatment Market
Hematology
Global Bleeding Disorders Market
Hematology
Thalassemia Treatment Market