
 Coma Diagnosis and Treatment Market | 2026-2036
Coma Diagnosis and Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Coma Diagnosis and Treatment Market Analysis
Buyer concentration among hospital networks is repositioning vendor negotiation leverage across the coma care ecosystem. Siemens Healthineers leverages its integrated imaging-to-monitoring portfolio to anchor long-term service contracts with consolidated health systems. Medtronic plc sustains competitive pressure through its deep neurostimulation and drug delivery installed base, while GE Healthcare competes on real-time data analytics integration across enterprise IT architectures.
Coma diagnosis and treatment encompasses the clinical identification of unarousable unconsciousness through standardized scoring systems such as the Glasgow Coma Scale, coupled with interventions ranging from mechanical ventilation and intracranial pressure management to targeted temperature modulation and pharmacologic arousal protocols. Diagnostic Equipment commands the largest revenue pool given capital intensity of MRI, CT, and EEG platforms, while Software Solutions for predictive neurological monitoring represents the fastest-expanding margin segment as artificial intelligence-enabled pattern recognition shifts from research to bedside deployment. Monitoring Systems occupy a mature but defensible position through recurring sensor and consumable attach rates.
FDA breakthrough device designations and EU MDR compliance timelines jointly shape product development roadmaps and market access sequencing for manufacturers. The EPA regulates waste streams from single-use neurodiagnostic consumables, while HIPAA frameworks govern cloud-based patient data architectures that increasingly underpin remote monitoring deployments. Stakeholders must weigh regulatory capital requirements against the pull-through potential of platform-based care models that bundle hardware, software, and clinical decision support into longitudinal contracts.
Market Dynamics
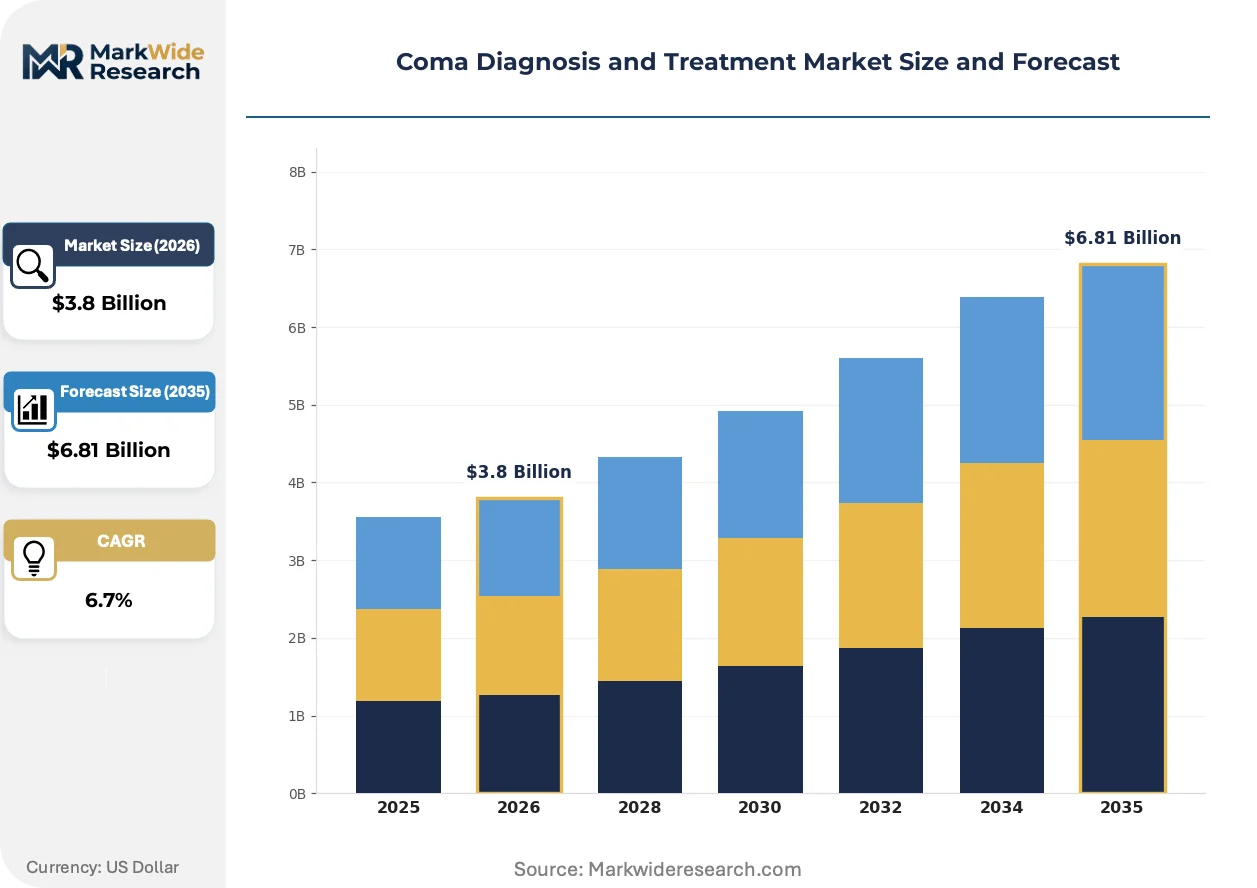
Hospital procurement consolidation across North America is compressing vendor margins while extending contract durations, forcing equipment manufacturers to bundle software subscriptions and service agreements into multi-year platform deals.
Growth Catalysts
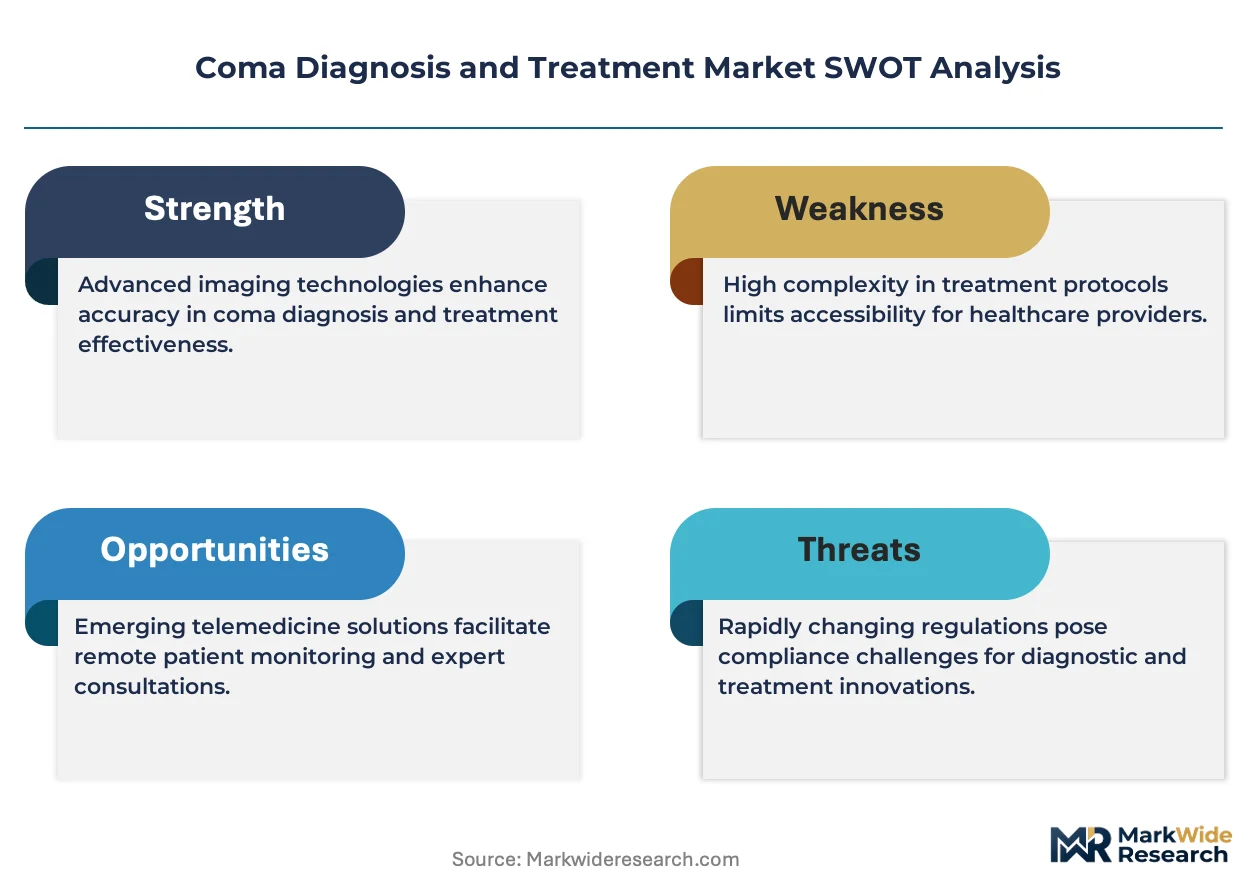
- FDA Breakthrough Device Pathway:The accelerated review track shortens commercialization timelines for novel brain monitoring platforms, enabling earlier revenue recognition for neurotechnology developers.
- Germany's Specialized Unit Density:University medical centers in Germany operate the highest per-capita concentration of dedicated coma management facilities, creating concentrated demand for premium diagnostic suites.
- AI-Enabled Pattern Recognition:Machine learning algorithms trained on EEG and intracranial pressure datasets are migrating from research environments to bedside deployment, expanding addressable software markets.
Market Restraints
- EU MDR Compliance Burden:Extended certification timelines and heightened clinical evidence requirements for Class III neurological devices are delaying product launches and inflating regulatory capital reserves.
- Single-Use Consumable Waste Streams:EPA regulations governing disposable neurodiagnostic electrodes and sensors are adding compliance overhead and disposal costs to recurring revenue models.
- Capital Intensity of Imaging Platforms:MRI and CT suite procurement requires multi-million-dollar commitments that strain capital budgets at mid-tier hospitals, concentrating sales among consolidated health systems.
Strategic Opportunities
- Cloud-Based Remote Monitoring:HIPAA-compliant architectures for continuous neurological surveillance outside ICU settings are opening post-acute and rehabilitation facility channels previously inaccessible to device vendors.
- Predictive Analytics Integration:Convergence of real-time biosignal processing with electronic health record systems is creating demand for enterprise-wide neurological decision support platforms.
- Temperature Modulation Protocols:Targeted therapeutic hypothermia equipment represents an underdeveloped segment with expanding clinical protocol adoption in tertiary care centers.
Industry Challenges
- Neurocritical Care Specialist Scarcity:Shortages of board-certified intensivists trained in multimodal neuromonitoring are limiting utilization rates for advanced diagnostic installations.
- Interoperability Friction:Integration of proprietary brain monitoring data streams with third-party hospital information systems requires costly custom engineering and extended deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coma Diagnosis and Treatment Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Diagnostic Equipment, Therapeutic Devices, Monitoring Systems, Software Solutions End User: Hospitals, Specialty Clinics, Rehabilitation Centers, Emergency Departments Technology: Neuroimaging, Biosensors, Electrophysiology, Drug Delivery Systems Application: Neurological Assessment, Metabolic Monitoring, Patient Stabilization, Rehabilitative Care |
| Companies Covered | Siemens Healthineers, LivaNova PLC, Medtronic plc, Abbott Laboratories, Baxter International, GE Healthcare, Natus Medical Incorporated, Johnson & Johnson, Koninklijke Philips N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coma Diagnosis and Treatment Market Emerging Trajectories
Artificial intelligence is migrating from research abstraction to clinical workflow automation, compressing diagnostic latency while regulatory frameworks on both sides of the Atlantic accelerate approval pathways for software-as-medical-device platforms.
Continuous EEG monitoring coupled with machine learning classifiers is automating seizure detection and prognostic scoring in comatose patients. Academic medical centers in the United States and Germany are deploying these systems at scale, replacing labor-intensive manual trace review. The technology is automating clinical decision support, reducing time-to-intervention for neurological emergencies while compressing staffing requirements for around-the-clock monitoring.
The EU Medical Device Regulation's heightened clinical evidence standards are restructuring product development roadmaps for neurological device manufacturers. Class III brain monitoring systems now require extended post-market surveillance and periodic safety update reports, extending time-to-revenue for novel platforms. European manufacturers are responding by front-loading clinical trial investment and prioritizing MDR-compliant quality management system overhauls ahead of notified body audits.
Health system procurement officers are consolidating vendor relationships through longitudinal platform contracts that bundle hardware, software, and clinical support into single-source agreements. Independent distributors and regional equipment resellers are losing access to neurocritical care suites as direct manufacturer relationships with integrated delivery networks expand. This concentration is most visible in the United States, where hospital network mergers have reduced the number of independent purchasing decision points by double-digit percentages over the past five years.
Coma Diagnosis and Treatment Market Segmentation
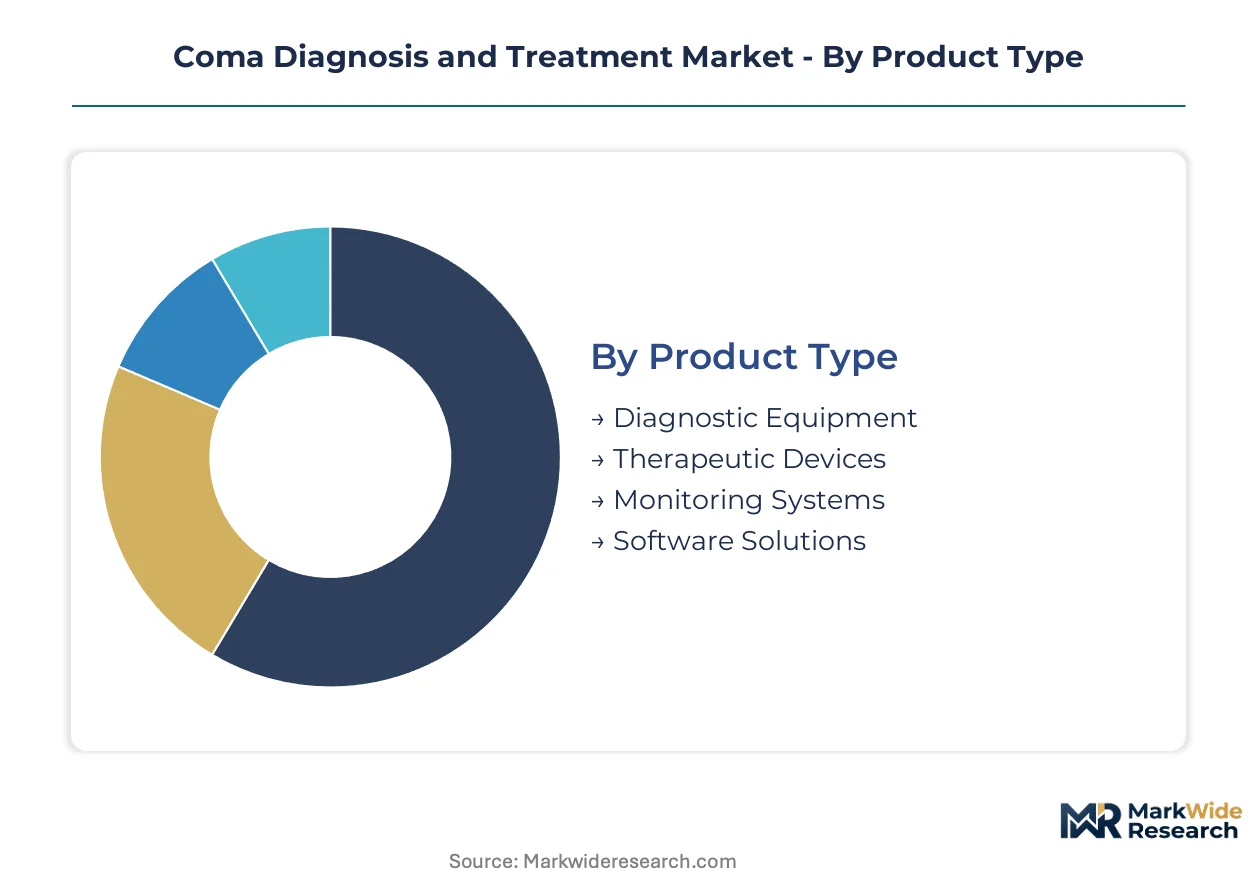
Coma care requires coordinated technology deployment across acute diagnosis, therapeutic intervention, and longitudinal monitoring. Segment boundaries blur as vendors bundle hardware, software, and clinical support into platform contracts. Procurement officers evaluate segments through total cost-of-ownership lenses rather than discrete equipment purchases.
Product Type:
Supply concentration tilts toward capital-intensive imaging platforms where Siemens Healthineers and GE Healthcare anchor installed bases through multi-year service agreements.
- Diagnostic Equipment:MRI, CT, and EEG platforms constitute the revenue foundation. German university medical centers and US academic hospitals concentrate demand for high-field neuroimaging suites. Capital intensity limits procurement to consolidated health systems with dedicated neurocritical care infrastructure.
- Software Solutions:AI-enabled pattern recognition platforms for EEG and intracranial pressure monitoring are climbing the fastest as FDA breakthrough designations accelerate bedside deployment. Cloud architectures and HIPAA-compliant data pipelines expand addressable markets beyond traditional ICU settings.
- Therapeutic Devices:Targeted temperature modulation systems and neurostimulation hardware support acute intervention protocols. Mid-tier hospitals defer purchases due to specialist staffing requirements.
- Monitoring Systems:Continuous intracranial pressure and cerebral perfusion sensors generate recurring consumable revenue. Sensor interoperability with third-party displays remains a deployment friction point.
Today's leader: Diagnostic Equipment. Tomorrow's challenger: Software Solutions.
End User:
Customer type determines contract structure, with hospitals demanding enterprise-wide platform deals while smaller facilities seek modular procurement.
- Hospitals:Tertiary centers with dedicated neuro-ICUs drive premium equipment procurement. Consolidated US hospital networks leverage volume for extended payment terms and embedded clinical support.
- Emergency Departments:Rapid neurological assessment protocols concentrate demand for portable CT and point-of-care EEG. Time-to-diagnosis pressures override capital cost sensitivity.
- Specialty Clinics:Focused neurodiagnostic facilities prioritize high-throughput EEG and evoked potential systems. Patient referral relationships shape equipment selection.
- Rehabilitation Centers:Long-term consciousness monitoring creates demand for ambulatory EEG and functional imaging. Reimbursement variability constrains technology adoption.
Volume concentrates in Hospitals. Margin expansion potential sits with Emergency Departments.
Technology:
Maturity curves diverge sharply, with established neuroimaging facing margin pressure while biosensor platforms capture R&D investment.
- Neuroimaging:MRI and CT modalities dominate diagnostic workflows. Equipment refresh cycles extend as software upgrades substitute for hardware replacement.
- Biosensors:Minimally invasive intracranial and cerebral oximetry sensors are expanding most quickly. Disposable electrode economics attract venture funding for novel form factors.
- Electrophysiology:Continuous EEG and evoked potential systems automate seizure detection. Machine learning classifiers reduce specialist interpretation burden.
- Drug Delivery Systems:Programmable infusion pumps support targeted hypothermia and pharmacologic arousal protocols. Integration with monitoring platforms enables closed-loop control.
Established dominance: Neuroimaging. Disruption vector: Biosensors.
Application:
Clinical workflow integration determines technology valuation, with acute stabilization commanding immediate spend and rehabilitative care requiring longitudinal reimbursement alignment.
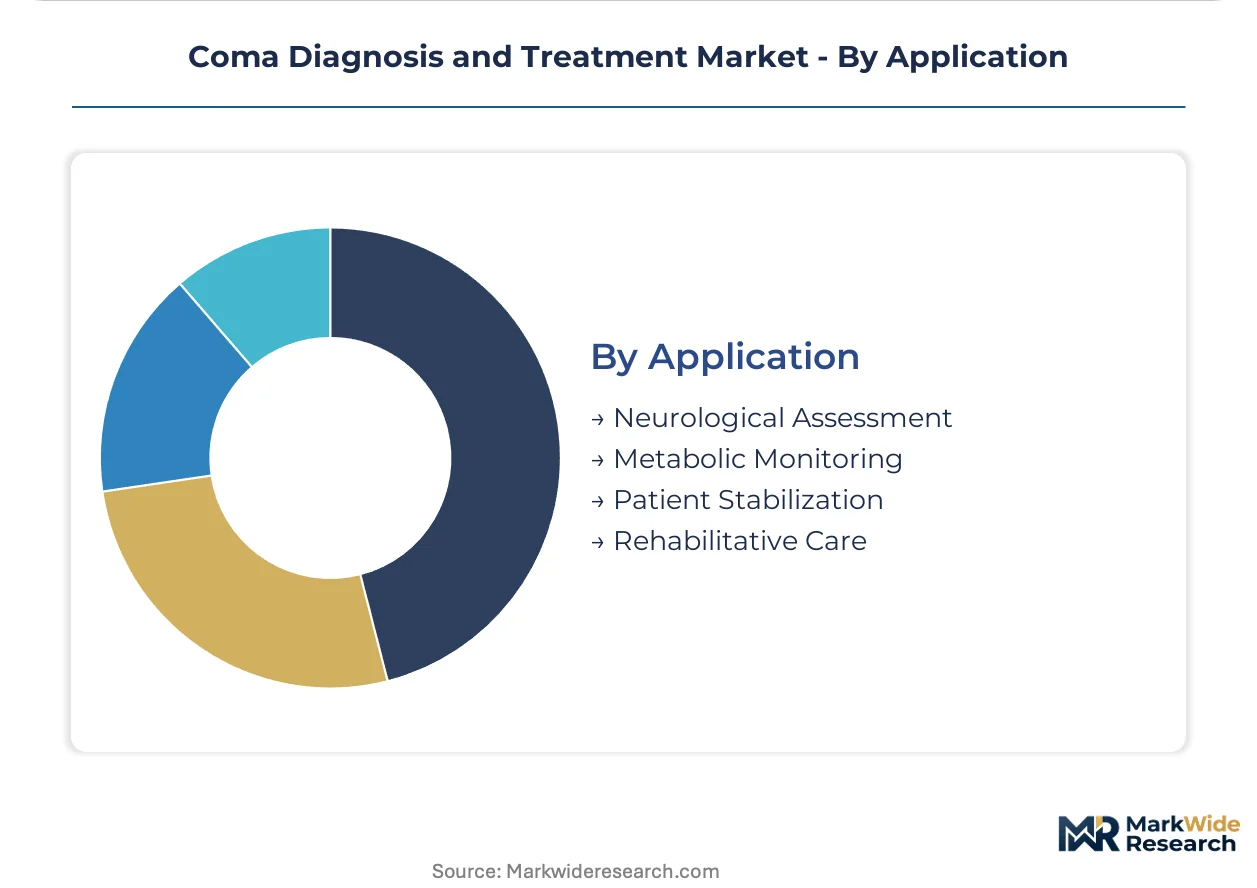
- Neurological Assessment:Standardized scoring systems and multimodal monitoring guide prognosis. Academic medical centers in Germany and the United States deploy comprehensive assessment protocols.
- Patient Stabilization:Intracranial pressure management and ventilatory support demand immediate intervention. Equipment utilization rates track directly with neurocritical care specialist availability.
- Metabolic Monitoring:Continuous glucose and lactate surveillance supports secondary brain injury prevention. Integration with electronic health records remains incomplete.
- Rehabilitative Care:Consciousness recovery monitoring extends technology deployment into post-acute settings. Payer coverage variability limits market penetration.
Immediate priority: Patient Stabilization. Long-term platform opportunity: Rehabilitative Care.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany operates the highest density of specialized coma management units per capita globally, while the United States concentrates absolute procurement volume within consolidated hospital networks. Japan and China are expanding neurocritical care infrastructure through targeted hospital upgrades. The United Kingdom and France maintain steady replacement demand for diagnostic platforms.
United States
Hospital network consolidation across Texas, Florida, and the Northeast Corridor is compressing vendor margins while extending contract durations to seven-year platform agreements. The FDA's breakthrough device designation pathway accelerates commercialization timelines for novel brain monitoring platforms. Academic medical centers in Boston and Houston deploy comprehensive multimodal neuromonitoring suites at scale.
Germany
University medical centers in Bavaria and Baden-Württemberg operate dedicated coma management facilities with the highest per-capita concentration worldwide. The EU MDR's heightened clinical evidence requirements for Class III neurological devices are extending certification timelines and inflating regulatory capital reserves. Berlin and Heidelberg anchor research clusters where AI-enabled EEG pattern recognition shifts from laboratory to bedside deployment.
Japan
Aging demographics and stroke incidence are driving demand for portable CT and point-of-care EEG systems in emergency departments. METI funding supports domestic manufacturers developing next-generation neuroimaging platforms. Tokyo and Osaka medical centers lead adoption of continuous intracranial pressure monitoring with integrated machine learning classifiers.
China
Tier-1 hospitals in Beijing, Shanghai, and Guangzhou are prioritizing neurocritical care suite construction as part of national hospital upgrade programs. NMPA regulatory reforms are streamlining approval pathways for innovative neurological devices while maintaining stringent post-market surveillance requirements. The Yangtze River Delta region concentrates manufacturing capacity for disposable neurodiagnostic electrodes.
United Kingdom
NHS England's specialized commissioning frameworks are concentrating coma care referrals into designated neuroscience centers across London, Manchester, and Glasgow. MHRA alignment with EU MDR standards is maintaining regulatory continuity for neurological device imports. The Oxford-Cambridge arc supports digital health ventures developing cloud-based neurological monitoring architectures.
Coma Diagnosis and Treatment Market Vendor Landscape
German producers anchor the premium imaging tier; American specialists hold dominant positions in neurostimulation and drug delivery systems. The vendor base structures around three tiers: diversified conglomerates with integrated care portfolios, mid-scale neurology-focused device manufacturers, and emerging AI-software platforms seeking hardware partnerships. M&A activity concentrates on predictive analytics capabilities, while strategic partnerships bundle diagnostic hardware with longitudinal service contracts.
Within the diversified conglomerate tier, Siemens Healthineers and GE Healthcare exemplify platform-based competition through multi-year service agreements anchoring hospital network relationships. Medtronic plc occupies a position representing the neurotechnology specialist archetype, with installed base depth in stimulation and monitoring hardware creating defensive moats against software-centric entrants. These three entities collectively illustrate how vendor consolidation is repositioning negotiation leverage across procurement cycles.
| Leading Market Players |
|---|
| Siemens Healthineers |
| LivaNova PLC |
| Medtronic plc |
| Abbott Laboratories |
| Baxter International |
| GE Healthcare |
| Natus Medical Incorporated |
| Johnson & Johnson |
| Koninklijke Philips N.V. |
| Others |
Supply Flow & Price Mechanics
AI-enabled software companion development is compressing hardware margins while concentrating procurement leverage among consolidated US hospital networks and German university medical centers. This technology transition simultaneously elevates recurring SaaS revenue streams and forces traditional equipment vendors toward platform bundling.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for disposable neurodiagnostic electrodes and sensors. Three-tier pricing structure across premium, standard, and economy levels separates FDA breakthrough-designated platforms from CE-marked equivalents and unvalidated imports. Cost compression in the standard tier is intensifying because mid-tier hospitals defer capital purchases. Emergency departments demonstrate the least price sensitivity due to time-to-diagnosis pressures, while rehabilitation centers face the highest budget constraints.
Supply Chain Analysis
Dual-sourcing requirements from consolidated health systems are mandating multi-supplier qualification for critical components. Manufacturing concentrates in Germany for precision imaging platforms, the United States for neurostimulation hardware, and China for disposable electrodes. Supply chains draw from rare earth elements for MRI magnets, semiconductor chips for signal processing, and specialized polymers for biocompatible sensors. Single-source vulnerability around advanced MRI magnet production creates structural risk. Distribution runs through direct manufacturer relationships with integrated delivery networks, displacing independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coma diagnosis and treatment market functions as a stable compounder, with neurocritical care infrastructure buildouts in Germany, the United States, and China providing steady demand visibility across the analysis window.
For Market Incumbents: Cement platform dominance by embedding AI-enabled pattern recognition into longitudinal service contracts with consolidated hospital networks. Deepen backward integration into sensor manufacturing to defend margins against commoditization of disposable components. Prioritize MDR compliance investment ahead of notified body audits to maintain European market access. For New Entrants and Emerging Players: Direct-to-clinician digital channels offer the lowest friction entry path for AI-software platforms seeking hardware partnerships. Target rehabilitation centers and post-acute facilities as the most penetrable segment, where reimbursement alignment lags but technology gaps remain acute. Pursue white-label integration with established imaging vendors as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale neurology-focused device manufacturers lacking AI capabilities but holding installed base depth. The five-to-ten year viability framing favors platforms with recurring revenue attach rates over pure hardware plays. Watch FDA breakthrough device designation velocity as the signal indicating inflection in software valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Submission | Accelerated review timelines compress time-to-revenue for AI-enabled monitoring platforms. |
| Hospital System Partnership | Longitudinal platform contracts with consolidated networks anchor recurring revenue visibility. |
| Software Companion Development | Machine learning classifiers for EEG pattern recognition differentiate hardware commoditization. |
| CE Marking Pathway | MDR compliance investment maintains European market access amid heightened clinical evidence requirements. |
| Reimbursement Strategy | CPT code alignment for continuous neuromonitoring unlocks post-acute facility penetration. |
Methodological Framework
Bottom-up hospital procurement modeling reconciled against top-down neurotechnology manufacturing tracking forms the analytical core. Primary interviews with neurocritical care intensivists, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR notified body databases, hospital capital expenditure disclosures, and CMS Medicare reimbursement schedules. Triangulation between demand-side utilization patterns and supply-side production capacity ensures cross-verified market sizing.
Input-output matrices map diagnostic equipment, software solutions, therapeutic devices, and monitoring systems against end-user segments across the projection horizon. Segmentation dimensions include product type, technology maturity curve, clinical application workflow, and regional regulatory cluster. CAGRs derive from installed base growth rates, replacement cycle compression, and software attach rate expansion. Forecast inputs incorporate neurocritical care specialist supply constraints and AI algorithm regulatory clearance velocity.
The model assumes a particular technology adoption path; alternative pathways for bedside-deployed machine learning classifiers would alter the outlook. Forecasts reflect assumptions around FDA breakthrough designation throughput, EU MDR certification timeline normalization, and hospital network consolidation velocity. Deviation in neurocritical care workforce expansion would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Neurology
Brazil Neurology Devices Market
Neurology
United Kingdom Neurology Devices Market
Neurology
Mild Cognitive Impairment Market
Neurology
Brain Ischemia Market
Neurology
Global Vertigo Treatment Market
Neurology
Bell Palsy Treatment Market
Neurology
Moyamoya Disease Market
Neurology
India Neurology Devices Market
Neurology
Interventional Neurology Market
Neurology
Peripheral Neuritis Treatment Market
Neurology
Pediatric Neurology Device Market
Neurology
Multiple Sclerosis Therapies Market
Neurology
Optic Neuritis Treatment Market
Neurology
Chordoma Disease Market
Neurology
US Optic Neuritis Market
Neurology
3D Neuroscience Market